




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 16, 2026 | NCFA Market Insight | Consumer Duty And Digital Finance

Data Source: UK Financial Conduct Authority Financial Lives Survey
On Mar 13, 2026, the UK Financial Conduct Authority published good practice and areas for improvement on consumer understanding, which is critical under Consumer Duty. It's important because the FCA wants firms to show that customers actually understand products, risks, costs, eligibility, and support at the point of decision. This moves the debate past disclosure.
The FCA has real evidence about consumer weakness. Its 2024, a UK Financial Lives survey found that 12% of adults, about 6.3 million people, had limited understanding of the products they held.
Another 19%, about 10.3 million, had low confidence with everyday numeracy (34% poor or low financial numeracy). Three in 10 said their preferred communication channel had been withdrawn, causing difficulty for most of them.
The FCA also cites research showing that 1 in 7 adults have literacy skills at or below those expected of a 9 to 11 year old.
The study also notes that 22% of adults lacked confidence managing money and 36% had low knowledge about financial matters.
Those numbers explain the policy intent. If firms keep pushing more financial decisions into online self serve journeys, regulators want evidence that speed doesn't come at the expense of understanding.
The FCA says it used a wide evidence base, including supervisory findings, form data, behavioural research, and engagement with industry bodies, charities, and consumer groups.
It also ran a September 2025 survey of 38 firms across insurance, retail banking, payments, consumer finance, and Contract for Difference providers.
The review focused on five areas: (1) management information and testing, (2) innovation and communication design, (3) vulnerability and accessibility, (4) financial promotions, and (5) governance and oversight.
1. One firm used website analytics to find where customers got stuck during a sales process, tested improvements, reduced the number of clicks needed to complete the task, and cut helpline calls.
2. Another smaller firm tested a renewal letter with customers including two with sight impairments, then introduced large print, a 100 word summary, and clearer next steps. Follow up calls and a micro survey then showed better understanding of excesses and cancellations, with fewer complaints about unclear letters.
3. In another example, a firm set an internal target of at least 80% correct recall of key points when testing communications with customers in vulnerable circumstances and repeated drafting until it hit that threshold.
The FCA is not just asking for better UX or a cleaner narrative. It is asking for an integrated control system that links insight, design, testing, vulnerability, promotions, and governance.
The FCA says the publication may help policymakers and other stakeholders improve customer understanding across financial services. That makes it relevant in Canada on two levels.
For fintechs and financial institutions, it offers a practical operating playbook for testing, accessibility, promotions, and governance. For policymakers and regulators, it shows what a more detailed supervisory model looks like when a market evolves from broad conduct guidance to clearer expectations on proof, monitoring, and accountability.
NCFA has already highlighted the demand side of this issue in its analysis of FCA Financial Lives gaps. This new FCA paper adds the supply side. It shows how firms are expected to respond.
The takeaways travel well beyond the UK. Firms should approach it as an operating model. Policymakers should study it as a regulatory benchmark. Consumer Duty is pushing the market from disclosure to proof, and that's raising the standard for digital finance. If the market wants better outcomes, stronger trust, and fewer harmful misunderstandings, it will need more than disclosure rules alone. It will need evidence that customers actually understand what they are being shown and asked to do.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 16, 2026 | NCFA Market Activity | Cross Border Payments Infrastructure

On Mar 13 2026, global payments platform Airwallex announced a $1.135B over five years across the United Kingdom and EMEA to expand product development, engineering capacity and regional operations.
The company reported 116% year over year revenue growth and a 226% increase in transaction volume across EMEA (Europe, Middle East, and Africa). The expansion includes plans to hire about 100 senior engineers in London, the first time Airwallex will base engineering teams in the United Kingdom.
Airwallex provides infrastructure for international businesses including multicurrency accounts, cross border payments, foreign exchange, card issuing, and expense management.
In its 2025 year end mission update, the company said its platform processes more than $266B in annual transaction volume. The firm also reported that 95% of transactions run through local payment rails across 127 countries, with about 94% settling the same day.
The investment adds engineering capacity and infrastructure in one of the world’s largest markets for cross border business payments. Global businesses increasingly rely on platforms that provide local accounts, foreign exchange, international payouts and card services through a single financial infrastructure provider.
Large platforms are responding by building regional engineering teams, expanding local rail coverage and increasing settlement speed. Airwallex’s reported transaction scale and investment size show how quickly infrastructure providers are scaling to serve cross border digital businesses.
Competition global payments platforms combine local payment rail access, multicurrency financial services and software integration in one system capable of handling large international transaction volumes.
Platforms processing hundreds of billions in transaction volume are investing heavily in local payment rail access and engineering capacity as competition intensifies in cross border payments infrastructure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 16, 2026 | NCFA Insight | Consumer Fintech And Housing Payments
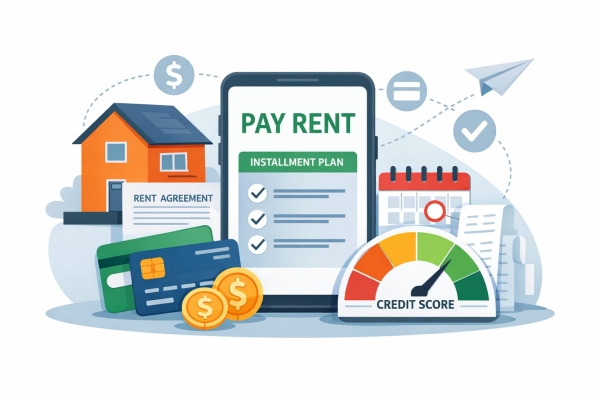
AI generated image: Rent Now Pay Later (RNPL)
On Mar 14 2026, CNN rent BNPL trend coverage in the US highlighted a new area of growth for consumer fintech, Rent Now Pay Later. BNPL providers and payment platforms are starting to move into rent payments, the largest recurring expense for many households.
Canada is already heading down this path. Fintech firms have spent several years pulling rent into the credit system through reporting and credit building services. KOHO rent credit programs allow renters to build credit history through rent payments, while rent credit history tools from Borrowell allow renters to add up to two years of past rent payments to their credit profile.
Now the model goes further.
Instead of only reporting rent payments, fintech platforms are beginning to split, finance, or route rent payments through credit rails. Rent is starting to look less like a fixed housing cost and more like a financial transaction that can generate data, fees, rewards, and short term credit exposure.
The underlying driver is housing affordability. rent burden data from Statistics Canada shows 33.0% of Canadian renter households spent 30% or more of income on shelter costs in 2022, a commonly used affordability threshold. Among private market renters who don't receive rent subsidies, the share rises slightly to 34.0%.
When roughly one third of renters already operate near an affordability limit, even small timing mismatches between income and rent payments can create pressure. Many workers receive pay every two weeks while rent is due monthly. Payment flexibility tools are now working to bridge that gap.
Several Canadian fintech firms are building products around rent payments. Zenbase offers split rent payments while reporting payment history to credit bureaus. Toronto fintech Chexy allows renters to pay rent by card, turning rent into a transaction that can generate rewards and short term credit float.
Borrowell focuses on rent reporting, allowing rent payment history to appear in an Equifax credit file. Products from KOHO, Borrowell, Zenbase, and Chexy differ in structure but share the same direction. They're moving rent deeper into payments infrastructure and credit data systems.
It's an important problem to focus on because rent is one of the largest financial flows in household budgets. Once fintech platforms innovate the payment stream, the implications extend into credit scoring, underwriting, rewards programs, and consumer debt exposure.
The benefits are straightforward. Rent reporting can help renters build credit files that traditional lending products often overlook. Payment flexibility can help align rent payments with pay cycles.
The risk emerges when flexibility substitutes for affordability. The reality is splitting rent into installments doesn't reduce the underlying cost of housing. It only spreads the obligation across time. Service fees, credit card interest, and repeated installment use can gradually turn a convenience feature into ongoing credit reliance.
This fact will likely determine how the category evolves. Products designed for occasional payment timing behave very differently from models that depend on frequent borrowing by financially stressed households.
Canadian regulators already monitor buy now pay later products as a consumer finance issue. The BNPL pilot study from the Financial Consumer Agency of Canada surveyed 1,034 Canadians to better understand how these services are used and whether consumers fully understand repayment terms and penalties.
Rent installment services raise similar questions. When the largest household bill starts moving onto credit rails, repayment discipline, fee transparency, and repeat usage patterns become key areas of concern and focus for both fintech providers and regulators.
Products that help renters manage payment timing or build credit history can deliver real value. But if rent flexibility becomes another channel for consumer borrowing, the category will face the same scrutiny that now surrounds buy now pay later services.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 13, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Open Banking Open Finance And Data Sharing, Payments And Market Infrastructure, Regulation And Policy

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026).
Regulators are aligning competition rules and data protection in a way that directly affects how AI systems access, process, and govern data. For fintechs and financial institutions building on platform infrastructure, data strategy, consent design, and compliance architecture are becoming tightly coupled decisions.
Large platforms, AI firms, fintechs, and financial institutions that depend on platform distribution, data access, identity layers, or app infrastructure face a more active compliance environment. Platform terms, profiling practices, interoperability rules, and access conditions can change through ongoing regulatory review. Firms with high dependency on a small number of gatekeepers face increased operating risk, while firms that diversify distribution, strengthen direct customer relationships, and build adaptable data and compliance architectures will be better positioned.
The next edge will come from firms that can operationalize data standards, identity rails, and compliance workflows across jurisdictions rather than wait for policy intent alone to close the gap.
This deal says scale in cross border payments is moving toward platforms that already combine distribution, compliance support, and endpoint reach. For smaller wallet, remittance, and banking partners, the harder question is no longer whether they can connect. It is whether they still control enough of the customer relationship or economics once a larger stack sits in the middle.
This brings Ripple inside the licensed payments system in Australia. It can handle more of the payment flow itself instead of relying on partners. That includes onboarding, compliance, FX, and payout. For banks and fintechs, this means a digital asset firm can now compete more directly on cross border payments with full regulatory coverage, not just as a crypto overlay.
This impacts payment processors, merchant platforms, and consumer fintechs that want to own checkout and settlement. A payment aggregator license pulls merchant onboarding, refunds, and settlement into one accountable layer, so competitors and partners should expect tighter expectations on merchant screening and operational controls as volumes grow.
This impacts fixed income platforms, treasury and collateral systems, and anyone building workflows that touch Government of Canada collateral. Dealer funding and hedging capacity affects liquidity and trading costs.
This impacts capital markets fintechs that want distribution through regulated channels. When a top tier exchange brand commits to a tokenization partner, procurement and diligence tighten fast. Builders should prepare for deeper questions on governance, surveillance, custody controls, and how tokenized assets move without breaking compliance reporting and investor protections.
This raises the execution standard for digital onboarding, disclosures, promotions, and support flows. For fintechs, good UX is no longer enough on its own. Firms need evidence that customers understand what they are seeing and can act on it without avoidable confusion.
Ottawa is pushing affordability through multiple channels at once, including taxes, housing, and core banking fees. For banks, that puts more pressure on legacy fee revenue and raises the importance of better alerts, cash flow tools, and low cost account design. For fintechs, it strengthens the case for products that help users avoid failed payments, manage short term liquidity, and lower everyday banking friction.
Banks lose part of a high margin penalty fee and face more pressure to compete on better alerts, balance visibility, payment controls, and products that help customers avoid failed payments in the first place. Direct product and revenue implications across consumer banking.
This opens a formal rulemaking lane around one of the fastest growing grey areas in digital markets. It matters for exchanges, brokers, market makers, and fintech platforms. How far regulated market structure will let them scale before they run into tighter product boundaries.
This guidance impacts how Canadian DIY investment platforms can design tools and user experiences. Online brokers and fintech wealth platforms now have clearer room to provide decision support, portfolio models, and guided interfaces, but they must build stronger safeguards to ensure those tools do not cross the line into regulated investment advice (a condition of the OEO regulatory exemption).
Public payment rails can widen access, but they can also compress private platform economics and add pressure onto merchant pricing. For banks, fintechs, and payment providers, the real issue is not only whether public rails expand. It is how pricing design changes volume, margin, and who absorbs the cost.
A charter application signals a potential change in funding and balance sheet strategy for an AI lending platform and it can reshape partner economics for banks and credit unions that currently fund originations.
This is more than a weak quarter. It puts credit quality, funding resilience, and covenant headroom back at the center of the non prime lending story, which matters for alt lenders, securitization partners, credit investors, and fintechs selling underwriting, servicing, collections, and portfolio monitoring tools into the consumer lending stack.
This matters for brokers, carriers, and digital asset clients because premium payments are a treasury workflow. Once stablecoins clear premiums across real counterparties, buyers and carriers will ask harder questions about controls, reconciliation, and how funds move from premium collection to coverage without losing traceability.
This roadmap puts Europe closer to a tokenised market structure built around central bank money rather than private settlement workarounds. It matters for banks, FMIs, tokenisation platforms, and securities infrastructure teams because the market is now moving from exploratory work toward live design choices on standards, networks, and governance.
This opens a cleaner path for brokers and institutional desks that want crypto execution without rebuilding their stack around proprietary APIs. Once crypto routing uses the same FIX plumbing as other asset classes, firms will put more weight on consistent controls, audit trails, and operational readiness across both traditional and digital venues.
Payment networks are scaling distribution and wallet reach. Tokenized market structure is moving closer to institutional use. Canada’s NSF fee cap also cuts into a legacy bank revenue line and raises the value of tools that help customers avoid failed payments. The strongest fintechs and financial institutions are combining regulatory discipline, strong rails, and practical financial workflows that reduce friction for users.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 13, 2026 | NCFA Market Activity | AI In Finance And Trading Infrastructure
Image: Freepik AI
On March 13 2026, QuantPower said it received official exchange approval under the CTCL framework, a regulatory step that allows its automated execution strategies to connect to the exchange trading system through compliant infrastructure. The company said the approval covers the Algo Application category for F&O segment execution strategies.
QuantPower said the approved setup includes proprietary and client trading, a direct connection using trimmed CTCL, Linux based infrastructure, and in house systems developed by parent company Wisdom Tree Ventures Pvt. Ltd. The company also said the approved strategy list includes Iron Fly and other algorithmic trading strategies.
The company says the exchange reviewed its automated trading system and decision support infrastructure under the CTCL framework. That gives the story more weight than a standard product update because it confirms the platform has crossed a formal exchange review process for live strategy execution.
QuantPower says it was founded in 2022 in Noida and has since added broker tools, backtesting, and options analytics. It also points to earlier recognition, including a 2023 award for Best Algo Trading Platform in India and a 2024 award for Best Trading Platform in India.
QuantPower says its platform includes a strategy builder, algo bots, historical backtesting, advanced options analytics, real time market scanners, and signal based trading tools. It also says subscription plans start at ₹299 per month, which points to a retail and small trader access model rather than a pure institutional product.
As exchanges and regulators tighten rules around algorithmic trading, the firms that win will likely be the ones that combine automation with compliant connectivity, risk controls, and audit trails. That creates room for fintech builders working on execution systems, surveillance, broker connectivity, and trading analytics.
While this announcement does not change market structure on its own, it's a clear sign that AI enabled trading platforms are moving deeper into regulated infrastructure (beyond institutional desks) rather than staying at the edge of the market.
As algorithmic tools move toward retail and small trader access, will compliant infrastructure become the real moat in AI driven trading?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 13, 2026 | NCFA Market Activity | Digital Lending And Mortgage Infrastructure
On March 11 2026, Royal Bank of Canada announced it acquired Toronto based Pinch Financial, a fintech company that verifies borrower information digitally and helps Canadians submit applications to lenders. Terms of the deal were not disclosed. The deal isn't a brand extension for RBC, nor is it venture investing. It's investing in workflow tech that removes friction from one of the most document heavy parts of consumer finance.
RBC President and CEO Dave McKay, gave the clearest reason for the deal:
“Pinch’s technology will help us accelerate our digital roadmap to deliver a quicker, more streamlined mortgage experience for Canadians.”
Canada’s mortgage market is too large and too complex for banks to ignore small operational gains. CMHC reported that residential mortgage debt reached $2.3T in August 2025, up 4.8% from a year earlier. In a market of that size, faster verification, cleaner data collection, and fewer manual handoffs can improve turnaround times, reduce processing costs, and make the borrower experience easier to manage.
Pinch isn't a new idea in search of a problem. The company was founded in 2016 and has helped tens of thousands of Canadians apply for mortgages and purchase homes since launch. That gives the acquisition more weight than a simple talent buy. RBC is buying a working piece of mortgage infrastructure with real borrower and lender usage and learnings behind it.
Andrew Wells, CEO, Pinch Financial:
"We started Pinch to make mortgages more relevant and familiar for digital-first consumers--making the qualification process faster, simpler, and more transparent for borrowers,"
The deal also says something important about how Canadian banks are approaching fintechs now. When a major bank buys a focused platform instead of building everything internally, it usually means the technology solves a real operational bottleneck. In this case, the bottleneck is qualification and application flow, where delays often come from documents, verification checks, and repeated back and forth with borrowers.
For fintech founders, it's a good sign that banks are still buying specialized technology when it improves speed, reduces manual work, and fits into an existing regulated workflows. That makes mortgage technology, document automation, borrower verification, and lending operations more than nice to have tools. They are becoming strategic assets.
Competition in mortgages is no longer just about rate sheets, comparison sites, and branch reach. It is also about who controls the workflow behind the decision. Platforms that make qualification faster and cleaner can influence conversion, cost per file, and customer retention. Startups do not always need to replace incumbents to create value. In many cases, they create strategic value by building tools that incumbents adopt, partner with, or acquire. Pinch is a clear example of that pattern.
If banks keep buying mortgage workflow technology instead of building it, who will own the most valuable part of home lending in Canada: the balance sheet or helpful tech inside the borrower's journey?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 12, 2026 | NCFA Fintech Market Activity | Digital Assets And Payments Compliance
Image: Freepik/rawpixel.com
On Mar 11 2026, Hong Kong based stablecoin payments firm RedotPay outlined regulatory progress across Canada, the United States, and Argentina as it builds the registrations required to operate in more regulated markets.
The company holds Money Services Business registration with FinCEN in the United States and registration with FINTRAC in Canada (jurisdiction of incorporation is the province of BC), and is pursuing Virtual Asset Service Provider registration in Argentina. These steps allow the firm to work with regulated partners as it expands its stablecoin payment platform.
RedotPay offers a wallet and card based payment system built around stablecoins, allowing users to send digital assets while recipients receive local currency. The company says its platform now serves more than six million users across over 100 countries and processes roughly $10 billion in annualized payment volume.
Stablecoin payment platforms often present themselves as borderless financial infrastructure. In practice, access still depends on local regulatory registration. Firms must establish compliance credentials before banks, card networks, payment processors, and institutional partners will work with them.
In Canada, FINTRAC registration places RedotPay inside Canada's anti money laundering supervision framework. For digital asset payment companies, that registration is typically the first threshold for operating credibly and building domestic partnerships.
Other rules may also apply depending on the product model, including the Bank of Canada’s Retail Payment Activities Act (RPAA) for payment service providers and provincial securities oversight for certain digital asset activities.
Competition in crypto payments is moving away from unique app features alone and toward regulated distribution. Firms that secure registrations across multiple jurisdictions gain earlier access to payment rails, banking relationships, and local partner networks. Firms that delay those steps often remain limited even if their technology works.
It's a dynamic that's becoming more visible as stablecoin payment platforms grow. Compliance infrastructure is no longer just a back office function. It increasingly determines which firms can expand internationally and which ones stall when regulatory scrutiny increases.
As stablecoin payment firms expand globally, will long term advantage come from product features or from who can secure regulated market access first?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016