




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Stablecoins | Nov 3, 2025
Image from Loon press release
On October 27, 2025, Loon announced a CAD $3 million pre-seed round and the acquisition of the CADC stablecoin, led by Version One Ventures with participation from Garage Capital and Canadian angels.
The company acquired CADC, a stablecoin originally launched by Paytrie Inc. in 2021 that has processed more than CAD $200 million in on-chain transactions, according to the announcement.
Loon aims to develop a Canadian-dollar stablecoin that operates under Canadian regulation and has pre-filed a prospectus with the Alberta Securities Commission as the first step toward full approval. The company says it is working closely with regulators to define clear standards for the stablecoin sector and strengthen accountability across the industry.
Short term priorities for Loon include onboarding distribution partners (exchanges, fintech apps, liquidity providers) and building trust through clear rules, transparent reserves, and reliable operations in a market long dominated by US dollar stablecoins.
CADC allows users and businesses to send and receive Canadian dollars on blockchain networks instantly and at any time. This means a developer in Halifax can receive payment from a client in Vancouver within seconds, or a Toronto-based importer can complete transactions with suppliers abroad without relying on traditional banking hours or payment delays.
The system is designed to provide continuous access, real time settlement, and deeper liquidity, while maintaining wholesale-level foreign exchange efficiency.
Kevin Zhang, CEO of Loon:
"Canada is at a crossroads. We can either remain dependent on foreign financial infrastructure or build our own sovereign rails for the digital era. By providing a regulated, trusted digital Canadian dollar, we're unlocking the next generation of innovation, from payments to capital markets."
The timing of Loon’s raise aligns with national policy attention on digital assets. The Bank of Canada urged policymakers to weigh the merits of federal stablecoin regulation in September 2025, showing growing support in Canadian-dollar models. See NCFA’s analysis of Canada’s stablecoin race entering a critical phase, which describes how policy and market interest are converging.
Also see NCFA’s recent coverage of banks and fintechs backing a regulated stablecoin with Tetra Digital Group, expanding interest in compliant Canadian-dollar payment infrastructure. Related initiatives include Stablecorp’s $5M raise to accelerate QCAD adoption, VersaBank’s plan to launch VCAD, the world’s first bank issued deposit based digital currency, and its U.S. pilot of tokenized deposits, activity all contributing to Canada’s development of regulated digital currency infrastructure.
The policy backdrop includes expectations that the upcoming federal budget 2025 will address financial services modernization and digital assets.
Canada is moving from talk to implementation on regulated digital currency rails. Loon's pre-seed round confirms that a trusted CAD-backed model can attract capital while engaging with regulators. Stablecoins are practical and essential financial infrastructure with potential benefits for payments, cross-border settlement, and market efficiency, all of which align with the need to focus on innovation, access to capital, and national competitiveness.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Competition | Oct 31, 2025

Today, the Competition Bureau of Canada released a new draft of "Anti-Competitive Conduct and Agreements Enforcement Guidelines" for the public and stakeholder consultation to be submitted by January 29, 2026. These guidelines are part of a larger effort to modernize how Canada enforces competition law, which directly affects fintechs, startups, and any business working to scale in today’s digital economy.
The proposed guidance updates how the Bureau will interpret and enforce sections 75 to 79 and 90.1 (see Competition Act text), including key areas such as:
- Refusals to deal and exclusive arrangements
- Market restrictions and tied selling
- Abuse of dominance
- Civil agreements between competitors that may restrict competition
It also consolidates older enforcement materials, including the now superseded 'Price Maintenance Guidelines' and 'Abuse of Dominance Guidelines' into a single updated document that reflects legislative amendments made between 2022 and 2025.
For fintechs, platform businesses, and other high-growth ventures, this kind of regulatory clarity matters. Whether you are entering a data-sharing agreement, challenging a gatekeeping incumbent, or navigating pricing structures, clearer enforcement guidance reduces ambiguity and legal exposure.
The draft guidelines account for several recent reforms to the Competition Act, including:
- A restructured test for abuse of dominance
- New scrutiny on certain business collaborations (even when parties are not direct competitors)
- An expanded ability for multiple provisions to apply in a single enforcement case
According to the Bureau, these updates are designed to reflect how competition issues appear in evolving markets, including digital services and platform ecosystems.
In prior consultations, public feedback has directly influenced how the Bureau created its final guidance, whether on wage-fixing, platform conduct, or innovation impacts. Stakeholder input has led to more usable, grounded enforcement tools that reflect market realities.
This consultation is substantive. If your business model depends on partnerships, licensing, data access, or competition with larger players, this consultation is worth your attention.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Equity Crowdfunding | Oct 31, 2025
Image: Gander Social via FrontFundr equity crowdfunding campaign
On October 24, 2025, Gander Social, a Canadian alternative to foreign-owned social platforms, announced that they surpassed $1 million raised from more than 1,595 investors in its initial private community phase, exceeding their target in just over a week. Then on October 30, the company announced in a release that they are opening the campaign up to the public on FrontFundr, inviting Canadians across the country to join its growing base of community owners.
The campaign has now raised almost $1.2 million and is targeting $1.5 million and continues to grow rapidly through organic participation and word-of-mouth sharing, demonstrating the strong appetite for Canadian-built platforms and the expanding role of equity crowdfunding in mobilizing retail investors, especially at a time when early stage venture funding channels are under pressure.
Led by Ottawa-based longtime creative director turned founder CEO Ben Waldman, Gander Social is built by a small team of Canadian engineers and creators who want to give people a trustworthy alternative to ad-driven social media. The company is structured as a Public Benefit Corporation, showing its commitment to long-term public accountability rather than short-term profit. Waldman described the movement behind Gander as “more like a call to arms,” a push to rebuild online spaces around community ownership and digital sovereignty.
BenWaltman, CEO Gander Social:
By setting a minimum investment of $255, Gander is making participation accessible to everyday Canadians. The campaign reinforces the growing “keep it in Canada” mindset that prioritizes domestic ownership, ethical innovation, and sustainable platform design. Investors are not just looking for returns but they want to help define the kind of digital economy they want to see in Canada.
As Canada feels the geopolitical pressures, across the country investors are embracing equity crowdfunding to participate directly in the innovation economy and keep growth capital in Canada. It’s a model that strengthens community engagement while advancing national competitiveness and financial inclusion.
For policymakers and fintech advocates, Gander’s raise demonstrates how equity crowdfunding can mobilize citizens to fund nationally significant ventures. It shows how financial innovation and digital sovereignty can align to strengthen Canada’s independence, resilience, and competitiveness in a global tech landscape increasingly defined by foreign control. Learn more about the Gander Social campaign here.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech | Oct 30, 2025
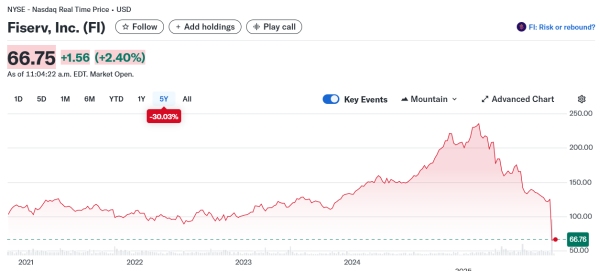
Image: Fiserv (FI) (Yahoo Finance Chart, Oct 31, 2025)
What triggered Fiserv’s record stock crash?
On October 29 2025, Fiserv Inc.’s stock plunged 44 percent in a single trading day after management sharply cut revenue and earnings forecasts. The Forbes report confirmed that guidance for full year organic revenue dropped to roughly 3.5% to 4.5% (down from 10%), and adjusted earnings per share fell to about $8.50 to $8.60 (previous range near $10.25).
Outlets called it the company's worst trading day on record, while Reuters reported that roughly $30 billion USD in market value was wiped out.
The Financial Times reported that some of Fiserv’s problems came from its business in Argentina. The company had invested heavily there to grow its payments and merchant services, but rising inflation and unstable policies hurt results.
Yahoo Finance verified that quarterly adjusted earnings were $2.04 per share on $4.92 billion in revenue, both falling short of analyst estimates, and that management’s revised guidance signalled weaker growth into 2026.
The speed and scale of the decline caught analysts off guard and the abrupt reversal in management guidance spooked investor confidence more than the revenue miss itself.
The credibility hit reflects a governance gap and not a market anomaly. Canadian financial institutions face a similar risk. When boards and risk teams depend too much on vendors’ optimistic projections, they can be caught off guard when results fall short. Honest forecasts, active oversight, and clear accountability are essential to maintain trust.
The slowdown of Fiserv’s merchant processing as noted by Reuters, raised red flags because it showed how much of the global financial ecosystem depends on a handful of vendors for core services.
Canadian credit unions and regional banks operate within similar limits, relying on few providers for payments, fraud monitoring, and digital banking infrastructure. A major vendor’s disruption could ripple through daily operations.
Fintechs should avoid relying on a single provider for critical services. Where possible, they should use multiple vendors or include clear backup and continuity plans in core contracts. A stable vendor network is now part of staying resilient, not just managing costs.
MarketWatch linked Fiserv’s current struggles to its 2019 First Data merger, which left the company with high debt and overlapping systems.
Many Canadian institutions are undergoing similar digital transformations. The Fiserv experience shows that modernization without aligned governance and risk planning can backfire.
Further with respect to Argentina, expanding into fast growing but unpredictable markets can look appealing, but without strong local plans and risk controls, it can backfire when conditions change.
Banks should aim to strike the balance between innovation, cutting costs, and building long term strength. Fintechs on the other hand need to be realistic and transparent with financial reporting and growth goals. Making promises that can’t be met damages trust faster than any technical problem.
Fiserv is undergoing a strategic reset. In a release, the Fiserv appointed Paul Todd as CFO effective October 31, named Takis Georgakopoulos and Dhivya Suryadevara as co-presidents effective December 1, and refreshed its board under new independent chair Gordon Nixon. Two directors will step down on January 1 2026 as part of a governance overhaul. Whether these measures restore confidence remains uncertain.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Financing | Oct 30, 2025

Image: Freepik/rawpixel.com
On October 27, 2025, Wealthsimple announced it had raised $750 million in new equity funding at a $10 billion post money valuation. The deal includes $550 million in new shares and up to $200 million from secondary sales.
Dragoneer Investment Group and GIC led the round, joined by CPP Investments, Power Corporation of Canada, IGM Financial, ICONIQ Capital, Greylock Partners, and Meritech Capital.
Crossing the $10 billion valuation milestone shows how far Canada’s fintech industry has come. Wealthsimple’s steady rise from startup to profitable platform proves that a Canadian firm can reach global scale while keeping its focus on trust, compliance, and user experience. This new round comes at a time when many fintechs worldwide are struggling to raise growth capital.
Wealthsimple has been profitable since 2024 and now manages over $100 billion in assets for more than three million Canadians.
Michael Katchen, CEO and co-founder, Wealthsimple:
“This raise reflects deep confidence from new and returning investors in our mission and our role as a defining Canadian company. We were intentional in choosing partners committed to the long-term future of Wealthsimple. These are well-respected, global leaders with a proven track record scaling category leaders, and who believe in our vision for the future of financial services.”
Choo Yong Cheen, Chief Investment Officer, Private Equity, GIC:
“We look for companies that will transform industries for decades to come, and Wealthsimple is one of them. Their track record of innovation, from investing to trading to spending, combined with deep trust from Canadians, positions them to build a defining, generational company in Canadian financial services.”
Institutional investors such as CPP Investments and Power Corporation bring more than capital. They bring credibility. Their involvement helps normalize fintech as a core part of the financial system, not a novel experiment. This type of institutional participation encourages other large funds to view Canadian fintechs as viable, well governed opportunities for long term growth. It also shows that responsible innovation can attract serious capital without sacrificing values like inclusion and transparency.
Wealthsimple’s record of profitability and compliance gives regulators a real life example that innovation and stability can work together. The company’s consistent performance may help policymakers as they work to finalize the implementation of open banking.
Wealthsimple’s growth story and impact goes beyond one company. It's an achievement that reflects how far Canada’s fintech community has evolved, from early crowdfunding to full service digital banking. It gives startups and investors a reason to believe that they can scale globally while keeping their roots in Canada. For NCFA, this success reinforces the importance of a financial ecosystem that rewards innovation, broadens access to capital, and strengthens Canada’s competitiveness on the world stage.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 30, 2025
Estonia has become one of the most attractive EU hubs for crypto businesses: digital-first processes, e-Residency, and clear MiCA-aligned rules make it ideal for launching compliant exchanges, wallets and custody services.
Thanks to this, obtaining a crypto license in Estonia is profitable, fast, and legal.
Prifinance leverages this environment to deliver end-to-end support - from company formation and AML/KYC frameworks to regulatory communication and post-authorization compliance.
|
Advantages of working with Prifinance |
Numbers |
| Experience in international consulting | 30 years |
| Completed projects | 10,000+ |
| Crypto licenses obtained | 400+ |
| Supported jurisdictions | 40 |
| Successful cases on complex requirements (including MiCA) | 100+ |
| Lawyers, auditors, and consultants | 100+ |
This track record ensures brand reliability and practical experience when you scale in Europe.
A MiCA-compliant Estonian license (CASP/VASP) gives lawful access to the EU market with passporting rights, clear consumer protections, and harmonised reporting requirements. You need this license when your project: accepts fiat/crypto from users, offers custody or wallet services, executes crypto-to-fiat or crypto-to-crypto trades, processes remittances, or markets token sales to EU residents.
Beyond legal permission, the license demonstrates institutional-grade governance - strict KYC, continuous transaction monitoring, secure IT architecture, and appointed compliance officers - which improves access to banking, liquidity partners and institutional clients. These elements are crucial at launch and become non-negotiable as trading volumes, AML scrutiny, or institutional relationships grow.
Why Estonia - practical benefits
We prioritise your brand and market credibility from day one. That means not only preparing an application that satisfies regulators, but also shaping how counterparties and clients perceive you: professional legal structure, transparent ownership, robust compliance policies, auditor-ready documentation, and clear public-facing materials.
Our offering includes: company incorporation in Estonia, preparation of AML/KYC and internal control manuals, recruitment and registration of key personnel, technical security checklists, liaising with the FIU/FSA, and post-license support. By pairing compliance with marketable governance, we help your brand convert regulatory compliance into a competitive asset.
Prifinance works with major banking and fintech partners and maintains long-term relationships with thousands of international clients.
Our partners include leading financial and technology companies such as CIM Banque, Commerzbank, Payoneer, OCBC Bank, Binance, Mashreq, Odav Print, Montify, and Blockchain Life.
Our client feedback and case experience show smooth licensing processes and effective post-license support - a practical advantage when regulators request clarifications or audits.
Visit https://prifinance.com/en/cryptocurrency-license/ to request a tailored licensing plan, get a cost estimate, and start the application process: Prifinance provides full-cycle support for Estonia CASP/VASP applications and post-authorization compliance. Send a request through our site to receive a personalized proposal.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Prediction Markets | Oct 29, 2025

Image: NHL Calder Memorial Trophy example (Polymarket)
On October 22, 2025, the National Hockey League (NHL) announced new multi-year partnerships with Kalshi and Polymarket. It's the first time a major sports league has given prediction markets an official seat at the table.
Both Kalshi and Polymarket will use official NHL data, league marks, and broadcast rights to let fans interact with games through regulated financial platforms. The partnerships show how fintech innovation is breaking into unexpected territory, and why responsible design and governance matters just as much as bold ideas.
Think of a prediction market as a meeting point between finance and curiosity.
People can trade small contracts based on real-world outcomes, such as who will win this year's Stanley Cup or a playoff series? How many goals a team might score? Or whether a player reaches a milestone? The prices of those contracts is based on supply and demand, so they reflect what the crowd believes will happen.
Kalshi operates under the U.S. Commodity Futures Trading Commission (CFTC), while Polymarket began as a blockchain experiment using the Polygon network and USDC stablecoin.
For fans, prediction markets turn watching into participation.
For fintechs, it validates that with the right mix of data, incentives, and community interactions financial tools can become part of mainstream entertainment when framed responsibly. Innovation when paired with trust can educate and expand access, too.
Behind the excitement sits a serious legal question. Kalshi is fighting a federal battle with the New York State Gaming Commission, which insists that its contracts are a form of unlicensed sports wagering. Kalshi argues otherwise. Other regulators in places like Massachusetts and Nevada have voiced similar concerns. Each ruling is a test of whether innovation can coexist with public accountability. The company says federal law gives the CFTC authority, not state gaming boards.
Polymarket’s path has been anything but linear. After paying a $1.4 million CFTC fine in 2022 for operating without registration, the firm earned approval to relaunch in the U.S. in 2025 by acquiring QCEX exchange with a CFTC license.
By changing from a fully decentralized model to one that aligns with compliance standards, Polymarket demonstrated how they could innovate within regulatory frameworks. Now it sits alongside Kalshi as an NHL partner. A fintech built on blockchain that's earned institutional trust by embracing regulation, instead of resisting it.
As covered by the Sports Business Journal, the NHL didn’t jump in blindly. Reports show the NHL consulted regulators and examined consumer protections before agreeing to the partnerships.
Even so, the American Gaming Association called the deal “deeply troubling” (subscription required) warning that fans could confuse regulated markets with gambling. That tension captures a bigger issue facing every fintech today. That is how to innovate responsibly while protecting users. The NHL partnership suggests that fintechs can scale mainstream by demonstrating to regulators And customers that innovation and safety can coexist.
For Canada, the NHL partnership is a glimpse into what the future of participatory finance could look like. Canadian regulators have already been exploring frameworks for digital assets, open banking, and tokenized finance.
Prediction markets fit naturally into that conversation. If handled properly, they could open new avenues for retail engagement and capital formation while reinforcing Canada’s reputation for responsible fintech growth.
Prediction markets are moving from the edges of crypto into the center of participatory commerce. By partnering with Kalshi and Polymarket, the NHL is betting not only on fan enthusiasm but on fintech’s capacity to build trust through transparency. For Canada’s fintech community, the moment reinforces a truth long advocated by NCFA, when innovation, regulation, and inclusion advance together, everyone gains.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016