





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 19, 2026 | NCFA Insight | Capital Markets And Funding, Crowdfunding, Regulation And Policy
On May 16, 2026, U.S. Regulation Crowdfunding (Reg CF) marked 10 years since eligible companies could start raising capital under the SEC’s final crowdfunding rules. Our colleagues at Crowdfund Insider posted New 10 year Reg CF data from Crowdfund Capital Advisors (CCA) providing the market with a full decade of evidence, certainly something rare in early stage finance.
For NCFA and its community, this milestone deserves attention, since the association has supported investment crowdfunding through advocacy, education, market intelligence, and ecosystem building for well over a decade. In 2022, Fintech Fridays hosted a special episode on 10 Years of Investment Crowdfunding, focused on the JOBS Act. This 2026 anniversary is different because it's been 10 years since Reg CF actually went live.
The data suggests that a meaningful portion of companies using Reg CF were not just raising money once and disappearing. CCA reviewed 10,771 offerings by 8,955 issuers, and 6,063 issuers completed 7,459 offerings. Those numbers show a market with repeat activity, not just one off campaigns.
The revenue data sends a stronger business signal. Among issuers with three or more revenue data points, CCA reports 27% median annualized revenue growth, with 70% growing revenue and a 1.81x median revenue multiple. This means many companies with enough reporting history showed measurable operating growth after raising capital through crowdfunding. That supports the case that Reg CF financed real businesses, not only speculative startups.
Among issuers that raised multiple rounds, CCA reports a 24% median valuation CAGR, a 1.54x median valuation step up, and valuation increases for 79% of multi round issuers. That suggests many repeat issuers returned to the market with stronger investor validation and higher implied company value.
The repeat raise numbers are important too. More than 7,400 successful offerings from about 6,000 issuers suggests a meaningful number of companies returned to the market more than once. That points to crowdfunding evolving beyond one time community fundraising into an ongoing capital formation channel for some businesses.
Sherwood Neiss, Principal, Crowdfund Capital Advisors:
“A decade of actual market data tells a completely different story.”
That sentence captures why this milestone matters. Reg CF didn't replace venture capital like many suggested. It didn't solve every funding gap, but it democratized and proved that regulated online capital formation can support real issuers, real investor participation, and measurable growth over time.
The strongest data point is not only the growth metrics. It's now also about discipline. CCA separates issuers that keep reporting and return to the market from those that disappear from the data. It's important because transparency creates trust. A crowdfunding market cannot mature if investors, platforms, regulators, and researchers cannot track performance after the raise.
CCA reports that there's a large compliance gap in reporting. Among 5,077 Reg CF issuers with active annual reporting obligations, only 301, or 5.9%, are fully current. Another 32.4% are partially current, while 61.7% are not current. It's a gap that needs to be fixed. It is a reason to modernize reporting, reduce unnecessary friction, and build better data infrastructure.
Canada should use the Reg CF 10 year milestone to modernize investment crowdfunding. The current $1.5 million 12 month issuer cap under National Instrument 45-110 now acts as a real constraint for stronger companies, especially when campaigns can approach the limit before meeting full market demand. NCFA has long argued that Canada risks falling behind international peers that raised their crowdfunding limits years ago, including the U.S., which increased the Reg CF cap to USD $5 million in 2021.
Canada should raise the issuer cap, index it to inflation, and create a higher fundraising tier for issuers that meet stronger disclosure, financial reporting, and portal due diligence standards. NCFA has also previously advocated for right sized disclosure rules, including director and officer certified financial statements for smaller raises, reviewed financial statements for mid sized raises, and audited financials only for larger raises where the added cost is proportionate.
Investor participation rules also need modernization. Canada should review the current retail investment limits, allow greater participation from experienced and repeat crowdfunding investors, and explore a knowledge based or self certified investor category with appropriate safeguards. A modern private capital market should not assume that all retail investors have the same risk profile, sophistication, or investing experience.
Structural incentives would help strengthen the market further. Canada should explore clearer pathways for TFSA and RRSP eligibility where appropriate, support secondary market liquidity after holding periods, and encourage co investment structures that allow funds, angels, and retail investors to participate together in compliant online financings.
Canada needs standardized campaign data, stronger post raise reporting, issuer education, and technology enabled compliance for KYC, background checks, risk warnings, issuer updates, and ongoing disclosure. NCFA previously covered why Reg CF data quality matters. If regulators and policymakers rely on incomplete reporting data, they risk misunderstanding how capital actually forms, performs, and scales through online private markets.
A stronger crowdfunding market doesn't require weaker oversight. It requires smarter rules, better data, and a funding framework that reflects how modern private capital forms online.
The 10 year Reg CF story is evidence that digital investment markets can widen participation, support early stage companies, and create a more transparent private capital market. The next phase should focus on quality, not just volume. Better issuer readiness, clearer post raise reporting, credible data, secondary liquidity experiments, and stronger investor education can help crowdfunding move from alternative finance into core capital formation infrastructure.
For NCFA, this is also a moment to recognize the builders, platforms, lawyers, advocates, educators, investors, and founders who kept pushing when the market was dismissed as too small or too risky. Reg CF at 10 shows that the model works when policy, platforms, and market discipline move together. Canada should not watch from the sidelines at a time when more capital needs to flow.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Apr 29, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Banking And Credit Infrastructure

On Apr 29, 2026, KOHO launched KOHO Crypto powered by Ndax, giving users a way to buy, hold, and manage digital assets inside the KOHO app. KOHO brings crypto trading into a money management app already used by more than 2.5 million Canadians.
The pricing is the main user hook. KOHO Crypto starts at 0.5% per trade for KOHO Everything members, 1% for Extra and Essential members, and 1.5% for non members. Users can start with as little as $1, access more than 20 crypto assets, and fund purchases instantly from their KOHO balance.
KOHO is also using an incentive to bring existing Bitcoin holders into the app, offering a limited time 3% BTC transfer match up to $150 for eligible Bitcoin moved into KOHO powered by Ndax.
| Feature | KOHO Crypto | Wealthsimple Crypto |
|---|---|---|
| Base trading fees | 0.5% to 1.5% based on KOHO plan. Users can start with $1. | 2.0% for Core, 1.0% for Premium, and 0.5% for Generation. |
| Volume pricing | KOHO does not list volume tiers on its crypto page. | Volume based fees can fall to 0.05% for $10M+ in 30 day crypto trading volume. |
| Current incentives | Limited time 3% BTC transfer match, up to $150. KOHO pays the matched amount in CAD after 12 months. KOHO reimburses trading fees after 90 days for eligible transfers over $1,000. | Wealthsimple charges no trading fee on USDC bought or sold with USD. Wealthsimple also charges no trading fee on recurring crypto purchases through automated paycheque investing. |
| Funding and FX | Users fund trades from a KOHO balance. KOHO says all coins pair with CAD, with 0% FX fees, no hidden spreads, and no unexplained markups. | Users can place trades in CAD or USD where Wealthsimple supports it. Wealthsimple says it uses its corporate FX rate when CAD settlement requires conversion, and includes that cost in the trading fee. |
| Transfers | KOHO currently limits external transfers to one way Bitcoin deposits. KOHO does not yet support transfers out. | Wealthsimple supports a broader crypto account setup, with trading, swaps, recurring purchases, and staking where available. |
| Staking | KOHO does not yet offer staking. | Wealthsimple charges staking fees of 30% of rewards for Core and Premium clients, and 15% for Generation clients, plus applicable validator fees. |
| Custody and regulation | Ndax, a CIRO member, powers the product. KOHO says qualified custodians hold at least 80% of client crypto, with a smaller amount in operational wallets. | Wealthsimple Crypto operates inside Wealthsimple’s broader regulated investing platform and fee schedule. |
| Platform strategy | KOHO embeds regulated crypto access inside a daily money app where users already spend, save, borrow, and build credit. | Wealthsimple places crypto inside a broader wealth and investing platform, where pricing improves with client tier, trading volume, and account depth. |
The comparison shows two different cross sell strategies. KOHO is using crypto to deepen a daily money relationship, with low entry size, CAD pricing, and a Bitcoin transfer incentive aimed at existing holders. Wealthsimple is using crypto inside a wealth platform, where pricing improves with account tier, trading volume, and wider product depth. KOHO’s advantage is access from a spending balance. Wealthsimple’s advantage is depth for investors already using its trading and wealth products.
Many crypto platforms still require users to transfer funds out of a banking or spending account before trading. KOHO keeps the experience inside the same app people already use for spending, saving, and building credit. It also removes foreign exchange friction by pricing transactions in Canadian dollars.
Daniel Eberhard, CEO, KOHO:
“Access has been one of the biggest barriers for the average Canadian to dive into crypto. We’re also seeing growing demand from people who want more flexible ways to build wealth, especially at a moment when financial pressure and instability are high. By bringing crypto into an environment Canadians already trust, we’re making that access more practical and aligned with how people actually manage their money.”
Calgary based Ndax provides the regulated trading infrastructure and custody framework behind the product, while KOHO controls the customer interface. In this way, KOHO doesn't have to become a standalone crypto exchange to offer digital assets. It can embed regulated trading into its financial platform.
The timing fits Canada’s regulated fintech buildout. KOHO registered as one of the first Canadian fintech payment service providers under the Retail Payment Activities Act in 2025 and later became a Payments Canada member as a supervised PSP. These are important qualifications because consumers now trust fintech apps with more of their financial lives.
Crypto demand remains real, but trust is still uneven. The CSA 2024 Investor Index found that crypto assets are among the six most commonly held investment types in Canada, with 33% of investors under 35 reporting crypto asset holdings.
For KOHO, the product expands wallet share. For Ndax, it opens distribution through a consumer finance app with national reach. For Canadian fintech, the trend is clear. Regulated crypto access now sits inside existing financial apps instead of forcing users into separate trading venues.
Will crypto access in Canada grow less through standalone exchanges and more through trusted financial apps? The hard part is giving users simple access without turning everyday money tools into speculation funnels.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA works with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 28, 2026 | NCFA Fintech Insight | Capital Markets And Funding
Image: Freepik/DC Studio
On April 27, 2026, Prime Minister Mark Carney launched the Canada Strong Fund, calling it Canada’s first national sovereign wealth fund. Ottawa will seed the fund with $25B over three years and invest alongside private capital in Canadian projects tied to energy, critical minerals, infrastructure, advanced manufacturing, transport, data, telecommunications, and other national priorities.
The Canada Strong Fund is an attempt to change how Canada builds. The constraint isn't only capital. It's the shortage of investable assets that meet institutional standards on returns, timing, governance, approvals, and scale. Canada has capital but it has fewer projects that investors can underwrite with confidence compared to global peers.
The Rt. Hon. Mark Carney, Prime Minister of Canada:
"Through the Canada Strong Fund, all Canadians will have the opportunity to share directly in these benefits.”
Canada’s capital problem shows up as fewer productive assets and weaker productivity. Workers operate with fewer productive assets than peers in the United States and across the OECD. C.D. Howe Institute research shows that investment capital per worker is falling. In 2025, investment per worker in Canada is expected to be about 70% of the OECD average and about 55% of US levels.
The gap is larger in the areas that matter most for productivity. In 2024, Canada invested only about 41% as much as the US in machinery and equipment per worker, and about 32% as much as the US in intellectual property. Software investment per worker is about half US levels, while US research and development spending is roughly four times higher.
The gap is real and shows up in the economy. Canadian companies operate with fewer machines on the floor, less software across teams, and fewer systems they can scale. The Canada Strong Fund aims to close that gap by turning national priorities into projects investors can back with real capital.
The Canada Strong Fund will be seeded by the government with $25B over three years, but the outcome still depends on discipline.
Who's going to invest? Pension funds, infrastructure funds, banks, insurers, private credit, sovereign funds, and strategic corporates all have the capacity to deploy capital. Finance Canada says Canadian pension funds hold over $3T in assets.
Projects need to make money, get approved without long delays, and run with clear rules that keep politics out of investment decisions. Finance Canada says the fund will target market rate returns, operate at arm’s length through a Crown corporation, and focus mainly on equity investments. That helps align the fund with private investors. If execution slips, that alignment can break down quickly.
Alberta offers a provincial reference point launching the Heritage Savings Trust Fund in 1976, which grew from $1.5B to $31.9B by Dec 31, 2025. Over time, it also contributed more than $45.8B to public spending. That supported public priorities, but it limited compounding. A sovereign wealth fund cannot build long term national wealth if returns are regularly redirected to annual budgets.
Ottawa has also signalled a potential retail investment product that would allow Canadians to participate directly. Retail access requires clear disclosure, defined liquidity, strong suitability controls, and consistent reporting. Public participation raises the standard for execution.
On Apr 28, the federal government released the 2026 Spring Economic Update putting the Canada Strong Fund inside a broader build agenda. Capital is only one constraint. Canada also needs workers, approvals, governance, reporting, and project discipline.
Finance Canada says Team Canada Strong aims to recruit, train, and hire 80,000 to 100,000 skilled trade workers by 2030 to 2031. That matters because housing, infrastructure, energy, and major projects need enough skilled workers to turn capital into real assets.
For fintech and alternative finance, the practical role is retail access. If Canadians can invest in national projects, the experience needs to be simple, trusted, and clear. People need to know what they are buying, how risk is explained, how many flows in and out, and what kind of reporting they can expect after they invest.
Can Ottawa help build more productive assets while maintaining commercial discipline and public trust? If it can, the fund can help close Canada’s capital formation gap and give Canadians a direct stake in national wealth creation. If it cannot, Canada risks creating another financing structure that absorbs capital without improving how the country builds.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 14, 2026
Image: Freepik
The online gambling scene is shifting, with players moving away from classic reel slots toward more dynamic games. TV shows stand out because they make you feel part of a live broadcast. Both new and experienced Casoola Casino players enjoy them for the interactive experience without needing to learn complex rules. In this space, Lucky Wheelioinaire from Imagine Live has become a top choice, outpacing traditional slots in popularity.
Lucky Wheelioinaire is a live game in the format of a television show from Imagine Live. This provider specialises in live content with an emphasis on visual presentation and simple rules. Although Lucky Wheelioinaire is a relatively new gaming product, it fits perfectly with the trend of recent years, in which the key role is played not by mechanics but by gamblers' emotions. At its core, the game is all about a spinning wheel, and the result comes down to which sector it stops on. Casoola Casino Online players adore Lucky Wheelioinaire for its dynamic live atmosphere and fast results.
At first glance, Lucky Wheelioinaire follows the familiar mechanics of a spinning wheel, but there are a number of details that distinguish it from its competitors:
This combination makes Lucky Wheelioinaire accessible to both beginners and experienced players. This makes it more popular than similar classic formats with the same mechanics.
Lucky Wheelioinaire is based on a clear sequence of actions, uncluttered with unnecessary mechanics. To experience a unique gaming experience, Casoola Casino Online players need to complete the following steps:
This structure makes the game logically predictable but unpredictable in its outcome. This makes Lucky Wheelioinaire accessible even to beginners with no experience.
Overall, Lucky Wheelioinaire demonstrates how a live format can be adapted to the needs of gamblers at Casoola Casino Online and other leading gambling platforms. The game doesn't require a complex setup, yet it retains the dynamic, show-like feel of being part of a show. This combination explains its growing popularity among Canadian gamblers.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 13, 2026 | NCFA Insight | Wealth Investing And Trading, Public Sector Policy And Industrial Strategy
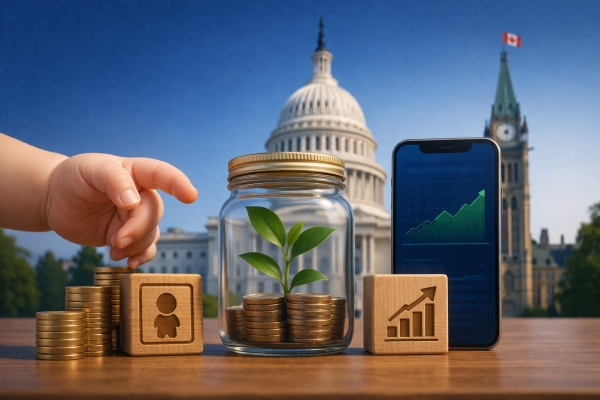
On April 6, 2026, US Treasury announced BNY will serve as financial agent for Trump Accounts and Robinhood will act as brokerage and initial trustee. Treasury will also retain control over the initial app and account operations. That structure combines public funding with private platform delivery from day one.
Trump Accounts are proposed government seeded investment accounts for children with funds held in low cost diversified investments over a long time horizon. The account terms are clear. $1,000 initial contribution for eligible children born between 2025 and 2028 if a parent or guardian files the required election and establishes the account. The U.S. recorded about 3.6 million births in 2025. That gives the program the potential to direct roughly $3.6 billion a year into newborn accounts before any additional family or employer contributions.
Vlad Tenev, CEO, Robinhood:
“It puts us in front of the next generation of investors.”
Governments don't build programs like this just to encourage saving. They also want increased market participation, earlier household asset formation, and a stronger connection between citizens and capital markets. The platform gets early distribution, early familiarity, and a better shot at keeping the user relationship when the child becomes an adult investor.
Robinhood will provide trustee and brokerage services, while the US Treasury says the app is being built as a custom white label product for the government. So this isn't the usual bank branch or advisor channel look and feel, but rather a state backed account delivered through a digital product stack.
The natural question is could it work here in Canada, which already supports early saving, but the model is different. RESP assets reached $89.8 billion at the end of 2024. RESPs (Registered Education Savings Program) are opened through financial institutions such as banks, financial planners, scholarship plan dealers, and insurance companies. it has wide distribution and access, but it doesn't create a single national interface or give one platform a government backed starting position.
A Canadian version built on one fintech or brokerage would not just add another savings product. It would simplify delivery and reduce administrative complexity, but it would also concentrate distribution. The firm responsible for onboarding, app design, and long term account interaction would gain a durable role in the household financial relationship. A multi provider model would support competition and choice, but it would be harder to coordinate at scale and slower to implement. It's a trade off of any policy decision in programs that combine public funding with platform delivery.
Other countries show both the appeal and the operational risk. In February 2026, HMRC said 758,000 Child Trust Funds remained unclaimed and average balances were £2,242. The policy succeeded in creating accounts. It was less successful at keeping every user connected to them. That is a useful lesson for any government thinking about seeded accounts today.
Government seeded accounts do more than promote saving. They decide who gets first access to the customer relationship. In Canada, that would be the real policy choice. Not whether to support early investing, but whether to hand long term distribution power to a platform.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 13, 2026

Most modern slots feature wild symbols. Players at gambling sites like Casino Online Pistolo Casino look forward to these symbols appearing on the screen, as they award additional wins and are accompanied by interesting visual effects. Users should be aware of this game element. Below, we'll discuss how wild symbols work.
In video slots, the wild symbol originally replaced other symbols, similar to how jokers work in card games. If four identical symbols appear on an active payline along with the wild symbol, the combination will award a win as if five identical symbols appeared on the screen. Players should remember that the wild symbol can only substitute for standard symbols. It cannot be used as a Scatter or bonus symbol.
Let's look at some features of wild symbols.
If users want to know how the wild symbol works in a particular game, they should consult the paytable.
The ability to substitute for other icons is a key aspect of the wild symbol in Casino Online slots. Still, some developers add additional features that make this symbol even more useful. Below, we'll analyze the basic types of wild symbols.
As we can see, the wild symbol in Casino Online increases users' chances of success. It turns an unsuccessful spin into a winning one. This feature is especially useful in bonus rounds, where the appearance of such a symbol can provide additional multipliers.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 31, 2026
Crypto casino gaming now moves billions of dollars every year. Many players prefer these sites because they use provably fair technology, allow fast blockchain withdrawals, and offer games designed specifically for cryptocurrency betting. With the right site and game, players can verify outcomes and track exactly what happens to every wager.
The online gambling market is projected to surpass $100 billion by 2026, and crypto casinos continue to gain market share. Players are increasingly drawn to transparent systems, quick withdrawals that settle in minutes rather than days, and games whose outcomes can be verified.
Some of the most popular crypto casino games today include crash multiplier games, provably fair Plinko, high-volatility themed slots, modern 3D slot titles, and live dealer roulette with multiplier bonuses. Each offers a different style of gameplay and risk level.
This guide covers five of the most popular crypto casino games in 2026. All of them appear on licensed sites with fairness verification systems, fast crypto withdrawals, and active player communities.
Choosing the right crypto casino game requires understanding a few key factors.
The following five games are widely played by crypto casino users in 2026:
Each represents a different type of gameplay, from multiplier betting to slots and live dealer experiences. Let’s start:
Best for: Players who enjoy fast rounds and transparent outcomes.
Standout feature: A very low house edge combined with provably fair verification for every round.
Best for: Players seeking frequent payouts and unique slot mechanics.
Standout feature: A rare slot format where characters appear from underground instead of spinning reels.
Best for: Players looking for a high-volatility slot with the possibility of large multiplier wins.
Standout feature: Stacking multipliers combined with cascading reels and a maximum payout exceeding 21,000x the original bet.
Best for: Players who prefer simple gameplay with strong transparency.
Standout feature: Flexible risk settings combined with high RTP and full outcome verification.
Best for: Players who enjoy live dealer experiences combined with high multiplier potential.
Standout feature: Random lightning multipliers that dramatically increase payouts on selected numbers.
A trustworthy license ensures player protection and fair payouts. Always confirm the casino is regulated before depositing cryptocurrency.
High-volatility games may produce huge wins but also long losing streaks. Select games that fit your budget and risk tolerance.
Provably fair technology allows players to verify that outcomes were generated before the wager was placed, improving transparency.
One advantage of crypto gambling is fast payouts. Choose sites that process withdrawals quickly so winnings can be accessed without delays.
Some bonuses exclude certain games from wagering contributions. Reading the rules first prevents unexpected restrictions.
Transparency is one of the main reasons crypto casino gaming continues to grow. Provably fair algorithms and publicly listed RTP values allow players to analyze games before placing bets. This level of accountability is uncommon in traditional online casinos.
Selecting the right game involves more than choosing the biggest bonus or flashiest design. The most important factors are volatility, bankroll compatibility, fairness verification, and withdrawal reliability.
Before depositing, always confirm the site’s license and payout speed. Those checks ensure that when you win, your funds are secure and accessible.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
