




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


April 24, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Regulation And Policy, Artificial Intelligence And Data

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026).
RBI has moved from restriction to licence cancellation. Payments banks, wallets, sponsor banks, and fintech platforms should treat this as a hard reminder that governance, compliance controls, depositor protection, and supervisory responsiveness decide whether a regulated licence survives under stress.
Instant payments are starting to add shared, rail-level risk intelligence. Banks and vendors that can plug network signals into fraud controls and payment decisioning will gain speed without giving up control.
The UK is pulling payments reform, stablecoins, open banking, and AI-agent payments into one policy agenda. That gives banks, fintechs, and infrastructure firms a clearer build direction for the next phase of digital money and payment rails.
The PACE Act would move direct rail access from a bank only model toward a supervised nonbank pathway. Payment firms, wallets, remittance providers, and crypto platforms should watch whether Congress turns scale, reserves, and OCC oversight into the price of direct Fed access.
The fee cap changes the economics of Canadian order flow in securities traded on both sides of the border. Marketplaces, brokers, and trading firms need to revisit rebate models, routing logic, and best execution analytics before Nov 2026.
The SEC and CFTC are reducing reporting load while keeping coverage of the largest funds. That lowers compliance cost for smaller firms and shifts the reporting system toward large, systemically relevant managers.
Treasury clearing is now forcing decisions on affiliate repo, cross border booking, liquidity management, and contingency planning. That puts market structure, funding, and clearing operations under live pressure ahead of the compliance dates.
Finfluencer enforcement is now coordinated across jurisdictions and aimed at the platforms as well as the promoters. That raises the compliance and monitoring burden for firms using social channels for distribution and puts more pressure on platforms to block illegal promotions at source.
Client money control failures are still drawing fast and expensive action. Firms handling safeguarded funds need clean role separation, approval controls, reconciliations, and evidence trails that hold up under review.
SMCR reform is now moving from policy into implementation. Banks, fintechs, and regulated firms need to update role mapping, certification processes, accountability records, and reporting workflows without leaving control gaps during the transition.
The rule change is now live. Fund managers, administrators, auditors, and reporting vendors need to update related party reporting workflows and disclosure logic from this reporting cycle forward.
This gives firms a live FCA pathway for AI in production. Providers building AI for payments, risk, compliance, and customer decisioning now have a clearer read on how regulators expect live testing, monitoring, and evidence to be handled.
The UK is refining its crypto framework before implementation to ensure stablecoin payments work within regulated financial systems. For fintechs, this points to a clear direction: stablecoins are moving into formal payment rules, not operating outside them.
OSFI is aligning regulatory reporting with IFRS 18. Insurers, auditors, and regtech providers will need to update reporting systems, data classification, and validation processes ahead of the 2027 transition.
Australia is moving digital asset platforms from patchwork treatment into a licensing regime with custody, settlement, market conduct, and financial resource expectations. For exchanges, brokers, custodians, and tokenised custody platforms, this raises the operating floor before the regime starts in 2027.
N3XT puts tokenized bank money directly onto blockchain rails while retaining the deposit relationship with the issuing institution. That operating model now sits beside tokenized deposits for corporate treasury being developed by much larger banks, but N3XT entered the market with a live product built around continuous settlement from the outset. The difference between bank issued deposit tokens and reserve backed stablecoins is becoming commercially relevant as both compete for institutional payments, liquidity and onchain settlement.
This puts focus on how firms log interactions, flag risk, assign review, and retain records. See related coverage on AI escalation controls and AI chat exposure in court.
Fintech execution is getting more technical and less forgiving. Payments now need network-level risk data. Markets need tighter routing, clearing, and reporting controls. AI and social distribution need evidence, safeguards, and audit trails. The advantage belongs to firms that can turn regulatory change into product, compliance, and infrastructure readiness faster than competitors. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
April 22, 2026

Canada's online casino sector enters 2026 as one of the most data-rich verticals in the country's digital economy. Ontario's private-operator framework, open since April 2022, has pushed annual online wagering past CAD 82 billion, and Alberta's own private-operator market went live in mid-2025 with a similar structure. That volume, combined with the card-level telemetry operators already collect, has turned Canadian online casinos into an obvious testbed for the same AI and personalisation stack that Canadian fintech has been building on the wealth and payments side for the past five years.
The practical effect is visible in how bonuses are priced, how promo codes are matched to players, and how casino brands like LeoVegas Canada, Casumo Canada, BetVictor Canada, Spin Casino, and Jackpot City now decide what welcome offer a new sign-up sees on their first visit. What used to be a flat welcome package pinned to a homepage banner has turned into a dynamic offer grid, served in real time and recalculated every few hours. For a fintech audience, the interesting part is not the marketing itself but the underlying bonus-matching engines, player-lifetime-value models, and payment-rail integrations with Interac e-Transfer, Trustly Canada, iDebit, and Instadebit that quietly power the whole experience.
Canadian players who want to compare the current welcome packages side by side typically start with an independent directory that aggregates the active casino promo codes in Canada across licensed operators, because those listings surface the wagering requirement, game weighting, expiry window, and maximum cashout on a single screen instead of forcing a tab-by-tab review of each casino's terms page. This kind of structured comparison data is also what AI matching engines on the operator side ingest to benchmark their own promo pricing.
Three market structures now coexist in Canada. Ontario runs a private-operator model where licensed brands such as 888casino Canada, Betway Canada, BetVictor Canada, LeoVegas Canada, Casumo Canada, and PokerStars Canada compete directly for the same players. Alberta replicated that framework in mid-2025, bringing a second province into private-operator territory. British Columbia and Quebec remain on provincial-lottery-only models through PlayNow and Loto-Québec, which means their promo code economics are set centrally rather than by a competitive operator cohort. The Canadian Criminal Code remains the underlying legal framework, and Bill C-218 opened single-event sports betting across the country in 2021, which is what allowed the Ontario and Alberta casino frameworks to attach parlay and live-bet products to their core slots and table offerings.
Market sizing estimates vary, but the consensus range for Canadian online casino gross gaming revenue in 2025 is roughly CAD 2 billion, with Ontario contributing the majority and Alberta ramping from a standing start. That revenue is spread across more than forty active operator brands in Ontario alone, which is why differentiation has moved away from headline bonus size and toward how well an operator's personalisation stack matches the right promo code, game recommendation, and deposit path to the right player at the right moment. Betano Canada and Pinnacle have also expanded their Canadian casino and sportsbook cross-sell in parallel, which has pulled more recreational players into the online casino funnel and given operator analytics teams a broader behavioural sample to train bonus models on. The practical upshot is that a Canadian casino player in 2026 sees a promo code grid that has been silently AB-tested against thousands of similar players in the same cohort.
A Canadian casino promo code is a short alphanumeric string that maps to a specific bonus configuration inside the operator's offer management system. The headline number on a landing page is only the first of roughly seven parameters a player actually needs to read. The real economic value of a promo code is determined by wagering requirement, game weighting, minimum-odds restrictions on any sportsbook portion, expiry window, maximum cashout, maximum bet per spin while the bonus is active, and whether the bonus is sticky or non-sticky relative to the deposit.
Independent aggregators that publish a current list of casino promo codes in Canada normalise all seven parameters across operators so the comparison is apples-to-apples. That matters because a 200 percent match with a 50x wagering requirement on slots-only is almost always worse in expected value than a 100 percent match with 25x wagering and a broader game mix, even though the first number looks larger. The aggregator model is also why operators increasingly price their bonuses against competitive benchmarks rather than against last year's internal calendar.
Promo Code Structure Comparison Across Canadian Operators
| Operator | Welcome Offer Type | Typical Wagering | Expiry | Max Cashout |
| LeoVegas Canada | Match + free spins | 35x bonus | 14 days | CAD 5,000 |
| Casumo Canada | Match + spins tiered | 30x bonus | 30 days | CAD 2,500 |
| BetVictor Canada | Match, sticky | 40x bonus | 7 days | CAD 1,000 |
| Spin Casino | Staggered match over deposits | 50x bonus | 7 days | CAD 10,000 |
| Jackpot City | Match on first deposit | 50x bonus | 7 days | CAD 7,500 |
| 888casino Canada | Match + no-deposit spins | 30x bonus | 14 days | CAD 2,000 |
The shift from static welcome packages to dynamic offers runs on two model families. The first is the bonus-matching engine, which takes a prospect's acquisition channel, device, deposit method, and early-session behaviour, and returns the specific promo code variant that maximises conversion to a first deposit without eroding contribution margin. The second is a player-lifetime-value prediction model that uses the first seven to fourteen days of activity to estimate a twelve-month net revenue figure, which then feeds into reload-bonus pricing for that specific player.
Canadian operators building these stacks rely on many of the same research groups that serve the country's wealthtech sector. The Vector Institute in Toronto, Mila in Montreal, and Amii in Edmonton all produce graduates who move between fintech and iGaming roles, and the Pan-Canadian AI Strategy has funded infrastructure that both sides use. For a closer look at how the same personalisation techniques travel across Canadian financial services, NCFA coverage of AI-powered personalisation in financial services walks through how AI-driven customer profiling has matured on the banking and payments side, and the parallels to how a casino's offer engine behaves are direct.
Promo code mechanics only work if the money moves fast enough to support them. In Canada, Interac e-Transfer is the dominant deposit rail for online casinos, with Instadebit, iDebit, Trustly Canada, Visa Direct, and PaySafe vouchers filling the rest of the mix. Trustly Canada's Pay N Play integration has been particularly consequential because it folds identity verification and account funding into a single flow, which cuts the time between a promo code redemption and an active bonus balance to seconds.
AI is now layered onto the payment rail itself. Operators use fraud-scoring models at the deposit step to separate genuine first-time players from bonus abusers who cycle through cards and e-wallets to farm welcome offers. The same models flag suspicious withdrawal patterns on the way out, which keeps the house edge on promo code economics intact and protects the operator's ability to keep offering aggressive welcome packages. Payment speed also influences which promo code a player actually claims: a 48-hour payout rail cannot realistically support a low-wagering no-deposit bonus the way a near-instant rail can.
Payment Rails Used by Canadian Online Casinos
| Payment Rail | Typical Deposit Speed | Typical Withdrawal Speed | Common Minimum |
| Interac e-Transfer | Near-instant | 4 to 24 hours | CAD 10 |
| Trustly Canada (Pay N Play) | Near-instant | Same-day possible | CAD 20 |
| Instadebit | Near-instant | 1 to 3 business days | CAD 10 |
| iDebit | Near-instant | 1 to 3 business days | CAD 10 |
| Visa Direct | Near-instant | 1 to 3 business days | CAD 10 |
| PaySafe voucher | Near-instant | Withdrawals routed elsewhere | CAD 10 |
The same behavioural data that powers bonus targeting also powers the responsible-play side of the stack. Canadian operators now deploy intervention models that flag rapid deposit escalation, loss-chasing sequences, overnight-session clustering, and sudden increases in average bet size. When the model's confidence crosses a threshold, the player sees a soft intervention such as a session-time prompt, a temporary deposit-limit suggestion, or a cooldown. The better implementations combine this with a visible self-exclusion path and an option to route the player to not-for-profit support services.
The interesting design question is how aggressively a promo code engine should be allowed to retarget a player who has just been flagged by the responsible-play model. Mature Canadian operators suppress bonus outreach entirely for flagged players for a defined cooldown, which means the personalisation stack has to accept constraints from the safeguarding stack. That alignment is what separates a credible 2026 operator from a legacy brand that bolts AI onto the marketing side without touching the player-protection layer. Canadian self-exclusion infrastructure such as Ontario's centralised self-exclusion registry and the provincial options available elsewhere give operators a clean technical handoff, but the editorial question of when to pause a promo code feed and when to resume one remains a live product decision. The operators who get that decision right tend to be the ones whose responsible-play and marketing teams share a single dashboard rather than two competing ones.
Year three of Ontario's private-operator market has settled into a clear pattern. Headline bonus inflation has slowed because the top operators all benchmark each other's promo codes weekly, which compresses the spread. Differentiation has shifted to game mix, exclusive studio content, loyalty program design, and payout speed. Smaller operators compete on tighter niches such as live-dealer-first, crash-game-first, or sportsbook-forward cross-sell into casino. Alberta's first year has mirrored Ontario's first year almost exactly, with the same operators leading market entry and the same promo code archetypes being tested.
For a detailed trade-press view of how competition has evolved since launch, BetaKit's one-year review of Ontario's iGaming market tracks the operator-by-operator dynamics and the strategic moves brands have made as the market has matured. The piece also covers how acquisition costs have climbed as the top of the funnel has thickened, which is another reason operators have leaned harder on AI-driven personalisation: when paid acquisition gets more expensive, the economic return on better onsite matching goes up in lockstep.
Product roadmaps at Canadian online casinos in 2026 are converging on a shared set of bets. Bonus-matching engines are moving from rule-based to model-based, with reinforcement learning being tested by several of the larger brands to optimise long-run player value rather than next-deposit conversion. Loyalty programs are being redesigned so that tier progression reflects sustained healthy play rather than raw volume, which is partly a response to public scrutiny of high-roller economics. Affiliate and aggregator relationships are being renegotiated as attribution models get smarter at identifying which promo code exposures actually drive incremental first-time deposits.
The cross-pollination with Canadian fintech is the quiet through-line. The same engineers who built real-time fraud scoring for Interac and the same research groups that trained the underlying models are now shipping features into Canadian casino platforms. For fintech founders watching the space, iGaming is a useful mirror for what happens when a regulated consumer market gets large enough to justify a full personalisation stack, what the unit economics look like once that stack is live, and what the operational constraints feel like when the safeguarding layer and the growth layer sit on the same data.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 17, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure
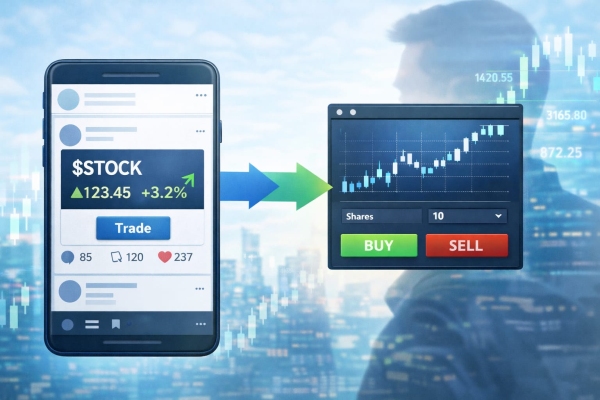
On April 15, 2026, Wealthsimple confirmed integration with X Smart Cashtags. Canadian users can tap a ticker in X and go straight to that security’s detail page in Wealthsimple. Signed-in users land on a screen ready to review or trade. In other markets, Cashtags show real firm data and discussion, but don't yet connect directly into a brokerage.
X now keeps price charts, asset context, and related posts inside the feed. Users can check the setup without leaving the platform. Wealthsimple captures the order once the user decides to trade. X product leadership also showed the flow publicly in this product demo on X.
𝕏 has always been the best source of financial news for traders and investors. Billions of dollars are allocated every day based on what people read on Timeline.
Today we're launching our new Cashtags feature in the US and Canada on iPhone, bringing real-time financial data to… pic.twitter.com/c8s7X9gHTO
— Nikita Bier (@nikitabier) April 14, 2026
Social trading platforms have linked discussion and execution for years. What’s different here is the handoff. X holds the user inside the conversation, shows live market context, and then routes directly to a brokerage when intent is already formed.
That changes where brokerages compete. They no longer control discovery from start to finish. X controls attention and early decision-making. Wealthsimple captures execution after that point.
It's an important evolution. If discovery keeps integrating onto social platforms, brokerages will rely less on brand-led acquisition and more on conversion at the moment of trade. Speed, pricing, reliability, and trust start to matter even more once the user arrives ready to act.
Wealthsimple gains distribution from a high-attention platform where market conversations already happen. It also depends on X for that flow. The partnership trade-off will become more important when competition ramps up as other platforms build similar yet differentiated models that turn brokerage apps into downstream execution layers.
X has been heading in this direction for years, and has steadily added financial data, market context, and navigation into one surface. Smart Cashtags push conversations about markets further to where trades begin.
Interestingly, as more brokers plug into the same surface. Feeds may become more responsive to user behaviour. If that happens, X doesn't need to become a regulated brokerage, because it only needs to control the point where intent forms and connects.
Canadian regulators are already addressing this type of activity. CSA and CIRO guidance makes it clear that securities laws apply when online content influences investment decisions, including cases where users are directed toward trading platforms.
The model itself is allowed, but closer links between content and execution are likely to draw more scrutiny as expectations around disclosure and influence continue to tighten.
In this case, a post, a cashtag, and a direct path to a trade sit in the same flow. That makes it harder to separate general information from something that could be viewed as influencing a transaction.
Responsibility isn't just with creators alone. Platforms that present the content and connect users, along with the brokerages that execute the trade, may face closer scrutiny as these connections become more direct.
Social platforms are starting to control where intent forms, while brokerages compete to capture execution once that intent is already there.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 20, 2026 | NCFA Insight | Capital Markets And Funding, Regulation And Policy
On April 15, 2026, Europe’s largest private market investment platform Crowdcube outlined a full menu of primary and secondary options. Investors can now fund companies and sell private company shares through the same platform. So the equity crowdfunding story is not only about raising capital, but also about what happens after the raise.
In the UK, a non public company can now structure a raise in three ways.
It can then choose how to execute the transaction, either through Crowdcube for retail participation, through the London Stock Exchange’s PISCES private market for institutional access, or through both at the same time.
Here’s a recent example outlining how this works in practice. Crowdcube says Chip completed a £11 million transaction. That total included £8.9 million in primary capital and £2.1 million in secondary sales. In other words, the company raised new funds while giving early investors and employees a chance to sell part of their holdings.
This applies to private company shares held by retail and early investors, not publicly listed equities.
Canada isn't starting from zero. Platforms such as Hiive support pre IPO private share transactions for qualified buyers and sellers under exempt market rules. That means Canada does have private secondaries, but not a broad, regulated system for intermittent trading of private company shares.
The better comparison is Hiive versus PISCES. Canada has exempt private secondary platforms where transactions are negotiated, access is limited, and liquidity is episodic. The UK is moving toward a regulated framework where private company shares can trade through repeatable windows on approved venues, with more standardized access and price discovery.
As a result, platforms haven't developed structured secondary liquidity in the same way, and investors often wait for a later financing, an acquisition, or a public listing to exit. That delay has real effects.
When investors know they may be locked in for years, fewer participate and those who do often invest smaller amounts. That reduces momentum in early rounds.
It also limits how quickly capital can recycle into new companies, since returns stay tied up until a major exit.
For founders, it creates pressure to deliver a large liquidity event instead of offering smaller, earlier opportunities for partial exits. It also makes it harder to use equity as a tool to attract and retain talent, since employees may not see a clear path to liquidity. Over time, this slows the overall flow of capital through the ecosystem.
This can also affect upside. When early investors and employees have limited options to realize value while a company remains private, pressure builds toward a full exit. That can lead some companies to sell earlier than they otherwise might, which may limit how much value is created over the longer term.
Meanwhile, the UK is building a different approach. In August 2025, the Financial Conduct Authority approved the London Stock Exchange to operate PISCES, a regulated venue for intermittent trading of private company shares.
Unlike a public market, PISCES uses scheduled trading windows instead of continuous listing. It is also designed to bridge private and public markets, as outlined in NCFA’s breakdown of the PISCES framework. Transactions routed through PISCES can reach institutional buyers and settle on exchange infrastructure. Stamp duty exemption also reduces costs for sellers.
Simply put, a UK private company can now raise capital, provide partial liquidity, and choose the investor mix in one coordinated process.
By contrast, a Canadian company using investment crowdfunding still focuses on raising capital first. Liquidity comes later, if it comes at all.
When investors can see a path to liquidity, they’re more willing to participate earlier. When founders can offer partial exits, they can manage employee and early-investor expectations more effectively. And when capital can recycle, the market compounds faster.
Access to private markets was the first step. Liquidity is the next one. Platforms that support both can attract more liquidity and better manage how early-stage capital forms and flows.
UK platforms are building liquidity into private markets at the point of fundraising. Canada still focuses just on the raise. A practical next step in Canada would be to pilot regulated secondary trading windows for private shares under existing frameworks such as National Instrument 45-110. Regulators could test those windows under controlled conditions and measure how they affect liquidity without increasing unwanted risk. That would give investors a clearer path to exit, help founders manage early shareholders, and let capital recycle more efficiently across the ecosystem.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 17, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Regulation And Policy, Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Risk Compliance And Regtech
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026).
OSFI has returned non bank financial institution risk to the supervisory foreground. That puts more attention on leverage, liquidity, and credit formation outside the traditional banking perimeter.
European policymakers are now linking stablecoins, tokenized deposits, and payment sovereignty. If banks move on this, product teams will need to build for liquidity, redemption certainty, and distribution at scale.
The UK now has a clearer crypto timetable. Firms can see when the authorisation gate opens, when the regime goes live, and which business models sit inside scope. That gives exchanges, custodians, stablecoin issuers, and staking providers a more defined build and compliance window.
Pakistan has opened a formal banking channel for licensed virtual asset firms while keeping balance sheet exposure and client money handling tightly controlled. That gives the market a clearer regulated path for fiat access without relaxing the banking perimeter.
A global bank has expanded tokenized deposits into the U.S. for real treasury and liquidity use. That brings tokenized money closer to core banking and cross-border cash management, not just digital asset experimentation.
The SEC has drawn a clearer line around how crypto interfaces can operate without crossing into broker dealer registration. That gives wallet providers, front ends, and trading interfaces a more defined design perimeter, while keeping execution control, solicitation, and custody inside the regulated boundary.
Open finance now has a regulator defined build plan with a clear timeline. That gives banks and fintechs a window to develop data driven products beyond payments and reshape how credit and financial services are distributed.
Stablecoin settlement now runs through a $60 billion cross border network. Banks and existing rails face direct competition on settlement.
This gives Payward regulated U.S. clearing infrastructure that took more than a decade to build. That puts crypto-native derivatives closer to the core of U.S. market structure and gives banks, brokerages, and fintech partners a new route into regulated digital asset derivatives.
The SEC has reopened foundational questions around the main surveillance infrastructure for U.S. equity markets. That puts market structure, compliance technology, cost allocation, and data governance back into active review.
The FCA has reduced reporting friction without removing oversight. That changes daily reporting operations for trading firms and market makers, and it forces compliance, data, and regtech teams to adjust how short position data is calculated, submitted, and published.
The trade entry point is entering the social layer. X now controls how users move from conversation to market data, while brokerages plug into that flow to capture execution.
Crowdcube is linking retail private markets with regulated public market infrastructure. That gives companies a new way to raise capital and provide liquidity without waiting for an IPO, and it opens institutional demand to retail-originated share flow.
The update raises the compliance baseline across multiple financial crime domains at once. Banks, PSPs, and fintechs operating in or through UAE corridors will need to adjust risk models, monitoring systems, and correspondent banking controls.
This week tightens the real constraint on fintech execution. It is no longer access or distribution, it is whether your product can operate inside the rules of the rails it touches. Payment flows now include machine-initiated actions, reporting regimes are getting simpler but less tolerant of errors, and market infrastructure expects you to plug in cleanly from day one. If your system cannot enforce permissions at the transaction level, produce a clear audit trail, and align with regulated reporting without rework, it will slow down as the market speeds up. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 15, 2026 | NCFA Fintech Market Activity | Wealth Investing And Trading, Financial Inclusion And Access
On April 13, 2026, Common Wealth announced a $12 million Series A financing to expand workplace retirement access in Canada. The Toronto company says the funding will support distribution, advisor partnerships, platform development, and retirement income tools for older Canadians.
The gap is large and measurable. Common Wealth says more than 10 million Canadians working in the private sector do not have access to a workplace retirement plan. It also says the shortfall is most acute among smaller employers, where less than 20% (1 in 5 employers) with 5 to 499 employees offer a workplace retirement plan. 75% of adults aged 55 to 64 have $100,000 or less in savings. The data is pretty clear and points to a broad and growing retirement access problem across the labour market.
Since early 2024, Common Wealth says it has grown its employer base by 3x, now serving more than 1,500 employers across Canada. It says more than 80% of those employers set up a workplace retirement plan for the first time. Over the same period, membership increased 3.5x, assets under administration rose 4x, and its advisor network expanded to more than 400 advisors.
Alex Mazer, Co-founder and CEO, Common Wealth
“We’re opening up the retirement market for small and mid-sized employers and their employees – people who’ve been left behind by a legacy industry built for big employers and wealthy people. And we’re building the platform to help Canadians with one of their biggest financial concerns: turning their savings into income they can count on.”
The financing builds on a $15 million venture debt facility established with Flow Capital in July 2025. The company says it will use the new capital to reach more small and mid-sized employers, deepen advisor distribution, improve member retirement income tools, and invest in its core technology and AI capabilities.
Workplace retirement access in Canada still depends heavily on employer size and legacy plan economics, and as a result long term financial security is still closely tied to where someone works and whether their employer can support a plan.
Common Wealth is not trying to replace large institutional pension plans. It's going after the segment that incumbent providers have served weakly or not at all. That's where the distribution opportunity lies. It means there's also a financial inclusion angle.
Common Wealth is attracting capital by targeting a large, underserved part of the Canadian retirement market.
If more small employers can offer plans and more workers can save through payroll-linked structures, retirement savings becomes less dependent on individual initiative alone.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 14, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure, Wealth Investing And Trading
On April 13, 2026, Broadridge launched digital asset capabilities for Canadian wealth management firms, bringing crypto and tokenized assets into the same system used for traditional investments. The platform supports trading, custody, and asset servicing across both digital and conventional assets.
Broadridge says its digital asset infrastructure processes more than $8 trillion in tokenized assets each month across global markets. It's an important figure because it shows this type of infrastructure is already operating at scale, even as Canadian wealth firms are only now starting to bring digital assets into mainstream portfolio systems.
The operational gap has been clear for a while. Many wealth firms have handled digital assets through separate providers, separate custody arrangements, and separate compliance processes. That creates friction for advisors, clients, and back office teams. Broadridge is trying to remove that split by putting digital and traditional assets into one environment.
Tim Gokey, Chief Executive Officer of Broadridge:
"Digital assets are increasingly becoming a part of a diversified portfolio, and Canadian wealth managers need a way to support tokenization. The Broadridge digital asset solution delivers a streamlined and integrated suite of capabilities built upon the scale and functional depth of our existing solutions. By simplifying complexity behind the scenes, we are creating a streamlined front-end experience for our clients that will accelerate digital adoption in Canada."
Canadian wealth management is one of the most regulated and operationally conservative parts of financial services. By including digital asset capabilities into this layer suggests adoption is moving past early users and toward advisor-led distribution, formal oversight, and standard portfolio administration.
Instead of routing digital assets through separate systems, firms can manage them alongside existing portfolios using the same workflows and controls. That reduces operational friction and makes it easier to supervise activity across asset types.
Broadridge continues to push into tokenized market infrastructure. Just last week, Broadridge added on chain governance to tokenized equities, extending support for proxy voting, disclosures, and lifecycle events across tokenized holdings.
Broadridge is bringing digital assets into the core systems used by Canadian wealth firms. With this approach, tokenized assets are being built into core financial workflows, not left in parallel systems.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016