




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


April 14, 2026
Image: Freepik
The online gambling scene is shifting, with players moving away from classic reel slots toward more dynamic games. TV shows stand out because they make you feel part of a live broadcast. Both new and experienced Casoola Casino players enjoy them for the interactive experience without needing to learn complex rules. In this space, Lucky Wheelioinaire from Imagine Live has become a top choice, outpacing traditional slots in popularity.
Lucky Wheelioinaire is a live game in the format of a television show from Imagine Live. This provider specialises in live content with an emphasis on visual presentation and simple rules. Although Lucky Wheelioinaire is a relatively new gaming product, it fits perfectly with the trend of recent years, in which the key role is played not by mechanics but by gamblers' emotions. At its core, the game is all about a spinning wheel, and the result comes down to which sector it stops on. Casoola Casino Online players adore Lucky Wheelioinaire for its dynamic live atmosphere and fast results.
At first glance, Lucky Wheelioinaire follows the familiar mechanics of a spinning wheel, but there are a number of details that distinguish it from its competitors:
This combination makes Lucky Wheelioinaire accessible to both beginners and experienced players. This makes it more popular than similar classic formats with the same mechanics.
Lucky Wheelioinaire is based on a clear sequence of actions, uncluttered with unnecessary mechanics. To experience a unique gaming experience, Casoola Casino Online players need to complete the following steps:
This structure makes the game logically predictable but unpredictable in its outcome. This makes Lucky Wheelioinaire accessible even to beginners with no experience.
Overall, Lucky Wheelioinaire demonstrates how a live format can be adapted to the needs of gamblers at Casoola Casino Online and other leading gambling platforms. The game doesn't require a complex setup, yet it retains the dynamic, show-like feel of being part of a show. This combination explains its growing popularity among Canadian gamblers.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Apr 13, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech
A public dispute and investor backlash at World Liberty Financial (WLFI) is exposing two issues in token markets: who controls the asset, and what happens when a project uses its own token as collateral.
The control question surfaced first. Justin Sun alleged hidden wallet freeze controls in WLFI's token design. World Liberty rejected the allegation and threatened legal action, which doesn't settle the technical question, but it does expose the governance problem. If investors are unclear about who can intervene and control the asset, confidence weakens quickly.
Justin Sun, investor in World Liberty Financial:
“a trap masquerading as a door”
I am calling on World Liberty Financial @worldlibertyfi to publicly disclose who controls the single guardian EOA and the 3/5 multisig that govern the WLFI smart contract.
Every investor has the right to know who holds the power to freeze their assets.
Here is what on-chain… https://t.co/dxYKDp5Zbi— H.E. Justin Sun 👨🚀 🌞 (@justinsuntron) April 13, 2026
The collateral issue is easier to understand and harder to dismiss. $75 million borrowed against WLFI means the project used its own token to support leverage. If the token falls, the collateral weakens. That creates a self reinforcing risk where price declines can lead to more pressure on the asset. If the position needs support, pressure can build on price, liquidity, and trust at the same time.
The current backlash doesn't come out of nowhere. Earlier in the project’s lifecycle, WLFI’s initial token sale reached only 4% of its $300 million target, raising about $12 million on day one. The token was structured as a non transferable governance asset, which limited liquidity and reduced speculative demand. Those early signs pointed to questions around investor incentives and value capture that are now resurfacing in a different form.
This is where token design and investor protection collide. Admin controls, freeze powers, or blacklist functions are not unusual on their own. In some cases, they support compliance and fraud controls. The problem starts when those powers are not clearly understood by holders, or when decentralization language creates expectations the structure doesn't meet. At one point, the asset can look less like open infrastructure and more like a centrally managed financial product.
The borrowing structure adds another layer. Projects can use leverage to support operations or liquidity, but using the native token itself as collateral blurs the line between treasury management and price support. Investors then have to evaluate not only market risk, but also insider control, disclosure quality, and whether the structure holds up when markets turn the other way.
A key lesson here is that token markets still move faster than disclosure standards. That gap is manageable in a strong market, but it can quickly break when investors start asking who controls the asset, who benefits from the structure, and who carries the downside when confidence breaks.
Investor revolts in token markets rarely stop at price. When a project uses its own token as collateral and holders are unsure who can intervene in the asset, trust can disappear quickly.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 13, 2026 | NCFA Insight | Wealth Investing And Trading, Public Sector Policy And Industrial Strategy
On April 6, 2026, US Treasury announced BNY will serve as financial agent for Trump Accounts and Robinhood will act as brokerage and initial trustee. Treasury will also retain control over the initial app and account operations. That structure combines public funding with private platform delivery from day one.
Trump Accounts are proposed government seeded investment accounts for children with funds held in low cost diversified investments over a long time horizon. The account terms are clear. $1,000 initial contribution for eligible children born between 2025 and 2028 if a parent or guardian files the required election and establishes the account. The U.S. recorded about 3.6 million births in 2025. That gives the program the potential to direct roughly $3.6 billion a year into newborn accounts before any additional family or employer contributions.
Vlad Tenev, CEO, Robinhood:
“It puts us in front of the next generation of investors.”
Governments don't build programs like this just to encourage saving. They also want increased market participation, earlier household asset formation, and a stronger connection between citizens and capital markets. The platform gets early distribution, early familiarity, and a better shot at keeping the user relationship when the child becomes an adult investor.
Robinhood will provide trustee and brokerage services, while the US Treasury says the app is being built as a custom white label product for the government. So this isn't the usual bank branch or advisor channel look and feel, but rather a state backed account delivered through a digital product stack.
The natural question is could it work here in Canada, which already supports early saving, but the model is different. RESP assets reached $89.8 billion at the end of 2024. RESPs (Registered Education Savings Program) are opened through financial institutions such as banks, financial planners, scholarship plan dealers, and insurance companies. it has wide distribution and access, but it doesn't create a single national interface or give one platform a government backed starting position.
A Canadian version built on one fintech or brokerage would not just add another savings product. It would simplify delivery and reduce administrative complexity, but it would also concentrate distribution. The firm responsible for onboarding, app design, and long term account interaction would gain a durable role in the household financial relationship. A multi provider model would support competition and choice, but it would be harder to coordinate at scale and slower to implement. It's a trade off of any policy decision in programs that combine public funding with platform delivery.
Other countries show both the appeal and the operational risk. In February 2026, HMRC said 758,000 Child Trust Funds remained unclaimed and average balances were £2,242. The policy succeeded in creating accounts. It was less successful at keeping every user connected to them. That is a useful lesson for any government thinking about seeded accounts today.
Government seeded accounts do more than promote saving. They decide who gets first access to the customer relationship. In Canada, that would be the real policy choice. Not whether to support early investing, but whether to hand long term distribution power to a platform.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 13, 2026

Most modern slots feature wild symbols. Players at gambling sites like Casino Online Pistolo Casino look forward to these symbols appearing on the screen, as they award additional wins and are accompanied by interesting visual effects. Users should be aware of this game element. Below, we'll discuss how wild symbols work.
In video slots, the wild symbol originally replaced other symbols, similar to how jokers work in card games. If four identical symbols appear on an active payline along with the wild symbol, the combination will award a win as if five identical symbols appeared on the screen. Players should remember that the wild symbol can only substitute for standard symbols. It cannot be used as a Scatter or bonus symbol.
Let's look at some features of wild symbols.
If users want to know how the wild symbol works in a particular game, they should consult the paytable.
The ability to substitute for other icons is a key aspect of the wild symbol in Casino Online slots. Still, some developers add additional features that make this symbol even more useful. Below, we'll analyze the basic types of wild symbols.
As we can see, the wild symbol in Casino Online increases users' chances of success. It turns an unsuccessful spin into a winning one. This feature is especially useful in bonus rounds, where the appearance of such a symbol can provide additional multipliers.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 10, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Regulation And Policy, Payments And Market Infrastructure, Artificial Intelligence And Data

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026).
Cross border bank resolution just got more executable. Legal friction around emergency bail in mechanics drops, especially where US investors hold affected securities. That gives global banks, broker dealers, and market infrastructure firms a clearer playbook for how securities conversions and investor treatment can run under stress. It also signals where the SEC may formalize exemptions, which matters for anyone structuring cross border capital, custody, or resolution workflows.
CIRO is setting the next year’s pressure points now. Dealers and vendors in compliance, cyber, complaints, registration, and market surveillance can see where regulatory work and operating expectations are headed.
Treasury is putting a government account program into market through a named bank agent, a brokerage trustee, and an app structure it still controls. That creates a new federal operating model for account access, custody, and distribution.
This gives banks, payment firms, and digital asset operators a live regulatory perimeter for fiat backed stablecoins in one of Asia’s key financial centres. It also raises the pressure on other jurisdictions to show whether they want sandbox activity, bank led issuance, or a full licensing track.
That raises the compliance bar for exchanges, issuers, and market operators, and it gives tokenized products a clearer path into a more tightly supervised investment framework.
A regulated bank is bringing stablecoin access into clearing infrastructure under MiCAR. That gives bank-led digital asset services a clearer route into the European market and narrows the gap between fiat clearing and tokenized money.
Swiss banks are testing whether domestic currency stablecoins belong inside regulated payments and settlement infrastructure. That puts local currency control, settlement design, and bank relevance into the same build decision.
The FDIC is starting to put bank level rules around stablecoin issuance, custody, reserve treatment, and tokenized deposits. Banks, vendors, and stablecoin infrastructure firms now have a clearer target for operating inside the insured deposit perimeter.
Banks are now treating frontier AI as a cyber and resilience issue, not just a productivity tool. That puts model access, vendor controls, and critical system defence closer to the core of financial risk management.
Anthropic isn't closing the door on developers, but it's separating heavy third party agent usage from consumer subscription pricing. That raises the operating cost for external Claude tools and gives Anthropic tighter control over how third party workflows consume compute.
Circle is packaging stablecoin settlement, compliance, and conversion into one managed payments layer. That lowers the barrier for institutions that want faster cross border settlement without taking on direct digital asset operations.
Visa is moving AI agent shopping from demos into payment rails. That gives merchants, issuers, and partners a clearer path to support agent led transactions inside mainstream checkout and acceptance infrastructure.
Crypto rails are moving behind mainstream checkout flows with conversion and settlement packaged into one payments stack. That lowers integration friction for operators and gives stablecoins another live payments entry point inside a regulated consumer flow.
LISE is running a live capital raise under the EU DLT Pilot Regime which had a slow start, with real pricing, subscriptions, and settlement on new rails. If this holds up through allocation and trading, it strengthens the case that SMEs and smaller issuers could reach public capital through a simpler stack with fewer legacy layers.
A tokenization platform has crossed into full FCA authorisation with real operating scale. That places tokenized asset infrastructure inside the regulated investment perimeter rather than alongside it. As more firms follow, tokenization shifts from service layer into core market infrastructure.
Trading connectivity, hosting, and market data are consolidating into fewer managed platforms. That matters for firms trying to cut complexity, lower operational drag, and keep trading infrastructure closer to production grade service levels.
This is a technical update, but it feeds directly into dealer risk models and operating controls. Trading, credit, and operations teams treat these lists as live reference data, not background guidance.
Control points are tightening. Stablecoin rules align closer with bank standards. AI commerce runs through existing payment rails. Trading and data infrastructure consolidate. LISE adds a live IPO under the EU DLT Pilot Regime. Tokenization now shows up in collateral, governance, and issuance. NCFA covered how tokenization is scaling in collateral and cash and how governance is moving onchain. This week adds primary issuance.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 10, 2026 | NCFA Fintech Insight | Capital Markets And Market Infrastructure
On April 9, 2026, subscriptions opened for the ST GROUP IPO on LISE (Lightning Stock Exchange), a regulated European exchange that brings trading and settlement together for tokenized securities under the EU DLT Pilot Regime. The fixed price is €18.25 per share and the company is raising about €2.6 million, with room to increase the offer to about €3.0 million. The offer runs through April 20, with a possible extension. That gives the EU DLT Pilot Regime something it has needed for a while: a live primary equity raise with real terms, a real issuer, and a real funding target.
The EU DLT Pilot Regime has been in force since March 2023. It gives firms a legal framework to run trading and settlement for tokenized financial instruments through new market structures, including a DLT multilateral trading facility and combined settlement system. In other words, Europe didn't create this regime to generate headlines about blockchain. It created it to test whether capital markets infrastructure could be rebuilt with fewer layers, faster settlement, and lower operating friction.
LISE says it operates both an organized multilateral trading facility and a distributed ledger settlement system under Regulation (EU) 2022/858. Traditional public listings split trading, post trade processing, and settlement across separate institutions. LISE is testing whether more of that stack can sit inside one regulated environment. If that model works, it will change listing economics, in addition to settlement mechanics.
Tokenized infrastructure is already running at scale in other parts of the market. Tokenization is gaining traction in collateral and cash markets, where platforms like Broadridge’s distributed ledger repo system are processing more than $300 billion in average daily volume and trillions in monthly activity. Governance is moving in the same direction, with on-chain voting and corporate actions now being applied to tokenized equities. Now, LISE is testing and bringing primary issuance into that stack.
That is where the small to medium enterprise (SME) angle becomes important. Smaller companies often stay out of public markets because the structure is too heavy for the amount of capital they need. The friction and costs are simply too great for the legal work, process coordination, time to market, listing support, and the number of institutions involved. A simpler stack doesn't remove disclosure, governance, or investor protection requirements, but it can help remove costs and delays. That is why this offer deserves attention. It is one of the clearest live tests so far of whether tokenized infrastructure can make public capital markets more usable for smaller issuers rather than just more efficient for large enterprise players.
ST GROUP also makes the test more credible. It's not a crypto-native issuer trying to force a blockchain story into the market. It's an operating company in aerospace and defense. A real issuer with fixed pricing and a defined subscription window, so in a way it's much more than just a pilot announcement.
The strategic implications are significant. If integrated issuance, trading, and settlement work in production as planned, pressure will begin to build across legacy chain and support around smaller listings. Exchanges, depositories, advisers, and other support layers still add value, but they also add cost. When a regulated venue starts collapsing parts of that chain into software and workflow, the market gets to see which service layers are essential and which are inherited from older infrastructure.
Canada faces a similar financing problem. Many growth companies find public markets too burdensome while private capital remains opaque/uneven, and bank lending has limits. If Europe can show that regulated digital market infrastructure lowers the cost of reaching investors without cutting corners on market structure, it will create a live benchmark for how smaller issuers could access capital differently in a world of tokenized equity issuance.
It now comes down to execution. Subscriptions need to convert. Settlement needs to clear without friction. Trading needs to open with enough depth to support price discovery. If those pieces hold, LISE shows that regulated tokenized infrastructure can support real capital formation. The EU DLT Pilot Regime is now being tested in a live market with real issuers, real investors, and real money on the line.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 10, 2026
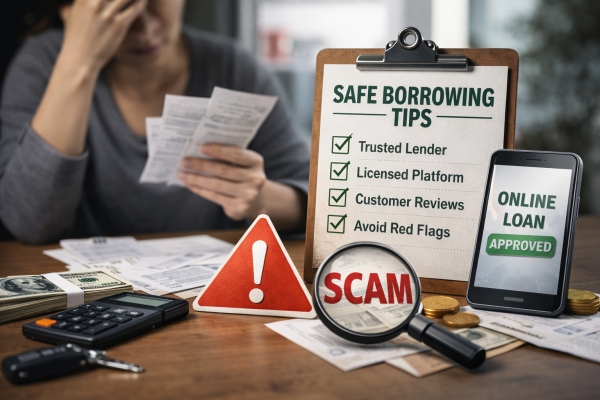
Few things are as terrifying as finding yourself in a financial pinch, and the worst part is that one could crop up at any time. Medical emergencies, property damage, and car issues—all of these can throw a wrench into your financial plans, and finding a solution as soon as possible is necessary so that you can get back on track.
One way you can do this is to borrow money from a trustworthy lender. With a loan or a virtual credit line, you can pay for the financial emergency right away and then spread out your payments across a certain time period to make them more manageable.
But it can be tricky to find a reliable provider, as well as borrower-friendly solutions. If you plan on borrowing money, it’s crucial to look for options that are safe and reputable if you want to avoid additional long-term debt or financial stress.
Here are a few tips to help you filter out the riskier options and find lenders and borrowing solutions that will genuinely be good for your situation:
If you’re looking for a reputable lender to borrow money from, then you should first explore the options offered by trustworthy banks. Banks usually offer low annual percentage rates (or APRs) for personal loans, making each installment easy to pay back. Some banks may also offer better rates or payment options for existing customers.
Alternatively, instead of borrowing money from a traditional bank, you can consider approaching a Bangko Sentral ng Pilipinas-regulated digital bank. Maya provides good options if you have a time-sensitive goal and you’re looking for a fast loan that is both convenient and secure. You can also expect fewer requirements for approving loans and a less complicated application process, allowing you to get the funds you need as soon as possible.
Besides traditional and digital banks, there are also many trustworthy lending platforms out there with good rates and transparent terms and conditions. The first step towards determining if a lender is safe is to check if it’s registered with the Securities and Exchange Commission (or SEC).
You can easily check this through the SEC website. Steer clear of lenders that don’t display any credentials, contact information, or licensing details on their site.
Reviews from previous customers are a reliable way to check a lender’s trustworthiness and safety. But don’t just look through their website’s testimonials. Instead, look for discussions on online forums, independent review platforms, and social media groups. These sites are where customers can be fully transparent about their experiences with a particular lender or a borrowing solution. Feel free to jump into these conversations as well to ask about their thoughts on the customer service, terms and conditions, and collection practices.
There are many predatory lenders out there who are out to take advantage of desperate borrowers, and it’s up to you to keep yourself safe by being on the lookout for any red flags. Be sure to stay away from lenders with high interest rates, unclear payment terms, or lack of proper paperwork.
Also, when speaking to a potential lender, pay attention to their customer service and how they generally treat you as a borrower. Loan sharks, or illegal money lenders, often use intimidation or threats during payment collection. Remember to trust your gut—if you don’t feel safe continuing the transaction, it’s better to back out before you borrow.
If you know anyone who already has experience with lenders or lending platforms, good or bad, feel free to ask them about insights and recommendations. They may have had a good borrowing experience and are happy to give you a referral, or they may be able to warn you about shadier lenders that you should avoid. Personal referrals can be a reliable shortcut to finding trustworthy loan sources, especially if you’re overwhelmed and unsure where to begin looking.
Keep your guard up even as you’re about to commit to a lender or solution. Before you consent to the agreement, make sure to read the terms and conditions carefully and ensure that the fees, interest rates, payment schedules, and penalties for missed payments are clear-cut and free of loopholes.
Avoid loan providers, for example, that bury important details in the fine print or pressure you into signing quickly. If something in the terms is unclear, don’t be afraid to ask for clarification; if the lender is unable to do so, then it’s better to cancel the loan entirely and search for a more trustworthy option than risk it.
At the end of the day, the best way to determine if a lender is trustworthy or not is by following your instinct. Even if they have no visible red flags throughout the entire transaction, if something doesn’t sit right with you, then it’s better to move on to other available options.
Rest assured that there are plenty of reputable services out there that can offer you the convenience you need without making you feel uneasy, from regulated digital banks to established lending platforms. Even if you need the money as soon as possible, carefully weigh the best options before settling on one.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016