





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


February 26, 2026
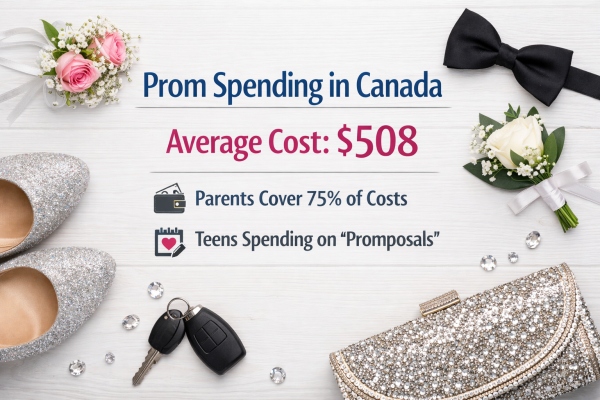
A national survey in Canada found that teens and their families are planning to spend a significant amount on prom this year.
On average, Canadian households with teenagers expect to spend about $508 on prom during the current prom season. That figure is a decrease from previous years, when the average was around $804, showing that many families are tightening their budgets while still wanting to make the night special.
Prom is widely seen as a major event for high school students. It is often described by experts as one of the biggest social occasions in a teenager’s life, a celebration of finishing school and a rite of passage.
Many parents are willing to help cover the costs, and the survey suggests that about three-quarters of total prom expenses are paid by parents, reflecting how important the event remains for families despite financial pressures.
Although hundreds of dollars are still being spent, the survey highlights a notable drop in expected spending compared with earlier years. The average planned spend of $508 represents roughly $300 less than the previous year’s figure of $804.
This decline suggests that families may be trying to balance making prom memorable with concerns about personal finances and the rising cost of living.
The reduction in spending might reflect careful budgeting by parents and teens. Some families are choosing to focus spending on a few key elements of the prom experience, while trimming costs on others.
For example, parents might prioritise the prom dress or formal outfit at around $200-$300 (Source: Dress2Party) but look for savings on extras such as limousines or professional photos.
Part of the overall prom culture — and one area that can add to the cost — is the trend known as the “promposal.” This has become more popular in recent years, especially among teenagers influenced by social media and American pop culture. A promposal is a creative or elaborate way of asking someone to be your prom date, sometimes involving decorations, gifts, or special outings.
The Canadian survey found that 65 per cent of graduating teens were willing to spend money on their promposal, with an average spend of about $151 on the gesture itself. This shows how even the lead-up to prom can carry significant costs as teens seek memorable and social-media worthy moments.
Despite the focus on costs, many families and students continue to view prom as an important milestone. For teenagers, prom is not just a dance — it is one of the few times in high school when everyone dresses up, takes photos, enjoys a night out with friends and sometimes with a date, and celebrates a key life transition.
Experts say that prom can also be an opportunity for parents to talk with their children about money and budgeting. In fact, the organisation behind the Canadian survey highlighted that prom is a chance for teens to learn about setting limits, planning expenses and understanding how to manage money in a real-world context, which can be useful before they head to college or university.
For many families, the challenge is finding a balance between creating a memorable prom experience and managing practical finances. The reduction in average expected spend suggests that many are becoming more mindful of budgets, particularly where the wider cost of living is a concern. Even as prom remains a cherished event, there is a growing awareness that spending does not necessarily need to be extravagant to be meaningful.
Some parents and teens choose to find creative ways to cut costs — for example, by renting dresses, asking friends to take photos instead of paying for professionals, or sharing transport rather than hiring private vehicles. These approaches can help keep the celebration within reach while still allowing students to enjoy what many describe as one of the most memorable nights of their school years.
Overall, the survey highlights that prom in Canada continues to be an important part of high school life, but one that is evolving with economic pressures. With an average planned spend of $508 and parents covering roughly 75 per cent of costs, families are still investing in the tradition, even as budgets tighten.
Prom remains a celebration of achievement, friendship and transition, and despite changes in how much money is spent, it continues to hold emotional and cultural significance for teenagers and their families across the country.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Feb 24, 2026 | NCFA Fintech Market Activity | Alternative Finance And Home Equity Sharing

House rich, cash poor? Home equity sharing
On February 10 2026, The Home Equity Partners (HEQ) reported surpassing $10M in managed home asset value within its first year, highlighting early traction for home equity sharing agreements as Canadian households search for ways to access liquidity without taking on new debt.
The Toronto-based fintech became operational in May 2025 and offers homeowners capital in exchange for a share of future home value rather than interest payments. Homeowners receive funds today and settle later when the property is sold or refinanced.
That structure positions home equity sharing as a complement to traditional options such as HELOCs or refinancing. The difference is simple. Homeowners don't add interest bearing debt. They share both potential appreciation and downside risk with the provider.
This isn't only a mortgage stress product. It appeals to homeowners who feel house rich but cash constrained, including:
HEQ's model lands in a market where housing affordability remains under sustained pressure. CMHC’s latest housing supply gaps report says a return to affordability levels last seen in 2019 requires building about 430,000 to 480,000 new housing units per year over the next decade, roughly double the current pace. But supply shortages and higher borrowing costs continue to limit traditional refinancing options for many homeowners.
Data tracking mortgage carrying costs shows many households face elevated payment ratios relative to income, with housing costs absorbing a growing share of disposable income across major Canadian cities. Read this Bank of Canada staff analysis about the typical Consumer's path to mortgage delinquency.
The company says its early portfolio reflects growing interest from homeowners seeking liquidity without increasing monthly obligations. While the $10 million figure remains modest relative to Canada’s housing market, it's an early sign that new financial products can tie directly to residential assets.
For fintech operators, the approach blends property finance, alternative lending logic, and long term investment exposure. Investors receive participation in home value changes, while homeowners gain flexibility that traditional credit products cannot always provide.
The structure also introduces new considerations. Pricing transparency, valuation methods, exit timing, consumer awareness and education will impact adoption and regulatory attention as the model expands.
If mortgage renewals and affordability pressure continue to strain Canadian households, will equity sharing evolve into a mainstream financing option or remain a niche tool for homeowners seeking flexibility without additional debt?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 18, 2026 | NCFA Fintech Market Activity | Payments and Cybersecurity
Image: Freepik/viarprodesign
On February 18 2026, reports of fake Olympic merchandise stores harvesting payment data surfaced ahead of the Milan Cortina Winter Games, exposing how large scale sporting events create concentrated digital commerce risk for consumers and payment providers.
Security researchers said fraudulent online stores replicated official Olympic branding and targeted fans through paid social ads. These sites collected card details and personal information at checkout, highlighting how event driven ecommerce spikes attract coordinated fraud campaigns designed to exploit urgency and trust.
Olympic Games generate predictable surges in travel bookings, ticketing, merchandise sales, and hospitality spending. That volume creates a short window where fraud actors can test payment authentication controls, merchant verification processes, and consumer awareness at scale. For payment providers, the risk is less about individual transactions and more about reputational and chargeback exposure across thousands of purchases.
Major global events have historically accelerated payments adoption, from contactless transit trials to mobile wallet acceptance across venues. At the same time, they expose gaps in digital identity verification, merchant onboarding, and fraud detection workflows. This combination turns Olympic commerce into a real world stress test for payment security infrastructure.
Canadian cross-border spending behaviour consistently ranks high per Olympic visitor card spend, meaning domestic issuers and fintech wallet providers often absorb fraud impacts even when the transaction originates overseas. That creates incentives for stronger real time transaction monitoring, merchant intelligence, and consumer education before peak travel windows.
Large scale events compress digital commerce into short intense spending cycles. When Olympic demand meets fraudulent storefronts and social commerce ads, which payment safeguards will prove most resilient for consumers, merchants, and fintech platforms?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 16, 2026
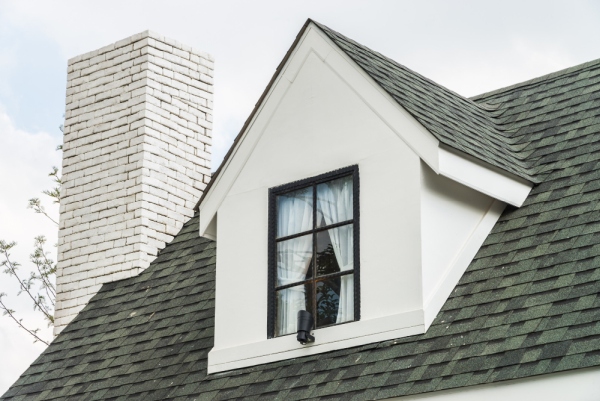
Image: Freepik/lifefostock
The roof is the primary defence against natural forces. Strong winds are one such natural disaster that can pose a formidable threat to the roofing system. If you live in Canada, roof damage from strong winds is common.
Most roofs are designed to withstand wind speeds, but severe storms can easily cause significant damage. It is essential to recognize the signs of wind damage to prevent costly repairs. Given the prevalence of strong winds in Canada, it's critical to identify the common signs of wind-related roof damage.
Damaged and missing shingles are common signs of wind damage in Halifax. Strong winds can tear and lift singles from the roof, leaving them completely exposed to the elements. After facing a windy storm, get your roof inspected by professionals. Also, check the shingles for visible damage. Prompt action in replacement is essential to prevent water infiltration.
Tiny granules are used to coat roof shingles, which in turn helps to protect it from the harsh UV rays and changing weather. These granules can be stripped off by high winds, making the shingles highly vulnerable. When you see granules in the downspouts and gutters, it indicates that the roof needs repair due to wind damage. Loss of granules can even lead to premature aging of shingles.
Roof ventilation components, such as turbine ridge vents and vent pipes, can be damaged by strong winds. A proper ventilation system is crucial for preventing moisture buildup and balancing the attic temperature. You can check out with insulation contractors Halifax. Adequate inspection of components shall be conducted to check for cracks, density, and displacement after strong winds and heavy storms. Remember, poor ventilation can lead to poor air quality and higher bills.
In some instances, strong winds can cause structural damage to the roofing system. A deformed or sagging roof line clearly indicates such damage. If you notice irregularities in the shape of your roof, it's essential to contact roofing professionals without delay. A compromised roofing structure can pose a significant risk factor and should be addressed immediately.
The effects of wind damage are not immediately visible at certain times. The water stains on the walls and ceiling are indicative of hidden damage. If you notice discoloration or damp spots, call the experts right away to identify the source of the leak. This can lead to mould growth and structural damage if prompt action is not taken.
Your roof is the first line of defence; hence it is important that you take proper care of it. The moment you recognize the early signs of wind damage, you should take prompt action to prevent extensive repairs down the road. Regular roof inspections from Artisanroofing.ca, especially after severe weather, can help you maintain a weather-resistant, secure roofing system. If you suspect any kind of wind damage to the roofing system, immediately contact the expert-looking contractors to assess the extent of the damage and the cost.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 5, 2026
Selling rare coins or gold can feel overwhelming. You want a fair price, but the process seems complicated. This guide breaks down what you need to know to make informed decisions and get the best return on your precious metals.
Before you sell, you need to know what you have. Rare coins and gold pieces vary wildly in value. A coin's worth depends on its metal content, rarity, condition, and historical demand.
Gold coins fall into two categories: bullion and numismatic. Bullion coins like American Eagles or Canadian Maple Leafs trade close to their metal value. The price follows the spot price of gold, which changes daily based on global markets. Numismatic coins have collectible value beyond their metal content. A pre-1933 gold coin might sell for several times its melt value because collectors want it.
Rare coins without gold content can still command high prices. A 1909-S VDB penny in mint condition sells for thousands of dollars. The 1916-D Mercury dime? Collectors pay premium prices for clean examples. Condition matters tremendously in coin collecting.
When you're ready to sell, working with experienced buyers makes the difference. Austin Coin Buyers can assess your collection and provide current market valuations based on actual sales data, not outdated price guides.
Professional grading helps establish value. Third-party grading services like the Professional Coin Grading Service (PCGS) and Numismatic Guaranty Company (NGC) authenticate and grade coins on a 70-point scale. A coin graded MS-65 (Mint State 65) will sell for more than the same coin in MS-60 condition.
Grading costs money. You pay fees for submission, grading, and return shipping. For common coins worth less than $100, grading might cost more than the value increase. Save grading for coins that could be worth $500 or more. A dealer can help you decide which coins justify the expense.
Gold purity also affects value. The United States Mint produces coins in 22-karat (91.67% pure) and 24-karat (99.99% pure) gold. Jewelry often uses 14-karat (58.3% pure) or 18-karat (75% pure) gold. Buyers test gold items to verify purity before making offers.
Gold prices fluctuate based on economic factors. When inflation rises, investors buy gold as a hedge. During economic uncertainty, gold typically gains value. The spot price represents the current trading price for one troy ounce of pure gold.
Let's break it down. If gold trades at $2,000 per ounce and you have a one-ounce American Gold Eagle (91.67% pure), your coin contains about $1,833 worth of gold. Dealers typically pay 90-95% of melt value for bullion coins. You might receive $1,650-$1,740 for that coin.
Rare coins don't follow spot prices as closely. A Saint-Gaudens Double Eagle in exceptional condition might sell for $2,500 when it contains only $1,800 in gold. Collectors pay for scarcity and beauty, not just metal.
Timing your sale can affect your return. Watch gold prices over several weeks. If prices trend upward, waiting a few days might net you more money. If prices are falling, selling sooner protects your value.
You have several options for selling rare coins and gold. Each has pros and cons.
Local coin dealers offer immediate payment and face-to-face transactions. You can ask questions and get answers right away. Reputable dealers have established businesses and care about their reputation. They buy regularly and know current market prices.
Online marketplaces like eBay reach more buyers. You might get higher prices from collectors willing to bid competitively. But you'll pay listing fees, final value fees, and payment processing fees. Shipping precious metals requires insurance and tracking. Scammers exist online, both as buyers and sellers.
Auction houses work well for extremely rare or high-value items. They market to serious collectors and provide authentication services. Auctions take time, and you'll pay commission fees of 10-20%. Reserve prices protect you from low-ball sales, but they might prevent a sale if bidding stays weak.
Pawn shops buy gold and coins but usually pay the least. They need to resell at a profit and often lack specialized knowledge about rare coins. Visit pawn shops only if you need cash immediately and have no other options.
Honest dealers outnumber scammers, but problems exist. Watch for these warning signs.
Pressure tactics should send you away immediately. "This price is only good today" or "I have another buyer waiting" are manipulation techniques. Legitimate dealers know their offers are competitive and don't rush you.
Vague or confusing explanations about pricing indicate problems. A good dealer explains exactly how they calculated their offer. They'll show you the spot price, discuss premiums, and justify their buying percentage. If you don't understand the math, ask again or leave.
No physical location or unclear business information raises concerns. Check for a real address, phone number, and business license. Online reviews help, but read carefully. A few negative reviews among hundreds of positive ones is normal. Patterns of similar complaints deserve attention.
Clean hands and a clean workspace protect your coins. Dirt and oils from your fingers can damage rare coins. Never clean old coins yourself. Cleaning removes the patina that collectors value and can reduce a coin's worth by 50% or more.
Organize your items before meeting with a dealer. Group similar items together. Separate gold coins from silver coins. Put rare coins aside from common ones. This preparation shows you take the process seriously and helps the dealer work more efficiently.
Bring documentation if you have it. Receipts, previous appraisals, and certificates of authenticity all help establish value. Original packaging for modern bullion coins adds to their worth.
Know your bottom line before you start negotiations. What's the minimum price you'll accept? Having this number in mind prevents you from making emotional decisions or accepting low offers out of convenience.
Expect the dealer to examine each item carefully. They'll check dates, mint marks, and condition. For gold items, they'll test purity using acid tests or electronic testers. This process takes time, especially for large collections.
Ask questions during the evaluation. Why does this coin grade higher than that one? How did you calculate the gold content? What affects this coin's value? Good dealers enjoy sharing their knowledge.
The dealer will make an offer based on their evaluation. You can accept, decline, or negotiate. If the offer seems low, ask them to explain their reasoning. They might point out damage you didn't notice or explain current market conditions.
Get your payment in your preferred form. Cash works for smaller transactions. Checks or bank transfers suit larger sales. Some dealers offer both. Whatever you choose, get a detailed receipt listing each item sold and the price paid.
Inherited coins require extra care. You might not know what you have or what it's worth. Don't rush the process.
Sort items roughly by type. Put gold coins in one group, silver coins in another, and so forth. Look for obviously old or unusual pieces. These might have the most value.
Consider getting a second opinion on inherited collections. If one dealer offers $5,000 and another offers $8,000 for the same items, that gap tells you something. Most honest dealers will price within 10-15% of each other.
Estate sales sometimes include coins that the original owner thought were rare but aren't. The 1943 steel penny, for instance, is common despite its unusual appearance. A dealer can separate the truly rare from the merely old.
The IRS treats precious metals as collectibles. When you sell coins or gold for more than you paid, you owe capital gains tax. The collectibles tax rate maxes out at 28%, higher than the 15-20% rate for stocks.
Keep records of what you paid for items. Your cost basis reduces your taxable gain. If you inherited coins, the cost basis usually equals their value on the date of death, not what the original owner paid.
Sales over $10,000 in cash trigger reporting requirements under federal law. Dealers must file Form 8300 with the IRS. This applies to cash only, not checks or electronic transfers.
Consult a tax professional if you're selling a large collection. They can help you time sales to minimize taxes or split sales across tax years to stay in lower brackets.
Selling rare coins or gold requires research and patience. Understanding what you own, getting fair appraisals, and choosing the right buyer all affect your outcome.
Trust matters more than getting the absolute highest price. A dealer who pays 5% less but treats you fairly and honestly beats one who quotes high numbers but uses deceptive practices.
Take your time, ask questions, and don't settle for the first offer. Your rare coins and gold deserve careful attention, and you deserve fair compensation for your items.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jan 26, 2026 | NCFA Fintech Market Activity | Personal Finance and Consumer Savings
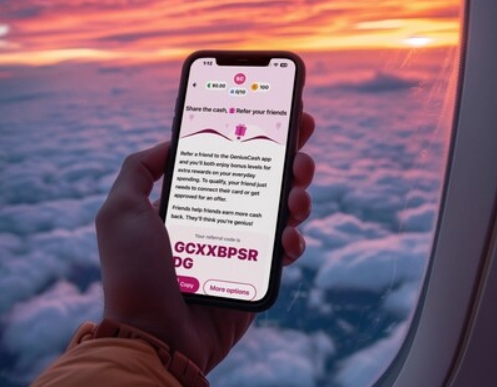
Product image of the GeniusCash app
Image courtesy of GeniusCash via CNW Group
On January 15 2026, GeniusCash announced a $100M cash back pledge for Canadians and positioned it as a longer term push to expand cash rewards tied to everyday financial product decisions.
The company says it has already paid out close to $5M in cash back rewards. It frames the pledge as a public goal to scale that payout total to $100M over time, with progress updates planned.
GeniusCash describes a model that pays rewards as cash deposits rather than points. The release gives a simple example. A user can earn a $100 bonus for signing up for a selected credit card or bank account, and that reward contributes to the $100M target.
The pledge also expands the company’s product coverage. The release says GeniusCash plans to add more exclusive cash back offers across banking, credit cards, insurance, and other personal finance products, and it plans to increase financial education content tied to saving opportunities.
Stephen Weyman, Co-Founder of GeniusCash:
"We know every dollar counts right now for Canadian households. Groceries, gas, rent, it all adds up. We started GeniusCash to be a trusted friend to Canadians, the one that tips you off on how to get money back on your everyday expenses. Since setting this goal we have crossed the $5 million dollar mark in cash back paid, and we're just getting started. By pledging to give back $100 million, we're doubling down on our commitment to help families thrive and help stretch their budgets. This isn't hype, it's a mission. And we're inviting everyone to join us."
Cash back platforms live or die on trust and clarity. When consumers chase bonuses across multiple products, what guardrails will keep the experience transparent and prevent reward-marketing from turning into regret later?
This announcement is as a growth play that leans on two pressures Canadians feel every month. Prices stay high, and households keep looking for small wins that add up. The pledge sets a measurable target. The next validation point is whether the platform scales payout volume while keeping product selection clean and consumer outcomes easy to understand.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Payments | Jan 12, 2026
Image: Freepik/stockking
On January 8, 2026, UK consumer watchdog Which? published an eye-opening article, "Why cancelling your card might not stop fraud"explaining why cancelling a compromised card doesn't always stop fraud. The article covers a real world case showing how replacement card details can continue moving through global payment systems, allowing fraudulent charges to resume even after a bank issues a new card. What stands out is that the issue has little to do with careless consumers or missed fraud alerts. It sits deeper, inside how modern card payment infrastructure is built to keep payments running.
Most global card networks run automatic card updater services. These systems exist to make sure legitimate payments don’t suddenly fail when a card expires or gets replaced.
If a cardholder has previously saved their card with a merchant, the card network can automatically send the replacement card details to that merchant. The cardholder doesn’t need to approve anything and doesn’t need to take any action. It just happens.
These services operate across Visa, Mastercard, and American Express. They help subscriptions and recurring payments keep working without interruption. The problem is that the same process can also allow fraud to continue if a criminal has already saved stolen card details inside an account they control. So even when the bank issues a replacement card, if the network automatically updates that account with the new card details, then the fraudulent charges/payments can continue (and likely will leaving consumers bewildered and in the lurch).
In practice, when an automatic card updater service refreshes stored card details, the update usually happens quietly between the card network, the issuing bank, and the merchant (it all runs in the background).
Cardholders are typically told that a replacement card has been issued. They aren’t clearly told that the new card number may be sent automatically to merchants where the old card was saved, including after fraud. They also aren’t told which merchants receive those updated details.
Some merchants may show a generic message such as “your payment details were updated,” but this varies by platform and is easy to miss. There isn't a standard alert explaining that replacement card credentials were transmitted automatically.
Many consumers never realize that automatic updates exist at all. And in most cases, they don’t know the updates can continue after fraud unless someone stops them. Then it stands to reason that they also likely don’t know they can ask their bank to turn them off. Automation keeps running by default, while awareness and consent lag behind.
The Which? article confirms that issuing banks can disable updater services or perform what fraud teams often describe as a full wipe. This stops replacement card details from being shared with any online accounts or digital wallets.
The catch is that this step isn’t automatic. In most cases, the customer has to know the option exists and ask for it. Once a consumer later adds their card back to trusted merchants, those accounts may again become eligible for automatic updates.
That means that the outcomes depend more on awareness than on risk.
Fraud isn’t a routine card replacement; it’s a security failure, and the system doesn’t always treat it that way. Automatic updater services make sense when a card expires or gets damaged, but when fraud has already occurred, letting replacement credentials continue to move silently through the system creates avoidable risk. Requiring express consumer consent after fraud and making full wipe policies the default response would reduce repeat incidents and avoid putting the burden on consumers to navigate payment systems they can’t see.
This situation is a good example of how invisible infrastructure decisions can cause real harm when transparency and control fall behind automation. Payments innovation can’t rely on convenience alone. Trust in digital finance depends on how clearly systems explain what’s happening and how decisively they contain risk once something goes wrong.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
