




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Sep 10, 2026
Large companies face specific security challenges that need careful planning and investment. Protecting sensitive data and physical locations is essential for keeping a safe business environment. Companies should not only react to threats but also actively create a secure space for employees and customers. Security should be a key part of business strategy, not an afterthought.
As threats evolve, large companies must update and improve their security practices. Today's tools and technologies help businesses build strong security measures, providing peace of mind and a safer operational environment. Here are ways to boost your company's security.
Access control systems are crucial for security in large organizations. These systems allow companies to control who can enter different parts of their facilities. Using card access or biometric systems like fingerprints or retina scans, businesses can ensure only authorized personnel can enter sensitive areas.
Access control systems are flexible. Companies can change access permissions as needed, quickly responding to changes in staff or security requirements. This flexibility helps create a safe working environment, making employees feel secure knowing that only approved individuals can enter restricted areas.
Moreover, advanced systems with real-time monitoring features improve overall safety. This technology lets security teams monitor movement throughout the premises, spot suspicious activity, and act promptly when needed. A solid access control system is vital for protecting assets and keeping confidential operations secure.
Video surveillance systems are essential for security in large companies. Modern technology provides high-definition video, allowing businesses to monitor their facilities effectively. By placing cameras in key locations, companies can oversee both indoor and outdoor areas.
Real-time monitoring in video surveillance systems helps security staff detect and respond to incidents quickly. Recorded footage is also valuable for training, resolving incidents, and handling insurance claims. This documentation helps businesses improve their security procedures by highlighting weaknesses over time.
Investing in smart video analytics can further strengthen this security solution. These systems automatically detect unusual activity or specific events, speeding up response times and increasing operational efficiency. In short, video surveillance systems give businesses the tools they need to tackle security challenges and maintain a safe environment.
Weapons detection systems are important for protecting corporate spaces. These advanced systems can find firearms and other dangerous items before they become a threat. Quickly putting these systems in place can improve the safety of employees and clients, giving everyone peace of mind.
Using weapons detection systems in busy areas, like entrances or conference rooms, adds extra protection. These systems operate quietly, allowing companies to keep a welcoming atmosphere while prioritizing safety. Their fast and accurate detection enables security staff to identify threats swiftly, so they can respond without causing disruptions.
By integrating weapons detection systems into their overall security plans, large companies can show their commitment to workplace safety. This proactive strategy not only discourages potential threats but also fosters a culture of safety among employees. A strong focus on security can become a core part of the company's identity, building trust both inside and outside the organization.
As businesses move more operations online, cybersecurity is a major concern. Large companies that handle large amounts of data and run complex networks must invest in strong digital security measures. Effective cybersecurity solutions are necessary to protect sensitive information and keep operations running smoothly.
Installing firewalls, antivirus software, and intrusion detection systems helps create layers of protection against cyber threats. Regular software updates and employee training on spotting phishing attacks also strengthen a company's cybersecurity. Educating employees allows them to contribute to the organization's safety efforts.
Incident response plans are also vital. These plans prepare companies for possible breaches and ensure prompt action when they occur. By having clear steps to follow, businesses can reduce damage and recover quickly. Investing in robust cybersecurity solutions shows a commitment to protecting data and maintaining trust with clients and stakeholders.
Using AI weapons detection system and integrated security solutions can make safety efforts easier and more effective for large companies. This approach combines different security systems into one unified system. By streamlining security measures, businesses can improve management, enhance communication among security teams, and respond better to threats.
Integrated solutions give a complete view of a company's security needs. Real-time data sharing between systems increases awareness and helps teams act quickly in emergencies. This coordination helps organizations build stronger safety and resilience.
Choosing integrated security solutions is a smart decision that boosts efficiency and effectiveness, creating a protective environment for the business. When considering security options, keep in mind that the best solutions blend technology and strategy. What matters is a commitment to proactive safety measures that protect resources and improve the work environment.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Sep 10, 2026
Image: Unsplash/Andrey Matveev
Modern consumer technology is designed to feel simple. You open an app, make a payment, check your identity, or access a service and the process can be over in seconds. What users rarely see is the software working behind the scenes to make those interactions possible.
From payment systems and authentication tools to databases and cybersecurity controls, today's digital services rely on layers of technology that work together. As more everyday activities move online, the reliability and security of that infrastructure matter more than ever.
Almost every digital service depends on software connecting different parts of the customer experience. An app might communicate with payment providers, databases, authentication systems and third-party services before completing what appears to be a simple request.
That creates a balancing act. Software needs to be fast enough that users aren't left waiting, flexible enough to accommodate new requirements and reliable enough to keep services running.
For financial and fintech services, even more happens behind the interface. A platform might need to verify a customer's identity, authorise a transaction, detect suspicious activity and protect sensitive information within seconds.
Security is no longer something that can sit quietly in the background. For consumers, it is increasingly part of the experience itself.
Recent events involving MikroTik RouterOS offer a useful reminder. On the 5th of September 2026, CERT Polska confirmed that attackers were actively exploiting vulnerabilities that could allow them to take full control of affected devices when SSH access was exposed to the public internet. MikroTik's patched releases included:
CERT Polska advised administrators to update immediately and check devices for signs of unauthorised changes.
Connected technology depends on software that has to be maintained throughout its lifespan. A product can be functional when it launches yet become a security risk later if vulnerabilities are discovered and patches are ignored.
Software updates can therefore be an essential part of keeping connected services and devices secure.
Payment technology provides another example of infrastructure consumers rarely think about.
A modern platform might support cards, bank transfers, digital wallets or other payment methods. Each transaction needs to move between different systems while authentication, fraud checks and security measures operate in the background.
Ideally, none of this feels complicated to the customer.
That's part of the challenge. Businesses have to introduce enough security to protect users without turning every transaction into a lengthy process. Multi-factor authentication, encryption and automated fraud detection can add protection without necessarily creating unnecessary friction.
Consumers increasingly expect payments to be both secure and almost invisible.
The importance of dependable software becomes clearer when digital platforms reach millions of people.
Poland's mObywatel application had more than 11 million users by March 2026, according to the country's Ministry of Digital Affairs. The platform provides access to digital documents and public services, with plans to integrate the European Digital Identity Wallet into the wider ecosystem.
Reliability isn't simply about keeping an app convenient. A problem with the underlying software could affect huge numbers of people trying to access important documents or services.
The same principle applies to banking applications, digital payment platforms, online marketplaces and other services that people increasingly rely on. The more people a platform serves, the more important it becomes to build infrastructure that can cope with demand while remaining dependable.
Consumer-facing online services show how these technologies increasingly overlap. Several systems have to communicate before the user reaches the service they wanted.
Online betting is one example. Consumers researching the regulated market might consult a list on covers.com when comparing options. Resources like this can help consumers understand the different platforms available, while the technology behind those platforms handles everything from account security to payments. The smoother that process is, the less users have to think about the complex systems working in the background.
Operators need systems capable of managing accounts, processing payments, carrying out security checks and handling large amounts of data. They also have to respond to regulatory requirements and protect users from fraudulent activity.
The front end might look straightforward. The infrastructure behind it is anything but.
Most people don't think about the infrastructure behind an app until something goes wrong. When everything works, expectations are fairly straightforward. Consumers want digital services that are:
Meeting those expectations means balancing security, reliability and ease of use. The best platforms make this complicated work feel effortless to the consumer.
As digital services become part of everyday life, consumers expect them to be fast, reliable and secure. New technologies such as AI, automation and digital identity only increase the need for strong safeguards.
In the end, the technology people trust most might be the technology they barely notice: payments go through, identities are verified and personal information stays protected. Behind that simplicity is a sophisticated combination of software, security and infrastructure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 9, 2026 | Legal Issues, Regulation, Consultation
Image: Pexels/RDNE Stock project
Divorce can change much more than a relationship. Property, savings, wills, beneficiary designations, support obligations, and future inheritances can all become part of the financial cleanup. The rules are particularly important when significant assets are involved because assumptions about who owns what do not always match the law.
The numbers give the issue some scale. According to the 2021 Census, about 695,630 people in Ontario were divorced and not living common-law, while another 333,775 were separated and not living common-law. Changes to succession law that took effect in 2022 also altered how certain separated spouses are treated when someone dies, making current legal advice especially important.
People often assume that anything inherited during marriage automatically remains theirs after the relationship ends. There is some basis for that idea, but the rules contain important exceptions.
Under family property law, property inherited from a third party during marriage can generally be excluded from net family property if it still exists at the valuation date. Property that can be traced back to an inheritance may also qualify for exclusion.
The family home is different. If inherited money is used to acquire or improve a matrimonial home, or the inherited property itself becomes that home, the normal exclusion may not apply.
Documentation therefore matters almost as much as the source of the money.
Divorce generally changes a former spouse's position under a will, but it does not necessarily erase every possible financial obligation between two people.
For anyone trying to understand inheritance rights after divorce in Ontario, Nussbaum Law explains how divorce, separation, support obligations, joint ownership, beneficiary designations, and estate claims can interact. The firm provides family-law and estate-litigation services and notes that unresolved support or other legal obligations may continue to affect an estate even after a marriage has ended.
This is why the answer to “Can my former spouse still receive anything?” may depend on much more than whether a divorce order exists.
Everyday conversation tends to treat separation and divorce as interchangeable. Legally, they are distinct.
Separation generally involves spouses living apart following the breakdown of their relationship. Divorce formally terminates the marriage.
That distinction can become particularly important when one spouse dies before all financial and estate matters have been resolved. Property division, support obligations, wills, and estate entitlements may interact differently depending on the couple's legal status and existing agreements.
Someone who has moved out and started a separate life should not assume every legal connection has disappeared with the moving boxes.
Inherited assets receive certain protections during property division, but a matrimonial home operates under different rules.
Government guidance explains that even when a family home was inherited or received as a gift, it does not receive the same excluded-property treatment that might apply to other inherited assets. Its value can therefore become relevant to the equalization calculation.
That distinction can catch people by surprise.
Suppose someone inherits money and leaves it in a separate investment account. Compare that with using the inheritance to pay down the mortgage on the family home. Those choices can produce very different consequences.
Before transferring substantial inherited funds into jointly used property, getting individual legal advice can be worthwhile.
A major relationship change is a sensible time to review estate documents.
Under succession legislation, when a marriage ends through divorce, gifts to a former spouse in an existing will are generally treated as revoked unless the will indicates a contrary intention. The same principle applies to certain appointments, such as naming that former spouse as executor.
That does not mean an old will should simply be forgotten.
The remaining provisions may no longer distribute the estate the way you want. Executors, alternate beneficiaries, trusts, guardianship arrangements, and other instructions could all deserve reconsideration.
A current will is usually easier for everyone to understand than an old document that has to be interpreted through later legal changes.
Your will is only one part of estate planning.
Life insurance, pensions, registered accounts, jointly owned assets, and other financial arrangements may have their own beneficiary or survivorship provisions. That means changing a will without reviewing everything else can leave inconsistencies behind.
The Government of Canada's information on getting separated or divorced recommends reviewing finances carefully after a relationship breakdown, including joint accounts, credit arrangements, insurance, investments, and retirement planning.
Create a complete inventory rather than trying to remember accounts individually. Administrative details are easy to overlook when a separation already involves housing, finances, family arrangements, and legal paperwork.
If you want to claim that an asset should be excluded from property division, you may need to establish where it came from and what happened to it afterward.
Keep estate documents, bank statements, investment records, transfer confirmations, and other paperwork showing the original inheritance and its subsequent movement.
Tracing becomes more difficult when inherited funds are repeatedly transferred between accounts or mixed with other money.
Government guidance on dividing property after a relationship ends specifically identifies inherited property other than the family home as an example of property that may be excluded. It also explains how assets and debts are considered when calculating family property.
Good records cannot guarantee a particular legal outcome, but missing records rarely make a complicated financial dispute easier.
Inheritance questions should not be handled in isolation.
Look at property division, support arrangements, jointly owned assets, insurance, beneficiary designations, wills, registered accounts, and any obligations established through an agreement or court order.
Timing matters too. Moving inherited funds, changing ownership, or making large financial decisions before understanding their legal consequences can create problems that are difficult to reverse.
The goal is not to assume every former spouse will make a claim or that every inheritance will become disputed. It is simply to know where the potential complications are before making decisions involving significant assets.
Divorce already creates enough paperwork. Your estate plan does not need to become the sequel.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 7, 2026 | NCFA Insight | Digital Identity Privacy KYC AML ATF, Regtech Compliance Governance, Legal Issues Regulation Consultation
On September 4, 2026, reporting by CBC and the Centre for Information Resilience linked Maple Digital Financial Solutions to the sanctioned TGR network through corporate, personnel and digital connections. Maple is a Vancouver based money services business registered with FINTRAC and offers international payments, foreign exchange and virtual currency services. There is no finding that Maple itself laundered money.
The reporting points to overlapping directors, shared contact information, archived websites and other digital traces connecting Maple and The OneGate with TGR related entities. Former Maple director Andrejs Carenoks (also known as Andrejs Bradens) was sanctioned by the United States in 2024 for his alleged role in TGR. Maple director Janis Zvigulis has also served as a director of The OneGate and TGR Wealth Solutions in the United Kingdom. Zvigulis has not been identified as personally sanctioned.
“FINTRAC registration confirms that an MSB operates within Canada’s anti money laundering regime. It does not mean the business is licensed, endorsed or free of risk.”
FINTRAC says this plainly in its Money Services Business Registry. Registration means a business has satisfied the legal requirement to register. FINTRAC does not license or endorse the firms listed there.
Registration still comes with real obligations. MSBs must verify clients, keep records, report certain transactions and maintain a compliance program. FINTRAC can examine firms, impose penalties and revoke registrations when legal requirements are not met.
As of March 31, 2025, FINTRAC listed 2,778 registered MSBs. During 2024 to 2025, 509 new MSBs registered, 351 renewed, 198 ceased their registrations and 12 registrations were revoked.
The CIR investigation into The OneGate found an international payments network spanning at least seven jurisdictions and reported strong open source evidence connecting it to TGR. The OneGate's U.S. company was registered to the same Vancouver address as Maple Digital Financial Solutions.
The U.S. Treasury sanctioned Carenoks in December 2024 and identified TGR Partners and TGR Wealth Solutions among entities connected to the network. Treasury described TGR as an international illicit finance network used for sanctions evasion and money laundering involving digital assets.
Those links do not establish that Maple committed money laundering. They do explain why checking a FINTRAC number alone is not enough for a bank, payment company, fintech or corporate customer deciding whether to enter or continue a financial relationship.
Canada's 2025 National Risk Assessment identifies professional money launderers, transnational criminal networks, crypto assets and some types of MSBs among the areas with high money laundering exposure. The report says Canada's MSB sector includes nearly 3,000 businesses with very different products, customers and risk profiles.
For a fintech or bank, an active registration should be one check among several. Directors, owners, related companies, sanctions exposure, jurisdictions, payment partners and the firm's operating history can tell a very different story from the registry entry alone. Those checks also need to continue after onboarding because ownership, counterparties and sanctions status can change.
Canada has recently made it easier for reporting entities to compare what they are seeing. FINTRAC information sharing rules introduced in June allow eligible firms to exchange designated information for detecting money laundering, terrorist financing and sanctions evasion, subject to privacy requirements. That gives banks, payment firms and fintechs another way to spot connections that may be difficult to see inside a single customer file.
FINTRAC itself tells consumers to research an MSB before using it and says it cannot provide information about a firm beyond what appears in the public registry. That leaves customers and commercial counterparties with their own decision to make. Registration confirms legal status inside the AML regime, while trust still depends on who controls the business, who it deals with and what those relationships reveal.
How much should an active FINTRAC registration influence whether you trust an MSB?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 29, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Competition And Market Structure, Regulation And Policy, Risk Compliance And Regtech, Lending Consumer Credit And BNPL, Cross Border Payments And FX, Digital Banking And BaaS, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Payments Infrastructure And Money Movement

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026).
This is a material step beyond the group's 2025 exploration phase. TD and Scotiabank are now participating in a global bank-led issuance venture while Canada's own stablecoin framework is still moving through implementation. The Canadian question is whether major banks build meaningful CAD-denominated digital-money capacity alongside domestic initiatives or gain scale first through shared global USD infrastructure.
Coinbase supplies the regulated trading and custody stack while Webull keeps the investor interface and brokerage relationship. That reduces the infrastructure brokers need to build themselves and gives specialist providers another route into Canadian retail distribution. It also intensifies Canadian crypto competition over who owns the customer and who supplies the regulated back end.
The useful proof is the cash leg. Tokenized securities have limited value if settlement still depends on separate legacy rails. This transaction puts the asset and payment legs onchain in a live regulated market environment, bringing programmable settlement closer to something institutions can actually use.
LSEG is extending tokenization from private markets and settlement infrastructure toward public equities. The harder test is whether tokenized shares can preserve legal ownership rights, corporate actions, price integrity and regulated settlement while gaining wallet portability and longer trading access. If that model works, public-market infrastructure begins competing directly with blockchain-native distribution without abandoning the protections of an exchange-listed security.
Coinbase is bringing regulated crypto derivatives distribution into Canada without routing the products through Coinbase Canada itself. The important boundary is eligibility as it expands access for sophisticated investors while keeping the offering outside ordinary retail availability. It also gives regulated venues a stronger alternative to offshore derivatives platforms for Canadian capital, hedging and price discovery.
The important development is bank ownership of shared tokenized deposit infrastructure, not the financing round. Cari is moving toward production with banks helping govern, fund and use the network while retaining the customer relationship. Alongside other shared bank blockchain infrastructure, the test is whether common digital money networks can achieve enough participation and interoperability to compete with institution specific systems.
Forty-three state licences give OpenPayd something infrastructure providers can't create through software alone: regulated geographic reach. The company can now connect its payment stack to a much larger U.S. operating footprint while combining fiat and digital asset permissions across the United States, United Kingdom and Europe. The test is how quickly that regulatory coverage converts into client activity and payment volume.
Final approvals put the transactions into execution. National Bank is positioned to absorb Laurentian's retail and SME relationships while Fairstone combines its commercial lending operations with Laurentian's commercial specialization. Customer migration, product continuity and retention now determine how much of the approved transaction value survives the transfer.
Australia's digital asset licensing transition now has a firm market access deadline. Firms still relying on transitional relief need the correct licence application or variation underway before September 30, while brokers, tokenization businesses, market operators and clearing providers must test whether their activities fall inside the existing financial services perimeter ahead of the new 2027 digital asset regime.
Singapore is converting stablecoin policy into the legal requirements issuers will operate under. The consultation advances the status tracked in NCFA's stablecoin regulatory intelligence from a finalized framework awaiting legislation toward implementation. Reserve, redemption, capital and cross-border requirements can now be tested against issuer economics before the rules are finalized.
The case makes privileged information a concrete event contract surveillance problem. Exchanges and brokers need controls that can connect unusual positions with access to confidential information, investigate suspicious activity and enforce trading restrictions. NCFA's regulated event contract infrastructure brief tracks this market integrity gap as distribution expands.
Section 311 can reach beyond a targeted foreign bank because U.S. institutions must also identify transactions routed indirectly through other correspondent relationships. Banks and payment firms therefore need enough counterparty visibility to detect the institution behind a payment chain, not only the correspondent presenting the transaction.
The investigation puts transaction monitoring and global compliance governance under direct supervisory scrutiny at a major cross-border payment provider. The operating test is whether controls identify known laundering typologies across high-risk channels and whether global decisions support local obligations. The eventual findings could provide useful evidence for how regulators assess AML controls across international payment networks.
Australia's AML expansion has reached the point where AUSTRAC is testing whether newly covered firms have entered the regulatory system at all. Service classification, enrollment and working AML controls can no longer remain implementation projects. Regtech providers also gain a much larger addressable compliance market, but buyers will need products matched to obligations regulators are actively checking.
Conditional approval advances Revolut from U.S. fintech distribution toward direct regulated banking capacity. Its U.S. business still relies on a partner bank, while NCFA's Revolut company intelligence had tracked the national bank application as pending. A completed charter would give Revolut more control over deposits, credit and payment connectivity, but the remaining federal approvals and preopening requirements still determine whether that capacity reaches customers in 2027.
OpenReserve is trying to combine conventional banking, tokenized deposits, digital asset custody and stablecoin infrastructure inside one national bank structure. Preliminary approval brings that model closer to regulated operating capacity, but the remaining test is execution: capital, controls, final authorization and separate approval for the planned stablecoin subsidiary still stand between the proposed structure and live customer activity.
TabaPay is trying to internalize regulated banking capacity rather than relying exclusively on sponsor bank relationships. Owning an OCC chartered bank could give the payments fintech more control over settlement, sponsorship, redundancy and difficult client use cases while retaining outside bank partners. The acquisition still requires regulatory approval, making the next test whether supervisors accept that vertical integration and its governance model.
A successful Swedish licence would turn Allica's international expansion from a funding plan into regulated market access. The bank now has to prove that its UK SME model can satisfy a new supervisor and compete in a concentrated, highly digital banking market. Approval would also give Allica a potential base for wider European expansion rather than requiring each new market to begin from the UK.
The US$3 billion target gives scale to the real time receivable funding model introduced in the United States this week. VersaBank is betting that faster access to bank balance sheet funding can take business from conventional securitization and warehouse structures. Fiscal 2027 will test whether partner demand converts into several billion dollars of new assets without weakening credit quality or funding economics.
The licence adds another authorized BNPL provider while reinforcing regulatory permission as a condition of market access in Saudi consumer finance. New entrants have to compete inside that perimeter, putting more weight on underwriting, merchant distribution, pricing and compliance execution once authorization is secured.
QR Ph is extending domestic interoperability into cross-border acceptance without requiring merchants to install another payment system. That reduces one of the practical barriers to international wallet acceptance, especially for smaller merchants. The competitive question is whether national QR networks increasingly become gateways through which global payment aggregators reach local commerce.
Agorá has crossed the real-money test identified in earlier Project Agorá testing. The harder questions now concern legal finality across jurisdictions, liquidity, interoperability and whether a shared multicurrency platform can reduce correspondent-payment friction at institutional scale without weakening central-bank control or commercial-bank money.
Banks are pushing deeper into stablecoins, tokenized deposits and direct control of payment infrastructure, while fintechs are trying to own more of the regulated stack themselves. The fight is increasingly over who controls the account, the customer relationship and the transaction flow.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 4, 2026 | NCFA Insight | Digital Identity And Trust, Digital Assets Blockchain And Tokenization, Regulation And Policy
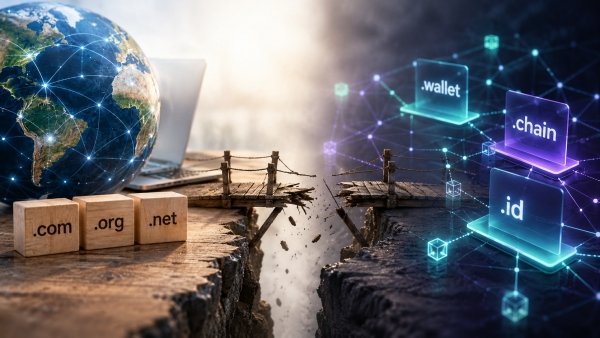
On August 10, 2026, ICANN opened a consultation on alternative naming systems that could affect how blockchain based and other naming systems work alongside the global Domain Name System. Comments are open until September 21, 2026 at 23:59 UTC.
ICANN is the nonprofit organization that coordinates the global Domain Name System, including the rules for top level domains such as .com, .org and newer gTLDs. The consultation matters most to domain registries, Web3 naming providers, digital identity firms, wallet and payment companies, cybersecurity specialists and brands that could be affected if the same name appears across multiple naming systems.
ICANN is dealing with a problem that did not exist when the DNS was designed. Alternative naming systems can create names outside the global DNS, while registry operators and potential applicants in the 2026 New gTLD Program are now interested in using some of the same top level strings in both systems. If that happens, users need confidence that the same name is controlled by the same party wherever they encounter it.
ICANN has not approved a general integration model. Its Technical Study Group is testing whether the same gTLD string can operate in both the DNS and an alternative naming system without creating unacceptable security or stability problems. The current consultation asks whether the proposed technical requirements are strong enough.
The report focuses on what ICANN calls string+controller integration. In plain language, if the same name appears in both systems, the same party should control it in both. That relationship also has to remain intact when names are registered, transferred, suspended, expire or change hands.
That becomes especially important when a name is used for identity, wallets, payments or other digital services. A human readable name only helps if users can trust who is behind it. If control changes in one system but not the other, the same looking name could point to different parties.
For fintech and digital asset firms, the risk is less about domain mechanics and more about mistaken identity. A wallet name, payment identifier or digital identity and authorization system can become easier to use, but also easier to misunderstand if two systems recognize the same string without keeping ownership aligned.
Several registry operators and potential 2026 round applicants have already asked ICANN about this kind of integration. Reviewing similar technical questions one application at a time could become expensive and slow, particularly when requests are referred for additional technical review.
The Technical Study Group was created to develop common requirements that future applicants could work from. That would not guarantee approval, but it could make the process more predictable for registries deciding whether to build services that connect conventional domains with alternative naming systems.
The consultation also comes before another policy step. ICANN says proposed registry agreement language related to these services will be published for a separate public consultation. Comments submitted now can still affect the technical work before those contractual terms are finalized.
For domain registries, Web3 naming providers, digital identity firms, cybersecurity specialists, wallet providers and affected brands, the practical questions are already clear.
Should the same party always control both versions of a name? What happens if ownership changes in only one system? And what safeguards are needed so users can tell who they are actually dealing with?
Comments close September 21, 2026 at 23:59 UTC. Affected stakeholders can submit input directly to ICANN before the deadline.
Can the same name work across two systems without creating confusion over who controls it?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
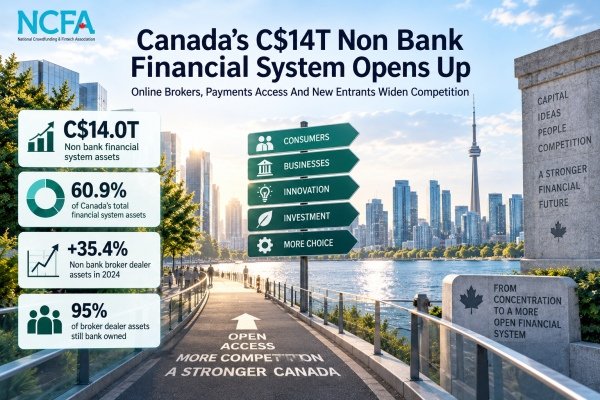
On September 3, 2026, Bank of Canada staff released new non bank finance data showing that Canada’s non bank financial sector held C$14.0 trillion in assets at the end of 2024, equal to 60.9% of the financial system. The Bank's broad definition includes pension funds, insurers, investment funds, financial auxiliaries and other intermediaries. Much of the 2024 increase also came from stronger market valuations.
The headline number is only part of the story. Faster growth is appearing in narrower bank like activities, online brokerage and specialty finance, while commercial banks still retain enormous asset and distribution advantages.
Canada already had a huge financial system outside deposit taking banks. What's changing is how customers reach it, where credit can originate and how many firms can compete for data, payments, investing and banking services.
Canada already had a vast financial system outside banks before fintech took off. Pension funds, insurers and investment funds have held enormous pools of financial assets for decades. The Bank says non bank assets have grown at an average annual rate of 6.9% since 2010.
The C$14 trillion also grew faster in 2024 because markets rose. Other investment funds increased 18.8%, pension assets rose 9.6% and insurance assets rose 9.8%. The Bank attributes much of that growth to stronger valuations.
Fintech arrived inside a financial system that was already enormous. Since then, investing has become easier to distribute online, more credit products have appeared outside traditional bank lending, payment firms have gained access to national infrastructure and financial data is being opened to approved competitors. Customers now have more ways to reach financial products without starting at a bank branch.
Online brokerage is one of the clearest changes in the Bank's data. Non bank broker dealer assets grew 35.4% in 2024, and the Bank says online brokers drove the increase.
Digital investing can win customers quickly because opening an account, moving cash and buying securities no longer requires the same physical distribution network.
The incumbents are nowhere close to disappearing. Non bank firms account for only about 5% of Canada's broker dealer assets. Bank owned broker dealers hold the other 95% of those assets.
The contrast is striking. Challenger activity is changing customer behaviour much faster than it is changing institutional asset share.
A Canadian can now invest through a digital broker, buy an ETF, hold cash inside an investing app and compare financial products without spending much time inside a traditional branch. The banks still own enormous distribution and balance sheet capacity. They no longer own every customer entry point.
Specialty finance has grown quietly beside the banks. Finance companies represent 11.8% of the narrow non bank measure and grew 7.1% in 2024. Statistics Canada includes consumer lending, corporate lending, leasing, mortgage investment corporations and mortgage finance corporations in its non bank credit work.
The official statistics have also expanded over time to capture newer models such as buy now pay later financing.
A mortgage can start outside a bank and still end up inside one. Mortgage finance corporations can originate loans through brokers and then sell them to regulated financial institutions. A borrower may meet a non bank lender first while a bank later funds or owns the mortgage.
Competition and cooperation can exist in the same transaction.
Canadian finance is becoming more distributed without becoming neatly divided into banks on one side and challengers on the other. Origination, funding, servicing, securitization and ownership can happen at different institutions. That makes the system more competitive in places and more interconnected at the same time.
Private credit shows the same Canadian pattern. Non bank loans have supplied about 15% of external funding for Canadian non financial businesses for roughly a decade. Private credit has not rapidly replaced domestic bank lending.
Canadian institutions are still heavily involved. The Bank estimates that private lending by Canadian investors plus Canadian bank lending to private credit funds totalled about C$500 billion around the beginning of 2026, with most of the activity in the United States.
Canadian pensions, insurers and banks know the asset class well. Much of the capital is simply being deployed elsewhere.
That divide is already visible in Canada's C$500 billion private credit exposure. Canadian institutions have substantial capacity to invest in private lending, while Canadian businesses still depend much more heavily on banks and public debt markets.
Payments access is opening to firms that historically could not participate directly. Payments Canada says registered payment service providers can now apply for membership and Real Time Rail participation. Wise, KOHO, Float, Paramount Commerce and Brim were among the first PSP members admitted in 2026.
The Real Time Rail is scheduled to launch in the fourth quarter of 2026 with instant clearing and settlement and support for direct PSP participation.
Financial data is opening too. Canada's consumer driven banking framework makes competition an explicit objective and creates accreditation routes for regulated financial institutions and registered payment firms.
Approved providers will be able to request customer permissioned financial data instead of relying on screen scraping or proprietary bank connections.
The opening of Canada's payments system now extends into consumer driven banking. A challenger with payment access and customer approved data has more room to build a financial relationship without depending on an incumbent for every connection.
In June, OSFI launched a streamlined approvals framework for targeted new entrants. It covers eligible credit unions and firms with technologically innovative or emerging banking models.
OSFI is aiming for a clearer three phase process and a targeted 12 month review after a complete formal application is accepted.
Foreign banks already have a formal route into Canada. OSFI assesses applications for full service and lending branches and recommends eligible applications to the Minister of Finance.
Entry is still tightly supervised. Capital, liquidity, governance, business plans, home country supervision, security and risk management remain part of the approval process.
A firm that qualifies for federal entry can pursue much more than a better financial app. Regulated banking capacity, payment access and customer approved data can put more of the customer relationship inside the challenger itself. The requirements remain demanding, but the route is clearer.
Securities rules are changing at the same time. The Canadian Securities Administrators has expanded the Listed Issuer Financing Exemption, allowed eligible venture issuers to adopt semi annual reporting and introduced other measures intended to reduce financing and disclosure friction.
In July, the CSA said more than 10% of eligible companies had already opted into semi annual reporting and that significant capital had been raised under the expanded exemption.
More financial assets do not automatically create more productivity. A pension portfolio can rise because markets rise. A fund can buy existing securities. Canadian institutions can invest abroad. None of those outcomes guarantees more financing for a Canadian company trying to commercialize technology, buy equipment or scale internationally.
That allocation question runs directly into whether Canada can turn financial access into productive participation.
The C$14 trillion headline makes the productivity problem harder to dismiss. Canada is not short of financial assets. The harder question is whether more of the system can connect viable Canadian businesses with capital on terms that let them invest, grow and compete.
The Bank itself recognizes the upside. Its paper says these non bank firms can foster innovation, increase competition, serve underserved markets and improve financial system efficiency.
The same activities can also carry leverage and transform credit or liquidity in ways that spread stress through funds, dealers and financing markets. More activity outside bank balance sheets can distribute risk while making some connections harder to see.
The Bank's 2026 work on private credit and market based finance reflects that concern without treating every non bank institution as a threat.
As activity spreads across funds, dealers, lenders and platforms, risk travels with it. Credit, liquidity, customer data and operating dependencies become harder to follow when they are shared across more institutions. Regulators have to preserve the benefits of wider competition while keeping those connections visible.
Banks still anchor the system. Their share of total financial system assets barely changed in 2024. They still dominate broker dealer assets, business lending, deposits and many of the funding relationships behind non bank finance.
The starting points are multiplying. Online brokers compete for investors. Specialty lenders compete for borrowers. PSPs can gain direct payment access. Approved providers can compete around financial data. Eligible new entrants can pursue federal regulation through a clearer process.
Canada's banks remain deeply entrenched, but more of the financial activity around them is open to competition. Incumbents keep the scale while challengers gain more ways to reach customers, move money, originate credit, raise capital and, in some cases, become regulated institutions themselves.
Talking Point
Canada already has C$14 trillion of finance outside traditional banks. More firms are now gaining ways to compete for customers, payments, data, credit and regulated entry while the banks remain dominant.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016