




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Apr 29, 2026 | NCFA Resource | Artificial Intelligence And Data, Risk Compliance And Regtech
The MIT AI Risk Repository is an open database created by researchers at MIT to bring structure to AI risk. It compiles more than 1,700 documented risks from 74 existing frameworks and studies into a single system. The aim is practical. AI risk guidance exists, but it is scattered and inconsistent across sources. This repository organizes it into a shared taxonomy, with links that show how risks connect and compound across systems.
In practice, this gives teams a consistent way to map risk across AI systems.
Teams already running AI in production will get the most from this. If you’re operating models in lending, fraud, onboarding, or customer support, it gives you a structured way to think about risk across systems. Larger fintechs and financial institutions dealing with audit and regulatory pressure will find it useful quickly. Early stage teams without deployed models will likely find it heavy and not immediately relevant.
The strength here is structure. It turns fragmented AI risk concepts into something teams can actually use, and the causal links add depth that most frameworks miss. At the same time, it does not rank risks by likelihood or impact, and it does not translate directly into controls or regulatory compliance. Some classifications reflect interpretation across sources, and emerging risks may not be fully captured. Teams still need to apply judgment and build their own control layer on top.
Repository Homepage (AI risk overview and navigation)
Full Risk Database (AI risk dataset for audits)
Causal Taxonomy (AI risk relationships mapping)
Domain Taxonomy (AI risk classification framework)
Research Paper (AI risk methodology and design)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Apr 28, 2026 | NCFA Insight | Risk Compliance And Regtech, Digital Assets Blockchain And Tokenization, Open Banking Open Finance And Data Sharing, Payments And Market Infrastructure, Capital Markets And Funding

On Apr 28, 2026, the Government of Canada released its Spring Economic Update key measures. For fintech and financial institutions, a deeper and more integrated operating model is now taking form across fraud, payments, digital assets, banking fees, data access, and capital formation. Canada wants more competition in financial services, but not at the cost of weak controls. The update points to a more disciplined market where firms can win through lower costs, faster rails, better data access, and stronger fraud prevention (at least that's the strategic read).
François Philippe Champagne, Minister of Finance and National Revenue, Government of Canada:
“From geopolitical shifts to supply chain disruptions to rapid technological breakthroughs, including in artificial intelligence, the world is changing quickly and Canada must adapt to thrive.”
The update treats fraud as a structural weakness in the financial system, not just a policing problem. Canada will establish the Financial Crimes Agency as a dedicated federal body for serious and complex financial crime, with police powers, civilian leadership, specialized personnel, and an asset recovery mandate.
The funding is material. Ottawa proposes $352.7 million over five years and $82.1 million ongoing for the agency, plus $46.2 million over five years for the Public Prosecution Service of Canada and $19.6 million over five years for the Department of Finance Canada.
For fintechs, banks, platforms, and payment firms, this raises the bar. Fraud controls now need to work across onboarding, funding, transactions, identity, communications, reporting, and recovery. A good product experience will not carry a weak risk model.
The clearest digital asset measure is the proposed crypto ATM ban. Annex 2 goes further than a policy signal. It proposes amendments to the Proceeds of Crime Money Laundering and Terrorist Financing Act and regulations to make it a criminal offence to operate a cryptocurrency automated teller machine.
Crypto ATMs connect cash to crypto quickly with limited friction, and can move scam proceeds outside the banking system before recovery becomes realistic. CBC reported that Canada has nearly 4,000 crypto ATMs, the most per capita in the world, and that some smaller deposits require only a phone number when under $1,000.
It's a targeted intervention of digital assets at what the government feels is the weakest access point. Serious crypto firms, custodians, exchanges, and tokenized finance builders should take note. Regulatory pressure will always look to where where money enters, exits, and escapes oversight.
The update recognizes that money services businesses support remittances, currency exchange, digital payments, competition, and inclusion. It also says criminals increasingly abuse MSBs for money laundering, terrorist financing, sanctions evasion, and fraud.
FINTRAC revoked the registration of 84 MSBs in March 2026 alone. Ottawa now proposes new Ministerial Directive powers, expanded authority for FINTRAC to refuse or revoke MSB registration, measures to prevent non compliant MSBs from re registering, more criminal record checks, action on shelf MSBs, and better visibility into what services each MSB actually provides.
This resets the perimeter. MSBs are now seen as critical risk gateways that can no longer just sit at the edge of the system as light infrastructure. This will help strong operators over time because weak competitors will find it harder to hide behind registration status alone.
The update links competition policy directly to household financial costs. New NSF fee rules cap charges at $10, down from $45 to $50, with expected consumer savings of more than $600 million annually. Ottawa also intends to consult on prohibiting investment account transfer fees at federally regulated financial institutions. Those fees currently cost Canadians an average of $150 per transfer.
Fee friction has long protected incumbent economics. Lower caps and easier switching reward firms that use better data, real time balance checks, clearer pricing, and lower operating costs. Fintechs should treat this as a product opening opportunity.
The update keeps consumer driven banking as part of Canada's competition agenda. It says amendments to complete the Consumer Driven Banking Act have passed, giving consumers greater control over their finances.
Annex 2 also points to related amendments involving the Retail Payment Activities Act, the Payment Clearing and Settlement Act, the Consumer Driven Banking Act, and the Stablecoin Act as part of Bank of Canada cost recovery consolidation.
Read this as infrastructure alignment. Canada is preparing the back office of regulation for a more digital financial system.
The Canada Strong Fund creates another fintech touchpoint. Ottawa describes it as a national investment initiative focused mainly on equity investments in strategic Canadian projects and companies. The government also intends to offer Canadians a widely accessible retail investment product tied to the fund.
Canada wants citizens to participate directly in national growth assets while protecting initial invested capital. If Canadians can invest in strategic projects through a national vehicle, how directly competitive will it be and what role will regulated online investment platforms, exempt market dealers, wealthtech firms, and investor education tools play?
Canada is finally becoming more competitive, albeit with a much tighter control layer. Fraud enforcement gets funding and focus. Crypto ATMs face prohibition. MSBs face deeper scrutiny. Banking fees face compression. Open banking remains active. Payments, stablecoins, and data access move into more coordinated oversight. Retail capital access gets a new public investment model.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
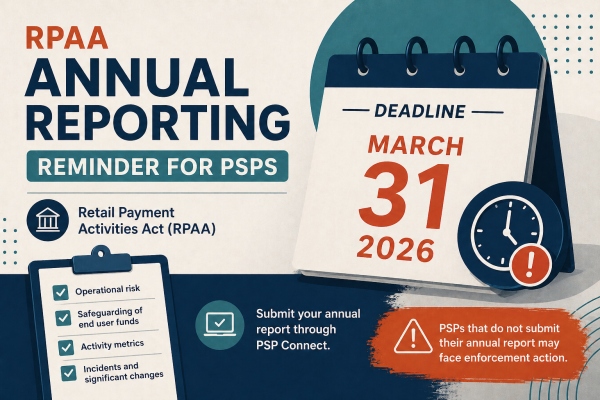
On Apr 27, 2026, the Bank of Canada reminded PSPs under the Retail Payment Activities Act that annual reports were due by March 31, 2026. PSPs registered after March 30, 2026 are not required to submit an annual report for 2025.
PSPs that missed the deadline should submit their report as soon as possible or face potential enforcement action.
The reporting framework is detailed. PSPs must follow the Bank’s annual reporting policy, which requires annual reports by March 31 each year, and its retail payment metrics policy, which covers the value of end user funds held, EFT volume and value, end users served, and other PSPs served. This turns reporting into an operating discipline (to avoid a year end scramble).
The Bank’s reporting guide shows that PSPs must report across operational risk, incident management, end user funds safeguarding, significant changes, incidents, activity metrics, financial information, and record keeping.
The form also asks about cyber security controls, third party service providers, agents, mandataries, safeguarding accounts, shortfalls, and independent reviews.
For operators, (1) data infrastructure must support audit ready reporting, (2) governance must match supervisory expectations, and (3) product design must account for regulatory visibility from day one.
For investors and partners, reporting compliance is a useful test of execution quality. Firms that can operate inside regulated environments with clean reporting, strong controls, and reliable evidence will have an advantage as oversight expands.
The Bank’s information session walks PSPs through annual reporting requirements, including required data fields, operational risk disclosures, activity metrics, and submission through PSP Connect.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 29, 2026 | NCFA Fintech Market Activity | Lending Consumer Credit And BNPL, Capital Markets And Funding
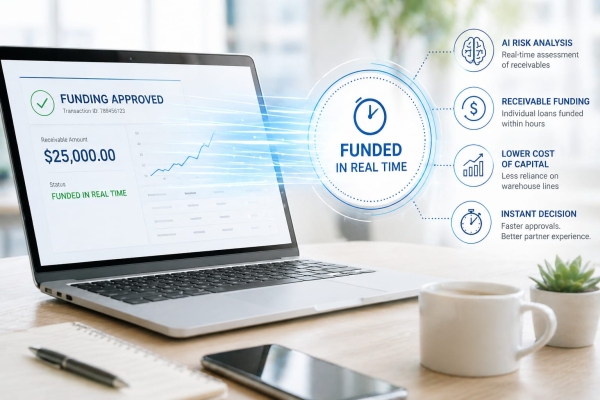
On Apr 29, 2026, VersaBank and FinanceIt Canada announce breakthrough in Real Time Structured Receivable Program pilot, an AI enabled funding model for point of sale finance receivables.
The change is in timing. Many point of sale lenders originate loans and then hold those receivables for 5 to 30+ days before financing them. VersaBank aims to fund individual receivables within hours. That shortens the gap between origination and funding and reduces the need for warehouse lines.
The program already operates at scale. VersaBank’s Structured Receivable Program portfolio exceeded CAD $4.4 billion as of Jan 31, 2026 and has grown at a 33% compound annual rate over the past five years. In the U.S., it completed more than US $310 million in fundings in its first year, above a US $290 million target.
The pilot with FinanceIt focuses on funding at or near the point of sale. FinanceIt originates consumer loans across home improvement, retail, and other merchant channels. If funding happens closer to origination, partners can reduce how long loans sit on balance sheet and lower the cost of carrying receivables.
This approach also changes how lending platforms access capital. Many point of sale and BNPL providers rely on warehouse facilities and forward flow agreements before selling loans into securitization or institutional channels. Shortening the time between origination and funding improves capital turnover and reduces reliance on those structures.
It's AI's decision support layer that's supporting faster decisions. VersaBank positions the program as using AI to assess and structure receivables in real time, allowing funding decisions without batch processing or manual review cycles.
David Taylor, President and CEO, VersaBank:
“This represents a breakthrough innovation in point-of-sale financing.”
It's the combination of faster decisioning and immediate access to capital. Funding can move closer to continuous, loan level decisions rather than batch processing. That allows capital to be deployed when a loan is approved instead of after it sits waiting in a pool. Over time, this leads to more precise pricing and better use of balance sheet capacity.
What happens when capital is deployed at the moment a loan is approved instead of days later, and which lenders are set up to operate at that speed?
Funding speed is becoming a core driver of economics in point of sale lending. When capital is deployed at origination, lenders can reduce costs and improve returns without taking on more credit risk.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 28, 2026 | NCFA Insight | Artificial Intelligence And Data, Banking And Credit Infrastructure
On Apr 27, 2026, Customers Bank announced a multiyear collaboration with OpenAI to deploy AI across commercial banking operations. The bank has nearly $26 billion in assets and already has 75% of team members using OpenAI powered tools. Customers Bank even used an AI voice clone on its last earnings call. The bigger change is how the bank is deploying AI agents across lending, onboarding, and payments.
On its Q1 call, Customers reported more than 500 internal agents and custom GPTs, over 28,000 hours saved through AI enabled workflows, and productivity gains equal to almost 15 full time employees. Q1 results also show $69.7 million in net income available to common shareholders, total deposits up $813.9 million from Q4, and total loans up $609.0 million from Q4.
Sam Sidhu, President and CEO, Customers Bancorp
“We expect a fundamental re-engineering of how Customers Bank operates. We have spent the last year building the operational and governance infrastructure to deploy AI at scale. This strategic collaboration with OpenAI gives us the frontier models, engineering expertise, and ability to co-create a roadmap toward becoming an AI-native bank."
Customers Bank wants AI inside its operating model, with OpenAI engineers working directly with the bank to automate commercial lending, deposit onboarding, and payments. The bank’s cubiX platform already processes about $2 trillion in annual payments volume, giving the collaboration a live operating base, not a pilot or lab only environment.
During Q1 2026 earnings call, Sidhu disclosed that his prepared remarks had been delivered by an AI clone, not read by him. While it was sure to be a memorable call at that point, it's important if AI can represent management's voice in a public market setting, boards need rules for disclosure, script approval, recordkeeping, and accountability before the next experiment becomes normalized.
AI banking use cases aren't just theatre. Customers Bank wants to reduce its commercial loan closing from 30-45 days to about 7 days. It also wants complex commercial account opening to fall from more than a day to under 20 minutes. They are targeting the slowest, most expensive parts of commercial banking.
This is where smaller banks and fintechs should pay attention. AI in banking won’t be won by buying a model and asking staff to use it. The value comes from redesigning workflows around agents, then keeping humans on approvals, exceptions, and risk judgement. That requires clean data, mapped processes, audit trails, escalation rules, and ownership of each AI output.
There's a regulatory approach too. Investor relations, lending decisions, onboarding, and payments all require accountable systems. If an agent drafts, routes, ranks, or speaks, the bank's still on the hook for the result. The lesson is not “let AI run the bank.” It's use AI to remove friction, but keep governance strong enough to prove who approved what and why.
Can Customers Bank turn AI from a productivity tool into an AI enabled engine powering lending, deposits, and payments?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 28, 2026 | NCFA Insight | Risk Compliance And Regtech
Image: Freepik
On Apr 26, 2026, the CBC reported that Premier Wab Kinew announced at a weekend fundraiser that Manitoba plans to restrict youth access to social media and AI chatbots.
At the time of publishing, an official government release, bill or consultation paper wasn't available so treat this as early insight rather than a confirmed regulatory event (just yet). The stronger proof is already visible in global policy patterns, so it's only a matter of time.
Australia’s social media minimum age rules took effect on Dec 10, 2025, and eSafety reported that platforms had removed access to 4.7 million under 16 accounts across Australia by mid December 2025.
In Europe, the European Commission has published minor protection guidelines under the Digital Services Act, and the European Parliament has backed a minimum age of 16 for access to social media, video sharing platforms, and AI companions.
Given the trajectory and potential risks of AI, the debate isn't just about doom scrolling any more. It's fuelling a compliance market for age assurance, safer design, and AI access controls.
Australian government's rules put responsibility on age restricted platforms to take reasonable steps, not on parents to police every account. So age restrictions and assurance are now an infrastructure issue. A checkbox, self declared birth date, or parental reminder won't satisfy regulators when millions of accounts need to be assessed, restricted, or removed.
Children can get pulled into endless feeds, autoplay videos, harmful recommendations, bullying, sexual exploitation, self harm content, eating disorder content, and late night scrolling that cuts into sleep. That's why social media is getting the attention from lawmakers first. The bigger question for fintech and digital identity comes next. Once governments make platforms check age, the same requirement can spread to other digital services used by minors.
The EU hasn't implemented a social media ban on age just yet, but it's building the infrastructure that could support stricter controls. On July 14, 2025, the European Commission released an age verification app prototype under the Digital Services Act. The Commission says the app would let users prove they are over 18 when accessing restricted adult content while keeping control of other personal information, including their exact age and identity.
The Commission’s age verification page says the solution was technically ready for implementation as of Apr 15, 2026. The blueprint also gives platforms a practical build plan. It covers the technical specs, system design, data connections, and open source code needed to support age checks. Age assurance now has to protect children without creating a new privacy problem. Platforms need a trusted age signal. Users should not have to share a full identity file just to prove they meet an age limit.
The clearest policy clue comes from Europe’s treatment of AI companions. On Nov 26, 2025, the European Parliament voted 483 in favour, 92 against, and 86 abstentions on a non legislative report calling for a minimum age of 16 for social media, video sharing platforms, and AI companions, unless parents authorize access for users aged 13 to 16.
The same Parliament release cites research that 97% of young people go online every day, 78% of 13 to 17 year olds check their devices at least hourly, and one in four minors show problematic or dysfunctional smartphone use. It also cites 2025 Eurobarometer impact of digitalisation findings that more than 90% of Europeans see online child protection as urgent, including 93% for social media’s negative impact on mental health, 92% for cyberbullying, and 92% for restricting access to age inappropriate content.
Those numbers explain why AI gets pulled into the same debate. Doom scrolling rules target addictive design and harmful content discovery. AI companion rules target interaction, dependency, personalized responses, manipulation, and adult like conversations with minors. NCFA has already examined youth AI protection risks, including lawsuits involving generative AI and vulnerable users. Regulators are starting to connect age, vulnerability, consent, product design, and AI behaviour into one compliance problem.
The public debate may start with under 16 social media bans. The business reality runs deeper. Governments want digital services to know when a user is a child, adjust the experience, and prove that controls work. Age assurance is becoming part of digital trust infrastructure. AI makes the stakes higher because the product doesn't just offer access to content anymore. It talks back, adapts, remembers, and can build dependence. That's why kid risk now part of the compliance stack. Once age becomes a regulated access condition, the same logic can reach payments, gaming, lending, investing, AI assistants, marketplaces, app stores, and identity wallets.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 28, 2026 | NCFA Fintech Insight | Capital Markets And Funding
Image: Freepik/DC Studio
On April 27, 2026, Prime Minister Mark Carney launched the Canada Strong Fund, calling it Canada’s first national sovereign wealth fund. Ottawa will seed the fund with $25B over three years and invest alongside private capital in Canadian projects tied to energy, critical minerals, infrastructure, advanced manufacturing, transport, data, telecommunications, and other national priorities.
The Canada Strong Fund is an attempt to change how Canada builds. The constraint isn't only capital. It's the shortage of investable assets that meet institutional standards on returns, timing, governance, approvals, and scale. Canada has capital but it has fewer projects that investors can underwrite with confidence compared to global peers.
The Rt. Hon. Mark Carney, Prime Minister of Canada:
"Through the Canada Strong Fund, all Canadians will have the opportunity to share directly in these benefits.”
Canada’s capital problem shows up as fewer productive assets and weaker productivity. Workers operate with fewer productive assets than peers in the United States and across the OECD. C.D. Howe Institute research shows that investment capital per worker is falling. In 2025, investment per worker in Canada is expected to be about 70% of the OECD average and about 55% of US levels.
The gap is larger in the areas that matter most for productivity. In 2024, Canada invested only about 41% as much as the US in machinery and equipment per worker, and about 32% as much as the US in intellectual property. Software investment per worker is about half US levels, while US research and development spending is roughly four times higher.
The gap is real and shows up in the economy. Canadian companies operate with fewer machines on the floor, less software across teams, and fewer systems they can scale. The Canada Strong Fund aims to close that gap by turning national priorities into projects investors can back with real capital.
The Canada Strong Fund will be seeded by the government with $25B over three years, but the outcome still depends on discipline.
Who's going to invest? Pension funds, infrastructure funds, banks, insurers, private credit, sovereign funds, and strategic corporates all have the capacity to deploy capital. Finance Canada says Canadian pension funds hold over $3T in assets.
Projects need to make money, get approved without long delays, and run with clear rules that keep politics out of investment decisions. Finance Canada says the fund will target market rate returns, operate at arm’s length through a Crown corporation, and focus mainly on equity investments. That helps align the fund with private investors. If execution slips, that alignment can break down quickly.
Alberta offers a provincial reference point launching the Heritage Savings Trust Fund in 1976, which grew from $1.5B to $31.9B by Dec 31, 2025. Over time, it also contributed more than $45.8B to public spending. That supported public priorities, but it limited compounding. A sovereign wealth fund cannot build long term national wealth if returns are regularly redirected to annual budgets.
Ottawa has also signalled a potential retail investment product that would allow Canadians to participate directly. Retail access requires clear disclosure, defined liquidity, strong suitability controls, and consistent reporting. Public participation raises the standard for execution.
On Apr 28, the federal government released the 2026 Spring Economic Update putting the Canada Strong Fund inside a broader build agenda. Capital is only one constraint. Canada also needs workers, approvals, governance, reporting, and project discipline.
Finance Canada says Team Canada Strong aims to recruit, train, and hire 80,000 to 100,000 skilled trade workers by 2030 to 2031. That matters because housing, infrastructure, energy, and major projects need enough skilled workers to turn capital into real assets.
For fintech and alternative finance, the practical role is retail access. If Canadians can invest in national projects, the experience needs to be simple, trusted, and clear. People need to know what they are buying, how risk is explained, how many flows in and out, and what kind of reporting they can expect after they invest.
Can Ottawa help build more productive assets while maintaining commercial discipline and public trust? If it can, the fund can help close Canada’s capital formation gap and give Canadians a direct stake in national wealth creation. If it cannot, Canada risks creating another financing structure that absorbs capital without improving how the country builds.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016