




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 14, 2026 | NCFA Market Activity | Wealth, Investing And Trading, Financial Inclusion, Embedded Finance
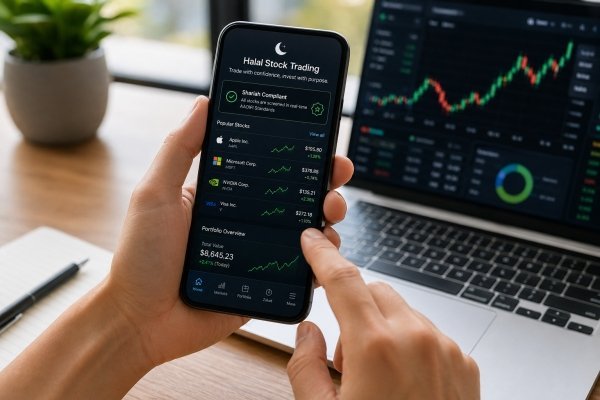
On July 14, 2026, Toronto based Islamic fintech Manzil launched self directed halal stock trading across the United States, United Kingdom, United Arab Emirates, Saudi Arabia, Qatar, and Bahrain. The service combines fractional shares, live Sharia screening, Zakat and purification calculators, and accounts that don’t pay interest on uninvested cash.
Investors can start with US$100. Manzil charges US$48 a year plus 0.4% of invested assets, although it waives the annual subscription for accounts holding at least US$100,000.
The launch extends Manzil beyond managed portfolios. Customers now choose individual stocks, while Manzil controls which securities enter the trading universe and monitors whether they remain compliant with its Sharia standards.
That changes the product from a portfolio service into an active investing account. It's also a practical model for international fintech expansion where Manzil owns the customer experience and religious compliance, while regulated partners provide the brokerage functions underneath.
Halal investing requires more than excluding companies involved in alcohol, gambling, tobacco, weapons, or other prohibited activities. A company’s debt, interest income, and other financial ratios can also affect whether its shares meet Sharia requirements.
Manzil screens its available stocks against standards set by the Accounting and Auditing Organization for Islamic Financial Institutions. Customers can’t buy a stock that falls outside the approved universe. If its status changes after purchase, Manzil notifies the investor.
The product removes several steps from the customer’s normal process into a single account. An investor no longer needs to research compliance in one service, trade through another, and calculate Zakat or income purification separately. The customer still controls each investment decision, but the software restricts the available securities and supplies the religious compliance information needed to manage the portfolio.
That's strategically differnt than say a halal exchange traded fund. Wealthsimple’s halal ETF gives Canadian investors access to a screened portfolio, but investors don't get to choose the individual companies held inside it. Manzil Trading offers direct stock selection within an approved universe.
The fee also places pressure on the product to prove its value. Many general brokerages charge little or nothing for basic stock execution. Manzil customers pay for continuous screening, religious calculations, restricted stock access, and specialized support.
That package will appeal only if it saves enough time, reduces uncertainty, and offers a wide enough selection of approved stocks. The overall compliance experience is therefore part of the product, not a marketing feature added after the trade.
Manzil isn’t building every regulated function required to operate the account. Investment advisory services are offered through Manzil Investment Advisors, a U.S. registered investment adviser. Securities are offered through Alpaca Securities, a U.S. broker dealer and self clearing brokerage provider.
The companies started working together in 2025 when Manzil launched managed investment portfolios for American Muslims. The new trading service extends that relationship from managed portfolios into customer directed stock execution.
Alpaca provides the brokerage connections, account system, custody, clearing, and fractional share access. Manzil can focus on Sharia governance, product design, education, customer acquisition, and support.
This division of work and strategic partnership lowers the cost of launching an investment product. Becoming a broker, building clearing operations, and connecting directly to markets would require far more capital, specialist staff, and regulatory approvals.
Customer access still depends on the registrations, exemptions, onboarding rules, and brokerage permissions that apply in each jurisdiction. Manzil says it is gradually expanding towards more than 100 countries, but the service is currently available in six.
The current rollout shows how a vertical fintech can enter several approved markets without recreating the entire brokerage system in each one. Alpaca handles the common transaction functions. Manzil retains control of the customer requirement that distinguishes the product.
Manzil isn’t competing only with other halal investing companies. It is also competing with the customer habit of combining a mainstream brokerage with a separate screening application, or avoiding direct stock investing altogether.
An integrated account can win when the customer requirement affects every transaction. Compliance isn’t occasional for a Muslim investor who follows Sharia rules. It determines which stocks can be bought, how holdings are monitored, and whether part of a return needs to be purified.
That gives Manzil room to build a deeper financial relationship. The company already offers managed investing, funds, home financing, savings products, and Islamic wills across its Canadian and U.S. businesses. Its halal home financing book passed $100 million in 2025, showing that its customer proposition extends beyond investing.
The growth model is commercially attractive because the same trust can support several products. A customer who uses Manzil for home financing may also use it for investing, savings, estate planning, or money management. Each product can lower the cost of acquiring the next relationship.
Its pricing strategy is being tested as it scales. At US$48 a year plus 0.4% of assets, Manzil needs customers to value the integrated experience more than a general brokerage paired with a separate halal screening tool.
For founders, the useful insight isn’t simply to target a niche. The customer requirement must change the workflow in a way that mainstream providers don’t serve well. Manzil’s religious rules affect product selection, account design, data, calculations, and customer support. That creates a stronger commercial position than branding a standard brokerage for a defined community.
Manzil is Canadian, but Canada isn’t among the first markets for its new trading service. The international product relies on U.S. advisory and brokerage entities, while Canadian investment dealers operate under a separate registration, custody, clearing, and self regulatory framework.
Manzil hasn’t said whether regulation, partner availability, economics, or product sequencing explains Canada’s absence. The launch does show that a Canadian fintech can validate a customer need at home, then use regulated foreign partners to distribute a different product across approved markets.
The customer need remains significant at home. Mohammed Sawwaf previously told an industry discussion that the lack of halal financial products excludes many Muslim Canadians from services other consumers take for granted.
Financial inclusion isn’t only about whether someone can open an account. The account must also meet the legal, cultural, or religious requirements that allow the customer to use it.
Manzil is building around that gap. Its international trading launch will show whether a specialized Canadian fintech can retain control of customer trust and product rules while licensed partners carry the regulated transaction work.
Can a vertical fintech build an international investment business by owning the customer rules and experience while regulated partners supply the brokerage system underneath?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 14, 2026
Canadian regulatory debates tend to focus on payments, open banking and digital assets. Online gambling rarely gets the same attention from the fintech community, yet Ontario's decision to open a regulated iGaming market in April 2022 stands as one of the more instructive regulatory experiments this country has run in recent years. It shows how a province can bring a large grey-market industry under domestic supervision without banning anything and without building the whole system in-house.
Under the Criminal Code, gambling in Canada is lawful only when a province conducts and manages it. For decades that phrase was read narrowly: provincial lottery corporations ran their own sites, and everything else operated offshore. Canadians could gamble on hundreds of internationally licensed platforms, but none of those sites answered to a Canadian regulator, paid Canadian taxes or followed Canadian consumer-protection rules.
Ontario's answer was structural rather than prohibitive. The province created iGaming Ontario, working alongside the Alcohol and Gaming Commission of Ontario (AGCO), and invited private operators to sign operating agreements with it. On paper, the province still conducts and manages the market, satisfying the Criminal Code. In practice, private brands compete within a supervised commercial environment. It is a workaround, but a deliberate and legally considered one, and so far it has held.
The model rests on a division of labour. AGCO acts as the regulator: it registers operators and gaming suppliers, sets standards and enforces them. iGaming Ontario handles the commercial side, including the operating agreements and the revenue-sharing arrangements that return a portion of gaming revenue to the province.
The standards themselves reach further than many observers expected. Operators must have their games independently tested for fairness, run anti-money-laundering controls, verify the age and identity of every customer, and report data to the regulator. Advertising is constrained too: AGCO later tightened its rules on marketing that could appeal to minors, including the use of athletes and celebrities. Operators that stay outside the system lose the ability to advertise legally in the province, which has proven a meaningful commercial incentive to register.
For consumers, the practical differences are easy to overlook because a regulated site looks much like an unregulated one. The protections sit underneath. Players on Ontario-registered platforms must be 19 or older and verified as such. They get enforceable complaint pathways, mandatory tools for setting deposit limits, and access to a centralized self-exclusion program that works across all registered operators rather than one site at a time.
Transparency has improved as well. Independent directories such as Canadian Online Casinos now document which operators hold registrations and on what terms, making it easier for a player to check a site's status before creating an account. That kind of third-party reference layer barely existed when the market was entirely offshore. None of this removes the risks of gambling, and the regulated model treats it accordingly: operators are required to present gambling as entertainment, encourage limit-setting and point players toward support services.
Other provinces are watching, and Alberta has already passed legislation to build a comparable market. Ontario's experience offers a few transferable lessons. First, players migrate to regulated sites when the legal offer is genuinely competitive; a restrictive market that pushes people back offshore defeats the purpose. Second, separating the regulator from the commercial entity avoids the conflict of interest that arises when one body both profits from gambling and polices it. Third, advertising guardrails are easier to set at launch than to retrofit after public complaints.
There are open questions too. Self-exclusion registries remain provincial, so a player barred in Ontario can still sign up elsewhere, and the long-term effect of regulated markets on problem-gambling rates will take years of honest measurement to establish.
For an association focused on financial innovation, the interest here is less about gambling than about method. Ontario took a digital industry that regulation had failed to reach, found a lawful structure to house it, and paired market access with enforceable standards. That template will look familiar to anyone following the open-banking file, and it deserves study for the same reasons.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 14, 2026
Many Hamilton residents decide to handle their own injury claim after a car accident. The injury seems minor, the insurance company sounds cooperative, and the paperwork looks manageable. That confidence often fades fast. Ontario's injury claim system has rules, deadlines, and settlement tactics that aren't obvious from the outside, and honestly, most people don't discover that until they're already stuck. If you've been hurt in an accident and you're wondering whether it's worth getting legal help for what looks like a small claim, the answer depends heavily on the facts of your case, the type of injury you have, and how the insurer responds. This article breaks down what "minor injury" actually means under Ontario law, how insurance companies approach these claims, and the situations where legal help isn't optional so much as it's just practical.
The classification matters more than most people realize. Under Ontario's Minor Injury Guideline (MIG), sprains, strains, and whiplash-associated disorders fall into a capped treatment category, a maximum of $3,500 in medical and rehabilitation benefits, set by the Financial Services Regulatory Authority of Ontario. That cap is brutal. A serious injury lawyer in the Hamilton area regularly sees claimants who accepted MIG treatment limits without knowing they qualified to be moved out of that category entirely. Insurers have a direct financial reason to keep you inside the MIG, because staying there limits what they pay out. You don't necessarily know that a psychological condition, a pre-existing injury, or a delayed diagnosis can all support a reclassification request if it's properly documented.
Not everyone who walks away from a crash with a soft tissue injury is stuck under the $3,500 MIG cap. Ontario's insurance regulations let claimants move outside the MIG if they have a documented pre-existing condition aggravated by the new injury, or if they develop a psychological impairment because of the accident. Both exceptions require proper medical documentation, usually from your family doctor, a physiotherapist, or a psychologist. The insurer won't flag this for you. You need to build and submit that evidence yourself, or have a lawyer do it, because missing this step means accepting a $3,500 ceiling on rehabilitation costs when you may have been entitled to far more. Injuries that feel minor at first can carry financial consequences that aren't apparent until weeks or months later. By that point, some claimants have already signed a settlement.
Reclassification doesn't happen automatically. It requires an OCF-18 (Treatment and Assessment Plan) from a regulated health professional, plus supporting clinical notes that connect the new injury to the pre-existing condition or psychological impact, and insurers can dispute every piece of it. That dispute triggers a formal examination under Ontario's dispute resolution process, a system with its own timelines and procedural rules that most claimants don't know exists until they're already caught inside it. Missing the filing deadlines closes off benefits you were eligible for. The MIG cap is low enough that the difference between staying inside it and getting reclassified can run to several thousand dollars in treatment costs, even when the original injury seemed small.
Insurance adjusters are trained to close files quickly and economically. That's not a criticism. An early settlement offer, sometimes made within days of an accident, can feel like genuine relief, but it's legally binding once you sign, and it typically includes a full release of any future claims. Symptoms worsen after settlements more often than people expect, and at that point there's no recourse. Ontario's no-fault accident benefits system and tort claims operate on different tracks, and a signed release on one doesn't always protect you on the other; understanding which system you're actually dealing with takes some working out. Whether you have a viable tort claim against an at-fault driver on top of your accident benefits isn't something most people get right the first time through.
Early offers are almost never the best offer. Insurers carry claims data telling them, at a statistical level, how much a given injury type costs to resolve. Their first number reflects their ideal outcome, not a fair assessment of your losses. Soft tissue injuries can take four to six weeks to stabilize, and a small percentage of apparent whiplash cases develop into chronic pain, so signing a release before you know your prognosis is a real risk. You're also dealing with a professional adjuster who knows the system far better than you do. None of this means every early offer is a trap. But you should know what you're signing before you sign it, and a second opinion on the value of the claim costs very little at this stage.
Not every minor injury claim needs a lawyer. If your injuries are fully resolved, your treatment costs fall within the MIG cap, the insurer accepts your claim without dispute, and you understand exactly what you're signing, handling it yourself is a reasonable choice. Rarely do all those conditions line up together. The more common situation is that one or more of those elements is uncertain: symptoms haven't fully resolved, the insurer has raised a dispute, or you've received an offer that seems low, but you're not sure by how much. In those situations, the cost of getting it wrong outweighs the time it takes to speak with a personal injury lawyer, and most offer free consultations, so the barrier to a professional read on your situation is genuinely low.
There are several situations where trying to manage a minor injury claim alone creates real risk:
Any one of these factors changes how complicated your case is. And the two-year limitation period for tort claims in Ontario means that delaying too long to get advice can permanently close off legal options.
Whether you need a lawyer for a minor injury claim in Hamilton isn't a yes-or-no question with a fixed answer. It turns on your injury, the insurer's response, your treatment costs, and whether a viable tort claim sits alongside your accident benefits file. The system is more technical than it looks. Financial consequences of mishandling even a "minor" claim can be outsized, and if your situation involves any disputed benefits, a possible reclassification out of the MIG, or an early settlement offer you're unsure about, getting a legal opinion before you commit to anything is the straightforward move. Most personal injury lawyers in Hamilton offer free consultations. There's no real cost to asking the question before you sign anything.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 13, 2026 | NCFA Market Activity | Cybersecurity And Fraud, Artificial Intelligence And Data, Banking And Credit

On June 25, 2026, Jack Henry expanded its Google Cloud collaboration to develop agentic AI security for banks and credit unions. The U.S. banking technology provider serves about 7,400 community financial institutions and plans to combine Google Security Operations, Gemini Enterprise Agent Platform, and Mandiant Consulting across Google Cloud, other cloud services, and on-premises systems.
The deal is less about access to an advanced model than the work required to deploy one inside a bank. Security evidence is spread across user accounts, devices, applications, networks, and cloud services. Analysts must connect those records quickly enough to determine whether an alert is harmless or part of an attack. Smaller institutions often lack the security teams and integration capacity to do that across several enterprise products.
The divide and conquer commercial logic of the deal is Google brings the models, security software, and threat expertise. While Jack Henry brings the bank relationships and operating knowledge required to put them to work.
Google Security Operations collects security data from across an institution’s systems and connects related alerts into an investigation. Its Triage and Investigation Agent can retrieve evidence, apply threat intelligence, assess likely causes, and explain its findings.
Google says the agent has processed more than five million alerts and reduced a typical 30-minute manual investigation to about 60 seconds. Those are Google product results, not outcomes reported by Jack Henry customers.
The operating gain comes from completing the early investigation before an analyst steps in. Instead of opening several products, finding related records, and rebuilding the sequence of events, the analyst receives an assembled case with supporting evidence and a proposed response.
Sensitive actions still require clear limits and human oversight. Google can pair AI investigations with fixed playbooks and require approval before isolating a device, disabling an account, or blocking traffic. Jack Henry hasn’t said where it will draw those boundaries, how customers will audit agent decisions, or what happens when an automated recommendation is wrong.
Release timing, pricing, implementation requirements, and the first participating institutions also remain undisclosed, so the announcement is good on tech direction but light on adoption or performance figures inside an operating bank.
Mandiant Consulting adds threat modelling, security assessments, and red team testing. That work tests the design before attackers do. Gemini handles reasoning, while Google Security Operations provides the data and investigation tools.
Jack Henry must make the combined service fit each institution’s systems, controls, and support model. That integration is the difficult part.
A bank could buy Google’s security products directly. It would still need to connect the right data, define agent permissions, build response procedures, satisfy audit requirements, and decide who remains accountable for each action.
Jack Henry already operates inside that environment. Its core processing, digital banking, payments, lending, and operational products support institutions that rarely replace critical systems. It also manages hosted and on-premises deployments that a cloud provider may not control.
The companies began working together in 2022 on cloud data, reporting, and integration services. Security extends that relationship into a product Jack Henry can configure around each customer and deliver through an existing technology and support contract.
That could make AI security another banking software service rather than a separate enterprise purchase. Core providers already control the connections, implementation work, and customer access needed to distribute agents at scale.
Security specialists still compete on detection quality, threat intelligence, and response tools. CrowdStrike and Palo Alto Networks are adding agents to their products, while Fiserv offers managed cybersecurity services and is developing AI capabilities. Jack Henry competes from a different position. Its advantage is knowing how community institutions run and where security tools must connect.
Google gains a route into thousands of regulated institutions without implementing its products one bank at a time. Jack Henry can add a service whose value depends on its knowledge of each customer’s systems and operating requirements.
This is where enterprise AI economics become clearer. Foundation models can be sourced from a small group of large providers. The commercial asset is access to the workflow where the model can complete useful work under controlled permissions.
That favours software companies with deep customer integration. Fintech founders don’t need to build a foundation model, but a general AI interface won’t be enough. TD’s AI loan decisioning deployment shows why the value comes from placing verification and decision tools inside an active lending workflow. A specialized process, regulated decision, proprietary dataset, or difficult integration gives an agent work that an incumbent can’t easily reproduce.
Jack Henry hasn’t announced a Canadian release, but the deployment problem is familiar. Canadian regulated AI workshops have identified vendor dependence, data quality, model validation, and accountability as barriers to production use.
Access to a capable model isn’t the constraint. Banks need to connect it to existing systems without losing control of data, permissions, decisions, or operational risk. National Bank’s Sardine deployment follows that reality by embedding external device intelligence and risk scoring into retail, commercial, and wealth operations.
The Canada AI Consortium is working on common controls for models, agents, users, and enterprise systems. Its use cases differ from Jack Henry’s security project, but the operating requirement is the same: agents need restricted access, visible decisions, and accountable people.
For Canadian banks and fintechs, the commercial challenge is solving those controls inside regulated workflows. Products that leave the integration and governance work to the bank may struggle to progress beyond a pilot.
As foundation models become easier to replace, will banking software competition depend less on who owns the AI and more on who controls the workflows where agents can act?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Payments Canada says Canada’s Real-Time Rail (RTR) By-law and Rules received all necessary approvals on June 30, 2026, take effect August 24, 2026, and support a planned Q4 2026 launch. RTR is Canada’s new real-time exchange, clearing and settlement system for instant, data-rich payments.
The approved Rules establish participant roles and the legal operating framework, but they do not provide automatic access. PSP participation can also require RPAA registration where applicable, Payments Canada membership, a direct or agent settlement model, ISO 20022 integration, centralized fraud services, testing, certification and continuous operations.
Coverage includes the RTR By-law, RTR Rules, public policies, PSP participation pathways, direct and indirect settlement, centralized fraud controls, ISO 20022, payment finality, testing, phased launch and the capabilities the framework can support.
Use this Regulatory Intelligence page to understand what is now approved, identify the operating path that fits your role, follow the dependencies behind each capability and open the official documents needed for implementation.
RTR is the result of a decade-long modernization effort, not a 2024 initiative. The journey includes early design work, vendor selection, missed launch targets, a 2023 delay acknowledgement, a 2024 program restart, legal consultation, rule approval and the current transition toward production.
This is the overview readers need before entering the detailed framework. It separates the changes now settled in the approved legal framework from the implementation work that still determines who can participate, how they connect and what they can offer.
The By-law and Rules establish the formal basis for payment-message exchange, clearing, settlement, participant roles, compliance, recourse and system operation. Implication: planning can proceed against approved rules rather than draft policy.
Canadian Payments Act changes and RPAA registration allow eligible PSPs to seek Payments Canada membership and RTR participation. Implication: eligibility opens the route; it does not grant automatic membership, direct settlement or production access.
Organizations may pursue direct settlement, use a settlement agent, build customer products through an RTR participant or provide connectivity and software services. Implication: control, cost, time and continuing obligations differ materially by pathway.
Direct settlement requires a Bank of Canada RTR settlement account; other participants may rely on a settlement agent. Implication: liquidity, funding, contracts, resilience and operating responsibility change with the settlement model.
Confirmation of Payee, Central Fraud Analytics, the Central Risk List and Central Fraud Reporting complement participant controls. Implication: firms must integrate, contribute data, make documented decisions and support continuous fraud operations.
Technical specifications, ISO 20022 mapping, security, testing, certification, operational readiness and 24/7 support remain production gates. Implication: time and cost now shift from rule uncertainty to execution readiness.
Choose the role you want to play, confirm whether RPAA registration applies, and map the Payments Canada membership, settlement, fraud, testing and 24/7 operating work that follows.
Start with the customer result you want to deliver. Then compare direct participation with partner, software, connectivity or managed settlement routes before committing to the highest-cost model.
Rule approval removes one source of uncertainty. The next signals are participant approvals, settlement agreements, certification, pricing, product launches, customer adoption and fraud performance.
Select any item to see what it requires, what it enables and where to go next. Follow the highlighted connections from legal authority and operating rules into participation, controls, customer use cases and infrastructure opportunities. For product nodes, the right panel also points to the numbered shared-rail functions shown directly below this map.
Select the role closest to the operating model being considered. The pathway below shows the sequence of gates, the regulatory and operating work that increases cost or time, what the route unlocks and where a lighter model may be available.
Move from the RTR rules into the distinct regulatory, implementation, competition and innovation questions that affect market entry and commercial deployment.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 4, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Digital Assets Blockchain And Tokenization, Cybersecurity Fraud And Financial Crime, SME Finance And Business Banking, Capital Markets And Market Infrastructure, Policy Regulation And Governance, Risk Compliance And Regtech, Data Privacy And Governance

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026).
AI training data now carries an auditable collection burden across source choice, legal basis, sensitive data and model output controls. Canadian fintechs using European personal data should map what is scraped, why it is needed, who controls the processing and how records can be filtered or removed before consultation language becomes supervisory practice.
Fund innovation depends on regulatory speed as well as product design. Asset managers, exchanges, fintechs, wealth platforms and regulators should watch how dedicated approval pathways and product specific guardrails influence the pace of retail investment innovation without reducing investor protection.
Swift is testing whether tokenized deposits can extend today's banking infrastructure into always available cross border payments without replacing existing settlement systems. The pilot results will provide an early benchmark for bank led tokenized payment networks.
Always on market design is moving beyond crypto. Exchanges, brokers, clearing firms, liquidity providers, risk teams and regulators should watch how 24/7 trading changes oversight, operations, margin, surveillance and market resilience.
Credit infrastructure is consolidating around data depth, identity coverage and alternative underwriting. Lenders, fintechs, credit bureaus, SME finance platforms and regulators should watch how alternative data, fraud controls and AI assisted decisioning affect credit access for thin file borrowers and small businesses.
Hong Kong is replacing a widely used authentication method across online securities and regulated virtual asset trading. Brokers and platforms also need stronger monitoring, client notifications and incident response procedures, while senior management may be held accountable for losses caused by inadequate controls.
The findings connect payment design directly to fraud exposure, customer friction and trust. Lower fraud by transaction count is encouraging, but higher losses by value and rising first-quarter fraud show why scale requires stronger authentication, transaction risk data and coordinated controls. These operating results add important context to the UK’s payment milestone and Canada’s trust framework.
Financial institutions and technology providers will gain a structured environment for testing AI security tools against European requirements. Firms serving the European market should prepare to demonstrate model safety, operational resilience and secure deployment before advanced systems enter critical financial operations.
AI cyber risk is now a financial stability issue. Banks, fintechs, payment firms, infrastructure operators, software vendors and supervisors should watch how AI vulnerability discovery, third party concentration, open source dependencies and cyber resilience planning become part of financial sector oversight.
Circle's trust charter places a major stablecoin issuer inside the U.S. federal banking framework. The pace of implementation, custody adoption and any future expansion into reserve management will show whether trust banks become the preferred operating model for regulated stablecoin infrastructure.
The paired licences let one regulated provider connect crypto conversion, asset transfers, conventional payments and payment accounts. Firms pursuing similar models across Europe will need to determine when MiCA authorization must be combined with payment permissions as their products cross from digital assets into fiat payment execution.
Crypto platforms are moving toward regulated multi-asset investment access. Exchanges, brokers, dealers, crypto platforms, regulators and investors should watch how derivatives, equities and crypto converge inside licensed investment platforms.
MiCA is becoming a market access gate for global digital asset firms. Banks, payment companies, custodians, stablecoin issuers, exchanges and compliance teams should watch how full EU authorizations shape cross-border crypto services, institutional distribution and regulated stablecoin infrastructure.
Eltropy is turning agentic banking into a platform market rather than a closed vendor product. The commercial question is whether shared controls, integrations and distribution can make specialized financial agents easier for smaller institutions to adopt.
Regulated AI adoption needs control infrastructure, not only models. Banks, insurers, telecoms, fintechs and compliance teams should watch how agent oversight, inference monitoring, shared IP and enterprise control planes become part of Canadian AI governance.
AI in retail finance is becoming a competition, consumer protection and fraud issue at the same time. Banks, fintechs, wealth platforms, insurers, lenders and compliance teams should prepare for AI agents, personalization, delegation, identity controls and new forms of consumer harm.
Large fintechs are testing direct charter strategies again. Lenders, BNPL firms, embedded finance platforms, banks, investors and regulators should watch whether major payment and credit firms choose bank partnerships, owned charters or hybrid models for the next stage of regulated growth.
Regulators are increasing both the reach and speed of financial misconduct enforcement. Firms now face faster detection, coordinated action across jurisdictions and far less time to correct weak promotion, reporting and compliance controls.
This week’s intelligence points to a more mature phase of financial innovation. Stablecoins are entering regulated banking structures, tokenized deposits are nearing live payment use, regulators are setting terms for continuous markets, and AI governance is becoming a practical operating requirement. In Canada, the Real Time Rail rules, PSP access model and planned Q4 launch show how domestic payment modernization is entering the same execution stage. Advantage will favour institutions that can combine trust, regulatory readiness and delivery at scale.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jul 10, 2026 | NCFA Resource | Payments And Money Movement, Regulation And Policy, Risk Compliance And Regtech

Canada’s Real-Time Rail is Payments Canada’s new exchange, clearing and settlement system for instant, data rich payments. Its approved By-law and Rules establish the legal and operating framework for PSP access, participation, settlement, fraud controls, ISO 20022 implementation, testing and the planned Q4 2026 launch.
On July 10, 2026, NCFA published a Real-Time Rail Rules and Access Intelligence Guide that brings the requirements, participation routes and operating considerations into one practical reference.
The guide covers the RTR By-law and Rules, Payments Canada membership, PSP access, direct and indirect settlement, Bank of Canada settlement accounts, centralized fraud controls, technical integration, payment finality, operational readiness and the products and services the rail could support.
The resource helps readers separate what has been approved from the work still required before an organization can participate in the RTR or launch a product using it.
Legal eligibility does not create automatic access. Depending on the operating model, a firm may still need RPAA registration, Payments Canada membership, a direct or agent settlement arrangement, ISO 20022 integration, fraud service connectivity, security controls, testing, certification and continuous operations.
The guide also compares different routes into the market. Organizations may pursue direct settlement, work through a settlement agent, develop customer products through an RTR participant or provide software, connectivity, fraud, testing and managed access services.
This resource is useful for payment service providers, banks, credit unions, fintech founders, infrastructure providers, fraud and identity firms, compliance teams, investors, policymakers and organizations assessing real time payment products.
It is especially useful for teams working through access, settlement, liquidity, fraud controls, ISO 20022, testing, certification, payment initiation, pay by bank, treasury, reconciliation and embedded payment models.
The strength of this resource is that it brings Canada’s RTR rules, access requirements, settlement choices, fraud services and implementation dependencies into one working reference. It also explains how real time payments connect with consumer driven banking, data portability and the next generation of digital financial services.
The guide can also help firms choose a realistic operating role before committing to the cost and continuing obligations of direct participation. Direct settlement provides more control, while partner, software, connectivity and managed settlement models may offer a more practical route to market.
The limit is that approval of the By-law and Rules does not complete implementation. Technical specifications, participant onboarding, commercial agreements, testing, certification, pricing, product launches, customer adoption and fraud performance will continue to develop.
Readers should use the guide for ecosystem intelligence and planning, not as legal, financial, investment, compliance or professional advice.
Canada Real-Time Rail Rules And Access (primary NCFA Regulatory Intelligence page)
PSP Registration With The Bank Of Canada (RPAA registration and supervision)
Open Banking In Canada Opportunity Brief (payment initiation and open finance opportunities)
RTR By-law And Rules Approval (official Payments Canada update)
Payments Canada Real-Time Rail (official system hub)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016