




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


August 31, 2026 | NCFA Insight | Artificial Intelligence And Data, Competition And Market Structure, Data Privacy And Governance
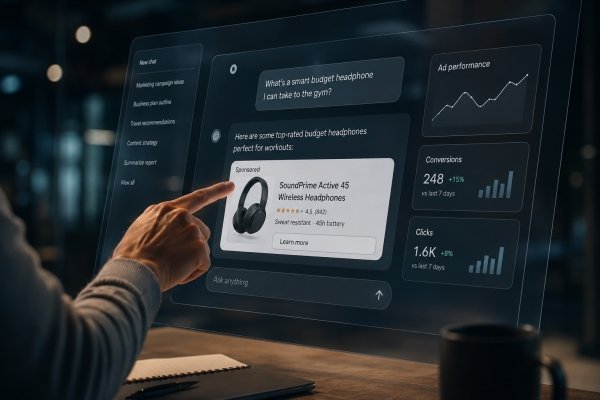
On August 31, 2026, OpenAI said ChatGPT Ads reached a US$1 billion annualized revenue run rate in less than 200 days. Tens of thousands of advertisers are using the platform, OpenAI reports more than one billion weekly active ChatGPT users, and ads are available across more than 40 countries through direct sales, agencies and technology partners.
US$1 billion is a run rate, not revenue already collected. At that pace, ChatGPT Ads would produce roughly US$250 million per quarter. That's small beside the companies OpenAI now competes with for advertising budgets, but getting there in less than seven months gives advertisers, competitors and regulators something tangible to watch.
Notably, on the same day OpenAI announced the milestone, European regulators designated ChatGPT a Very Large Online Search Engine under the Digital Services Act. In the United States, the FTC and 22 states sued Amazon over alleged practices in its advertising auctions. Google is already operating under court ordered search remedies after losing a U.S. monopolization case.
OpenAI is building its advertising business in a market where regulators already know how digital distribution, auction rules, data and default positions can concentrate power.
ChatGPT Ads started as a U.S. test on February 9 for adult Free and Go users. Canada, Australia and New Zealand followed in the spring. OpenAI added self service Ads Manager and cost per click buying in May, expanded into the U.K., Mexico, Brazil, Japan and South Korea in August, and is now adding more markets across Europe, India, the Middle East and North Africa.
The product itself has grown just as quickly. CPC and outcome optimized bidding now account for most campaigns, according to OpenAI. Advertisers can use Pixel and Conversions API measurement, product feeds, geographic targeting and custom audiences, while more than 50 technology and measurement partners connect businesses to the platform.
OpenAI says one ecommerce advertiser produced a 3x return on ad spend over 28 days, while one technology partner reported that more than 80% of traffic generated by ChatGPT ads came from new customers. Those are select examples supplied by OpenAI, so they shouldn't be treated as typical campaign performance. OpenAI also says it doesn't yet have reliable performance benchmarks across industries and campaign types.
Back in February, NCFA asked whether conversational advertising could develop into a new route for product discovery. Six months later, OpenAI has a US$1 billion annualized ad run rate, self service buying, conversion tools and tens of thousands of advertisers. Businesses will pay to advertise inside AI conversations, and enough of them are doing so to create a sizable new revenue stream.
Alec Shao, Newegg performance marketing manager, an advertiser on OpenAI's own ads site explains the attraction directly:
“We want Newegg to be part of the conversation when someone is researching what to buy.”
OpenAI isn't close to Google in advertising revenue. Alphabet reported US$81.63 billion of Google advertising revenue in Q2 2026. Search and other advertising alone generated US$63.27 billion, up from US$54.19 billion a year earlier.
Meta generated US$59.36 billion of Q2 advertising revenue, while Amazon generated US$19.81 billion from advertising services. OpenAI's roughly US$250 million quarterly equivalent makes clear how much ground separates a fast growing new entrant from established digital advertising businesses.
However, ChatGPT offers advertisers something those numbers don't capture. Search advertising usually begins with a query. Social advertising often begins with interests, behaviour and attention. Amazon can catch a shopper close to purchase. A ChatGPT conversation can contain a goal, budget, constraints, preferences and several rounds of comparison before an ad is selected.
OpenAI says its ad system considers the context and intent of the current conversation, the ad and landing page, advertiser supplied context hints and, when personalization is enabled, selected information from a user's wider ChatGPT experience. Advertiser hints describe relevant conversations, topics or keywords, but they aren't exact match search keywords.
The auction is already becoming familiar territory for performance marketers. OpenAI supports CPM and CPC buying and recommends starting CPC bids around US$3 to US$5. It says eligible ads compete through a relevance weighted second price auction.
Whether a detailed conversation produces a better customer than a search keyword hasn't been established. Advertisers now have enough buying and measurement tools to start finding out.
Regulators may reach AI advertising earlier than they reached search and social platforms. Google is already operating under court ordered search remedies, while Amazon now faces allegations over how its ad auctions were priced. OpenAI is entering the same commercial territory with regulators already alert to distribution control, auction transparency, data use and platform power.
ChatGPT Ads is still small beside Google, Meta and Amazon, but it reached a US$1 billion annualized run rate in less than 200 days. Regulators may not need to wait for comparable scale before asking how the market works, especially if distribution, data or auction rules begin limiting competition.
Canadian advertisers can already create and manage ChatGPT Ads through OpenAI's self service Ads Manager, with a minimum daily budget of C$25. Canadian financial firms face an important limit, though. OpenAI currently generally prohibits financial services ads outside the United States, where approved advertisers can be accepted case by case for products such as credit cards, mortgages, brokerages, insurance, loans and payments.
OpenAI treats financial services as a restricted category requiring extra safeguards, including enhanced advertiser verification or manual review, and says advertisers may have to prove they are properly licensed.
Financial software, budgeting tools and educational products may have more room to experiment. For firms that can participate, can ChatGPT produce customers at a better cost and with stronger intent than search, social media, affiliates or other channels?
Will regulators act on AI advertising before market power becomes difficult to unwind?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
August 31, 2026 | NCFA Market Activity | Digital Assets Blockchain And Tokenization, Wealth Investing And Trading, Competition And Market Structure, Capital Markets And Market Infrastructure
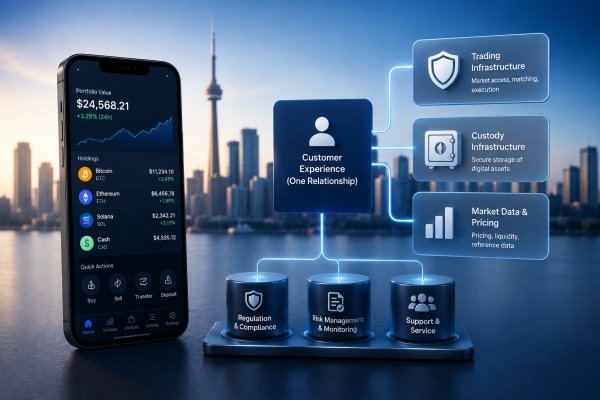
On August 31, 2026, Coinbase announced its Webull Canada partnership, supplying the trading and custody services behind Webull's new Canadian crypto offering. Webull maintains the investor relationship and brokerage experience, while Coinbase handles two core crypto functions. The same partnership already supports Webull in the United States, Brazil and Australia.
Webull Canada Crypto Limited was registered as an Investment Dealer and admitted to CIRO membership effective June 17, 2026. Coinbase Canada, Inc. is registered as a Restricted Dealer across Canada.
Crypto arrives after Webull spent more than two years expanding its Canadian brokerage. It launched here in 2024 with Canadian and U.S. equities and later added registered accounts, options, cash management, desktop trading and longer trading hours. Canadian stocks and ETFs now trade at zero commission, while selected securities are available around the clock five days a week.
When Webull entered Canada, its offering was much narrower. The company has since added enough products that crypto now joins an account already spanning stocks, options, cash, margin, TFSAs and RRSPs.
Using Coinbase lets Webull add crypto without building its own trading and custody systems from scratch. It can use infrastructure already supporting the same partnership elsewhere, reducing the amount of technology and operating capability Webull has to build internally.
Webull still has to persuade Canadians to use the product. The company reports 26 million registered users globally but doesn't disclose its Canadian customer count, leaving a large gap between the breadth of its local product menu and what outsiders can see about actual adoption.
A Canadian investor trading crypto through Webull remains inside Webull's experience, but Coinbase can still earn from the trading and custody taking place underneath it.
Coinbase has been selling more of those capabilities to financial institutions. Its Crypto as a Service business targets banks, brokers, fintechs and payment companies that want to offer digital assets without building everything themselves. Coinbase said in 2025 that more than 200 institutional clients were already using its infrastructure.
Webull gives Coinbase another customer for that business while Coinbase continues competing directly for Canadian crypto users through its own platform. The two companies can pursue the same investor from different positions. Webull wants the account and ongoing customer relationship. Coinbase can benefit whether the investor chooses Coinbase directly or reaches its services through Webull.
Webull is relying on Coinbase for key parts of the service. If trading, custody, pricing or service problems arise, Webull still has to deal with the customer impact.
Webull isn't alone in combining its own customer experience with outside financial infrastructure. Wealthsimple offers stocks, cash and crypto from one relationship, while its regular crypto service uses external custodians including Tetra Trust, Coinbase Custody and BitGo. Its recent in app DEX trading beta uses a different model, creating a self custody wallet for the client and routing trades through a third party DEX aggregator.
Crypto focused firms such as Coinsquare, Newton and Shakepay started from a different approach, building their customer relationships around digital assets before adding more services. Webull started as a brokerage and is bringing crypto into an account already built around conventional investing.
Customers can now see a growing number of competing apps even when some important functions behind those apps come from the same suppliers. If several brokers rely on a small group of firms for custody, execution or liquidity, competition at the customer level can grow faster than the number of companies providing the underlying services.
Building everything internally isn't automatically better and often depends on the lifecycle stage of the firm and target customer base. It can preserve more control and economics, but it also brings technology, security, compliance and operating costs. Buying specialist infrastructure can get a product to market faster, provided the platform is comfortable with the dependency and the economics.
Webull has removed many of the obvious product gaps since entering Canada. Investors can now trade Canadian and U.S. equities, options and crypto, use registered accounts and access longer trading hours. Another product won't automatically pull customers away from Wealthsimple, established brokerages or dedicated crypto platforms.
Existing Webull users may be the easiest audience. They can add crypto beside the rest of their portfolio without opening another trading relationship. Whether that convenience produces meaningful Canadian crypto activity won't be clear until Webull discloses more about adoption or the market provides other evidence.
Coinbase receives another benefit if the model continues to expand. Its Webull relationship now spans four countries, so a successful Canadian launch gives Coinbase another example it can use when selling trading and custody services to other financial firms. It doesn't need its name on the customer's home screen to participate in the transaction.
Webull and Coinbase are building different businesses from the same Canadian launch. One wants to own more of the investor relationship. The other can earn by supplying financial functions to companies that already have one.
As financial apps buy more of what they offer from specialist providers, who keeps more of the long term value: the company with the customer or the company running the service underneath?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 31, 2026 | NCFA Market Activity + Insight | Banking And Credit, Competition And Market Structure, SME Finance And Business Banking, Consumer Finance And Lending

On August 31, 2026, Laurentian Bank confirmed the final key regulatory approvals for Fairstone Bank to acquire Laurentian and for National Bank to take its retail and SME banking portfolios. The parties expect to close on November 1, 2026, with Laurentian retail and SME products and services scheduled to migrate to National Bank by late 2026.
National Bank gets deposits, borrowers and customer relationships it can run on a much larger banking platform, while Fairstone gets Laurentian's commercial bank and lending capabilities that would take years to build. Canada loses a long standing independent full service bank, but the transaction also gives a growing specialty lender more commercial depth while strengthening National Bank's customer base.
Laurentian reached this point after a difficult 2023 and 2024, followed by a partial recovery in 2025. A strategic review ended without a sale, a major technology outage was followed by leadership changes, restructuring costs climbed and loan volumes weakened. Commercial lending was growing again by 2025, which helps explain why Fairstone wanted the commercial bank while National Bank wanted the retail and SME portfolios.
Fairstone Bank will acquire all outstanding Laurentian common shares for C$40.50 each, valuing the transaction at approximately C$1.9 billion in cash. National Bank will take Laurentian's retail and SME portfolios, which held approximately C$3.6 billion of loans and C$7.5 billion of deposits at July 31, 2026. Final cash consideration for those portfolios will depend on balances at closing, and Laurentian has said the transaction would approximate net book value using earlier reference balances.
National Bank also acquired Laurentian's C$705.7 million syndicated loan portfolio for C$646.2 million in February plus certain assumed liabilities. The Minister of Finance, OSFI, CIRO and relevant securities regulators have approved the transactions, while the Competition Act condition has been satisfied subject to no change in circumstances involving the Competition Bureau.
Closing remains targeted for November 1. Laurentian retail and SME customers are expected to migrate to National Bank by late 2026, while Laurentian's retail branches and employees do not transfer with the portfolios. Laurentian is responsible for closing the branches and terminating or reassigning affected employees before closing.
Laurentian's board launched a strategic review in July 2023 that considered a sale, divestitures and other options. By September it had decided to remain independent and focus on efficiency, simpler operations and businesses where management believed the bank could compete.
Weeks later, a planned IT maintenance update led to a mainframe outage that disrupted customer services. Éric Provost replaced Rania Llewellyn as CEO on October 2, while Michael Boychuk became board chair. The outage did not determine Laurentian's future on its own, but it exposed an operational weakness at a bank already trying to modernize and regain customer confidence.
The cleanup was expensive. Laurentian cut staff, closed its equity research business, reduced office space, suspended its Advanced Internal Ratings Based credit project and simplified technology and operations. It recorded C$228.4 million in impairment and restructuring charges in fiscal 2024 and reported a C$5.5 million annual net loss, compared with C$181.1 million of profit the previous year.
Total net loans fell by C$1.8 billion in 2024, including declines in commercial, personal and residential mortgage lending. Laurentian cited high interest rates, weaker loan demand, volatile markets and changes in its lending mix. Its disclosures do not establish Canada's later immigration, temporary resident or international student policy changes as a material cause of mortgage volumes, deposits, credit performance or the eventual transaction.
Commercial lending then recovered. By October 2025, commercial loans had grown 8% from a year earlier to C$17.9 billion, led by commercial real estate, inventory and equipment finance, while deposits reached C$24.0 billion. Laurentian had repaired enough of its commercial business to make that franchise attractive even though keeping retail, SME and commercial banking together no longer produced the strongest outcome.
National Bank is buying customer portfolios rather than Laurentian's retail operating structure. It gains loans, deposits and established relationships without taking Laurentian's branches or retail employees, allowing those customers to be served through National Bank's existing digital services, physical network and product range.
The transaction follows National Bank's acquisition of Canadian Western Bank, but the job is different. CWB brought a complete regional banking franchise. Laurentian brings selected customer books, reducing the amount of physical infrastructure National Bank has to absorb while still adding deposits and borrowers.
Fairstone is buying the part of Laurentian that complements its own lending strategy. Home Trust brought alternative mortgages, deposits, GICs and broker distribution, while Fig added digital lending and API based distribution. Laurentian adds commercial real estate, equipment finance, inventory finance, United States lending and capital markets expertise.
Those commercial capabilities were built over years, including Laurentian's 2017 acquisition of Northpoint Commercial Finance. Fairstone therefore gets experienced teams, underwriting history and customer relationships that would be expensive and slow to reproduce. It's already a Schedule I bank, so the acquisition does not give Fairstone its first banking licence. It gives the group substantially more depth across consumer, mortgage, digital and commercial credit.
National Bank takes the retail and SME deposit book, so Fairstone does not inherit Laurentian's entire funding base. The strategic gain is less about collecting all of Laurentian's deposits and more about adding specialized commercial lending to a group already built around credit.
Laurentian's sale comes as Canadian challengers pursue very different ways to grow.
Also, OSFI's streamlined approvals process could make entry more predictable for additional banking models. Laurentian therefore does not prove that smaller Canadian banks cannot survive. Its own technology, leadership and restructuring problems were significant. What the deal does show is how costly it can be for a smaller full service bank to recover from those problems while continuing to fund technology, cybersecurity, compliance, risk management, customer acquisition and a competitive range of products.
That is becoming more demanding as specialized competitors attack individual parts of banking without carrying every cost of a traditional bank. Consumer driven banking should also make financial data easier for customers to take elsewhere, raising the value of having a clear reason for them to stay.
Laurentian retail and SME customers will have to migrate products and services to National Bank, and businesses may need to update payment instructions, accounting connections, treasury processes and other systems tied to their bank. Fintechs that simplify onboarding, account connectivity, cash flow visibility, identity verification and payment routing can reduce friction while customers are already reviewing their financial relationships.
SME credit creates another opening because a forced banking transition gives businesses a reason to compare lenders. Faster underwriting helps, but better SME financial data remains essential if digital lenders want to price risk accurately rather than compete only on speed. Consumer driven banking should eventually make future migrations easier by allowing customers to authorize reusable financial data instead of rebuilding every connection manually.
Fig creates another possibility through embedded credit. Its digital lending model already places loans inside partner experiences, while Laurentian brings deeper commercial underwriting. Together, those capabilities could support financing through dealer networks, vertical software, SME platforms and other workflows where businesses encounter credit while completing the job that created the financing need.
National Bank has to migrate Laurentian customers while continuing its Canadian Western Bank integration. Fairstone has to combine businesses serving different borrowers through different systems, channels and credit models. Pricing changes, technology problems, weak communication or difficult conversions could reduce the value either buyer expects to capture.
Credit conditions add another risk because commercial real estate, mortgages, consumer lending and SME credit react differently to rates and economic weakness. Both buyers need underwriting, funding and risk controls to keep pace while integration is underway.
The result will determine whether Laurentian's disappearance mainly reduces competition or redistributes it. Canada is losing one independent full service bank, but the assets going to Fairstone could give another challenger considerably more weight.
A clean National Bank migration could give Laurentian customers more products and distribution while producing better economics from the acquired portfolios. Successful Fairstone integration could create a stronger specialty competitor across consumer credit, mortgages, digital lending and commercial finance.
The result will determine whether Laurentian's disappearance mainly reduces competition or redistributes it. Canada is losing one independent full service bank, but the assets going to Fairstone could give another challenger considerably more weight.
Does dividing Laurentian between National Bank and Fairstone preserve enough competition to compensate for losing one of Canada's long standing independent banks?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 22, 2026 | NCFA Fintech Whisperer | Capital Markets Infrastructure And Funding, Cross Border Payments And FX, Payments Infrastructure And Money Movement, Cybersecurity Fraud And Financial Crime, Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Treasury Liquidity And Cash Management, Sustainable Finance ESG And Financial Inclusion, Digital Banking And BaaS, Wealthtech Investing And Trading, Regulation And Policy, Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026).
BankChain Alliance adds an association led ownership model to existing bank tokenized deposit networks. Its published plan gives community and regional banks a proposed role in governing shared infrastructure, although the technology provider and participating bank commitments remain unresolved.
RQD combines the financing announcement with disclosed operating volume from its proprietary clearing platform. The expansion plan covers digital-asset custody and tokenization alongside equities and options infrastructure. NCFA’s Alpaca platform analysis examines another provider combining brokerage distribution with regulated clearing and custody.
The pilot tested the digital asset and payment legs within the same institutional transaction. NCFA’s tokenized market infrastructure analysis explains why tokenized securities require a compatible settlement asset. CIMB identifies coupon distribution, secondary transfers and redemption as potential future applications. Commercial production availability has not been announced.
The completed transaction extends Canton's institutional custody and collateral infrastructure into a full repo cycle. Repeat volume, additional counterparties and accepted legal, accounting and capital treatment will determine whether the structure advances beyond a single transaction.
The H1 numbers extend the concentration documented in KPMG's 2025 fintech investment review. Canadian founders now face a market where capital favours scale, regulated access, specialized technology and measurable economics. Infrastructure reform could improve the position of companies that can convert lower data and payment friction into customer adoption.
This is a material follow-on to the June financing behind EDGE's prediction market banking infrastructure. ProphetX provides named distribution and active account funding use for EDGE Connect. Higher limits, dedicated insured accounts and continuous FedNow access give the rail an operating profile that routine partnership announcements lack.
Apex could give Gemini a distribution route through brokerage platforms that already serve tens of millions of investors, while Gemini supplies the regulated venue, execution and clearing. That directly expands the commercial case for event contract distribution infrastructure around brokerage connectivity, compliance and access. The parties still need a definitive agreement, so the LOI establishes the proposed structure rather than a completed rollout.
The March dialogue announcement established the bilateral payments file. The completed August meeting adds an agreement to explore UPI distribution and cross-border payment partnerships, while commercial implementation remains unresolved.
This is a material follow-on to Visa and Nium's earlier stablecoin settlement work. BLOOM adds central bank led governance, multicurrency scope and an explicit interoperability mandate. Together with Nium's recent U.S. card issuance expansion, the pilot gives Nium a larger role across both payment distribution and institutional settlement.
Fasset is putting new capital into the banking, liquidity and settlement connections behind its existing transaction volume. Stablecoins already support settlement across parts of Own Network, placing the company inside the infrastructure opportunity around programmable stablecoin payments rather than relying on token issuance alone. Its 100-plus banking corridors give Fasset a base for competing on routing cost, settlement reach and access across markets where payment infrastructure remains fragmented.
RBC is consolidating ownership of the corporate cash cycle, from payment execution and foreign exchange to liquidity and trade finance. Multinational clients gain a coordinated entry point across Canada and the U.S., raising the integration benchmark for fintechs selling treasury software, cross border payments or working capital tools into the same accounts. The structure continues the transaction banking competition already pushing large banks to invest in digital business payment capabilities.
This is a defined core replacement with a named platform, systems integrator, investment budget and migration sequence. Deutsche Bank says the old and new systems will operate in parallel during the transition to support operational resilience and continuity of service. Testing remains planned for year-end, and no migrated products have yet been reported.
The design gives community banks and credit unions a way to offer AI assistance inside authenticated banking while maintaining institution-level data and transaction controls. iTHINK gives the launch a concrete customer and near-term operating timeline.
The transaction verifies that the connection can process an international card at an approved Syrian merchant. The announcement does not disclose how many merchants are enabled, which issuing markets can participate or when international card acceptance will become widely available.
Banks, payment firms and vendors must revise ISO 20022 delivery schedules without treating the delay as cancellation. Release dependencies, vendor contracts and address-data remediation still need clear ownership while the industry waits for a replacement timeline.
The launch extends USD1's institutional settlement use cases from a planned fund-services pilot to native availability on Canton. Named counterparties and recurring atomic settlement volumes are still needed to prove adoption.
PaidIt combines identity resolution, recipient communication and payment delivery for cases that often depend on manual tracing. CBA’s internal use gives the product operating evidence ahead of its planned institutional client rollout.
August 24 gives prospective RTR participants a live legal framework, while operational access still depends on membership, settlement arrangements, technical integration, fraud controls, testing and certification. The RTR rules and access requirements show why eligibility alone does not put a PSP into production. Firms that can clear the remaining technical and operating requirements will be better positioned to build instant payment, pay by bank, treasury and embedded payment products when the system launches.
Owning Altruist gives Vanguard direct infrastructure across RIA custody and advisor workflows, not only fund distribution. Advisors and competing platforms should watch closing conditions, pricing, product access and whether standalone governance preserves Altruist's independence.
Putting regulated multibank data inside an agent interface connects advisory automation to a structured financial source layer. For wealth firms evaluating governed AI agent workflows, the integration supports portfolio analysis and adviser preparation inside an environment they may already use.
Nasdaq says Q6 data will appear as high-risk alerts inside the existing Verafin investigation workflow, covering check fraud, payment-card fraud and account takeover. The proof-of-concept average demonstrates potential lead time, but it does not establish that every alert will arrive before a fraudulent transaction.
Fraud and compliance teams can now buy agentic case operations within a large identity platform rather than assembling a separate agent layer. Regulated customers still need evidence for each automated decision, clear escalation rules and accountable human owners when an agent closes or changes a case.
The task force turns quantum readiness for fintech into a coordinated financial-sector program. Institutions and vendors should inventory cryptography, rank critical systems and document external dependencies before sector guidance becomes a delivery deadline.
This puts post-quantum preparation into an institutional transaction environment where banks and regulators can test the same cryptographic architecture before migration becomes an operating requirement. That is the implementation work behind financial sector quantum readiness: testing wallet controls, signing standards, governance and cross-border interoperability while existing cryptography still works. A shared reference architecture could also reduce the cost and uncertainty of each institution designing its own migration approach.
India is making technology resilience more measurable while standardizing how cyber incidents enter regulatory reporting. Exchanges, clearing corporations and depositories now face a more structured test of whether critical systems remain reliable and recoverable, while common incident data should make weaknesses easier to compare across institutions and over time.
The task force turns federal quantum policy into a financial sector implementation program. Firms now have a coordinated forum focused on cryptographic inventories, vendor dependencies, digital assets and migration execution. It extends the operating case in quantum readiness analysis: the immediate challenge is finding vulnerable cryptography and planning replacements before migration becomes an operational deadline.
The cohort gives regulators a supervised setting to examine how autonomous financial systems are authorized, monitored and escalated. The useful proof will come from controls that preserve human accountability when an agent completes a task or supervises another agent.
Rowan takes delegated AI access to financial accounts from recommendations into execution. Permission limits, action logs, reversibility and responsibility for losses become core product controls when a conversation can trigger a financial action.
Google is packaging domain methods, licensed data access, workflow execution and governance as one financial AI stack. Banks evaluating the preview will need to examine the quality of its research outputs, permission controls, audit records and integration with existing systems. The same control requirement is already visible in AI agent spending infrastructure, where authorization and observability determine whether automated execution can enter production.
Starling has moved agentic AI inside the authenticated business banking workflow and given it authority to execute a defined financial action, rather than limiting it to analysis or customer support. That brings the consent and liability questions around AI initiated payments into a live bank product: who authorizes the action, what limits apply, how the instruction is recorded and what happens when an automated decision is wrong. For business banking, the commercial opportunity is also concrete. The bank can automate tax, invoicing, fraud checks and cash management inside the account instead of leaving those workflows to separate software providers.
The national improvement does not describe every borrower or every region. Ontario homeowners are carrying persistent mortgage stress while severe non-mortgage delinquency has eased slightly across Canada, giving lenders a more uneven credit picture than the headline rate suggests. That divergence affects underwriting, limit management and collections across consumer lending, including products now becoming more visible in Canadian credit files. Geographic exposure and housing obligations are becoming more important when lenders assess where household credit risk is actually accumulating.
For banks, insurers and investors, the liability perimeter has narrowed. Statutory emissions duties remain, while private climate claims can no longer use this route through tort law. Underwriting, due diligence and climate-risk analysis should reflect the distinction.
Frontier AI preparedness is moving from awareness into evidence of execution. Financial firms need tested escalation authority, recovery plans, dependency mapping and governance that still works when incident timelines compress. The supervisory question is increasingly whether organizations can prove those controls operate under pressure, not whether boards have discussed AI risk.
The mandate changes how payment innovation enters supervisory decision making at the central bank. Stablecoin and payment infrastructure proposals will still have to satisfy financial stability requirements, but innovation becomes an explicit secondary consideration rather than an external policy goal. The practical test is how that mandate affects approvals, infrastructure design and competition as new payment models reach systemic scale.
The notice separates sports and entertainment products from the limited event contracts already available through Canadian investment dealers. NCFA’s event contract infrastructure brief tracks the dealer controls, surveillance, settlement and product-classification requirements connected to permitted contracts.
The final rule directs supervisory attention toward material financial risk and compliance with banking law. It also requires the agencies to tailor unsafe-or-unsound findings and MRA treatment to institution-specific risk factors. The rule does not apply to institutions outside OCC or FDIC supervision.
Payment firms and stablecoin providers will gain a formal innovation consideration within Bank of England supervision, but no automatic approval or lighter standard. Product teams will still need to prove that new payment models protect stability, resilience and users.
The proposed consent judgment gives algorithm design liability a concrete control framework built around age assurance, usage restrictions and parental permissions. Fintech teams offering youth accounts, gamified investing or automated recommendations can compare their controls with these requirements while the court reviews the agreement.
Thailand is working on both sides of institutional crypto access at once: the investment product investors can buy and the custody arrangements funds can use behind it. That puts product approval, offshore asset safeguarding and institutional distribution inside the same regulatory design problem rather than treating crypto ETFs as a listing question alone.
Control of the rails, data, distribution and risk is becoming more valuable. Capital is concentrating around firms that can prove scale and economics, while banks and infrastructure providers invest directly in tokenized settlement, real-time funding, AI and fraud controls. The opportunity remains large, but owning a critical part of how money moves is becoming more valuable than adding another product.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 26, 2026 | NCFA Insight | Regulation And Policy, Artificial Intelligence And Data, Risk Compliance And Regtech, Competition And Market Structure
On August 26, 2026, U.S. attorneys general announced a settlement with Meta worth up to US$17.1 billion over allegations that Facebook and Instagram were designed to keep children and teens engaged despite risks to their health and well-being. If the court approves the agreement, Meta also has to limit how long minors can use its apps, restrict overnight access and school-hour notifications, strengthen age checks and give families more control over what young users see.
Meta isn't required to admit it did anything wrong under the settlement. It does expect to record an approximately US$10 billion legal expense in Q3 2026. Governments aren't only extracting billions from Meta. They're putting enforceable limits on features that help determine how often young people open Facebook and Instagram, how long they stay and what keeps them scrolling.
Users under 18 will start with a combined two-hour daily limit across Facebook and Instagram. Parents can approve more time, but teens can't simply turn the limit off themselves. Meta also has to block most access from midnight to 6 a.m. by default and mute most notifications during school hours.
The agreement goes deeper. Teens get regular break prompts and more control over personalized feeds, autoplay and visible like counts. Meta also has to strengthen age assurance, identify children under 13, improve parental controls and maintain protections against harmful content and unwanted adult contact.
Recommendations, notifications, autoplay and frictionless consumption help technology companies turn attention into usage, retention and advertising revenue. That's why the settlement is strategically important. A feature can be commercially valuable for years and still become expensive if evidence eventually shows that the same behaviour driving engagement is contributing to harm.
NCFA's Algorithms Go On Trial As AI Scales Across Society unveiled the lawsuits challenging recommendation systems, infinite scroll, autoplay and notifications as deliberate product choices rather than simply arguing about what users post. Those cases have now produced jury findings, large financial awards and operating restrictions. The debate over addictive design is becoming much harder for boards to leave with legal counsel or the product team.
Meta can afford the settlement though. The company earned enough to absorb an approximately US$10 billion quarterly legal charge without changing the financial guidance it gave investors in July. Markets also reacted positively after the settlement was announced, reflecting relief that Meta avoided the potentially larger uncertainty of continuing the federal trial.
That is precisely why boards should study what happened.
Years of complaints, research, lawsuits and internal evidence accumulated around the same basic concern: were Facebook and Instagram using product features to keep children engaged in ways that could harm them? The exposure grew from a difficult policy issue into jury verdicts, court-ordered controls and now one of the largest state settlements ever reached with a single company.
August coverage of the New Mexico Meta ruling showed how quickly the consequences were already expanding. That case combined a US$375 million jury award with a further US$567 million abatement fund and requirements affecting teen usage, notifications, age assurance, adult contact and AI chatbot interactions involving minors.
If management keeps getting signals that a profitable feature may be harming young users and keeps pushing it anyway, the issue eventually belongs with the board. Investors should know when those warnings reach directors, what they’re told and who can decide that the revenue is no longer worth the risk.
Meta also negotiated an unusually strategic feature into the settlement.
Its own disclosure describes an approximately US$18 billion payment structure over ten years. About US$12.7 billion is allocated to participating states regardless of what competitors do. Roughly US$5.3 billion is released only if both TikTok and YouTube adopt specified teen protections and make matching payments.
That gives Meta billions of reasons to bring its competitors along.
Commercially, the logic makes sense given the amount of competition. If Facebook and Instagram restrict teen usage while TikTok and YouTube remain more permissive, users and coveted 'attention' can migrate to competing apps. Meta bears the cost while rivals gain more opportunity to capture the hours, content consumption and advertising inventory Meta gives up.
The terms get tougher if TikTok and YouTube participate. Meta's daily limit falls from two hours across Facebook and Instagram to one hour per app, while its nighttime block expands from midnight to 6 a.m. to 10 p.m. through 7 a.m.
So Meta isn't simply asking competitors to copy its safety policies. It is trying to prevent child-safety rules from becoming a competitive handicap carried mainly by Facebook and Instagram.
TikTok and YouTube haven't agreed to the framework. Until they do, Meta could still end up operating under restrictions its largest rivals don't share.
Concern about how digital products affect children has been building for years. In 2023, NCFA analyzed Canadian research into children's privacy and consent that called for stronger safeguards to be built into digital products from the start. Children don't assess consent, persuasive design or data collection the way adults do, yet personalization and recommendation systems routinely influence what they watch, read and do next.
Meta's settlement gives those concerns a much larger financial consequence. Governments are no longer relying only on warnings or disclosure requirements. They are specifying age checks, usage limits, notification controls, parental oversight and independent monitoring.
Once those requirements appear in a multibillion-dollar agreement, other platforms know what regulators may ask for next. The settlement doesn't create legal precedent, but it gives attorneys general a detailed set of measures they can use in future negotiations and enforcement.
AI companions and conversational assistants can respond personally, remember context and keep conversations going. Research into youth use of AI reported that 72% of teens had tried AI companions and examined evidence of young people using generative AI for emotional and mental health support.
AI can change the type of exposure a child experiences. A recommendation feed influences what a young person sees next. An AI system can respond directly, adapt to the conversation and encourage the user to keep engaging.
For companies serving children or vulnerable users, it's even more important to know what the system is encouraging, where harmful patterns are appearing and who can change the product when the interaction becomes uncomfortable.
The same principle can be seen in fintech where younger customers use digital wallets, investing apps, financial education tools and AI assistants. Meta's settlement rules don't apply to those products. The relevant lesson is that companies need to understand how their own systems influence behaviour before a regulator or court does it for them.
Meta's US$17.1 billion settlement shows how expensive the problem can become when concerns about engagement, harm and product design build for years without a convincing response.
When a company knows a profitable engagement feature may be harming young users, who should have the authority to decide when growth has gone too far?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 26, 2026 | NCFA Market Activity | Payments Infrastructure And Money Movement, Digital Assets Blockchain And Tokenization, Banking And Credit, Competition And Market Structure
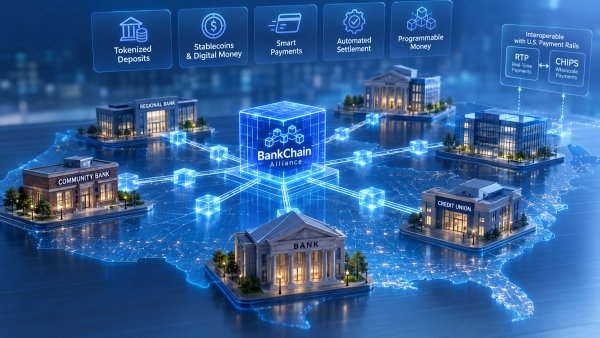
On August 25, 2026, 39 U.S. state bankers associations formed BankChain Alliance to build a shared blockchain network for financial institutions. The planned infrastructure would support smart payment tools, tokenized deposits, stablecoins and automated settlement, with participating banks able to take an ownership role. Together, the associations represent thousands of financial institutions serving millions of consumers, businesses and communities.
BankChain is selecting a technology partner and targeting a 2027 launch. It says the network will interoperate with other networks and that banks across the country will be invited to take ownership. The technology platform, ownership terms for individual banks, operating rules and settlement design haven’t been disclosed, so BankChain remains infrastructure under development rather than a live payment rail.
Building tokenized payment infrastructure involves more than choosing a blockchain. Banks need core system integration, compliance controls, security, operating rules and connections to other financial networks. Those costs are easier for a large institution to absorb than for a community or regional bank.
BankChain's model proposes that banks share more of the work and costs while retaining a say in how the network operates. If enough institutions participate, common infrastructure could reduce the amount each bank needs to build independently and give smaller banks another route into tokenized deposits and programmable payments.
The economics are still unknown. BankChain hasn't disclosed participation costs, ownership terms or implementation requirements. A shared network won't solve much for smaller institutions if joining it still requires expensive integrations, duplicated compliance work or several connections to outside payment systems.
BankChain is entering a market where another bank-led model is already taking shape. In June, The Clearing House launched an on-chain money initiative designed to clear and settle tokenized commercial bank deposits between institutions while connecting blockchain activity with its RTP and CHIPS payment networks.
The Clearing House begins with infrastructure that already clears and settles more than $2 trillion in payments each day. BankChain begins with 39 banking associations and plans to build a common network around institutions that may not have the resources to develop proprietary infrastructure.
Interoperability is paramount given that banks will need tokenized money to move between institutions and connect with established payment infrastructure. BankChain says its network will be interoperable, but hasn't explained how those connections will work.
BMO and TD Bank U.S. are among the institutions supporting The Clearing House initiative. Their participation gives Canadian financial institutions a direct view into one model for connecting tokenized commercial bank money with established U.S. payment rails while BankChain develops a different model based on shared ownership.
Individual bank commitments, network architecture and participation economics will determine whether BankChain becomes usable shared infrastructure.
Can shared ownership make tokenized payment infrastructure economical for smaller banks, or will access to established clearing networks and customer distribution remain the bigger competitive advantage?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 26, 2026 | NCFA Community Announcement | Fintech And Innovation, Artificial Intelligence And Data, Capital Markets And Funding
Elevate is less than a month away! Checkout the latest Elevate 2026 agenda giving founders, investors and technology operators a closer look at the conversations coming to Toronto from September 22–24.
For Canada's fintech community, the mix is worth watching. Elevate's 2026 programming spans fintech, artificial intelligence, capital, commercialization and other technologies competing for investment, customers and talent. NCFA is a Community Partner for this year's festival at Meridian Hall.
Canadian fintech has a direct place in the program.
Eva Wong, Co-Founder and Chief Product Officer of Borrowell, is among the announced speakers, bringing experience from one of Canada's established consumer fintech companies to discussions about product, fintech and the development of Canada's digital finance market.
The latest agenda announcement also highlights Mati Staniszewski, Co-Founder and CEO of ElevenLabs; Adam Collins, Chief Communications Officer at Reddit; and Jessica Chalk, Founder and CEO of myStoria.
Those adjacent technology perspectives are relevant to financial innovators. AI is entering customer service, fraud detection, compliance, product development and internal operations, while fintech companies still have to turn technical capability into products customers trust and businesses can scale.
For founders, the useful question isn't simply which technology attracts the most attention. It's where new capabilities can solve a real financial problem, reach customers and support a viable company.
Elevate is also expanding direct access between founders and investors.
Its Meeting Exchange program is doubling capacity for 2026, with more than 750 curated one-to-one meetings for investment-ready startups.
That adds a practical capital component to a festival expected to bring together approximately 10,000 technology professionals, entrepreneurs, founders, executives and investors.
For early and growth-stage companies, concentrated access to investors, potential customers, partners and other founders can make the trip more useful than a schedule built around stage content alone.
NCFA community members can receive 20% off General Pass tickets for Elevate Festival 2026.
Use promo code: NCFAELEVATE20
📅 September 22–24, 2026
📍 Meridian Hall, Toronto
More speakers and sessions are being added ahead of September.
For fintech founders, investors and operators, the value is in the overlap. Finance is colliding with AI, new infrastructure, changing customer expectations and tighter competition for capital. Elevate offers three days to test ideas with people building, funding and buying technology across those markets.
#ElevateFest2026
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016