




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Sep 25, 2026

Choosing a payment gateway is one of the first infrastructure decisions a Canadian e-commerce founder makes - and one of the hardest to reverse.
Switching processors later means re-tokenizing cards, reconfiguring checkout flows, reconciling historical data, and often pausing growth while engineering catches up. Get it wrong early, and you pay twice: in fees and in the operational drag of failed payments, chargebacks, and support tickets your team was not staffed to handle.
Before you commit, run a full payment gateways comparison - Stripe, PayPal, and Adyen each handle refunds, chargebacks, and authentication flows differently, which directly affects your post-checkout support burden.
This guide is for founders, operators, and fintech-curious investors evaluating Stripe, PayPal, and Adyen for Canadian online businesses in 2026. It covers what each platform does well, where they fall short, and how payment choices ripple into customer support, compliance, and unit economics.
Canada's e-commerce market continues to mature, but founders face a specific set of constraints:
Payment processors are no longer "backend plumbing." They are front-line infrastructure for conversion, fraud prevention, and regulatory posture - especially as AI-driven commerce and embedded finance reshape checkout experiences across the ecosystem NCFA Canada covers daily.
Before comparing logos, define what your business actually needs:
| Criterion | Questions to ask |
| Checkout conversion | Does it support one-click, wallets, local methods, and mobile-optimized flows? |
| CAD settlement | How fast do funds arrive in your Canadian bank account? |
| Multi-currency | Can you charge in USD/EUR without a separate entity? |
| Fraud & 3DS | How are SCA, 3D Secure, and high-risk transactions handled? |
| Disputes & chargebacks | What tooling exists for evidence submission and win rates? |
| Platform fit | Native Shopify, custom stack, marketplace, or subscription billing? |
| Support load | Do payment errors generate customer tickets you must resolve manually? |
The cheapest per-transaction rate is meaningless if failed authorizations and confused shoppers create a support queue that scales linearly with revenue.
| Stripe | PayPal | Adyen | |
| Best for | Developer-led DTC, SaaS, subscriptions | Consumer trust, quick launch, marketplaces | Enterprise, omnichannel, high volume |
| Canadian SMB fit | Excellent (Shopify, APIs) | Strong (brand recognition) | Moderate (overkill for early stage) |
| Setup complexity | Low–medium | Low | Medium–high |
| Typical pricing | ~2.9% + $0.30 CAD (varies) | ~2.9% + fixed fee (varies) | Interchange++ (custom quotes) |
| Wallet / PayPal button | Via Stripe | Native | Supported |
| Subscription billing | Strong (Billing) | Basic | Strong |
| In-person / POS | Terminal available | Zettle | Unified commerce strength |
| Ideal stage | Seed to scale | Launch to growth | Scale to enterprise |
Strengths
Stripe has become the de facto choice for Canadian startups building on Shopify, custom React storefronts, or subscription models. Its API-first design, documentation quality, and ecosystem (Billing, Radar fraud tools, Terminal) make it attractive for technical teams.
For Shopify merchants, Stripe powers Shopify Payments in many regions - reducing friction at onboarding. Founders running headless commerce or multi-product SaaS often prefer Stripe's granular webhooks and reconciliation exports.
Weaknesses
When to choose Stripe: You want one stack for online + subscriptions + future POS, and your team can manage webhooks, dispute evidence, and payout reconciliation.
Strengths
PayPal's brand still converts skeptics. For Canadian SMBs selling to US and international buyers, the PayPal button can lift checkout completion - especially among customers who do not want to re-enter card details on a new storefront.
Setup is fast. PayPal Commerce Platform supports marketplaces and seller onboarding. For founders validating product-market fit, PayPal remains a credible "week one" option.
Weaknesses
When to choose PayPal: You need recognizable trust signals immediately, sell cross-border to wallet-preferring buyers, or run a marketplace model where seller payouts matter.
Strengths
Adyen is built for operators who sell online, in-store, and across markets from one platform. Interchange-plus pricing can win at volume. Unified reporting across channels appeals to retail brands expanding from DTC into physical retail.
For Canadian companies with global ambitions - particularly those already processing millions monthly - Adyen's single-stack narrative reduces vendor fragmentation.
Weaknesses
When to choose Adyen: You are processing significant volume across channels, need global acquiring in one contract, and have finance ops to manage interchange-based pricing.
Currency conversion
Charging in CAD but paying suppliers in USD? Conversion spreads matter. PayPal and Stripe both apply FX margins on top of base rates. At scale, a 0.5% FX difference is material.
Failed payments and involuntary churn
Subscription businesses lose 20–40% of churn to failed card charges (expired cards, insufficient funds, bank soft declines). Stripe Billing and Adyen offer retry logic; PayPal's subscription tooling is less sophisticated. Each failed renewal can become a support ticket if dunning emails are weak.
3D Secure and authentication friction
Strong Customer Authentication (SCA) and 3DS reduce fraud but increase checkout abandonment when implemented poorly. European shoppers and Canadian issuers increasingly challenge transactions. Misconfigured 3DS flows generate "payment failed" emails that flood support - even when the customer did nothing wrong.
Chargebacks and dispute fees
A chargeback costs more than the transaction fee: you lose the sale, pay a dispute fee, and spend ops time assembling evidence. Gateway dispute portals vary widely in usability. Founders who ignore dispute win rates leak margin quietly.
Refund processing timelines
Refund speed affects customer sentiment. PayPal and Stripe timelines differ by funding source. Slow refunds drive "where is my money?" tickets - a support cost rarely modeled in gateway spreadsheets.
Founders often evaluate gateways in finance silos. Operations teams live with the consequences.
Common payment-driven support scenarios:
| Issue | Customer behavior | Ops impact |
| 3DS failure at checkout | Abandons cart or retries multiple times | Lost revenue + confused emails |
| Duplicate charge appearance | Contacts support immediately | Refund or investigation |
| Address / AVS mismatch | Order held, customer anxious | Manual review queue |
| Subscription renewal fail | "Why was I cancelled?" | Retention risk |
| Cross-border decline | Assumes fraud, posts on social | Brand damage |
Automating post-purchase support (order status, refund policy, payment retry guidance) reduces ticket volume - but the root cause is often gateway configuration, not customer irrationality.
Smart founders pair payment stack decisions with support automation strategy. Fix checkout friction first; automate repetitive WISMO and refund questions second.
Choose Stripe if:
Choose PayPal if:
Choose Adyen if:
Run both Stripe + PayPal if:
Many Canadian SMBs start with Shopify Payments (Stripe) and add PayPal Express for international conversion - then revisit at $1M+ ARR when fee optimization and unified reporting justify complexity.
Canadian founders should stay aware of evolving payment oversight:
NCFA's ecosystem regularly covers payments regulation, embedded finance, and fintech policy - worth monitoring as your volume grows and compliance surface area expands.
Where to Invest After You Choose a Gateway
Payment selection is step one. These investments compound ROI:
For most Canadian e-commerce founders in 2026, Stripe remains the strongest default for growth-stage DTC and SaaS - especially on Shopify. PayPal earns its place when wallet trust and cross-border conversion justify the fees. Adyen makes sense when unified commerce and global volume are already realities, not aspirations.
The right gateway is not the one with the lowest advertised rate. It is the one that maximizes successful transactions, minimizes dispute drag, and keeps your support team focused on problems that actually require judgment.
Model the full cost - FX, chargebacks, failed renewals, and tickets - before you scale ad spend. Your payment stack is a fintech decision with P&L consequences long after checkout.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
September 25, 2026

Entrepreneurs are trained to manage uncertainty. They build forecasts with incomplete data, make decisions under pressure and keep teams moving through shifting market conditions.
Divorce creates a different kind of uncertainty.
Legal questions become entangled with parenting, housing, cash flow, business ownership and emotionally charged communication. Meanwhile, the company does not pause. Employees still need decisions, investors expect updates, customers require support and the next financing milestone remains on the calendar.
For founders, executives and technology professionals, divorce is not only a private family matter. It can become a leadership, financial and operational risk event. Managing it well requires more than working longer hours or applying the same intensity used to solve a product problem.
It requires the right advisory team, disciplined communication and a system for making consequential decisions without allowing personal conflict to consume the business.
A salaried employee may have income, savings and retirement accounts to consider. A founder’s financial life can include far more moving parts:
A company may appear valuable on a pitch deck without producing much personal liquidity. Conversely, an early-stage equity position that seems speculative today could become valuable after a financing, acquisition or public offering.
How these assets are treated depends on the facts and the applicable provincial or territorial law. A founder should not assume that shares registered in one person’s name, assets held digitally or property accumulated through a corporation are automatically excluded from the divorce process.
Early advice from qualified legal, tax and valuation professionals is essential.
Divorce involves several kinds of problems, and no single professional is meant to solve all of them.
A family lawyer provides legal advice and represents the client’s interests. An accountant or business valuator may analyze corporate income, ownership and value. A tax professional can identify the consequences of proposed transfers or settlement options. A therapist supports mental health and deeper emotional healing.
A divorce coach fills a different role. Coaching can help a client organize priorities, prepare for professional meetings, improve difficult communication and remain focused on practical next steps.
Busy professionals exploring this type of support can learn more from Heidi Dinning, a certified divorce coach and family communications expert who works with clients on divorce strategy, high-conflict communication, co-parenting and preparation for mediation or legal proceedings.
A coach does not replace a lawyer, accountant, valuator or therapist. The value comes from helping the client use each professional more effectively.
Founders rarely begin due diligence by searching through random email threads five minutes before a meeting. The same discipline should apply to divorce preparation.
Create a secure inventory of relevant personal and business records. Depending on professional advice, that may include:
This is an organizational step, not an invitation to copy confidential corporate information without authorization. Founders should ask legal counsel how to preserve relevant records while respecting company obligations, employee privacy and securities requirements.
Information should be collected transparently and lawfully. Concealing, deleting or transferring assets can create serious legal and credibility problems.
Divorce generates messages that feel urgent because they are emotionally uncomfortable. Not every message requires an immediate reply.
Entrepreneurs who are accustomed to rapid decision-making may respond too quickly, especially when a text or email feels unfair. That reaction can intensify conflict and create a written record that is difficult to explain later.
Before responding, ask:
A divorce coach can help a client review communication patterns, identify triggers and draft a clear response without turning every disagreement into a legal escalation.
This creates a valuable pause between reaction and action.
Founders make high-stakes decisions every day, but divorce can reduce the mental capacity available for those decisions. Sleep disruption, fear and repeated conflict make it harder to assess trade-offs objectively.
A useful approach is to divide decisions into three categories.
These can be adjusted with limited consequences, such as changing a weekly scheduling system or choosing where routine information will be shared.
These involve meaningful financial or parenting effects and should be considered carefully with the appropriate adviser.
Selling shares, transferring property, accepting a settlement or making public statements about the separation may create lasting consequences. These decisions should not be made simply to end an uncomfortable conversation.
The speed valued in a startup is not always an advantage in a divorce. Good leadership sometimes means slowing the process down long enough to obtain reliable information.
Personal disruption becomes a company problem when too many operational decisions depend on one person.
A founder navigating divorce should review what would happen if they were temporarily unavailable. This does not require sharing private details with the entire team. It requires ensuring that the company is not dependent on the founder answering every question in real time.
Consider:
If the divorce may affect ownership, governance, financing or disclosure obligations, the appropriate corporate and family-law advisers should be involved. The board may also need information when the issue creates a material risk, but disclosure should be deliberate and limited to what is professionally required.
Technology professionals often have a complicated digital footprint. Personal and corporate data may be spread across cloud storage, password managers, shared subscriptions, smart-home systems, cryptocurrency wallets and devices used for both work and family communication.
During separation, review digital access carefully without locking a spouse out of jointly owned property or interfering with information that must be preserved.
Useful steps may include:
Company IT staff should not be drawn into a personal dispute. If corporate security is potentially affected, involve the appropriate security or legal leader through a controlled process.
Lawyers, accountants and valuators are valuable because of their specialized expertise. Meetings are more productive when the client arrives with organized documents, clear questions and a defined objective.
Before each professional meeting, prepare a short brief:
A divorce coach can help build this agenda and organize the emotional noise surrounding the issue. This allows legal and financial professionals to concentrate on the work only they are qualified to perform.
Entrepreneurs are used to developing solutions quickly. Children experiencing a family separation may not need a solution in the moment. They may need time, reassurance and permission to have complicated feelings.
A parenting plan is not simply another operating agreement. It affects a child’s routines, relationships and sense of security.
Avoid treating time with children as a metric to be maximized or a negotiation to be won. Where it is safe and appropriate, keep children out of adult conflict, avoid using them as messengers and do not ask them to report on the other household.
Co-parenting coaching can help parents prepare for difficult conversations, establish workable communication practices and keep decisions centred on their children’s needs.
Legal complexity is not the only factor that makes divorce expensive. Repeated conflict can generate unnecessary correspondence, emergency meetings and negotiations over issues that might otherwise have remained manageable.
Watch for patterns such as:
A structured communication process can reduce confusion. Keep messages brief, address one subject at a time and separate factual requests from emotional commentary. When a response is not urgent, draft it and review it later.
The first days of separation can feel chaotic. A simple sequence can restore a degree of control:
A successful divorce strategy is not about eliminating emotion. That is unrealistic. It is about preventing emotion from driving every legal, financial and parenting decision.
For a busy founder or technology leader, the right support structure protects more than personal well-being. It preserves attention, improves the use of professional advice and reduces the likelihood that a private crisis will become an unmanaged business risk.
Entrepreneurs already understand the value of expert guidance in areas outside their specialization. Divorce should be approached with the same discipline. Build the team, organize the information, protect the company and create enough space to make decisions based on facts rather than fear.
This article provides general information only and does not constitute legal, financial, tax, investment or mental-health advice. Divorce and property laws vary by jurisdiction. Obtain advice from qualified professionals who understand your circumstances.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 24, 2026 | NCFA Market Activity | Regulation And Policy, Capital Markets And Market Infrastructure, Wealthtech Investing And Trading, Risk Compliance And Regtech

On September 24, 2026, FAIR Canada challenged Wealthsimple's prediction market proposal for a wider Canadian prediction market. Wealthsimple wants regulators to change how event contracts qualify for retail trading. FAIR wants the current limits to remain unless wider access can be shown to benefit investors and serve the public interest.
Wealthsimple published its proposal on August 4. On August 27, Canadian securities regulators kept sports and entertainment contracts outside securities and derivatives regulation. FAIR has now challenged the remaining case for adding more event contracts to the investment dealer channel.
Wealthsimple's August 4 white paper goes well beyond its Predict product. CIRO currently limits authorized dealers to contracts based on economic forecasts, environmental forecasts and financial indicators. Wealthsimple argues that these categories are subjective because similar contracts can fit more than one label or receive different treatment.
Its alternative focuses on who determines the result. Wealthsimple proposes approved settlement sources that include government agencies, established data providers, recognized institutions and selected news organizations. A Canadian unemployment contract could settle using Statistics Canada data, while a Bitcoin price contract could use an established financial benchmark.
The proposal could reach categories that Canadian investment dealers can't offer today. Wealthsimple includes accredited electoral authorities among potential settlement sources even though political event contracts are prohibited. It would still exclude contracts involving death, personal harm, terrorism, the initiation of armed conflict and events where one identifiable person can determine the outcome.
Canada already opened a narrow regulated route earlier in 2026 when Wealthsimple entered Canada's regulated prediction market. Regulators drew another boundary on August 27 when the CSA and CIRO kept sports prediction markets outside securities rules. The CSA said sports and entertainment contracts shouldn't be regulated under securities and derivatives legislation, while CIRO said it would not approve dealer applications to offer them.
The Canadian market remains tightly controlled. CIRO has authorized two investment dealers to facilitate event contract trading, with offerings limited to economic forecasts, environmental forecasts and financial indicators. Contracts must have at least 30 days to maturity. Leverage is prohibited, along with elections, referendums, political nominations and other political events.
A dealer that wants to offer contracts outside those categories must file another material business change with CIRO. Other event contract categories remain under regulatory review.
FAIR doesn't dispute that an event contract can meet the legal definition of a derivative. It disputes what should follow from that classification. Its September response asks regulators to consider investor benefit, capital market purpose, market integrity and the public interest before permitting additional categories for retail trading.
That conflicts directly with Wealthsimple's settlement source approach. A reliable source can determine the result of a contract, but FAIR argues that it doesn't establish whether the contract belongs in the retail investment market. Reliable settlement and retail eligibility are separate questions in FAIR's analysis.
The two organizations also differ on the economic case. Wealthsimple says prediction markets can aggregate information, produce useful prices and help people hedge risk. FAIR says there isn't enough evidence that Canadian retail investors use the contracts already permitted for those purposes.
Wealthsimple also wants Canada to revisit its binary options rules. Multilateral Instrument 91-102 was introduced in 2017 after regulators faced widespread fraud involving offshore binary option platforms. Wealthsimple argues that regulated event contracts operate differently because trades pass through regulated dealers, futures intermediaries, exchanges and clearing organizations.
It also questions what the 30 day minimum achieves. A contract can satisfy the rule when it is listed and still trade shortly before expiry. Wealthsimple would rely more on dealer controls including recommended loss levels, deposit limits, cooling periods, trading breaks, self exclusion, education and market surveillance.
The rule still applies directly to prediction markets. Ontario regulators relied on MI 91-102 in a 2025 Polymarket settlement, finding that event contracts offered to Ontario residents included prohibited binary options with less than 30 days to maturity. FAIR argues that shorter contracts can also produce faster turnover and repeated exposure to gains and losses, so changing the rule requires evidence about the investor effects as well as differences in market structure.
Wealthsimple says more than one million Canadians have already used prediction markets, mainly through offshore platforms. The figure is based on survey data rather than trading records. An Angus Reid Institute survey of 1,803 Canadian adults found that 4% had used a prediction market.
The same survey found limited interest among people who hadn't used one, while opposition to allowing prediction markets was higher than support. The results confirm that Canadians are participating, but they don't show how customers behave inside a regulated investment account. They also don't establish whether people use these contracts for hedging, forecasting or short term speculation.
The permitted Canadian market can now produce better evidence. Participation, repeat trading, average exposure, realized gains and losses, liquidity and spreads can all be measured. Regulators can also examine attempted manipulation and surveillance events, an issue NCFA has explored through prediction market insider trading and surveillance.
Another useful measure is whether Canadians leave offshore platforms once a regulated option is available here. Wealthsimple argues that some will and dealer data can show whether that happens and whether their trading behaviour changes.
Canada is really deciding three things. The August 27 decision on sports and entertainment shows that a contract can meet one legal test without automatically qualifying for retail trading through an investment dealer.
Wealthsimple wants less focus on the subject of the contract and more on how it works, how the result is settled and what controls the dealer has in place. FAIR wants stronger evidence that adding more contracts would benefit investors and support capital market activity. Canadian trading data can help answer that.
The contracts already allowed in Canada can show who is trading, how often, how much they gain or lose and whether enough buyers and sellers show up. Regulators can also see whether a regulated Canadian option pulls users away from offshore platforms. That would give them Canadian evidence to work with instead of relying mainly on legal arguments and overseas trading volumes.
Canada already permits a narrow range of regulated prediction markets. Which additional event contracts should qualify, and what does actual Canadian trading behaviour say about expanding access?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 23, 2026 | NCFA Market Activity | Payments Infrastructure And Money Movement, Digital Assets Blockchain And Tokenization, Banking And Credit, Competition And Market Structure

On September 22, 2026, BMO, CIBC, National Bank of Canada, RBC, Scotiabank and TD announced that they are jointly exploring CAD tokenized deposits. The first phase aims to transfer tokenized deposits across Canadian financial institutions. Longer term, the banks want to connect the project with other emerging digital asset infrastructure.
It's a partnership at an early stage, but banks have been here before. The banks haven't disclosed a project name, investment amount, technology provider, structure or governance model. They also haven't explained whether each bank would issue its own tokenized liability or exactly what happens when a deposit transfers from one institution to another.
Canada's largest banks compete hard for deposits, payments and corporate clients. They also have a long history of building together when six versions of the same underlying system would cost more and work less effectively.
March 5, 2026 The Bank of Canada completed Project Samara with Export Development Canada, RBC and TD. EDC issued a C$100 million tokenized bond to a closed investor group and settled the payments in wholesale central bank money. The experiment achieved real time settlement and improved data integrity, but system complexity, liquidity costs and new governance requirements offset some of the efficiency gains.
May 27, 2026 The Bank of Canada joined BIS Project Agorá. Its prototype combines tokenized commercial bank deposits with wholesale central bank money on a programmable platform for wholesale cross border payments.
September 10, 2026 OSFI clarified how Canadian bank regulation treats tokenized deposits. OSFI said the technology used to represent a product doesn't determine its legal nature and that tokenized deposits are not legally distinct from traditional deposits simply because they are represented digitally.
September 22, 2026 All six major Canadian banks announced that they were exploring a Canadian dollar tokenized deposit solution together. That brought the Canadian story from capital markets testing and international experimentation into a domestic partnership between the banks that hold much of the country's commercial deposits.
These projects weren't announced as one coordinated program. Seen together, they show the regulatory, settlement and commercial pieces of tokenized Canadian dollar finance being worked on at roughly the same time.
OSFI's position gives the partnership a clearer legal starting point. Tokenization doesn't automatically turn a bank deposit into a different financial product. Existing legal, technology, cyber and third party risk requirements still apply, and banks are expected to engage their supervisors before launching novel products.
Deposit insurance will depend on the final design, however the Canada Deposit Insurance Corporation says innovative products, including tokenized deposits, may qualify for protection when they meet the legal requirements for an eligible deposit. CDIC assesses them case by case, so the Big Six project can't yet be described as insured.
It is also different from Canada's developing stablecoin market. Canada's federal stablecoin framework applies its new issuer regime to non-financial institutions. Banks and credit unions already operate under prudential regulation.
A qualifying tokenized deposit can preserve a customer's deposit claim on a bank while adding new ways to transfer or settle value digitally. Canada's stablecoin framework, by comparison, requires non-financial issuers to back fiat stablecoins with reserves and provide redemption at par.
It becomes important if tokenized securities, stablecoins and bank deposits eventually need to exchange value on the same financial networks. Canada's banks aren't simply exploring another digital asset. They are exploring what regulated commercial bank money could look like inside those networks.
The idea of competitors cooperating behind the customer layer isn't new in Canadian banking. Payments, identity, cheque processing and compliance have all produced examples where financial institutions shared systems or standards, then kept competing on the services built around them.
| Collaboration | What The Banks Shared | What Happened |
| Interac | Canada's major financial institutions came together in 1984 to create a national shared cash dispensing network. | That network expanded into debit and electronic transfers. In 2025, Interac processed 7 billion debit transactions and 1.6 billion e-Transfers. |
| SecureKey | BMO, CIBC, RBC, Scotiabank, TD and Desjardins backed common digital identity infrastructure. | The institutions invested C$27 million in SecureKey in 2016. Its Canadian verification capabilities later became part of Interac. Interac Verified handled 544 million transactions in 2025. |
| Symcor | BMO, RBC and TD combined cheque processing that had previously been handled separately. | The collaboration consolidated 21 processing sites to seven and put the banks on one technology platform. |
| CanDeal Third Party Risk | All six major banks are working with CanDeal on common third party due diligence and compliance processes. | The banks and CanDeal announced their investment in February 2026. The amount wasn't disclosed and the project is still publicly described as a pilot, so there isn't a verified outcome yet. |
Interac began in 1984 because customers needed access to cash beyond their own bank's machines. Four decades later, the same network supports everyday payments and money transfers at national scale. The banks didn't need six incompatible cash networks to compete for customers.
The identity example required actual shared capital. BMO, CIBC, RBC, Scotiabank, TD and Desjardins put C$27 million into SecureKey in 2016 to commercialize a common digital identity network. Interac later acquired the Canadian rights to SecureKey's digital ID services, including Verified.Me. Interac Vrified processed 544 million transactions in 2025.
Symcor example highlights the cost argument more directly. When BMO, RBC and TD combined cheque processing in 1996, the operation cut 21 processing sites to seven while moving the banks onto one technology platform. Customers still chose among competing banks. The repetitive work behind cheque processing no longer had to be reproduced three times.
The Big Six returned to that model this year. In February, they invested with CanDeal in a common third party risk solution intended to reduce repeated supplier checks and standardize due diligence. CanDeal hasn't disclosed how much the banks invested or published enough results to judge the pilot yet.
Banks can share the plumbing where duplication adds cost, then compete on products, pricing, service and customers.
Tokenized deposits make the shared infrastructure question more practical. One bank can digitize its own deposits, but interbank use requires agreement on how the claim is preserved, how compliance controls apply and how settlement is completed. That is where common rules become necessary.
Interac's history also shows how access can impact a shared network. The Competition Bureau previously challenged Interac's restrictions that limited competitors' access to the network. The resulting agreement widened participation and required access to the technical information needed to connect. Later changes gave Interac an independent board and a for profit structure while keeping access open and non-discriminatory.
That history makes the new partnership's promise to include other deposit taking institutions worth watching. Access rules haven't been published yet. The eventual treatment of smaller banks, credit unions and other eligible institutions could determine whether the project becomes widely useful Canadian infrastructure or mainly a shared capability for its six founding banks.
That question is more relevant now than it would have been a few years ago. Payments Canada has widened membership, regulated payment service providers have entered federal supervision, consumer driven banking is being implemented and Canada has enacted a stablecoin framework. A new tokenized deposit system would be entering a financial market where more firms are gaining roles in payments, data and digital money.
Banks and payment networks elsewhere are already testing different ways to keep commercial bank money useful as financial activity becomes more programmable.
| Initiative | Current Scale Or Stage | What It Adds To The Comparison |
| Kinexys by J.P. Morgan | More than US$4 trillion processed since inception and about US$7 billion daily. | A single global bank has already taken blockchain based payments, settlement and tokenization into production at substantial volume. |
| Citi Token Services | Live 24 hours a day across participating Citi markets. | Citi uses tokenized bank money for near real time cross border payments and liquidity transfers inside its own network. |
| Great British Tokenised Deposits | Seven banks and building societies participating in a live industry pilot. | The UK is testing shared tokenized deposits against marketplace payments, remortgaging and digital asset settlement rather than leaving the use cases theoretical. |
| The Clearing House | Owned by 25 large U.S. financial institutions and developing interbank clearing and settlement for tokenized commercial bank money. | The model connects tokenized deposits with existing RTP and CHIPS payment infrastructure and says banks of all sizes will be able to participate. |
| BankChain Alliance | Thirty nine U.S. state banking associations are developing bank owned blockchain infrastructure targeted for 2027. | The proposed ownership model is designed to give community and regional banks a role in common digital money infrastructure. |
The UK project is interesting because it's testing specific jobs that tokenized deposits could do. Those include marketplace payments, remortgaging and digital asset settlement. UK Finance and EY identified more than 40 potential business benefits and estimated that tokenized deposits could generate more than £3 billion in economic benefit.
The U.S. examples take different approaches. J.P. Morgan and Citi have built their own bank networks for institutional clients. The Clearing House is taking a shared industry approach so tokenized commercial bank money can clear between institutions and connect with payment systems that already exist.
Canada hasn't yet said which structure it plans to use. The Big Six partnership could become a common platform, a set of interoperable bank issued tokens or something else. Canada's earlier bank partnerships show that sharing core infrastructure can reduce duplication. The international examples also show that the real test will be whether the system supports useful transactions at scale.
The Big Six partnership will be judged by whether it can support useful transactions at lower cost and with less duplication than existing systems.
Canada's largest banks have successfully shared payment, identity, processing and risk infrastructure before. Can they do the same with tokenized deposits while giving enough institutions access for the partnership to become useful national infrastructure?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 22, 2026 | NCFA Story Intelligence | SME Finance And Business Banking, Open Banking And Open Finance, Capital Formation, Competition And Market Structure

On September 17, 2026, the UK regulator went looking for evidence that its own rules were blocking small business finance.
It didn't find much.
Instead, the FCA SME finance review found problems scattered across the financing process. Some small firms don't know which product fits. Applications can be repetitive. Valuable businesses can own little conventional collateral. A lender can say no for reasons that have more to do with its own risk appetite than the health of the company. And after a decline, the entrepreneur may be left wondering where to go next.
Canada looks different at first glance.
Small business debt approval reached 97% in 2025.
That is a strong number. But approval is only one part of the financing process.
Why is the Competition Bureau reviewing SME lending, why did 76% of borrowers still have to pledge collateral, and why are specialist lenders building financing products around needs that conventional credit doesn't always serve?
The problem may not be a simple shortage of money.
It may be what happens between a viable SME and the right capital at the right stage of its life.
The UK expected to find regulatory barriers. The FCA concluded that its regulation was not a major obstacle to SME finance. What surfaced instead were problems with finance readiness, market navigation, risk assessment, repeated customer checks, product availability, alternative lending and personal guarantees. SMEs account for 60% of UK private sector employment, yet only 21% of the value of UK business loans goes to them.
Canada starts from a much stronger approval number, but fewer firms enter the debt market. ISED's 2025 Credit Conditions Survey found that 20% of small businesses requested debt and 97% received full or partial approval. Ninety seven per cent of requested dollars were authorized. The average amount approved was C$140,148 and the average interest rate fell to 5.8%. In the UK, around 50% of smaller businesses used external finance in Q3 2025, while challenger and specialist banks supplied 60% of gross SME bank lending. The measures aren't directly comparable because the UK figure includes credit cards, overdrafts, leasing and other products. Still, the UK data show SMEs using a wider range of external finance, alongside a market where challenger and specialist banks now provide 60% of gross SME bank lending. That makes Canada's 20% debt request rate worth looking at more closely.
The loan gets smaller. Much of the work doesn't. A lender still has to identify the customer, understand the business, assess risk, collect financial information, document the facility and service the account. The FCA found that high underwriting and customer support costs can make smaller or more complicated loans commercially unattractive. Bank of England research cited in the review found that operating and impairment costs mattered more than capital requirements in explaining weaker returns on SME lending.
Smaller firms can end up trying to fit products built for someone else. A bank can justify the time needed to structure a large commercial facility. The economics get harder when the business needs C$50,000 or C$100,000 and wants an answer quickly. David Gens, Founder and CEO of Merchant Growth, described that mismatch in a recent NCFA Fintech Fridays conversation. Merchant Growth has since funded more than 15,000 Canadian small businesses and deployed over C$1.5 billion, building around smaller financing needs and current business performance.
Collateral still carries enormous weight. In 2025, 76% of Canadian small business borrowers had to pledge collateral. The requirement reached 93% for long term debt. Buildings, machinery, inventory and receivables give lenders assets they can value and potentially recover if the borrower fails.
A fintech can become more valuable without owning much more that a lender can seize. Revenue rises. Customers renew. Software improves. Proprietary technology becomes harder to replicate. Yet BDC notes that patents and intellectual property can be harder for banks to value, making financing more difficult for businesses such as SaaS, ecommerce, cleantech and media companies.1
Canada has already decided to share some of that lending risk. The Canada Small Business Financing Program supported 6,409 loans worth almost C$1.9 billion in 2024 to 2025. Startups and businesses operating for less than one year received C$1.4 billion, or 74.1% of the total.
Follow the money and the old lending logic is still visible. Leasehold improvements accounted for C$1.2 billion and equipment another C$350.9 million. Working capital and intangible asset loans together represented only C$51.5 million, or 2.7% of program lending.
Revenue gives the lender something else to watch. BDC now says technology financing can take recurring revenue such as ARR and MRR into account. Predictable subscription revenue can help demonstrate repayment capacity even when profitability is still developing.2
The public guarantee can follow the loan through someone else's front door. BDC's Business Accelerator Loan Program supports working capital facilities between C$25,000 and C$500,000. The participating financial institution originates and manages the loan while BDC guarantees it.
The UK is trying to make business information do more work. The FCA sees open finance as a way to give lenders more complete and timely information, reduce duplicated applications and improve decisions. SME lending is one of the UK's first priority open finance use cases. The FCA plans to publish options for its first open finance scheme in early 2027.
Canada sees the same lending opportunity in consumer driven banking. Budget 2025 says the framework can reduce administrative work for SMEs, connect banking information with accounting, tax and payroll tools, support faster loan decisions and provide access to new forms of financing.3
Then comes the moment a lender says no. The FCA heard that some SME borrowers receive limited explanations for a decline. That can be particularly frustrating when the problem is lender specific. A bank may simply have little appetite for the sector, ticket size or type of risk. The business itself may still fit another provider perfectly well.
Canada can still leave the borrower back at the original door. Under BDC's Business Accelerator Loan Program, the participating institution manages the credit decision. If the borrower is declined, BDC says it has no visibility into the reason and directs the entrepreneur back to the financial institution for more information.
Canada is now looking closely at competition in SME lending. The Competition Bureau is reviewing SME loan competition in Canada, including lender entry, expansion and switching. The Bureau says Canada's market is dominated by large banks, smaller lenders appear to face barriers, comparing offers can be difficult and the borrowing cost gap between SMEs and large firms is wider than in many OECD countries.8
Meanwhile, Canada is adding capital further up the financing ladder. Budget 2025 committed C$1 billion to a new Venture and Growth Capital Catalyst Initiative and another C$750 million toward businesses facing early growth funding gaps.4
Manufacturers are already showing why timing matters. Only 87% of manufacturing applicants were approved for debt in ISED's 2025 survey, compared with 97% across small businesses overall. Now tariff pressure is hitting the same sector. Statistics Canada reported that 49.7% of manufacturers expected U.S. tariffs to hurt their business over the next 12 months, compared with 32.2% of Canadian businesses overall.5
Ottawa is responding with liquidity because the pressure arrives in cash flow first. The latest federal package adds C$1.5 billion to the Regional Tariff Response Initiative, a new C$500 million BDC liquidity stream for immediate cash flow pressure and another C$2 billion through the Canada Strong Diversification Fund.6
The UK is fixing friction inside the financing process. Its response includes better finance navigation, reform of referral after a declined application, better commercial credit data, digital verification, Consumer Credit Act reform and open finance focused directly on SME lending.
Canada is building capacity from several directions. Public guarantees support smaller loans. BDC lends directly and through partner institutions. Consumer driven banking can improve underwriting. The Competition Bureau is looking at lender competition. Ottawa is adding venture and growth capital. Tariff programs are supplying emergency liquidity.
Canada's SME finance numbers don't describe a credit desert. A 97% approval rate makes that clear.
A small business can have customers, revenue and a good reason to borrow and still be the wrong size for a lender's economics. A fintech can build valuable intellectual property faster than it builds conventional collateral. A manufacturer can suddenly need working capital because tariffs change its cash cycle. And a company that grows from C$25,000 of financing to C$250,000 can find itself proving the same business all over again.
Canada is already working on many of these problems. That's important. The opportunity isn't to replace banks, BDC or existing programs with one new solution.
It's to make the financing relationship itself work better as the SME changes.
Current business data can lower underwriting cost. Public guarantees can make smaller loans practical. Intellectual property can become easier to finance when valuation and recovery evidence improves. Consumer driven banking can help verified information travel. Specialist lenders can serve needs that large institutions aren't structured around. Growth equity can take over when debt stops being the right answer.
Put those pieces together and the financing process starts looking like a relationship that grows with the company (not disconnected and fragmented).
And for someone's sake, SMEs shouldn't have to become the wrong kind of business just to fit the available loan.
If a Canadian SME keeps proving itself through stronger revenue, better cash flow, customers and intellectual property, why should its financing relationship have to start over every time the business reaches a new stage?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 12, 2026 | Last Updated Sep 22, 2026 | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Regulation And Policy, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Open Banking Open Finance And Data Sharing, Payments Infrastructure And Money Movement, Cross Border Payments And FX, Lending Consumer Credit And BNPL, Cybersecurity Fraud And Financial Crime

] Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026, August 29-September 4, 2026, September 5-September 11, 2026).
The relief gives trading apps, software developers and wallet interfaces a clearer way to connect users with regulated derivatives markets without automatically entering the introducing broker registration perimeter. Firms still need to test their activities against the letter's conditions, especially where software takes a more active role in solicitation or execution.
Tokenized U.S. equities now have a defined regulatory route for limited onchain secondary trading. Venues, liquidity providers and infrastructure firms can assess whether their technology, custody, smart contracts and market controls meet the conditions rather than waiting for a complete rewrite of securities market rules.
A US$600 million final close gives one of Canada's largest fintech investors substantial capital to deploy while venture markets remain selective. The size of the fund also keeps Canadian based investment capacity relevant in financing fintech companies that may need several rounds of private capital before reaching an acquisition or public market.
Canada is putting much larger pools of private financing beside more aggressive investment tax treatment. The question for fintech and technology companies is how much of that capital reaches growth businesses, AI, cybersecurity and commercialization. NCFA's RBCx scaleup analysis shows why Canadian companies still need more late stage domestic capital to scale at home.
UK crypto firms now have a defined test for which activities require permission and a live timetable for entering the new regime. Firms need to map each product, custody arrangement, trading function and technical role to the perimeter before the application window closes, rather than relying on existing registrations to carry forward.
The Senate vote leaves U.S. digital asset firms without the federal market structure framework the bill was intended to establish. Exchanges, issuers and other market participants remain exposed to existing SEC and CFTC rules while Congress decides whether the legislation can be revived.
Tax certainty is becoming part of Canada's large investment toolkit. Faster binding rulings can affect financing structures, project economics and investment approvals when tax treatment needs to be settled before significant capital is committed.
The FCA has taken tokenized gold beyond the exploratory stage covered in NCFA's earlier wholesale collateral analysis. Market participants now have a defined regulatory input window on ownership, transfer, pledging and potential market treatment before authorities decide whether more specific rules are warranted.
Bastion now has a federal route for bringing stablecoin issuance, custody and conversion infrastructure under one OCC supervised trust bank structure. Enterprise clients evaluating white label stablecoin programs gain another federally supervised infrastructure provider, while Bastion still needs to complete the conversion requirements before operating under the national charter.
Agora now has a federal charter route for moving AUSD issuance, custody and transaction services into an OCC supervised trust bank. The approval gives institutional stablecoin infrastructure a clearer federal operating structure, but Agora cannot begin business through the proposed bank until it satisfies the OCC's preopening conditions.
Hong Kong is coordinating licensing, tokenized securities, stablecoins and settlement infrastructure within one policy program rather than treating them as separate initiatives. Financial institutions and digital asset firms can plan against a clearer sequence of regulated distribution, tokenized cash settlement and round the clock infrastructure as the individual measures are implemented.
LMAX is now using Standard Chartered for regulated institutional custody in both Europe and the Middle East. The arrangement gives the bank a live client for its Luxembourg custody platform and extends the pair's relationship from trading and credit intermediation into asset safekeeping.
The settlement reaches directly into loan design, pricing, disclosure and dealer oversight rather than ending with a financial penalty. Auto lenders and lending platforms serving higher risk borrowers should review affordability controls, dealer incentives, add on products and post origination relief processes against the practices targeted by the agreement.
Catena puts an AI agent focused financial model inside the federal trust bank charter process. If it completes the OCC requirements, businesses could combine agent permissions with custody, investment management and transaction services under one supervised institution, creating a regulated test case for how autonomous software can be given financial authority without removing business control.
Colombia gives Revolut another market where it can operate through its own regulated bank rather than relying only on partner institutions. The approval follows its recent conditional U.S. bank approval, showing how the company is assembling local banking permissions market by market while retaining one global product and technology platform.
Open Banking API versioning is now a production dependency for firms connected to AIB. Third party providers need current payloads and validation rules in production because specification mismatches can translate directly into rejected requests and disrupted customer flows.
Two national card systems are becoming directly usable across each other's markets without requiring a separate international card product. For banks, payment providers and merchants in the Gulf, deeper national network interoperability can lower reliance on additional payment layers while giving customers more ways to use domestic cards when travelling across the region.
Instant payment access is reaching smaller financial institutions through shared infrastructure rather than individual rail integrations. Credit unions can add FedNow, RTP and future digital payment capabilities while retaining their core systems and control of member funds, reducing one of the technical barriers that can separate community institutions from larger banks.
The digital euro program is entering practical merchant and payment provider testing rather than remaining a design exercise. Participating firms can now test integration, checkout, payment acceptance and operational workflows, giving the Eurosystem direct evidence on how a potential digital euro would function inside everyday commerce.
Regulated stablecoin infrastructure is entering ordinary business settlement rather than stopping at issuance and transfer tests. The workflow adds operating evidence to NCFA's question of whether stablecoins are becoming payment infrastructure, with treasury value now depending on reconciliation, redemption and commercial recordkeeping as much as token transfer.
OSL can now handle funding and settlement across six major currencies through one banking relationship instead of assembling separate connections market by market. For institutional digital asset clients, that can simplify fiat access, treasury operations and liquidity management while keeping settlement connected to regulated banking infrastructure.
The expansion gives Thunes customers more ways to reach recipients across six additional markets through one network connection. That reduces the number of local payout relationships a cross border provider needs to manage while extending access across bank accounts, wallets and cash pickup channels.
European financial institutions will need to extend structured third party risk controls beyond ICT services into other critical outsourced functions. Banks, payment firms, investment firms and cryptoasset businesses should review how they identify material providers, document due diligence, monitor subcontracting and plan exits as the new framework replaces the existing outsourcing regime.
The acquisition places widely used smart contract security infrastructure inside a major institutional ratings and market intelligence group. Banks, asset managers and tokenization firms could gain broader access to onchain security assessment and benchmarking, while control of a key security provider shifts closer to the institutions building regulated digital asset products.
Capital is available, but access is being defined more tightly through licences, exemptions, APIs, settlement rails and operating controls. For Canadian fintechs, the way forward is to stay abreast of these changes early and building around the permissions, infrastructure and compliance requirements before they become standard market expectations.
Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 15, 2026 | NCFA Market Activity | Digital Banking And BaaS, Cross Border Payments And FX, Competition And Market Structure
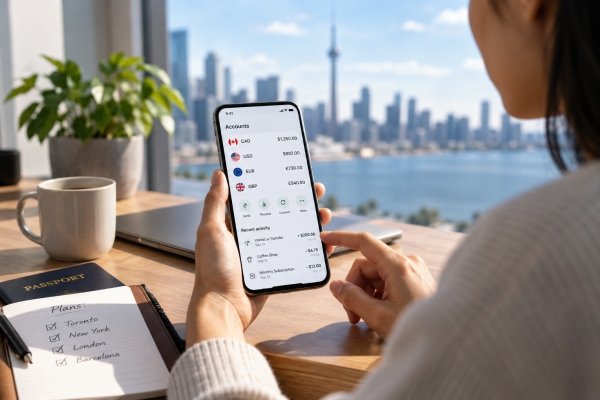
On September 14, 2026, UK-based global payments company Wise launched a Chequing Account in Canada with no monthly fee, Interac e-Transfer support, Canadian account details, pre-authorized debits, debit-card access and multi-currency features. The launch takes Wise further into everyday Canadian financial activity while keeping the cross-border tools that built its original customer base.
The account is available to personal and business customers in Canada. Customers can hold more than 40 currencies, receive money using account details available across 22 currencies and send money to more than 70 countries. Wise converts currencies at the mid-market rate and charges a separate conversion fee that currently starts from 0.19%, depending on the currency and transaction.
Canadian customers can send up to C$25,000 to a supported Interac email address and receive up to C$25,000 per day through Interac Autodeposit. Wise doesn't charge its own fee to receive Autodeposit payments, and the September launch removed the Wise fee for sending CAD to an Interac alias and adding CAD through Interac. Incoming transfers that require a security question and manual acceptance aren't currently supported, and an email registered for Wise Autodeposit can't remain registered for Autodeposit at another financial institution.
Wise also provides Canadian institution, transit and account numbers for electronic deposits and withdrawals. Customers can receive pay, set up pre-authorized debits for recurring bills, spend through a physical or digital debit card and withdraw cash at ATMs. Wise currently charges no withdrawal fee on the first C$100 each month, then C$2.69 plus 2.69% on the amount above C$100, while an ATM operator can charge its own fee.
Group Spend lets customers create a shared balance for expenses such as household bills or trips. Wise's international features are still a key difference. Customers can hold CAD and dozens of other currencies in one account, convert between them and receive money using account details available in 22 currencies.
Wise Payments Canada Inc. is not a Canadian bank. It is registered with the Financial Transactions and Reports Analysis Centre of Canada as a Money Services Business under registration M15193392 and with the Bank of Canada as a payment service provider under the Retail Payment Activities Act. It also holds a Quebec money services business licence.
Wise keeps customer funds separate from its operating money under Canada's payment-safeguarding rules. For its Chequing Account, Wise says eligible deposits are held in trust at a Canada Deposit Insurance Corporation member institution with customers identified as beneficiaries. Eligible deposits can receive CDIC protection of up to the equivalent of C$100,000 per beneficiary if the member institution fails and the trust-disclosure requirements are satisfied; Wise itself is not a CDIC member.
Foreign-currency balances aren't automatically excluded because CDIC can cover eligible deposits in Canadian or foreign currency. Coverage still depends on the deposit meeting CDIC rules, and balances held for the same customer at the same member institution can be combined when insurance limits are calculated.
Wise also became a Payments Canada member in January 2026 after federal rule changes opened membership to regulated payment service providers. That gives Wise a formal role inside Canada's payments system and makes eligible PSP members able to seek participation in payment systems under the applicable rules. Membership doesn't automatically give Wise direct access to every Canadian payment rail.
Canadian consumers can already choose among traditional banks, digital banks and fintech accounts that cover much of the same daily activity. Wise competes with domestic payment functions and a deep multi-currency product, while using a regulated non-bank structure for the account itself.
Big Six banks: Traditional banks still combine chequing with lending, credit, branches, drafts and direct deposit-taking. RBC Day to Day Banking, for example, has a standard C$4 monthly fee and includes 12 debit transactions plus unlimited Interac e-Transfers. Wise removes the monthly fee and adds much deeper multi-currency functionality, but it doesn't replace the full range of services available through a bank.
Wealthsimple: Wealthsimple has expanded deeper into everyday banking with chequing, payments, direct deposit, cards and other daily money tools. Customer cash is held in trust with CDIC member institutions rather than by Wealthsimple as a bank. Wise has the stronger cross-border proposition through currency holding, foreign account details and international transfers.
KOHO: KOHO combines prepaid-card spending, Interac transfers, Autodeposit and bill payments, with customer funds held through a trust structure designed to qualify for CDIC protection. Its product is centred more heavily on Canadian spending, credit building, rewards and budgeting, while Wise puts international money management at the centre of the account.
EQ Bank: EQ Bank's Personal Account also has no monthly fee and includes unlimited Interac e-Transfers, bill payments, direct deposit and card access. The legal model is different because EQ Bank is a trade name of Equitable Bank, a federally regulated bank and CDIC member that accepts deposits directly. EQ already uses Wise for international transfers, making it both a competitor in everyday banking and a distribution partner for Wise's cross-border capability.
Neo Financial: Neo gained direct Interac e-Transfer access in April 2026 and offers digital chequing functions including Interac transfers, bill payments, pre-authorized debits and card spending. Its focus is more Canadian spending, credit and rewards, while Wise brings a much deeper international money layer.
Wise now covers many of the tasks that keep a chequing account central to a customer's financial life, while adding something most Canadian chequing products don't offer at the same depth: one account built around both domestic use and frequent cross-border money movement.
Canada's regulatory changes give non-bank providers more room to compete for that relationship. RPAA supervision applies operational-risk and safeguarding requirements to payment service providers, while Payments Canada membership brings qualifying fintechs closer to national payment systems. Consumer-driven banking could extend that competition further if customers gain easier ways to connect financial data and services across institutions.
Wise is also giving the launch a physical presence through a temporary pop-up at Toronto Eaton Centre on Level 1 from September 14 through October 11. Customers can register, get product help and participate in launch promotions there, but the location is a Wise promotional and service activation rather than a Canadian bank branch.
Wise can now handle many of the transactions Canadians associate with a primary chequing account while remaining a regulated non-bank provider. How much of the everyday banking relationship can fintechs win before customers care less about whether their main account comes from a bank?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016