




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 9, 2026 | NCFA Insight | Capital Markets Infrastructure And Funding, Competition And Market Structure, SME Finance And Business Banking
On September 9, 2026, RBC announced a C$1.4 billion Canadian technology initiative anchored by RBCx Growth Fund I. The proposed fund will make direct late stage equity investments in Canadian technology companies with global ambitions. RBC plans to invest up to C$416 million, or US$300 million, including an initial US$200 million commitment to portfolio companies.
The C$1.4 billion headline encapsulates the wider initiative, not the size of RBCx's Growth Fund I. But its disclosed something more interesting: equity will be invested alongside commercialization support, strategic partnerships and access to RBC's banking, capital markets and public sector relationships.
RBCx already has reach. It says it banks 3,500+ technology companies, has invested in 10 venture funds and more than seven companies directly, and operates four RBC owned ventures. Fintech runs through part of that history: Mydoh has reached more than 140,000 Canadians, Ownr has registered or incorporated more than 130,000 businesses, and Dr.Bill has processed C$4.1 billion in medical billings for more than 14,000 physicians.
The new fund has a broad mandate spanning enterprise software, AI, cybersecurity, health tech, frontier technology, energy, climate and agricultural technology. Its strategic value comes from the model around it. RBCx can potentially combine equity, venture debt, banking, customers and capital markets support across the same company lifecycle.
Canadian companies do not become global competitors because someone writes a larger cheque at Series C. They get there by building management depth, repeatable sales, enterprise customers, regulatory capability, financial controls, technology that can handle growth and enough distribution to reach new markets. Those capabilities need to start forming years before the biggest financing round arrives.
The capital data shows how narrow the funnel becomes. Canadian venture investors deployed C$2.69 billion across 250 deals in the first half of 2026, yet only 18 later stage deals accounted for C$984 million. Sixteen rounds of C$50 million or more absorbed 59% of all venture dollars, while RBC cites PitchBook data showing Canadian investors led only 33% of domestic growth rounds over the past decade.
There is pressure further upstream too. Canadian VC fundraising fell to just over C$2.1 billion in 2025, with the five largest funds capturing 83% of the capital raised. When fewer funds have enough capital to support companies through multiple rounds, fewer startups get the time and resources needed to build serious operating capability.
That is the bigger Canadian issue. Founders need capital, but they also need customers, talent, workable regulation, financial infrastructure and enough room to execute. International growth only gets harder when those capabilities are weak at home. If too few startups build them early, there will be fewer strong growth companies and even fewer Canadian firms capable of competing globally at scale.
This is where RBCx could be more useful than another pool of equity. A scaling company may need venture debt, operating credit, FX, treasury, foreign accounts and enterprise customers while it is raising its next round. RBCx already works across many of those needs, which gives founders a chance to build financial and commercial capacity before the company becomes large enough to attract the biggest investors.
Customer access is another valuable part. RBC says portfolio companies may receive commercialization support, customer strategy help and introductions through its commercial banking, capital markets and public sector relationships. Founders will care about what those introductions produce: paid pilots, enterprise contracts, distribution and follow on capital.
RBC has a clear commercial incentive in seeing those companies grow. A startup that becomes a large technology company can eventually become a valuable client across lending, treasury, FX, employee banking, wealth and capital markets. RBC has not stated customer lifetime value as the motive for Growth Fund I, but the economic alignment is obvious.
BDC and Canadian venture firms already supply growth capital, so success shouldn't necessarily be measured by dollars deployed. A better measurement may be whether RBCx backed companies win larger customers, build foreign revenue faster, raise future capital from a stronger position and keep meaningful operating capability in Canada. That connects directly with Canada's productive growth challenge where promising companies need enough capital and operating capacity to become globally competitive businesses.
Canada's scaleup problem starts well before the scaleup round. RBCx already works across banking, venture investing and technology businesses, and Growth Fund I adds equity to that mix. If the combination helps more Canadian companies build customers, capability and financing strength early enough to compete globally, the initiative will have earned its C$1.4 billion headline.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
On September 9, 2026, BMO InvestorLine announced unlimited zero commission trading on stocks and exchange traded funds for all self directed clients. The pricing takes effect September 14. BMO is also removing brokerage account administration fees and cutting options pricing to zero base commission plus $0.90 per contract, down from $1.25.
BMO says InvestorLine is the first direct investing brokerage owned by one of Canada’s five largest banks to eliminate commissions across stock and ETF trades. That’s important, but it isn’t where Canada’s zero commission story begins. Wealthsimple had already made free stock trading a consumer proposition in 2019. National Bank and Desjardins followed in 2021. Questrade took its remaining stock and ETF commissions to zero in 2025.
What BMO changes is where the pressure has reached. A trading fee that survived for years inside Canada’s largest bank owned brokerages is now disappearing at one of them.
BMO is not the first Canadian financial institution to offer zero commission trading. It is the first of the Big Five to make unlimited zero commission stock and ETF trading its standard self directed price.
That leaves a more interesting question than who cuts next. If the trade itself costs nothing, what are Canada’s brokerages really competing to win?
In March 2019, Wealthsimple Trade opened zero commission investing to Canadians. Wealthsimple said most Canadian trading services were charging roughly $5 to $10 per trade at the time.
The proposition was easy to understand. Buy or sell a stock and the headline commission was zero.
Low cost online brokerage was already well established in Canada. Questrade had been competing with bank owned brokers since 1999 and spent years cutting the cost of self directed investing.
Wealthsimple changed the reference price. Instead of asking whether a digital broker was cheaper than a bank, customers could ask why a stock trade needed a commission at all.
Discount brokers already make trading cheaper. Wealthsimple makes zero easy to see, easy to compare and available through a mobile app. Every brokerage still charging by the trade now has a much simpler price to compete against.
Canada wasn’t developing in isolation. Robinhood began building its U.S. brokerage around commission free trading in the 2010s.
By October 2019, the pressure had reached the largest American brokers. Charles Schwab cut its US$4.95 online stock commission to zero. TD Ameritrade, E*Trade, Fidelity and others followed.
Those decisions weren’t cosmetic. When E*Trade announced zero commissions in 2019, it estimated the change would reduce revenue by roughly US$75 million per quarter.
Brokerage shares fell sharply as investors worked out what a disappearing transaction fee meant for firms that had relied heavily on commissions.
Robinhood shows that free trading can pull customers toward a new platform. The U.S. incumbents show what happens when enough customers begin expecting the same price. Canadian brokerage economics are different, but the competitive pressure travels.
The first Canadian bank owned brokerage to go all the way wasn’t BMO.
On August 23, 2021, National Bank Direct Brokerage eliminated commissions on online Canadian and U.S. stocks and ETFs.
National Bank called it a Canadian first for a bank owned direct broker. Its previous standard commission had been $6.95.
National Bank was unusually clear about the business logic.
Martin Gagnon, then Executive Vice President of Wealth Management, said “The objective is very simple. It’s to increase our client base.”
National Bank’s securities brokerage commission line was about C$60 million for the quarter, but management said only a very small fraction of that amount was at risk from the direct brokerage pricing change. Transaction revenue had already become a smaller part of the business.
National Bank proves that a Canadian bank owned brokerage can give up the visible trading fee when gaining customers, assets and other business is worth more.
Desjardins also removed online stock and ETF commissions in 2021.
By January 2026, Desjardins Online Brokerage reported C$30 billion in assets under administration. Assets had climbed 80% over four years and the number of platform and mobile app users had increased 30%.
Zero commissions alone didn’t produce those gains. They do show that the model can operate at meaningful Canadian scale.
Questrade took the pricing question further in February 2025 when it removed online stock and ETF commissions across its self directed accounts.
By 2026, the company reported more than C$80 billion in assets under administration and was extending well beyond basic trade execution. Questrade Connects Brokerage Accounts To AI Agents follows its expansion from lower cost trading into personalized portfolios, banking and agent accessible investing.
The commission is gone, but the platform has more products to sell.
A customer who arrives to buy a stock can also hold cash, borrow, use managed portfolios, buy private assets, open banking products or use new investing tools. That makes the account itself more valuable than the fee on an individual trade.
BMO now brings unlimited zero commission trading inside the Big Five.
Immediately before the announcement, its standard InvestorLine price was $9.95 per online stock trade. A customer making 100 commissionable trades a year could spend about $995 on those commissions.
At 250 trades, the amount was roughly $2,487.50. At 500, it reached $4,975.
The other Big Five brokerages aren’t standing still, but their standard offers remain different.
TD Direct Investing lists a standard stock commission of $9.99. RBC Direct Investing lists $9.95 for its full brokerage offer, while GoSmart includes a limited number of free trades. CIBC Investor’s Edge lists $6.95 for standard online equity trades and offers commission free ETFs. Scotia iTRADE lists a standard equity commission of $9.99, with some Scotia banking packages including a limited number of free trades.
National Bank gets there five years earlier. BMO matters because unlimited zero commission stock and ETF trading now reaches one of the institutions at the centre of Canadian banking.
Zero commission doesn’t mean zero cost.
BMO says it can earn 1.6% on currency conversions below US$25,000, with the percentage declining as the transaction gets larger.
A US$10,000 conversion at 1.6% works out to US$160. That is far larger than the $9.95 stock commission that disappears.
The same calculation matters across the industry. Wealthsimple lists a 1.5% foreign exchange fee on applicable Canadian dollar and U.S. dollar conversions.
Brokerages can also earn revenue from options, margin borrowing, subscriptions, interest, advisory services, managed portfolios and other financial products.
A $0 order therefore tells investors the cost of the trade. It doesn’t tell them the total cost of using the brokerage.
The brokerage can give up the transaction fee because customer assets create other opportunities. Currency gets converted. Cash stays on the platform. Some investors borrow, trade options, buy managed products or add other financial services.
Wealthsimple makes the strategy especially visible. What began with investing now stretches across cash, cards, tax, mortgages, private investments, crypto and other financial products.
Its growth also shows the scale challengers can reach. By early 2026, Wealthsimple said it served more than 3 million Canadians and had passed C$100 billion in assets under administration.
BMO starts from the opposite direction. It already has banking, lending, cards, advice and wealth management. Taking the trade commission to zero gives an existing bank another way to keep self directed investors inside a much larger financial relationship.
That makes BMO’s decision more than a brokerage price cut. A digital challenger can use cheap investing to enter the relationship. A large bank can use the same price to defend one it already has.
BMO removes one of the easiest price differences for investors to compare. Brokerages now have to win on total cost, foreign exchange, options, margin, tools, advice, product access and how much of a customer’s financial life they can serve.
BMO’s zero commission pricing follows years of pressure from discount brokers, fintechs and earlier bank competitors. Once the stock trade costs nothing, the bigger prize is the customer, their assets and the rest of their financial relationship.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
| | |
|---|---|---|
| | |
September 8, 2026 | NCFA Insight | Payments Infrastructure And Money Movement, Digital Assets Blockchain And Tokenization, Treasury Liquidity And Cash Management
On September 8, 2026, Visa introduced an onchain credit model for stablecoin card programs that combines VisaNet settlement data with financing provided by Credit Coop. Visa isn't the lender. Credit Coop provides stablecoin denominated revolving credit secured by settlement receivables, while authorized Visa settlement records help lenders assess how participating programs are actually performing.
Visa says more than 160 stablecoin card programs are live globally, with payment volume up nearly 200% year over year. Its stablecoin settlement volume recently passed a US$20 billion annualized rate, more than 15 times the prior year. Credit Coop has financed more than US$2.5 billion since 2023 across more than 3,000 borrowing events and 9,000 repayments, with zero defaults reported across participating facilities.
Visa says more than US$694 billion in stablecoin denominated loans have been sent through onchain lending protocols since 2020. The new element is using payment network data to support credit decisions for businesses operating inside the card system.
Card programs can owe Visa money before they have collected the related funds from cardholders. Large issuers usually finance that timing gap through bank credit lines, warehouse facilities or securitizations. Those structures work well when portfolios are large and lenders have enough operating history to assess them.
Early stablecoin card programs can have a different funding profile. Visa says some need only a few million dollars, draw and repay capital every day and settle through weekends and holidays. At that scale, the fixed cost of arranging a traditional facility can be difficult to justify, while the borrower may not yet have enough history to satisfy an institutional lender.
Visa's financing model uses a revolving Credit Coop facility to fund daily settlement obligations against the receivables generated by the card program. As cardholder payments arrive, those proceeds repay and replenish the line.
That financing need grows with the card programs themselves. Wirex and Crossmint connected wallets, card issuance and stablecoin spending earlier this year, showing how quickly the customer facing infrastructure is becoming easier to assemble. Financing the settlement behind those products is a different problem.
The concept is similar to bringing rent payments into a traditional credit file. A recurring payment record that was previously difficult for lenders to use becomes additional evidence about the borrower. Here, the new evidence is payment network data being used to support onchain credit.
With the card program's authorization, Credit Coop receives daily Visa settlement files through a secure data connection. It compares those records with the onchain repayment history when sizing facilities, confirming settlement requirements and monitoring repayment. The borrower is no longer the only source of information about its payment obligations.
Credit Coop's Spigot smart contract controls how incoming receivables service the facility. Cardholder proceeds flow through the contract, which routes repayment before the remaining funds reach the borrower's operating account. The structure performs a role similar to a controlled bank lockbox, but repayment can occur programmatically.
Visa says stronger data and a longer repayment record have attracted more lenders to the facilities, reducing borrowing costs for participating programs by as much as 30%.
The same data connection can also support funding closer to the actual settlement obligation. Instead of drawing a larger amount in advance and holding unused capital, the daily settlement file can trigger a same day disbursement for the net amount owed to Visa. That reduces the time capital sits idle and ties lender exposure more closely to actual settlement activity.
Rain provides the longest operating record disclosed by Visa. The Visa Principal Member has used a Credit Coop revolving facility since August 2023 and settles directly with Visa in USDC. Rain says it tokenized its card receivables, allowing incoming payments to service financing through programmable contracts.
Visa reports that approximately US$2 billion of Rain settlement has been financed through the structure, with more than 2,000 borrowing events and 7,000 repayments. They also report zero defaults and says every settlement obligation under the facility has been funded on time. The underlying program figures were supplied by Credit Coop, so they should be treated as reported operating data rather than independently audited results.
Visa says Karta's U.S. card program used Credit Coop while its operating history was still developing. In June 2026, Karta raised US$140 million, including a US$125 million institutional credit facility from Community Investment Management and a US$15 million Series A led by Galaxy Ventures. Karta reported 10 times growth in 2025 and another four times increase in revenue and payment volume quarter over quarter in Q1 2026.
The growth gives the model its strongest strategic relevance. Onchain credit can help finance a younger payment program while it builds a verifiable repayment record. Larger institutional facilities can become available later when the portfolio reaches the scale and maturity conventional lenders want. Visa explicitly says this model adds to warehouse lending and securitization rather than replacing them.
Canada already has a direct connection to Visa's stablecoin settlement strategy. In May, Visa Canada and Wealthsimple began testing USDC settlement for certain Visa Canada obligations. There is no public evidence that the Credit Coop financing model is currently available to Canadian programs, but it gives Canadian issuers and payments firms a concrete example of how stablecoin settlement can connect to working capital and credit.
If payment network data can help a young card program prove credit performance before it qualifies for a traditional warehouse facility, onchain credit may become a bridge into institutional finance rather than a separate system.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 8, 2026 | NCFA Insight | Cross Border Payments And FX, Payments Infrastructure And Money Movement, Digital Assets Blockchain And Tokenization
On September 8, 2026, Circle agreed to acquire Tazapay, a Singapore headquartered B2B payments company serving payment providers and financial institutions. Circle says Tazapay brings more than US$25 billion in annualized payment volume, 60+ banking and fintech partners and payout connections across 100+ markets. Approximately 60% of its transaction volume involves stablecoins.
The US$400 million transaction will be paid in Circle Class A shares, subject to specified adjustments. Circle signed the agreement on September 4 and expects it to close in 2027 after required approvals, including approval from the Monetary Authority of Singapore. The acquisition has not closed.
Tazapay was already a Circle Payments Network design partner, and Circle Ventures led an extension of its Series B in March 2026. Circle is now acquiring to own a company that connects stablecoin settlement with local banking, FX and payout access.
Tazapay connects businesses to international collections, local payouts, foreign exchange and stablecoin conversion. Its payments platform supports card payments from 170+ countries, local payment methods in 100+ countries, payouts across 100+ countries and balances in 40+ currencies.
Its operating scale has grown quickly. In August 2025, Tazapay reported more than US$10 billion in annualized volume, 300% annual growth and operational breakeven. Circle reported more than US$25 billion in annualized volume as of July 31, 2026.
Tazapay's Series B reached US$36 million after Circle Ventures led the March extension. So going from payment partner to investor to proposed owner gives Circle more direct control over a business already connecting digital dollars with conventional payment systems.
Stablecoins can settle value across borders, but businesses usually receive and spend local currency. Circle Payments Network reflects that model. Payout partners convert stablecoins to fiat for local delivery, while Circle provides USDC settlement and network routing. Circle's payout network already includes Tazapay and other regional providers.
Circle is also connecting external networks rather than owning every payout route. In May 2026, Nium joined Circle Payments Network with payout infrastructure spanning more than 190 countries and 100 currencies. That partnership gives Circle substantial reach without an acquisition. In Tazapay's case, Circle is paying US$400 million to bring part of that payment capability inside the company.
Circle says roughly 60% of Tazapay transaction volume involves stablecoins. Tazapay describes its stablecoin service as payment and conversion through onramps and offramps, so the figure does not mean 60% of transactions run entirely onchain. Stablecoins may handle settlement while customers still enter or leave through fiat.
Other large payment companies are making similar acquisitions. Stripe completed its purchase of Bridge in 2025, Ripple agreed to acquire Rail for US$200 million, and Mastercard completed its acquisition of BVNK in August 2026. Mastercard explicitly described the deal as connecting digital assets with traditional payment rails. Taken together, a competitive market is forming around the links between stablecoins, banks, FX and local payments.
NCFA's Programmable Stablecoin Payments highlights the same commercial opportunity opening around payment routing, treasury, reconciliation, compliance and bank integration around stablecoin settlement rather than simply issuing another token.
Tazapay has a direct Canadian operating connection. Tazapay Canada Corp. is registered with FINTRAC as a money services business and with the Bank of Canada as a payment service provider under the Retail Payment Activities Act. Tazapay says the Canadian entity handles foreign exchange, fund transfers and virtual currency activity, and provides its stablecoin payment and conversion services. However, Circle has not disclosed a specific role for Tazapay Canada Corp. post acquisition, and therefore should not be treated as automatically giving Circle new Canadian permissions.
The more immediate Canadian relevance is commercial. Tazapay already connects stablecoin settlement with fiat conversion and local payout access. Canadian fintechs serving international businesses face the same need to connect digital money with bank accounts, FX, compliance and usable local payment methods.
Stablecoins can settle globally, but businesses still need banks, currencies and payout systems at either end. As those connections become more valuable, will the leading stablecoin companies keep renting access or increasingly own the rails?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 29, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Competition And Market Structure, Regulation And Policy, Risk Compliance And Regtech, Lending Consumer Credit And BNPL, Cross Border Payments And FX, Digital Banking And BaaS, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Payments Infrastructure And Money Movement

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026).
This is a material step beyond the group's 2025 exploration phase. TD and Scotiabank are now participating in a global bank-led issuance venture while Canada's own stablecoin framework is still moving through implementation. The Canadian question is whether major banks build meaningful CAD-denominated digital-money capacity alongside domestic initiatives or gain scale first through shared global USD infrastructure.
Coinbase supplies the regulated trading and custody stack while Webull keeps the investor interface and brokerage relationship. That reduces the infrastructure brokers need to build themselves and gives specialist providers another route into Canadian retail distribution. It also intensifies Canadian crypto competition over who owns the customer and who supplies the regulated back end.
The useful proof is the cash leg. Tokenized securities have limited value if settlement still depends on separate legacy rails. This transaction puts the asset and payment legs onchain in a live regulated market environment, bringing programmable settlement closer to something institutions can actually use.
LSEG is extending tokenization from private markets and settlement infrastructure toward public equities. The harder test is whether tokenized shares can preserve legal ownership rights, corporate actions, price integrity and regulated settlement while gaining wallet portability and longer trading access. If that model works, public-market infrastructure begins competing directly with blockchain-native distribution without abandoning the protections of an exchange-listed security.
Coinbase is bringing regulated crypto derivatives distribution into Canada without routing the products through Coinbase Canada itself. The important boundary is eligibility as it expands access for sophisticated investors while keeping the offering outside ordinary retail availability. It also gives regulated venues a stronger alternative to offshore derivatives platforms for Canadian capital, hedging and price discovery.
The important development is bank ownership of shared tokenized deposit infrastructure, not the financing round. Cari is moving toward production with banks helping govern, fund and use the network while retaining the customer relationship. Alongside other shared bank blockchain infrastructure, the test is whether common digital money networks can achieve enough participation and interoperability to compete with institution specific systems.
Forty-three state licences give OpenPayd something infrastructure providers can't create through software alone: regulated geographic reach. The company can now connect its payment stack to a much larger U.S. operating footprint while combining fiat and digital asset permissions across the United States, United Kingdom and Europe. The test is how quickly that regulatory coverage converts into client activity and payment volume.
Final approvals put the transactions into execution. National Bank is positioned to absorb Laurentian's retail and SME relationships while Fairstone combines its commercial lending operations with Laurentian's commercial specialization. Customer migration, product continuity and retention now determine how much of the approved transaction value survives the transfer.
Australia's digital asset licensing transition now has a firm market access deadline. Firms still relying on transitional relief need the correct licence application or variation underway before September 30, while brokers, tokenization businesses, market operators and clearing providers must test whether their activities fall inside the existing financial services perimeter ahead of the new 2027 digital asset regime.
Singapore is converting stablecoin policy into the legal requirements issuers will operate under. The consultation advances the status tracked in NCFA's stablecoin regulatory intelligence from a finalized framework awaiting legislation toward implementation. Reserve, redemption, capital and cross-border requirements can now be tested against issuer economics before the rules are finalized.
The case makes privileged information a concrete event contract surveillance problem. Exchanges and brokers need controls that can connect unusual positions with access to confidential information, investigate suspicious activity and enforce trading restrictions. NCFA's regulated event contract infrastructure brief tracks this market integrity gap as distribution expands.
Section 311 can reach beyond a targeted foreign bank because U.S. institutions must also identify transactions routed indirectly through other correspondent relationships. Banks and payment firms therefore need enough counterparty visibility to detect the institution behind a payment chain, not only the correspondent presenting the transaction.
The investigation puts transaction monitoring and global compliance governance under direct supervisory scrutiny at a major cross-border payment provider. The operating test is whether controls identify known laundering typologies across high-risk channels and whether global decisions support local obligations. The eventual findings could provide useful evidence for how regulators assess AML controls across international payment networks.
Australia's AML expansion has reached the point where AUSTRAC is testing whether newly covered firms have entered the regulatory system at all. Service classification, enrollment and working AML controls can no longer remain implementation projects. Regtech providers also gain a much larger addressable compliance market, but buyers will need products matched to obligations regulators are actively checking.
Conditional approval advances Revolut from U.S. fintech distribution toward direct regulated banking capacity. Its U.S. business still relies on a partner bank, while NCFA's Revolut company intelligence had tracked the national bank application as pending. A completed charter would give Revolut more control over deposits, credit and payment connectivity, but the remaining federal approvals and preopening requirements still determine whether that capacity reaches customers in 2027.
OpenReserve is trying to combine conventional banking, tokenized deposits, digital asset custody and stablecoin infrastructure inside one national bank structure. Preliminary approval brings that model closer to regulated operating capacity, but the remaining test is execution: capital, controls, final authorization and separate approval for the planned stablecoin subsidiary still stand between the proposed structure and live customer activity.
TabaPay is trying to internalize regulated banking capacity rather than relying exclusively on sponsor bank relationships. Owning an OCC chartered bank could give the payments fintech more control over settlement, sponsorship, redundancy and difficult client use cases while retaining outside bank partners. The acquisition still requires regulatory approval, making the next test whether supervisors accept that vertical integration and its governance model.
A successful Swedish licence would turn Allica's international expansion from a funding plan into regulated market access. The bank now has to prove that its UK SME model can satisfy a new supervisor and compete in a concentrated, highly digital banking market. Approval would also give Allica a potential base for wider European expansion rather than requiring each new market to begin from the UK.
The US$3 billion target gives scale to the real time receivable funding model introduced in the United States this week. VersaBank is betting that faster access to bank balance sheet funding can take business from conventional securitization and warehouse structures. Fiscal 2027 will test whether partner demand converts into several billion dollars of new assets without weakening credit quality or funding economics.
The licence adds another authorized BNPL provider while reinforcing regulatory permission as a condition of market access in Saudi consumer finance. New entrants have to compete inside that perimeter, putting more weight on underwriting, merchant distribution, pricing and compliance execution once authorization is secured.
QR Ph is extending domestic interoperability into cross-border acceptance without requiring merchants to install another payment system. That reduces one of the practical barriers to international wallet acceptance, especially for smaller merchants. The competitive question is whether national QR networks increasingly become gateways through which global payment aggregators reach local commerce.
Agorá has crossed the real-money test identified in earlier Project Agorá testing. The harder questions now concern legal finality across jurisdictions, liquidity, interoperability and whether a shared multicurrency platform can reduce correspondent-payment friction at institutional scale without weakening central-bank control or commercial-bank money.
Banks are pushing deeper into stablecoins, tokenized deposits and direct control of payment infrastructure, while fintechs are trying to own more of the regulated stack themselves. The fight is increasingly over who controls the account, the customer relationship and the transaction flow.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
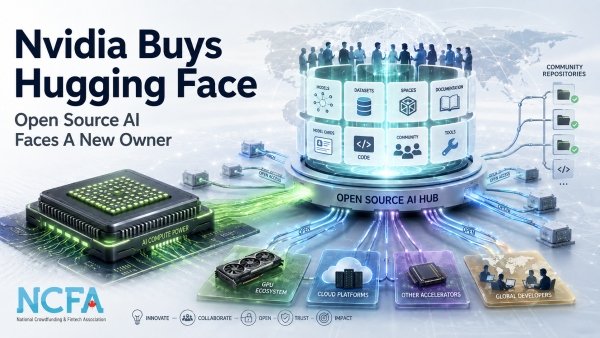
On September 3, 2026, Nvidia announced a definitive agreement to acquire Hugging Face for US$12.9303 billion. The deal would put one of the biggest platforms for open source and open weight AI alongside the company that already dominates much of the market for AI computing.
The price includes about US$11.9 billion for Hugging Face stockholders and up to US$1 billion in equity awards for employees joining Nvidia. The transaction hasn't closed. Nvidia says it expects completion in the first half of 2027, subject to regulatory approvals and other closing conditions.
Nvidia is making a very public promise with the deal. Hugging Face will remain open. Developers will still be able to choose their models, clouds, inference providers and computing platforms. Nvidia hardware will not be required.
That promise goes directly to the tension. Hugging Face became valuable because developers, startups, researchers and rival chip companies could all build there. Nvidia can make that ecosystem stronger. Ownership can also make some of those same users wonder whether an open source AI platform can feel as independent once one of the most powerful companies in AI owns it.
Hugging Face has grown into one of the main places developers find, share and use open AI models. Nvidia says more than 18 million developers, researchers and creators use the platform, along with more than 200,000 companies.
The company was worth far less only three years ago. Hugging Face raised US$235 million in 2023 at a US$4.5 billion valuation, with investors including Google, Amazon, Nvidia, Intel, AMD, Qualcomm, IBM and Salesforce.
Nvidia is now paying close to three times that valuation. The premium makes more sense when Hugging Face is viewed as distribution, developer access and influence over how open models get discovered and deployed.
Hugging Face is valuable because millions of people already use it to decide what to build with. Nvidia is buying that relationship as much as the software behind it. The more developers stay, the more valuable the acquisition becomes.
Nvidia already has enormous power in AI computing. Reuters Breakingviews says Nvidia holds more than 80% of the AI accelerator market, while its chips have become a reference point for a growing market in GPU rental pricing.
That power is one reason the acquisition attracts attention. Nvidia will own a major open model platform while selling the hardware many of those models run on.
Hugging Face has also become important to Nvidia's competitors. Its own 2026 data says AMD and Nvidia are the two most active publishers of new open models on the Hub, with each releasing more than 200 model repositories this year.
AMD uses open models to prove its chips can run real workloads. Google, Microsoft, IBM and other companies also publish and distribute models through the platform.
The acquisition does not remove AMD, Google or other hardware and cloud providers from Hugging Face. Nvidia says support for rival silicon will continue. The tension comes from whether those companies remain just as comfortable investing there when the owner also competes with them.
Nvidia says rival chips will stay welcome. Nvidia's CEO Jensen Huang says developers will keep choosing their own models, frameworks, clouds, inference providers and computing platforms. Nvidia compute will not be required to build on or deploy through Hugging Face.
Developers are already debating what ownership could mean in practice. Some community reactions welcome Nvidia because open models create demand for compute. Others worry about future defaults, private repositories, hardware preference and whether another independent open source AI platform will eventually be needed.
Nvidia doesn't have to close Hugging Face for ownership to change how the platform feels. Developers will notice which hardware gets optimized first, which services are easiest to connect and whether rival products remain equally visible and easy to use.
Open models fit Nvidia's economics surprisingly well. Hugging Face says hardware vendors are publishing open models because a model optimized for their chips is one of the clearest ways to prove the hardware works.
Nvidia can therefore benefit even when the model itself is free to download. More open model use can create more inference and training demand across data centres, enterprises and local machines.
That dependence cuts both ways. Some of Nvidia's biggest customers, including hyperscalers and AI labs, are building their own chips. The Hugging Face deal gives Nvidia a wider developer base at a time when those customers are trying to reduce their own dependence on Nvidia hardware.
Open source AI gives Nvidia access to thousands of smaller users instead of relying only on a few giant buyers.
Nvidia can support open source AI and still benefit commercially from its growth. The company does not need every developer to buy a proprietary Nvidia model. It benefits when more models create more computing demand.
China is pushing hard in the same open model market. Hugging Face data shows Chinese labs released many of the largest open models in 2026. Qwen has become one of the most important model families on the Hub, with more than 151,000 derivative repositories.
Hugging Face says Qwen based models reached more than 2 billion downloads across repositories with declared parameter counts this year.
Chinese open models are also competing on access and cost. Hugging Face found that 59% of Chinese releases above 20 billion parameters used Apache 2.0 licences and another 22% used MIT licences during the period it studied, although some very large releases have begun adding commercial restrictions.
That gives developers another source of capable models as U.S. companies debate how open their own ecosystems should remain.
Open models are part of the technology rivalry between the United States and China. Nvidia's Hugging Face acquisition gives a U.S. company more influence over a global platform at the same time Chinese model families are winning large developer communities of their own.
One possible response to Nvidia ownership is that developers simply stay. Hugging Face already has millions of models, datasets, applications and established workflows. Rebuilding that network somewhere else would be difficult.
Microsoft's GitHub acquisition offers one useful precedent. Microsoft promised GitHub would stay open and independent, and competing developers and platforms continued using it after the acquisition.
Another possibility is that developers begin spreading their work across more places. ModelScope, GitHub, local model tools, cloud registries and private enterprise repositories already give users alternatives for parts of the Hugging Face experience.
A future competitor would not need to copy every Hugging Face feature on day one. It could win users by offering easier migration, open governance, strong model provenance or a clearer commitment to hardware independence.
Network effects make a full replacement difficult, but communities can fragment before platforms collapse. Developers can keep models on Hugging Face while using other tools for discovery, inference, deployment or discussion. Competition may arrive piece by piece rather than through one new platform.
No price increase has been announced. Nvidia says Hugging Face will remain open and hardware choice will continue. That leaves plenty of room for the acquisition to improve reliability, inference tools and enterprise deployment without raising basic access costs.
Costs could still change indirectly. Developers may pay more if the easiest experience ends up depending on premium services, Nvidia optimized infrastructure or harder to replace integrations. The opposite is also possible. Better tooling and stronger open models could lower the cost of running AI compared with closed model APIs.
The acquisition does not automatically mean higher prices. The more interesting cost risk is switching. A service can remain affordable while becoming expensive to leave because models, workflows, integrations and teams are built around it.
Startups could gain from Nvidia's reach. A stronger Hugging Face can give model companies better distribution, more reliable infrastructure and easier access to enterprise customers.
For founders trying to get an open model discovered, being close to a platform used by 18 million developers can be commercially powerful.
Startups may also have less bargaining power if distribution, compute and enterprise access become more concentrated around the same company. A startup can benefit from the platform while still wanting credible ways to deploy elsewhere.
That tension is already visible in competition for cheaper AI inference, where AMD and other hardware companies are trying to give developers alternatives to Nvidia's dominant GPU position.
The upside is distribution. The risk is dependence. Founders will care less about who owns Hugging Face than whether they can still take their models, customers and economics somewhere else when they need to.
Financial institutions face the same ownership question from a different angle. Banks and insurers are already putting AI into governed workflows where data controls, approvals, audit evidence and operational resilience are required.
Governed financial AI workflows become harder when a firm cannot easily change models, clouds or providers without rebuilding controls around them.
Portability can therefore matter more than ownership alone. A bank may be comfortable using Hugging Face under Nvidia if models can still travel across clouds and chips and the institution can keep its own data, controls and audit evidence.
Regulators are also paying more attention to AI vendor concentration and operational dependence as financial firms embed more external technology into critical work.
Financial institutions do not need every AI supplier to be independent. They do need credible ways to change suppliers, hardware and deployment environments without losing control of regulated workflows.
The deal could still produce a strong outcome for open source AI. Nvidia has the engineering resources, compute and enterprise distribution to make Hugging Face faster, more reliable and easier for companies to use.
If AMD, Google, cloud providers, Chinese model labs and independent developers keep contributing, Nvidia can own the platform while the ecosystem remains genuinely competitive.
The harder outcome is quieter. Hugging Face stays open, but developers gradually find Nvidia products easier, cheaper or better supported than alternatives. No door closes. Choice simply becomes less balanced over time.
That is why Nvidia's promise will be judged through product behaviour rather than the announcement itself.
The most valuable version of Hugging Face may be one where Nvidia owns it and its competitors still want to build there. If that happens, Nvidia gets a larger open source AI ecosystem without destroying the trust that made the platform worth almost US$13 billion.
Talking Point
Nvidia does not need to close Hugging Face to gain more influence over open source AI. The deal becomes more valuable if developers, startups and rival chipmakers keep using the platform anyway.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 3, 2026 | NCFA Market Activity | Digital Banking And BaaS, Regulation And Policy, Payments Infrastructure And Money Movement
On September 3, 2026, Revolut received conditional U.S. bank approval from the Office of the Comptroller of the Currency form Revolut Bank US, N.A., a federally chartered national bank headquartered in Stamford, Connecticut. Revolut says it is still working through FDIC, Federal Reserve and final OCC approvals and remains on track for a 2027 launch. U.S. customers cannot open accounts with Revolut Bank US yet.
Revolut already serves U.S. customers, but the regulated banking are with other institutions. Lead Bank supports Revolut's prepaid card accounts and banking services, while Savings Vault funds are held at Cross River Bank. Revolut controls the app and customer experience, but those partner banks hold deposits and perform key regulated functions.
Revolut says the proposed bank would offer loans, credit cards and FDIC insured deposits, alongside access to stablecoins and cryptocurrencies. Its charter application also describes deposits, savings, business credit, payments, remittances and foreign exchange. Some investment and digital asset services could still sit with affiliates or outside providers rather than inside the bank itself.
Revolut has been working toward this for months. It dropped plans to buy a U.S. bank earlier this year and chose to apply for a new national bank instead. The OCC received the Revolut Bank US application on March 4. Conditional approval six months later gets the company much closer to owning the bank behind its U.S. app.
Today, Revolut can build the app, price subscriptions and design much of the customer experience, but it still depends on banks such as Lead Bank and Cross River Bank for core banking functions. That arrangement helped Revolut enter the U.S. without taking on the full cost of becoming a bank, but it also means product changes, deposit economics and parts of the customer relationship depend on outside institutions.
With its own bank, Revolut could keep more of that customer relationship inside the company. Deposits could sit at Revolut Bank US, lending income could stay within the group and the company could build products without asking a partner bank to support every change. Revolut also says direct access to payment networks such as Fedwire and ACH could make transfers faster and cheaper.
The economics become more interesting at Revolut's current size. Its 2025 financial results included US$6.0 billion in revenue, US$1.7 billion in net profit, US$67.5 billion in customer balances and a US$2.9 billion lending portfolio. Revolut now serves more than 80 million customers worldwide and is adding roughly one million customers every 17 days.
The U.S. opportunity is still much less developed than Revolut's business in Europe and some other markets. A bank charter gives the company a chance to compete for deposits, credit and primary banking relationships rather than mainly offering an app connected to somebody else's bank. Revolut has also committed to invest US$500 million in the U.S. over the next few years as it builds the products and operations around that effort.
Conditional OCC approval is a major regulatory step, but it is not permission to open the bank tomorrow. Revolut still needs FDIC approval for deposit insurance, Federal Reserve approvals for its U.S. holding structure and final OCC clearance. The company also has to finish staffing, capitalization, technology, compliance and operational testing before customers can be moved onto the new bank.
Owning a bank also changes the risk Revolut takes on. A partner bank carries much of the regulated balance sheet today. Revolut Bank US would have to manage its own capital, liquidity, credit losses, consumer compliance, BSA and AML controls, cybersecurity, governance and federal examinations.
Lending makes that especially real. A payments app can process money without taking the same credit risk as a bank making personal or business loans. Once Revolut starts lending from its own balance sheet, growth has to be backed by sound underwriting, reserves, collections and enough capital to absorb losses when borrowers struggle.
The company is already building that structure though. Its application calls for a separate U.S. bank board and senior executives responsible for finance, risk, compliance, legal, lending and operations. Revolut says it remains on track for 2027, but the launch date still depends on regulators being satisfied that the bank is ready to operate safely.
Revolut's first Canadian attempt ended very differently. The company launched a limited beta in 2019 and left Canada in 2021 without establishing a domestic bank. The earlier product was much narrower than the banking business Revolut now operates in several markets.
Jan Pilbauer now leads Revolut Canada, and Revolut has described the market as attractive, but there is still no announced launch date or public Canadian bank licence application. A U.S. national bank charter certainly doesn't give Revolut permission to take deposits or operate a bank in Canada.
If Revolut does return, it would arrive as a much larger and more regulated company than the one that left five years ago. It now operates licensed banks in multiple countries, carries a growing lending book and is building local banking operations rather than relying only on cards and foreign exchange. Canada has also changed, with OSFI's streamlined approvals framework giving eligible new entrants a clearer federal application process.
None of that means a Canadian relaunch is close. It does mean the next attempt, if it happens, could look much more like a full digital bank than the limited product Revolut tested here before.
Revolut is now trying to do something large fintechs often avoid for as long as they can it seems. That is to own a regulated bank, the deposits, the lending and more of the customer economics. That can produce more revenue and more control, but it also means the compliance failures, credit losses and funding mistakes belong to Revolut too.
How much more can Revolut earn when it owns the bank behind the app?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016