




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 4, 2026 | NCFA Fintech Insight | Digital Assets Blockchain And Tokenization

On Apr 29, 2026, NCFA published a resource post on crypto adoption data across 11 European markets, based on the ARI10 Report Cryptocurrency Adoption in Europe 2026. The data points to a market that's moved past early awareness but hasn’t yet settled into consistent daily use just yet. That gap is where the next phase of competition starts.
The study surveyed 11,068 respondents across 11 countries between Jan 9 and Jan 15, 2026:
Roughly four in ten respondents have already researched, owned, or traded crypto. Just over three in ten qualify as investors. People know what crypto is, and many have already touched it. Crypto is by far no longer fringe.
However, Poland’s 47.10% exposure rate and France’s 30.41% rate describe very different market conditions. Norway, Spain, and Romania also show stronger engagement than the overall average. For operators, that means Europe has different adoption curves. It breaks into local markets depending on income, education, age, product trust, and financial habits.
Single broad brushed strategies may miss the mark. A wallet, exchange, payment product, or tokenized asset platform needs to match how users actually behave in each market, not how the regional average looks in a slide deck.
Investors still participate primarily for financial gains. Nearly half point to potential value growth, and more than two thirds cite financial motives overall. That makes crypto adoption look less like daily payment adoption and more like investment market participation.
This actually strengthens the crypto infrastructure story. Exchanges, custodians, payment firms, banks, and tokenization platforms keep investing because they’re trying to move crypto from access to daily utility. But user behaviour still leans toward buying, holding, and trading. The next stage of growth and adoption depends on how useful crypto becomes inside regular financial workflows, not just easier to purchase.
Risk and volatility rank at 33.3%. Lack of funds follows at 32.1%. Technical knowledge comes in at 31%. Lack of trust in exchanges reaches 28.6%. Regulatory uncertainty ranks much lower at 9.3%.
Regulation supports trust and scale, especially for institutions. But regulation alone doesn't turn interest into everyday use. Users need clearer entry points, better risk explanations, stronger platform trust, and products that make participating in crypto feel normal and useful.
This is where the current market opportunity is in Europe. Not in chasing generic adoption, but by turning curiosity into confidence, and confidence into repeat and useful behaviour.
Crypto adoption has reached a point where awareness and regulation are no longer the main constraints (at least in Europe and based on this study). The next iteration depends on whether the industry can turn interest into trusted, useful, everyday financial behaviour. Access the full report on Crypto adoption in Europe
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 4, 2026
Image: Unsplash/Tech Daily
The crypto market is characterized by fast changes in the value of currency, which at times can be extremely favorable but at other times creating disastrous effects. Different from the stock market, the prices of cryptocurrencies often react more quickly to events, changes in the mood of investors, and global economic factors. For those just starting out, this constant fluctuation may seem chaotic but for ones who have been trading for a while, volatility is the element which makes their trading plans workable.
A lot of new investors that want to work with crypto prop trading make their first experience which leads them to the realization that volatility is not a monster to be chased away but the fact that should be looked in the eye. Firstly, before learning how to open a trading account with a crypto prop firm or how to make a start in crypto prop trading, you have to realize why the prices of the markets swing so wildly in one direction and how the traders can exercise self control in dealing with the reactions instead of letting their feelings take the lead.
The term market volatility is generally used to describe the velocity and the extent of the changes in the price of an asset happening in such a short period of time that many holders hardly notice them. In crypto trading, however, a single minute may be sufficient to witness sudden and significant price changes.
There are many reasons why there can be dramatic upward and downward price swings for cryptocurrencies such as Bitcoin and Ethereum including fluctuating investor demand, regulatory developments, influence of social media or massive purchasing by institutions.
On the one hand, operating in highly volatile conditions provides opportunities to gain whereas on the other hand, it significantly increases the risk hitters may suffer losses without proper preparedness.
There are a few reasons why crypto markets are much more volatile than other markets like stocks or forex.
Compared with the stock market and other investments, the crypto market is still immature. Besides being less regulated, this market has fewer large players and this results in stronger reactions to both genuine information and hearsay.
Due to the fact that stock exchanges are not operating around the clock, the prices of stocks are settled at the end of the trading day whereas in the crypto world, things are different as the market is always open and prices are changing even during the night, including weekends and holidays when the number of active participants is lower. This continuous activity is responsible for the building up of trading momentum and many cases where a quick change of direction happens.
The price of cryptocurrencies could very well be affected by a simple tweet from a leading figure in the industry, tip off news from a crypto exchange or an announcement by a government official regarding a change in regulations. There is a good chance that if these events are accompanied by an emotional reaction of the market, prices would move even more drastically.
Traders who master knowledge of volatility are less likely to make emotional mistakes and they can scale back their risk accordingly.
The higher the volatility in the market, the more frequent are the unexpected price changes. Hence, it is crucial for traders to fix their stop loss points way ahead to keep their money safe.
This is doubly true for crypto prop traders as the risk management rules are usually quite strict.
Taking a large position in a very volatile market can be a recipe for a huge loss. By opting for smaller positions, traders equip themselves better to withstand unanticipated market moves and maintain consistency in their trading.
It would be unrealistic to expect every one of price fluctuations to indicate a trading opportunity. By holding on for a signal instead of recklessly following price moves, one can steer clear of poor entries that are elicited by fear or greed.
While a lot of traders looking for crypto prop trading firms with the best terms are mostly concerned with getting capital, managing volatility is just as critical.
A prop firm that instantaneously funds trades could be giving the trader quick access to significantly bigger account size, however, when it comes to fast market moves, without having the right mindset in place, rapid losses can occur. Volume based traders often underperform those who develop a deep understanding of price action and trade on the basis of well informed decisions.
When you get into crypto prop trading, it is wise to research volatility in addition to technical analysis. Being a keen observer of the market trades helps in making better choices over time.
Professional traders use fixed habits that help them stay calm even in the face of strong price changes.
With a written game plan in hand, it is easier to keep one's feelings in check. Prior to the trade, all the decisions on entry, exit, and risk allocation should be made.
Whenever a trader feels panicky after reading news, it is usually a sign of poor timing. It is a good policy to always crosscheck facts and refrain from indulging in the frenzy aspect of the market until there is confirmation.
Investing all of one's capital into one type of asset is just asking for trouble. Allocating funds across an array of different assets is a good way to mitigate risks due to sudden events in the market.
Keeping a log of one's triumphs and failures, as well as emotional judgments, is a good way to formulate improvements. The ability to stick to one's game plan and stay consistent are far more valuable than one isolated, flawless trade.
The thing is, volatility itself is not good or bad it's through volatility that both opportunities and risks arise.
Bitcoin remains priced according to demand, large investors, governmental and media announcements, and the overall mood of market participants. And since it's always open, the market price can change rapidly.
Yes but only if they follow safe rules. Starting with small trades, using stop loss orders, and staying away from impulsive decisions are some of the ways to be on the safe side.
Since significant price movements could result in rule violations or losing the account more quickly than expected, funded traders need to be very cautious in their risk management.
Volatility remains a major characteristic of cryptocurrency trading, and those able to turn it into a feature can become even stronger investors. Rather than viewing the sudden price changes as a disaster, clever traders analyse the trends, manage the risks, and remain calm in the face of pressure.
Trading on one's own account or funded accounts, success comes more from being prepared than guessing. While the crypto market is bound to keep moving quickly, well disciplined traders who have a good understanding of volatility will be the ones best able to navigate the future.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 4, 2026
The ability to hire the best available talent regardless of geography has become a baseline expectation for competitive companies. Engineering teams, creative departments, and commercial roles are increasingly filled by professionals located in countries where the hiring company has no operational presence. The problem is not identifying those candidates; it is employing them legally. Establishing a local legal entity in a foreign market typically takes three to six months, requires ongoing administrative maintenance, and creates permanent compliance obligations that are difficult to unwind if the market does not develop as planned.
For companies that need to hire now rather than after completing a multi-month incorporation process, this gap between hiring intent and legal readiness represents a real cost, in delayed product development, lost candidates, and competitive disadvantage. That's why global EOR services have moved from a niche HR solution to a standard tool in the international workforce strategy of companies across sectors.
An employer of record (EOR) is a third-party company that legally employs workers on behalf of a client organization in a foreign jurisdiction. The EOR holds the employment contract, processes payroll, withholds taxes, administers benefits, and maintains compliance with local labor law. The client company directs the employee's work on a day-to-day basis, while the EOR carries the legal employer liability in the local market.
Global EOR services extend this model across multiple countries simultaneously. In other words, a single provider can serve as the legal employer of record for employees located in dozens of different countries, managing the distinct compliance requirements of each jurisdiction through one coordinated service relationship. Thanks to this, companies can build internationally distributed teams without replicating the legal and HR infrastructure of each target market internally.
This is materially different from working with a staffing agency, which supplies candidates but does not assume ongoing employer liability. It is also distinct from a professional employer organization (PEO), which typically operates as a co-employer in markets where the client already has a legal presence. An EOR operates in markets where the client has no entity at all.
Here's when a global EOR model can enter the game: when the company's hiring needs outpace its legal infrastructure, and the cost or complexity of establishing entities in every relevant market is disproportionate to the hiring volume.
You should attentively analyze whether the following scenarios describe the organization's current situation:
The majority of companies that adopt global EOR services report that the model significantly reduces time-to-hire in new markets and eliminates the compliance overhead that previously made international hiring prohibitively complex for teams without dedicated global HR functions.
Understanding the operational mechanics helps companies set realistic expectations and structure the engagement effectively.
When a company engages an EOR provider, the worker signs an employment contract with the EOR entity in their country. That contract reflects local employment law requirements, including probationary period terms, notice periods, mandatory benefits, and severance entitlements. The client company signs a separate services agreement with the EOR, defining the commercial terms, IP ownership provisions, and the scope of the employer's day-to-day direction of the worker's activities.
The worker operates functionally as a member of the client's team. They follow the client's processes, use the client's tools, and report to the client's management structure. The EOR handles the payroll cycle, tax filings, benefits enrollment, and any HR administrative processes required by local law.
Compliance management is the core value of the EOR model. Labor laws vary significantly across markets, including mandatory minimum wages, statutory leave entitlements, public holiday requirements, employer social security contribution rates, and termination procedure rules. What is also important here is that these regulations change; a provider that was compliant twelve months ago needs ongoing legal monitoring to remain compliant today.
What reliable global EOR services should have from a compliance standpoint:
Modern EOR services are supported by software platforms that consolidate workforce administration across all active countries. These platforms typically cover employee onboarding and document collection, payroll processing and payslip delivery, benefits enrollment and management, time and expense tracking, and reporting dashboards that give HR and finance teams consolidated visibility across markets.
Pay attention to the self-service capabilities available to employees. A well-designed platform allows workers to access their own employment documents, view payroll history, submit expenses, and track leave without routing every request through an HR intermediary. This reduces administrative volume and improves the employee experience for distributed team members.
A large number of companies that engage global EOR services do so initially to regularize an existing contractor workforce. This transition is operationally straightforward when managed systematically.
We recommend completing this process market by market rather than attempting a simultaneous global conversion, which reduces coordination complexity and allows the HR team to verify that each country's transition has been executed correctly before moving to the next.
Not all EOR providers operate with the same model or coverage quality. The most highly demanded options in the enterprise segment typically offer their own in-country legal entities rather than relying entirely on sub-vendor networks, which produces more consistent compliance standards and clearer accountability.
From a financial perspective, pricing structures vary considerably across providers. Per-employee per-month flat fees are the most predictable and easiest to budget. Percentage-of-salary models become significantly more expensive at higher compensation levels, which matters particularly for senior technical and commercial roles. Apart from this, setup fees, country activation fees, and offboarding costs should be evaluated as part of total cost of ownership rather than ignored in favor of the headline monthly rate.
It will be helpful to request references specifically from companies with similar workforce profiles, including comparable team sizes, comparable countries of employment, and comparable roles. An EOR that performs well for a twenty-person team in Western Europe may not have the operational depth to support a two-hundred-person distributed team across Asia-Pacific, Latin America, and Africa simultaneously.
Typical integrations that a mature EOR platform should support include HRIS systems, finance and ERP platforms, expense management tools, and time tracking applications. A platform that cannot connect to the client's existing HR infrastructure will create parallel data workflows that increase reconciliation risk and administrative overhead.
Global EOR services remove the primary operational barrier to international hiring: the requirement to establish a local legal entity before employing anyone in a foreign market. First of all, they allow companies to hire compliantly in new geographies within days rather than months, which translates directly into faster team assembly and competitive advantage in markets where talent is scarce. Secondly, they transfer the ongoing compliance burden of cross-border employment to a specialized provider, freeing internal HR and legal teams to focus on workforce strategy rather than regulatory administration.
The organizations that use this model most effectively treat it as a long-term infrastructure decision rather than a temporary workaround. Selecting a provider with genuine in-country expertise, transparent pricing, and robust technology will determine whether the EOR relationship enables growth or simply adds a new administrative layer.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 29, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech
The ARI10 Cryptocurrency Adoption in Europe 2026 report provides a large scale view of crypto asset exposure, investor behaviour, regulatory concerns, and market confidence across Europe. The study draws on more than 100,000 individual responses from over 11,000 respondents across 11 European countries, including Poland, France, Italy, Germany, the Netherlands, the United Kingdom, Norway, Sweden, Hungary, Romania, and Spain. The study was developed with Dr Grzegorz Sobiecki of the Warsaw School of Economics and conducted by UCE Research.
In practice, this gives fintechs and digital asset firms a clearer view of where crypto adoption sits across European markets. The public findings point to nearly 40% of respondents having some exposure to cryptocurrencies, about 31% actively investing, and more than 56% identifying unclear regulation as a barrier to further adoption. For exchanges, wallets, payment providers, compliance teams, and investor education platforms, the report helps connect adoption demand with trust, regulation, and user experience.
This is most useful for teams that need market level evidence before making product, compliance, or expansion decisions. Crypto exchanges, payment providers, wallets, compliance teams, investors, and policy teams can use it to compare adoption patterns and trust gaps across Europe. Canadian fintechs can also use it as a reference point for how MiCA, consumer confidence, and digital asset infrastructure are influencing user behaviour in a large regulated market.
The strength is scale. This report gives operators data across 11 countries at a time when crypto adoption, regulation, and infrastructure are coming together. Poland’s 47.1% exposure rate shows how far some markets have moved, which makes the country comparisons useful for expansion decisions.
The limits sit in the data. The study covers 11 countries, not the full European market, and relies on survey responses rather than transaction level data. The methodology uses weighting to adjust for sample bias, and the report is produced by ARI10, a digital asset infrastructure provider. Treat it as a strong directional view of market behaviour, not a complete or neutral benchmark.
Launch Article (public summary and report context)
ARI10 Market Summary (key findings and business implications)
Full Report Download (gated access)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 1, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Payments And Market Infrastructure, Regulation And Policy, Capital Markets And Market Infrastructure

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026).
Open banking is moving from policy design into standards governance. The next control point is who sets the technical, data, consent, and implementation standards that banks, fintechs, and payment firms will have to build against.
AI governance is now part of prudential supervision. Banks, insurers, super funds, and vendors need evidence that AI systems can be explained, challenged, monitored, and shut down without breaking critical operations.
Canada is moving financial crime policy closer to the access points where fraud enters the system. Crypto ATMs, MSBs, account funding, and platform coordination now sit inside the same risk conversation. For fintech operators, the message is practical: faster finance needs stronger onboarding, monitoring, reporting, and partner controls. Weak compliance is becoming a market access problem, not just a regulatory issue.
CSA is removing unnecessary personal data from registration filings before the formal rule amendment is complete. Registrants, dealers, advisers, and compliance vendors should update onboarding, change notice, and filing workflows to reduce data collection and privacy risk.
ESG ratings regulation is moving from consultation into reporting design. Data providers, asset managers, platforms, and compliance teams should watch what information the FCA tests now, because today’s pilot data fields can become tomorrow’s supervisory evidence.
Europe’s digital euro case is now less about payment choice and more about infrastructure control. Banks, wallets, processors, and fintechs should watch how legal tender status, offline payments, privacy, and private sector distribution are built into the final framework.
Mercury’s conditional approval shows how fintech infrastructure is moving closer to regulated bank ownership. The test now is execution: capital planning, compliance controls, risk governance, deposit insurance approval, payments operations, and regulator confidence.
Brazil is drawing a clear line inside regulated cross border payment infrastructure. eFX providers get broader investment related use cases, but crypto and stablecoins stay outside the supervised settlement flow between providers and foreign counterparties.
Stablecoin settlement is moving deeper into card network infrastructure. Visa’s multi chain expansion gives issuers and acquirers more settlement options while keeping a global payment network as the common operating layer.
AI commerce is moving beyond card rails into wallets, super apps, banking interfaces, and wearable devices. Payment providers now need agent controls, authentication, settlement, and audit trails built directly into mobile workflows.
Canada is creating a new public capital vehicle that blends nation building, private co investment, and retail participation. For fintechs, dealers, platforms, and wealth firms, the key watch item is the retail product design: distribution, disclosure, capital protection, eligibility, liquidity, and how ordinary Canadians gain access to strategic national investments.
The FCA is trying to reduce friction in UK listings. Issuers, banks, advisers, and research teams should watch this closely because research timing affects IPO execution, investor education, and how competitive London looks beside other listing venues.
The stablecoin yield fight is moving from a hard stop to a narrower fight over rewards design. Stablecoin issuers, exchanges, wallets, and banks should watch whether Congress draws the line around deposit like yield, activity based rewards, and who gets to define the difference.
Tokenized equities are being routed into existing U.S. market structure rather than a parallel venue. That makes the DTC pilot more important: the operating question is no longer whether tokenized securities can trade, but how clearing, settlement, custody, controls, and shareholder rights fit inside the national market system.
Bank led tokenized deposits are moving from experiments toward shared network infrastructure. The signal is not only the technology transfer. It is the bank roster, production launch timing, and push to keep always on settlement inside the regulated deposit perimeter.
Korea is moving bank led stablecoin infrastructure toward cross border distribution and wallet access. Stablecoin providers, banks, and payment firms should watch whether KRW backed settlement becomes a regulated bridge between domestic bank money and global digital commerce.
Simon Walls, Executive Director of Markets, Financial Conduct Authority
“Tokenisation has the potential to play an important role in asset management, and its adoption will be driven by firms and investors. We have focused on delivering what the market has asked for: a clear, practical framework that provides confidence in how fund tokenisation can operate within our rules, both now and into the future.”
Institutional Bitcoin adoption is expanding through public equity as well as direct digital asset holdings. Pension funds, asset managers, banks and capital markets participants should watch whether listed Bitcoin treasury companies become a common route for regulated institutions seeking digital asset exposure within existing investment mandates.
Tokenized equities are moving into the transfer agent layer. That matters because shareholder records, voting, dividends, and issuer controls are the plumbing that separates real tokenized securities from synthetic exposure or offshore wrappers.
Bank issued digital money is moving closer to core banking infrastructure. Lyriq gives banks a way to run tokenized deposit style money flows with controls, auditability, settlement finality, and core integration built in from the start.
Tokenized Treasury funds are moving from passive yield products into active collateral infrastructure. Exchanges, custodians, asset managers, and institutional trading desks now have a working model for combining yield, margin, custody, and counterparty risk controls in one operating stack.
This week is about ownership of core financial infrastructure. Canada introduced a sovereign wealth fund. Fintechs pursued bank charters. Global banks, exchanges, transfer agents, payment networks, and core processors advanced tokenized deposits, fund tokenization, tokenized shares, stablecoin settlement, and AI agent payments. These initiatives are about control: who owns the account, who controls settlement, who keeps custody, who sets the rules, and who earns the economics when financial assets and payments become programmable.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 1, 2026 | NCFA Fintech Market Activity | Risk Compliance And Regtech, Artificial Intelligence And Data
On May 1, 2026, Datavault AI and CyberCatch announce a binding letter of intent for Datavault AI to acquire 100% of CyberCatch in an all stock transaction structured as a court approved plan of arrangement under the Business Corporations Act (British Columbia).
The proposed deal values CyberCatch at about CAD $136.8 million (CAD $5.11 per share). CyberCatch shareholders would hold about 7.52% of the combined company, with Datavault AI shareholders holding about 92.48% on a non fully diluted basis.
CyberCatch CYBE is listed on the TSX Venture Exchange and OTCQB US Venture Market, focuses on continuous compliance and AI driven cyber risk testing. Its platform uses generative AI to assess whether controls are in place, then uses agentic AI to simulate attack scenarios and produce a Cyber Breach Score. The model is built around continuous validation rather than periodic audit cycles.
Timing aligns with rising demand for continuous security assurance. The release cites Gartner estimates that global information security spending will reach $240 billion in 2026, while AI driven security could grow to $160 billion by 2029 (up from $49 billion 2025). IBM’s 2025 Cost of a Data Breach report places the average U.S. breach at $10.22 million and the global average at $4.44 million.
Regulatory pressure is picking up. The U.S. Department of Defense started rolling out its CMMC program on Nov 10, 2025, and stricter certification requirements are expected to expand in 2026 across about 220,000 contractors and suppliers. CyberCatch aligns its platform with widely used standards such as CMMC 2.0, NIST, ISO 27001, HIPAA, and PCI.
There’s also a growing focus on future security risks. As computing power increases, current encryption methods may become easier to break. CyberCatch is working on quantum resistant encryption, and signs like Google’s 2029 timeline for upgrading its systems show that companies are starting to prepare now.
Nathaniel T. Bradley, CEO, Datavault AI:
“Cybersecurity is no longer a separate stack from data and AI - it is the precondition for both. CyberCatch's continuous compliance platform is expected to provide another strategic advantage by adding to DataValue®, DataScore®, and the IDE® a real-time risk and compliance signal at every node of our quantum-secured edge fleet, from federal contractors to enterprise data customers.”
For Datavault AI, the transaction adds a compliance layer to its broader data, edge computing, and tokenization infrastructure. The company positions CyberCatch as a way to deliver real time assurance across regulated environments, including fintech, healthcare, energy, and defence.
CyberCatch brings a Canadian public market cybersecurity and regtech platform into a U.S. AI infrastructure strategy.
The transaction is subject to a definitive agreement, due diligence, board approvals, CyberCatch shareholder approval, British Columbia court approval, Nasdaq approval, TSX Venture Exchange approval, and other customary closing conditions. The parties have agreed to a 45 day exclusivity period.
Will continuous, AI driven compliance become a required layer for regulated industries, or will firms continue relying on periodic audits that do not reflect real time risk?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 1, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, Regulation And Policy
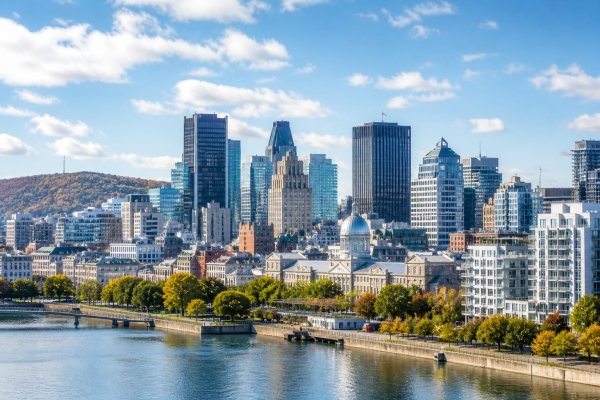
On Apr 29, 2026, Canada confirmed progress on the Defence, Security and Resilience Bank after multilateral negotiations in Montréal concluded on the proposed charter. Participating countries unanimously support Canada as host country for the future headquarters once the institution is ratified.
The initiative isn't a bank yet but it's making progress. Ratification, capital commitments, governance design, and member alignment is still ahead. But the structure already points to something bigger. It brings sovereign credit, bank balance sheets, defence procurement, SME finance, and private capital into one coordinated financing layer.
The DSRB aims to deliver long term, low cost financing for defence, security, and resilience projects across supply chains. Finance Canada says the focus includes small and medium sized enterprises and member governments that face real financing gaps. The model itself relies on targeted guarantees and risk assessments to reduce investment risk in defence and dual use sectors.
That changes how capital flows. Instead of direct public spending alone, the DBSR bank lowers financing risk. Member countries provide credibility. Commercial banks and capital markets can then lend or invest with stronger protection than they would normally have on their own.
Canada’s upside goes beyond hosting. It pulls the country into how this system actually runs, from treasury and legal structuring through to risk modelling, credit guarantees, and the financing that supports procurement and supply chains. Earlier provincial bids for the DSRB platform showed that the real competition was never just location. It was influence over how a new allied financing system gets built.
At launch, it runs through banks. They hold the balance sheets, structure the deals, and take the risk. That’s where capital moves. Fintechs shows up behind the curtain. Lenders need to see who they are financing, what risk looks like in real time, and where money should go. That creates room for infrastructure that handles verification, risk signals, payments, and supply chain visibility.
Execution is the real test and Canada's Achilles heel. A headquarters doesn't automatically build capacity. Canada has to connect this bank to procurement, to real companies, and to lenders that will actually deploy capital. SMEs need a clear way in. Banks need line of sight into who they can back. If that clicks, the DSRB does more than fund projects. It turns defence demand into investable flow and pulls private capital into the system. If it does not, it stays concentrated with governments and large contractors.
The real question is not whether Canada hosts the DSRB. It is whether Canadian banks, fintechs, and policymakers turn it into a working capital channel for domestic firms or leave it concentrated with global institutions and large contractors.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016