




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


March 26, 2026

Image: Pixabay/tourque
There has been considerable discussion in recent years about gaming licenses from the Malta Gaming Authority (MGA) and whether they still hold value in an increasingly regulated world. With Canada’s provincial markets moving toward their own regulatory frameworks, some players question whether this license matters anymore. The possibility of more provinces following Ontario’s lead and introducing their own licensing systems has led some to believe that international MGA licenses will soon become unnecessary for Canadian players.
However, the reality is more nuanced. In practice, MGA licensed casinos remain some of the most commonly used and trusted platforms among Canadian players. For those looking into their options, websites like MGAcasinos.ca are dedicated to helping players find the best MGA casino sites in Canada. This website offers a list of online casinos that have a proven track record of player protection, fair gaming standards, and high-quality gaming features.
In this article, we’ll take a closer look at why the MGA license still holds strong value in the Canadian market and why so many players continue to prefer it across Canada.
The MGA is the government body responsible for regulating gambling in Malta. It was established in 2001, and Malta became one of the first countries in the European Union to formally regulate online gaming back in 2004. That head start gave the regulator decades to build out one of the most respected licensing frameworks in the industry.
It operates under Malta’s Gaming Act, which came into full effect in August 2018 after a major overhaul of the country’s gambling laws. Today, it oversees both land-based and online operators, sets the standards they must follow, and has the authority to issue fines, suspend licenses, or cancel them altogether when operators fall short.
What sets the MGA apart from lesser-known licensing bodies is the level of scrutiny involved. Operators must pass background checks, demonstrate financial stability, meet technical requirements, and implement responsible gambling measures before they can receive a license.
Ongoing compliance is expected, not just during the application stage. In practice, this means licenses are not automatically renewed. Recent figures reported by Next.io show that multiple operators applied for renewals, and not all were approved, reflecting the regulator’s continued oversight and willingness to deny extensions where standards are not met.
Canadian players have a lot of options when it comes to online gambling, but MGA licensed casinos consistently stand out. The reasons go beyond simply being internationally licensed. Here’s a clear breakdown of why these platforms are so popular among Canadian players:
Outside Ontario, most Canadian provinces don’t have fully regulated markets for private online casinos. Provincial lottery corporations offer their own platforms, but these options are limited. Additionally, most provinces haven’t established a licensing system for private operators.
As a result, many players turn to internationally licensed sites for more choice and flexibility. This is why Canadian players frequently encounter MGA licensed casinos, as these platforms are widely available and well-established, making them a natural choice for players seeking quality online gaming.
The MGA has been around for many years now and is well known among online casino players in Canada. This long presence has helped build familiarity and trust, so many players already recognise what to expect from it. Because of that, these licensed casinos are often preferred over other jurisdictions, not just for compliance reasons, but because players feel confident using platforms they already know.
Licensed casinos under the MGA have to follow strict player protection rules designed to keep players safe. This includes:
MGA casinos partner with some of the biggest software providers in the industry, including NetEnt, Microgaming, and Evolution Gaming. This means Canadian players have access to thousands of high-quality slot titles, table games, and live dealer experiences. The variety and innovation available at these casinos often surpass what provincial platforms can offer.
Canadian players benefit from a wide range of payment methods at MGA casinos, including:
Withdrawals are often faster, and the variety ensures players can deposit and play in ways that are convenient and secure.
MGA casinos are known for offering competitive welcome bonuses, free spins, cashback, and loyalty programs. Compared to provincial platforms, these promotions are generally more varied, giving players extra value and incentives to try new games.
Many MGA licensed casinos are run by established international brands that seek long-term growth rather than short-term profits. Because the MGA is a highly respected regulator, this attracts reputable companies, which in turn gives Canadian players access to stable, trustworthy platforms. For players, this means these casinos are less likely to disappear suddenly and more likely to offer consistent service, fair games, and reliable payouts over time.
The MGA makes it straightforward to verify whether a casino actually holds a valid license. Here is how to check:
The Malta Gaming Authority has built a reputation as one of the more rigorous online gaming regulators in the world, and that is why Canadian players frequently encounter MGA licensed casinos when looking for options outside provincial platforms.
These casinos offer Canadian players a winning combination of safety, fairness, and variety. With strict regulatory oversight, secure transactions and protections for players, it is no wonder these casinos are so popular. Whether you are a casual gamer or a high-stakes player, exploring MGA licensed platforms can help you find trusted options and enjoy peace of mind while playing.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 26, 2026 | NCFA Fintech Market Activity | Banking And Credit, Digital Assets And Tokenization
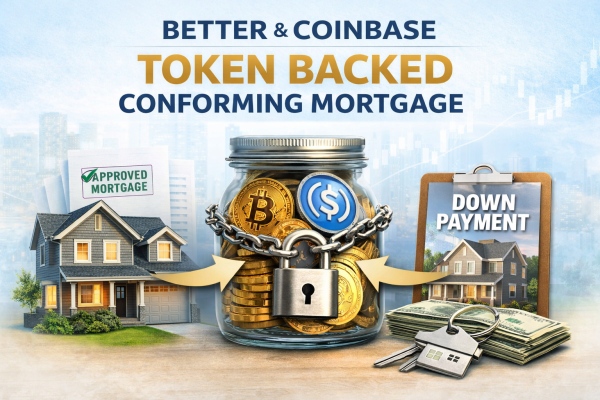
On March 26, 2026, Better and Coinbase launched the first token backed conforming mortgage. Qualified borrowers can pledge Bitcoin or USDC to fund a cash down payment while still taking out a standard mortgage that meets Fannie Mae rules. The structure lets borrowers use digital assets without selling them first and without automatically triggering a taxable sale event.
The product targets a large and growing borrower base. Better and Coinbase put the addressable market at 52 million Americans who own digital assets, equal to 20% of American adults. They also mention quite an age split, with 45% of younger investors holding crypto versus 18% of older investors. That age gap means it's much harder for younger buyers to meet traditional down payment cash requirements, yet many already hold part of their savings in digital assets.
There are no margin calls and no required top ups if Bitcoin falls in value. Price moves alone do not trigger liquidation. Collateral comes into play only if a borrower becomes 60 days delinquent, under the same treatment applied to standard conforming mortgages. Borrowers using USDC can also earn rewards on pledged balances, which may offset mortgage payments and lower the net effective rate.
The buyer profile is also broader than a luxury crypto niche. Better and Coinbase said 67% of token holders are 45 or younger and 26% earn less than US $75,000 a year. They also pointed to Redfin data showing 12.7% of Gen Z and Millennial homebuyers have already sold tokenized assets to fund a down payment, versus 3.5% of Gen X and 0.5% of Baby Boomers.
Digital assets are now included in standard mortgage structure, not just a trading or investment account. Token holdings now help fund a conforming mortgage down payment without forcing a sale first. As this model grows, digital assets will look less like something borrowers need to liquidate and more like collateral lenders may be willing to work with.
Better and Coinbase also plan to expand eligible collateral over time to include tokenized equities, fixed income, and tokenized real estate assets. If that happens, the story will not stop at mortgages. It will continue to proliferate into which consumer lending products can absorb token backed collateral and under what terms.
If digital assets can now help fund a conforming mortgage, which standard lending products could be next to accept token backed collateral?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 25, 2026 | NCFA Fintech Market Activity | Digital Assets And Tokenization
On March 25, 2026, BitGo added qualified custody support for USDCx and cBTC on the Canton Network. This expands its role on Canton beyond Canton Coin and into CIP-56 assets, the token format Canton uses for regulated financial markets.
The CIP-56 token standard supports private transactions, built in KYC and AML controls, delivery versus payment settlement, and final settlement within seconds. Those features give institutions the controls they need to use tokenized assets in real collateral and settlement workflows.
Canton describes itself as a privacy enabled blockchain network for institutional assets, with about 600 validators live and more than 15 million monthly transactions using Canton Coin in their flows. That's why BitGo's expansion is interesting because it plugs additional assets into a network that's already being built for regulated financial activity, not retail token trading.
USDCx already serves as the settlement currency for out of hours repo settlement and tokenized collateral workflows on Canton. It is issued through Circle’s xReserve framework. cBTC adds bitcoin backed liquidity to the same environment, giving firms another asset they can use across collateral and settlement activity. This isn't just broader token support. It makes the settlement layer more usable.
Qualified custody for Canton Coin launched in October 2025, and token support followed in less than six months. The work is no longer just about putting assets onchain. It is about building the custody, collateral, and settlement stack that institutions need around them.
Canton is also drawing in more institutional infrastructure, including tokenized money market fund infrastructure from Goldman Sachs and BNY. This BitGo move adds another piece to the same buildout. If tokenized finance is going to work at scale, firms need more than issuance. They need custody that institutions trust, settlement assets they can use, and compliant rails that hold up under real volume. That's where commercial value is starting to concentrate.
As tokenized markets add stablecoin settlement, bitcoin backed liquidity, and qualified custody, which firms become hardest to replace?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 25, 2026 | NCFA Insight | Regulation And Policy, Capital Markets And Market Infrastructure
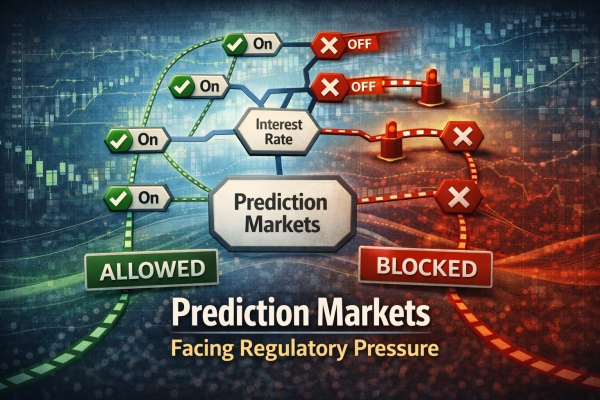
Sports volume built the business. Now rules, surveillance, and product limits will decide who lasts. On March 23, 2026, a bipartisan Senate bill moved to ban sports and casino style contracts on CFTC registered prediction market venues. The Senate release said a March Madness winner contract had already passed $100M in trading volume and that Super Bowl prediction market volume topped $1B in 2026.
Those numbers explain why prediction markets are now under direct pressure from lawmakers. Prediction markets are no longer fringe. They now sit in a fight over who regulates them, which contracts stay allowed, and whether the business still works under tighter rules.
Sports helped prediction markets reach a wide audience fast, but that same growth put them in direct competition with state regulated sportsbooks and tribal gaming interests. The Prediction Market Senate bill to ban sports contracts is aimed straight at that overlap. It would prohibit any CFTC registered entity from listing contracts that closely resemble a sports bet or a casino style game. If it advances, sports contracts would be the first part of the business to take a hit. That in itself wouldn't kill prediction markets, but it would force a reset around contracts that look more like economic, financial, or commercial forecasting and less like entertainment wagering.
Sports contracts brought scale, attention, and league partnerships. NCFA looked at that earlier when the NHL partnered with Kalshi and Polymarket. Sports now look like the part of the business most likely to trigger a stronger federal and state response.
Polymarket and Kalshi tightened their controls on the same day. On March 23, Polymarket tightened its market integrity rules across both its DeFi venue and its CFTC regulated US exchange. The updated rules ban trading on stolen confidential information, illegal tips, and outcomes a trader can influence.
Kalshi added candidate and athlete trading bans covering political candidates, athletes, referees, coaches, and team staff, and introduced a whistleblower feature to tighten insider risk controls.
These aren't minor changes. They prove Kalshi and Polymarket understand that insider risk is now a live issue. Prediction markets want to be treated as financial infrastructure, but financial infrastructure has to show it can police insiders, document rules, and respond fast when abuse appears. NCFA covered that tension earlier when prediction markets started pricing geopolitical events.
Canada is taking a narrower approach. The Globe and Mail reported today that Wealthsimple cleared a regulatory hurdle to offer forecast contracts in Canada, but only for economic indicators, financial markets, and climate trends. Sports and election contracts are out. Wealthsimple is the second firm to receive this approval in Canada, after Interactive Brokers Canada.
Interactive Brokers Canada has positioned contracts around government, economic, finance, and climate events, not sports books in a different wrapper. The product is already live in Canada on that basis.
Wealthsimple now brings local retail distribution, stronger brand reach, and a better chance of testing whether forecast contracts can find a market here without leaning on the sports volume that pushed the US fight into the open.
Can a prediction market still grow once sports contracts face a ban, insider screening gets tighter, and compliance costs rise? Some firms may adapt by leaning into macro, rates, inflation, climate, earnings, and other information markets. Others may find that the most profitable contracts were also the ones most likely to trigger a crackdown.
The CFTC is also reviewing the rules. On March 12 2026, the CFTC opened an Advance Notice of Proposed Rulemaking on prediction markets and asked for public comment on which event contracts may be contrary to the public interest, how current rules apply, and what changes may be needed. That means this fight is not limited to one Senate bill or one week of headlines. The federal rule in the U.S. is now under review.
For Canadian dealers, fintechs, and market operators, there is room to build forecast products here, but the lane is narrower than in the US.
Prediction markets already proved they can attract users and volume. The next test is whether prediction markets can still grow once product limits tighten, regulators draw a harder line around what is allowed, and compliance demands rise.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 26, 2026
Airbnb was founded by Brian Chesky and Joe Gebbia in 2008. They started their business on a shoestring budget, offering air mattresses on the floor for rent during a conference in San Francisco. The pair placed an advert offering a cheap room or ‘bed space’ with breakfast. As a result, they made a decent profit, which allowed them to pay the rent.
Money was needed to maintain the website offering mattresses for overnight stays. At the time, the election campaign was in full swing. The main frontrunners were Barack Obama and John McCain. The budding entrepreneurs bought cheap cereal and boxes and released limited-edition ready-made breakfasts with a personalised number and a high price tag of $40. The cereal cost just $1 per box. Thanks to media coverage and social media, the Obama boxes sold out in three days. The idea brought in $20–30,000.
It was from such a simple idea that the story of a company began, one that is now familiar to literally everyone.
Take a break from work and ideas – have some fun here Voltage Bet - online sportsbook
Oculus was founded in 2012 by Palmer Luckey, who created the first prototype of a virtual reality headset. By the age of 22, he was already worth $500 million. Out of curiosity, he collected a range of outdated virtual reality devices. One day, Laki managed to buy a headset that had once sold for $97,000 for just $87. To expand his collection, Laki taught himself electronics: he bought broken iPhones, repaired them and sold them on at a higher price. That’s how he made $30,000.
These unsuccessful older models became the basis for new developments. Palmer was simply an enthusiastic teenager who loved video games and science fiction films. It was solely through his enthusiasm and passion that the young man was able to create what experienced engineers had been trying to do before him.
Slack was created in 2013 as a tool for internal company communication. Tiny Speck, a company founded by Stewart Butterfield, developed the game Glitch, which flopped. However, in the process, a communication tool was created that became the foundation for Slack. The messenger with advanced functionality was launched in 2014. The platform quickly gained popularity by solving the problem of fragmented workplace communications.
Key factors in its success were word of mouth, an open platform with an API for integrating apps and bots, and a focus on organisational transformation. Slack works with competitors and offers integrations with various services: Google Calendar, Zoom and Microsoft Teams.
The company considers building an ecosystem to be a successful model for growth and meeting user needs. So it turns out that, by solving its own problems and challenges, the team created a service that many companies need.
The brand’s history began in 1965, when its founder, Fred DeLuca, opened a sandwich shop in Connecticut at the age of 17. This was how the future businessman decided to earn money to pay for his medical studies.
Peter Buck, a friend of his father’s, helped Fred open his first eatery, providing $1,000 to develop the business. Fred and Buck became business partners and were ‘fired up’ by the idea of creating a chain of restaurants across the state. DeLuca put his dream of becoming a doctor on hold and began learning the ropes of running a business. It is worth noting that in the early days, Fred made the sandwiches himself and managed to cope with the large flow of customers.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 23, 2026 | NCFA Insight | AI Governance And Data Sovereignty
On March 22, 2026, the Guardian reported that UK Financial Conduct Authority has hired US firm Palantir for a three month trial worth more than £30,000 a week to analyze its intelligence data lake. The reported scope includes highly sensitive material tied to fraud, money laundering, insider trading, case files, suspected wrongdoing reports, and consumer complaints. It's a significant AI governance and privacy risk given that the FCA regulates around 42,000 businesses across the UK's financial ecosystem.
Palantir is a US based data and analytics company that builds software platforms used by governments, intelligence agencies, and financial institutions to organize and analyze large, sensitive datasets. Its systems combine data integration with artificial intelligence and machine learning tools, which allows users to run complex analysis across entire data environments. That capability makes it effective for regulatory and investigative work, and also places it at the centre of ongoing concerns about data access, oversight, and reliance on external vendors in critical public systems.
The FCA has stated that Palantir acts only as a processor, the data stays hosted in the UK, the data cannot be used to train Palantir systems, encryption keys for the most sensitive files stay with the FCA, and the data must be destroyed at the end of the contract. These are all good safeguards but that doesn't end the debate.
The real question is whether a regulator should give a foreign AI operator working access to one of its most sensitive data environments.
The FCA wants better tools to detect financial crime across a very large supervisory perimeter. However, the concern is that once a foreign vendor obtains access to a highly sensitive operating environment, the public risk grows beyond just legal ownership of the data. What happens if controls fail beyond what the contract itself governs?
If a system ingests more than expected, if metadata creates a wider intelligence layer than planned, if privileges become too powerful, or if future use expands beyond the original trial, the exposure can widen even when formal safeguards remain in place. While none of this proves failure it does highlight why sensitive AI contracts and said deployments need much closer scrutiny than standard software procurement.
The trial is short, the weekly cost is disclosed in reporting, the data environment is sensitive, and the FCA says it has placed strict limits on processor role, hosting, training use, encryption control, and deletion. A second report on the FCA Planatir deal indicates the trial is designed to test whether advanced analytics an improve fraud detection, AML/KYC procedures, and insider training within the scope of firms the FCA supervised. But most already concur that AI, if given enough data, can perform small miracles compared to current data tools.
So the harder policy question becomes are the current safeguards enough when the downside of failure is so high, and the data risk in question is a primary financial services regulator, and not a low sensitivity pilot?
Many jurisdictions now rely on a small number of leading foreign AI and cloud firms to quickly integrate, operate, and scale advanced systems. Once workflows, analytics, procurement, and staff capability start to rest on a handful of outside platforms, exiting becomes more difficult due to dependence.
A country can keep data local and still lose practical control if key capability depends on foreign firms for models, compute, software layers, and operational support. This is why the question is bigger than privacy alone. It reaches into resilience, sovereignty, and the future of digital public infrastructure.
Europe is addressing this problem with both law and capacity. The EU AI Act already sets binding rules for higher risk AI use, while the EU’s wider strategy ties AI policy to competitiveness and technological sovereignty. The question in Europe is no longer whether to regulate AI. It is how to enforce those rules while building enough domestic capacity to avoid overdependence on foreign providers.
Canada isn't yet at Europe’s stage. Ottawa still leans on privacy law, sector rules, and evolving AI policy rather than a fully enacted economy wide AI framework. It is progressing more directly on capability, though. The Canadian Sovereign AI Compute Strategy makes clear that domestic control over compute and data infrastructure is a matter of national security and economic resilience issue, not only an industry growth objective.
That concern is already visible in Canadian data. In Canada AI Strategy Confronts Capital Flight, federal consultation inputs point to risks around sovereign capital, procurement, domestic IP retention, and keeping more AI value inside Canada. Also, the acceleration of AI deployments is exposing AI Governance Gaps that many legal experts have flagged.
The FCA Planatir contact creates at least five questions Canadian policymakers should ask early.
The AI race isn't just about who deploys and adopts first. It's also about who keeps control over sensitive data, institutional leverage, and critical digital infrastructure while deploying.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 23, 2026 | NCFA Insight | AI Policy And Regulation
On Mar 20 2026, the White House released a national AI policy framework and legislative recommendations that asks Congress to build a single federal approach to AI and limit conflicting state laws. Washington looks to reduce regulatory fragmentation before state level AI rules harden into a patchwork. The framework isn't law but a blueprint for Congress to show where U.S. AI policy is heading and what type of rules the White House thinks are needed to support large scale use of artificial intelligence across the economy.
The document argues that state by state AI rules can impose uneven burdens on firms trying to build and deploy AI systems nationally. The White House position is that Congress should set the main framework and stop conflicting state rules from slowing deployment. At this point, it's less about creating a new AI regulator and more about stopping fifty different rulebooks from becoming the default U.S. model.
The framework highlights six areas: child protection, energy and electricity costs, intellectual property, free expression, public education and workforce readiness, and maintaining U.S. leadership in AI.
Policymakers want to lower friction for deployment while demonstrating that safety and public concerns are still being addressed. It's a delicate balance because it tells the market what the White House sees as the main tradeoff. The focus is not on building a heavy new AI rule set, but rather on enabling scale, lowering infrastructure bottlenecks, and avoiding fragmented oversight.
AI is already proliferating across lending, fraud detection, compliance, payments, customer operations, and model driven decisioning. A patchwork of state by state compliance would raise cost, slow deployment, and make national rollout harder for both incumbents and startups.
A single federal framework wouldn't solve every issue. Questions around accountability, model assurance, liability, and sector specific supervision would still remain. But it would remove a major barrier by making it easier to roll out AI across the United States.
The U.S. approach is mainly about fragmentation. The White House wants one national frame instead of competing state level rules.
The UK conversation is more operational. The FCA’s Mills Review asks how AI could impact retail financial services through 2030 and beyond. Industry responses focus more directly on deployment barriers inside finance, including data access, Digital ID, payments infrastructure, and rulebook friction.
Canada is taking a broader path. The federal government’s AI strategy process gathered input from more than 11,000 Canadians and 28 task force members, with stronger emphasis on trust, safety, responsible adoption, and national direction. NCFA has already flagged the execution risk in this approach in its analysis of Canada’s AI strategy and capital flight risk.
The difference is important. The U.S. is trying to stop fragmentation. The UK is pressing on execution barriers. Canada is still nuturing national direction. Each approach points to a different policy priority and will result in a different speed of deployment and potential competitive advantage (or disadvantage).
Jurisdictions that reduce friction and create usable operating environments will attract more investment, deployment, and talent. Jurisdictions that let regulatory complexity pile up will throttle adoption even when the technology is ready.
The White House's AI policy framework makes the federal direction clearer. The U.S. is trying to stop state level fragmentation before it becomes the default AI regime. It's important for fintechs and financial services because the level of scale, cost, and deployment speed depends heavily on whether one federal rulebook replaces fifty competing ones.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016