




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


March 20, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Regulation And Policy, Payments And Market Infrastructure

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026).
This adds a new regulated counterparty node for banks, payment partners, and fintech vendors that use CIRO membership as a gating factor for onboarding, integrations, and supervised operating scope.
This puts fund distribution onchain with rules built into the asset. Transfers can enforce who can hold and trade without separate manual checks. That changes how funds issue, manage investors, and handle transfers. It points to tokenized fund infrastructure moving into live use, not pilots.
This affects crypto trading platforms, market makers, treasury teams, and regulators watching stablecoin market structure in Canada. Lower margin on eligible inventory can improve capital efficiency and balance sheet use, but only inside a tighter control framework. It means regulated treatment of stablecoins is moving deeper into prudential design, not just disclosure and registration.
A core global index now trades outside exchange hours. Price formation can start on crypto venues before futures markets reopen, which puts pressure on where liquidity shows up first. If activity builds on chain, traditional venues risk reacting instead of leading. For brokerages, exchanges, and market infrastructure providers, this is not theoretical. Firms need to decide whether to support 24/7 access, how to manage risk when markets never close, and how to compete with venues that remove time and geographic limits.
Crypto issuers, exchanges, custodians, brokers, investors, and token builders now have a clearer US reference point for token design, disclosures, and jurisdiction planning. The practical implication is significant. Firms exposed to staking, airdrops, wrapped assets, stablecoins, or token distribution models can reassess compliance, product structure, and market access strategy with more precision across SEC and CFTC lines.
This is for banks, lenders, treasury teams, and fintechs that rely on bank balance sheets and bank distribution. Capital rules affect lending capacity, pricing, and risk appetite. A lighter or more targeted framework can change how banks allocate capital and where they are willing to compete.
Banks facing margin pressure, conduct costs, and weak returns are under more pressure to lower their operating base faster. The practical implication for lenders, fintechs, and banking vendors is that AI and automation are moving from pilot projects into cost and staffing decisions. Firms that can automate servicing, operations, and control workflows without weakening customer outcomes or compliance will be in a stronger position.
This gives UK facing fintechs and suppliers a cleaner map of where supervisors focus and where firms should spend compliance and product time. Payments, retail banking, consumer finance, and wholesale market firms can now align internal control roadmaps to sector specific priorities instead of broad portfolio letters, which tightens how boards and senior managers justify investment decisions.
Federal procurement remains difficult for new entrants to access, with complexity and restrictive design favouring repeat suppliers. At the same time, the report outlines clear changes that could open participation, improve competition, and expand access for fintech, govtech, and smaller vendors seeking to sell into government.
China is widening the distribution base for state digital money inside the banking system. Analysts see the bigger role in cross-border settlement and in building a payments channel that's outside dollar-based infrastructure such as SWIFT. China is pushing public digital money deeper into bank distribution while closing space for private stablecoin models.
This expands direct access for credit unions that want to build or buy modern payment capabilities. Credit unions, processors, and fintech partners can now plan for real system participation, not just eligibility on paper.
This is for banks, cross-border payment firms, remittance providers, treasury teams, and stablecoin infrastructure players. Stablecoin payouts are moving closer to standard bank payment flows instead of sitting outside them as a separate integration project. That lowers friction for bank adoption and puts more pressure on legacy cross-border payout models.
Mastercard is building direct control over how funds move between bank accounts and stablecoin systems. That changes routing, pricing, and who captures value in cross border and treasury flows. For fintechs, payment products will increasingly need to support both fiat and digital settlement paths in the same workflow. For banks, this puts more pressure on correspondent banking and other legacy cross border revenue lines.
This changes how investor harm connects to enforcement outcomes. Dealers, registrants, and their vendors now need tighter client records and cleaner evidence trails because the process depends on what harmed investors can prove and what firms can produce quickly and accurately when claims arrive.
This lowers reporting cost and workload for smaller public companies. It changes how often new financial data enters the market. Investors and data platforms will have less frequent updates. For issuers, this improves the economics of staying public. If adopted more widely, it moves Canada toward a lighter reporting model for venture markets.
Industry participants are pushing to remove limits that keep tokenized market infrastructure in pilot mode. That pressure targets how quickly the EU can move from controlled testing toward scalable digital asset markets.
Tokenized securities into the core of exchange trading. They will trade the same way as regular shares, on the same book, with the same symbol and rules. No separate venue, no parallel system. It removes a major barrier with tokenization now aligned with the same clearing, settlement, and surveillance systems as the rest of the market.
A forward flow commitment supports predictable loan takeout capacity, which can stabilize origination volume when bank balance sheets tighten or pricing changes.
Public companies, investors, analysts, and fintech platforms that rely on earnings data will face longer gaps between official disclosures. Less frequent reporting reduces the flow of standardized financial data into the market. Firms that can generate alternative data, continuous signals, and independent performance insight will have an advantage as reliance on scheduled earnings reports declines.
When one of India's largest fintech payments company pauses an IPO, it tells founders, investors, and late stage boards that the public market window remains fragile. That affects valuation expectations, liquidity planning, and timing for other fintech listings.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 19, 2026 | NCFA Feature | AI Finance Policy
On Jan 27 2026, the UK Financial Conduct Authority launched the Mills Review into the long term impact of AI on retail financial services to examine how AI could reshape consumers, firms, markets, and regulation through to 2030. NCFA flagged the review earlier in NCFA Weekly Fintech Intelligence Jan 24-30, 2026.
On Mar 4 2026, Innovate Finance submitted its response to the Mills Review, setting out where the UK fintech industry believes deployment will stall unless policy and infrastructure move faster. The paper cites Bank of England and FCA data showing 75% of firms now use AI, up from 58% in 2022. The issue is no longer whether AI adoption will happen. It is what still blocks firms from using AI inside live financial workflows at scale.
AI is clearly evolving from chatbot assistance to execution at scale. The submission describes AI agentic systems that can act on behalf of users. One example is an AI bot that handles everything from comparing mortgage deals to submitting the application and coordinating with conveyancers under user permission.
The value is no longer only in the model itself (ie. speed, quality, cost, expertise), but rather the full operational chain from customer permission to data access to execution to payment. That's why industry is focused on a stacked layer of tech solutions from Open Finance and Digital ID to payment access and rulebook friction to ensure AI can fully complete financial tasks.
The same logic applies to industry concerns over gatekeepers. As AI agents begin to initiate and route transactions, control moves to the layer that connects the agent to the payment method and the financial product. If that layer becomes concentrated, a small number of providers can influence access, routing, and competition.
The response uses real commercial examples and market data, highlighting that AI in finance is already underwriting, trading, core banking, and compliance.
The next phase isn't whether or not firms can build AI tools. It is whether regulation and infrastructure will allow them to use those tools in broader customer and transaction flows.
The stronger points made is that AI in finance won't scale on model quality alone. It will however scale on the stack around the model. That means smart data, Open Finance, Digital ID, fraud data sharing, wallet infrastructure, and payment access. Without those layers, AI stays stuck in narrow support roles. With them, it can move into lending, advice, payments, and automated execution.
That is why the response is more useful than another generic values and ethics based AI policy statement. It identifies where deployment slows, where control could become concentrated, and what has to move together if the UK wants AI to scale significantly inside financial services.
Canada is also building its next AI strategy. The federal government launched an AI Strategy Task Force in September 2025 as part of a 30 day national sprint, and later said it heard from more than 11,000 Canadians and 28 task force members. The Canadian process is broad. It is focused on national AI leadership, trust, safety, adoption, and public interest.
That broad approach is already raising execution questions. NCFA covered this earlier in its analysis of Canada’s AI strategy and capital flight risk, which argued that deployment, investment, and commercialization need clearer direction.
The UK industry response to the Mills Review is more targeted. It focuses on what is blocking AI deployment inside financial services today. Open Finance, Digital ID, payment access, wallets, third party model assurance, and rulebook friction sit at the center of that response.
Canada is still discussing the national direction of AI while UK fintech industry is already laying out what has to change for AI to work inside live financial workflows. The lesson for Canada is straightforward. AI policy cannot move on its own. Open Finance, Digital ID, wallet policy, payments modernization, and data access frameworks need to move with it or adoption in regulated finance will stay limited.
There is also a market structure lesson. If agent led payments grow, whoever controls the interface between the agent, the wallet, and the payment rail can control distribution. Policymakers who want competition and innovation to hold need to keep that layer open.
The industry response to the Mills Review is not just a call for clearer AI rules. It argues that the next barrier sits outside the model. Data access, identity, payments, and regulatory clarity now decide whether AI in finance stays at the support layer or moves into execution. The firms and jurisdictions that solve those bottlenecks will have the advantage.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 19, 2026 | NCFA Market Activity | Digital Assets
On Mar 18, 2026, licensed S&P 500 perpetual trading went live on Hyperliquid through Trade[XYZ]. The product gives eligible non US investors 24/7 access to leveraged long or short S&P 500 exposure without expiry. A core global equity benchmark now trades onchain 24/7.
S&P says its linked ecosystem drives $1T daily trading across futures, options, ETFs, and structured products. Moving that benchmark into a perpetual format allows liquidity to form before traditional sessions open. Early demand for the product already looks real. Decrypt reported $10M open interest shortly after launch, while S&P’s release says Trade[XYZ] markets on Hyperliquid have already cleared $100B volume since October 2025 and are running at more than $600B annualized.
Price discovery no longer has to wait for markets to open. If more benchmark trading starts off hours on crypto venues, traditional exchanges risk following market moves instead of leading them. Even a modest change in where liquidity shows up first can change how volatility spreads across markets.
Investors now have a route to benchmark exposure at any hour, across borders, on a venue built for continuous trading. That changes expectations around access, monitoring, and response time for exchanges, brokerages, data analytics and risk teams. It also raises risk with reports that the product can offer leverage up to 50 times, which means off hours trading can bring sharper liquidations and sweeping moves when order books are thin.
The global implication is bigger than one listing. A major index owner has opened a new channel for benchmark access on chain. That puts pressure on incumbents that still depend on fixed sessions, regional access, and legacy infrastructure. If this model gains traction, exchanges will need to defend their role not just on liquidity depth, but on speed, availability, and product reach.
Canadian fintechs, dealers, market infrastructure firms, and regulators should pay attention to how benchmark access is changing. If clients start expecting round the clock exposure and faster market response, organizations that stay tied to old windows may lose ground. Firms that build around new access patterns, stronger risk tools, and better market visibility will have a chance to capture more of the next layer.
This is not just a crypto wrapper on a known index. It is an early sign that benchmark distribution is starting to move onto new rails. The firms that adapt early can help shape where liquidity, data, and customer activity go next.
The next phase will depend on where liquidity builds and how quickly institutions respond. If trading depth increases on these venues, more benchmarks, sectors, and asset classes will follow into perpetual formats. That would push exchanges, clearing systems, and regulators to respond to a market that no longer operates in sessions. However, if liquidity remains thin, these products will stay a niche trading layer. The open question is how fast global capital markets will adjust to always on access?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 19, 2026 | NCFA Fintech Market Activity | Payments Operations And AI
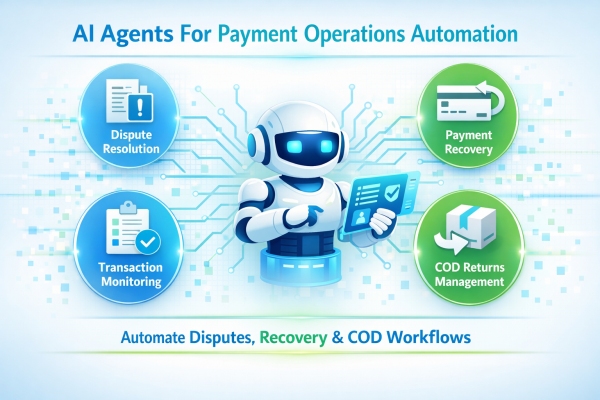
On Mar 12 2026, Razorpay launched Agent Studio, a product it says lets businesses build and run AI agents across payment and post payment workflows. Razorpay says the system is built on Anthropic’s Claude Agent SDK.
Based in Bengaluru, India, Razorpay was founded in 2014 and has grown into one of India’s largest payment platforms. The company says it supports millions of businesses, reaches more than 300 million end consumers, and processes about $180 billion in annualized payment volume. Its stack spans payment acceptance, processing, disbursements, payouts, and business banking through RazorpayX.
Agent Studio targets the operational layer that sits around those flows. In its launch post, Razorpay lists agents for dispute response, subscription recovery, abandoned cart follow up through WhatsApp or email, settlement summaries delivered through messaging, and cashflow forecasting over a 3 to 7 day window. It also includes tools for cash on delivery orders, such as identifying and analyzing returns sent back to the seller.
These workflows cost merchants and payment teams money every day. Disputes create losses and take time to resolve. Failed recurring payments reduce revenue. Abandoned carts lower completed purchases. Cash on delivery returns add shipping and handling costs. Razorpay is building automation around these problem areas, not just the payment itself.
The company is also introducing a no code agent builder in beta and plans to open the system to third party agents. That points to a setup where merchants choose automation for specific tasks across the payment lifecycle, instead of relying only on bundled platform features.
This extends Razorpay’s recent work on AI driven payments, including its earlier work with NPCI on agentic payments to enable AI driven transaction flows. The focus now moves to what happens after a payment, where recovery, customer support, and problem cases still rely heavily on manual work.
Acceptance rates and pricing are still important for PSPs and merchant platforms. Operational efficiency is becoming part of the core value proposition, especially where it directly improves recovery and reduces cost.
If agents handle disputes, recovery, reporting, and cash on delivery losses, does competition start to favour the provider that cuts the most cost for merchants, not just the one with the lowest processing price?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 19, 2026

For a long time, it was believed in the business world that a leader should project nothing but confidence. Why does this model cease to be effective in IT?
The stereotype of the ‘invulnerable leader’ took shape back in the days of rigid hierarchical structures. In IT projects, everything changes very quickly and there is a great deal of uncertainty — and at this point, such a model becomes detrimental to the business. When a leader tries to appear flawless, they create a distance.
Employees stop raising issues at an early stage, as they fear they will fall short of the ideal that has been set. The manager gets a distorted picture, and for an IT project, this is critical.
The ‘unspoken’ is a void that the brain fills in itself. And it most often fills it with negative thoughts and emotions. If a manager remains silent about difficulties, the team begins to think: ‘There’ll probably be redundancies, the project will be shut down, or the money will run out.’ Anxiety grows, people put less effort into the project, or they resign. Competent openness, on the other hand, fills this void with explanations — and the tension dissipates.
Tired of work and business? Then relax with us and enjoy the thrill – play live social casino games
Won’t admitting vulnerability, such as feeling nervous before an important pitch, undermine the founder’s authority in the eyes of investors?
On the contrary. Investors invest in the founder’s competence. Someone who speaks honestly about risks and their state of mind comes across as someone who is truly in control of the situation. Admitting vulnerability is not a complaint from a weak leader, but a statement of fact. For example, when we were developing Matthew Eat Bot, we openly discussed the challenges of integrating with external APIs with the team. Such honesty shows that we understand the scale of the task and are prepared for it, rather than simply ignoring the obstacles.
It makes the human factor a normal and natural part of the work. If a manager can say, ‘I’m worried about this release,’ then employees are also entitled to be just as honest. At Gratio, this helps to quickly identify any issues. People don’t waste energy pretending to be perfect; they simply do their jobs well. Trust in this context translates into real savings: faster communication and fewer unnecessary costs.
Where is the line between ‘thoughtful openness’ and excessive emotionality, which might scare off partners and investors?
The line lies in the purpose. A leader shares their vulnerabilities not to elicit sympathy, but to create a safe working environment. Openness must be practical: if you’re discussing a problem, immediately show how to solve it, or ask for specific help. This is a working conversation, of which there may be as many as a hundred during the process. The main goal is one: to make the business more sustainable through honest relationships between management and the team.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 18, 2026 | NCFA Fintech Market Activity | Banking Distribution And Market Expansion
On Mar 17 2026, BMO announced a multi year expansion of new financial centers in the United States, adding more than 130 locations in California and about 15 in Arizona over the next five years. BMO already operates more than 220 financial centers in California, so the new build represents growth of more than 50% in that state.
Seven California financial centers are scheduled to open in 2026, with three in Greater Los Angeles, two in the Bay Area, and two in San Diego. In Arizona, the bank plans to expand in Phoenix and Tucson.
BMO is betting on distribution by putting more capital behind in person, advice led banking in high growth U.S. markets at a time when many firms still talk as if digital channels alone will carry the next phase of growth.
BMO describes each new site as a modern financial advice hub covering personal and business banking, commercial banking, and wealth management. It is expanding to deepen relationships, cross sell more products, and win over higher value clients who still want face to face advice for borrowing, business growth, and wealth decisions.
This also shows that branch strategy is splitting by market. Some regions still face access pressure from branch closures, which NCFA has covered in rural cash access, while banks such as BMO are still adding physical advice hubs in faster growing urban markets.
That's the strategic point. Digital tools lower servicing cost, but physical distribution remains important when banks compete for trust, complex financial needs, and local business relationships.
BMO is also signalling confidence in the long term value of U.S. regional expansion. The bank says the new network across California and Arizona is expected to support hundreds of jobs over five years, while also investing in renovations and relocations across its existing footprint.
If TradFi banks invest in physical centers for advice, trust, and higher value relationships in growing urban markets is it because digital banking plus AI services are at risk of missing the mark?
In growth markets, a physical footprint can still be a customer acquisition and advisory asset if the banking experience moves from transaction counter to relationship hub.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 17, 2026 | NCFA Insight | Banking Regulation And Digital Assets

The debate is heating up over crypto and fintech access to US banking infrastructure since actions already taken by the Office of the Comptroller of the Currency (OCC) on Dec 12 2025 to conditionally approve five national trust bank charters for the following crypto firms: First National Digital Currency Bank, Ripple National Trust Bank, BitGo Bank & Trust, Fidelity Digital Assets, and Paxos Trust Company. These charters allow firms to operate under federal oversight for custody and payments without taking deposits.
On Mar 17 2026, the Wall Street Journal reported that regulators are considering expanded crypto bank access, points to further expansion along this path rather than a new standalone rule. The direction is reinforced by guidance such as the OCC bulletin on digital asset and stablecoin activities, which shows regulators are already defining how non traditional firms operate within the federal banking perimeter.
It's significant because national trust charters give firms a way to scale across the US without relying on fragmented state licensing. They provide a regulated path into custody, payments, and fiduciary services under a single federal supervisor, without becoming full service deposit taking banks.
Traditional banking groups are pushing back. In a statement opposing OCC conditional approval of five national trust bank charters, the Bank Policy Institute (BPI) said the decision left “substantial unanswered questions” about how these firms would operate and be supervised. BPI has also filed specific objections to trust charter applications, including its opposition to Connectia Trust’s national trust bank application and its opposition to BitGo Trust’s conversion to a national trust bank.
The concern is regulatory parity. Banks argue that if crypto and fintech firms can access core custody and payments infrastructure through trust charters without taking deposits, they may gain entry to important parts of the banking system without facing the same balance sheet requirements as full service banks. That tension is at the center of the policy debate. Who gets access to regulated infrastructure, and under what conditions.
The US isn't waiting for a new trust charter rule. It's progressing through approvals, guidance, and case by case decisions that give some firms a clearer path into regulated custody, payments, and fiduciary services under federal oversight.
A national trust charter can reduce dependence on fragmented state licensing, improve credibility with institutional partners, and make it easier to build around regulated payment and custody infrastructure. But know that the regulatory bar isn't low. Firms pursuing this path still need strong governance, compliance, risk controls, and operating discipline. Access is possible, but it is conditional.
Canada is taking a different approach. In the US, the trust charter debate is about whether crypto and fintech firms can enter deeper into the banking system through a federal charter pathway. In Canada, the main stablecoin related framework sits inside securities and crypto trading platform oversight, not bank chartering. Canadian regulators use the term value referenced crypto assets (see CSA Staff Notice 21 333) and sets conditions around reserves, disclosure, redemption rights, assurance, and platform controls before these assets can be offered to clients. That means the US debate is mainly about institutional status and access to banking infrastructure, while the Canadian debate is mainly about asset eligibility and client protection on regulated platforms.
In Feb 2026, OSFI announced a targeted fast track approval framework for new entrants that will launch in June 2026 and give eligible applicants a quicker, clearer, and more predictable path into the federal system. The initial scope includes provincial credit unions seeking federal status and firms with technologically innovative or emerging banking models.
The real question is not whether crypto firms become banks. It is whether regulators create a consistent operating standard for firms that want access to core financial infrastructure without becoming full service deposit taking institutions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016