




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


February 20, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Regulation And Policy, Artificial Intelligence And Data, Payments And Money Movement, Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026).
This is a procurement and capital boost for defence not seen in decades. Fintechs that help defence suppliers get paid faster, manage cash under milestone contracts, and prove tight controls on funds and data have a generational opportunity with real distribution next quarter. See defence push: Montreal joins provincial bids for global DSR bank platform
This is a money and proof moment for insurtech. Founders selling automation into carriers and brokers should expect buyers to ask for hard baseline metrics, verified before and after results, and fast integration plans this quarter because the market now funds teams that tie automation to combined ratio math and measurable cost takeout.
The UK is embedding crypto firms inside the existing Financial Services and Markets Act framework used for banks, investment firms, and other regulated financial institutions. Firms will likely need stronger governance, clearer business models, defined senior management accountability, and enough financial resources to pass a full authorisation assessment. This tends to favour well capitalized firms that can build institutional grade compliance and risk management from the start.
Tariff volatility shouldn't come as a surprise to anyone and still important to note that this does not take tariffs off the table. Founders and investors should assume trade cost risk still moves through other statutes and policy tools, so the teams that win next quarter make cash forecasting, FX, and settlement controls easier to run when pricing and demand change overnight.
This locks in the timeline banks plan around. Founders selling credit, underwriting, treasury, capital markets, or risk tooling into federally regulated institutions should expect earlier capital impact questions and tighter evidence requests in the next quarter because partners align product decisions to November 2026 and January 2027 effective dates long before final publication.
BoC's action should put every payments and wallet provider on notice. Partners should ask sharper questions about where customer funds sit, who controls access, how fast you can prove balances, and how you recover when something breaks. Teams that can answer those questions with evidence keep distribution moving when scrutiny rises. Feb 27, 2026 Update: The Bank of Canada issues a revised order that allows XTM to resume retail payment activities under court supervised monitoring (a controlled restart).
This can open practical opportunities into German buyers and programs, but only for teams that can pass strict security and governance reviews. Fintechs using AI should expect tougher diligence on where models run, how data moves, how vendors get controlled, and how incidents get handled. If you can show that evidence quickly, you may shorten procurement cycles and avoid months of back and forth. Large buyers tend to follow the standards governments back when they buy software at scale.
This is how stablecoins get real distribution, through bank grade plumbing that owns the hard parts. The next quarter gets more competitive for cross border payments and FX because buyers will compare everyone against always on settlement plus clean, provable books, not just a faster rail.
This is what a real time payments stack looks like when a credit union commits to execution. Vendors selling into credit unions should plan for tighter requirements on open APIs, core and digital banking integration, automated balancing, and exception handling in the next quarter because buyers now expect one platform to run multiple rails without adding operational headcount.
This partnership puts telecom scale on the same path as regulated payouts. If you want in, plan for a buyer that starts by stress testing your operations, not your pitch. Bring evidence you can trace every $ end to end, spot problems fast, reverse or recover cleanly, and keep service levels steady when volume spikes or fraud pressure rises. The teams that win make risk controls feel invisible to users while giving partners real time confidence that money moves exactly as promised.
Founders selling treasury and payments infrastructure should expect tougher questions on reconciliation, exception handling, and control ownership in the next quarter because a bundled PSP sets a higher baseline for speed and operational calm.
This is a real bridge into institutional credit rails. Founders building crypto credit, collateral, custody, and risk tooling should expect tougher questions next quarter on liquidation rules, collateral segregation, reporting, and investor grade controls, because rated structures pull crypto lending into the same discipline set as mainstream ABS.
This tightens delivery expectations for banks and their vendors. Payments and onboarding fintechs should expect stricter timelines and stronger evidence demands next quarter because partial coverage can trigger enforcement.
This week shows the market continuing to get stricter and more operational. OSFI closes the CAR 2027 consultation and puts bank capital planning on a fixed runway. The Bank of Canada order against XTM puts wallets and payments providers back under a microscope on safeguarding and access controls. Modern Treasury pushes more buyers toward one provider that owns rails, reporting, and controls. Desert Financial’s move into FedNow, RTP, and Visa Direct shows how fast credit unions now expect real time payments to work at scale. mea Platform’s $50M round reinforces that capital still rewards insurance automation when it ties directly to combined ratio math. The PSR fine in the UK makes clear that payments safety controls ship on deadline, or regulators step in.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
February 20, 2026 | NCFA Market Activity | Policy and Regulation
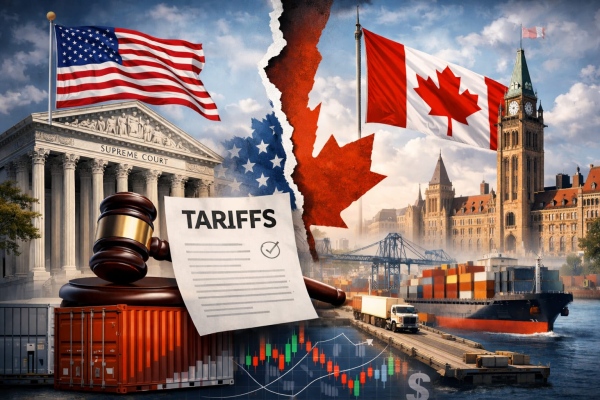
On February 20 2026, the U.S. Supreme Court tariff ruling found President Trump overstepped authority when invoking emergency powers to impose tariffs, delivering a 6 to 3 decision that impacts trade policy expectations across North America.
The ruling removes one of the most aggressive tariff pathways by confirming that emergency powers cannot serve as a broad trade policy tool. However, other legal authorities remain available, meaning tariff risk does not disappear. Policymakers in Ottawa have already begun reviewing the decision’s implications as cross border supply chains remain exposed to policy shifts.
Canada has already experienced tariff volatility during earlier policy cycles. April 2025 tariff impacts on Canadian businesses highlights how sudden trade actions disrupted pricing, inventory planning, and SME financing decisions. Separate analysis of Canada’s tariff trade tensions and economic spillovers shows how cross border friction affects supply chains and investment confidence even when exemptions exist.
The latest ruling may remove one legal foundation for tariffs, but uncertainty remains as governments retain alternative tools. For Canadian exporters and importers, planning risk continues to dominate strategic decision making.
Recent trade data reflects tariff driven disruption across the Canada United States corridor. Statistics Canada indicators show softening export volumes and declining imports during escalation periods, spotlighting how policy uncertainty can translate into pricing pressure, inventory swings, and capital allocation challenges for businesses operating internationally.
If tariff policy remains unpredictable despite judicial limits, will exporters accelerate adoption of embedded treasury, automated FX, and digital trade finance tools as core resilience infrastructure?
Tariffs apply to goods, yet financial effects surface across payments, FX settlement, and liquidity management. Companies facing trade uncertainty typically increase hedging activity, rely more heavily on short term working capital, and demand faster reconciliation to manage cash exposure.
The Supreme Court decision restores an important legal boundary but doesn't end tariff uncertainty. Political pressure around industrial policy and trade protection remains elevated, suggesting continued volatility in cross border commerce.
For Canada’s fintech ecosystem, the news may strengthens the role of fintech platforms focused on cross border payments, FX automation, trade finance digitization, and SME liquidity tools. Firms that help businesses forecast cash flow, manage currency risk, and access capital faster become operational buffers against geopolitical volatility.
You may also like:
Canada Confronts a Changing World at Davos 2026
Does CUSMA Support Fintech Services Across Borders?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 20, 2026 | Global Fintech Funding Research
Image: Freepik
On February 18, 2026, KPMG released Pulse of Fintech H2 2025 reporting global fintech investment reached $116B in 2025, up from $95.5B in 2024, while total deal count fell to 4,719, the lowest level in eight years. That combo tells the real story. More money shows up, but it doesn’t spread out. It stacks into fewer companies, fewer rounds, and more pressure on proof.
KPMG’s regional totals show how concentrated 2025 really was. The Americas pulled in $66.5B across 2,409 deals, with the United States at $56.6B across 1,977 deals. Canada sits inside the Americas corridor where the biggest pools of capital live, but that also means Canadian fintechs compete head to head with scaled US plays for the same investor attention.
The report shows Canadian venture capital fintech investment dropped from $9.9B in 2024 to $2.4B in 2025. A few large late stage rounds can dominate totals in a smaller market, so timing matters. Still, perception isn't great and Canada can’t rely on one breakout year to carry credibility and market confidence.
EMEA recorded $29.2B across 1,484 deals.
ASPAC came in at $9.3B across 763 deals.
Exit value more than doubled to $104.4B in 2025 from $46.8B in 2024, and exit deal count rose to 486 from 438. Stronger exits recycle capital and resets valuation benchmarks. It won’t lift every company but it can improve the mood for 2026 if momentum holds.
KPMG shows payments investment totals $19.2B in 2025 compared with $20.4B in 2024, while deal count falls from 655 to 542. The segment stayed large, but investors picked winners.
The report also flags continued payments traction in emerging markets in H2 2025, with South America standing out, supported by instant payments regimes such as Brazil’s Pix and Argentina’s Transferencias 3.
For Canadian payments firms, this isn’t about chasing every corridor. It’s about owning a clear wedge. If you can show strong fraud outcomes, fast settlement, clean reconciliation, and deep enterprise integration, you stand a chance in a market that rewards proof. If you can’t, you’ll get stuck in the crowded middle.
Digital assets and currencies investment rose from $11.2B across 1,584 deals in 2024 to $19.1B across 1,199 deals in 2025. Dollars r0se while deals fell, which usually means institutions backed fewer, larger infrastructure outcomes. KPMG points to stablecoins, corporate participation, and regulatory clarity as drivers going into 2026. KPMG also highlights growing interest in asset tokenization, including money market funds and real estate.
Canada’s opportunity sits in the infrastructure layer. Regulated custody, compliant settlement, strong controls, and enterprise tokenization tooling can travel across borders. Delays cost builders time, and time costs them market position and money.
Investment in AI driven fintech rose from $12.1B in 2024 to $16.8B in 2025, while deal count rose from 1,183 to 1,334. This is one of the few areas where both dollars and deal flow grew. Still, KPMG notes corporates often partner directly with large tech and AI providers, which raises the bar for specialist fintechs.
Canadian AI fintech teams can’t just say they use AI. They’ve got to show what it changes. Lower fraud losses, faster underwriting, better collections, fewer false positives, and lower service cost. If the numbers don’t move, the story won’t land with investors/buyers.
Insurtech rebounded from $2.9B in 2024 to $8.6B in 2025 while deal volume slipped to a 10 year low of 291 deals. KPMG linked much of the rebound to two outlier transactions, including the $2.6B acquisition of Next Insurance and the $2.5B take private of Sapiens International. That’s the lesson. A handful of transactions can drive the headline while most companies still fight for small checks.
Cybersecurity investment fell to $0.7B in 2025 from $0.9B in 2024, and deal count fell to 72 from 93. At the same time, rapid change driven by AI is increasing the focus on data security because automation depends on trusted data. Banks are consolidating data into protected lakes to support advanced automation and exploring new security models to reduce operating cost while improving outcomes.
This funding dip means larger buyers and platforms are taking more control. Canadian security focused fintechs need to sell enterprise outcomes that tie directly to risk reduction and operational cost.
Regtech investment dropped from $6.8B in 2024 to $4.9B in 2025 while deal count rose from 431 to 519. That pattern often means smaller rounds and cautious checks. The report also describes large banks investing more in internal AI driven compliance tools, which can reduce third party budgets for point solutions.
Canadian regtech firms should focus on selling what banks can’t build quickly, such as shared utilities, cross institution data networks, workflow embedded reporting, and tooling that reduces total compliance cost at scale.
Wealthtech investment fell to $1.4B in 2025 from $4.9B in 2024 while deal count stayed almost flat at 57 in 2025 versus 58 in 2024. KPMG highlights a Canadian bright spot in Wealthsimple who secured about US $538M (CAD $750M) in an equity funding round in H2 2025, and was just awarded CIX Summit's 2026 Innovator of the Year award. That shows global capital still backs Canadian category leaders when they reach scale and earn trust.
Canada faces the challenge of global capital concentrating while Canada’s totals reset from $9.9B to $2.4B. That creates a narrative risk if Canada doesn’t produce repeatable scale outcomes. The upside sits in the same places global capital is leaning into. Payments still attracts large dollars even as investors consolidate. Digital assets funding returns through stablecoins and tokenization infrastructure. AI fintech attracts both dollars and deal flow when it improves real operating results.
Canada needs to stay focused and practical. Build infrastructure grade companies, prove measurable outcomes early, and tie growth to regulated adoption. That’s where the bigger checks go when fewer companies are getting funded.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 20, 2026
Image: Freepik/DC Studio
Along with the rest of the world, Canada's citizens are facing new cybersecurity threats. This can make it hard to feel confident online. The real-world result can lead to financial loss, sensitive data being available to all, and a wider impact on the economy.
Here are some of the issues you could encounter, as well as measures to protect yourself.
One of the newest types of issues is AI-powered scams, or deepfakes. Criminals use AI to create personalized social engineering attacks. This could be in the form of fake videos of celebrities "talking" to you or as a romance scam.
Always verify the person you are speaking to independently, especially if they ask for money or passwords. Remember, celebrities will never do this, so it is an immediate red flag.
Check any videos carefully. If you watch, you will be able to spot weird movements that break the AI illusion, such as words not matching with mouth movements.
Malicious websites are selling compromised credentials such as passwords, user logins and personal information, which can lead to account takeovers.
Avoid your accounts being at risk by manually requesting removal from major broker sites. There are legitimate companies you can pay to do this, as it is time-consuming.
Try to practise good online hygiene. Make sure you have strong passwords that you change regularly. Do not open strange emails, as they could be links to harvest your data. Importantly, if you do think someone has information they shouldn’t, report it to the relevant body in Canada.
As a small to medium-sized business owner, your company is important to your personal life. You may notice that your business is targeted by scammers to gain access to secure networks. This puts any personal data in your care at risk.
Implement rigorous vendor risk management, as well as mapping the supply chain for any vulnerabilities. Make it part of your policy to conduct regular manual checks as well as employ software to monitor your network continuously.
Ransomware remains the top cybersecurity threat. It works by infiltrating your systems and network, rendering your data inaccessible. This enables fewer technical criminals to launch attacks against both individuals and businesses.
Make sure you have system backups offline and regularly check for and apply security patches to all systems. Consider using a VPN free to encrypt your data, making it harder for criminals to access and read.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 19, 2026 | NCFA Fintech Market Activity | CIX Summit
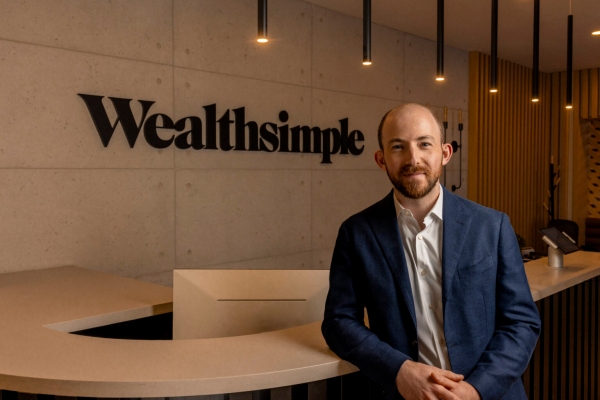
Image: Michael Katchen, Co-founder and CEO, Wealthsimple
On February 19 2026, Elevate named Wealthsimple Innovator of the Year for 2026 CIX Summit, who achieved a banner record year that included assets under administration doubling from $50B to more than $100B, 650,000 new clients, and more than 3 million Canadians served.
The release ties the award to three proof points that matter for founders and investors who care about durable scale.
First, it says Wealthsimple raised $750M in equity financing at a $10B post money valuation in October 2025 while maintaining profitability.
Second, it highlighted product expansion that moved beyond a single wedge, including 24/5 trading for US stocks, new trading tools including margin and expanded options strategies, plus a credit card.
Third, it points to distribution outcomes, including capturing 35% of all First Home Savings Accounts opened in Canada and ranking among the top three institutions in the country for net deposits.
Lisa Zarzeczny, CEO, Elevate:
“Wealthsimple exemplifies the bold innovation and execution that the CIX Innovator of the Year award celebrates. Their commitment to using technology to democratize access to sophisticated financial tools is exactly the kind of innovation Canada needs more of. We’re thrilled to honour their achievements and hear from Mike at CIX Summit about how they’re continuing to push boundaries in an industry ripe for disruption.”
This award lands in a moment where Canadian consumers keep moving toward digital first money management, and incumbents keep responding with pricing and product changes like options fee changes and real gold investing, plus competitive positioning where challenger platforms push directly at big bank margins. Those tracks connect cleanly to what CIX rewards here, which is compounding execution across product, distribution, and balance sheet strength.
In addition to Innovator of the Year award, see all 14 CIX 2026 startup award winners across early, emerging, and growth categories.
Mike Katchen is scheduled to accept the award and speak at CIX Summit 2026 on March 25 2026 at the Design Exchange in Toronto, alongside curated startup presentations and investor meetings, according to the release. NCFA is sharing a 20% community partner discount on CIX Summit passes for its community. Use CIXNCFA20 for 20% off. CIX publishes ticket options and event logistics on its official ticket page. Register with NCFA and save.
If a fintech can add hundreds of thousands of clients while it doubles assets, raises late stage capital, and expands into credit, what becomes the real incumbent moat in Canada next, distribution, product depth, or trust?
Awards do not build companies, but they do spotlight operating models that work. Congratulations to Michael Katchen and the entire Wealthsimple team for leading fintech in Canada across a number of fronts. Well deserved!
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 18, 2026 | NCFA Fintech Market Activity | Tokenization and Digital Assets
Image: Freepik
On February 18 2026, WLFI announced a strategic collaboration with Apex Group covering over $3.5 trillion in serviced assets, with a planned pilot to explore using WLFI’s USD1 stablecoin for tokenized asset subscriptions, distributions, and redemptions.
Apex Group operates in 52 countries and explains the work and partnership as a way to bring regulated stablecoin infrastructure into fund administration workflows, with the stated goal of streamlining settlement and improving operational efficiency for institutional clients.
The collaboration also extends beyond cash movement. Parties will evaluate ways to make WLFI assets, including real estate and infrastructure holdings, available on the London Stock Exchange Group Digital Market Infrastructure platform, subject to applicable regulations and requirements. The Apex Group will also explore making assets tokenized using Apex Digital 3.0 available through WLFI’s planned mobile app, which the release says will support digital asset management and connections to bank accounts and wallets.
Zach Witkoff, Chief Executive Officer and Co Founder, World Liberty Financial:
“Working with Apex Group allows us to demonstrate USD1’s tremendous utility within capital markets infrastructure. This collaboration accelerates our mission to make WLFI assets accessible at the most established financial services platforms globally.”
The release also describes WLFI as inspired by President Donald J. Trump. The link to a political brand raises the stakes for how market participants evaluate governance, oversight, counterparty risk, and reputational exposure, especially when the use case touches institutional fund servicing rather than retail trading. Early WLFI token sales generated significant investor demand and capital commitments, positioning the ecosystem as both a funding vehicle and an emerging digital asset platform.
For tokenized funds, the operational promise is clear. Subscriptions and redemptions create predictable and repetitive money movement. A stablecoin rail can compress settlement timelines, tighten reconciliation loops, and reduce dependency on multi step bank handoffs, if the controls meet the standard that allocators and regulators expect.
If administrators can run clean tokenized fund flows on stablecoin rails, other administrators, custodians, and infrastructure providers will feel pressure to offer equivalent settlement options, or to partner with providers that already can. That competition will centre on who can deliver reliability, auditability, safeguards, and integration speed.
Peter Hughes, Founder and Chief Executive Officer, Apex Group:
“Our clients are increasingly interested in blockchain based solutions that deliver tangible benefits and cost savings. This collaboration with World Liberty Financial lets us examine how USD1 and stablecoin infrastructure can modernize our platform and services, while providing the edge to support our clients as digital asset integration becomes standard practice.”
If stablecoins start handling fund subscriptions and redemptions at scale, do administrators become the main gatekeepers that decide which stablecoin rails earn institutional trust?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 18, 2026 | NCFA Fintech Market Activity | Payments and Cybersecurity
Image: Freepik/viarprodesign
On February 18 2026, reports of fake Olympic merchandise stores harvesting payment data surfaced ahead of the Milan Cortina Winter Games, exposing how large scale sporting events create concentrated digital commerce risk for consumers and payment providers.
Security researchers said fraudulent online stores replicated official Olympic branding and targeted fans through paid social ads. These sites collected card details and personal information at checkout, highlighting how event driven ecommerce spikes attract coordinated fraud campaigns designed to exploit urgency and trust.
Olympic Games generate predictable surges in travel bookings, ticketing, merchandise sales, and hospitality spending. That volume creates a short window where fraud actors can test payment authentication controls, merchant verification processes, and consumer awareness at scale. For payment providers, the risk is less about individual transactions and more about reputational and chargeback exposure across thousands of purchases.
Major global events have historically accelerated payments adoption, from contactless transit trials to mobile wallet acceptance across venues. At the same time, they expose gaps in digital identity verification, merchant onboarding, and fraud detection workflows. This combination turns Olympic commerce into a real world stress test for payment security infrastructure.
Canadian cross-border spending behaviour consistently ranks high per Olympic visitor card spend, meaning domestic issuers and fintech wallet providers often absorb fraud impacts even when the transaction originates overseas. That creates incentives for stronger real time transaction monitoring, merchant intelligence, and consumer education before peak travel windows.
Large scale events compress digital commerce into short intense spending cycles. When Olympic demand meets fraudulent storefronts and social commerce ads, which payment safeguards will prove most resilient for consumers, merchants, and fintech platforms?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016