




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


February 5, 2026
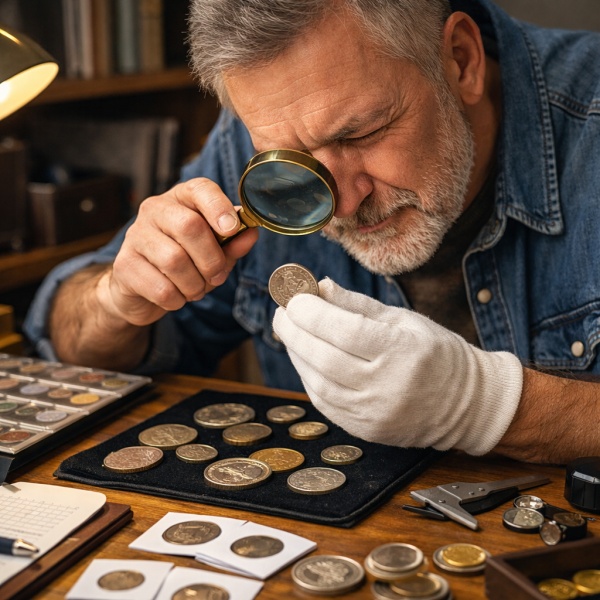
Selling rare coins or gold can feel overwhelming. You want a fair price, but the process seems complicated. This guide breaks down what you need to know to make informed decisions and get the best return on your precious metals.
Before you sell, you need to know what you have. Rare coins and gold pieces vary wildly in value. A coin's worth depends on its metal content, rarity, condition, and historical demand.
Gold coins fall into two categories: bullion and numismatic. Bullion coins like American Eagles or Canadian Maple Leafs trade close to their metal value. The price follows the spot price of gold, which changes daily based on global markets. Numismatic coins have collectible value beyond their metal content. A pre-1933 gold coin might sell for several times its melt value because collectors want it.
Rare coins without gold content can still command high prices. A 1909-S VDB penny in mint condition sells for thousands of dollars. The 1916-D Mercury dime? Collectors pay premium prices for clean examples. Condition matters tremendously in coin collecting.
When you're ready to sell, working with experienced buyers makes the difference. Austin Coin Buyers can assess your collection and provide current market valuations based on actual sales data, not outdated price guides.
Professional grading helps establish value. Third-party grading services like the Professional Coin Grading Service (PCGS) and Numismatic Guaranty Company (NGC) authenticate and grade coins on a 70-point scale. A coin graded MS-65 (Mint State 65) will sell for more than the same coin in MS-60 condition.
Grading costs money. You pay fees for submission, grading, and return shipping. For common coins worth less than $100, grading might cost more than the value increase. Save grading for coins that could be worth $500 or more. A dealer can help you decide which coins justify the expense.
Gold purity also affects value. The United States Mint produces coins in 22-karat (91.67% pure) and 24-karat (99.99% pure) gold. Jewelry often uses 14-karat (58.3% pure) or 18-karat (75% pure) gold. Buyers test gold items to verify purity before making offers.
Gold prices fluctuate based on economic factors. When inflation rises, investors buy gold as a hedge. During economic uncertainty, gold typically gains value. The spot price represents the current trading price for one troy ounce of pure gold.
Let's break it down. If gold trades at $2,000 per ounce and you have a one-ounce American Gold Eagle (91.67% pure), your coin contains about $1,833 worth of gold. Dealers typically pay 90-95% of melt value for bullion coins. You might receive $1,650-$1,740 for that coin.
Rare coins don't follow spot prices as closely. A Saint-Gaudens Double Eagle in exceptional condition might sell for $2,500 when it contains only $1,800 in gold. Collectors pay for scarcity and beauty, not just metal.
Timing your sale can affect your return. Watch gold prices over several weeks. If prices trend upward, waiting a few days might net you more money. If prices are falling, selling sooner protects your value.
You have several options for selling rare coins and gold. Each has pros and cons.
Local coin dealers offer immediate payment and face-to-face transactions. You can ask questions and get answers right away. Reputable dealers have established businesses and care about their reputation. They buy regularly and know current market prices.
Online marketplaces like eBay reach more buyers. You might get higher prices from collectors willing to bid competitively. But you'll pay listing fees, final value fees, and payment processing fees. Shipping precious metals requires insurance and tracking. Scammers exist online, both as buyers and sellers.
Auction houses work well for extremely rare or high-value items. They market to serious collectors and provide authentication services. Auctions take time, and you'll pay commission fees of 10-20%. Reserve prices protect you from low-ball sales, but they might prevent a sale if bidding stays weak.
Pawn shops buy gold and coins but usually pay the least. They need to resell at a profit and often lack specialized knowledge about rare coins. Visit pawn shops only if you need cash immediately and have no other options.
Honest dealers outnumber scammers, but problems exist. Watch for these warning signs.
Pressure tactics should send you away immediately. "This price is only good today" or "I have another buyer waiting" are manipulation techniques. Legitimate dealers know their offers are competitive and don't rush you.
Vague or confusing explanations about pricing indicate problems. A good dealer explains exactly how they calculated their offer. They'll show you the spot price, discuss premiums, and justify their buying percentage. If you don't understand the math, ask again or leave.
No physical location or unclear business information raises concerns. Check for a real address, phone number, and business license. Online reviews help, but read carefully. A few negative reviews among hundreds of positive ones is normal. Patterns of similar complaints deserve attention.
Clean hands and a clean workspace protect your coins. Dirt and oils from your fingers can damage rare coins. Never clean old coins yourself. Cleaning removes the patina that collectors value and can reduce a coin's worth by 50% or more.
Organize your items before meeting with a dealer. Group similar items together. Separate gold coins from silver coins. Put rare coins aside from common ones. This preparation shows you take the process seriously and helps the dealer work more efficiently.
Bring documentation if you have it. Receipts, previous appraisals, and certificates of authenticity all help establish value. Original packaging for modern bullion coins adds to their worth.
Know your bottom line before you start negotiations. What's the minimum price you'll accept? Having this number in mind prevents you from making emotional decisions or accepting low offers out of convenience.
Expect the dealer to examine each item carefully. They'll check dates, mint marks, and condition. For gold items, they'll test purity using acid tests or electronic testers. This process takes time, especially for large collections.
Ask questions during the evaluation. Why does this coin grade higher than that one? How did you calculate the gold content? What affects this coin's value? Good dealers enjoy sharing their knowledge.
The dealer will make an offer based on their evaluation. You can accept, decline, or negotiate. If the offer seems low, ask them to explain their reasoning. They might point out damage you didn't notice or explain current market conditions.
Get your payment in your preferred form. Cash works for smaller transactions. Checks or bank transfers suit larger sales. Some dealers offer both. Whatever you choose, get a detailed receipt listing each item sold and the price paid.
Inherited coins require extra care. You might not know what you have or what it's worth. Don't rush the process.
Sort items roughly by type. Put gold coins in one group, silver coins in another, and so forth. Look for obviously old or unusual pieces. These might have the most value.
Consider getting a second opinion on inherited collections. If one dealer offers $5,000 and another offers $8,000 for the same items, that gap tells you something. Most honest dealers will price within 10-15% of each other.
Estate sales sometimes include coins that the original owner thought were rare but aren't. The 1943 steel penny, for instance, is common despite its unusual appearance. A dealer can separate the truly rare from the merely old.
The IRS treats precious metals as collectibles. When you sell coins or gold for more than you paid, you owe capital gains tax. The collectibles tax rate maxes out at 28%, higher than the 15-20% rate for stocks.
Keep records of what you paid for items. Your cost basis reduces your taxable gain. If you inherited coins, the cost basis usually equals their value on the date of death, not what the original owner paid.
Sales over $10,000 in cash trigger reporting requirements under federal law. Dealers must file Form 8300 with the IRS. This applies to cash only, not checks or electronic transfers.
Consult a tax professional if you're selling a large collection. They can help you time sales to minimize taxes or split sales across tax years to stay in lower brackets.
Selling rare coins or gold requires research and patience. Understanding what you own, getting fair appraisals, and choosing the right buyer all affect your outcome.
Trust matters more than getting the absolute highest price. A dealer who pays 5% less but treats you fairly and honestly beats one who quotes high numbers but uses deceptive practices.
Take your time, ask questions, and don't settle for the first offer. Your rare coins and gold deserve careful attention, and you deserve fair compensation for your items.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
February 5, 2026

Early online iGaming platforms worked with very limited payment options. A player added one card to a profile and waited for funds to move through bank systems. Delays were common, and account control stayed minimal. Fintech changed that structure. Platforms such as Wildrobin Casino now rely on modern financial tools that support faster money flow, flexible account setup, and better control over digital funds.
The shift away from single-card links toward multi‑channel finance gave operators more stability and gave users clearer access to their balances without repeated manual steps.
Modern iGaming platforms rely on named payment systems that support speed and reliability. Interac e‑Transfer serves as a core option in Canada for direct bank payments. Visa and Mastercard remain active through tokenized card processing by providers such as Nuvei and Worldpay.
Digital payment networks such as PayPal and Skrill support fast deposits without card exposure. Some platforms also accept Bitcoin and Ethereum through processors like BitPay and CoinPayments.
Each method routes through a central payment gateway that manages settlement and tracking. This setup allows platforms to handle volume without manual review. Funds move through clear paths with predictable timing.
Wallet systems have become a core part of how iGaming platforms manage player funds. Services like Skrill Wallet, Neteller, and PayPal Balance let users load money once and use it across sessions without needing to go back to their bank each time. This setup keeps the process simple for the user and reduces friction during deposits and withdrawals.
Behind the scenes, real-time ledger systems track every transaction and update balances instantly. That helps prevent failed payments and gives support teams fewer issues to handle.
Some platforms also connect with crypto wallets through providers like Coinbase Commerce that allow players to use digital currencies without directly linking a bank account. Wildrobin Casino relies on these wallet solutions to keep money movement smooth and account values easy to manage.
Fintech companies provide tools that help platforms monitor payments and spot unusual account behavior. Risk engines from providers like Feedzai and SEON track how users deposit and withdraw, then check those patterns before any payment goes through. If something seems off, the system flags it right away.
For financial tracking, platforms often use systems like Stripe Sigma or the Nuvei Control Panel. These tools show payment totals, processing speed, and method breakdowns in real time. That means operators don’t need to wait for reports or pull numbers manually.
Platforms such as Wildrobin Casino use these systems to keep payment operations running smoothly while staying on top of account activity and transaction flow.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 4, 2026 | NCFA Insights | AI, Financial Infrastructure and Identity

On February 2 2026, security firm Wiz disclosed an exposed Moltbook database tied to autonomous AI agents containing millions of API keys. Around the same time, OpenClaw (an open source framework for running locally controlled AI agents) published documentation showing how locally run AI agents can access user devices, credentials and external services.
Autonomous AI agents aren't limited to chat style tools, and are beginning to touch real infrastructure that includes identity, wallets, and payment-related APIs.
This article discusses the what the emerging agent economy looks like in practice, why it matters for fintech founders and investors, and where governance and security pressure is building first. AI agents increasingly hold credentials, maintain state over time, and interact with external systems through APIs. That mix creates a new operational reality. Code is starting to act like a user, but without the same guardrails that traditional consumer finance expects.
Early agent frameworks are moving from single session prompts into persistent software. They can store memory, maintain identity, and run tasks continuously.
In OpenClaw’s model, locally run agents can interact with files, services, and external applications using user approved permissions. These agents can coordinate with other agents, call tools, and keep operating after a user stops watching the screen.
That capability becomes financially relevant the moment an agent can access a wallet credential, a banking API token, or a payment workflow embedded inside another platform.
Fintech products already sit on top of API keys, tokens, and delegated permissions. Wallet providers, open banking connectors, payment facilitators, and embedded finance stacks often rely on shared secrets and scoped access to move data or value. AI agents introduce a new actor into that system. A human might authorize a connection once, then an agent can repeatedly execute actions across that access channel at machine speed.
If an AI agent initiates a transaction, who owns responsibility for the outcome.
If an agent uses an API credential and a vendor later mishandles logs or storage, who absorbs liability.
If an agent operates in the background, how do firms enforce consent, audit trails, and appropriate use.
The Moltbook exposure matters because the risk is suddenly tangible. An unsecured database containing API keys is not a routine bug. It shows how quickly agent networks can create large pools of credentials that become attractive targets. When an environment contains millions of agent identities, a failure in credential storage or access control can scale into massive compromise. And of course, the financial equivalent is obvious. Once agents connect to wallets, payments, or identity services, insecure key management becomes a direct financial risk.
Fintech teams already know that credential hygiene and access governance decide security outcomes. AI agents compress that timeline. Humans leak keys through mistakes. Agents and agent networks can leak keys through architecture. That is why builders should treat agent access as its own risk class, separate from standard consumer or enterprise authentication patterns.
Regulators do not yet have comprehensive frameworks for AI agents operating inside financial workflows. Even so, policy direction in adjacent areas points to where enforcement will land first. Authorities focus on accountability, auditability, and consumer harm, regardless of channel. That already shows up in digital advice and online influence. Learn how CSA and CIRO tighten expectations around digital investment advice and influence when content or workflows can affect investor behaviour at scale.
AI agents create a similar accountability gap. If an agent provides recommendations, executes actions, or routes users into products, platform operators will need evidence of controls. That will include permissioning, logging, dispute handling, and clear assignment of responsibility when something goes wrong.
If AI agents can hold credentials and execute actions through financial APIs, what controls will separate trusted automation from uncontrolled delegated access?
The agent economy is coalescing at the edge of finance. AI agents that operate with identity and persistent access can become a new layer between users and money transfers. The winners will treat governance as part of product design. They will harden credential management, build clear authorization flows, and design auditability that works when software, not a person, invokes actions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 4, 2026 | NCFA Expert Intelligence | AI Risk and Governance
On February 3 2026, Dentons published a Voice from the Market North American Legal AI report following the firm’s inaugural Legal AI Summit. The report captures data insights from legal, business, and operations leaders across sectors about how organizations are handling real world AI deployment, specifically where AI adoption is creating legal and governance risk before regulators provide clear framework.
The findings matter for fintech founders and operators because legal teams are often the first to see where risk accumulates, such as in contracts, vendor relationships, employee use, and product liability, long before the market or regulators respond.
Most organizations in the survey reported they are designing their own AI governance frameworks because universal regulations do not exist yet. That gap puts legal risk in the critical path for AI use inside financial products and services.
“We want to cover the basics, but we don’t want to stymie innovation or scare people away with too many ‘do nots.’”
This comment above is from a survey participant highlighting the tension leaders face: Smart governance is needed, but overly prescriptive rules can impede experimentation and execution. So it's a real operational conflict that stakeholders must resolve long before policy catches up.
The governance gaps in the report align with real risks fintechs already encounter:
Many fintechs are building AI capability faster than they are formalizing guardrails, which can expose firms to legal, operational, and compliance risk across functions where AI is integrated in workflows. Whether that's in credit decisions, document review, marketing, fraud monitoring, or customer support.
It also intersects with other areas NCFA has covered. For example, recent regulatory signals from the CSA–CIRO joint finfluencer guidance and the rise of stablecoin policy frameworks both show that Canada’s regulatory perimeter is tightening around behaviour and risk, not just product categories.
If legal risk surfaces first in AI contracts, vendor relationships, and internal use, where should fintechs build their earliest governance guardrails: in contracts, in internal policy, or in product design?
Regulation typically always lags innovation. Legal and governance frameworks are being created inside enterprises today because no universal rulebook exists. Fintech innovators and operators who anticipate these gaps and embed guardrails early will be better positioned to scale responsibly and avoid costly legal exposure down the road.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 3, 2026 | NCFA Fintech Market Activity | Stablecoins and Payments
On February 3 2026, VersaBank announced that Stablecorp’s QCAD is its first stablecoin customer, bringing a Canadian Schedule I bank into the custody and safeguarding of a Canadian dollar-backed digital currency.
Stablecorp issues QCAD as a 1:1 Canadian dollar-backed stablecoin with reserve funds held at regulated financial institutions. VersaBank provides custodial services and settlement support for QCAD transactions using its digital asset infrastructure and API framework.
Most stablecoin infrastructure in Canada still depends on global US dollar networks. QCAD represents a domestic currency alternative, and VersaBank’s role places regulated banking oversight directly inside the operational flow of a Canadian stablecoin.
VersaBank has been building digital asset custody and tokenized deposit capabilities over the past several years. Its platform supports digital asset APIs, ledger compatible settlement tools, and custody frameworks designed for fintech integration. Bringing QCAD onto this platform turns that infrastructure into a live payments and settlement environment rather than a technical capability waiting for use.
Transaction volumes aren't disclosed, but the structure matters more than scale today. A Canadian stablecoin now sits inside a regulated bank’s custody, reconciliation, and safeguarding systems. It's a practical step toward making stablecoins usable for treasury management, fintech on and off ramps, merchant settlement, and cross-border flows without relying on foreign currency rails.
David Taylor, President and CEO, VersaBank:
"We are pleased to support Stablecorp and QCAD as they bring a Canadian dollar stablecoin to market. Our digital asset custody and settlement platform was built for exactly this type of use case, where regulated banking infrastructure meets digital currency innovation."
If Canadian stablecoins can settle through Canadian regulated banks, what role will they play in future payment rails, treasury operations, and fintech infrastructure?
Instead of sitting outside the financial system, digital Canadian dollars are beginning to move through it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 4, 2026 | NCFA Fintech Market Activity | Funding and Capital Markets
Image: Freepik
On February 4 2026, NEO Financial announced it secured $68.5 million in equity capital from more than 100 Canadian investors to accelerate its securitization strategy and support further growth of its lending and credit products. The round includes participation from Alberta Investment Management Corporation (AIMCo), Northleaf Capital Partners, Plaza Ventures, Sandstone Asset Management, and Caldwell Growth Opportunities Fund. These are not typical venture participants. They are institutional capital allocators with deep experience in private credit, structured finance, and asset-backed investing.
NEO positions the raise as strengthening its balance sheet to expand its asset-backed funding programs and diversify capital sources tied to its consumer and merchant credit offerings. The company isn't raising capital simply to extend runway. It's raising capital specifically to support securitization activity that allows the company to recycle lending capital through structured vehicles and continue originating credit without relying solely on sponsor-bank facilities or traditional debt lines.
NEO reports that it serves millions of Canadians across retail and business financial products and has already built a sizeable loan portfolio through point of sale financing, credit products, and merchant services. Securitization allows that loan book to become a capital markets asset rather than a balance sheet constraint.
For Canadian fintech lenders, this represents a maturation point. Early growth in fintech credit often depends on venture equity and warehouse funding. Long term scale depends on access to institutional capital markets that can absorb receivables and recycle liquidity. NEO's financing is a sign that Canadian institutional investors are increasingly comfortable backing fintech platforms that combine lending operations with disciplined capital markets execution.
Andrew Chau, Co-Founder and CEO, NEO Financial:
"This investment supports the continued expansion of our securitization strategy and strengthens our ability to scale credit products responsibly for Canadians and businesses across the country."
When fintech lenders can turn their loan portfolios into new funding through securitization, does access to capital markets become the main factor separating national scale players from niche credit providers?
This raise shows how NEO is tying its lending growth directly to capital markets capability. Platforms that can convert loan origination into structured investment assets will have a structural advantage as lending volumes grow.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 2, 2026 | NCFA Fintech Market Activity | Payments and Regulation
On February 2 2026, XTM Inc said Everyday Payments had started the Retail Payment Activities Act compliance process for thousands of hospitality businesses across Canada.
The release tied the work to the Everyday platform that manages hospitality payout flows such as tip outs and shift-based earnings. It also linked the compliance path to the migration of the AnyDay Canadian hospitality solution into the newly formed Everyday Payments entity.
XTM said that on January 28 2026 it implemented additional risk mitigation measures to address legacy operational practices across the platform.
Marilyn Schaffer, CEO of XTM:
"While the RPAA transition has included challenges related to reconciliation and technology alignment, we welcome building from a place of discipline."
The release lists three specific changes:
First, it said it had implemented regulated trust accounts for each client with an expected completion window of 30 to 45 business days.
Second, it said it had moved from weekly to daily withdrawals to improve reconciliation, control, and visibility.
Third, it said it had added enhanced audit and review rights so business owners could independently assess account standing.
This is where RPAA stops being policy and starts being operations. Fund segregation, withdrawal cadence, and auditability now sit inside the day to day flow of money for hospitality workers and merchants.
Everyday Payments operates payout infrastructure used by restaurants, bars, hotels, and hospitality venues across Canada to distribute earned funds to workers and reconcile merchant balances. That scale is what makes these changes meaningful. When a platform supporting thousands of venues adjusts how funds are held, released, and reviewed, it foreshadows what other vertical payment operators will soon face as RPAA requirements mature.
The release also says RPAA's a system level baseline, requiring registration, operational risk management frameworks, safeguarding of end user funds, and incident reporting administered by the Bank of Canada. Remember RPAA registration opened on November 1 2024.
Gordon Reykdal, Executive Chairman, Everyday People Financial Corp, and Board Member, Everyday Payments:
“Applying under the RPAA to the newly formed Everyday Payments is a natural extension of how we operate our business. We welcome a clear and robust regulatory framework and believe it strengthens trust across the payments ecosystem, benefiting consumers, merchants, and partners alike.”
Daily withdrawals, regulated trust accounts, and merchant audit rights raise the operating bar. Which vertical payment platforms will treat that bar as a moat, and which will treat it as friction that slows growth?
RPAA compliance is now showing up inside real operational workflows that move money for frontline workers and merchants, not only inside financial institutions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016