




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 17, 2026 | NCFA Market Activity | Insurance And Insurtech, Embedded Finance, Artificial Intelligence And Data
On July 14, 2026, Cover Genius announced a US$100 million capital raise backed by Vista Credit Partners. The financing transaction values the embedded insurance company at US$1.9 billion and will support new AI tools, deeper platform integrations, international growth and selected acquisitions.
The size of the raise is only part of the story. Cover Genius is taking capital from the credit arm of Vista Equity Partners rather than announcing another conventional venture round. It comes after the company increased revenue by 50% in 2025 and built a large base of recurring platform relationships. That gives Vista a more established enterprise software business to finance, although the interest rate, maturity, covenants and any equity features weren’t disclosed.
Cover Genius now connects more than 200 digital platforms with over 50 insurance carriers. It has issued 240 million policies, protected more than 70 million customers and recorded US$3.2 billion in cumulative gross written sales. Its products are available in more than 60 countries and across all 50 US states.
Cover Genius is no longer simply distributing travel insurance at checkout. It provides the software, carrier connections, product design, pricing, claims handling and payment tools that let another company offer protection inside its own customer experience.
Cover Genius works behind platforms including Klarna, Revolut, Stripe, Booking.com, Agoda, Priceline, Uber, eBay and Turkish Airlines. Its reach now spans travel, ecommerce, retail, ticketing, logistics, mobility and financial services.
A platform can use Cover Genius to add insurance or a warranty without building separate systems for each carrier and country. Cover Genius adapts the product, price and presentation to the customer, transaction and location. It can also manage the policy after purchase and pay approved claims in more than 90 currencies.
That operating model reflects the same infrastructure approach seen across embedded financial services. The customer stays inside the merchant or fintech app while a specialist provider handles regulated work behind the scenes. The platform gains another source of revenue and can make the main purchase easier to protect.
Cover Genius competes with several companies. Bolttech combines insurance exchange technology with a broad carrier and distribution network. Qover builds digital insurance programs for fintech, mobility and other European platforms. Boost Insurance provides the regulated and technical stack behind embedded products in the United States. Tint works with marketplaces and software companies on tailored protection programs. Traditional insurers are also improving their APIs and selling directly through large digital partners.
Cover Genius has a scale advantage in the number of countries, industries and large platforms already connected to its system. That scale creates useful data across product selection, pricing, conversion and claims. It also makes the company harder to replace when a partner relies on it across several markets.
The new capital will fund three defined areas of AI development. Cover Genius plans to(1) improve how protection is selected and presented for each customer, (2) support agent led purchasing, and (3) automate more of the claims process.
1. Personalization could help a platform offer the right protection without adding too many choices at checkout. A travel site may know the destination, fare type, booking value and traveller profile. A retailer may know the product category, delivery route and expected replacement cost. Better use of that information could raise insurance sales while reducing irrelevant offers.
2. Agentic distribution has a less settled business case. As software agents begin booking travel or making purchases for users, they may also compare protection, read exclusions and complete the insurance purchase. Cover Genius wants its products and APIs to be available inside that process rather than waiting for a person to select a box on a checkout page.
3. Claims may deliver the clearer near term return. Cover Genius already operates XCover for policy and claims management, XClaim for approved payments and BrightWrite for pricing and product recommendations. More automation could shorten review times and reduce the support burden for both Cover Genius and its partners.
It also raises an important control question. Automated decisions need reliable evidence, clear reasons and a practical route for customers to challenge an outcome. Insurance claims are more sensitive than product recommendations. Faster processing will only improve the customer experience when the decision is also fair and understandable.
The financing choice suggests Cover Genius believes it has enough operating scale to add debt without giving up another large ownership stake. That can be attractive when revenue is growing and enterprise contracts provide better visibility. It also adds fixed obligations that equity financing doesn’t carry.
The company raised US$80 million in a Series D led by Spark Capital in 2024 after reporting 107% revenue growth for 2023. The latest transaction gives it more capital for product development and expansion, but the company hasn’t disclosed current revenue, profitability, cash flow or the cost of the new financing. A US$1.9 billion valuation alone doesn’t answer whether the credit structure is conservative or aggressive.
There are several ways the investment could work well. Cover Genius may deepen existing partner relationships, enter new industries and use AI to improve conversion and reduce claims costs. Its global carrier network could also make selected acquisitions more valuable because acquired products can be distributed through an existing platform.
Execution could become harder as the company expands. Insurance regulation remains local, partner integrations can be complex and claims quality has a direct effect on trust. Larger insurers and other global insurtech platforms are also investing in the same distribution layer. Cover Genius must grow without making its products harder to understand or its claims process harder to challenge.
Canadian insurers, fintechs, travel companies and ecommerce platforms face the same integration problem. Building protection internally requires carrier relationships, licensing, pricing, compliance and claims operations. A provider such as Cover Genius can shorten that work, although Canadian companies still need to understand who controls the customer data, product terms and claims decision.
The funding structure also offers a useful comparison for Canadian growth companies. Private capital markets are giving mature technology businesses more ways to finance expansion after venture equity. Credit can preserve ownership, but it works best when recurring revenue and cash flow can support repayment through a slower period.
Has Cover Genius become the insurance infrastructure layer for digital platforms, or will global carriers and competing insurtechs make embedded protection a lower margin service?
Angus McDonald and Chris Bayley founded Cover Genius after encountering fragmented insurance distribution while operating an online travel business. RentalCover became the first use case for combining digital distribution, policy administration and claims support.
RentalCoverRental vehicle protection distributed through digital booking platforms
LaunchA focused first product built around a clear travel use case
Founder LedEarly development preceded the company’s later institutional funding rounds
Travel And MobilityRental car bookings across multiple countries
Travel PlatformsOnline travel agencies and rental car booking businesses
Integrated ProtectionInsurance offered inside the booking flow rather than through a separate purchase
The first product mattered because it gave Cover Genius a practical route into a difficult market. The company learned the operating work before expanding the platform.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 17, 2026 | NCFA Insight | Regulation And Policy, Wealth Investing And Trading, Risk Compliance And Regtech

On July 9, 2026, the UK Financial Conduct Authority reported the results of its finfluencer enforcement campaign. A coordinated week of action involving 9 international regulators produced 3 arrests, 6 criminal proceedings, 11 warning or cease and desist letters, 50 warning alerts and 650 social media takedown requests.
Canadian regulators weren’t watching from the sidelines. The Alberta Securities Commission, Autorité des marchés financiers, British Columbia Securities Commission and Ontario Securities Commission participated in the June 2025 operation. Earlier analysis asked whether finfluencers were facing a crackdown or clearer regulation.
The FCA’s latest figures show that enforcement has now become repeatable. Investigators can identify illegal content, connect creators to products and firms, request platform removals, issue public warnings and escalate selected cases into criminal proceedings.
The scale of the FCA’s supporting operation is just as relevant. During 2025, it issued 2,329 warnings about unauthorized or potentially fraudulent firms, compared with 2,240 in 2024. It secured 17 criminal convictions involving fraud, insider dealing, money laundering and data protection offences. Twelve people paid a combined £1.77 million in market abuse fines for market abuse.
Technology is improving that capacity. FCA automation reduced the handling time for simpler supervisory cases from as much as 4 hours to about 6 minutes on average. That doesn’t automate consequential decisions. It clears routine work so investigators can spend more time on repeat promoters, hidden compensation, unauthorized firms and cross border distribution.
The 650 takedown requests are the most commercially relevant number. Arrests attract attention, but removing hundreds of accounts and posts targets distribution. Illegal promotions lose value when creators can’t reach an audience, acquire leads or direct followers to a trading platform.
The FCA can examine multiple parties within one campaign. A creator may publish the content, a financial firm may pay for it, an affiliate network may track referrals and a platform may distribute it. The underlying product can then lead investigators to an unauthorized operator or regulated firm with weak approval controls.
Criminal proceedings provide the upper end of that response. The FCA accused 3 people charged after the 2025 operation of promoting high risk contracts for difference without authorization. Each faces an allegation of communicating an invitation to engage in investment activity contrary to section 21 of the UK Financial Services and Markets Act.
The April 2026 second global week of action showed how quickly the system had expanded. Seventeen regulators participated. The FCA requested the removal of 120 accounts and identified 1,267 illegal financial advertisements that reached at least 2,338,372 accounts. People or firms already listed on its Warning List accounted for 66% of those advertisements.
That 66% figure exposes a persistent enforcement problem. Many promoters aren’t unknown actors. They continue publishing after regulators have already identified the related firm, person or offer. Effective supervision therefore depends on account removal, repeat offender monitoring and platform cooperation, not warnings alone.
The FCA also secured a guilty plea, began criminal proceedings against 2 more people, issued 34 new warning alerts and updated 14 existing warnings during the April operation. Coordination now combines prosecution, surveillance, education and content removal rather than treating each promotion as an isolated post.
Canada’s legal foundation is already in place. In December 2025, the CSA and CIRO published Staff Notice 31-369, which explains how securities law applies to finfluencers, issuers and registered firms. The practical requirements appear in Canada’s finfluencer guidance.
The guidance doesn’t create a separate licence for creators. It examines the activity itself. A creator may need registration when they provide investment advice as a business, facilitates trades, arranges referrals or connects paid subscribers to copy trading. General market commentary may qualify for an exemption, but creators must still disclose financial interests and other conflicts clearly and on time.
Compensation also changes the compliance analysis. Cash payments, securities, affiliate income, referral fees and free products can establish a commercial relationship. A disclaimer such as “not financial advice” doesn’t cancel the substance of a recommendation, the creator’s compensation or the transaction being encouraged.
Responsibility extends beyond the creator. Registered firms must supervise people acting on their behalf, address referral arrangements, retain records and review relevant communications. Issuers remain responsible for paid investor relations activity and promotional claims made for their benefit. The joint staff notice applies the same principles to AI generated content and digital personas.
The investor evidence explains why regulators are paying attention. An OSC study of 655 Canadian retail investors found that 35% had made a financial decision based on finfluencer content. Those who acted on it were 12.2 times more likely to report being scammed on social media and 2.3 times more likely to have experienced a significant investment loss.
The OSC also ran a simulated investment experiment involving 1,465 Canadians. After viewing a promotional social media post, 38% bought the featured asset. Only 8% of the control group did the same. The full findings and behavioural differences appear in the finfluencer effect on Canadian investors.
Canada has also produced direct enforcement results. In September 2025, the Alberta Securities Commission imposed sanctions on James Domenic Floreani and Jayconomics Inc. for promoting 4 issuers through YouTube, X and Patreon without clearly disclosing that they published the content on behalf of those issuers.
The respondents received a $30,000 administrative penalty, $10,185.10 in costs and 2 year restrictions covering investor relations activity, public securities promotion and securities or derivatives advice.
British Columbia added a preventive layer during the April 2026 operation. The BCSC issued 14 compliance letters to YouTubers and other promoters who had discussed publicly traded B.C. companies. It also referred to an active proceeding alleging that sponsored issuer promotions weren’t disclosed clearly.
The FCA operates a national financial promotions regime and can report one consolidated set of arrests, warnings, takedowns and prosecutions. Provincial and territorial authorities administer Canadian securities regulation, while CIRO supervises investment dealers, mutual fund dealers and regulated marketplaces.
Canadian action may therefore appear as several provincial cases, coordinated review periods, issuer investigations, warning letters and firm supervision rather than one national enforcement tally. That can make the activity look smaller even when regulators review the same creators, platforms and promotional networks.
The operating implications are already clear.
Platforms are also becoming part of the enforcement process. When regulators can connect warnings to hundreds of removal requests, account access becomes a compliance dependency. Firms using social media for distribution can’t treat the creator’s channel as an independent marketing asset beyond their control.
Canada doesn’t need to duplicate the FCA’s structure to produce comparable enforcement. Its regulators are already participating in the same international operations, applying national guidance and using provincial proceedings. The open question is whether those actions will become visible as a coordinated Canadian program or remain distributed across separate regulators and cases.
Will Canada’s finfluencer guidance support coordinated enforcement across provinces, platforms and firms, or will separate cases continue defining the compliance boundary?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA engages with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 16, 2026 | NCFA Market Activity | Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Digital Assets
On July 16, 2026, Alpaca raised US$135 million in new equity led by Peak XV, with participation from Elefund, Opera Tech Ventures and Unbound.
The announced financing totals US$435 million, including debt financing primarily from Payward, the parent company of Kraken, and BMO. Alpaca didn’t disclose how that debt was structured or allocated between the lenders.
The financing reflects a larger change inside the company. Alpaca started by helping developers connect applications to U.S. brokerage accounts. It now clears more trades itself, holds securities in custody, operates regulated businesses in several markets and supports companies offering tokenized stocks.
That business needs more than product capital. Brokers need liquidity, regulatory capital and operations that can settle trades and protect customer assets during volatile markets.
A software company can add customers without holding their assets or settling their trades. A broker cannot.
Alpaca clears U.S. equities through the Depository Trust & Clearing Corporation. It has also secured memberships with the Options Clearing Corporation and Fixed Income Clearing Corporation and joined Nasdaq.
Those connections reduce its reliance on outside clearing brokers and give Alpaca more control over execution, settlement and the economics attached to each account. They also bring higher capital, liquidity and operating requirements.
The lenders fit that business. Payward brings Kraken’s digital asset market experience and an existing Nasdaq tokenization partnership. BMO brings a global banking and capital markets balance sheet and is already working with CME Group and Google Cloud on tokenized cash for margin and settlement.
Both are financing a broker that connects conventional securities with tokenized markets.
Alpaca’s first pitch was simple. A fintech could add investing without becoming a broker.
The company now supports stocks, ETFs, options, fixed income and crypto for more than 300 fintech and institutional partners across more than 40 countries. It reported more than 9 million brokerage accounts in January 2026.
Self clearing, custody, securities lending, cash products and wider market access let Alpaca handle more of each account relationship. That can improve product flexibility and give the company access to more of the revenue generated after an account opens.
Its international expansion follows the same pattern. The WealthKernel acquisition added regulated brokerage and custody businesses in the United Kingdom and Europe. Alpaca later completed passporting across the European Economic Area and began adding European equities. In India, it acquired an IFSCA regulated broker dealer and payment service provider in GIFT City.
Alpaca is buying regulated market access rather than trying to export one U.S. brokerage model everywhere.
That can simplify expansion for its partners. It also leaves Alpaca managing different legal entities, customer protections and operating requirements across jurisdictions.
The company says revenue has doubled annually for three consecutive years. Revenue, profitability and product level economics remain private.
Alpaca says it now holds more than US$1.5 billion in assets backing tokenized U.S. stocks and ETFs.
Alpaca doesn't issue those tokens. It holds the underlying securities while other companies create digital representations for their own platforms. The rights attached to each token depend on its issuer and legal structure.
Tokenized stocks therefore do not remove brokerage, custody or corporate actions. Someone still has to hold the shares, settle transactions and reconcile the token with the underlying asset.
That is Alpaca’s commercial role. Its Instant Tokenization Network connects custody with minting, redemption and liquidity across token issuers and trading venues.
The same model is entering regulated markets. Nasdaq’s tokenized stock proposal retains exchange trading and clearing while adding a tokenized representation.
Tokenization becomes a measurable business when firms can handle custody, settlement, reporting and corporate actions at scale. Issuing more tokens is the easy part.
Alpaca is also making brokerage functions easier for software to use directly. Its command line interface exposes 108 functions covering orders, accounts, positions, market data and crypto. The company also offers an MCP server and an AI agent skills library.
Brokerage APIs are not new. What is changing is how much of the workflow software can complete before a person intervenes.
A financial institution can allow software to retrieve account information, assess opportunities and prepare or submit orders. The institution still sets permissions, limits, approvals and exception rules. Responsibility for the trade remains with the firm and account owner.
Alpaca says monthly active API users nearly quadrupled during the six months before the financing. It hasn't disclosed the starting number or how much of that activity came from AI agents rather than conventional algorithmic trading.
The tools are available. Institutions will decide how much authority to give them.
Alpaca already supports a Canadian use case through Manzil’s embedded brokerage launch. Manzil owns the customer proposition while Alpaca provides U.S. brokerage accounts, custody, clearing and fractional share access. That arrangement lets a Canadian fintech build for a defined customer segment without becoming a U.S. broker dealer.
BMO’s financing participation adds an institutional connection. The bank is backing a company that holds securities behind tokenized equities and is taking on more clearing and custody work.
Payward adds another Canadian connection through Kraken. Kraken operates nationally through Payward Canada’s restricted dealer registration, while its parent company is also working with Nasdaq on tokenization.
Canada has broker dealers, custodians, wealth platforms and digital asset firms. Few combine developer brokerage APIs, self clearing, tokenized equity custody and regulated businesses across several markets.
Alpaca shows Canadian firms what a more integrated brokerage business can look like. The practical decision is which functions to own and which to source from a specialist.
Alpaca started by helping developers connect to a broker. Today it is taking on more of the brokerage itself.
The company clears trades, holds securities, operates regulated businesses across several jurisdictions and supports tokenized stock platforms. Its AI tools extend those same functions to software.
The latest financing belongs in that progression. The Company Intelligence Snapshot below shows how Alpaca added those capabilities and where the new equity and debt fit.
How much of the brokerage business can Alpaca bring under one company before regulatory and operating complexity begins to offset the advantage?
Yoshi Yokokawa and Hitoshi Harada founded Alpaca in 2015. The company began with market data and machine learning tools, then built a commission free brokerage API that developers could use for algorithmic trading.
AlpacaDBFounded by Yoshi Yokokawa and Hitoshi Harada
LaunchDeveloper trading and brokerage APIs
Early VentureMore than US$6 million reported by the 2018 API launch
United StatesU.S. equities and algorithmic trading
DevelopersAlgorithmic traders and financial application builders
API AccessBrokerage functions exposed through developer tools
Alpaca entered brokerage through developers rather than a consumer trading app. That distribution choice later gave financial companies a way to build their own investing products on the same brokerage connection.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 7, 2026 | NCFA Story Intelligence | Payments And Money Movement, SME Finance And Business Banking, Capital Markets And Market Infrastructure
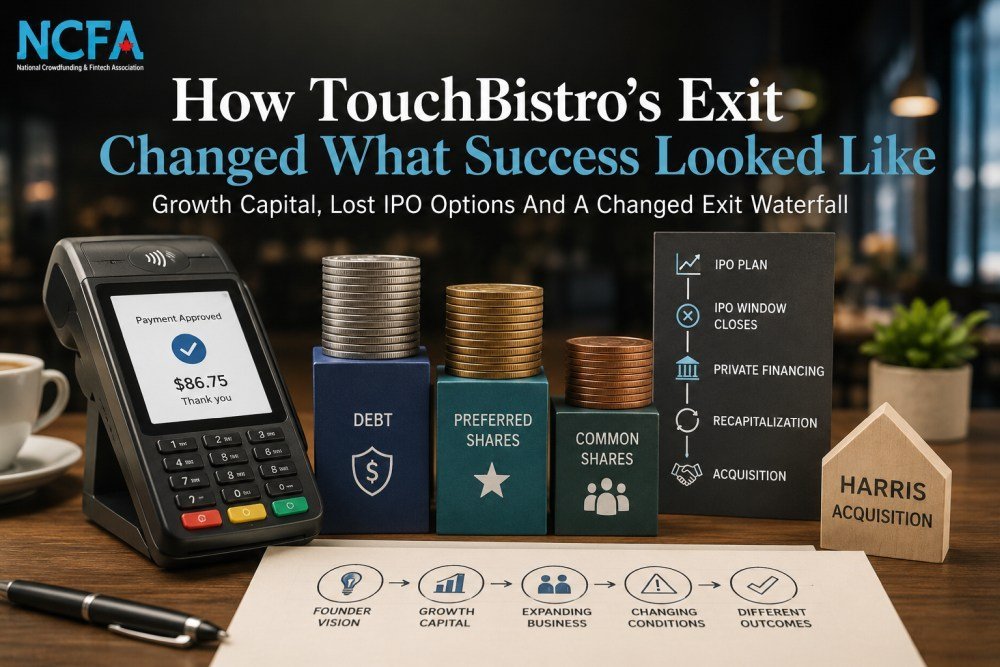
On July 7, 2026, Harris acquired TouchBistro, a Toronto restaurant technology and payments company whose point of sale, payment processing and management products serve more than 16,000 restaurants across over 100 countries. Harris, part of Constellation Software, didn’t disclose the purchase price.
The Globe and Mail later reported that Harris paid $100 million. Reporter Sean Silcoff said the transaction followed a December 2025 recapitalization that converted Francisco Partners’ debt into equity, gave the lender control of the board and reduced earlier shareholders to a minority position. He also reported a nine figure loss for OMERS and no recovery for employee common shares.
Those reported outcomes make the acquisition look like a failed exit. The operating record is more complicated. TouchBistro spent about 15 years building a global restaurant technology business, processing billions of dollars in transactions, expanding its product suite and surviving a pandemic that shut down much of its customer market.
The business had value. Its financing required more.
TouchBistro found a specific operating problem. Founder Alex Barrotti built the original product around restaurants that wanted mobile ordering, table management and point of sale software on an iPad. The narrow industry focus helped TouchBistro expand into reservations, loyalty, staff scheduling, online ordering, accounting, payments and restaurant management.
Investors saw a larger opportunity. Restaurants represented a fragmented global market with recurring software revenue, payment volume and room to sell several products into the same customer account. Venture backing could accelerate product development, international sales and acquisitions before larger competitors controlled the category.
BDC joined the shareholder base. TouchBistro’s 2017 Series C included BDC IT Venture Fund, giving the company backing from a federal Crown corporation alongside private investors. That public investment supported a Canadian company competing internationally, but it also carried a mandate to produce a financial return.
The C$72 million Series D raised the ambition. In June 2018, OMERS Ventures and JPMorgan Chase led the round, with BDC and existing investors participating. TouchBistro said it would expand research, enter more markets and double its workforce.
OMERS placed a major institutional bet. In September 2019, OMERS Growth Equity led a C$158 million Series E and invested C$85 million itself. Barclays Bank, RBC Ventures and BMO Capital Partners joined the round, while BDC, JPMorgan Chase and other existing investors participated.
The company had scale to support the pitch. OMERS said TouchBistro served more than 16,000 restaurants in over 100 countries and processed more than US$11 billion annually through its payment system. The financing supported product development, acquisitions, international expansion and hiring.
A public listing offered several advantages. It could provide new investment, establish a market price, give investors a route to sell shares and support acquisitions with public equity. It could also preserve TouchBistro as an independent Canadian company if public investors accepted the growth case.
There was no guarantee the market would cooperate. An IPO would require reliable growth, audited financial performance, predictable recurring revenue and public investor demand. The company never named an intended exchange in the sources reviewed, so the record doesn’t establish that TouchBistro rejected a Canadian listing.
The founder stepped out of the CEO role. In April 2021, Barrotti handed leadership to board chair Samir Zabaneh. He described the transition as a new stage requiring experience operating large global companies, not as a forced departure.
The operating job had changed. TouchBistro now needed to recover from the pandemic, control spending, expand payments revenue and compete with larger rivals. Leadership that was suited to founder led expansion wasn’t automatically suited to the next operating and financing phase.
A financing round doesn’t just fund the next stage of growth. It can quietly redefine which exits remain possible.
Private financing replaced the expected public route. In November 2022, Francisco Partners supplied C$150 million for product expansion, core services and acquisitions. Francisco Partners includes TouchBistro within its credit and structured solutions portfolio.
The financing bought time under new conditions. Equity absorbs losses until an exit. Debt introduces repayment, covenants, maturity dates and senior claims. Convertible instruments can later become ownership. The public announcement didn’t disclose the complete instrument, pricing, covenants or conversion terms.
The category kept getting harder. TouchBistro competed against Toast and other restaurant technology firms with their own payments, software, data and distribution advantages. Investment could finance products and acquisitions. It couldn’t guarantee that TouchBistro would outgrow a larger rival.
Cost discipline carried its own tradeoff. Silcoff reported that Zabaneh reduced costs while growth weakened. That doesn’t prove the reductions caused the later outcome. It shows the conflict management faced: preserve cash, invest against a larger competitor or raise more money into a weaker market.
A reported recapitalization reordered the company. In his public summary of the Globe investigation, Silcoff reported that Francisco Partners converted debt into equity in December 2025, took control of the board and reduced existing shareholders to a minority position.
The transaction wasn’t publicly announced at the time. TouchBistro’s full cap table, preference stack, debt balance and sale waterfall remain private. The reported control change explains the direction of the outcome, but it doesn’t provide enough information to calculate each shareholder’s recovery independently.
Venture investors judged the result against the money invested. A fund can’t treat survival, employment or customer continuity as its primary return. It needs distributions large enough to offset losses elsewhere in the portfolio and return money to its own investors.
Harris judged the operating business differently. Constellation Software and its operating groups acquire vertical software businesses that can serve specialized customers for years. They can focus on recurring revenue, customer retention, product depth, pricing and cash generation without needing a venture scale exit.
TouchBistro doesn’t prove that founders should reject venture capital. The company used institutional backing to build products, enter international markets, acquire technology and compete in a category that required significant investment. A smaller financing plan may have produced a smaller business or allowed a larger competitor to overtake it sooner.
It does show why the amount raised can’t be separated from the type of company being built and the outcomes its market can realistically support. Every round assumes a future. Higher valuations require more growth. Preferred investment adds priority. Debt adds fixed obligations and control rights. A delayed IPO, weaker market or missed target can leave a founder running the same company under very different economics.
Canada’s debate often starts with whether founders can access enough money. The early stage funding funnel is narrowing, and Canadian companies still face a limited pool of domestic investors capable of leading large rounds. Those are genuine constraints.
TouchBistro raises the question on the other side. Once money becomes available, is it structured around the company’s likely growth, customer market and exit routes? Canada’s longstanding need for flexible growth financing includes equity, debt and hybrid products. Flexibility only helps when founders and boards understand what each instrument can claim later.
Founders can’t control pandemics, public market windows or every competitive threat. They can model the consequences of a financing before signing it.
What sale price clears the preferences?
What happens if growth takes twice as long?
Which covenants transfer control after a missed target?
Could the company accept a strategic offer without leaving common shareholders with nothing?
Does the business have a credible route to the outcome its investors require?
Those questions aren’t pessimistic. They’re part of building the company.
TouchBistro built software that restaurants still use. Harris acquired its products, customer relationships and industry expertise. The work continues under a Canadian software owner.
The financial outcome followed a different logic. The expected IPO never arrived. Private credit reportedly gained control. Earlier shareholders lost priority. The eventual sale appears to have preserved the operating business without satisfying the venture investment behind it.
That is the distinction founders need to see before the next round, not after the sale.
A valuable company isn’t automatically a successful venture investment. A large exit isn’t automatically a founder win. Investment that opens the next stage can quietly close outcomes that once looked available.
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jul 16, 2026 | NCFA Resource | Digital Assets, Capital Markets And Market Infrastructure
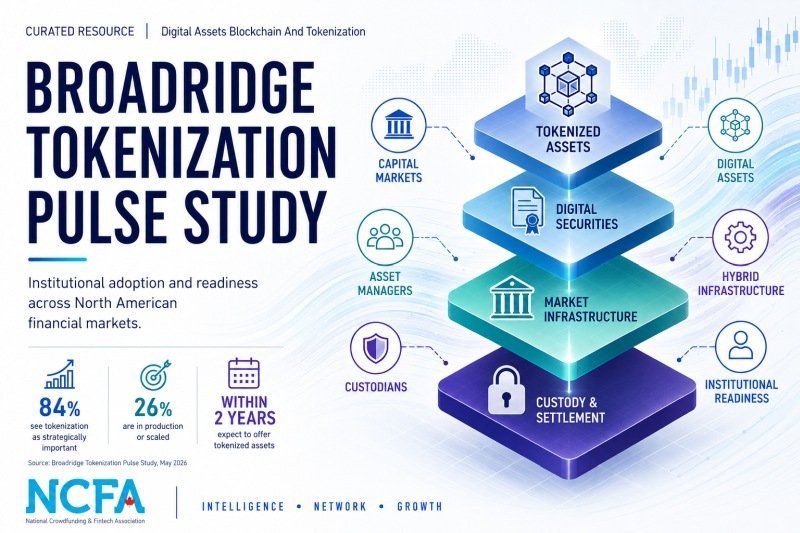
On July 16, 2026, Broadridge released its Tokenization Pulse Study, a survey of 200 senior financial services decision makers in Canada and the United States. The report examines adoption, investment, operating models, asset class priorities, and the practical barriers institutions face as tokenized assets enter production.
The findings show strong institutional interest with a wide gap between strategy and execution. While 84% of respondents consider tokenization strategically important, only 26% report being in production or operating at scale.
The study covers capital markets firms, asset managers, wealth managers, and digital asset firms. It compares their current activity, planned investment, expected adoption timelines, preferred infrastructure models, and reasons for pursuing tokenization.
Capital markets firms are furthest ahead, with 44% reporting production or scaled operations. That compares with 20% of asset managers and 9% of wealth managers. Nearly two thirds of all respondents expect to be ready to offer tokenized assets within two years.
The expected operating model is mainly hybrid. 92% believe traditional and digital assets will coexist for an extended period, while 69% plan to adapt existing infrastructure instead of building separate systems. This supports the view that tokenized financial infrastructure will need to connect with established market processes, governance, custody, distribution, and recordkeeping.
Asset classes are also developing at different rates. 80% expect tokenized mutual funds and money market funds to play a meaningful role within five years. Expectations for equities and private companies are closer to half of respondents.
This resource is useful for banks, custodians, dealers, exchanges, asset managers, wealth firms, market infrastructure providers, digital asset companies, investors, regulators, and technology teams.
It’s especially useful for organizations deciding whether to build, partner, integrate, or continue monitoring the market. The sector comparisons help readers judge how their own plans compare with North American institutions.
Strategy teams can use the report to compare stated priorities with actual production. The 84% strategic importance figure looks very different beside the 26% production rate. That gap helps identify where budgets, operating capacity, governance, and commercial demand still need work.
Product and infrastructure teams can use the asset class timelines to decide where near term demand is more credible. Mutual funds, money markets, and capital markets infrastructure currently show stronger institutional expectations than equities, private companies, or wealth distribution.
Canadian firms can also compare the findings with Canada’s stablecoin regulatory framework, securities regulation, custody requirements, and domestic market infrastructure. The survey includes Canadian respondents, but it doesn’t publish a separate Canadian data set.
The study’s main strength is its operating detail. It separates strategic interest from production, compares financial sectors, identifies preferred infrastructure models, and ranks regulatory, operational, commercial, budget, security, and organizational barriers.
Regulatory uncertainty was the most cited barrier at 33%. Operational complexity was especially important for capital markets firms, asset managers, and institutions managing more than US$250 billion. The results show that institutional interest alone isn’t enough. Firms still need workable governance, standards, controls, distribution, and a business case.
The study is commissioned by Broadridge, which provides tokenization infrastructure and related services. Readers should consider that commercial context when interpreting its conclusions. The sample is also limited to 200 North American decision makers, and the report does not provide country level results or independently test projected adoption timelines.
Broadridge Tokenization Pulse Survey Release (study findings and methodology)
Tokenization Starts Looking Like Financial Infrastructure (institutional market context)
Canada’s Stablecoin Regulatory Framework (Canadian regulatory context)
UK FCA Final Cryptoasset Rules (international regulatory comparison)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
```
July 15, 2026 | NCFA Market Activity | Cross Border Payments And FX, Banking And Credit, Digital Assets

On July 14, 2026, Flex raised US$70 million in a Series B1 led by Halo Fund and launched Flex Global, a cross border financial platform for internationally active business owners. The service combines multi currency accounts, payments, cards, private credit and stablecoin settlement while keeping the underlying digital asset infrastructure out of the customer experience.
The financing came six months after Flex raised a US$60 million Series B. Flex says it has now secured US$180 million in equity and US$300 million in debt. Reuters reported that the new round valued the company at about US$1.2 billion, based on information from a person close to the transaction. Flex didn’t disclose the valuation.
Flex Global extends the company’s private credit, business finance, personal finance, payments and financial operations platform into international accounts, currency conversion and stablecoin settlement. Flex says the service will support 32 currencies across more than 100 countries.
The customer doesn’t need to understand or manage the digital asset infrastructure. Stablecoins operate beneath a conventional financial interface while the business owner sees accounts, balances, payments and financial tools.
That design addresses a persistent gap between stablecoin payment potential and business adoption. Most companies aren’t looking for a token product. They want faster settlement, usable currencies, predictable access to funds and one record of what happened.
Flex is trying to make the underlying rail invisible while expanding the amount of the owner’s financial relationship it can control.
Flex Global is designed to let business owners hold and transfer value across markets through the same platform they use for credit, cards, payments and financial operations.
Stablecoins can provide a common settlement asset between two financial endpoints. The platform still needs to handle customer verification, currency conversion, transaction monitoring, liquidity, local payout access and reconciliation.
That operating bundle is more important than the token transfer itself. NCFA has seen the same model in Levl’s connection between bank and stablecoin rails, where the commercial product joins digital settlement with accounts, payment access and financial infrastructure.
Flex applies that mechanism to a direct owner relationship rather than selling infrastructure to another bank or payment company.
The customer value proposition is straightforward. An internationally active owner may currently use separate providers for business accounts, cards, foreign exchange, payments, working capital, expense management and personal finance. Flex wants to consolidate those products around one customer record and one financial interface.
Flex targets profitable middle market business owners whose needs often sit between small business banking and institutional private banking.
Founder and CEO Zaid Rahman has described the customer group as owners of businesses earning millions or tens of millions of dollars in annual revenue. They may manage several companies, international suppliers, personal investments, employees and private credit needs without the finance department of a large corporation.
The firm says it has onboarded a few thousand customers and is growing at roughly four times its prior year level. Reuters reported a nine figure annualized revenue run rate. The company plans to increase its team from about 110 people to more than 200 by the end of 2026.
Its platform brings several financial functions into the same commercial relationship:
Private credit gives Flex a different economic position from a payment application that earns mainly from transaction fees. The company can potentially earn across lending, interchange, payment services and software while using one product to distribute another.
Flex’s AI products support that integration. Beacon is positioned as a financial intelligence tool for owners, while the wider platform is designed to use customer financial data across credit and operating workflows.
Public disclosures don’t provide enough information to determine how much work its AI systems complete independently, how human review is applied or whether the tools improve financial outcomes. Those questions become more important as Flex handles more credit and payment activity.
The competitive group spans several fintech categories. Flex overlaps with:
The strategic difference is customer scope. Many competitors specialize in one financial job. Flex is trying to serve a narrow customer segment across several jobs.
That can improve distribution economics because the company doesn’t need to acquire a new customer for every product. It can also create operating complexity as more credit, payment, compliance and personal finance responsibilities sit inside one interface.
Stablecoin infrastructure is finding its clearest commercial role where conventional payment systems are slow, fragmented or unavailable outside banking hours.
Cross border business payments fit that profile. A company may need to coordinate foreign exchange, correspondent banks, payment cut off times, local accounts, compliance checks and reconciliation before the recipient can use the funds.
A stablecoin can shorten the settlement portion. It doesn’t complete the entire payment job.
The Noah and Cedar trade payment model shows how compliance, virtual accounts, foreign exchange and payout access must operate around stablecoin settlement before businesses have a usable product.
Flex is assembling similar functions inside an owner finance platform. The user may never hold a private key or choose a blockchain. Stablecoins become one part of treasury and payment execution rather than a separate asset decision.
That abstraction has commercial value because most businesses care about cost, speed, reliability and access to funds. They don’t necessarily care which settlement system transfers value between providers.
The model also creates dependencies. Flex must coordinate banking partners, stablecoin issuers, payment networks, liquidity providers and local market access. Customers will need clear information about where funds are held, which entity provides each service and what happens when a payment can’t be completed.
Canada’s regulatory position is becoming clearer after the enactment of its federal stablecoin framework. Implementation still depends on regulations, Bank of Canada supervision and alignment with payments, AML, securities and prudential requirements.
Canadian founders with international operations often assemble banking, cards, currency conversion, lending and treasury through separate providers. That challenge is consistent with Canada’s cross border interoperability gap, where strong domestic infrastructure hasn’t yet produced equally strong international payment performance.
Flex Global shows what a consolidated alternative could look like. It also creates a competitive question for Canadian banks and fintechs. Who owns the customer relationship when the payment rail becomes invisible and the platform spans both the business and its owner?
Flex is betting that middle market owners form a concentrated and valuable segment that conventional fintech platforms haven’t served as a complete financial category.
Cross border payments can become an entry point for accounts, cards, treasury, private credit and personal finance. Each product can supply more operating information and make the wider platform harder to replace.
The tension is execution. A product covering more than 100 countries can’t rely on one uniform banking, regulatory or liquidity structure. Availability may differ by customer location, business type, payment corridor, currency and partner.
Flex has raised enough capital to expand the platform, hire staff and acquire customers. The next proof is whether it can deliver reliable international financial services without passing the complexity underneath them back to the customer.
Will internationally active business owners consolidate banking, payments, credit and personal finance with one platform, or continue separating those services across specialized providers?
Zaid Rahman founded Flex to provide financial products for profitable middle market business owners whose business and personal needs often fall between small business fintech and institutional private banking.
FlexFinancial platform founded by Zaid Rahman
LaunchOwner focused financial products
Venture BackedInstitutional equity supports product development
United StatesProfitable middle market businesses
Business OwnersOwners with complex company and personal finances
Segment FocusPositioned between small business fintech and private banking
Flex began with a defined customer segment rather than one narrow product. That customer focus created room to add credit, payments, business finance and personal finance around the same owner relationship.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 15, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, Banking And Credit, Artificial Intelligence And Data

On July 15, 2026, Clutch launches its Lending Automation System (LAS), an end to end lending automation platform built specifically for credit unions. Twelve institutions ranging from US$256 million to US$6 billion in assets have selected it.
The product is designed around a different operating assumption than a conventional loan origination system. Straightforward applications can proceed from intake through decisioning and funding without waiting for a lender to manually advance each step. Applications that need judgment enter a structured staff workflow with the relevant member data, policy checks and required tasks already organized.
Clutch says institutions using the platform have recorded a 1.4x increase in funded loans, application and account opening times that are 2 to 4x faster, and 70% to 85% of loan applications processed automatically through fraud screening and underwriting, with the remaining applications routed to staff when judgment is required. Those are company reported results, but they describe a more substantial operating change than placing a digital form in front of an existing manual process.
The commercial issue is lending capacity. Credit unions compete through member knowledge and relationship service, yet many still rely on staff intensive workflows that become more expensive as application volumes rise. Clutch is trying to separate the loans that require judgment from those that mainly require verified data, policy execution and process completion.
The system combines three parts.
Digital Account Opening and Loan Origination captures applications through online, mobile, branch, call centre and dealership channels. Clutch says the application process can take less than five minutes.
Fastlane applies the credit union’s lending policies, bureau information, verification data and existing member relationship data. That can include account history, prior repayment behaviour, tenure and the depth of the member’s relationship with the institution. The system then sends eligible applications toward funding or identifies the files that need further review.
Clutch Fulfillment handles the exception workflow. Instead of presenting staff with a general queue and an incomplete file, it creates specific tasks, surfaces the relevant context and enforces the credit union’s policy requirements.
Automation is useful when the institution already knows what decision it would make if the required data were available and verified. Human review remains valuable when:
The platform therefore doesn’t eliminate underwriting judgment. It concentrates staff attention on the applications where judgment has more value.
Nicholas Hinrichsen, Co-founder and CEO of Clutch:
“Some loans don't need a person in the middle, they need a system that can move at the speed the member expects.”
Clutch’s operating claim is that a long standing member with strong repayment history and substantial savings shouldn’t wait several days for a routine answer. The risk is that relationship data, automated verification and policy logic still need to be accurate, explainable and consistently governed. Faster processing doesn’t reduce the lender’s responsibility for fair lending, fraud controls, model oversight or credit performance.
The U.S. credit union system remains large but continues to consolidate. The National Credit Union Administration reported 4,250 federally insured credit unions, 145.8 million members, US$2.48 trillion in assets and US$1.73 trillion in loans at the end of the first quarter of 2026. The number of institutions fell by 161 over 12 months.
Operating costs are also rising. NCUA data show non interest expense increased 7.6% year over year in the first quarter, with employee compensation and benefits accounting for more than half of the increase. That creates a direct commercial case for software that can process more applications without requiring staffing to rise at the same rate.
Clutch’s launch group spans institutions with US$256 million to US$6 billion in assets. That range is important because smaller credit unions usually have less technology staff, less capacity to manage complex integrations and fewer specialized underwriters. A phased model that begins with digital intake and automated decisions, then expands into full workflow automation, may be easier to adopt than a complete lending-system replacement.
A San Francisco company Clutch was founded in 2020 by Nicky Hinrichsen and Chris Coleman. It raised a US$65 million Series B in January 2025, bringing total reported funding above US$106 million, and launched its Fastlane automated decisioning and fulfillment engine in July 2025. Clutch now says it serves more than 175 credit unions and 25 million members.
Its reported scale gives LAS a distribution advantage. The company can sell the new system into an installed base already using its origination, deposit opening and engagement products. It can also draw on operational data from multiple institutions when refining product workflows, although each credit union still needs its own policies, controls and risk tolerances.
Clutch competes in a crowded field that includes core banking providers, loan origination vendors, digital onboarding platforms and automated underwriting companies. MeridianLink, Origence, Jack Henry, nCino, Blend, Amount, Fiserv and Finastra all address parts of lending intake, decisioning, workflow or servicing.
The distinction Clutch is offering is credit union specialization. It says LAS was developed over two years with credit union leaders and is priced, integrated and designed around the cooperative operating model rather than adapted from a general bank platform.
A platform that joins application capture, automated decisioning and exception handling can reduce handoffs between products. Each handoff creates delay, duplicate work and another opportunity for the member to abandon the application.
NCFA has already seen the same operating pressure in adjacent lending markets. Conexus backing JUDI.AI connects credit union capital with AI cash flow underwriting for small business loans. TD’s Trust Science deployment brings income verification and AI decisioning into a large bank lending workflow. FintechWerx’s Ruby Loans agreement targets AI-native SME origination for credit unions.
These systems address different borrowers and institutions, but the pattern is consistent. Lending technology is progressing from front end digitization toward data verification, decisioning, workflow control and funding.
For Canadian credit unions, the Clutch launch is relevant even though the initial deployment is U.S. focused. Canada is already seeing coordinated digital banking modernization. Canadian institutions face different provincial rules, market structures, core providers and lending practices. Can relationship based lenders automate routine credit work without weakening oversight or losing the human judgment that differentiates them?
Can credit unions automate enough of the lending process to compete on speed while preserving the relationship judgment that differentiates them?
Nicky Hinrichsen and Chris Coleman founded Clutch in 2020 and focused the company on digital lending for credit unions. The initial product helped institutions originate loans online without replacing their core systems.
ClutchFounded by Nicky Hinrichsen and Chris Coleman
LaunchDigital lending for credit unions
Venture BackedEarly institutional funding supports product development
United StatesCredit union market
Credit UnionsCommunity and cooperative financial institutions
Digital OriginationCompetes with lending technology and origination providers
Clutch entered through a defined institutional market rather than selling a general lending stack. That focus created the product knowledge and distribution base for a wider credit union operating platform.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016