




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 14, 2026 | NCFA Market Activity | Capital Markets Infrastructure And Funding, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data
On September 14, 2026, Paris-baesed digital asset firm Kaiko raised US$110 million in a Series B extension led by S&P Global. RBC joined BNP Paribas, Nasdaq Ventures, Bpifrance, Broadridge, Coinbase Ventures, DRW Venture Capital, Canton Foundation, Stellar and Susquehanna Private Equity Investments. Existing shareholders Anthemis, Point Nine and Revaia also participated.
Kaiko plans to invest the capital in its market data business and services for onchain capital markets. Its coverage spans more than 150 exchanges and protocols, with data used for pricing, trading, valuation, risk, surveillance and benchmarks.
S&P Global, RBC, Nasdaq, BNP Paribas and Broadridge bring something beyond capital. They operate businesses that depend on reliable prices, benchmarks, market data and institutional distribution. Their investment gives Kaiko deeper relationships with firms that could also become customers, partners or distribution channels as tokenized securities and digital assets enter more institutional products.
S&P Global was already working with Kaiko before leading the round. On September 1, S&P Dow Jones Indices and Kaiko launched the S&P Kaiko Digital Asset Indices, bringing more than 4,000 rates and indices into one suite. Kaiko provides digital asset data, calculation and connectivity across more than 150 exchanges, while S&P DJI brings benchmark administration, licensing and global distribution.
The relationship also reaches tokenized traditional assets. Earlier work brought the iBoxx U.S. Treasuries Index onto the Canton Network, giving onchain applications access to an established fixed income benchmark. S&P is therefore investing in a company it already uses across digital asset pricing, benchmark production and onchain data delivery.
RBC's participation puts a major Canadian bank alongside global exchanges, banks, data firms and digital asset investors backing Kaiko's expansion.
A tokenized bond or fund still needs a defensible price. Banks and asset managers also need reference rates, liquidity data and valuations that can flow into trading, collateral, risk, reporting and settlement systems across digital asset markets. Those requirements become harder when assets trade across multiple exchanges, blockchains and around the clock.
Institutional adoption is already growing in tokenized collateral and cash markets, where pricing, valuation and settlement quality directly affect whether products can scale.
Kaiko provides market data feeds, analytics, indices, pricing and monitoring tools. Its onchain services can also deliver licensed data directly into blockchain applications. That gives the company exposure to several parts of the market without depending entirely on crypto trading volumes.
The investors will participate in a Strategic Industry Working Group chaired by Kaiko and focused on data for tokenized capital markets. Nothing formal has been disclosed yet but there will be lots at the table including banks, exchanges, financial data firms, blockchain networks and market technology providers with different requirements for pricing and using tokenized assets.
So what does this mean for traditional data companies? Building digital asset expertise internally takes time, specialist market knowledge and direct connections to fragmented venues. Investing in firms such as Kaiko can give established providers access to those capabilities while they contribute distribution, benchmark credibility and institutional clients.
Coin Metrics competes for institutional market, network and reference data. Lukka is strong in valuation, accounting and audit data. CoinDesk Data competes in digital asset benchmarks and market information. Bloomberg and LSEG have much larger enterprise distribution and can add digital asset products to platforms already embedded inside banks and investment firms.
Kaiko brings deep digital asset expertise in pricing, benchmarks and institutional data. S&P's investment can help Kaiko reach more financial institutions, but it also highlights the competition. Large data companies already have the customers, distribution and capital to partner with specialists, buy them or build similar capabilities themselves.
Kaiko will need more revenue from indices, tokenized assets and enterprise data if it wants to rely less on crypto trading activity. The working group only becomes strategically beneficial if it leads to products, common data practices or stronger links into existing financial systems.
S&P Global isn't just buying exposure to crypto growth. It is backing specialist data capability it already uses. If tokenized markets scale, reliable pricing and benchmarks may be one of the harder and more valuable pieces for financial institutions to recreate themselves.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
September 11, 2026 | NCFA Regulatory Insight | Artificial Intelligence And Data, Regulation And Policy, Risk Compliance And Regtech
On September 9, 2026, the Government of Canada launched a National AI Literacy Initiative with the Alberta Machine Intelligence Institute. The $13 million partnership is expected to reach up to 1 million post secondary students and more than 50,000 K to 12 educators, alongside free learning for workers and other Canadians. The program sits under Canada's AI for All strategy and focuses on helping people understand AI, use it responsibly and recognize risks such as bias, misinformation and privacy loss.
Ottawa is working on the governance side at the same time. Its AI transparency consultation remains open until September 23 and asks whether Canada needs stronger ways to identify AI generated content, tell people when they are interacting with AI, explain system capabilities, track serious incidents and record what AI agents actually do. The consultation paper says 19.2% of Canadian companies used AI to produce goods or deliver services in the second quarter of 2026, up from 12.2% a year earlier and three times the 2024 level.
The federal government has already been working through many of those questions for its own use. On May 22, it published an agentic AI guide for departments and agencies. Ottawa says agentic AI is defined more by what a system “does” than what it produces because these systems can plan tasks, use tools, interact with other systems and act with limited human supervision.
The guide does not create new legal requirements for banks, fintechs or other private companies. It does offer a useful view of how Ottawa thinks AI governance changes once software gets permission to act rather than simply produce an answer.
Ottawa describes four levels of autonomy.
The government says agents generally provide the most value on work that is repeatable, time consuming and verifiable, with people retaining oversight and clear accountability. It flags higher risk uses in grants, procurement, regulation, financial decisions and services that affect people's rights or access.
The first agent specific principle is bounded autonomy. An agent should receive only the data, tools, permissions and authority required for its job. Ottawa recommends permission levels such as “draft only” and “read only,” along with data limits, rate limits, unique agent IDs and a clear indication of whether an agent is suggesting an action or actually carrying it out.
Actions that send, publish, approve, spend or update records should normally require human confirmation unless the expected impact is low and easy to reverse. Teams are also expected to test hostile inputs and realistic edge cases before granting wider permissions. Access can expand as the organization gains evidence that the controls work.
Ottawa's second principle is recoverability. Organizations should be able to pause or stop an agent, return systems to a safe state and reconstruct what happened. The guide recommends logs the agent cannot alter, external pause controls and recovery plans for actions that can't simply be undone.
The guidance assumes agents, tools or credentials may eventually be compromised. Federal teams are told to preserve time stamped records, use previews and human approvals where appropriate, and plan for recovery before deployment. These controls become particularly important when an agent can change another system, spend money or trigger an action that can't be cleanly reversed.
Every agent also needs a named human owner. Accountability stays with that person even when the agent acts autonomously inside approved permissions. If ownership becomes unclear, the agent should be paused or deactivated. When an employee changes roles or leaves, responsibility and access should be formally transferred or removed.
Ottawa also tells teams to watch for changes in quality and behaviour as tools, data and settings change. Spot checks, comparisons with human work and fresh risk assessments are recommended when permissions, data sources, scope or legal requirements change. Retiring an agent means removing its access, preserving required records and documenting what was learned.
Prompt injection gets specific attention because agents can read outside material and then act on other systems. Ottawa says emails, documents and user supplied content should be treated as data to analyse rather than instructions to follow automatically. An attacker who manipulates an agent's input becomes much more dangerous when that agent can also access accounts, update records or trigger transactions.
The current AI transparency discussion paper asks whether organizations should disclose when agents are used, what actions they can take, how human oversight works and how responsibility can be traced when agents interact with one another. Ottawa also discusses detailed activity logs, digital identity credentials and tools that monitor agent behaviour, while noting that some of these approaches are still developing.
Canada currently does not have a regulatory framework specifically governing agentic AI. Existing consumer protection and civil liability rules can still apply when AI systems cause harm, while regulated firms already have obligations around privacy, security, records, supervision and operational risk. The consultation is asking for input on possible transparency measures, not announcing new private sector requirements.
For financial institutions, the buying questions already exist. A bank giving an agent access to customer records, payments, trading, underwriting or compliance systems will want to know whose identity it uses, exactly what it can access, which actions require approval, where its logs are stored and how quickly access can be shut off. Questrade's AI brokerage access offers a practical Canadian example of why permissions and customer approval become important once an agent reaches financial accounts.
Vendors also need credible answers on permissions, ownership, auditability, recovery and security. Narrow access can make early deployment easier, strong logs can simplify audits and investigations, and clear ownership reduces the risk of agents remaining active after staff or vendors change.
These controls also affect cost and adoption. Firms need people and systems to manage identities, permissions, testing, logs, incidents and retirement. NCFA's analysis of the cost of deploying AI shows why governance is becoming part of the commercial case for enterprise AI rather than a separate compliance exercise.
Canada is funding AI adoption while getting more specific about how autonomous systems should be controlled. For financial firms, the advantage will go to AI vendors that can prove who owns an agent, what it can do, what it did and how quickly it can be stopped.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 11, 2026 | NCFA Market Activity | Artificial Intelligence And Data, Wealthtech Investing And Trading, Risk Compliance And Regtech
On September 10, 2026, OpenAI launched ChatGPT for Financial Services, a version of ChatGPT Work built for finance around GPT-6 Astra, premium financial data, connected firm information and tools for research, modelling and client materials. OpenAI developed the product with Morgan Stanley and Evercore as design partners, starting with investment banking and equity research.
A financial institution no longer has to start with a general AI model and then separately connect every data source, build research workflows and figure out how the output gets into a valuation model, research note or pitchbook. Some of that assembly work now comes inside the product.
That positions ChatGPT closer to the type of work bankers and analysts produce every day. It also puts OpenAI into more direct competition with fintech copilots, research platforms and financial software vendors building similar workflows around third party AI models.
ChatGPT for Financial Services includes premium datasets from providers such as Daloopa, PitchBook and LSEG News. OpenAI says the available data covers areas including earnings transcripts, financial statements, company fundamentals and private companies. Teams can start using supported datasets that are included without negotiating separate contracts or configuring their own connectors.
The scope still depends on the provider and dataset. PitchBook says users get access to its expanded Essential dataset, including firmographic information on companies, investors and funds. OpenAI's terms also set rules for each provider around timing, storage, copying and reuse.
OpenAI indexes and hosts supported partner data on its own infrastructure so the system can retrieve it faster and attach citations to figures and claims. In finance, analysts need to know where their numbers came from, which period it covers and whether the source supports the conclusion.
There are real limits. OpenAI's Financial Services Terms say data and outputs may be inaccurate, incomplete, delayed or outdated. Daloopa data listed in the terms is delayed by 24 hours, while Nasdaq pricing supplied through Financial Modeling Prep is delayed by at least 15 minutes. Those details become important when the same system is used for research, valuation work and client materials.
For financial data companies, ChatGPT can become another route to institutional users. OpenAI gets licensed data closer to the research workflow, while the provider keeps control over how its underlying information can be copied, exported or reused.
OpenAI is also going after the work produced after the research. Administrators can publish approved Excel, Word and PowerPoint templates so teams can turn analysis into valuation models, research notes, pitchbooks and other documents in the firm's own format and style.
Investment banking and research teams spend a lot of time getting numbers, commentary and analysis into the right spreadsheet, memo or presentation. If AI can produce that work using approved templates, companies can cut production time without rebuilding the workflow around a separate tool. Morgan Stanley and Evercore helped OpenAI identify those pain points. OpenAI says reliable data access and high quality artifact creation were among the biggest problems raised through the design work. The announcement doesn't say either firm has deployed ChatGPT for Financial Services across its entire organization at this point.
Fintech copilot models that mainly wrap a large language model around research or document creation now face tougher competition. Specialists still have room where they own proprietary data, regulated workflows, execution capability, integrations built for individual institutions or financial expertise that a general platform can't easily reproduce. NCFA recently looked at decision intelligence in financial services which highlights a similar competitive issue. Access to data matters, but the firms creating the most value will be the ones that turn it into better research, decisions and client outcomes.
ChatGPT for Financial Services includes enterprise controls such as SAML SSO, SCIM provisioning and access controls by role. OpenAI says business data is not used to train its models by default, data is encrypted at rest and in transit, administrators can configure workspace retention, and supported workspace logs can be exported through its Compliance Platform.
Those controls help firms manage who gets access and what information can be used. They don't make a bank, dealer, investment firm or advisor compliant by themselves. Each institution still has its own obligations around privacy, records, supervision, model risk, client information and material information that isn't public.
Its Financial Services Terms say the service provides information and tools for financial research and analysis and that OpenAI does not provide financial or investment advice. Users are told to apply independent professional judgment and check important sources, dates and calculations before relying on the output.
That keeps responsibility with the institution. Citations can make research easier to check and firm templates can make the output easier to use, but someone still has to stand behind the analysis, recommendation or client communication.
OpenAI is making general finance copilots easier to copy and harder to defend. Fintechs will need an edge in proprietary data, regulated execution, deep workflow integration or trusted financial expertise to compete.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Explore and compare companies in Canada’s open banking market by capability, market layer, documented Canadian traction and selected global benchmarks, from financial data and bank infrastructure to payments, business systems and intelligence.
Loading market map…
Learn how open banking and consumer-driven finance work, use Canadian market evidence alongside leading international examples, test key claims, and apply what you learn to product, operating, investment and policy decisions.
Choose A Topic (match it to your product, investment or policy question)
Choose A View
Gain Practical Insight
Start with the decision in front of you. Work through one topic or use the full guide to connect regulation, infrastructure, products, competition, adoption and risk.
Connect customer permission, standards, shared infrastructure, business models and trust.
See what could slow launch, adoption, scale or commercial value.
Compare who pays, who benefits, where margins sit and what evidence is still missing.
Separate announcements from operating evidence, activity from adoption and access from outcomes.
Search the full 146-module guide or narrow it by the perspective most relevant to you.
Search the full guide or narrow the modules by the decision or market question you are working on.
Explore selected current and emerging Open Banking discussions through verified market evidence, competing commercial cases and NCFA insight. Cast your view and compare with the market as participation builds.
Canada’s first phase has to prove that data access can improve real financial tasks before payment initiation arrives.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
The near term opportunity is strongest where better data cuts underwriting time, verification cost or manual work. If those services do not generate repeat use, payment initiation becomes more important to the commercial case.
Canada must decide how much operating evidence it needs before moving from data access into customer authorized payments.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
A staged rollout tied to transaction risk and proven operating performance would let Canada add useful functionality without treating every payment use case the same.
Compliance costs can protect consumers and still become a barrier if they do not reflect the activity and risk of the participant.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Consent, security, liability and consumer redress need a firm baseline. Other obligations should track the activity, exposure and risk a participant creates. If smaller firms carry costs that do not reduce material risk, the framework can weaken the competition and consumer choice it is meant to support.
Private agreements and industry standards continue to develop while the federal framework remains unsettled.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Commercial data sharing can keep growing without a settled federal rule. The competitive issue is who controls access terms. Continued uncertainty favours firms with the scale to negotiate bilateral arrangements and absorb repeated integration costs.
The UK has proven demand for Open Banking. The commercial test is whether payment services can fund continued investment without restricting access.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Paid services make sense when they deliver functionality, service levels or risk controls beyond the baseline. Charging for ordinary access too early can weaken fintech economics and reduce the demand needed to support a durable market.
Australia shows what happens when a mature data right expands faster than the ability to complete customer actions.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
More data can improve advice, comparison and underwriting. Action becomes more valuable when it removes a meaningful customer step. The case for wider authority should be judged against the friction it removes and the additional fraud, consent and liability risk it creates.
The UK now has to decide how standards should be governed once the market is established and commercial interests are stronger.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Standards need to adapt faster than legislation without giving the largest participants control over market access. Funding, technical administration, consumer representation and statutory enforcement should remain clearly separated.
AI agents can progress from reading financial data to recommending and executing financial actions.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
The key control is authority. Customers need clear limits on what an agent can do, for how much, for whom and for how long. Auditability, revocation and liability become more important as autonomy increases.
Brazil links Open Finance to a high frequency payment system, giving customers an immediate reason to use connected financial services.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Brazil shows the value of pairing data access with an action customers already understand and use frequently. Canada does not need the same payment model, but its early data services still need to solve problems often enough to create repeat behaviour.
Open finance can improve advice and competition, but every additional data category increases consent, privacy and implementation complexity.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Wider access is most useful when the additional data changes a financial decision or removes customer friction. Scope should follow clear use cases, with common identity, consent and liability controls reducing the cost and risk of expansion.
Explore commercial opportunities in Canadian open banking, consumer-driven finance, data access and financial infrastructure, then assess where new products and business models may be viable.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 11, 2026
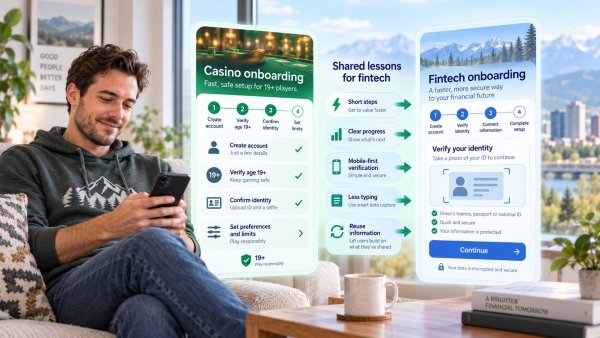
A new user does not care how many systems sit behind a sign-up screen. They care about something much simpler: how quickly can they get started?
That question matters for Canadian fintechs in 2026. Consumer-driven banking is moving forward, digital identity tools keep improving, and people are growing used to services that feel immediate on a phone.
The lesson is not to remove important checks. It is to make those checks feel like a natural part of the product.
Regulated gambling offers an interesting UX lesson because account creation has several moving parts. User details need to be collected, identity has to be confirmed, and the whole process needs to work smoothly on a small screen.
What stands out is how much of that complexity can stay behind the interface.
A person creating an account at Betinia Ontario (19+), for instance, moves through a digital registration journey where account details and verification form part of the same experience. For a user, that matters. The process feels connected rather than split into separate administrative steps.
Canadian fintechs can borrow that thinking.
Ask for information when it becomes relevant. Keep each screen short. Tell the user why a document or detail is needed. Show progress without filling the screen with technical language.
Little things add up.
Identity checks used to feel separate from the main product experience. You signed up, then got pushed into another process.
That distinction is disappearing.
Canada already allows several forms of remote identity verification under federal guidance. Phone cameras, document checks and digital records can turn what was once a desk-based process into a mobile interaction.
For product teams, this changes the design question.
Instead of asking, “Where do we put verification?”, it may be more useful to ask, “How do we make verification feel natural?”
The answer often comes down to interface details. A clear camera prompt is better than a paragraph of instructions. A progress bar can reassure someone that only a few steps remain. Pre-filled information can remove needless typing.
None of this sounds revolutionary. That is partly the point. Good onboarding often feels simple because somebody did the complicated work behind the scenes.
There is another lesson worth stealing: people dislike repeating themselves.
If a customer has already supplied a name, address or account detail, asking for it again creates a strange little pause. It feels as though two parts of the product are not talking to each other.
Fintech teams can remove much of that friction by designing onboarding as one continuous conversation.
Information should move with the user. Screens should remember what came before. Permissions should appear at the moment they make sense.
Think of it as good hospitality. If someone has already introduced themselves, you do not ask their name again five minutes later.
Digital products should show the same basic courtesy.
The timing is especially relevant for Canadian financial services.
Canada has been moving ahead with its consumer-driven banking framework, which is designed to give consumers more control over how their financial data is shared between approved services. The country is also preparing for faster payment infrastructure through the Real-Time Rail.
These developments point toward a more connected financial experience.
As secure data sharing becomes easier, onboarding could involve less manual entry. A customer may be able to authorize access to information that already exists rather than filling out another long form.
That changes expectations.
If money and data can move quickly, opening an account should not feel stuck in an older era of paperwork and repetitive fields.
Onboarding is often discussed as a conversion metric. For fintechs, it is much more than that.
It is the customer’s first real experience of the company.
A clean flow says the product is organized. Clear explanations show respect for the user’s time. A short series of well-designed steps makes complicated technology feel manageable.
That first minute can set the tone for everything that follows.
Canadian fintechs do not need to copy the gambling sector itself. The useful lesson sits in the product mechanics: short steps, mobile-first verification, clear progress, smart reuse of information and fewer unnecessary interruptions.
When those pieces work together, onboarding almost disappears.
And that may be the best sign that it has been designed well.
Online gambling in Ontario is restricted to those 19+. Support resources: ConnexOntario, 1-866-531-2600.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 10, 2026 | NCFA Market Activity | Cross Border Payments And FX, Digital Banking And BaaS, SME Finance And Business Banking
On September 9, 2026, Toronto and Montreal fintech Beacon announced an oversubscribed C$20M financing round as it expands financial services between Canada and India. Existing investors led the round, with new investors participating. Beacon also says its user base doubled in seven days on C$11,000 of advertising and that the app reached the #1 Finance position in Canada's App Store. The company hasn't disclosed how many users, active customers or transaction volume, so the growth claim shows demand without telling us how large the business has become.
Beacon was founded in 2023 by Stuart Szabo and Aditya Mhatre around a problem newcomers know well. Moving to Canada can mean opening accounts, moving savings, paying bills and maintaining financial obligations in another country at the same time. Its earlier C$5.25 million seed round helped build around that need.
The product set shows how far that idea has travelled.
Beacon is trying to turn one cross border relationship into several recurring financial services. The C$20 million gives the company more room to build around everyday money, remittances, bill payments and business payments across the same corridor.
Cross border finance becomes more valuable when several recurring problems belong to the same customer. Someone living in Canada may be supporting family in India, paying a loan or utility bill there, receiving money from India and running everyday finances here. Beacon now addresses each of those jobs in some form, which gives it more opportunities to stay relevant between remittance transactions.
Beacon's UPI transfers let users send Canadian dollars to an Indian UPI ID or bank account, with Beacon saying 98% of UPI transfers arrive within a minute. India Bill Pay uses Bharat Connect for expenses such as utilities and loan payments. Customers can use familiar Indian payment methods while funding transactions from Canada.
Canada and India are also allocating more attention on these flows. Recent Canada India UPI talks included cross border remittance and merchant payment cooperation. Competition is building too. Skydo's Canada launch added another specialist targeting Canada India business payments.
Cost remains important. World Bank data for the third quarter of 2025 put the average cost of sending C$200 from Canada to India at 4.28%, including fees and foreign exchange margins; the average for C$500 was 2.69%. Banks, Wise, Remitly and other providers already compete heavily on rate, speed and reliability, which makes a wider product relationship more valuable than another transfer option.
Beacon Business adds a second customer type. Registered Canadian companies can fund locally and pay Indian businesses or individuals through local payment rails, with Nium supporting parts of the service. Consumer finance and SME payments can therefore develop around the same Canada India expertise, banking relationships and regulatory work.
A remittance customer typically has little loyalty if another provider offers a better exchange rate tomorrow. Beacon's response is to give that customer more reasons to keep using the app. Everyday Canadian money, UPI transfers, Indian bill payments, incoming transfers from India and business payments all sit around the same cross border relationship.
That can improve the cost structure of acquiring a customer. Someone who sends money home a few times a year may generate limited revenue. A customer who also keeps money on the platform, pays bills and uses other financial services creates more transactions and more opportunities for Beacon to earn over time. Some may eventually bring business payments onto the platform too.
This corridor focus can help Beacon compete with much larger firms. Wise and Remitly operate across many countries and currencies. Canadian banks have huge customer bases and established financial products. Beacon can go deeper on Canada India use cases, integrate local payment methods and build around customers whose financial lives genuinely span both countries.
That focus still depends on several regulated relationships. Beacon is registered with FINTRAC as a money services business and says it is registered with the Bank of Canada as a payment service provider under the Retail Payment Activities Act.
Beacon started by helping people arrive in Canada. It's now building around the financial ties they keep with India and the businesses some of them go on to run. The strategic question is whether corridor specialization compounds. Better product knowledge, reusable regulatory work, customer referrals and a growing product set can all improve the value of the same customer relationship. If Beacon can keep extending that relationship rather than buying a new customer for every product, the C$20 million round funds something more interesting than another remittance app.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 9, 2026 | NCFA Insight | Capital Markets Infrastructure And Funding, Competition And Market Structure, SME Finance And Business Banking
On September 9, 2026, RBC announced a C$1.4 billion Canadian technology initiative anchored by RBCx Growth Fund I. The proposed fund will make direct late stage equity investments in Canadian technology companies with global ambitions. RBC plans to invest up to C$416 million, or US$300 million, including an initial US$200 million commitment to portfolio companies.
The C$1.4 billion headline encapsulates the wider initiative, not the size of RBCx's Growth Fund I. But its disclosed something more interesting: equity will be invested alongside commercialization support, strategic partnerships and access to RBC's banking, capital markets and public sector relationships.
RBCx already has reach. It says it banks 3,500+ technology companies, has invested in 10 venture funds and more than seven companies directly, and operates four RBC owned ventures. Fintech runs through part of that history: Mydoh has reached more than 140,000 Canadians, Ownr has registered or incorporated more than 130,000 businesses, and Dr.Bill has processed C$4.1 billion in medical billings for more than 14,000 physicians.
The new fund has a broad mandate spanning enterprise software, AI, cybersecurity, health tech, frontier technology, energy, climate and agricultural technology. Its strategic value comes from the model around it. RBCx can potentially combine equity, venture debt, banking, customers and capital markets support across the same company lifecycle.
Canadian companies do not become global competitors because someone writes a larger cheque at Series C. They get there by building management depth, repeatable sales, enterprise customers, regulatory capability, financial controls, technology that can handle growth and enough distribution to reach new markets. Those capabilities need to start forming years before the biggest financing round arrives.
The capital data shows how narrow the funnel becomes. Canadian venture investors deployed C$2.69 billion across 250 deals in the first half of 2026, yet only 18 later stage deals accounted for C$984 million. Sixteen rounds of C$50 million or more absorbed 59% of all venture dollars, while RBC cites PitchBook data showing Canadian investors led only 33% of domestic growth rounds over the past decade.
There is pressure further upstream too. Canadian VC fundraising fell to just over C$2.1 billion in 2025, with the five largest funds capturing 83% of the capital raised. When fewer funds have enough capital to support companies through multiple rounds, fewer startups get the time and resources needed to build serious operating capability.
That is the bigger Canadian issue. Founders need capital, but they also need customers, talent, workable regulation, financial infrastructure and enough room to execute. International growth only gets harder when those capabilities are weak at home. If too few startups build them early, there will be fewer strong growth companies and even fewer Canadian firms capable of competing globally at scale.
This is where RBCx could be more useful than another pool of equity. A scaling company may need venture debt, operating credit, FX, treasury, foreign accounts and enterprise customers while it is raising its next round. RBCx already works across many of those needs, which gives founders a chance to build financial and commercial capacity before the company becomes large enough to attract the biggest investors.
Customer access is another valuable part. RBC says portfolio companies may receive commercialization support, customer strategy help and introductions through its commercial banking, capital markets and public sector relationships. Founders will care about what those introductions produce: paid pilots, enterprise contracts, distribution and follow on capital.
RBC has a clear commercial incentive in seeing those companies grow. A startup that becomes a large technology company can eventually become a valuable client across lending, treasury, FX, employee banking, wealth and capital markets. RBC has not stated customer lifetime value as the motive for Growth Fund I, but the economic alignment is obvious.
BDC and Canadian venture firms already supply growth capital, so success shouldn't necessarily be measured by dollars deployed. A better measurement may be whether RBCx backed companies win larger customers, build foreign revenue faster, raise future capital from a stronger position and keep meaningful operating capability in Canada. That connects directly with Canada's productive growth challenge where promising companies need enough capital and operating capacity to become globally competitive businesses.
Canada's scaleup problem starts well before the scaleup round. RBCx already works across banking, venture investing and technology businesses, and Growth Fund I adds equity to that mix. If the combination helps more Canadian companies build customers, capability and financing strength early enough to compete globally, the initiative will have earned its C$1.4 billion headline.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016