




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 1, 2026
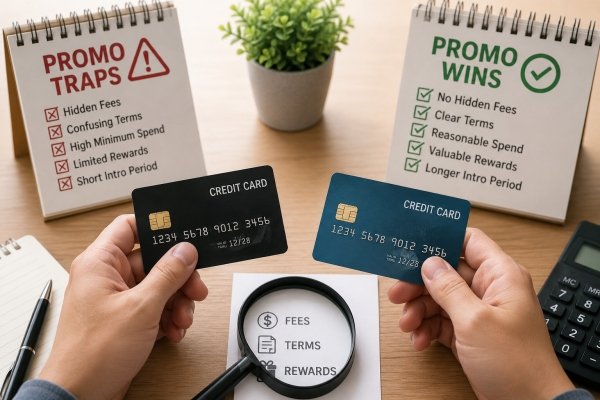
Issuers have plenty of strategies to make credit cards more appealing, and one of these is offering promotional deals that come with extra benefits or rewards for new applicants. These promos are often designed to give potential cardholders a head start on earning rewards, allowing them to maximize value from their spending while also testing the card’s features. However, not all credit card deals are legitimate. Some may seem attractive at first, but they’re actually traps that offer misleading promises to consumers or take advantage of them through hidden fees and costs.
Knowing what a genuine credit card deal looks like can help you avoid making costly mistakes or falling victim to fraudulent schemes. Here are key indicators to look for when evaluating a promo.
A promo’s credibility often depends on who is offering it. Deals from established card issuers are more likely to deliver what they promise, since these institutions want to protect a reputation built on honesty and reliability. If you want to make sure that your rewards and benefits will actually be honored, it’s a good idea to check the issuer’s track record before applying. This way, you can avoid deals with vague mechanics or misleading rewards.
Take Maya, as an example. Considered to be the #1 digital bank in the Philippines, Maya is a widely trusted platform by many Filipinos. More than that, it’s also regulated by the Bangko Sentral ng Pilipinas, which means it follows strict rules to protect customers. Considering these, you can be confident that any Maya credit card promo you choose offers legitimate rewards and honors your rights as a consumer.
Clear and fair introductory rates are tell-tale signs that you can benefit from a credit card promo. A good offer will specify the interest rates for purchases, balance transfers, or cash advances, as well as how long the introductory period lasts. Having access to this information enables you to plan your spending and understand the costs of credit card ownership upfront, which reduces surprises while building your confidence in the deal.
A good credit card promo also has competitive rates. These reflect fair pricing compared with other cards and provide assurance that you’re not overpaying for the perks offered by the credit card promo. To find out if the rates are truly competitive, it’s helpful to compare them with similar cards and check for any additional fees that might apply. This will let you identify promos that genuinely save you money and avoid ones with hidden costs.
Some card promos require you to meet a spending threshold within a set period—usually a few months—to qualify for rewards. A credit card deal that works in your favor wouldn’t impose extremely high minimums that can create stress or even lead you to debt. A promo that matches your lifestyle often aligns with your normal spending habits, meaning you can realistically achieve the rewards without overspending. The minimum spend will depend on the type of card, with premium cards having much higher thresholds than standard cards. Knowing your typical monthly spending can help you find a promo that can complement and even reward the way you manage your finances.
A winning promo clearly explains how to earn and redeem rewards. The steps to qualify for bonuses should be simple and easy to follow, without confusing requirements. Transparent mechanics allow you to understand exactly what actions are needed to benefit from the promo. When the process is straightforward, you can confidently plan your spending and qualify for rewards without frustration.
Legitimate credit card promos disclose all relevant fees and penalties upfront. Annual fees, late payment charges, and interest rates should be clearly listed, with no surprises hidden in fine print. Fair fee structures ensure that the credit card’s rewards and perks do not come at an unreasonable cost. Checking these fees, in turn, helps you avoid deals that look appealing but could end up costing more than the benefits they offer.
Clear and accessible terms make it easy to know how a promo works. Key details, like eligibility, reward limits, and deadlines, are often highlighted, making it simple for applicants to see what they’re signing up for. Promos with vague rules or overly complicated wording are often misleading and should be approached with caution, as they can hide limitations or costs that reduce the value of the offer. That’s why, before applying for a card or joining a promo, make sure to read the fine print and clarify anything that seems unclear. This ensures you don’t end up missing rewards, facing unexpected charges, or falling into credit card promo scams.
In the end, careful attention to the details of any credit card promo can save you from unexpected costs and disappointment. When you can recognize the key elements of what makes a genuine offer, you can quickly spot deals that truly reward your spending. Couple this with the right strategies for evaluating your options, and you can select promos with clear benefits and enjoy real value from your card.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 29, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Regulation And Policy

NCFA has published a practical guide to the UK cryptoasset regulations and FCA final rules. It helps firms, platforms, issuers, custodians, compliance teams, investors and policymakers understand how the UK framework applies across regulated digital asset activities.
The primary Regulatory Intelligence guide organizes the rule package by authorisation, scope, stablecoin issuance, custody, trading platforms, disclosures, market abuse, prudential requirements, Consumer Duty, governance, operational resilience, financial crime, reporting and implementation readiness.
The resource gives readers a structured entry point into the UK cryptoasset regime without treating the rulebook as one long regulatory document. It directs readers to the detailed Regulatory Intelligence explorer, where each rule area separates requirements, implementation work, consultation outcomes and NCFA analysis.
That distinction is important because firms need to prepare for more than registration. They may need to assess permissions, governance, safeguarding, disclosures, capital, operational controls, market integrity, customer communications, reporting and senior management accountability.
The framework also gives Canadian and global readers a useful comparison point as tokenized financial infrastructure, stablecoins and regulated digital asset markets develop. The central question is which firms can meet regulated market standards while continuing to build useful products and services.
This resource is designed for crypto trading platforms, custodians, stablecoin issuers, digital asset infrastructure firms, fintech founders, compliance teams, securities lawyers, investors, policymakers and market participants comparing global crypto regulatory models.
It is especially relevant for organizations assessing FCA authorisation, custody controls, stablecoin infrastructure, consumer disclosures, market abuse controls, governance, prudential requirements and operational readiness.
The strength of the resource is its practical structure. It turns a large regulatory package into a clear intelligence layer that readers can use to identify obligations, implementation dependencies and areas requiring specialist legal, compliance, technology or operational work.
It also supports jurisdictional comparison. Canadian and global market participants can use the UK rules to compare approaches to crypto authorisation, custody, stablecoins, disclosures, platform conduct, market integrity and consumer protection.
The guide is not a substitute for legal advice. Regulatory treatment depends on the facts, firm structure, permissions, product design and activities performed in or into the UK. Readers should use it for ecosystem intelligence and planning, then review the FCA primary materials and consult qualified advisers.
UK Cryptoasset Regulations And FCA Final Rules
Primary NCFA Regulatory Intelligence guide with the full rule explorer, implementation analysis, timeline and source links.
Tokenization Starts Looking Like Financial Infrastructure
Market infrastructure context for tokenized cash, custody, settlement and regulated digital asset rails.
Deloitte And Stablecorp Bring QCAD To Banks
Canadian stablecoin infrastructure context for banks and regulated financial institutions.
FCA Final Crypto Rules Announcement
Official FCA source announcing the final UK cryptoasset rule package.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 30, 2026 | NCFA Story Intelligence | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure
Tokenization promised to change capital markets for more than a decade.
The promise is still attractive. Put ownership on chain. Reduce paperwork. Automate compliance. Improve access. Speed up settlement. Make private assets easier to distribute, manage, and transfer.
But markets don’t run on promises. They run on operating models, regulation, distribution, controls, liquidity, and trust.
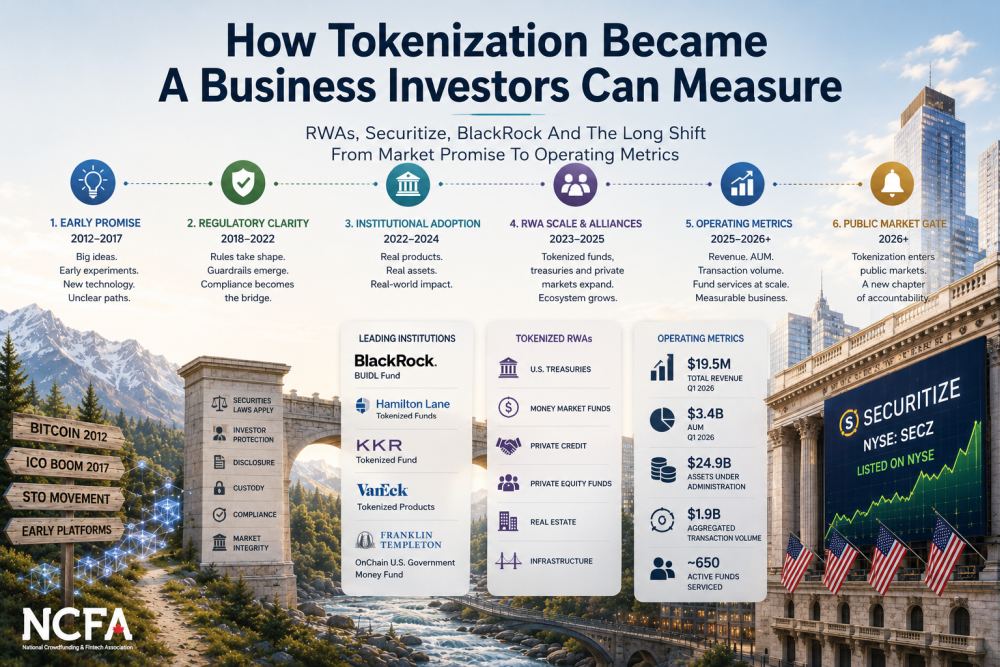
That’s why Securitize’s expected NYSE listing is the trigger. The listing isn’t the whole story. It’s the latest chapter in a longer path from tokenization as a market idea to tokenization as a business investors can measure.
The first wave sold a powerful idea. Security tokens, STOs, fractional assets, real estate tokens, private shares, and blockchain based markets promised to bring traditional securities into programmable digital form. The early security token field was framed as a more regulated answer to the ICO boom.
The market didn’t overhaul itself. Early security token projects ran into the same walls: unclear regulation, thin liquidity, limited distribution, custody questions, fragmented platforms, investor eligibility rules, and the simple reality that a tokenized security still has to behave like a security.
The hard work was never only technical. A tokenized fund still needs investor onboarding, KYC, AML, transfer rules, custody, servicing, reporting, distributions, tax records, corporate actions, and permissioned secondary transfers. Those aren’t marketing features. They’re the boring parts that make markets work.
Regulators kept reminding the market that labels don’t change obligations. Hester Peirce’s point that tokenized securities still have to follow securities laws captured the practical boundary. Faster settlement and automation don’t remove investor protection, disclosure, and market integrity requirements.
Real world assets changed the packaging. The market stopped asking whether everything should become tokenized and started asking which assets actually benefit. Treasuries, money market funds, private credit, private equity funds, and alternative assets became more practical test cases than vague claims about digitizing every market.
Private markets gave tokenization a clearer job. Citi, Wellington Management, and WisdomTree tested private market tokenization in 2024, showing how smart contracts could support operating efficiency in traditionally manual private market processes.
Hamilton Lane used tokenization to lower access friction. In 2022, Hamilton Lane and Securitize said qualified US investors would gain access to tokenized feeder funds tied to direct equity, private credit, and secondary transaction strategies.1 Securitize later said one Hamilton Lane fund reduced the minimum investment from about $5 million to $20,000.2
KKR showed that major alternatives managers would test the model. Securitize launched a tokenized fund offering exposure to KKR’s Health Care Strategic Growth Fund II in 2022, framing the product around broader access to alternative investments through digital ownership.3
BlackRock changed the market’s confidence level. BlackRock launched BUIDL, its first tokenized fund, on Ethereum in March 2024. The fund was backed by cash, US Treasury bills, and repurchase agreements, with BNY Mellon enabling interoperability between digital and traditional markets.4
BUIDL became a measurable adoption signal. In March 2025, Securitize said BUIDL surpassed $1 billion in AUM and identified itself as the tokenization provider for the fund.5 BlackRock’s BUIDL launch became one of the clearest institutional signals that tokenization was entering regulated asset management.
Securitize turned the thesis into operating data. In Q1 2026, Securitize reported $19.5 million in total revenue, up 39% year over year, $3.4 billion in AUM at quarter end, $24.9 billion in assets under administration, $1.9 billion in aggregated transaction volume, and roughly 650 active funds serviced through Securitize Fund Services.6
Those numbers change the conversation. Investors can ask normal operating questions: revenue mix, servicing fees, client concentration, transaction volume, fund growth, margins, profitability, operating leverage, customer retention, regulatory execution, and how much tokenization demand converts into durable revenue.
The listing is the trigger. Securitize and Cantor Equity Partners II said the business combination was expected to raise approximately $400 million in gross proceeds, close after shareholder approval and customary conditions, and list on the NYSE under ticker SECZ.7
The listing doesn’t settle the thesis. It exposes the thesis to market discipline. A listed tokenization company has to explain growth, losses, expenses, institutional demand, regulatory risk, competitive pressure, and whether tokenized fund adoption can become a durable public company business.
Canada has a practical watchlist. The opportunity isn’t to copy a US listing. Canadian firms can look across the tokenization value chain: custody, transfer services, fund administration, compliance, exempt market distribution, private market platforms, digital identity, investor onboarding, reporting, and secondary trading.
Regulated product design may decide the next chapter. The OSC’s long term asset fund project pointed to possible retail exposure to traditionally inaccessible assets and raised the opportunity for tokenized long term funds with embedded compliance, transparent records, fractional access, and guardrails.
Tokenization didn’t become measurable overnight. It moved through years of big claims, stalled experiments, regulatory pushback, operating layer buildout, institutional product design, and real world asset packaging before public markets had a company they could evaluate with ordinary business questions.
That may be the clearest test. The first tokenization wave asked investors to believe in a technology. The next wave will ask investors to evaluate execution. Revenue. Margins. Assets. Transactions. Clients. Losses. Retention. Market share. Operating leverage. That is a much harder test, and a much more useful one.
For Canada, the lesson is practical. The next winners may not be the firms issuing the tokens. They may be the firms solving everything around them: custody, compliance, investor onboarding, fund administration, reporting, liquidity, and regulated distribution. That’s where durable businesses are often built, and where Canada’s capital markets innovation map can help identify opportunities that are still taking shape.
What operating metric would convince you that tokenized markets have moved beyond promise?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 29, 2026 | NCFA Resource | Open Banking Open Finance, Regulation And Policy
Last updated: September 11, 2026

NCFA has published a new Regulatory Intelligence guide to Canada Open Banking and Consumer Driven Banking Rules. The interactive resource organizes the proposed regulations, implementation requirements, consultation questions and strategic issues shaping Canada’s regulated open banking framework.
For a broader view of Open Banking and Consumer-Driven Finance, including the Canadian market map, 146 learning modules, company intelligence, global benchmarks and interactive discussions, explore NCFA Open Banking & Consumer-Driven Finance Interactive Intelligence.
The guide tracks accreditation, data scope, consent, authentication, security, technical standards, liability, reporting, complaints, national security review, fees and administrative monetary penalties. It also explains why consumer trust, fraud prevention and clear accountability are central to implementation. For further analysis, see Canada's Open Banking Strategy Starts With Trust.
The resource gives readers a structured way to understand what the proposed Consumer Driven Banking Regulations would require before final rules are published.
Instead of treating the regulations as one long legal document, the guide breaks them into operating topics. Each section separates regulatory requirements, implementation work, consultation considerations and NCFA’s strategic perspective.
Canada’s open banking framework is progressing from policy design into regulatory implementation. Firms need to understand more than API access. They need to prepare evidence for accreditation, consumer consent flows, registry checks, authentication records, security safeguards, breach response, complaint procedures, service standards, reporting obligations and board level accountability.
The 60-day Canada Gazette consultation closed on August 26, 2026. The proposed regulations remain subject to finalization, while firms continue preparing for accreditation, supervision, data-sharing, consent, security and operational requirements.
This resource is useful for fintech founders, open banking platforms, financial institutions, credit unions, payment service providers, data aggregators, regtech providers, compliance teams, investors, policymakers and industry associations.
It is especially useful for organizations assessing accreditation, product design, consent architecture, data sharing duties, technical standards, cybersecurity, consumer protection and implementation costs.
The strength of this resource is its focus on regulatory readiness. It converts the proposed Consumer Driven Banking Regulations into a practical intelligence layer that can support planning, consultation, product design and ecosystem coordination.
The guide connects the proposed regulations to Canada’s policy objectives, including stronger consumer protection, fraud mitigation, secure financial data sharing, competition and confidence in the open banking framework.
It also connects regulation to commercial opportunity. The guide identifies where read access, data portability, identity and income verification, cash flow analysis, embedded workflows, write access and open finance may create future product and infrastructure demand.
The regulations remain proposed and may change following consultation. Readers should use the guide for ecosystem intelligence and planning, not as legal, financial, investment, compliance or professional advice.
Canada Open Banking and Consumer Driven Banking Rules (primary NCFA Regulatory Intelligence guide)
NCFA Open Banking & Consumer-Driven Finance Interactive Intelligence (market map, 146 learning modules, company intelligence, discussions and global benchmarks)
Canada's Open Banking Strategy Starts With Trust (consumer protection and fraud readiness)
Open Banking In Canada Opportunity Brief (commercial opportunity layer)
NCFA Financial Innovation Map (ecosystem context)
Proposed Consumer-Driven Banking Regulations (official Canada Gazette source)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 29, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, SME Finance And Business Banking, Artificial Intelligence And Data, Fintech And Innovation
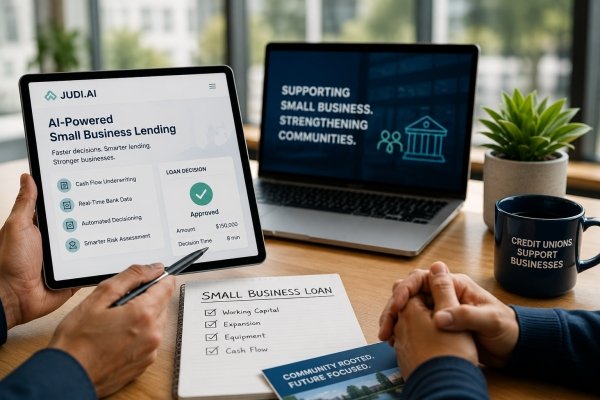
On June 29, 2026, Conexus Venture Capital invests in JUDI.AI, a Vancouver fintech whose AI cash flow underwriting platform helps credit unions and community banks make faster small business lending decisions. Existing investor Unitus Community Credit Union also participated.
The round size wasn't disclosed, but its a strong transaction. A credit union backed venture fund is financing AI lending infrastructure that already serves credit unions and community banks across Canada and the U.S.
JUDI.AI says its platform has processed more than $2 billion in small business loan applications, supports more than 50 clients, and can reduce the loan application and decisioning process from more than seven days to under ten minutes without collecting financial statements. The platform uses permissioned bank transaction data, a domain specific credit model, and a real time view of cash flow to assess small business borrowers.
Small business lending has always fit the credit union model in theory. Credit unions know local communities, relationship banking, and member service. The problem is operating cost.
A small business loan can still require bank statements, financial statements, manual review, back and forth questions, policy checks, risk scoring, and approval work. If the process takes too long, borrowers look elsewhere. If the process costs too much, lenders struggle to serve smaller tickets profitably.
JUDI.AI is targeting that gap. The platform combines cash flow analysis, automated underwriting, loan portfolio reporting, and analytics for credit unions and community banks. Instead of relying only on older financial statements or conventional lending metrics, it helps lenders assess live business activity through permissioned transaction data.
That gives credit unions a way to compete on speed without abandoning lending discipline.
Conexus was already familiar with the platform before the venture investment. The announcement says small business members in Saskatchewan previously used JUDI.AI for years to access loans faster, while Conexus reduced the time required to process applications.
That makes the investment more than a financial bet. Conexus is backing a tool it's used inside its own lending workflow, where speed, borrower experience, staff capacity, and credit discipline all matter.
Gord Baizley, CEO of JUDI.AI, framed the business around lending practice:
"At JUDI, we're not just selling a platform. We're championing a methodology. We've learned that success in small business lending is more than just technology, but a holistic approach that blends people, process, technology and intentional growth."
Better SME credit infrastructure is not only about faster models. It also depends on workflow design, risk controls, lender adoption, borrower experience, and portfolio monitoring.
JUDI.AI's model fits a larger fintech pattern. SME finance is increasingly built around current business activity rather than static documents.
That connects directly to Canada's open banking opportunity and NCFA's Open Finance SME Capital Access opportunity work. Read access can support income verification, affordability checks, cash flow insight, fraud signals, onboarding, and SME credit.
For small businesses, the commercial value comes when permissioned financial data helps lenders understand revenue, expense patterns, repayment capacity, seasonality, and account behaviour without weeks of manual collection.
The AI model needs good data, the lender needs clear controls, and the borrower needs a simpler application path. If those pieces work together, small business credit can become faster and more accessible without turning into loose lending.
JUDI.AI's decade of performance data also gives the platform a stronger adoption story than a new AI wrapper. Credit unions are buying a tested underwriting process designed for their borrower base.
Float's $85 million Series C shows Canadian business finance platforms expanding across payments, cash management, credit, and AI finance workflows.
EQ Bank's Business Card launch adds spending, cashback, interest, and cash flow tools to its SME banking stack.
Better banking options for Canadian SMEs remain a live competition issue as business owners seek lower friction, better credit access, and more useful digital financial tools.
NCFA's Financial Innovation Map tracks SME finance, open finance, AI underwriting, business banking, and financial data infrastructure opportunities.
The Conexus investment shows how credit unions can use venture capital as more than a financial return tool. They can back fintech infrastructure that improves member service, strengthens local business lending, and gives community based institutions a better way to compete with digital lenders.
For JUDI.AI, the next step is continued growth. The platform already supports credit unions and community banks across Canada and the U.S., and the new capital supports North American growth and product development. The strongest path is helping lenders approve strong small business borrowers faster, manage risk with better cash flow data, and keep local credit relationships inside the credit union system.
The competitive question is whether credit unions can adopt fast enough? Fintech lenders, banks, embedded finance platforms, and business finance software firms are all trying to own more of the SME finance relationship. Credit unions have trust and local presence. They now need digital credit infrastructure that matches borrower expectations.
If credit unions can combine local member trust with AI cash flow underwriting, can they become the strongest distribution channel for small business lending in Canada?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
Jun 29, 2026

Despite its importance, billing precision often falters under manual handling. Errors emerge without warning when human input governs invoicing tasks. Financial forecasts shift unpredictably due to late or incorrect payments. Coordination among carriers, brokers, and shippers grows harder with each added layer of complexity. Instead of relying on outdated routines, some firms now allow software to handle incoming documents. Approval timelines shorten once digital systems take over verification steps. Expense tracking improves when data flows continuously through connected platforms.
Financial decisions gain clarity when data comes together, tied directly to shipping operations. With current logistics platforms, automated processes reveal hidden expenses through precise tracking instead of guesswork. Unnecessary payments shrink while oversight grows stronger across spending areas. Invoice handling shifts into alignment with broader efforts to manage costs where margins matter most.
With the proper use of Invoice handling in logistics shifts when automation takes over. From carrier bills to vendor statements, manual checks become unnecessary. Data pulls automatically, cross-checked with delivery logs for accuracy. Validation happens without human input, cutting down mistakes significantly. Payments go through only when services are confirmed and terms met. Agreement fulfillment decides whether a charge is processed.
It’s important to know and understand that payment cycles shrink when automation takes over, far beyond just cutting errors. Because invoices move faster, carrier relations tend to stay stable. Penalties fade into the background where timing used to fail. With tighter control over outgoing funds, businesses handling large shipping loads find breathing room - even on narrow profit paths.
Among key factors shaping expenses in freight operations, mismatches in invoicing stand out - often tied to wrong pricing, repeated charges, or absent shipping details. When digital tools compare submitted bills with agreed terms and proof of delivery, problems surface sooner. Payments stay accurate because checks happen before funds move. Consistency in accounting data improves when all units refer to the same verified outcomes.
Administrative effort contributes significantly to overall expense. Handling invoices by hand takes hours from both accounting and logistics personnel, raising daily operating costs. With delivery management software, the burden lessens so employees can shift attention toward activities like reviewing supplier terms or assessing efficiency trends. Integrated with tools managing deliveries, companies achieve clearer visibility into shipments - this clarity streamlines how invoices are verified.
When we look at links towards wider logistics networks, automated invoicing gains capability. Through integration with transport management setups, firms match charge records to current delivery movements. A cohesive picture of supply chain actions emerges - precision strengthens alongside fiscal clarity.
Because route optimization software connects to billing records, firms gain clearer insight into transport spending. Where delivery timing meets invoice data, hidden waste often appears. Fuel reports that match up with dispatch logs reveal gaps in efficiency. Through consistent system links, pricing forecasts grow more reliable. Unexpected charges drop when navigation choices reflect financial tracking.
To lower logistics expenses, focus must shift beyond rate negotiations alone. Through precise financial oversight, operational waste declines notably. Visibility into transport expenditures, when immediate, supports informed choices. With automation handling invoices, errors decrease while efficiency rises. Manual tasks shrink as systems enforce tighter budget adherence. Stronger controls emerge across logistical operations naturally. Cost management improves without added complexity.
With growth in logistics networks comes greater reliance on data, making automation essential to cost control. Where firms implement unified platforms alongside wider technological tools, improvements emerge across accuracy and sustained output. Financial discipline follows when processes evolve beyond manual handling into coordinated digital workflows.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 29, 2026

Image: Unsplash/Jonas Augustin
More operators usually mean more competition. It also means more decisions. As Canada's regulated betting market expands, access to clear information is becoming just as valuable as access to the market itself.
Ontario's regulated betting market has become one of the largest digital gaming markets in North America in a remarkably short period. What began as a new regulatory framework in 2022 has developed into a market with dozens of competing operators, millions of active accounts, and billions of dollars in annual wagering activity. Growth on that scale creates opportunities for operators, but it also creates a practical challenge for consumers. More choice means more decisions, and that places a greater premium on information.
The pace of growth in Ontario has been difficult to ignore. By the end of the 2024-25 fiscal year, the province's regulated market included 50 active operators, more than 2.6 million active player accounts, $82.7 billion in total wagers, and $2.9 billion in gaming revenue. Those figures represented the third full year of operation for the market and demonstrated that consumer adoption continues to accelerate.
Growth creates competition, yet competition also creates complexity. A consumer comparing two operators in 2022 faced a very different environment from someone evaluating dozens of sportsbooks and gaming brands today. Market participants compete on pricing, promotions, betting markets, mobile functionality, payment options, and user experience. Once the number of available choices increases, access to reliable information becomes increasingly valuable.
Open banking is built around the idea that consumers should have greater control over their financial information and a clearer view of the choices available to them. Canada's commercialization roadmap includes developments such as the Real Time Rail, expected in Q3 2026, alongside broader plans for consumer-directed finance. Those initiatives are designed to make switching providers easier and encourage stronger competition between market participants. The same forces are increasingly visible in regulated betting markets.
The underlying concept is straightforward. Markets become easier to navigate when information is more accessible and consumers can evaluate options without unnecessary friction. Betting markets are different from banking products, but the challenge is similar. A larger number of participants creates more choice; better information helps people make use of that choice.
Modern sports betting involves far more than picking a winner before kickoff. Futures markets move throughout a season, live betting prices react to events in real time, and player props can change within minutes of breaking news. Bettors increasingly compare market depth, promotional offers, banking options, and mobile functionality before opening an account. The top betting platforms currently active in the Canadian market listed on Covers.com provide a structured view of those differences, helping bettors assess everything from betting markets and odds availability to withdrawals, mobile performance, and promotional competition.
Ontario is no longer the only province attracting attention. Alberta is preparing to launch its own regulated competitive market on July 13, 2026, creating another major development in Canada's digital gaming sector. The province has stated that the objective is to move operators from the grey market into a regulated framework that provides stronger consumer protections and clearer oversight.
The launch is significant because it expands the competitive model beyond Ontario. New operators entering Alberta will compete for attention in much the same way operators compete in Ontario today. Consumers will face a growing number of choices, particularly in sports betting, where differences between platforms can be found in market depth, pricing structures, and product features. Information resources are likely to become more important as that competition develops.
Canada's open banking framework is designed to make comparing providers easier and encourage stronger competition. Progress toward the Real Time Rail and wider consumer-directed finance initiatives outlined in Canada's open banking commercialization roadmap reflects that broader objective.
The betting sector is developing along a similar path. Ontario's regulated market generated $82.7 billion in wagers during fiscal year 2024-25, and those numbers continue to grow. As markets expand and more operators compete for customers, information becomes part of the infrastructure supporting competition itself.
Consumers still make their own decisions, but access to clearer information makes those decisions easier to navigate. That principle applies whether the subject is financial services, digital payments, or Canada's rapidly growing regulated betting market.
Alberta's upcoming launch suggests that Ontario is unlikely to remain Canada's only major competitive betting market for much longer. As more provinces explore regulated models and additional operators enter the market, consumers will face a growing range of choices. That makes transparency increasingly valuable.
Better information does not replace competition; it helps people make better use of it, which is ultimately what healthy digital markets are supposed to achieve.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016