




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Financing | Aug 18, 2025
Image via Cohere's funding announcement 2025
On Aug 14 2025, Cohere announced its latest $500 million raise at a $6.8 billion valuation in an oversubscribed round led by Radical Ventures and Inovia Capital, with participation from AMD Ventures, NVIDIA, PSP Investments, Salesforce Ventures, HOOPP, and others. The fresh capital will help Cohere accelerate efforts to build the next generation of secure enterprise and sovereign AI solutions. Cohere is positioning its security-first agentic AI as an alternative to repurposed consumer models, emphasizing local data control, regulatory compliance, and digital sovereignty.
Jordan Jacobs of Radical Ventures commented:
“Cohere is fulfilling the promise of building privacy-first, cloud-agnostic models and agentic AI applications that drive extraordinary productivity gains for enterprises and governments worldwide.”
Patrick Pichette of Inovia Capital now joining Cohere’s board, said:
"[The company's] relentless focus on data privacy, customization, and time-to-value” [places it at the forefront of global enterprise AI]."
Over the past year, Cohere doubled its annual recurring revenue to more than $100 million USD and launched North, its flagship agentic AI platform, deploying solutions across sectors with partners like Oracle, Dell, RBC, Bell, Fujitsu, LG CNS, SAP, and Ensemble Health Partners. Cohere is also expanding its leadership team, as part of its growth strategy with Joelle Pineau, former VP of AI Research at Meta and professor at McGill University, joining as Chief AI Officer, and Francois Chadwick, former Uber acting CFO, joining as Chief Financial Officer.
Aidan Gomez, Co-founder and CEO of Cohere:
“Cohere is becoming the world’s chosen partner for integrating AI into critical industries. We are at a pivotal moment in accelerating the delivery of secure AI that empowers enterprises worldwide.”
Cohere’s trajectory is part of a much broader Canadian AI scale-up story. The country benefits from deep academic research centres (Mila, Vector, Amii), growing pools of venture capital, and the federal government Scale AI innovation cluster in Montreal which channels hundreds of millions of dollars into commercialization projects. Together these forces are turning Canadian AI from research excellence into global market strength. Below are some Canadian AI companies operating at scale.
Cohere’s $500M raise demonstrates Canada’s growing capacity as a hub for enterprise-level AI innovation, alongside other Canadian-founded scale-ups like Tenstorrent, Waabi, Clio, Docebo, 1QBit, Ada, and Sanctuary AI. Canada's momentum shows that we're not only incubating promising ideas and startups but supporting scale-ups that are impacting global AI markets with capital, partnerships, and converging talent.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
AI | Aug 14, 2025
Image: Freepik/pikisuperstar
On August 12, 2025, AI search giant Perplexity stunned the tech world with a bold $34.5 billion bid for Chrome, adding to the mounting antitrust pressure currently facing Google. Now Chrome, the world's most widely used browser with over 3 billion users is at the center of regulatory discussions that could force Google to sell Chrome after a US federal judge ruled the company maintains an unlawful monopoly in online search.
Perplexities proposal however is unlikely to succeed immediately, as regulators weigh remedies that could drastically change the browser market, expand competition, and challenge Google’s dominance.
Founded in 2022, Perplexity is currently valued at $18 billion USD (July 2025) and built a reputation as one of the fastest growing AI companies. Its platform processes hundreds of millions of monthly queries and recently launched an AI driven web browser called Comet.
According to a term sheet seen by Reuters, Perplexity's bid promises to keep Chromium open source, invest $3 billion over two years and make no changes to Chrome’s default search engine (preserving user choice).
Aravind Srinivas, CEO Perplexity, said the offer to buy Chrome was “designed to satisfy an antitrust remedy in highest public interest by placing Chrome with a capable, independent operator.” It's certainly a bold move, highlighting AI's role in the future of internet access.
The bid is closely aligned with findings from the US Department of Justice's antitrust case where Judge Amit Mehta has ruled that Google’s agreements with device makers and carriers unlawfully entrenched its dominance in search.
Potential remedies are still being reviewed and could include a forced sale of Chrome. The possibility has already attracted interest from OpenAI, Yahoo, and Apollo Global Management.
Some analysts argue that Chrome’s integration with Google’s ad ecosystem and its dominant market share could justify a higher valuation than Perplexity’s offer. Others see the move as a calculated play to raise Perplexity’s visibility ahead of any divestiture decision. A forced sale could become one of the largest transactions in tech history and alter how billions of users access and navigate the web.
Google has offered no sign that it's prepared to sell Chrome and is expected to appeal any divestiture order, which could delay a resolution for years. Google CEO Sundar Pichai testified at a U.S. antitrust trial that forcing the company to share search data with rivals would give away its intellectual property, hurt innovation, and make it easy to copy Google Search. Google says any forced sale of Chrome would threaten user privacy and cybersecurity, and damage complementary services, partners, and competition, and it plans to appeal if it loses.
This case is a reminder that entrenched market dominance in digital infrastructure can face real legal challenges in countries that take competition seriously, and that strategic timing matters when entering regulated, high barrier markets. A forced sale of Chrome could set precedent for similar actions in fintech, payments, and AI driven services, creating risks and opportunities for companies ready for the next iteration of the internet.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto IPO | Aug 14, 2025
Image: Freepik AI
Bullish is a Cayman Islands based crypto exchange focused on institutional grade digital asset trading and market intelligence, and also the media owner that also operates CoinDesk. Bullish first tried to go public through a SPAC deal in 2022 during a difficult period for crypto markets but that plan was abandoned. The company waited for market conditions to improve before trying again.
By Q2 2025 sentiment toward both crypto and IPOs flipped positive. Supportive policy developments on stablecoin regulation from Washington helped stoke interest from big investors. At the same time Bitcoin was trading near $120,000 and other high profile fintech IPOs like Circle and Figma had delivered strong first day gains, fuelling expectations for Bullish.
Bullish priced its IPO at $37 per share which was above its revised range of $32 to $33 and well above its original $28 to $31 range. The company sold 30 million shares and raised about $1.11 billion at a valuation of $5.41 billion at the offer price. JPMorgan, Jefferies and Citigroup were among the underwriters. BlackRock and ARK Invest each indicated plans to invest up to $200 million.
The shares began trading on the NYSE under the ticker BLSH on August 13 2025. They opened at $90 and quickly climbed to $118, which led to multiple trading halts for volatility. By the close the stock was at $68, an increase of about 84% from the offer price, valuing the company near $10 billion.
Institutional interest in Bullish is significant. The company’s mix of a trading platform and media data outlet set it apart from competitors like Coinbase and Binance.
Also the timing of the IPO, expectations for an interest rate cut in September, a rising crypto market and signs of clearer regulation in the United States, all contributed to this success.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Regulatory Consultation | Aug 13, 2025
Image: Freepik/DC Studio
On August 12, 2025, the Canadian Investment Regulatory Organization (CIRO) announced proposed changes for consultation to update rules for Order Execution Only (OEO) dealers, which are digital-first platforms, such as Questrade, Wealthsimple Trade, MogoTrade, or RBC Direct Investing. The proposal would allow a wider range of tools for use, as long as safeguards like clear disclaimers and conflict avoidance measures are in place.
Currently, OEO dealers are allowed to let clients place trades but they are not allowed to provide investment advice. Current restrictions limit these dealers from offering features such as sample portfolios, self assessment tools, or certain educational supports, to avoid triggering “recommendations.”
Today, non CIRO fintechs and investor education organizations can offer self assessment tools, model portfolios, and interactive investor education features because they are not registered dealers. CIRO regulated dealers operate under strict rules, which can hold back innovation. The proposed changes could help close this gap by allowing regulated CIRO platforms to provide more engaging and competitive resources to DIY investors.
One motivation for the proposed rule change is the sharp increase of retail investors turning to social media, forums, and finfluencers for guidance. CIRO has warned that unverified online information can expose investors to serious risks. Expanding what regulated platforms can offer would give DIY investors more access to credible, compliant sources of information and reduce reliance on potentially misleading content.
CIRO is accepting comments on the proposal until November 10, 2025 and has made updating OEO guidance a priority for 2026. If adopted, these changes could reshape investor education in Canada by giving regulated platforms greater flexibility while maintaining essential protections.
The outcome of this proposal will determine how much flexibility regulated CIRO ealers have to innovate in investor and financial education. For fintech innovators and market participants, it's a sign that regulators are open to modernizing rules to better meet the needs of today’s self directed investors.
NCFA will continue to follow this development and share updates on how the final framework could influence the future of investor engagement.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Open Banking | Aug 13, 2025

Image: Freepik
FCA Releases Governance Plan for UK’s new Industry-led Open Banking Standards Body
On August 8, 2025, the UK’s Financial Conduct Authority (FCA) published its FS25/4 feedback statement outlining the governance framework for a new Future Entity to oversee the open banking standards in the UK. The plan details how the Future Entity will be funded, governed, and held accountable. It will be industry led and operated, not a government agency, but will function under the FCA’s oversight. For Canada, the model demonstrates how industry expertise can be combined with regulatory accountability to support innovation and trust.
Since 2017, open banking in the UK has been run by Open Banking Limited, a government run entity created by the UK’s Competition and Markets Authority (CMA) to deliver its order requiring the nine largest banks to create interoperable APIs. Known earlier as the Open Banking Implementation Entity (OBIE), it was a time limited role to boost competition in banking, and not designed to be a permanent governance model.
The FCA’s plan replaces OBIE with the Future Entity, which will have a long term, industry wide mandate. This change moves open banking oversight from a CMA specific enforcement body to an independent standards setter governed under the Data (Use and Access) Act 2025. This legal framework means the Future Entity can later expand into open finance and other areas of data portability.
The Future Entity will be a not for profit company limited by guarantee, funded by contributions from its users and beneficiaries including banks, fintechs, and other participants. Its board will be appointed by an independent appointments committee, not directly by the government or the FCA. The FCA will regulate it as an interface body under the Data (Use and Access) Act, but will not manage its day to day operations. This allows industry to lead on technical standards while the FCA can intervene if those standards do not protect consumers or the market.
The governance approach is similar to a self regulatory organisation (SRO). It is run by industry, sets technical and operational API standards, and monitors compliance. Like an SRO, it will send reports to the regulator. The key difference is that the Future Entity will not have enforcement powers. All formal enforcement remains with the FCA. This keeps legal authority with the regulator while allowing the industry to deliver the technical work.
Commercial operators will use the Future Entity’s standards to create products and services to meet interoperability while leaving space for competition and innovation. The Future Entity itself will only operate directly if there is no commercial incentive or there is a proven market failure.
Industry participants are already working on variable recurring payments for uses such as bill payments, which is planned for 2025. The FCA will hold workshops this summer and fall 2025 to finalize operational details, with a full plan expected by the end of the year.
Canada currently has no permanent open banking standards body. The UK approach shows how Canada could move a temporary regulatory order to a more permanent industry led framework without losing accountability or slowing progress.
An industry led and funded non-profit organization, supported by contributions from all users and beneficiaries, can create shared responsibility and boost financial sustainability. With an SRO style approach, industry leads on technical delivery while the regulator retains enforcement powers, can speed innovation while protecting consumers and market stability.
Important to keep the standards setting body separate from commercial operators to streamline interoperability and ensure a level playing field (reducing risk of favouritism towards certain providers). Applying these principles from the start could help Canada avoid disruptive governance changes later and build a system that supports both innovation and public trust. Learn more about Canada's open banking journey.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto Policy | Aug 11, 2025
Image: Freepik
On August 7, 2025, President Trump signed an executive order called, "Democratizing Access to Alternative Assets for 401(k) Investors", directing U.S. regulators to explore ways to allow cryptocurrencies and other alternative assets in defined contribution plans like 401(k)s.
While it doesn't immediately mean that Americans can directly hold crypto investments in their retirement accounts, it does instruct the Department of Labor (DOL), the Securities and Exchange Commission (SEC), and the Treasury to coordinate on new frameworks that could make it possible. If this happens, it will have significant implications for U.S investors but also for fintech innovators and regulators in Canada who are monitoring trends South of the border.
The order requires the DOL to review and update its fiduciary guidance for retirement plan sponsors, with a specific focus on clarifying what due diligence, risk disclosure, and participant education would be required if crypto were included as an option.
It also directs the SEC to consider revisions to certain securities rules, including elements of the accredited investor framework, that could impact the packaging of crypto investment products for retirement plans.
Treasury and related agencies have been tasked with aligning tax, reporting, and compliance rules to avoid conflicting obligations. According to the official fact sheet, the review process is expected to produce proposed rule changes by early 2026.
Advocates explain that opening retirement plans to digital assets could help diversification and align with investor demand, especially among younger savers who already hold crypto in personal accounts.
This change could also create a massive new liquidity channel for the crypto sector while bringing it further into regulated financial infrastructure, as reported by Forbes.
For fintech and crypto innovators, Trump's executive order could blow up the addressable market for crypto retirement products, custody solutions, and participant education tools.
With opportunity comes risks of course. The DOL has previously raised concerns about crypto’s volatility, liquidity constraints, and valuation complexities in retirement plans.
Business Insider reported that plan sponsors could face elevated litigation risks if participant loses are tied to crypto holdings, especially without clear safe harbour protections. Implementation also requires custodians and record keepers to adapt their current systems for daily valuations, liquidity management, and tax reporting.
The U.S. executive order isn't about adding more ETFs to retirement accounts. It opens the door for 401(k) participants to gain exposure to actively managed investment vehicles investing in digital assets and other private market investments, directly within a tax-advantaged plan registered with the government. This could mean direct holdings of Bitcoin or Ethereum, or participation in private crypto funds not listed on public exchanges, if fiduciaries deem them prudent and compliant with ERISA standards.
In Canada, the gap is very real today. Registered plans like RRSPs, RRIFs, TFSAs, and employer pension plans cannot directly hold cryptocurrency. The Canada Revenue Agency’s qualified investment rules prohibit digital assets themselves from being held in registered accounts, whether or not the plan is self-directed. Investors can only gain crypto exposure through qualified investments such as Bitcoin or Ether ETFs listed on a designated stock exchange, or shares of publicly traded crypto companies. Private crypto funds, unlisted trusts, or direct wallet holdings are currently prohibited in all registered accounts.
If the U.S. implements this framework, Canadian retirement plans would be at a competitive disadvantage in offering digital asset investment innovation. For Canadian fintechs, such U.S. policy could create new product development opportunities south of the border, while providing an unprecedented case study for domestic regulators on how to balance investor protection with access to alternative assets.
This latest crypto policy development is another wake-up call and market opportunity for Canadian fintechs and regulators. The next 12 to 18 months will determine whether or not U.S. agencies can produce rules that satisfy both innovation advocates and investor protection, fiduciary watchdogs. If they succeed, Canada’s own retirement savings design could be the next frontier for digital asset integration, and if so, they need to be ready to respond.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Artificial Intelligence | Aug 8, 2025
Image: Freepik/kjpargeter
On August 7, 2025, OpenAI officially announced the release of GPT-5, it's latest artificial intelligence (AI) model with advanced capabilities that could significantly transform sectors in the near future, including fintech. From improving app development processes to enhancing customer engagement, GPT-5 offers companies with powerful tools to innovate and stay competitive. This article looks at key features, performance, and how it could be applied to real-world fintech applications.
GPT-5 introduces several exciting features, each with direct relevance to fintech. Here's an overview of some key upgrades and how they can impact fintech businesses:
GPT-5 can now handle more multi-step, data-driven tasks; it's more agentic. In fintech, where decision outcomes usually rely on complex financial models and large datasets, GPT-5 can generate more accurate insights and prediction results. A credit risk model that combines structured data (e.g., income, credit history) with unstructured data (e.g., social media sentiment, customer reviews).
GPT-5’s improved reasoning can analyze these diverse data sources in real-time, helping fintechs and financial institutions make better lending decisions that ultimately reduce default risks. For example, a fintech company offering microloans could integrate GPT-5 into their platform to analyze the creditworthiness of borrowers by evaluating non-traditional data sources, such as purchasing behavior or community feedback, alongside traditional financial data.
One of GPT-5’s most anticipated features is vibe coding, which is in hot demand. Just look at vibe coding pioneer Lovable, the fastest growing software company in history. Instead of writing lines of code, developers or pretty much anyone who can engineer a robust prompt, can now simply describe the functionality they want, and GPT-5 will generate the actual code. This has massive implications for fintech businesses looking to quickly prototype new applications or tools without extensive coding expertise. For example, a fintech startup looking to launch a budgeting app can describe the app’s desired features, such as “track user spending across categories like food, rent, and entertainment”, provide the data sources and GPT-5 will create an actual working app prototype, saving time, reducing costs, and enabling product innovators to quickly test ideas in the market.
GPT-5 can handle more complex multimodal tasks, allowing it to interact with a wider range of data types and inputs in real-time (i.e., text, images, audio, video), offering users a more dynamic and improved customer experience, such as an AI concierge service assistant that can respond to user questions and use cases using not just text but also analyze and generate images like financial charts or explainer videos, improving communication and user satisfaction.
For example, fintech platform offering investment advice could use GPT-5 to generate personalized financial reports for clients. Instead of just providing text-based summaries, the model could generate visual reports with graphs and interactive charts, making the information more understandable for users.
GPT-5 takes personalization to the next level by adjusting its responses in real-time based on a user’s preferences and needs during the conversation. It doesn’t store information beyond the current session but uses contextual understanding to make financial advice more relevant. For example, if a user mentions an interest in low-risk investments, GPT-5 will personalize its responses accordingly, even if the user doesn't repeat it later in the conversation. It also adapts the complexity of its advice based on the user's level of knowledge, whether they need basic tips or more detailed strategies. This ability to dynamically adjust in real-time helps fintech companies deliver highly personalized experiences without relying on long-term memory.
Fraud prevention and regulatory compliance are critical in fintech for trustworthy regulated transactions. GPT-5 comes with stronger pattern recognition capabilities that can help automate these processes. By analyzing huge amounts of transactional data in real-time, GPT-5 can spot suspicious activities and flag potential fraud better than before.
GPT-5 can also be integrated into regulatory compliance tools to ensure that fintechs and their users meet legal requirements by identifying gaps and discrepancies of non-compliant behaviours. By analyzing not just transaction patterns but also customer interactions (e.g., communications with support), GPT-5 could improve fraud detection accuracy and reduce false positives.
Reports say GPT-5 reduces factual error rate by 45% compared to GPT-4o, so responses are more reliable and accurate. This is of course highly useful for fintech use cases that need high accuracy to support decision making such as a loan approval.
Checkout Datacamp's GPT-5 benchmarking review for details. In short, GPT-5 is better than GPT-4o at coding, math, multimodal tasks, and handling large contexts, making it a more powerful AI to handle complex tasks required in financial services.
OpenAI's launch of GPT-5 has not been without its challenges. CEO Sam Altman admitted that the rollout faced several issues, particularly with an automatic model selecting feature, which initially wasn't working as expected. In a Reddit AMA, Altman admitted that the model’s rollout was "bumpy" but reassured users that the team made some improvements to GPT-5, which "will seem smarter starting today". Also after many users expressed a preference for the older model's personality and performance, OpenAI decided to reinstate GPT-4o for ChatGPT Plus subscribers. It appears that Altman underestimated how much users valued GPT-4o's specific traits.
To explore the power of GPT-5's vibe coding, we tested its capabilities by asking it to create a mini interactive game that incorporates the NCFA logo. The goal was to see how easy it was to use GPT-5 to generate a simple, interactive point driven game from a single plain language prompt.
Here’s the prompt we used:
"Create a simple interactive game where users can click to collect NCFA logos that appear randomly on the screen. The game should have a basic scoring system, a start and stop button, and a simple animation for the logos as they appear and disappear. The game should be created using HTML, CSS, and JavaScript. The NCFA logo should appear as an image file that I can upload."
It took GPT-5 about 10 seconds to generate the full code, which included:
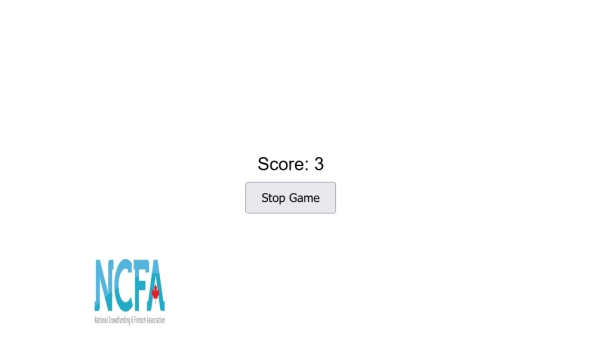
Image: NCFA logo game code vibing test
The game worked perfectly with the National Crowdfunding & Fintech Association of Canada's logo intermittently bouncing all over the screen, with points accumulating with each accurate click on the logo. Imagine creating promotional games or interactive educational tools quickly without needing extensive coding experience. Yes, the warning to software engineers is true.
Funny that Microsoft recently published a report predicting the top 40 job types at risk of being taken over by AI agents, but somehow their list doesn't seem to include software programmers? At the same time, Microsoft's CTO said that in the next 5 years, AI will handle 95% of all coding.
GPT-5 is another step towards the future of artificial intelligence, now offering fintech businesses more advanced tools to innovate quickly. Whether it’s improving decision making with advanced reasoning or customer engagement with personalized experiences, or simplifying app development with vibe coding, GPT-5 is a powerful asset for any fintech company at this point of the AI revolution, making it an critical intelligence engine for to help fintechs improve operations and deliver smarter, more personalized experiences for their customers. Now just wait for all the competition looking to level up next.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016