




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 19, 2026 | NCFA OpEd | Digital Assets Blockchain And Tokenization, Lending Consumer Credit And BNPL, Capital Markets And Funding
By Hudhaifah Zahid (Kode), Founder and CEO, Grynvault
Private credit has become one of the most important financial markets in the world because banks serve fewer borrowers, operators, and asset classes with the speed and flexibility the market now requires. That opening created room for faster capital, more specialized underwriting, and structures closer to the underlying cashflow.
Yet private credit still inherits the old problem: it prices long term real world risk through fiat benchmarks. A five year operating asset is often judged through short term rates, credit spreads, inflation assumptions, and currency movements that have little to do with the asset itself. The structure may be private, but the denominator is still public market money.
That is the part worth questioning. Private credit solved access to capital. The next step is better pricing of capital.
Every credit contract begins with a simple question: what is the correct cost of capital? In fiat finance, the answer usually comes from central bank policy, government bond yields, credit spreads, and lender appetite. Those inputs are useful, but they also shift constantly. A borrower can look good in one rate regime and weak in another. A yield can look attractive in one currency and ordinary in another. A nominal return can look safe while purchasing power quietly leaks away.
Private credit feels closer to reality because it touches actual businesses, equipment, vehicles, receivables, inventory, and property. But the moment every outcome is measured only in dollars, the same distortion returns. Did the investor earn a real return, or just more nominal units? Did the operator create value, or repay in cheaper currency? Did the asset perform, or did inflation cover the mistake?
This becomes sharper when capital crosses borders. A Canadian operator, a U.S. investor, and a global capital pool experience inflation through different currencies, costs, and policy cycles. Currency adds another layer of noise. The market can price the loan, the lease, or the receivable, but it still needs a cleaner way to compare performance across time and jurisdiction.
The usual benchmark global markets usually look at to help with pricing are U.S. Treasury bills (T Bills). They give investors a simple way to park cash, and earn what we call a “risk free” rate from which to calculate all new additional risks. However, that function is failing.
For a long time, U.S. government debt gave global markets a simple mental anchor. Investors could park capital, earn a nominal return, and treat that yield as the baseline for additional risk. But the more capital hides in short duration instruments, the less useful that baseline becomes for pricing long term productive assets. T bills may be useful for liquidity, collateral, and cash management. They do not answer whether a five year vehicle facility, equipment contract, or operating business receivable preserved purchasing power after inflation, currency movement, and settlement risk.
A short duration instrument is a weak mental anchor for five year plus productive finance. A vehicle facility, equipment contract, or operating business receivable carries usage risk, collateral risk, performance risk, inflation risk, and settlement risk. Those risks unfold over time. Pricing them against rolling short term yield can make the contract look rational while the purchasing power result remains unclear.
Private credit should earn a premium for doing hard work in the real economy. It sources, underwrites, monitors, services, and resolves. That premium becomes more durable when the market measures performance against a harder monetary benchmark instead of an unpredictable and inefficient baseline. So, what’s the alternative?
Bitcoin is a strong contender, as we lay out how a truer long term cost of capital can be derived from its use as a reserve asset in business. Its monetary and digital nature makes it easy to introduce into global deals, as just by having it in the portfolio, you are forced to ask: did our use of capital justify giving up Bitcoin exposure over the same period?
That question disciplines the contract. It forces the investor and operator to compare productive asset performance against scarce money. If the asset produces enough utility, cashflow, and settlement value, the deal deserves to exist. If it trails the monetary asset it displaced, the structure reveals weakness that fiat inflation and refinancing can otherwise conceal.
In practice, private credit often behaves like an arbitrage business. Capital is sourced at one cost, deployed at a higher expected return, and judged by the spread. That model works until the denominator weakens faster than the spread can compensate.
Let’s walk through an example of how we do this at Grynvault. Bitcoin changes the cost of capital function and can be used to more accurately price risks. Say that we are financing a $10,000 car. The operator brings $2,500 as a contribution, what would have been the down payment. A $625 is retained upfront as a program fee and $1,875 is placed into a Bitcoin linked reserve and we start collecting a fixed amount of roughly $212.50 per month for 60 months. At a Bitcoin price of $100,000, that reserve equals 0.01875 BTC.
At the end of the contract, the reserve helps discover the final cost of capital. If Bitcoin is flat or down, the operator receives the value of the original Bitcoin linked reserve based on the settlement price, and their effective cost reflects that outcome. If Bitcoin rises by 1.5x, the $1,875 reserve becomes $2,812.50. Based on a Bitcoin denominated rebate formula and full operator performance, roughly $1,997 could be rebated to the operator, with the remaining upside strengthening investor returns.
The rebate remains performance based and discretionary within the structure. The operator earns it by making payments on time, preserving the asset, and completing the contract properly. This keeps the fixed payment asset use experience intact while allowing the final settlement to behave like a variable cost of capital priced against Bitcoin’s monetary performance instead of central bank rates.
For investors, the base case remains asset backed cashflow. The Bitcoin reserve adds a long term settlement layer that can improve outcomes while keeping volatility out of monthly payments. Where permitted, return of capital mechanics can also make the cashflow profile more tax aware, with final economics recognized at settlement according to the applicable structure and jurisdiction.
Traditional financing often places the operator and investor on opposite sides of the same rate. If the investor earns more, the operator usually pays more. If the operator pays less, the investor usually earns less. A Bitcoin linked reserve changes that relationship because part of the outcome comes from the monetary layer rather than only extracting more from the user of the asset.
The operator keeps a fixed monthly payment and can earn a lower final cost through performance. The investor keeps access to real asset cashflow and can earn additional upside through the reserve. Weak performance limits the operator’s benefit. Strong performance creates room for a better settlement. The contract becomes a score the operator can improve instead of a price frozen forever at origination.
That is the deeper private credit implication. Bitcoin allows a facility to separate operating affordability from final cost discovery. Monthly payments can stay boring while the settlement layer captures the truth of time, performance, collateral quality, and monetary appreciation. This alone exemplifies good pricing and long term thinking.
Private credit investors are usually paid for taking illiquidity, complexity, and credit risk. Over long horizons, they also need protection from monetary erosion. A portfolio can show a healthy nominal yield and still fail to preserve purchasing power if the denominator weakens faster than expected.
A Bitcoin linked reserve gives private credit a way to hold part of the economics in scarce money while the operating asset continues to produce local currency cashflow. That combination is the bridge. Fiat remains useful for monthly payments, taxes, insurance, servicing, and regulatory compliance. Bitcoin strengthens the long term settlement value.
This is especially relevant for cross border capital. Investors can fund productive assets in one jurisdiction while monitoring part of the performance against a global monetary benchmark. Operators can keep paying in the currency they earn. The facility can report both views. The local economy gets capital, while investors receive a cleaner purchasing power lens.
Canada is a strong place to build this category because the need is practical. Small businesses, dealers, operators, and asset owners need flexible capital. Investors need yield that survives inflation. Fintech platforms need structures that are transparent, compliant, and grounded in real cashflow.
The opportunity is to bring Bitcoin into private credit as pricing infrastructure. That means disciplined underwriting, real collateral, conservative servicing, clear reporting, careful custody, and settlement rules that align incentives. The market needs productive finance measured against better money, built with real collateral and transparent settlement rather than synthetic yield.
Grynvault is one attempt to build that bridge. Start with a real asset. Pay the seller cleanly. Give the operator fixed payments. Hold a Bitcoin linked reserve beside the contract. Reward performance at settlement. Use the remaining upside to strengthen investor returns. Report the economics in both local currency and Bitcoin terms.
The old private credit premium was illiquidity. The next premium may be monetary discipline. The platforms that win will price risk across borders more clearly, protect long term purchasing power more intelligently, and turn sound money into a practical advantage for productive finance.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 19, 2026
Modern online casino games increasingly focus on movement and nonstop visual activity, and Betscore Casino reflects how continuous motion has become a major part of modern digital gaming experiences.
Online casino games have evolved significantly from the static reel machines that once dominated the industry. Today’s players expect games to feel active, visually dynamic, and constantly responsive throughout every session. Developers now design many casino games around continuous movement in order to maintain attention and create stronger engagement.
This shift can be seen across many modern slot formats and live casino games. Cascading reels, animated transitions, moving symbols, expanding grids, and fast visual reactions all contribute to gameplay experiences that feel more fluid and energetic than traditional casino games.
Betscore Casino reflects how online casino platforms increasingly support games that rely on motion and visual momentum to create more immersive digital entertainment experiences.
One of the main reasons motion based casino games have become so popular is because they create the impression that gameplay never fully stops. Traditional slot machines often followed a simple pattern where the reels spun, stopped, and reset before the next round began.
Modern casino games increasingly avoid these static pauses. Cascading reels allow symbols to disappear and new ones to fall into place automatically after wins, while animated transitions keep the screen visually active between gameplay phases.
Players often find these systems more engaging because the game feels alive and constantly evolving. Even after the initial spin result appears, additional animations and movement continue building anticipation.
Betscore Casino highlights how modern casino developers increasingly design games around ongoing visual activity rather than isolated gameplay moments.
Many modern slots also combine motion based mechanics with multipliers, expanding symbols, and bonus triggers to create even longer sequences of uninterrupted activity.
These layered mechanics help maintain player focus and create stronger emotional pacing during gameplay sessions.
Modern digital entertainment heavily influences how casino games are designed today. Video games, mobile apps, and streaming platforms all prioritize movement and visual responsiveness in order to maintain user engagement.
Online casino games increasingly follow similar principles. Developers use motion not only as decoration, but also as a gameplay tool that shapes pacing and emotional intensity.
Animations now serve multiple purposes during gameplay. Moving backgrounds, animated reels, glowing symbols, and cinematic effects all help make sessions feel more immersive and visually stimulating.
Betscore Casino reflects how casino platforms increasingly prioritize smooth visual flow and dynamic presentation as part of modern online gaming experiences.
Mobile gaming has strengthened this trend even further. Smartphone users are especially responsive to games that provide constant movement and quick visual feedback because these mechanics create stronger engagement during shorter sessions.
Continuous motion also helps games feel more modern and technologically polished compared to older casino formats with minimal animation and slower pacing.
The growing popularity of movement focused casino games reflects a broader shift in digital entertainment habits. Modern users increasingly expect fast visual feedback and experiences that feel continuously interactive.
Because of this, casino developers continue experimenting with mechanics that reduce downtime and keep gameplay visually active for longer periods.
Betscore Casino represents how online casino platforms continue evolving toward more dynamic and visually fluid gaming environments shaped by modern entertainment expectations.
This does not mean traditional casino games are disappearing. Instead, many classic formats are being redesigned with more animation, smoother pacing, and stronger visual transitions in order to remain competitive within today’s digital landscape.
As online casino gaming continues developing, continuous motion will likely remain one of the defining characteristics of modern game design. The ability to create smooth, visually active, and constantly evolving gameplay experiences will continue playing a major role in attracting players seeking more immersive digital entertainment.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 15, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026).
Tokenized funds need reliable exits before more institutions treat them as usable collateral or treasury assets. Asset managers, custodians, exchanges, treasury teams, and tokenization platforms should watch how redemption speed, stablecoin liquidity, and access controls become core requirements for institutional tokenized finance.
Community and regional banks are starting to package stablecoins, tokenized deposits, and digital asset lending inside bank led distribution. Banks, fintechs, core providers, custodians, and compliance teams should watch how association channels turn digital asset access into a practical banking product instead of a standalone crypto service.
Fintechs and FIs now compete on governed AI use in underwriting, fraud, servicing, and cost discipline, while security and model risk stay on the board agenda.
Voice is becoming searchable compliance evidence across more markets and languages. Banks, dealers, wealth firms, fintechs, and regtech vendors need stronger controls for recorded calls, multilingual surveillance, off channel risk, and investigation workflows.
Fraud controls are becoming more coordinated across regulators, law enforcement, platforms, and financial institutions. Banks, fintechs, PSPs, regtech vendors, and digital asset firms should expect higher expectations around intelligence sharing, scam detection, AI oversight, and real time monitoring.
Agent driven commerce needs payment controls that can handle authorization, settlement, spending permissions, dispute handling, and compliance review without slowing automated workflows. Stablecoins are increasingly being positioned as the settlement layer for machine initiated transactions.
Agent payments now need privacy, settlement, authorization, and audit controls that work together. Payment firms, wallet providers, stablecoin issuers, AI agent platforms, and compliance teams should track how machine initiated transactions create new requirements for identity, transaction monitoring, and dispute handling.
Canadian banks, credit unions, fintechs, and infrastructure providers face growing pressure to modernize customer onboarding, payments, servicing, and digital account experiences at lower operating cost. Large coordinated modernization programs can influence vendor standards, integration expectations, and competitive timing across the Canadian banking market.
Direct PSP access to Interac e Transfer gives Canadian fintechs a stronger role inside everyday money movement. Banks, PSPs, payment firms, and compliance teams should track how direct participation changes onboarding, fraud controls, settlement readiness, and product competition across Canadian payment services. Koho is a a payment service provider member of Payments Canada with direct access to payment clearing and settlement.
Digital asset lending keeps adopting operational standards from traditional securities finance. Exchanges, custodians, prime brokers, lenders, treasury teams, and compliance groups should watch how collateral controls, settlement discipline, and institutional workflow expectations become standard requirements across crypto lending markets.
Tokenized settlement is entering exchange rulebooks, not just pilot decks. Exchanges, broker dealers, custodians, transfer agents, market data teams, and compliance teams need to prepare for tokenized securities that still trade under national market system rules, surveillance, reporting, T+1 settlement, and existing investor protections.
Asset managers, exchanges, custodians, brokers, and treasury teams increasingly need infrastructure that supports tokenized funds, collateral, and yield products inside institutional operating environments. Tokenized finance is becoming part of mainstream capital markets strategy rather than a separate digital asset experiment.
Tokenization now reaches core market infrastructure, not just crypto trading activity. Exchanges, custodians, transfer agents, dealers, issuers, and infrastructure providers need operating models that support tokenized securities inside existing settlement, governance, reporting, and post trade systems.
Broker dealers, RIAs, custodians, wealth platforms, and compliance teams now have another regulated route to offer digital assets inside familiar securities account structures. That raises the bar for firms still treating crypto access as a separate product channel instead of a brokerage, custody, and supervision question.
MiCA implementation now becomes a licensing, supervision, and market access issue for crypto firms operating in Poland. Exchanges, custodians, stablecoin firms, brokers, and compliance teams should watch how national supervisors apply enforcement powers, authorization standards, and transition rules as Europe’s crypto framework enters active supervision.
Crypto exchanges, custodians, stablecoin issuers, tokenization firms, banks, compliance vendors, and capital markets platforms should track this markup closely. The bill text moves U.S. digital asset policy from broad debate into statutory architecture, with direct implications for token classification, intermediary registration, custody, disclosure, DeFi obligations, and cross border market access.
The common thread is operational readiness. Firms increasingly compete on whether they can support governed AI, tokenized assets, stablecoin settlement, and real time compliance inside production systems rather than separate innovation programs. That pressure now reaches broker dealers, PSPs, banks, treasury teams, exchanges, and compliance groups at the same time. Founders, operators, and investors tracking these changes may also want to review coverage on tokenized market infrastructure, AI agents entering governed financial workflows, and agent driven commerce and payments as these themes continue to converge across fintech markets.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 15, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Payments Rails And Market Infrastructure, Regulation And Policy
On May 7, 2026, the Bank of Canada published staff research on global cryptocurrency flows. The paper looks at why crypto moves across borders, using Bitcoin flow data across up to 162 countries and testing whether key findings also appear across major stablecoins.
It's a practical resource for fintech teams trying to understand where digital assets connect to remittances, payment friction, macro stress, capital controls, sanctions, and financial system gaps.
The paper uses Chainalysis data to study cross border crypto flows from 2020 Q3 to 2023 Q3. The authors focus on Bitcoin first, then extend the analysis to USDT, USDC, BUSD, and DAI. That makes the research useful for teams that need to separate market noise from real cross border usage patterns.
Crypto flows don't always behave like traditional capital flows. The paper finds that crypto activity can rise when macro conditions weaken, when financial systems work poorly, or when people need cheaper and faster ways to send money across borders.
Payment firms, remittance providers, banks, stablecoin companies, and compliance teams should take note. Crypto rails often gain relevance where traditional rails feel costly, slow, restricted, or unreliable.
The paper also helps explain why stablecoins are becoming more prominent in payments and treasury conversations. If stablecoin flows follow similar cross border patterns to Bitcoin in key areas, policymakers and market builders can't treat them as only crypto assets. They need to assess them as financial infrastructure.
For Canadian fintechs, if users, businesses, and institutions adopt digital rails for real cross border needs, firms need to know where those rails improve service, where they create risk, and where regulators may focus next.
This resource is useful for fintech founders, payment companies, remittance providers, stablecoin infrastructure firms, crypto platforms, banks, AML teams, policy analysts, market infrastructure providers, and investors tracking financial system modernization.
It's especially relevant for teams working on cross border settlement, digital wallets, treasury tools, programmable payments, blockchain analytics, custody, transaction monitoring, and compliance operations.
The strength of this paper is scope. It compares crypto flows across a large country sample and tests several possible drivers instead of relying on one simple adoption story. The authors look at macro conditions, financial system quality, remittances, institutional quality, capital controls, and sanctions.
The paper also avoids a common trap. It doesn't treat all crypto activity as speculation. It shows how payments, remittances, and financial stress can help explain real cross border usage.
The limit is data construction. Cross border crypto flow analysis still depends on attribution methods, exchange activity, web traffic estimates, and assumptions about where users are located. The authors discuss those limits clearly. The paper is also Bank of Canada staff research, not an official Bank of Canada policy position.
For fintech teams, the best use is practical benchmarking. Use it to understand why crypto rails gain traction, where stablecoins may keep growing, and which risks regulators are likely to monitor more closely.
Bank of Canada Staff Working Paper 2026-15 (primary research paper on global cryptocurrency flows)
Patterns And Determinants Of Global Cryptocurrency Flows PDF (full paper with methodology, data, and empirical results)
BIS Project Atlas (global work on mapping crypto and DeFi activity)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 13, 2026 | NCFA Fintech Market Activity | Wealth Capital Markets And Investing, Risk Compliance And Regtech, Artificial Intelligence And Data
On May 12, 2026, U.S. wealthtech platform Envestnet expanded its Canadian B2B push with new platform capabilities, local leadership, and advisor tools tied to Canada’s Total Cost Reporting (TCR) rules. Those rules will require firms to show clients the full cost of investment solutions in dollar terms beginning in 2027. As a result, advisors need better portfolio evidence, cleaner reporting, and stronger tools to explain value.
In 2020, Envestnet announced that it expanded its Canadian footprint through a strategic partnership with Canaccord Genuity Wealth Management. In March 2025, it launched a direct indexing solution for Canadian advisors that can sit inside a Unified Managed Account (UMA). Now the recent 2026 announcement adds a regulatory catalyst with Total Cost Reporting turning fee transparency into daily advisor work.
Canadian regulators have been building toward this for years. In April 2023, the Canadian Securities Administrators and the Canadian Council of Insurance Regulators announced enhanced cost reporting requirements for investment funds and segregated fund contracts. The goal is simple. Investors should see the ongoing costs of owning funds more clearly, both as a percentage and as an aggregate dollar amount.
CIRO’s enhanced cost reporting amendments took effect on January 1, 2026. Starting in 2027, clients will receive annual reports for the 2026 calendar year that show more detail on investment fund costs. That includes fund expenses in dollars and fund expense ratios.
For advisors, it changes the client conversation because they'll need to explain what clients paid, why they paid it, and how the portfolio supports the client’s goals.
Envestnet is building its Canadian offer around Unified Managed Accounts, multi currency portfolios, data insights, and model based portfolio construction. It also promoted David Kamerman, CFP®, Principal Director, Head of Canadian Business Development, to lead strategic relationships and Envestnet’s Canadian wealthtech business.
David Kamerman, CFP®, Principal Director, Head of Canadian Business Development, Envestnet:
“As Total Cost Reporting reshapes the industry, advisors need practical ways to modernize how portfolios are constructed and managed. Our Unified Managed Account platform empowers advisors to build model-based, cost-conscious, high-conviction portfolios at scale helping them deliver stronger client outcomes while running more efficient businesses.”
Unified Managed Accounts are useful because they can bring different investment sleeves into one account structure. That can help advisors combine models, direct indexing, tax aware customization, and cost reporting without stitching together too many tools.
Envestnet launched its Canadian direct indexing service in March 2025. Canadian registered firms can use it by hiring Envestnet as a sub advisor. Direct indexing gives advisors more control over tax treatment, exclusions, personalization, and security level portfolio design. Under TCR, that control becomes easier to explain because advisors can connect cost, portfolio design, and client goals.
TCR benefits companies that connect cost transparency with better portfolio construction. Conversely, TCR exposes firms that only add a report after the fact.
The Canadian wealthtech market already has strong local competition. In March 2026, Calgary based OneVest launched an AI native wealth operations platform for onboarding, account opening, money movement, billing, documents, and advisor workflows. That gives Canadian firms a modular option built closer to domestic needs.
Envestnet brings scale. The company says it has 25 years of operating experience, $7.0 trillion in platform assets, and relationships with more than one third of financial advisors across banks, wealth managers, brokerages, and RIAs. Scale helps, but Canadian firms will still judge the platform on integration, usability, reporting quality, support, and cost.
Envestnet says it has a growing pipeline in Canada, but it does not disclose key metrics or direct indexing uptake.
TCR is a regulation that creates software demand as it changes the daily work of advisors who need better data, clearer reporting and stronger client conversations. As Total Cost Reporting makes investment costs more visible, will Canadian wealth firms compete on lower fees alone, or on better portfolio design, clearer value, and stronger advisor technology?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 12, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization
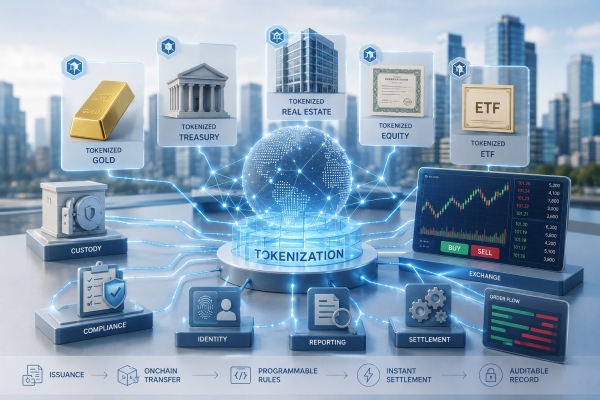
On May 4 2026, CoinGecko published its 2026 RWA Report, and the numbers tell a more interesting story than usual.
But here’s the unusual part. Most major RWA project tokens didn't benefit from that growth. CoinGecko found that six of the top seven RWA project tokens posted negative returns from January 1 2025 to March 31 2026, with losses ranging from 44.7% to 98.8%.
Tokenized assets are gaining traction, but the report shows a clear split. The market is growing around the systems that make tokenized assets useful, such as access, custody, liquidity, collateral, compliance, and distribution. It's not showing the same strength in the project tokens that investors once used to bet on the RWA theme.
Tokenized RWAs are growing quickly, but they still equal only 6.4% of the stablecoin market. Stablecoins grew from $199.77B to $301.65B during the same period.
It's a significant gap because BlackRock Targets Stablecoin Reserve Market in digital finance to help money move, settle trades, and flow collateral between platforms. Tokenized assets are building on that base, not replacing it.
The report also shows a clear preference for more institution friendly products. USDC grew 76.2% to $77.44B, while smaller regulated or compliance focused stablecoins also gained ground. That says demand is heading toward products that platforms, institutions, and regulators can actually work with.
Tokenized treasuries still lead the category, growing from $4.00B to $12.99B over the report period. But their market share fell from 73.7% to 67.2% as commodities, tokenized stocks, ETFs, and derivatives gained traction.
For much of the last cycle, Real World Assets mostly meant tokenized treasury products. Now the category is widening into broader market exposure.
Tokenized stocks scaled from $2.09M in June 2025 to $486.69M by March 2026. Tokenized ETF market capitalization reached $297.50M. The numbers are still very small compared to traditional markets, but are trending.
Tokenized commodities grew from $1.43B to $5.55B, driven mainly by gold backed products including PAXG and XAUT. The trading activity is telling. Tokenized gold recorded $90.70B in spot trading volume during Q1 2026, already higher than the full 2025 total of $84.64B.
That makes sense given gold's familiarity. It has deep global demand and already plays a role in portfolios and collateral conversations. Tokenization gives it faster movement, digital custody options, and easier access across crypto native platforms.
The report shows how quickly centralized platforms, such as Kraken, Coinbase, Crypto.com, Binance or Gate are now combining some mix of tokenized securities, stocks, ETFs, commodities, futures, perps, or licensed financial infrastructure alongside crypto trading.
The lines between crypto exchange, broker, derivatives venue, and tokenized asset marketplace are getting thinner. That raises the operating bar. It's also where major infrastructure opportunities start to appear.
RWA perps generated $524.79B in Q1 2026 trading volume alone, while daily open interest rose from $0.14B at the start of 2025 to $6.68B by March 31 2026.
The data suggests that many traders want exposure to real world asset prices without necessarily holding the underlying tokenized asset. Commodities still dominate this market, but stock and ETF perps are growing. Hyperliquid’s HIP-3 volume rose from $12.65B in Q4 2025 to $130.87B in Q1 2026.
This is trading infrastructure forming around tokenized and traditional assets at the same time.
CoinGecko’s report shows a tokenized asset market growing quickly, but unevenly. Tokenization is becoming infrastructure. Stablecoins still do the heavy lifting. Treasuries still lead. Gold trading volume has surged. Exchanges are adding capital markets functions. RWA perps are scaling quickly. At the same time, most RWA project tokens continue falling.
Tokenization is starting to look less like crypto hype and more like financial infrastructure that can make tokenized assets useful, compliant, liquid, and easy to access at scale.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 12, 2026 | NCFA Feature | Digital Banking And Credit Union Infrastructure

On May 12 2026, Intellect Design Arena announced that 37 Canadian financial institutions participating in the National Digital Banking Working Group (NDBWG) selected its eMACH.ai Digital Engagement Platform as part of a broader digital banking modernization effort.
This is more than a software contract. It's one of the clearest examples of smaller Canadian financial institutions coordinating technology execution to manage platform risk, modernization costs, and rising digital banking expectations.
Back in October 2024, Canadian credit union infrastructure provider Central 1 announced plans to wind down digital banking over a three to four year transition period. That created immediate pressure for many Canadian credit unions that relied on Central 1’s Forge and MemberDirect platforms.
In March 2025, Central 1 and Intellect finalized an operating partnership that transferred operation of Forge, MemberDirect, public website, and mobile app products to Intellect, along with digital banking engineering and service personnel.
The latest announcement now evolves beyond transition support into long term modernization.
The National Digital Banking Working Group formed after the Central 1 announcement to help participating institutions coordinate vendor evaluation, migration planning, procurement, implementation support, and governance.
According to NDBWG's website, the initiative was designed to help financial institutions navigate a system wide platform transition together instead of individually carrying the cost, risk, and operational complexity of replacing digital banking infrastructure. It's a coordinated modernization program.
NDBWG’s public member page lists 59 participating institutions across British Columbia, Alberta, Saskatchewan, Manitoba, and Ontario. The specific 37 institutions that formally signed with Intellect is likely a subset. Intellect states the participating institutions represent more than $11.7B CAD in combined assets and serve over 262,000 members.
Greg Sol, Board Chair, Credit Unions Future Committee:
“Building on the NDBWG’s rigorous process from vendor evaluation to a fully negotiated agreement, we’re confident that Intellect is the right long-term partner for Canada’s financial institutions.”
Canada’s banking competition debate often focuses on large banks and fintech challengers. Less attention goes to the infrastructure pressure facing smaller regional and community based financial institutions.
Members compare their credit union app with all other digital services they use daily. They expect simple onboarding, quick support, fewer branch visits, and secure ways to handle routine requests. Behind that experience, smaller institutions also face heavier compliance work, sharper fraud risk, and technology costs that keep climbing. For many smaller institutions, maintaining those capabilities independently becomes harder every year.
NDBWG’s model attempts to create digital scale without forcing consolidation. Participating institutions keep their local brands, governance, and member relationships while coordinating around infrastructure, migration planning, and platform execution.
The stronger advantage of a shared approach isn't the software itself, but rather the emerging operating model around it.
Canada already has one of the most concentrated banking systems in the world. If smaller institutions cannot modernize efficiently, the competitive gap widens further. Shared infrastructure and coordinated execution may become one of the few realistic ways for regional financial institutions to stay competitive without dramatically increasing operating costs.
Canada continues preparing for consumer driven banking, stronger fraud controls, and real time payments modernization. Those changes place additional pressure on legacy systems and fragmented operating models.
Steve Kingan, CEO, Frontline Credit Union:
“The NDBWG process gave our credit union the expertise and collective strength to navigate this transition in a way we couldn’t have managed alone.”
For fintech companies, this may also create opportunity. Smaller institutions need practical tools that reduce daily friction, protect members, and improve service without adding complexity. That creates room for focused partners in fraud prevention, digital identity, payments, workflow automation, AI assisted service, and embedded financial services tailored for smaller institutions.
It also explains why more vendors are building Canada ready digital banking platforms for credit unions rather than treating them as small versions of large banks.
Canada’s smaller financial institutions are starting to treat digital infrastructure as a shared strategic capability instead of a fully independent function.
NDBWG represents one of the clearest Canadian examples so far of institutions coordinating modernization to support local financial competition while reducing migration risk and operational cost. If implementation succeeds, it could become a practical model for how smaller financial institutions modernize in other parts of Canada.
Can smaller Canadian financial institutions can build enough shared digital scale to remain competitive while preserving regional and community based banking choice?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016