




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 25, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization
On May 20, 2026, 3iQ selected Anchorage Digital as the infrastructure and custody partner for its Canadian product suite. Subject to regulatory approvals and required prospectus or offering document amendments, 3iQ intends to migrate a significant portion of assets under management across six TSX listed exchange traded products to Anchorage Digital.
3iQ is a Canadian digital asset investment manager with a regulated public product suite. Anchorage Digital became the first OCC approved national crypto bank in the U.S. Canada has qualified digital asset custodians, but not an equivalent national crypto bank structure at Anchorage’s scale. The decision puts a hard question in front of Canada’s digital asset sector. Can Canadian infrastructure win large institutional mandates when issuers need custody, settlement, staking support, and regulatory comfort at scale?
The warning is now showing up in market activity. Canada has already debated whether domestic digital asset infrastructure can compete with larger U.S. regulated platforms. That issue became more visible when Balance applied for a Canadian special purpose trust structure to build institutional digital asset custody capacity at home.
If Canada approves digital asset products but doesn't build trusted infrastructure at home, more of the work, jobs, and revenue may migrate south. In this case, 3iQ keeps the Canadian listed products while Anchorage Digital captures more of the custody and infrastructure work behind them.
That choice is commercial, not patriotic. Large issuers choose the stack that lowers operating risk and helps them launch better products. That’s the reality test Canadian infrastructure providers now face.
3iQ says Anchorage Digital lets funds settle trades from cold storage without relying on hot wallets. Its Atlas network also lets 3iQ settle directly with trading counterparties and remove extra wallet steps. It means custody now affects much more than safekeeping. It affects how funds trade, settle, manage risk, support staking, and protect investors.
The partnership is also expected to support 3iQ’s expanded staking capabilities. That raises the stakes. Staking needs more than token custody. It needs validator access, clean reporting, strong controls, and regulatory comfort. The right custody partner can give a fund more room to build. The wrong one can hold it back.
Tommaso Mancuso, President and CIO of 3iQ:
"3iQ needs infrastructure providers that meet “the highest standards for security, flexibility, and regulatory alignment.”
That is the standard Canadian infrastructure has to meet now. Canada has digital asset talent, regulated products, custody ambition, and a real institutional market. But the operating stack behind those products still needs more depth, if they want to compete. Fund issuers need platforms that can handle scale, connect cleanly to trading counterparties, support approved product features, and satisfy regulators without adding friction.
Canadian policymakers should treat this as a competitiveness warning. Product approvals aren't enough if the custody, settlement, staking, and fund operations work scales outside Canada. The goal should be to keep more trusted digital asset infrastructure, jobs, and revenue at home.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 22, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Payments And Money Movement

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026).
Institutional digital asset infrastructure is increasingly converging around unified execution, settlement, compliance, and liquidity layers. Banks, fintechs, custodians, PSPs, brokers, and treasury teams should track how tokenized funds, stablecoin settlement, collateral movement, and onchain liquidity are becoming integrated into institutional operating environments rather than isolated crypto workflows.
Bank led stablecoins are becoming part of Europe’s regulated payment strategy. Banks, PSPs, stablecoin issuers, custodians, treasury teams, and compliance groups should track how euro denominated stablecoin infrastructure affects settlement options, liquidity design, and competition with USD stablecoins.
Stablecoin distribution is becoming a network access problem. Wallets, exchanges, PSPs, brokers, and embedded finance platforms need interoperability, regulated issuance, liquidity, and compliance controls that let users move between stablecoin networks without adding operational friction.
New York licensing remains a key test for institutional digital asset firms. Exchanges, custodians, brokers, lenders, and compliance teams should track which firms secure state level approvals because market access, client onboarding, and institutional trust still depend on regulated operating permissions.
USD account access is becoming embedded infrastructure for global platforms, not just a bank product. Fintechs, PSPs, marketplaces, payroll firms, and treasury teams should watch how account issuance, compliance controls, real time payments, and stablecoin rails converge inside programmable payment stacks.
Canadian dollar stablecoins are beginning to enter practical payment flows instead of remaining treasury or trading instruments. PSPs, banks, remittance firms, treasury teams, and compliance groups should watch how regulated stablecoin settlement changes cross border payout speed, corridor economics, liquidity management, and payment competition. CADC infrastructure continues to expand across Canadian digital payment markets.
Bitcoin reserve legislation is turning digital assets into a public balance sheet question, not just a market regulation debate. Crypto firms, custodians, exchanges, treasury teams, investors, and policymakers should track how federal reserve asset policy, seized digital asset management, and national competitiveness arguments reshape the next phase of U.S. crypto policy.
Card network economics are moving deeper into formal regulatory reporting. Merchants, acquirers, issuers, PSPs, payment networks, and embedded payment platforms should track how fee transparency, profitability evidence, and scheme oversight affect payment costs and competitive pressure across card acceptance.
The FCA is creating a clearer supervisory channel for firms that are already scaling, not just early sandbox participants. That matters because fast growth often creates new questions around controls, governance, technology, and consumer impact before a firm becomes systemically important.
Prediction markets are becoming a direct federal versus state jurisdiction fight. Exchanges, fintech platforms, compliance teams, policymakers, and investors should track how courts treat event contracts because the outcome could affect federal derivatives oversight, state gambling authority, consumer protection rules, and regulated forecasting markets.
Federal policymakers increasingly treat fintech infrastructure as part of U.S. financial competitiveness strategy. Banks, PSPs, digital asset firms, payment companies, and infrastructure providers should track how payment rail access, supervision, settlement services, and master account policy evolve as regulators face growing pressure to integrate fintech firms into core financial systems.
UK stablecoin policy is moving toward draft rule text and implementation design. Stablecoin issuers, banks, PSPs, custodians, wallets, and treasury teams should track how the Bank balances financial stability controls with usable payment products, especially around issuance limits, redemption, reserves, and access to settlement infrastructure.
Lowering community bank burden can open capacity, not just reduce paperwork. Fintechs, sponsor banks, core providers, lenders, and compliance teams should track whether tailored supervision gives smaller banks more room to partner, modernize, lend, and support local payment and deposit infrastructure.
Onchain markets need clearing and netting controls before more institutions treat them as reliable operating channels. Trading firms, custodians, brokers, stablecoin networks, and treasury teams should track how private obligation matching, liquidity savings, and counterparty controls develop across institutional digital asset markets.
Prediction markets are moving beyond politics and sports into private capital market intelligence. Exchanges, investors, fintech platforms, regulators, and market infrastructure providers should track how forecasting markets, institutional secondary market data, and tokenized trading systems increasingly converge around private company price discovery and market sentiment.
Regional exchange infrastructure competition continues to expand beyond traditional Western commodity benchmarks. Exchanges, clearing firms, commodity traders, treasury groups, and market infrastructure operators should track how Singapore based benchmarks, physical delivery systems, and digitally enabled collateral infrastructure increasingly support Asian commodity trade and price discovery.
The case is a governance and creditor risk warning for Canada’s fintech funding market. Investors, lenders, founders, and boards should keep closer watch on treasury controls, debt covenants, founder conduct, and creditor transparency as capital becomes more selective.
Canada’s MSB compliance risk is increasingly visible across multi service fintech models. Crypto firms, PSPs, FX dealers, remittance platforms, investors, and compliance teams should keep registration data current, map services accurately, and treat FINTRAC responsiveness as an operating requirement.
Payments, digital assets, AI fraud controls, and capital markets infrastructure are being rebuilt by registered firms with licenses, distribution, data, and balance sheets. Smaller fintechs can still win, but only where they solve a real operating problem and plug into the financial system with trust from day one. The opportunity is still open, but it will favour teams that move quickly, stay compliant, earn trust, and turn infrastructure change into useful products for customers, merchants, investors, and institutions.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 22, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Payments And Money Movement
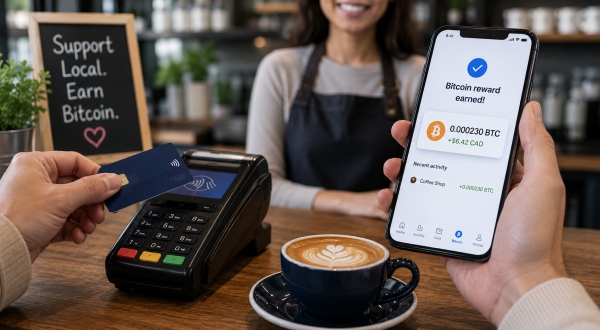
On May 21, 2026, Montreal based Shakepay opened the waitlist for its physical Shakepay Visa Prepaid Card and launched a 21 day campaign that turns everyday card payments into bitcoin rewards for customers and participating local businesses. The campaign builds on Shakepay’s Virtual Card, which the company says thousands of Canadians already use every week to earn bitcoin rewards on purchases.
Here’s how it works. Customers tap the Virtual Shakepay Card in store and earn points toward early access to the physical card. Those payments can also place local businesses on Shakepay’s campaign map. Businesses that sign up for Shakepay for Business during the campaign can claim bitcoin rewards after verification.
Shakepay is using rewards, merchants, and local campaign mechanics to push bitcoin into daily payment behaviour without asking customers or businesses to use bitcoin at checkout.
Jean Amiouny, CEO, Shakepay:
“Most rewards programs give people points they can only use inside someone else's system. We think Canadians should be able to earn an asset they can actually own,”
Shakepay is reframing rewards around ownership. Customers spend from their cash balance and earn rewards paid in bitcoin. That differs from closed loyalty points, which usually keep value inside one retailer, issuer, or rewards system.
Small businesses can explore bitcoin reserves without rebuilding payment acceptance or asking customers to pay with crypto. The bitcoin reward is tied to campaign activity and business onboarding, not direct bitcoin checkout.
The top 21,000 customers on the waitlist will receive early access to the physical card. The top 2,100 will be eligible for a Launch Edition card engraved with their waitlist rank. That gamified structure gives Shakepay a way to measure demand before full rollout.
The company says it helps more than 1.5 million Canadians access and use bitcoin through everyday financial products. Shakepay is a CIRO member, an Investment Dealer registered with the AMF, and a FINTRAC registered Money Service Business. They also recently became a member of Payments Canada. The Shakepay Visa Prepaid Card is issued by Peoples Trust Company under licence from Visa International Service Association.
Shakepay is testing whether bitcoin rewards can become a daily payments wedge in Canada. If the model works, bitcoin doesn't need to replace card rails to gain utility. It can ride on top of card spending, rewards, and small business treasury behaviour.
Will bitcoin adoption in Canada grow through direct crypto payments, or through familiar card and rewards products that make bitcoin part of everyday spending?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 22, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Payments And Money Movement, Capital Markets And Market Infrastructure
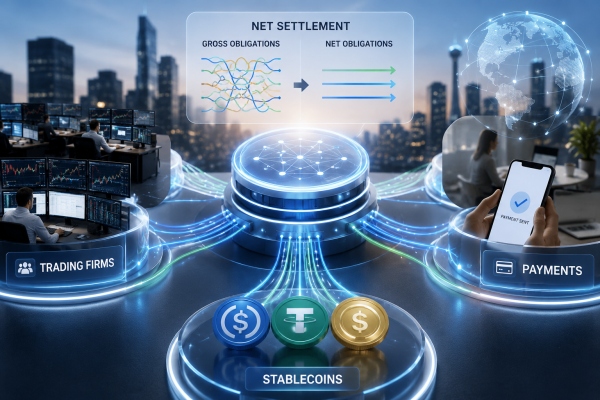
On May 21, 2026, Toronto based Cycles raised $6.4 million to build an open, privacy preserving clearing network for crypto markets and stablecoin payments. Blockchange Ventures led the round, with participation from Coinbase Ventures, Compound VC, Primitive Ventures, and angel investors. The round brings Cycles’ total funding to $8.7 million, following a $2.3 million pre seed in 2025.
Cycles is targeting one of the least glamorous but most important parts of financial infrastructure: clearing. In traditional markets, clearing reduces how much money has to move between counterparties by offsetting obligations first. Cycles wants to bring that function to on chain finance, where trading and payment flows still often require too much prefunding and too much gross settlement.
The first institutional product is Cycles Prime, which lets trading firms privately net OTC obligations across the network. Cycles says this can reduce liquidity requirements and counterparty exposure without requiring collateral, asset movement, or a change in counterparties. Cycles Prime is launching with Lynq and FalconX as anchor partners.
Ethan Buchman, Co Founder and CEO, Cycles:
“Clearing is a financial superpower that has historically only been available to large financial institutions,”
Without clearing, firms often move full payments back and forth instead of only settling the difference. That ties up capital and can increase risk when markets move quickly.
The release points to October 10, 2025, when more than $19 billion in crypto leverage was liquidated in roughly one day, with 70% of forced liquidations occurring in just 40 minutes. Cycles uses that event to show why capital efficiency matters. When markets rely on gross settlement and heavy prefunding, stress can move fast.
Cycles is betting that multilateral clearing can reduce that pressure. Meaning, many obligations can be matched against each other so less money has to move. If it works, trading firms may keep less idle capital parked across venues and counterparties.
The second product is Cycles Pay, a stablecoin payments app for individuals and businesses. Payments are routed through Cycles’ clearing engine, which nets obligations across participants to minimize capital movement. The product also includes invoicing and expense management with credit planned.
Stablecoins already help move value across networks. Clearing can make those flows more capital efficient. For businesses, the value isn't only faster payment. It's fewer trapped balances, better cash flow, and more private settlement.
Rob Schmults, General Partner at Blockchange Ventures:
"Clearing is the cornerstone of capital-efficient markets like foreign exchange allowing the movement of massive volumes of value without crippling liquidity requirements. We see Cycles providing an essential coordination layer to bring the efficiency and effectiveness of clearing to new markets. Doing this will allow businesses to clear and settle payments privately, optimize capital flow, and reduce the need for idle capital. As global adoption accelerates, Cycles can become a category defining standard for how value is settled and netted across entire ecosystems and markets."
If stablecoins are becoming payment rails, will clearing become the missing layer that turns on chain settlement from fast movement into capital efficient market infrastructure?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 22, 2026 | NCFA Market Activity | Banking And Credit Infrastructure, Payments And Market Infrastructure, Lending Consumer Credit And BNPL, Artificial Intelligence And Data
On May 21, 2026, Wealthsimple unveiled a major expansion of its financial services platform during its live product event, “Wealthsimple Takes Over Your Life”. The announcements included family accounts, business chequing, USD accounts, portfolio backed credit, spend insights, overdraft protection, and a monthly $1M client rewards program. The company said more than 4 million Canadians now use Wealthsimple and hold $150B in assets on the platform.
Wealthsimple isn't a Schedule I bank, but it delivers banking style services through regulated Wealthsimple entities, infrastructure access, and partner financial institutions. Wealthsimple says chequing balances are held in trust with CDIC member institutions, while Wealthsimple Payments Inc. and Wealthsimple Investments Inc. are not CDIC member institutions. Power Corporation disclosed a controlling interest in Wealthsimple through Power Financial, Great-West Lifeco, and IGM. In Q1 2026 results, Power valued its Wealthsimple ownership at $3.8B as of March 31, 2026.
NCFA also covered Wealthsimple’s $750M financing and $10B valuation, which gave Canadian fintech markets one of the rarest and strongest scaleup stories.
The event hit home how far Wealthsimple has moved beyond investing and trading. The company now wants a larger share of daily financial activity across deposits, payments, borrowing, business banking, and household finance.
This builds on earlier product expansion when Wealthsimple added credit and loan tools in 2025, including a cash back credit card and low interest credit line. The latest event pushes that same strategy further into operating accounts, secured borrowing, and household controls.
The business banking launch carried the clearest fintech impact. Wealthsimple introduced business chequing with online setup in less than 20 minutes, virtual cards, automated CRA payments, recurring transfers, interest bearing balances, and higher e transfer limits.
Those features target familiar problems for Canadian SMEs. Many owners still deal with low transfer limits, little or no yield on operating balances, manual tax payments, and weak cash management tools.
The Portfolio Line Of Credit may become one of the company’s most important financial products. Wealthsimple said eligible clients can borrow against portfolios at rates as low as prime minus 0.5%, or about 3.95% at the time of the event.
Clients can borrow up to 35% of portfolio value. A client with $200,000 on the platform could access up to $70,000 in credit, subject to eligibility and risk controls.
The product gives clients a way to fund business expenses, inventory purchases, major purchases, or debt refinancing without selling investments. This type of secured liquidity has historically been more common in private banking and wealth management.
For Wealthsimple, portfolio credit also deepens the customer relationship. The more assets clients keep on the platform, the more useful the credit product becomes.
Wealthsimple introduced three family finance products. Kids and teens accounts give parents card controls, alerts, limits, instant transfers, and parent paid interest. Households lets partners choose what they share, track accounts inside and outside Wealthsimple, and view family finances in one place.
Authorized traders lets a trusted family member make trades on another person’s behalf without password sharing. That addresses a practical issue. Many Canadians already help spouses, parents, or relatives manage investments informally. Wealthsimple is formalizing that process with permission based account access.
Wealthsimple also pointed to deeper access across Canadian payment systems. The company linked that access to cheaper wire transfers, free incoming wires, faster payroll deposits, lower FX costs, instant virtual card issuance, cash deposits through Canada Post, and ATM fee reimbursements.
Wealthsimple gained direct Swift access, becoming the first Canadian fintech to do so. It supports the company’s push into wires, cross border money movement, and lower cost global payments.
The Canada Post cash deposit feature gives clients access to more than 5,000 deposit locations. Wealthsimple said it processed cash deposit transactions in more than 900 communities during the first two months after launch.
Infrastructure access increasingly matters for large fintech platforms. It can improve speed, pricing, product flexibility, and customer experience while reducing dependence on older branch based banking workflows.
Wealthsimple’s Monthly Millionaire program will award $1M each month to one client. Every dollar deposited or saved creates an entry, while direct deposit doubles entries. Move over 'roll up the rim to win'!
The structure encourages clients to move payroll deposits and savings activity onto the platform. For Wealthsimple, that supports higher deposits, stronger engagement, and more primary account usage.
Canadian fintech competition is increasingly focused on who controls the broader financial relationship, not just a single product category. Wealthsimple now spans deposits, payments, investing, borrowing, family finance, business banking, and cross border accounts.
That puts the company into more direct competition with incumbent financial institutions across several revenue areas at once. The company's expansion shows how quickly a Canadian fintech can move when scale, capital, trust, and distribution come together.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 21, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization
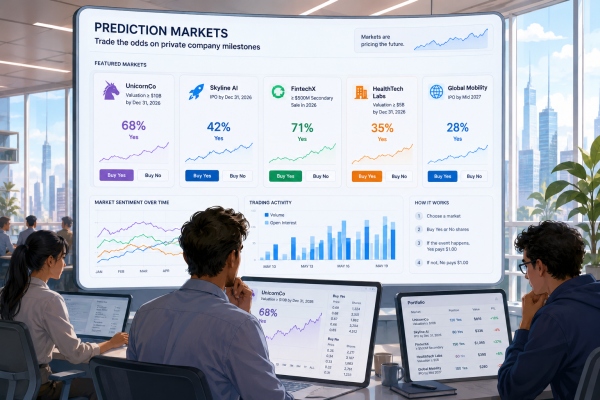
On May 19, 2026, Polymarket launched prediction markets tied to private company milestones, using Nasdaq Private Market data to resolve the contracts. Users can trade on events such as valuation milestones, IPO timing, and secondary market activity.
This isn't a gamble on private company ownership, since traders don't get shares, voting or information rights, or access to a company’s cap table. They get a tradable contract with a public price that reflects the market’s view of whether a specific private company event will happen. While the product doesn't open up private equity to everyone. It enables the public to take odds around private market outcomes.
Nasdaq Private Market says nearly 1,600 global unicorns now hold more than USD $5 trillion in combined value, while access remains mostly limited to institutions and high net worth investors. Private markets keep getting larger. Public visibility still lags.
Shayne Coplan, Founder and CEO, Polymarket:
“Prediction markets are one of the most powerful tools we have for democratizing access to financial information and opportunity.”
Private market pricing often arrives late. A funding round may show what investors paid albeit months ago. A tender may show one clearing point for one group of sellers. A secondary trade may reflect scarcity, transfer limits, or a specific share class. But the fact is none of those inputs gives the public a continuous read on what people think will happen next.
A contract price shows the market’s view of a future event, not the company’s fair value. If a contract trades near 70 cents, traders are roughly pricing a 70% chance that the event occurs. That doesn't necessarily make the odds right, but it makes the belief visible.
That in itself could move the needle for founders, employees, late stage investors, secondaries desks, and allocators. A live probability can show:
The Nasdaq Private Market (NPM) brings private market data from primary and secondary market activity, which gives the contracts a stronger reference point than rumours, social posts, or loose valuation chatter.
NPM also brings scale, and with that trust. The company says it's executed nearly USD $80 billion in secondary liquidity for more than 200,000 eligible employee shareholders and investors across more than 1,000 company sponsored liquidity programs. It's an important point because typically private market data is thin and opaque:
Prediction odds will be strongest where the underlying data is deep, current, and easy to verify. Or as Tom Callahan, CEO, Nasdaq Private Market puts it, “When retail participants enter any market, high-integrity data matters.”
This product could make private valuations harder to ignore and harder to defend. If a company carries a high valuation but prediction odds show weak confidence in a future valuation milestone, investors begin to lose confidence or ask sharper questions. If odds move right after a fundraise, product launch, regulatory event, or IPO rumour, the market gets a faster read on sentiment.
Secondaries may feel the effect first.
Prediction market odds don't replace diligence. But they add a public probability signal to a market that still depends on financials, contracts, board materials, customer data, and negotiated access.
One of the risks of course is a false signal. A small market can falsely produce a strong probability that rests on weak liquidity. A contract price may reflect a few motivated traders, not a deep view of private company value.
Information gaps also matter. Employees, early investors, brokers, lawyers, customers, and suppliers may know more than the public. As private company prediction markets grow, market integrity will become a bigger issue. Volume, open interest, spreads, trader concentration, and resolution rules will matter as much as the headline odds.
Regulators will be watching. These contracts straddle several policy lines at once, such as derivatives, gambling, securities, consumer protection, and private company information. The more these odds affect private market behaviour, the more scrutiny they will attract.
The strongest use case is private market intelligence. Prediction odds could augment traditional signals, such as secondary market data, valuations and company reported events. Together, the combined inputs may give investors a better view of timing, sentiment, and confidence before an IPO or liquidity event.
Private market infrastructure is becoming more transparent and data driven. Platforms that help investors understand price, risk, liquidity, and timing will have an advantage.
For founders, it adds a new pressure point to manage. Once the public can trade on company milestones, valuation becomes a public narrative before a public listing. That can create attention. It can also expose weak communication, inflated expectations, or a gap between private marks and public belief.
Bottom line: More companies are staying private longer, and more value is being created before public investors can participate. Prediction markets won't fix access on their own. But they may push the market toward better pricing tools, cleaner data, and more honest conversations about private company value.
If the odds become liquid enough, will private marks start answering to public probability signals?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 19, 2026 | NCFA Fintech Market Activity | SME Finance And Business Banking, Capital Markets And Funding
On May 19, 2026, Toronto founded fintech scaleup Relay secured $50 million in growth financing from General Catalyst’s Customer Value Fund. Relay serves U.S. small businesses with banking and money management tools. The financing is meant to accelerate customer acquisition while Relay keeps existing investment focused on product development.
Relay now supports more than 150,000 small business customers and oversees more than $1.3 billion in managed customer deposits through Thread Bank, Member FDIC. Since its $32.2 million Series B in May 2024, Relay says it is on track to grow revenue by 3.2x by the end of 2026.
The funding isn't a traditional equity round, since the General Catalyst’s Customer Value Fund gives Relay capital for customer acquisition. That lets the company spend on growth without pulling the same dollars away from product, compliance, support, and reliability.
Yoseph West, Co Founder and CEO, Relay:
“Every dollar invested in Relay supports passionate folks who work hard to build their businesses and realize their ambitions. This investment is a vote of confidence in the true value we deliver to those self-made entrepreneurs, so they can put every dollar to work,”
Relay already has customer scale, deposit traction, and a clear revenue growth target. The investor question is whether paid acquisition can keep working as Relay expands its brand footprint in the U.S. small business market?
Growth can damage a financial product if the operating base isn't ready. Small businesses need stable banking access, clear cash flow views, reliable support, and simple money movement. If acquisition gets ahead of service quality, trust can break quickly.
Andrew Ziperski, Partner, General Catalyst, Customer Value Fund:
“Relay has proven its deep understanding of what small business owners actually need to succeed, with a product that clearly resonates based on the strength of its customer acquisition machine.”
Relay is trying to own more of the small business finance workflow, not just the bank account. Its platform brings together accounts, cards, bills, invoices, capital, and other money tools. That gives owners a clearer view of cash coming in, cash going out, and what they can safely spend.
Recent product activity supports that strategy. Relay’s site now highlights receivables tools for invoices and payments, while its support pages show invoice tracking, accepted payment options, automatic reminders, and recurring invoices. Relay has also added Relay Capital term loans, offering small business lending alongside the same platform where owners already manage money.
That's where SMB banking is heading. Cash flow clarity helps them decide when to pay bills, hire, buy inventory, chase receivables, or seek financing. Relay’s strategy is to turn that daily operating pressure into the product.
Important caveat is that Relay's a financial technology company, not an FDIC insured bank. Banking services not related to Relay Capital term loans are provided by Thread Bank, Member FDIC.
Relay Capital term loans are provided through Fundbox, with business loans originated by Lead Bank. That partner model is common in U.S. fintech, but it puts pressure on compliance, disclosures, customer experience, and operational control.
SMB finance remains a large market, but the winning product is no longer just an account. It's the operating system that helps owners see cash, move money, access capital, and make faster decisions when conditions get messy.
If customer acquisition can be funded separately from core product investment, do stronger platforms gain an edge by scaling distribution without weakening banking reliability, support, and product depth?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016