




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


October 22, 2026
Customer acquisition is a moving target for fintech companies. A new product may need immediate visibility, while an established one may already attract visitors through search. The questions customers ask can change as the company adds features, enters new markets, or learns which audiences are most likely to convert. A search budget set at launch should be able to change along with the business.
Working with a digital marketing agency that manages both SEO and Google Ads makes those changes easier to spot and act on. The same team can see which paid searches produce qualified prospects, which website pages are gaining organic visibility, and where the next portion of the budget could have the greatest effect. Rather than treating ads and SEO as unrelated expenses, a fintech company can use them as parts of one customer acquisition plan.
Google Ads can help a company reach people searching for a relevant product today. That is useful for a launch, a new service, or a market where the company has little organic visibility. Paid campaigns can also reveal which search terms generate interest and which messages persuade visitors to take the next step.
SEO usually takes longer. A company needs pages that answer customer questions clearly, explain its products, and make its website easy to use. Those pages may gain organic visibility over time, giving prospective customers another way to discover the business. SEO still requires investment in research, content, technical work, and upkeep. Its value is that a useful page can continue attracting relevant visitors between campaign launches.
Neither channel should be expected to do every job. An ad can bring a visitor to a new product page before that page has earned an organic ranking. A well-established guide can introduce people to a problem before they are ready to request a demo. Together, the channels can reach customers at different points in their decision-making process.
A fintech company may begin with an informed guess about the words customers use. Actual search activity can challenge that guess.
Imagine a company offering expense-management software to small businesses. Its team might describe the product as an “expense automation platform,” while potential customers search for “track employee expenses” or “approve staff reimbursements.” Google Ads can help the company test these terms and see whether visitors who use them become qualified leads.
Those findings should inform the website. If a particular question repeatedly brings in the right audience, the company may need a dedicated page that answers it in detail. If visitors respond to a specific benefit in an ad, the landing page should explain that benefit just as clearly. Paid campaigns can therefore do more than generate traffic; they can help a company learn how customers describe their needs.
That learning is particularly valuable when marketing a product that takes time to understand. A prospective customer may need to compare approaches, review features, and discuss the purchase internally before making contact. Useful SEO content can support that process long after the first ad click.
As pages gain organic visibility, the role of paid search may change. Suppose the expense-management company publishes a practical guide to managing employee reimbursements. At first, it uses ads to reach people searching for that topic. Several months later, the guide and a related product page begin attracting relevant organic visitors and generating demo requests.
The company now has a decision to test. It could reduce paid spending on some of those searches and use the available budget to promote a new feature or reach a different audience. It could also keep the ads running if they continue to generate customers the organic results do not capture.
The important point is to make a measured change. A high organic ranking does not prove that an ad is unnecessary. Some people will click an ad even when the same company appears below it in search results. Others may respond to a particular ad message or arrive on a more focused landing page. Cutting spend based on rankings alone could reduce the total number of qualified leads.
A sensible test would adjust the budget gradually, then compare the combined results from paid and organic search. Did the number of qualified demos change? Did acquisition costs improve? Did the company reach customers it might otherwise have missed? Those answers should determine the next move.
Reallocating budget is more useful than simply reducing it. If organic search begins serving one established topic well, paid media can help the company pursue something new.
That might mean testing searches related to a recently released feature. It could mean reaching a new type of business, promoting a page built for a different market, or learning whether a more competitive term can produce customers at an acceptable cost. Ads provide a way to gather evidence while the company develops the content and organic presence needed for a longer-term effort.
The flow can also work in the opposite direction. If an SEO page starts attracting relevant visitors but few of them enquire, the team can test new messages and calls to action through paid campaigns. Results from those tests can guide improvements to the page.
This creates a cycle: ads provide timely feedback, SEO builds on what the company learns, and organic results help the team decide where paid spend is most useful next. The budget follows customer demand and business priorities rather than staying attached to a fixed list of keywords.
A search report can look encouraging while hiding a problem. Ads may generate clicks from people who cannot use the product. A page may rank well for a popular question but attract readers who are unlikely to become customers. For a fintech company, traffic and rankings matter most when they contribute to a worthwhile business result.
Before changing the budget, the team should agree on what a valuable conversion looks like. Depending on the product, that might be a qualified demo request, a completed application, or a new account that meets the company’s customer criteria. It should then track those outcomes across both paid and organic search.
Sales feedback adds another layer. Are the leads asking about the product the company actually offers? Do they serve the market the company can support? Are they ready to take a meaningful next step? Answers to those questions can be more useful than a lower cost per click.
Shared measurement also prevents each channel from claiming success in isolation. If the ads team reports more leads and the SEO team reports more traffic, the business still needs to know whether overall customer acquisition improved. Looking at the full picture makes budget decisions more credible.
Coordinated search marketing depends on what happens after someone clicks. A strong ad cannot compensate for a page that leaves visitors unsure what the product does. Likewise, organic visibility has limited value if the page does not help the right person decide what to do next.
The website should answer the question that brought the visitor there. A search for a specific feature should lead to a page explaining that feature, who it helps, and how it works. A broader educational search may be better served by a guide that explains the issue before introducing the product. Clear navigation can help readers move from learning to comparing and, when they are ready, to making contact.
For fintech companies, clarity is especially important. Customers may be evaluating a service that affects how they handle money or business operations. Marketing copy should explain the offer plainly and accurately. The SEO and ads teams should work from the same product information so that the promise in a search result matches the experience on the page.
A combined strategy does not require constant changes to campaigns. It requires a regular opportunity to ask whether the current allocation still makes sense.
In a monthly review, a company and its marketing team might look at the searches producing qualified customers, the pages gaining organic traction, and the areas where visibility remains weak. They can then choose a small number of changes to test: update a landing page, develop content around a proven customer question, or move part of the paid budget to a new opportunity.
NCFA Canada’s discussion of fintech startup challenges includes the cost of finding customers. That makes disciplined experimentation more valuable than maintaining two separate search plans indefinitely. Each investment should help the company understand where its next customers are coming from and how efficiently it can reach them.
SEO and Google Ads will not always rise or fall together. A new product may need more paid support; an established topic may need less. When both channels are managed against the same customer acquisition goals, a fintech company can respond to those changes deliberately—and put its budget where it has the best evidence of value.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
October 20, 2026 | Market Activity | Cross Border Payments And FX, Payments Infrastructure And Money Movement, Competition And Market Structure
On October 20, 2026, Mississauga fintech RemitBee announced a partnership with payment processor Adyen to simplify customer payments and support international expansion. A day earlier, RemitBee announced another partnership with TerraPay to expand overseas payouts, including transfers to digital wallets. Adyen will help RemitBee collect payments, while TerraPay will provide more ways to deliver money abroad. The agreements address two costs that can make international payments difficult to scale, collecting funds and paying recipients.
Founded in 2015, RemitBee serves hundreds of thousands of customers and supports transfers from Canada to more than 150 countries. It also offers RPass, a platform for businesses making international supplier, contractor and employee payments. The company has spent more than a decade building its Canadian customer base and international payment connections. Now it's expanding the services behind those transactions without having to build every payment connection itself.
Adyen will initially handle card payment collection in Canada, with additional payment methods planned as the relationship develops. RemitBee already supports debit card funding for international transfers and card payments for certain other services. The new arrangement focuses on how those payments are processed, rather than introducing card funding to the entire business for the first time.
Managing disputes has been costly. In an interview published by Adyen, RemitBee said its previous chargeback process involved too much manual work for the number of cases it handled. Adyen's automated tools and lower dispute fees could reduce that expense. Moving more payments onto one platform should also make reporting and reconciliation easier.
Adyen has direct acquiring and banking capabilities in the United States, United Kingdom and European Union. RemitBee sees those connections as useful for expansion beyond Canada, where adding separate processors and banking relationships would increase costs and complexity. It's an operating decision as much as a technology upgrade. Fewer systems to manage could leave more resources for customers and new products.
That choice also fits Canada's changing payment market. Adyen Canada became a member of Payments Canada in July 2026 as part of a broader expansion of payment system membership. Membership doesn't automatically provide direct access to every payment rail, but it gives newer payment providers a stronger position in Canada's financial infrastructure.
TerraPay gives RemitBee more ways to pay recipients through local banks and digital wallets. Its network connects 3.7 billion digital wallets and 7.5 billion bank accounts across more than 156 countries, with coverage in the United States, Asia, the Middle East and Africa.
For Canadian businesses paying overseas suppliers and contractors, more local payout options could mean fewer payment providers to manage. RemitBee can use TerraPay's network while continuing to handle currency conversion, customer service and compliance.
RemitBee's published consumer pricing offers free e-Transfer, EFT and bill payment funding on transfers of C$500 or more, with separate charges for debit cards. Its stated exchange rate margin generally ranges from 0.3% to 0.8%, depending on the destination. Lower processing and payout costs could improve RemitBee's margins or help it compete on price, but neither partnership has disclosed expected savings.
RemitBee's opportunity extends beyond consumer remittances. Canadian companies paying international suppliers, contractors and employees need competitive exchange rates, reliable delivery and clear payment records. Banks and established providers such as Wise already serve these customers, so adding more payment networks won't be enough to win their business.
RemitBee has an opening with smaller firms that regularly pay people across several countries. A business might need to pay one supplier through a bank account and another contractor through a mobile wallet, without managing separate providers for each destination. Combining those payment options with currency conversion and business payment records could make RPass more useful to companies with recurring international expenses.
There is still a commercial risk. RemitBee relies on outside processors and payout networks, while competitors can negotiate their own arrangements and compete aggressively on price. Its advantage will depend on retaining customers, keeping transfer costs competitive and earning enough from recurring business payments to support growth.
RemitBee is expanding its international payments business by connecting established processors and payout networks rather than owning them. That keeps the cost of expansion more manageable, but gives the company less direct control over key services. Can RemitBee turn access to global payment networks into a lasting competitive advantage, or will pricing, customer relationships and reliable delivery ultimately determine who wins?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 15, 2026 | Market Activity | Capital Markets Infrastructure And Funding, Digital Assets Blockchain And Tokenization, Wealthtech Investing And Trading
On October 15, 2026, New York fintech Fission announced a US$10 million Series A financing led by Pantera Capital to help investors sell tokenized fund holdings before their normal withdrawal dates. Circle Ventures, Borderless Capital, New Form, gumi Cryptos Capital and GTS CEO Ari Rubenstein also participated. Fission is building a business around buying investments from people who don't want to wait months to get their money back.
The round closed in September and follows a US$1.6 million pre-seed financing in Oct 2024. Fission plans to add more supported funds and increase the capital available for investor purchases. Its valuation and committed buying capacity haven't been disclosed.
Private investment funds often limit when investors can withdraw money. Some offer quarterly redemption dates, while others require approval before an investor can sell to someone else. Representing fund shares as digital tokens can make transfers easier, but investors still need an eligible buyer willing to pay for them.
Fission provides that buyer for supported investments. An eligible investor connects a digital wallet and requests a sale. Fission arranges the purchase and handles the required transaction steps. The investor receives cash before the fund's normal withdrawal date, while the buyer takes on the wait and the investment risk. The fund doesn't have to sell its underlying assets to complete that investor's early exit.
Founder and CEO Jonathan Shaffer told Fortune that an exit which might normally take about 200 days could settle through Fission in 90 seconds or less, for a fee. In August, Centrifuge introduced Fission liquidity for four tokenized funds linked to investment strategies from New York Life Investment Management, Apollo and Janus Henderson. The products include high yield corporate bonds, diversified credit, highly rated collateralized loan obligations and short term U.S. Treasuries.
Eligible holders can receive USDC, a stablecoin linked to the U.S. dollar, while the funds continue their usual settlement and withdrawal schedules. Those schedules range from the next business day to quarterly. For investors holding the Apollo diversified credit product, that could mean receiving money through Fission rather than waiting for the next quarterly redemption.
Shaffer described Fission's role in Centrifuge's announcement as providing "an independent liquidity layer" across different investment strategies. The company says it has processed millions of dollars in transactions, but hasn't published an exact total, transaction count or average price paid to investors. The four fund integrations show a working commercial application. They don't establish how much liquidity Fission can provide at scale.
Getting money out early has a price, and it varies considerably by fund. Research published in September 2026 estimated Fission's fees at 5.70% for Apollo's ACRDX diversified credit fund, 0.34% for New York Life's HYB high yield bond fund and just 0.02% for Janus Henderson's JTRSY Treasury fund. On a $10,000 holding, that means an estimated cost ranging from $570 to $2. These were estimates as of September 17, not fixed or guaranteed prices. The difference reflects the cost and risk of providing cash before the underlying investments settle.
That trade could appeal to an investor facing an unexpected cash need. For someone who can afford to wait until the next redemption date, paying for an earlier exit may make less sense. The service has to offer a price investors will accept while leaving enough return to compensate whoever supplies the cash.
There is also risk between the sale and the buyer's eventual exit. A fund's investments could fall in value. Withdrawals could be delayed during difficult markets. Some fund interests may require approval before being transferred. The buyer needs to understand those restrictions and price them correctly before committing capital.
Fund managers have a different concern. An outside buyer can provide liquidity without forcing the fund to sell assets early, which could make the investment more attractive to customers. But repeated sales at steep discounts could undermine confidence in the fund's reported value. Managers will want to know how Fission prices transactions and whether those prices reflect the need for quick cash or problems with the investments themselves.
Fission's growth will also depend on how much capital it can put to work. A fast sale of a small holding is one thing. Handling many large investor exits during a market downturn is a different test.
Fission's founders bring experience from institutional investing and digital securities. CEO Jonathan Shaffer previously worked at Point72, while cofounder Steve Bendit worked at Securitize. They know that making an investment easier to buy doesn't necessarily make it easier to sell. Fission's business depends on finding buyers, securing enough capital and offering prices investors will accept.
Existing tokenized fund operations already need to handle ownership records, investor eligibility and transfer restrictions. Fission must work within those rules while financing earlier exits. For Canadian private credit funds and alternative investment platforms, that could help attract investors who are reluctant to lock up their money. Any Canadian offering would still need to comply with securities laws and fund transfer requirements. Fission hasn't confirmed that its service is available in Canada.
Fission's opportunity isn't making private funds digital. It's making them easier to exit. If the company can consistently find buyers, offer fair prices and manage the risk of holding investments until redemption, it could remove an important barrier to private market investing.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 21, 2026
An online betting platform presents itself as one business. Customers register with a brand, deposit money into an account and choose a game or sporting event. Behind that experience, however, several specialist companies may be supplying the technology.
One provider can support the account system, another the sportsbook and another the live casino studio. Payments, location checks, sports data and independent testing introduce further businesses into the relationship.
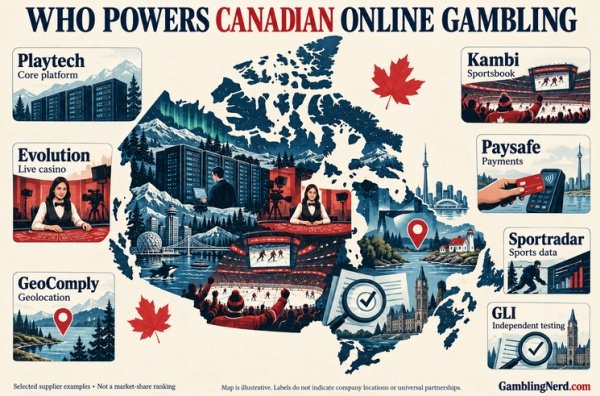
For fintech companies and investors, understanding those connections makes Canada’s gambling sector easier to assess. Gambling Nerd’s breakdown follows seven providers with documented Canadian activity, explaining what each contributes. These are selected examples, rather than a ranking by market share or a suggestion that every operator uses the same suppliers.
The operator’s website is the shopfront. The underlying platform helps organise the account and gaming services behind it.
Playtech illustrates this part of the ecosystem. Its original partnership announcement with NorthStar Gaming covered its IMS platform alongside casino, live casino, poker and bingo technology. NorthStar’s current corporate website identifies Playtech and Kambi as companies powering its Ontario offering.
A player account management system, commonly shortened to PAM, provides a central record of the customer’s account and activity. It connects with other systems rather than replacing every service an operator needs.
That distinction helps explain why a gambling business can buy substantial technology from a supplier while retaining its own brand, customer service and commercial strategy.
For a new operator, an established platform can reduce the amount of software it must build internally. The trade-off is a continuing dependence on integrations, contractual terms and the supplier’s development priorities.
A sportsbook requires more than a list of matches. Customers need markets, prices, bet acceptance and settlement, supported by systems that manage the operator’s betting exposure.
Kambi supplies sportsbook technology and services. Its relationship with NorthStar provides one Canadian example. A more recent development involves Ontario Lottery and Gaming Corporation.
In January 2026, Kambi announced that it had formally assumed contractual responsibility for OLG’s sportsbook services following an agreement with FDJ Gaming Solutions France and OLG. The announcement said OLG launched its Kambi-powered sportsbook on January 27, covering its retail and digital sports betting operations.
The example demonstrates an important distinction: the company whose name customers recognise is not necessarily the company supplying the underlying sportsbook.
Operators can buy different combinations of technology and managed services. A supplier relationship therefore needs to be understood at the product level, rather than reduced to “Company A powers Company B.”
Sportsbook systems depend on information about what is happening in the sporting event.
Sportradar supplies sports data and offers related services including odds, streaming and trading technology. It announced an Ontario gaming-related supplier registration in 2022, documenting its entry into the province’s regulated online wagering market.
Consider an in-play hockey market. A goal, penalty or change in game status can affect which bets are available and how they are priced. Data services help betting systems receive and process that information.
The distinction between data and sportsbook operation is useful, although suppliers’ product ranges can overlap. Buying a data feed does not necessarily mean outsourcing pricing, risk management or the complete customer-facing product.
For businesses evaluating a provider, the questions include event coverage, delivery speed, service reliability, usage rights and the handling of corrections.
A live blackjack table appearing inside an operator’s app may come from a specialist production business.
Evolution supplies live casino services, combining dealers, physical tables, cameras, streaming and interactive game technology. Its Canadian announcements include the launch of live casino services for OLG.ca, originally delivered from its Vancouver production studio, and services for multiple operators at Ontario’s private-market opening.
The operator distributes the experience through its own customer interface. The live casino supplier provides the game environment and supporting technology.
This helps explain why customers can encounter recognisable game formats across different casino brands. Branding and distribution can differ even when the underlying supplier is the same.
Live-dealer production also has a different operating model from a digitally generated slot game. Physical tables require staffing and studio capacity, alongside the technology needed to deliver the game.
The number displayed in a gambling account and the money moving through financial institutions are connected, but they are not the same system.
Paysafe provides payment processing and other payment products. In its Ontario market-launch announcement, the company described payment support for private operators and its longstanding processing relationship with OLG.ca. It explained how operators could access card processing and alternative payment methods through an integration with its services.
For an operator, a payment provider can simplify access to different ways of depositing and withdrawing money. That does not make the provider responsible for every stage of the customer journey.
A withdrawal can involve an operator’s authorisation, account checks, payment instructions and subsequent processing by financial partners. Faster movement at one stage does not guarantee that the complete withdrawal will be immediate.
Commercial evaluation therefore extends beyond transaction fees. Approval rates, reconciliation, fraud controls, settlement arrangements and the handling of failed payments all affect the service.
Identity and location answer different questions.
Identity checks establish who the customer is. Geolocation establishes where the device appears to be when accessing a service.
GeoComply provides geolocation and fraud-prevention technology. BET99 Ontario’s help centre offers a concrete operator example, explaining that GeoComply uses signals including Wi-Fi, GPS and cell-tower information to verify that customers are within Ontario.
A registered address alone cannot establish a customer’s current physical location. Someone can live in one province and use their phone while travelling elsewhere.
For operators, geolocation is consequently part of product access and compliance, rather than simply a convenience feature. Its integration must also accommodate legitimate customers whose devices or networks make verification difficult.
The supplier provides the technology; the operator still needs processes for customer support, exceptions and applicable requirements.
A supplier’s claim that a game works correctly is different from independent testing against defined requirements.
Gaming Laboratories International, or GLI, announced its recognition as an independent testing laboratory for Ontario iGaming in 2021. AGCO separately explains that it registers laboratories that test and certify gaming technology against the applicable standards.
Testing can examine relevant games and systems within a defined scope. It does not make the laboratory the regulator, nor does a certificate guarantee that every aspect of an operator’s business is compliant.
The Nerd Nook’s explanation of random number generators provides background on one technology used to produce digital casino outcomes. Testing examines implementation and applicable requirements; it does not promise a customer will win.
Physical live-dealer games should also be distinguished from RNG-generated games. Both require controls, but their outcome-generation processes differ.
These commercial providers operate within a market structure that varies across Canada.
In Ontario, private operators must register with AGCO and enter an operating agreement with iGaming Ontario. AGCO regulates the market, while iGaming Ontario performs commercial conduct-and-manage responsibilities for private operators. OLG’s online offering has a separate conduct-and-manage arrangement.
A supplier’s documented Ontario activity should therefore not be presented as blanket authorisation for every Canadian province.
The seven companies discussed here also represent only part of the ecosystem. Operators may contract separately for identity verification, cybersecurity, hosting, customer communications, responsible gambling tools and other services.
For NCFA’s fintech audience, the business opportunity extends well beyond launching another betting brand. Payments, data, identity and compliance services can support existing operators. Assessing that opportunity requires knowing precisely what a provider supplies, where it is permitted to operate and which responsibilities remain with its customer.
GamblingNerd.com is an independent gambling media website publishing experience-based reviews, guides and analysis of casinos, sportsbooks and poker sites. Originally launched as gamblingsites.org in 2007 and rebranded in 2025, Gambling Nerd also publishes The Nerd Nook, covering gambling mathematics, betting systems and sports betting strategy.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 21, 2026 | Insight | Capital Markets Infrastructure And Funding, Digital Assets Blockchain And Tokenization, Wealthtech Investing And Trading
On October 20, 2026, the U.S. Securities and Exchange Commission published guidance on tokenized stock trading, clarifying how certain U.S. public shares can trade on blockchain platforms without a company's affirmative approval. The guidance follows the SEC's September 17 Innovation Exemption, which allows limited trading of eligible public stocks through new digital venues. Sixteen companies, including Microsoft, Alphabet and Goldman Sachs, have reportedly objected to having their shares traded on the proposed OKXICE platform.
The exemption doesn't cover every public stock, and companies can block certain trading arrangements. Venues also face limits on which securities they can offer and how much trading they can handle. For investors and market operators, the questions are which stocks qualify, what ownership rights come with the tokens and whether these new platforms can compete with traditional exchanges. The October 20 guidance further explains how the existing exemption works without introducing new regulations.
The SEC allows qualifying venues to trade tokenized National Market System stocks, which generally include eligible shares listed on major U.S. exchanges and certain exchange traded products. The exemption covers qualifying securities tokenized by their issuers and arrangements involving independent third parties. It excludes rights, warrants and tokens that merely track a stock's price without providing the same ownership rights as the underlying security.
The SEC separates eligible stocks into two groups. Tier 1 includes shares in the S&P 500 and Russell 1000, along with certain qualifying exchange traded products. Major companies such as Apple, Microsoft, Alphabet and Nvidia fall within those indexes, although that doesn't automatically make their shares available on a tokenized venue. Tier 2 includes other eligible listed securities outside Tier 1, giving smaller public companies a potential route into these markets.
The limits are strict. A qualifying venue can offer up to 75 Tier 1 symbols, with trading in each capped at 0.25% of the stock's average daily share volume during the previous month. Tier 2 allows up to 250 symbols, with a 2.5% volume cap. Related venues must combine their trading activity when calculating these limits.
Consider a Tier 1 stock averaging 10 million shares traded daily. A qualifying venue and its affiliates could trade up to 25,000 tokenized shares per day. A Tier 2 stock with the same volume would have a limit of 250,000 shares. A first breach of a stock's volume limit doesn't automatically require suspension, but subsequent breaches require a three month trading pause for that security.
Investors must receive the same rights and privileges as holders of equivalent conventional shares. That includes applicable dividends and voting rights. The arrangements supporting those rights must be verified, and venues must meet requirements for trading halts, transaction records and technology safeguards. A token offering only synthetic exposure to a share price doesn't qualify under this exemption.
OKXICE is one of the first proposed venues testing the SEC's approach. It's a joint venture owned equally by Intercontinental Exchange, parent of the New York Stock Exchange, and OKC USA Holding, part of the OKX group. Its public trading notices describe a platform where approved investors could trade tokenized U.S. stocks against stablecoins using automated liquidity pools instead of a conventional stock exchange order book.
OKXICE plans to use Uniswap v4 technology on the X Layer blockchain to let approved investors trade tokenized stocks through pools of shares and stablecoins. Investors would need to verify their identities and use approved digital wallets. OKXICE says it won't hold customer assets or sell newly issued shares. Publishing its plans doesn't mean the SEC has approved the platform or that trading has started.
OKXICE initially proposed 63 stock symbols from 62 companies. Nine companies had objected by October 15, including Broadcom, Verizon, UnitedHealth, CoreWeave and AppLovin. Reporting on October 19 identified seven more, bringing the total to 16 companies, including Microsoft, Alphabet, Goldman Sachs, Qualcomm, Caterpillar, McDonald's and Western Digital.
One of the 16 objectors, Cerebras Systems, wasn't on the original proposed list. That means 15 of the original 62 companies had objected, leaving 47 without a reported objection at that point. Silence doesn't mean approval. It only means the company hasn't exercised its right to block that particular trading arrangement.
Applied Optoelectronics explained its concerns to The Wall Street Journal. The company questioned whether tokenized trading would benefit shareholders and worried about possible effects on its share price, trading activity and volatility. It also didn't want investors to mistake an independent tokenized offering for one supported by the company.
Under the SEC exemption, companies have 30 calendar days after receiving notice to object. If they object in time, that venue can't offer their tokenized shares under the exemption. The objection doesn't automatically prevent every other form of stock tokenization.
Trading platforms face a separate 30 day requirement. They must publish their operating plans at least 30 calendar days before trading begins. The SEC's October 20 guidance confirms that venues can publish proposed stock lists while companies are still deciding whether to object. They must disclose which decisions remain pending and update their lists as objections arrive or the periods expire.
Andrew Cuomo, co-chair of OKXICE, described the issuer objections as a "natural response". He said the venture expected some companies to wait before participating. Whether that resistance eases will depend partly on how the first venues operate and what benefits they can demonstrate to investors and issuers.
The potential appeal is clear. Investors could trade familiar U.S. shares outside regular exchange hours, hold them through approved digital wallets and use blockchain systems to complete transactions. But being able to trade at any hour doesn't guarantee liquidity or a competitive price. New venues still need enough investors and market makers to support reliable trading.
OKXICE proposes using automated market makers instead of matching every buyer and seller through a traditional order book. Liquidity providers would supply tokenized shares and stablecoins to trading pools, earning fees while taking market risk. If those pools don't attract enough capital, investors could face wider spreads or prices that differ from the conventional stock market.
Nasdaq has proposed a different model. In September 2025, Nasdaq sought SEC approval for tokenized stock trading within its existing exchange system. Investors could choose traditional or tokenized settlement, with the Depository Trust Company handling the process. The same trading rules, security identifiers and shareholder rights would apply.
Chuck Mack, Nasdaq's Senior Vice President of North American Markets, explained the company's approach.
"Past market failures teach us that it is imperative to ensure governance, resilience, and investor protection are embedded from the outset."
The two companies are taking different approaches. OKXICE plans to build a new blockchain trading platform, while Nasdaq wants to add tokenized stocks to its existing exchange system. Nasdaq's proposal follows a separate regulatory process and predates the October 2026 objections. For investors, the real focus is which approach offers better prices, reliable trading and strong shareholder protections.
Tokenized shares still need to give investors the same ownership rights as regular stocks. That means making sure dividends reach the right people, shareholders can vote and stock splits or mergers are recorded correctly. Investors who control their own digital wallets also need to protect their access keys. Losing them could mean losing access to their investments.
Investor protections can also differ. OKXICE isn't registered as a traditional stock exchange for trading under this exemption, so some rules that apply to established exchanges don't apply in the same way. The SEC exemption is temporary and lasts five years. That gives regulators time to assess how these markets operate before deciding whether to introduce permanent rules.
For Canadian fintech founders, the business opportunities go beyond operating a trading platform. These markets need companies that can protect assets, maintain accurate ownership records, verify compliance and supply trading liquidity. Brokers and transfer agents may also need new technology to connect blockchain transactions with existing securities systems. Demand for those services will depend on whether investors actually use the new markets.
Canada is also looking at how tokenized securities could trade under its own rules. In March 2026, the Canadian Securities Administrators launched Project Tokenization to explore trading, custody and settlement of digital securities. The initiative has since engaged more than 240 organizations, as reviewed in NCFA's capital markets innovation analysis. Unlike the SEC, Canada hasn't introduced a comparable exemption for tokenized public stock trading. For Canadian exchanges and fintech founders, the U.S. experiment offers an early look at which business models work and where existing securities rules may need to adapt.
If tokenized stocks attract buyers and sellers, keep trading costs competitive and preserve shareholder rights, they could become a useful alternative. If not, investors may have little reason to move away from traditional stock markets.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 20, 2026 | NCFA Story Intelligence | Capital Markets And Funding, Leadership And Governance, Artificial Intelligence And Data
On October 16, 2026, You Can See Everything opened in Canadian theatres. Four days later, the documentary about Elizabeth Holmes is still one of the biggest stories at the North American box office. It opened with about US$15 million from only 855 screens. That's an extraordinary result for a documentary about a founder whose company collapsed years ago and is now serving a federal prison sentence.1
Holmes didn't raise money because investors wanted to lose it. She sold a future that sounded possible, surrounded herself with people whose reputations made belief easier, and built a company whose story moved faster than outsiders could verify the technology. By the time the evidence caught up, investors had committed hundreds of millions of dollars.
What follows is a story of how founder trust becomes part of an investment case and how evidence can lose ground to momentum. The same human problem returns whenever investors finance an uncertain future.
The idea is bigger than the product. Theranos tells investors that its technology can run a broad range of tests from tiny amounts of blood. The company is private, the technology is closely guarded and outsiders have limited access to what happens inside the machines. That secrecy can sound like competitive protection when the founder is believed.
Conviction becomes part of the product. Holmes presents Theranos as a mission driven company that can transform healthcare. Investors hear a founder who appears certain about the future and willing to devote herself to it. That confidence is valuable in a startup because the product, market and operating model are all unfinished. It also makes the founder unusually important to the investment case.
The board looks formidable. Fortune described Theranos in 2014 as having one of the most illustrious boards in American business. George Shultz, Henry Kissinger, William Perry, Sam Nunn, James Mattis and other prominent figures gave Holmes access to experience, networks and public credibility that most young founders could never assemble.4
The board can't substitute for technical oversight. A famous director can open doors and challenge strategy. That doesn't automatically give a board the scientific depth to test a diagnostic platform. Prestige can make a young company look safer while leaving the hardest operating question untouched.
The numbers make the story feel real. A multibillion dollar valuation, hundreds of millions raised and national retail partnerships give investors familiar business signals. Those signals usually matter. They become dangerous when investors start treating them as evidence about the one thing the company still has to prove.
The media helps close the loop. Holmes becomes a symbol of Silicon Valley ambition. WIRED has now revisited its own 2014 coverage and acknowledged how media enthusiasm helped amplify the founder story before the science received enough scrutiny.7 The founder earns attention because investors believe. Investors see attention and find another reason to believe.
Good diligence can still ask the wrong question. Investors may spend weeks testing market size, legal structure, partnerships and founder references while the core product remains difficult to inspect. A deal room can contain thousands of pages and still miss the fact that matters most.
The founder can become the gateway to the evidence. That creates a dangerous loop. Investors trust the founder enough to accept the materials, then use those materials to decide whether they should trust the founder. Independent verification has to break that loop.
The criminal case narrows the facts. In January 2022, a federal jury convicts Holmes of conspiracy to defraud investors and three counts of wire fraud tied to transfers totalling more than US$140 million. The jury acquits her on patient related conspiracy and several patient fraud counts, while other investor counts end without a unanimous verdict.10
The sentence makes the cost tangible. In November 2022, Holmes receives 135 months in federal prison. She begins serving the sentence in 2023. The SEC had put the investor principle plainly years earlier when it said investors are entitled to “complete truth and candor” from companies and executives.11
The audience knows how the story ends. That makes the continuing fascination more revealing. People aren't buying tickets because the verdict is unknown. They are watching because confidence, ambition, deception and failure are still compelling human material.
Persuasion still moves money. Canadian investors see the same mechanism in a different setting. How AI Is Changing Canadian Investors’ Decisions found that 84% of surveyed self directed investors used AI, financial creators or both. Technology changes the channel. It doesn't remove the human desire to find someone or something that makes uncertainty feel easier.
Founder conviction still has value. Early stage investors are paid to finance businesses before every answer exists. A founder who can't make others believe in an uncertain future may never recruit the team, customers or capital needed to build it.
Conviction needs independent evidence beside it. Customer calls, production data, technical review, board oversight and financial reconciliation give investors something that doesn't depend on the founder's version of events. The earlier the company, the more important it becomes to know which assumptions are still beliefs.
Holmes is in prison, Theranos is gone and investors now know how the story ended. That makes the mistakes look obvious in hindsight. They were much harder to see when the company was raising money, signing national partners, attracting famous directors and appearing on magazine covers.
The next founder who lets belief outrun the evidence will probably look nothing like Holmes. The company may be building AI, financial infrastructure, robotics, biotech or something investors have not learned how to value yet. The founder may have respected backers, impressive customers and a demonstration that makes the future feel close enough to touch.
Early founders often have to sell conviction before the product, revenue or market fully exists. That's part of building a venture, not evidence of deception. Investors are financing a future that has not happened yet, so imagination belongs in the deal.
The line gets crossed when aspiration is presented as fact, a controlled demonstration is presented as independent proof, or hoped for traction is sold as something already verified. A founder can sell why the future might happen. The investor still has to know what is already true.
STORY INTELLIGENCE
How OpenAI And Anthropic Reached Public Markets
OpenAI and Anthropic show what happens when founder vision, strategic backers, governance choices and enormous private capital converge before public market scrutiny arrives.
FOUNDER BUILD
Inside a Licensed Profession: What Ownright’s Build Teaches Fintech Founders
Ownright offers a current founder case where credibility comes from operating evidence, regulatory fit, customer execution and a system that has processed more than $2 billion of transactions.
MARKET ACTIVITY
FNZ Turnaround Tests La Caisse and Canadian Pension Capital
Repeated capital raises and management changes at FNZ show what investor conviction looks like after the cheque is written, when ownership starts turning into active governance.
NCFA INSIGHT
Canada’s Early Stage Startup Funding Funnel Narrows
A tighter Canadian funding market raises the stakes for founders trying to earn attention and for investors deciding which stories deserve scarce early stage capital.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 20, 2026 | Last Updated: October 21, 2026 | NCFA Story Intelligence | Sustainable Finance And ESG, Investment And Capital Markets, Regulation And Policy
On October 20, 2026, Canada’s Taxonomy and Transition Planning Council released its final sustainable investment methodology. Canada now has a common way to assess green and transition activities after years of greenwashing disputes over financial products and bank commitments. Ottawa backs and funds the initiative, while an independent council develops and approves the standards. Adoption is voluntary, and detailed sector tests are still being written.
Canadians wanted products and investments that reflected their environmental priorities. Financial institutions saw customers, assets, lending opportunities and a stronger public story. Funds, ETFs, green bonds and huge sustainable finance commitments followed. Then investors started looking more closely at the holdings, counting rules and environmental results behind those claims.
What follows is a story of growing investor demand, billions in financial promises, and the widening gap between what institutions marketed and what they could prove.
Customers start asking for proof. Canadian environmental labelling programs such as Environmental Choice and EcoLogo bring product claims into everyday buying decisions during the 1990s. Buyers want to know what a label proves, not simply whether a package looks green. Later, investors bring similar expectations to savings and portfolios. 1
Financial firms see an opening. Responsible investing gains momentum when the UN backed Principles for Responsible Investment launch in 2006. Institutions from 16 countries representing more than US$2 trillion in assets sign on at the New York Stock Exchange. Investors are signalling that environmental, social and governance issues belong in investment decisions, and asset managers have a new market to serve.2
Canadian green bonds find buyers. EDC and Ontario give investors a named framework and intended use of proceeds before the money is committed. Named uses of proceeds give buyers more to check than a broad corporate promise. The proof still comes later. Issuers have to show where the capital went, what was completed and what the project delivered. A successful bond sale doesn't guarantee a successful environmental outcome.
Responsible investing grows beyond niche portfolios. By the end of 2017, Canada counted C$2.13 trillion in professionally managed assets using at least one responsible investment strategy. The Responsible Investment Association’s 2018 report put that at 50.6% of managed assets. The figure included screening and engagement strategies. It was not C$2.13 trillion of new green projects.
The banks raise their targets. As climate commitments become part of banks’ public image, Canada’s largest banks announce targets in the hundreds of billions. Corporate lending, underwriting, advisory work and other eligible services may all contribute under a bank’s methodology. A big cumulative number becomes a prominent measure of progress.
Investors start asking what sits behind the totals. A financing commitment can qualify under a bank’s own rules without proving that the financed activity later cut emissions. As the numbers climb, that gap becomes harder to ignore. Banks are selling sustainable finance. Their critics want to know what the money financed and what changed.Institutional investors were sending mixed signals too. In 2024, How Canadian Institutional Investors Voted on Climate 2024 found support for climate shareholder proposals varied sharply across major Canadian asset managers.
Fund marketing comes under review. The Canadian Securities Administrators issue ESG fund guidance in 2022 and revise it in 2024. Their reviews identify cases where promotional language reaches further than the investment documents support. The revised notice covers 112 prospectus reviews involving 57 managers, plus 39 continuous disclosure reviews involving 35 managers and 50 funds.6
Bank disclosures face formal complaints. By January 2024, Canadian banks face scrutiny over sustainability claims after Investors for Paris Compliance files securities complaints about RBC, TD, BMO, CIBC and Scotiabank. The group challenges how the banks support their sustainable finance claims. The allegations are not findings of wrongdoing. The original complaint sets out what the advocates asked regulators to examine.
RBC puts its counting method on paper. Its March 2024 framework says the bank uses its judgment when assessing eligible transactions. For credit, it can add authorized balances at successive fiscal year ends. The same continuing exposure may therefore contribute in more than one year. That isn't the same as reporting only unique new loans, and it says nothing by itself about the emissions a financed project later avoided.
Then the C$500 billion target disappears. In April 2025, RBC retires the commitment and cites uncertainty around measurement and Canada’s environmental claims rules. The move doesn't prove earlier transactions were misclassified. It does leave investors with a basic problem. A flagship number that once signalled leadership is gone just as scrutiny of the underlying methodology is intensifying.7
The fight moves into investment funds. In 2025, the OSC brings a case against Purpose Investments and CEO Som Seif over 19 allegedly misleading ESG communications made between 2019 and 2023. Purpose and Seif deny wrongdoing. After closing arguments in September 2026, the Tribunal reserves its decision. As of October 20, the allegations remain contested and there is no verified final merits ruling.8
The money stays, but new product launches slow. Morningstar reports C$67 billion in Canadian sustainable fund assets at the end of 2025. Only two new funds launch that year, down from 18 in 2024. The ten biggest net inflow winners attract C$4 billion while the rest lose C$2.9 billion combined. Greenwashing does not explain that result on its own. What the numbers do show is a market where assets keep growing while new money concentrates in fewer products.9
Green claims carry more legal risk. Competition Act changes in 2024 put environmental marketing under closer scrutiny. Parliament changes part of that regime in March 2026 by removing the requirement for business activity claims to follow an internationally recognized methodology. Misleading claims remain unlawful. By then, fintechs face new green claim rules under Competition Act, making documentation and evidence part of the commercial risk around environmental marketing.
The government work began years earlier. The federal Sustainable Finance Action Council receives a taxonomy mandate in 2021. Its 2022 roadmap report proposes green and transition classifications and a governance system, warning that delay could cost Canada investment opportunities. The early ambition to have a fuller framework in place by 2025 passes without one.
Ottawa funds the work but doesn't write the standard. In December 2025, Finance Canada selects the Canadian Climate Institute, working with Business Future Pathways, to support an independent taxonomy process. The federal government provides seed funding and a mandate. The independent Council owns the methodology and approval decisions.10
The 2026 consultation brings the difficult cases into the open. Canada has to decide how to treat investments that cut emissions inside steel, mining, transport and energy without pretending those industries are already green. A proposed emissions abatement category draws particular attention because a project can reduce emissions and still extend the life of a high emitting asset. Council chair Marlene Puffer connects the work directly to investment. “Ultimately, this work will underpin Canada’s ability to compete for capital with our peers around the world.”11
Because the taxonomy is voluntary, banks and fund managers now have a choice. They can align products with the common definitions or continue relying on their own frameworks unless another rule requires otherwise. Investors will be able to see which institutions use the shared standard and which do not.
That choice creates work for fintech firms that can keep the evidence attached to the financing claim. Activity screening, emissions records, approvals and audit trails all need to survive from origination through reporting. Capital is already moving into audit ready ESG software, including Novisto's USD $27 million raise. Banks, asset managers and borrowers will pay for systems that make sustainability claims easier to verify and harder to overstate.
A green label once helped a product stand out. Today, investors can ask much more of the claim behind it. Canada’s banks and fund managers have sold the promise of sustainable finance for years. Investors have answered with real money. The controversies have shown how quickly confidence frays when the language is more impressive than the evidence.
Canada's government backed, independently developed taxonomy gives the market a chance to reset that bargain. It is voluntary, and the technical tests are unfinished. No council can make an old claim true after the fact. Banks can show how a financing decision qualifies. Companies can keep the records behind the claim. Fund managers can tell investors exactly what they own.
Fintech founders have a market in the systems that keep these claims honest. Activity screening, emissions data, traceable loan records and assurance can become products that banks, issuers and investors will pay for. The firms that earn trust won't be the ones making the largest green promise. They'll be the ones that can show where the money went, what changed and who checked the evidence.
NCFA STORY
CSA Pauses Climate and Diversity Disclosure Rules
Canada paused mandatory climate disclosure rules in 2025 while material climate risks and misleading claims remained subject to securities law. Voluntary standards therefore carry more weight in the market.
NCFA INSIGHT
AI Won’t Solve SME Finance Without Better Data
Sustainable finance breaks down when businesses cannot collect and reuse reliable operating data. Better evidence infrastructure is becoming part of the financing opportunity for SMEs, lenders and fintechs.
NCFA STORY
Sustainability A Must for Fintech Growth
Fintechs face their own sustainability pressures as digital infrastructure consumes more energy and customers expect stronger environmental performance. The business opportunity and the operating risk are moving together.
NCFA VOICES
Businesses Competing on Social Values Use Fintech to Gain an Edge
Long before Canada had a taxonomy, customers were already rewarding companies that reflected their environmental and social values. Fintech gave firms new ways to turn those values into measurable participation.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016