





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


February 26, 2026 | NCFA Feature | Payments And Money Movement
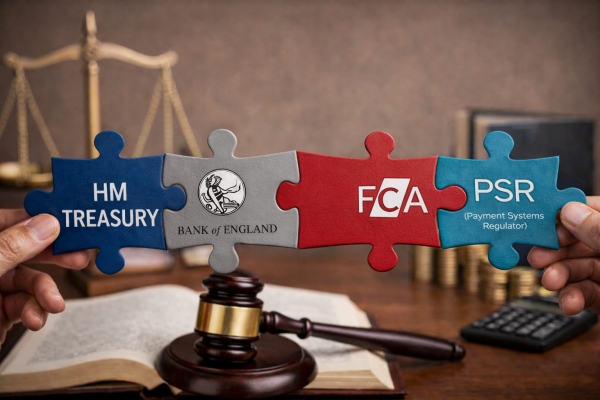
AI Generated Image: UK Payments Vision Delivery Committee
UK Regulatory Coordination is Clear While Canada Moves in Parallel
On February 26, 2026, the UK published a Payments Forward Plan (download 8 page PDF here)that gives fintechs something they rarely get in one place: a coordinated three year sequence for payments policy across HM Treasury, the Bank of England, the FCA, and the Payment Systems Regulator.
Great not just for regulatory coordination but for founders, operators, and investors who don't just need rules. They need timing, ownership, and a visible order of work and execution, which helps steer the ship and build market confidence for the future of payments, open banking, stablecoins, and digital money movement.
The Payments Forward Plan is a single sequenced plan with regulatory alignment from four regulatory authorities who collaborated on the Payments Vision Delivery Committee to execute the UK governments national payments vision. The roadmap covers retail payments, wholesale payments, and parts of digital assets, which means the UK is not treating payments as a narrow rails file. It is treating the next payments stack as a mix of bank rails, data sharing, digital money, and automation. That is what makes the document strategically useful. It gives the market a clearer view of what is coming, who carries which part of the file, and when firms should expect consultations, responses, gateways, and final rule work to land.
For as long as NCFA has been working in the financial technology sector, the UK has long been considered the 'gold standard'; the benchmark for fintech regulation for a simple reason. When regulators reduce uncertainty about what lands next, firms spend more time building and less time guessing. It gives the market a clearer path. That kind of visibility lowers planning friction across the sector and gives serious teams a better chance to line up product, compliance, and partnerships before the rest of the market catches up.
| Sector / Initiative | United Kingdom | Canada | Notes / Comments |
|---|---|---|---|
| Regulatory coordination and forward planning | One published cross regulator plan across HM Treasury, the Bank of England, the FCA, and the Payment Systems Regulator, with a visible three year sequence. | Canada now has active public workstreams across retail payments supervision, consumer driven banking, and the stablecoin framework, but those files still sit across separate policy pages. | Canada shows real movement across the same core layers. The main contrast is that the UK visibly puts more of the sequencing into one public roadmap. |
| Payments law and core policy sequencing | Q2 2026 HM Treasury consultation, Q4 2026 response, then FCA consultations and policy statements through 2027 and 2028. | Canada’s payments law sequencing is already live through the RPAA. Under the supervisory framework, PSP risk management and end user funds safeguarding requirements came into force on September 8, 2025, and firms that continue operating must meet ongoing supervision requirements. | Canada has moved from consultation into operating supervision. The UK gives a longer visible forward sequence, while Canada is already in live compliance mode on the PSP file. |
| Open banking and consumer directed data sharing | First live variable recurring payments under an industry led scheme in Q1 2026, FCA consultation in Q3 2026, and a policy statement in Q1 2027. | Canada’s Budget 2025 framework for consumer driven banking says the government will complete the Consumer Driven Banking Act, move quickly on phase one regulation after Royal Assent, and spend the next 12 to 18 months on a second phase that considers broader functionality, participant scope, and write access. See Canada Open Banking Commercialization Roadmap | Canada has a real public sequence here, even if it is not presented inside one cross regulator payments calendar. |
| Stablecoins, tokenised money, and tokenised deposits | Bank consultation work in H1 2026, final Bank rules by end 2026, FCA policy statement in mid 2026, authorisation gateway in Q3 2026, and broader regime live in October 2027. The plan also explicitly considers tokenised payments and tokenised deposits. | Canada’s official stablecoin framework says regulatory development starts after Royal Assent, continues over 12 to 18 months from early 2026, and is expected to come into force in 2027, with the Bank of Canada supervising issuers. | Both markets are active on stablecoins. The UK currently shows more visible choreography, while Canada already has a defined federal policy frame and implementation window. |
| Wholesale payments | The plan explicitly includes wholesale payments as part of the coordinated three year roadmap. | The Bank of Canada says its forward focus includes policy work on wholesale and retail payments infrastructure as part of broader payments system research and policy development. | Canada does have wholesale payments work in the official policy mix. What is less visible today is a single public milestone map that puts wholesale, retail, and digital assets on one page. |
| PSP oversight and supervisory perimeter | The forward plan folds payments supervision and upcoming rule work into one coordinated policy calendar across multiple authorities. | Under the RPAA mandate, the Bank of Canada supervises PSPs for operational risk, incident response, and end user fund protection, while the Minister of Finance handles national security screening. | Canada’s supervisory perimeter is already real and active. The distinction is not whether oversight exists. It is how visibly the next steps are sequenced in public. |
| Payments rail access and infrastructure participation | The UK plan covers retail and wholesale payments at a system level, including retail payments infrastructure design and short term enhancements to Faster Payments and Bacs by end 2026. | Canada’s membership expansion rules now let RPAA supervised PSPs apply for direct participation in Payments Canada systems, and five new PSPs were admitted on January 27, 2026: Wise, Float, KOHO, Paramount Commerce, and Brim. | Canada has moved from access policy to actual new entrants. That is a concrete infrastructure opening, even without one single national payments roadmap document. |
| CBDC and public digital money | The digital pound design phase remains active through 2026, with a blueprint and a decision on the future of the digital pound expected this year. | The Bank of Canada’s digital dollar page says it is scaling down work on a retail CBDC and shifting focus to broader payments system research and policy development, while continuing to monitor global retail CBDC developments and publish some related research. | Canada has stepped back from active retail CBDC build work and put payments supervision and infrastructure higher on the near term agenda. |
| Financial inclusion and emerging payment models | The plan explicitly includes financial inclusion and newer areas such as agentic AI payments inside the forward policy frame. | Canada’s consumer driven banking framework explicitly points to second phase work on write access and, beyond that, says the government is laying the foundation for broader open finance and open data that can support wider digital public infrastructure. | Canada is not mapping emerging payment models in the same broad way as the UK, but it's building policy groundwork that can widen payments and data driven product design over time. |
By publishing a 3 year future of payments roadmap, the UK is highlighting where it thinks the market is going. The plan explicitly pulls in open banking, stablecoins, tokenised payments, tokenised deposits, financial inclusion, agentic AI payments, and the digital pound design phase. Its fair to say that the UK sees the future of payments as an integrated stack where money movement, data access, programmable money, and automated decisioning increasingly sit in the same operating environment.
Payments firm may need to think about account access, stablecoin settlement, variable recurring payments, AI enabled workflows, and reporting standards as connected decisions, not separate roadmaps. The UK is effectively telling the market to plan that way now.
Canada’s issue is not a lack of movement. Open banking is moving. RPAA oversight is live. Stablecoin policy is taking shape. Payments Canada is widening access. The broader official backdrop is visible through Finance Canada’s financial sector policy hub. But firms still need to piece the sequence together from separate government pages, regulator actions, and infrastructure updates. That makes timing harder for founders, adds friction to internal planning, and creates more room for confusion in partner conversations.
The UK plan stands out because it cuts through that problem directly. It gives the market a more visible order of operations. Canada has substance, but not yet the same kind of single public sequencing document. That means more of the roadmap still has to be assembled by the private sector, which raises the execution burden on founders and operators who want to build ahead of policy instead of behind it.
For founders, if your business touches payments, open banking, stablecoins, treasury workflows, or digital money infrastructure, a visible sequence helps you decide what to build first, which approvals matter most, and when to line up counterparties. It also changes how you sell. Buyers trust teams that can point to named milestones and show how their roadmap lines up with them.
For investors, the plan gives a cleaner way to test whether a management team understands the path ahead or is still talking in broad trends. Companies that map product work to visible regulatory milestones usually carry less policy execution risk than companies that wait for each new rule to land before they react. That same test now applies in Canada too. The opportunity is real, but it rewards teams that can connect the dots across consumer driven banking, RPAA supervision, Payments Canada access, and stablecoin policy without waiting for one master roadmap to do it for them.
The UK has now published a cross regulator payments calendar with real ownership and visible sequencing for the next three years. Canada has real progress across the same core layers, but the path still takes more work to assemble. That is the real contrast. One market hands firms more of the map. The other still asks them to build more of it themselves. For on-going tracking of key impacts that matter most to markets, keep an eye on NCFA Fintech Whisperer Weekly Fintech Intelligence as the UK timeline advances and Canada’s separate pieces continue to progress.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
February 24 2026 | NCFA Market Activity
Image: Freepik
On February 24 2026, Toronto fintech Loop Financial announced it has introduced direct banking connectivity for business financial data, allowing SMEs to access account data through secure APIs instead of credential based screen scraping.
The announcement targets a persistent operational challenge for finance teams. Screen scraping connections often fail when bank interfaces change, forcing repeated authentication and delaying reconciliation. API based connectivity replaces that process with permissioned data exchange designed to improve connection stability and data accuracy across accounting systems.
Loop’s API layer integrates with accounting platforms including QuickBooks, Xero, and Wave, enabling transaction data to sync automatically without manual refresh cycles. Businesses operating across multiple financial institutions can gain more consistent visibility into cash positions and reporting workflows. The approach mirrors global infrastructure trends where tokenized access replaces credential sharing for financial data connectivity.
The company positions the infrastructure as a foundation for automation across bookkeeping, reporting, and financial operations. Reliable data flows support real time financial insights and reduce manual intervention in reconciliation processes.
Cato Pastoll, CEO of Loop:
"Financial data is the lifeblood of any growing company, yet for too long, Canadian founders have been forced to rely on technology that belongs in the early 2000s. When a bank feed breaks, it doesn't just create an error message; it halts month-end closes, creates blind spots in cash flow analysis, and forces finance teams to waste hours on manual data entry. We built this direct infrastructure because our customers deserve a financial operating system that works as hard as they do--without interruption."
Canada’s consumer driven banking framework remains in development, yet fintech infrastructure providers continue building capabilities aligned with expected data sharing models. Direct APIs reflect the architecture typically associated with secure data portability environments, including consent based access and standardized transmission methods.
Loop’s rollout highlights how market readiness can evolve ahead of regulatory implementation. Once formal frameworks are introduced, businesses already using API based connectivity may face fewer integration barriers.
Loop has expanded over recent years raising $6.4M CAD to build a global SMB finance platform, supporting cross border payments, FX management, and treasury tooling. The addition of direct data connectivity extends that platform strategy into financial data infrastructure.
For Canadian fintechs serving SMEs, data reliability remains a practical differentiator. Automated accounting workflows, embedded finance features, and financial decision tools all depend on stable connectivity between banks and software platforms.
Will early API infrastructure deployment by fintech providers accelerate adoption of consumer driven banking in Canada?
Foundational changes are taking place within Canada's fintech stack, after years of stagnation. Direct connectivity reduces operational friction today while aligning with future consumer driven banking expectations. Infrastructure improvements might appear incremental, but they influence how quickly financial innovation reaches everyday business users.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 20, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Regulation And Policy, Artificial Intelligence And Data, Payments And Money Movement, Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026).
This is a procurement and capital boost for defence not seen in decades. Fintechs that help defence suppliers get paid faster, manage cash under milestone contracts, and prove tight controls on funds and data have a generational opportunity with real distribution next quarter. See defence push: Montreal joins provincial bids for global DSR bank platform
This is a money and proof moment for insurtech. Founders selling automation into carriers and brokers should expect buyers to ask for hard baseline metrics, verified before and after results, and fast integration plans this quarter because the market now funds teams that tie automation to combined ratio math and measurable cost takeout.
The UK is embedding crypto firms inside the existing Financial Services and Markets Act framework used for banks, investment firms, and other regulated financial institutions. Firms will likely need stronger governance, clearer business models, defined senior management accountability, and enough financial resources to pass a full authorisation assessment. This tends to favour well capitalized firms that can build institutional grade compliance and risk management from the start.
Tariff volatility shouldn't come as a surprise to anyone and still important to note that this does not take tariffs off the table. Founders and investors should assume trade cost risk still moves through other statutes and policy tools, so the teams that win next quarter make cash forecasting, FX, and settlement controls easier to run when pricing and demand change overnight.
This locks in the timeline banks plan around. Founders selling credit, underwriting, treasury, capital markets, or risk tooling into federally regulated institutions should expect earlier capital impact questions and tighter evidence requests in the next quarter because partners align product decisions to November 2026 and January 2027 effective dates long before final publication.
BoC's action should put every payments and wallet provider on notice. Partners should ask sharper questions about where customer funds sit, who controls access, how fast you can prove balances, and how you recover when something breaks. Teams that can answer those questions with evidence keep distribution moving when scrutiny rises. Feb 27, 2026 Update: The Bank of Canada issues a revised order that allows XTM to resume retail payment activities under court supervised monitoring (a controlled restart).
This can open practical opportunities into German buyers and programs, but only for teams that can pass strict security and governance reviews. Fintechs using AI should expect tougher diligence on where models run, how data moves, how vendors get controlled, and how incidents get handled. If you can show that evidence quickly, you may shorten procurement cycles and avoid months of back and forth. Large buyers tend to follow the standards governments back when they buy software at scale.
This is how stablecoins get real distribution, through bank grade plumbing that owns the hard parts. The next quarter gets more competitive for cross border payments and FX because buyers will compare everyone against always on settlement plus clean, provable books, not just a faster rail.
This is what a real time payments stack looks like when a credit union commits to execution. Vendors selling into credit unions should plan for tighter requirements on open APIs, core and digital banking integration, automated balancing, and exception handling in the next quarter because buyers now expect one platform to run multiple rails without adding operational headcount.
This partnership puts telecom scale on the same path as regulated payouts. If you want in, plan for a buyer that starts by stress testing your operations, not your pitch. Bring evidence you can trace every $ end to end, spot problems fast, reverse or recover cleanly, and keep service levels steady when volume spikes or fraud pressure rises. The teams that win make risk controls feel invisible to users while giving partners real time confidence that money moves exactly as promised.
Founders selling treasury and payments infrastructure should expect tougher questions on reconciliation, exception handling, and control ownership in the next quarter because a bundled PSP sets a higher baseline for speed and operational calm.
This is a real bridge into institutional credit rails. Founders building crypto credit, collateral, custody, and risk tooling should expect tougher questions next quarter on liquidation rules, collateral segregation, reporting, and investor grade controls, because rated structures pull crypto lending into the same discipline set as mainstream ABS.
This tightens delivery expectations for banks and their vendors. Payments and onboarding fintechs should expect stricter timelines and stronger evidence demands next quarter because partial coverage can trigger enforcement.
This week shows the market continuing to get stricter and more operational. OSFI closes the CAR 2027 consultation and puts bank capital planning on a fixed runway. The Bank of Canada order against XTM puts wallets and payments providers back under a microscope on safeguarding and access controls. Modern Treasury pushes more buyers toward one provider that owns rails, reporting, and controls. Desert Financial’s move into FedNow, RTP, and Visa Direct shows how fast credit unions now expect real time payments to work at scale. mea Platform’s $50M round reinforces that capital still rewards insurance automation when it ties directly to combined ratio math. The PSR fine in the UK makes clear that payments safety controls ship on deadline, or regulators step in.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 13, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Regulation And Policy, Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech, Payments And Money Movement, Digital Banking And BaaS
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026).
If Congress moves in the spring, US partners will start asking harder questions now on stablecoin rewards, reserve treatment, and how customer funds and disclosures work across the full stack. Canadian fintechs that sell into US banks, issuers, brokers, or payment programs should treat this as a near term diligence trigger and tighten their positioning on governance, controls, and commercial terms before counterparties freeze decisions waiting for clarity.
This can tighten the enforcement loop for fintech ecosystems that touch payments, onboarding, compliance tooling, crypto rails, and cross border flows. Expect more partner questions on how you detect red flags, how you document decisions, and how quickly you can freeze, unwind, and report activity when a credible tip lands. Teams that treat case management and audit trails as part of the product will move faster in enterprise sales and face fewer surprises when an investigation starts.
This matters because sandbox access only helps when it reduces time and uncertainty. Teams that show strong governance, clear client protections, and clean reporting will move faster than teams that treat testing as a demo day. Learn about eligibility of the application process.
When a major hub ties tokenization to competitiveness, it raises the stakes for everyone else. Canadian fintechs that sell tokenized rails, custody, compliance, or payments infrastructure should watch how Hong Kong turns policy into approvals, because global buyers will compare jurisdictions and pick the one that reduces execution risk. The winners will package governance, controls, and reporting into the product so expansion doesn't turn into a compliance rebuild.
If the UK market truly removes practical caps for platform led raises, UK equity crowdfunding starts to compete more directly with later stage private rounds, not just seed. Canadian issuers and Canadian investors who already treat the UK as a secondary capital lane should watch how this affects round structure, disclosure burden, investor protections, and the cost of running a raise at scale.
This opens a practical channel for policy and market alignment with a top tier global finance hub. Fintechs that sell into banks, asset managers, or capital markets should track what this dialogue prioritizes, because it can influence what partners will fund, which standards they adopt, and where they source talent. Teams that can show real solutions in sustainable finance workflows, regulated innovation, and cross border market plumbing can use this moment to get in front of the right officials and decision makers early.
This matters because institutional adoption follows clarity. If your product cannot explain who holds control, who reconciles records, and how disputes get resolved, distribution will slow down no matter how good the tech looks.
Competition under the microscope, and it matters far beyond chatbots. If regulators treat access to high reach consumer channels as a competition issue, fintechs and financial institutions that rely on dominant platforms for onboarding, support, commerce, and embedded services should expect tighter questions about platform dependency, partner lock in, and contingency plans when a gatekeeper changes the rules.
Pakistan has moved a fully digital Islamic bank from pilot to commercial operations. The market test is now whether API-first banking and Shariah-compliant products can expand formal financial access at scale while meeting the control, resilience and trust expectations attached to a newly licensed bank.
The DIGIT pilot forces a few hard questions that every tokenized issuance vendor will face next. Who carries legal finality at each step. How participants reconcile token records with existing books without creating mismatches in stress. How the platform handles failed settlement, partial fills, and corporate actions without manual fire drills. HSBC’s selection also sets a benchmark for what UK buyers treat as table stakes, clean integration into current dealer and custodian workflows, clear control over keys and permissions, and audit ready evidence for every movement. If you sell issuance tooling, custody, post trade automation, or compliance workflows, you should map your roadmap to those practical asks now, because this pilot will shape the next wave of due diligence questions across wholesale markets.
This puts distribution and settlement on the same track as liquidity. Fintechs selling custody, treasury, payments, or compliance tooling should expect tougher buyer questions on how funds move end to end, how controls stay intact through banking rails, and how settlement risk gets boxed in when volume spikes.
If Malaysia standardizes supervised testing around wholesale payments and asset settlement, builders should track what the regulator expects around issuance controls, settlement finality, and operational risk. For banks and fintech partners, the fastest path to scale usually comes from proving how the money behaves under stress, not from polishing the user interface.
Fintech teams that rely on paid social, affiliates, influencers, or embedded widgets should treat marketing controls as part of the product. Buyers and partners will ask who approves copy, how teams prove UK targeting rules, and how fast they can pull campaigns across every channel. The teams that answer those questions cleanly keep momentum. The teams that cannot will watch growth stall at the trust layer. On a similar vein in Canada, the CSA and CIRO Set Clear Rules for Finfluencers.
This kind of operational failure rarely stays a one day headline in regulated markets. It turns into tougher questions from banks, insurers, and regulators about change controls, payout logic, segregation, and how quickly a platform can prove what happened. Fintech teams should treat payment engines and automated transfers like critical infrastructure, with tight permissions, clear audit trails, and hard stops that prevent a bad config from turning into a balance sheet event.
LSEG putting its name behind on chain settlement changes the competitive map, where regulators, CCPs, CSDs, custodians, and major brokers set the rules of the road. Interoperability becomes the make or break issue, not chain choice, because participants will demand one operating model that works across traditional settlement, collateral, corporate actions, and reporting. Fintechs that want to matter here should lean into the hard parts, how they reconcile token and legacy records without gaps, how they manage permissions and key control at institutional scale, and how they keep settlement predictable during spikes, outages, and exceptions. The winners will look like the safest pair of hands in the room, with proof that their tooling reduces manual breaks and shrinks settlement risk for real participants, not just pilot users.
This matters because cross border money movement often breaks first when liquidity gets tight. A stronger euro backstop can reduce settlement fear for banks that route Europe linked flows, and it can change how counterparties price risk in FX, trade finance, and payouts. Fintechs that sell treasury, FX, and cross border payment tooling can stand out when they show how their rails behave under stress and how they keep funds moving when funding markets turn ugly.
Stablecoin reward design sits on the desk of banks and lawmakers. CIRO custody expectations raise the standard for how platforms document segregation and access. The UK payments plan turns into real requirements that land inside onboarding, fraud controls, and settlement resilience. Tokenized assets, including tokenized gold, now face the same demand from buyers, show custody, show redemption, and show who owns the problem when something goes wrong. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 6, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026).
The hard part isn't moving money, it's proving every step. Teams that package premium flows with clean records and clear controls can earn carrier trust faster and grow without drowning in back office work.
This rule draws a hard line around who owns the onshore asset, who carries the filing burden, and what gets blocked before a token ever reaches the market. For founders building real world asset tokenization rails, this pushes compliance into the product spec, not the legal appendix. For investors and institutions, it also hints at where future supply can actually clear, which issuers can survive the documentation load, and which token structures will get rejected early.
This deal pushes tokenized gold closer to mainstream rails. Wallets and platforms now face tougher buyer questions on custody, redemption, and who controls the customer relationship at conversion.
Platforms that want to scale under Canadian dealer oversight now need custody choices, contracts, and segregation controls that hold up under faster and more explicit supervision.
Stablecoin rewards now sit on the critical path for US rules. Fintech teams that sell payments, custody, compliance, or market infrastructure into US regulated buyers should expect procurement questions to lock onto rewards design, reserve treatment, and where yield can legally sit in the stack.
A limited first cohort can steer who wins distribution and which stablecoin infrastructure stacks become the default for partners and platforms.
UK buyers will treat payments as national infrastructure, not a feature set. Fintechs that win distribution will show they can plug into policy goals on resilience, competition, and security while still shipping product fast.
This changes the bar for anyone selling account to account payments, open banking rails, fraud controls, or programmable payments. Founders should align roadmaps to the coming scheme design work and the Spring consultations the Bank flags, because UK infrastructure choices will shape product requirements for years.
This matters for any stablecoin issuer and infrastructure provider that wants institutional distribution. When regulators expand who can issue an eligible payment stablecoin for margin collateral use, counterparties get a clearer path to treat certain stablecoins as real plumbing inside regulated derivatives workflows. Fintechs that sell custody, collateral management, settlement, and stablecoin compliance can use this to anchor partner conversations around issuer structure, segregation controls, and how tokenized collateral actually clears inside regulated accounts.
This deadline forces teams that rely on Switzerland for issuance or operations to lock in licensing and controls early. Partners will push for clear governance, clean reserve treatment, and cross border compliance that holds up under scrutiny.
Fintech teams feel this through tighter budgets, higher buyer scrutiny, and more demand for products that raise productivity inside core financial workflows, especially in trade, credit, risk, and compliance.
Stress scenarios push banks to revisit credit appetite, model controls, and operational risk tolerance.
This deadline matters to fintechs that serve high net worth users, wealth platforms, brokers, and crypto firms that want UK market access. Teams that treat categorisation and conflicts as product logic, not legal text, will cut future remediation cost and speed up institutional partnerships.
OSFI sets an execution timetable that forces bank and fintech partners to treat prudential policy as a product requirement. Teams that sell underwriting, credit risk, treasury, or compliance tooling into federally regulated institutions will face tighter questions on governance ownership, model controls, and liquidity evidence.
This creates a real bottleneck for financings and time sensitive filings. Operators win time when they build buffer into launch plans, keep disclosure ready ahead of pricing, and avoid dependencies on last minute staff action.
Stablecoin rewards now sit in the middle of a real fight between banks and crypto firms, and that fight can decide how fast regulated buyers adopt stablecoin rails. In Canada, CIRO puts sharper expectations on digital asset custody, which raises the bar on contracts, segregation, and proof of control for any platform that wants to scale. In the UK, the payments roadmap starts to look like a build plan, not a wish list, and conduct rules keep moving into onboarding logic and product decisions. This week rewards teams that treat controls and governance as part of the product, because that is what buyers need before they expand distribution, and tokenized assets like tokenized gold now face the same test, prove custody, prove redemption, and prove who carries responsibility when real value moves across platforms.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA’s weekly newsletter, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 6, 2026 | NCFA Fintech Market Activity | Digital Banking and Regulation
Image: Freepik/lifeforstock
On January 29 2026, Nu received US bank approval to establish a US national bank under the Office of the Comptroller of the Currency (OCC).
The company said the approval supports its plan to build a federally chartered bank in the United States, subject to conditions and further steps before the bank can begin operating. A national bank structure sits at the core of how US banking works, including capital rules, governance expectations, and ongoing supervision.
Nu operates a large digital banking platform across Latin America. A US charter path places the firm inside a regime built for deposit taking institutions, not for sponsor bank partnerships or program structures. That changes what the company must build behind the scenes, including compliance controls, audit readiness, and risk management that can stand up to sustained regulatory oversight.
For founders and investors, this is a clean reminder about where scale often ends up. A fintech can grow quickly with product and distribution. A fintech can protect that growth only when it builds the governance and control stack that regulators and counterparties demand at national scale and volume.
A US national bank charter also sets a different operating ceiling. It can support a broader product set, a more direct funding base, and national reach under a single federal framework, but it comes with tighter obligations and less room for improvisation.
When a fintech steps into full bank regulation, which capability becomes the real constraint, distribution, underwriting, or the control stack that keeps regulators and partners confident?
Nu now faces an execution test that rewards operational strength, not marketing. Teams that incorporate governance as a product feature can sometimes scale faster because large buyers and regulators stop asking the same questions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
January 30, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Payments And Money Movement, Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization, Open Banking Open Finance And Data Sharing
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026)
Payment activity, API demand and recurring use increased while system performance remained stable. The figures establish an operating benchmark for countries building open banking around data access, payment initiation and commercial services. The later one billion payment milestone shows how quickly that base continued to expand.
Once a PSP can join the payments club directly, it can cut onboarding friction, tighten settlement and reconciliation, and show stronger operational maturity to banks, enterprise buyers, and regulators. Founders that treat membership readiness as an operating system will move faster when big partners demand proof. Investors should watch which PSPs turn access into volume and repeatable unit economics, not just press.
This is a planning signal for how the UK approaches AI in retail finance. Firms that sell into regulated buyers win time if they can show who owns outcomes, how models get tested, and how controls work across vendors and data flows. Teams that cannot evidence that quickly will find AI work slows down at the point of trust, not the point of build.
This matters to fintechs that sell into regulated buyers because coordination changes the buyer checklist. The winners standardize controls and reporting across spot, derivatives, custody, and settlement workflows so they do not rebuild the stack every time definitions and boundaries tighten.
This takes tokenization out of the hype lane and into build discipline. If you sell tokenized security rails to real institutions, you win deals when you answer the hard questions fast, who controls the record, how transfers stay legally effective, and where the product plugs into broker dealer, transfer agent, and clearing and settlement expectations.
This move embeds regulated stablecoin issuance directly into a global payments platform instead of leaving it at the edge. When stablecoins sit inside licensed EMI rails, settlement, liquidity management, and compliance become part of the core payments stack. Founders building wallets, FX, treasury, or cross border infrastructure should expect buyers to favor platforms that combine regulated issuance with distribution at scale.
A federal trust structure offers nationwide reach, clearer supervision, and stronger institutional credibility. Fintechs selling custody, settlement, compliance, or risk tooling should prepare for customers that operate under bank grade expectations. Investors should watch which applicants can survive the supervision burden that comes with federal status.
This pulls crypto compliance into product planning. Teams that want UK market access move faster when they convert these rule areas into workflows early, especially safeguarding, reporting, and accountable ownership across senior roles.
Payments access expands in Canada while regulators in the UK and US push firms toward clearer accountability in AI, crypto, and tokenized securities. The common thread is execution readiness. Buyers now ask who owns the record, who controls outcomes, and how a platform proves it can operate under supervision without slowing down. Fintechs that build for audit, governance, and market access early earn trust faster and avoid costly rebuilds when rules tighten around custody, settlement, and consumer outcomes. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA’s weekly newsletter, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
