





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 11, 2026 | NCFA Fintech Market Insight | Policy And Regulation And Market Entry

On Feb 26 2026, OSFI announced targeted fast track approvals framework for new applicants seeking to become federally regulated financial institutions. OSFI says the framework will launch in June 2026, and the goal is a quicker, clearer, more predictable approval process for eligible new entrants, without lowering prudential oversight.
The regulator limits the initial scope to two groups. One group is provincial credit unions seeking continuance as a federal credit union. The other group is entities with technologically innovative or emerging banking models, including fintechs and crypto asset custodians, that seek to incorporate as a bank or a federally regulated trust and loan company.
The framework will use right sized, risk based prudential reviews and provide clearer guidance on requirements and timelines. OSFI also points to service standards and a planned dashboard to track progress. Also noted is that the application fees won't change, and it will not refund fees if timelines are not met. OSFI says it will use what it learns to refine its processes to support a broader rollout later.
OSFI limits fast track entry to provincial credit unions seeking federal continuance and to innovative or emerging models seeking to incorporate as a bank or a federally regulated trust and loan company. In practical terms, and without naming specific companies, the most likely early candidates are firms that already run bank grade controls and need a federal licence to unlock the next product layer.
That includes fintechs offering primary account style products at scale, custody first firms that want a federal trust model, payments and treasury infrastructure firms expanding into trust style services, and mature wealth or brokerage platforms that want a bank or trust licence to bring more of the stack in house.
Canada’s competition problem is not only about products. It is also about who can enter the system and how predictable the regulatory approval path is. A clear approval path lets founders and boards plan capital, governance, compliance hires, vendor choices, and launch sequencing around a known process. That can reduce the cost of fintechs and challenger banks attempting a regulated model in Canada. Faster entry can increase competition and widen choice for consumers and small businesses, but only if the rules are clear enough that serious teams and investors can commit early.
Crypto custody firms also get a clear signal. By including crypto asset custodians in scope for this initial fast track approval framework, it puts digital asset custody on the list of models OSFI is willing to assess through a defined entry framework.
Having said that, service standards need to execute in real timelines. The dashboards mentioned by OSFI need to publish meaningful progress indicators, not vague stages. The review still needs to be rigorous, but the timeline and progress pathway needs to be legible enough that applicants know what is coming next and when.
If OSFI delivers a faster and more predictable regulatory entry approval framework without lowering the bar, which new models actually enter first, fintech banks, federal credit unions, or crypto custodians?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 10, 2026 | NCFA Fintech Market Activity | Wealthtech And Consumer Finance
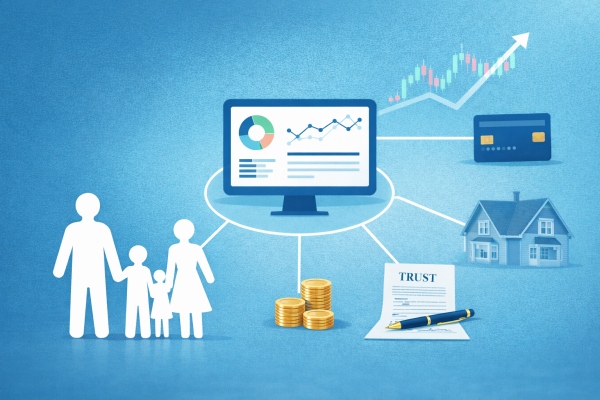
On March 4 2026, Robinhood unveiled new family finance products at its Take Flight event, adding a family investing experience, custodial and trust accounts, expanded managed investing tools, a new Platinum Card, and new Gold perks.
Vlad Tenev, CEO said:
“Robinhood will be the financial superapp for families to invest, plan, and grow wealth across generations.”
The platform continues to push further beyond retail trading and into family account oversight, wealth transfer, premium credit, and long term asset management. The new family hub is built to let households group accounts by family member, choose which accounts are visible, and assign permissions from view only access to full authority. Custodial accounts are rolling out now, while trust accounts and the family hub begin rolling out later this year.
This launch builds on an earlier NCFA analysis of Robinhood's wealthtech push and lifestyle finance strategy, but the new announcement goes further by tying family visibility, investing, credit, and wealth transfer into one customer experience.
The scale behind the launch is material. The platform reports 27.2 million funded customers, $324 billion in total platform assets, and $4.5 billion in 2025 revenue. That revenue rose 52% from 2024. Managed investing is also getting bigger. The firm says Robinhood Strategies now serves more than $1.5 billion in assets under management across more than 250,000 funded customers.
On the money side, it says there are more than 700,000 Gold Card customers with over $10 billion in annualized spend, while Robinhood Banking has more than 50,000 funded customers and over $800 million in cash deposits to date.
The premium card launch shows where the model is heading. The new invite only card carries a $695 annual fee and comes with richer travel, dining, and wellness benefits. That pricing puts the platform into a higher value segment as it tries to deepen relationships with customers whose financial lives are getting more complex.
When a platform bundles enough strategic product that can handle family account access, children’s investing, trust structures, managed portfolios, cash, and premium spending, it's getting closer to owning the main financial relationship in the household. That should raise eyebrows for banks, wealth platforms, and fintechs that still treat investing, credit, and family finance as separate product lines.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 5, 2026 | NCFA Fintech Market Insight | Open Banking And Policy And Market Structure

Image: Freepik/Drazen Zigic
On Mar 5 2026, the Bank of Canada made open banking timing comments at an Open Banking Expo highlighting timing and delivery risk. The central bank is still in the requirements stage and it will not commit to a launch date.
“somewhat daunted”
“the information-gathering stage alone will take months.”
In a LinkedIn post, Claire Brownell of The Logic also wrote that Ron Morrow, Executive Director of Payments, Supervision and Oversight, at the bank, “stopped short of confirming” that a 2026 launch is no longer realistic and said the information gathering stage “could take months,” with a clearer timeline only after that work finishes. Canada is still defining how open banking works before it can ship.
Yes, you heard it right. After almost a decade of analyzing, preparing, announcing, and promising the implementation of Consumer-driven Finance (aka Open Banking), the market learns that the bank is still in the information gathering phase.
Requirements work sounds boring, but it sets the rails for everything that follows. It decides which data gets shared, how consent works, how liability lands, how disputes get handled, and what the security bar looks like for every approved participant.
Canada already has a policy target, but the issue is execution speed. Canada's consumer driven banking framework describes open banking as a secure system that lets people and businesses share financial data with approved providers of their choice. Delay keeps Canadians stuck with expensive workarounds for data sharing and money movement like screen scraping.
Firms need clear standards on what data gets shared, how consent works, who is responsible when something goes wrong, and who can join the system. Without that clarity, banks and larger firms delay and smaller firms waste time building for rules that may change.
Delay also changes what gets built. Fintechs keep using screen scraping, password sharing, and one off partnerships because those options work today. That rewards the firms that already control customer access, instead of the firms building safer permission based tools.
Fintechs who have in some cases been waiting years for Open Banking's arrival can continue planning for two tracks. Keep shipping products that work under today’s rails, but design the next version around consumer permissioning, clean audit trails, and repeatable consent. Treat identity, consent, and dispute handling as core product work, not legal add ons. Companies that have these pieces in place will be ready when approval and accreditation rules finally arrive.
The cost of delay is that Canada keeps paying for friction, and Canadian fintechs keep competing with one hand tied behind their back.
If the requirements stage takes months, what needs to change so Canada ships a clear rule set fast enough for fintechs and banks to invest with confidence?
Hopefully this latest timing hiccup will lead to a safer, and more competitive data and payments layer in Canada.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 6, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization, Regulation And Policy, Lending Consumer Credit And BNPL, Sustainable Finance And ESG

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026).
This is for AI first fintechs, SaaS platforms, and builders selling usage heavy products because AI cost recovery is moving out of finance spreadsheets and into the billing stack itself. This means markup, model pricing, and token usage can all be baked directly into a single workflow.
This affects crypto custody, brokerage, and compliance tooling teams, plus firms that run secondary market controls, because it pushes more of the crypto perimeter into client asset rule design while tightening where firms must look for core market mechanics requirements.
This changes the operating timetable for lenders, brokers, and claims handling firms, and it pulls more pressure onto complaint intake, identity checks, fraud controls, and customer communications. Fintechs offering claims workflow solutions, onboarding checks, and redress automation now need to map product readiness to the late March rules and the 3 to 5 month build window.
This opens an official lane that matters for remittance firms, merchant payments providers, instant payments infrastructure teams, and institutions building Canada India payment flows. Once payment system operators are invited into the file, the discussion moves closer to real operating design, not just diplomacy.
This opens a new regulated advice lane between generic guidance and individual advice. It affects banks, pension providers, wealth platforms, and fintechs building support flows, because firms now have a near term path to turn customer guidance into a permissioned product with real conduct and authorisation consequences.
This is important for issuers, dealers, custodians, and market infrastructure teams because a central bank backed trial now shows how tokenized bonds and central bank settlement money can run through an on chain workflow, which raises expectations on governance, auditability, and integration before this model can scale beyond pilots.
A major exchange operator is tying its regulated futures roadmap to crypto spot reference prices while pushing tokenized equities distribution through a large crypto customer base.
This is for banks, payment infrastructure firms, tokenization platforms, and securities settlement providers. The BOJ is linking blockchain, tokenized central bank money, and core settlement design to active pilots, sandbox work, and future upgrades to BOJ NET, which raises the bar for how seriously the market should treat settlement infrastructure moving on chain.
This raises the enforcement baseline for broker dealers and their vendors. If you create or sell onboarding, surveillance, AML, or case management tooling, expect more pressure to prove risk based controls, faster SAR decisioning, and audit ready evidence because regulators are treating gaps in thinly traded securities monitoring as a serious control failure.
This is a positive announcement for fintech vendors that sell to government, defence, banks, and critical infrastructure. AI evaluation, cybercrime response, and resilience checks start to converge across buyers.
As Canada and Australia open the door to more pension investment, investors will want simple, auditable reporting and quick due diligence, especially for payments, AI, and critical supply chain projects.
This delay ties up cash for importers and their banks. When refunds take weeks to process, treasury teams need tighter visibility into duty exposure, eligibility tracking, and cash forecasting, and that opens room for fintech tools that automate reconciliation and working capital decisions created by policy whiplash.
This could impact how payments teams operate. If merchants can query verified payments events in natural language and automate workflows on top of unified data, AI payments will run the operating layer for routing, fraud, disputes, and cost control, which raises expectations on data quality, lineage, and accountability across the payments stack.
The Fed is opening a controlled access point for a crypto linked institution inside the U.S. payments system. That sets a live precedent for how non bank and digital asset firms may be handled under account access rules, even where service scope stays tightly constrained.
This for issuers, acquirers, sponsor banks, card fintechs, and treasury teams because stablecoins are moving closer to core network settlement, not just crypto side rails. Once a global card network starts wiring a bank issued stablecoin into settlement flow, teams need a clearer view on treasury design, reconciliation, network rules, and what faster money movement looks like in practice.
This pushes stablecoins deeper into everyday card economics, not just niche crypto wallets. It matters for issuers, program managers, fintech developers, and infrastructure teams because card issuance, settlement, and reconciliation are starting to move into the same onchain operating stack at global scale.
Singapore is placing climate transition planning inside supervised financial risk management rather than limiting it to public reporting. The approach gives Canadian regulators and institutions a comparator for connecting climate data, portfolio decisions, customer engagement and governance while avoiding blunt exclusions that could restrict financing without reducing underlying risk.
Core financial infrastructure continues to move closer to programmable systems while regulators tighten the rules around how firms operate and protect customers. Stablecoins are entering card settlement, tokenized bonds are moving through central bank backed pilots, and AI usage is starting to show up directly inside billing and payments operations. At the same time, regulators are opening new product lanes and expanding oversight of crypto custody, advice models, and consumer finance practices. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 2, 2026
Image: Unsplash/CardMapr.nl
Ontario’s regulated online gambling market is now measured in tens of billions of dollars. That scale has caught the attention of financial literacy advocates who see wagering not as entertainment alone, but as a financial behaviour. The question is simple: are the safeguards keeping pace with participation?
Online gambling in Canada is no longer a fringe activity. It sits inside the broader digital finance system you work in every day. Card networks process the payments and fintech firms build the rails while regulators try to get ahead of the game. Ontario offers the clearest picture: the province launched its regulated iGaming market in April 2022. Two years later, the numbers show just how quickly participation has grown.
In its 2023–2024 fiscal year, Ontario’s regulated online gambling market recorded $63 billion in total wagers and $2,4 billion in gaming revenue.
The first year of regulation, from April 2022 to March 2023, saw $35,5 billion in wagers. The jump from $35.5 billion to $63 billion in one year represents millions of card transactions moving through Canada’s payment infrastructure.
When activity reaches that scale, it becomes part of the larger financial system conversation. Consumer advocates are no longer talking only about odds and advertising. They are asking whether financial guardrails are designed for a market processing tens of billions in digital transactions.
The payments side of this discussion rarely makes headlines, but it is central. Visa and other networks sit behind a large share of online gambling deposits. Operating within global compliance frameworks, they classify transactions and manage settlements.
Visa’s recent expansion of stablecoin settlement across Central and Eastern Europe, the Middle East and Africa shows how fast payment rails are modernising. The initiative allows settlement in USDC and operates outside traditional banking hours. That is infrastructure innovation at scale, and a good argument can be made that this is the future of money, the future of finance. Regardless of ones feelings about crypto, one cannot ignore the fact that it is now something people are starting to use in every day transactions, and not just on-chain speculation.
This signals something as simple as it is interesting: the rails are getting faster and settlement options are widening. When payment systems modernise at that pace, consumer safeguards cannot rely on static policy language written for a different era of finance. Policy needs to catch up, and fast. Policy hardly ever moves at the pace of innovation, and maybe its time that changes.
Canada’s National Financial Literacy Strategy 2021–2026 focuses on building financial resilience and improving how people navigate digital financial services. The strategy calls for clearer information, stronger consumer protection and behavioural design that supports better decisions.
Online gambling now sits inside that digital ecosystem. It involves credit products, payment authorisations and real-time account transfers. When $63 billion in wagers flow through regulated platforms in a single province, it becomes part of everyday financial behaviour.
Advocates argue that safeguards should mirror the scale of activity. Deposit limits, clearer transaction labelling and easier access to account history are not abstract features. They are tools that support informed use of financial products.
Most Canadian players fund accounts with familiar tools. Visa remains one of the most recognised options. Behind the scenes, gambling transactions are commonly coded under Merchant Category Code 7995. Some issuers apply additional scrutiny or decline those payments based on internal risk rules.
That friction pushes players to look for clarity. Many compare online casinos that accept Visa in Canada to understand where card deposits are supported and under what conditions. The comparison is less about brand loyalty and more about payment certainty.
From a financial literacy perspective, this is where awareness becomes practical. A cardholder may not know how transaction coding affects approval rates and they may not understand how chargebacks are treated in gambling contexts. As wagering volumes rise into the tens of billions, even small gaps in understanding can scale quickly.
Canada’s open banking infrastructure continues to advance even before final policy implementation. The push is toward greater data portability and clearer consumer visibility over transactions.
Greater transparency has direct relevance here. When consumers can see where funds move and how categories are assigned, financial decision-making improves. In a market measured in billions of dollars, visibility is not cosmetic. It supports accountability across payment networks and platforms alike.
Ontario’s $63 billion wagering figure is not a social commentary. It is a financial data point. That scale places online gambling squarely inside Canada’s digital finance system.
The takeaway here is straightforward. Growth in participation requires growth in clarity. Safeguards need to be built into the rails, not layered on after problems appear. The Fintech world is technology driven, and competition in the field sets the pace. Can regulation keep up?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 27, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Regulation And Policy, Payments And Market Infrastructure, Risk Compliance And Regtech
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026).
This is early proof that capital is willing to line up behind an asset backed token model before issuance begins. It matters for tokenization platforms, digital asset builders, and market operators because demand at this level raises the stakes on what comes next, especially issuance design, trading access, settlement flow, and how real world asset tokenization earns trust beyond crypto native buyers.
This affects stablecoin issuers, wallet and exchange operators, payment firms that want stablecoin rails, and banks that can custody reserves or provide settlement accounts. The sandbox work turns authorisation readiness into near term execution, because counterparties will start asking who controls mint and burn, how reserves get safeguarded, how redemptions clear under stress, and what evidence you can produce before the September 2026 application gateway opens.
Institutional buyers tend to route flow to whoever can prove segregation, controls, and settlement certainty under supervision, and this move aims straight at that bar.
This is important for payment firms, open banking providers, digital asset infrastructure teams, and banks building new rails in the UK. A single forward plan from all four authorities makes timing harder to ignore, because product roadmaps, compliance sequencing, and partner conversations now sit against a more visible policy calendar.
This is a real infrastructure and distribution move in Canadian payments. It affects fintechs that bank through Peoples, embedded finance and sponsor bank partners, and any firm building around faster payments rails, because a stronger bank plus processor stack can tighten expectations on integration, uptime, message quality, and partner readiness well before RTR becomes fully operational.
Is this a key domino in AI finance? This is what AI looks like when it evolves from product feature to company structure. Large fintechs, payments platforms, and their investors now have a clear example of stronger results arriving alongside much smaller teams, placing more weight on execution quality, operating discipline, and how management builds from here.
This is one of the cleaner bridges between public capital, development finance, and founder scale. If you build inclusion fintech in ASEAN, expect the bar to move toward impact proof and deployment readiness, because capital now sits inside the same program that opens doors.
This is a significant turn of events for credit unions, fintechs, and crypto custody models that want a federal charter in Canada. A clearer approvals path can change when firms choose to enter the federal perimeter and how seriously investors and partners treat that option.
It affects stablecoin issuers, banks, custodians, exchanges, and fintechs that plan to distribute payment stablecoins, because reserve design, redemption handling, audits, supervision, and custody expectations start to look like core product requirements, not optional features.
This affects lenders, CRAs, and fintechs that rely on bureau data for onboarding and underwriting. Teams should expect more pressure on data completeness, dispute handling, governance, and audit evidence because mandatory sharing can reset what a clean credit file must look like.
This meeting keeps the door open to a simpler capital raising layer below broker dealer economics. Platforms, issuers, and service providers that touch private raises and secondary liquidity should watch for recommendations that tighten who can get paid, how referrals get documented, and what disclosure standard can unlock broader resale paths.
This raises the value of process maturity. If your fintech faces enforcement exposure, the timeline gives more room to assemble evidence, but it also rewards teams that keep clean records and can explain decisions fast when scrutiny hits.
Important for tokenized markets because clean settlement depends on clean reference data. Teams building custody, collateral, repo, and tokenized securities infrastructure must soon meet a higher standard on pricing integrity, entitlement controls, and auditability as institutional workflows move on-chain.
This is an immediate capital incentive change. If you sell insurer investment, treasury, or regulatory reporting tooling, expect more pressure to classify eligible exposure fast and produce clean evidence for PC4 filings while the treatment stays live.
This raises the cost of weak pre-trade controls. Teams selling OMS, EMS, surveillance, or post trade tooling into dealers should expect more demand for guardrails that prevent self matching and catch close related mistakes early, plus audit ready evidence when exceptions still occur.
The market continues to tighten where new rails are forming, and where management teams are being forced to adapt faster. Stay nimble and ahead of the curve. Be cautious about waiting for late stage confirmations. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 26, 2026 | NCFA Fintech Market Activity | Payments And Market Infrastructure
Image: Pixabay/viarami
On February 25 2026, Peoples Group announced a partnership with Fiserv to develop a next generation payments platform intended to serve financial institutions and fintechs across Canada.
The initiative combines Fiserv’s Enterprise Payments Platform with DNA core banking technology and represents one of Peoples Group’s largest technology investments. The infrastructure is designed to improve payment processing connectivity, support unified orchestration across card, account to account, and real time payment flows, and prepare for Payments Canada’s Real Time Rail environment.
The platform focuses on backend modernization rather than a consumer product launch. Peoples Bank of Canada, part of Peoples Group, continues to expand its role as a sponsor bank supporting fintech programs that rely on regulated balance sheet access, settlement infrastructure, and program management. Strengthening this capability can improve launch readiness for embedded finance, prepaid, and digital wallet partnerships while reducing reconciliation friction across payment channels.
Canadian payment modernization continues to advance in parallel to global peers, creating opportunities for infrastructure providers that invest early. Sponsor banks capable of supporting fintech scale with resilient payment processing and real time connectivity often become key enablers of ecosystem growth.
Peoples Group’s investment reflects how smaller specialized banks can play an outsized role in fintech enablement by focusing on platform capabilities rather than retail distribution.
Will deeper bank-fintech infrastructure partnerships accelerate Canada’s payment modernization timeline and expand the range of fintech products available to businesses and consumers?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Learn more.
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
