




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Jun 30, 2026

For those exploring a fresh online entertainment experience, this platform offers an impressive array of functionalities that cater to diverse preferences. Take advantage of the enticing welcome bonuses designed to give newcomers a robust start, enhancing their initial experience significantly.
The interactive environment features a user-friendly interface that simplifies navigation, making gameplay intuitive for both novices and seasoned players. Real-time statistics and analytics allow participants to track their performances and adjust their strategies accordingly, leading to tailored gaming sessions.
Additionally, engagement opportunities abound through community-driven events and tournaments that encourage friendly competition. Loyalty programs reward consistent players with perks and incentives, fostering a welcoming atmosphere. All these elements contribute to a dynamic and enjoyable online experience that is hard to resist.
An extensive array of gaming options caters to various preferences, ensuring that players can find something that suits their style. Unique titles often feature inventive gameplay mechanics, elevating the overall experience. Look out for offerings that combine traditional casino elements with modern twists, such as skill-based components or story-driven adventures, especially when exploring platforms in the crypto casino Canada segment.
Live-action games have transformed the entertainment landscape, allowing players to engage with real dealers in real-time. This format delivers an immersive atmosphere that mimics the ambiance of a physical venue, fostering social interaction. Consider trying out themed live shows, which blend popular culture elements into classic formats for an added layer of enjoyment.
Add-on features like progressive jackpots or customizable game settings enhance user engagement and provide opportunities for increased rewards. These options encourage diverse play styles, appealing to both casual gamers and high rollers. Regularly updated libraries help maintain interest, as new titles are introduced frequently, offering fresh and exciting challenges to explore.
To enhance the gaming experience, consider engaging with various limited-time offers and promotional events. Often, these promotions come in the form of deposit bonuses, where additional funds are credited to your account upon making a qualifying deposit. Pay attention to the details, as each promotion may have specific requirements.
Another attractive option is the referral program. By inviting friends to join, players can earn bonuses or free credits for each successful signup. This not only provides rewards but also creates a sense of community among users, fostering interaction and competition.
Loyalty schemes are designed to recognize and reward consistent participation. Players accumulate points based on their activities, which can later be exchanged for bonuses, gifts, or even exclusive experiences. Regularly check the loyalty program tiers to maximize benefits as you advance through levels.
Seasonal promotions often bring additional excitement, aligning offers with holidays or significant events. Participating during these times can lead to substantial bonuses and unique prizes. Ensure to monitor announcements for these opportunities, as they can significantly boost the gaming experience.
Lastly, subscribing to newsletters or notifications is a practical way to stay informed about the latest campaigns. This ensures that players never miss an opportunity to take advantage of exclusive offers, enhancing both engagement and rewards in the long run.
To enhance your engagement, the platform offers an intuitive layout designed for seamless interaction. Clear navigation bars and organized menus ensure that all available activities are easily accessible, minimizing time spent searching for options.
The color scheme is soothing, with a modern aesthetic that enhances visibility. Users can quickly identify sections such as betting options, account management, and help resources. This thoughtful design allows users to focus on their gaming experience without distractions.
Customer support is easily accessible, with a dedicated help center and live chat functionality. This feature enables users to receive assistance quickly, contributing to a positive overall experience.
Regular updates and user feedback integration demonstrate commitment to enhancing the interface. Continuous monitoring and tweaks based on popular user requests foster a community-focused environment, where player satisfaction is prioritized.
A wide range of multi-currency wallets is recommended for seamless and secure financial transfers. Look for options that support popular coins including Bitcoin, Ethereum, and various altcoins, enabling users to deposit, withdraw, and place bets with their preferred digital assets.
Security measures play a critical role in the reliability of online transactions. Implementing two-factor authentication (2FA) adds an extra layer of protection for users. Always ensure that the platform utilizes encryption protocols (like SSL) to keep personal and financial data secure from unauthorized access.
Consider utilizing platforms that offer blockchain technology for transparency. Each transaction is recorded on a public ledger, making it easier to verify and trace payments. This not only enhances privacy but also builds trust between users and the service provider.
For enhanced convenience, many users prefer platforms that enable direct cryptocurrency payments without the need for currency conversion. This can mitigate the risk associated with volatile exchange rates and hidden fees during conversions.
| Cryptocurrency | Transaction Speed | Typical Transaction Fees |
| Bitcoin | 10 minutes | $1-10 |
| Ethereum | 15 seconds | $0.50-5 |
| Litecoin | 2.5 minutes | $0.01-0.05 |
| Ripple | 3-5 seconds | Minimal |
Evaluate the transaction limits imposed by the service. Understanding the minimum and maximum deposit and withdrawal thresholds can help manage your gameplay or betting strategy. This information is often available in the FAQ section or customer support.
Regularly monitor the platform’s policy on transaction discrepancies. A responsive customer support team is beneficial in resolving any issues swiftly, ensuring a hassle-free gaming experience. Always choose platforms that offer clear communication channels for such concerns.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 26, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Risk Compliance And Regtech, Payments And Market Infrastructure, Regulation And Policy, Treasury Liquidity And Cash Management

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026, Jun 6-12, 2026, Jun 13-19, 2026).
Credit unions now have a clearer way to test stablecoins, tokenized deposits and digital asset accounts inside member owned financial institutions. Banks, core providers, payments firms, fintechs and regulators should watch whether these early programmes become production deployments for real time settlement, deposit tokens and broader member access to digital assets.
Stablecoin issuer regulation is becoming an AML and identity control issue, not only a reserve or redemption issue. Issuers, banks, custodians, wallets, exchanges and compliance teams should prepare for customer identification, verification, recordkeeping and risk controls as payment stablecoin frameworks mature.
Stablecoin regulation is moving from policy design into operating rules for payment infrastructure. Issuers, banks, custodians, payment firms, exchanges, and fintechs should watch how reserve design, redemption rights, safeguarding, and systemic supervision shape market access for regulated digital money.
Tokenization platforms are entering public capital markets. Asset managers, broker dealers, transfer agents, custodians, exchanges and investors should watch how public company access, regulated ATS infrastructure and cross border digital securities permissions shape the next phase of tokenized fund and real world asset distribution.
Event contract markets are facing a sharper boundary test. Exchanges, brokers, prediction market platforms, sports leagues, tribal gaming authorities and regulators should watch whether Congress narrows the line between federally regulated event contracts and state regulated gambling.
Private market trading infrastructure needs audit rules that firms can apply before transactions scale. Companies, auditors, advisers, venues and investors should watch how PISCES treatment affects independence checks, audit committee planning, transaction readiness and the operating model for periodic private share trading.
Canadian issuer disclosure is becoming more digital by default. Public companies, transfer agents, investor relations teams, legal advisers and compliance staff need to adjust delivery controls, SEDAR+ workflows, investor notices and request handling before the new access model takes effect.
Canadian equity market structure remains tied to US implementation timelines. Trading venues, brokers, market makers, and technology teams need more time to adjust routing logic, fee models, tick increments, compliance controls, and systems that support trading in interlisted securities.
Tokenization is moving closer to regulated market infrastructure. Exchanges, brokers, clearing firms, custodians, digital asset platforms, and regulators should watch how traditional market operators and crypto venues build permissioned pathways for tokenized securities, futures access, custody, execution, and compliance. Similar infrastructure questions are also emerging in event contract markets as new regulated venues, distribution channels, and contract frameworks develop.
Bank AI adoption is moving from pilots to operating metrics. Financial institutions, fintech vendors, compliance teams, investors, and regulators should watch how large banks measure AI value, scale employee access, govern automation agents, and connect AI deployment to fraud control, onboarding, productivity, risk operations, and compute infrastructure markets.
Cross border payments are becoming a regulated corridor strategy. Exporters, payment firms, banks, compliance teams and fintechs should watch how RPAA registration, money services business obligations, local payout capability and bank account connectivity affect competition in Canada India payment flows.
Digital euro policy is becoming payment infrastructure design. The next test is how offline use, privacy controls, holding limits, fees, PSP distribution, and cash protection fit into a system that has to work across public money, private payment providers, and existing rails.
Mortgage distribution is becoming a stronger fraud, licensing, and consumer protection issue. Brokers, lenders, fintech mortgage platforms, compliance teams, and investors should watch how higher penalties, clearer licensing rules, and stronger supervision reshape risk controls in mortgage services.
Financial crime detection no longer depends only on what individual institutions can see. Banks, credit unions, payment service providers, securities dealers, fintechs and other reporting entities can now strengthen risk detection by sharing designated information, creating new opportunities for collaborative fraud controls, network analysis and anti money laundering investigations.
Regulatory enforcement is becoming more incentive driven. Banks, insurers, investment firms, credit unions and compliance teams should review how early investigation strategy, breach assessment, remediation evidence and senior accountability affect enforcement outcomes.
Audit reporting is becoming more focused on useful disclosure, controls evidence and investor readability. Companies, audit committees, auditors, governance advisers and compliance teams should prepare for updated report content, Provision 29 controls statements and revised audit workflows before the December effective date.
Firms need to know where encryption is used, which vendors are exposed, which systems protect high value data, and how long migration will take. Crypto inventory, procurement language, vendor assurance, and roadmap planning should start before compliance dates become delivery pressure.
A regulated operating company is using a tokenized money market fund for its own liquidity rather than presenting it as a future client product. That moves tokenization into daily treasury operations, where continuous access, settlement speed, custody controls and balance-sheet utility can be tested against conventional cash-management infrastructure.
Approval processes are becoming more transparent and predictable for eligible applicants entering or expanding within Canada's federally regulated financial sector. Banks, fintechs, federal credit union applicants and regulated financial institutions should watch how the framework affects application timelines, market entry, organizational changes and future supervisory expectations. For background, see NCFA's earlier coverage of the Streamlined Approvals Framework proposal.
Manitoba has put AI governance and cybersecurity inside the same statutory control structure for the public sector. The next test is implementation. Regulations will determine how far the province goes on human oversight, technical standards, incident reporting and vendor procurement, and whether those requirements become a practical benchmark for other Canadian governments.
Every week brings hundreds of announcements. Only a small number signal meaningful change. This week's developments point to new opportunities across payments, digital assets, AI, capital markets and regulation that could influence where innovation accelerates, investment flows and new business models emerge next.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 26, 2026
Artificial intelligence has become one of the most exciting sectors for investors. From generative AI tools to enterprise automation, companies developing advanced AI models have attracted billions of dollars in funding and global attention. As a result, investors are increasingly looking for the next major opportunity among AI IPOs and pre-IPO AI companies.
One company generating significant interest is Anthropic. Known for developing Claude AI, Anthropic has emerged as one of the strongest competitors in the AI industry. Some technology analysts, including Jeff Brown, believe the company could eventually become one of the world's most valuable AI businesses. That growing optimism has fueled widespread searches for information about a potential Anthropic IPO and whether investors can benefit before the company goes public.
Anthropic is an artificial intelligence company founded by former OpenAI researchers with the goal of building reliable and safe AI systems for businesses and developers. Its flagship product, Claude, is a large language model designed to assist with writing, coding, research, data analysis, and complex business workflows.
Unlike many AI startups that primarily target consumers, Anthropic has focused heavily on enterprise customers. Businesses use Claude to summarize lengthy documents, automate repetitive tasks, generate software code, and improve productivity across different departments.
The company has also attracted partnerships and investments from some of the biggest names in technology. These strategic relationships have strengthened Anthropic's position in the rapidly expanding AI market while placing it alongside major competitors such as OpenAI and Google.
Interest in Anthropic investment opportunities has grown alongside the rapid adoption of generative AI. Organizations across healthcare, finance, legal services, education, and software development are integrating AI into daily operations, creating enormous demand for advanced language models.
According to the research discussed in the uploaded documents, Jeff Brown highlights Anthropic's enterprise-focused approach, rapid business expansion, and support from leading technology companies as key reasons for investor optimism.
Growing interest in the company has led many investors to examine Jeff Brown's Anthropic forecast, which explores why some believe Anthropic could become one of the most valuable AI businesses in the coming years.
Although Anthropic remains privately owned, its funding rounds and growing customer base have made it one of the most closely watched pre-IPO AI companies in today's market.
Jeff Brown's prediction centers on the belief that Anthropic could become a trillion-dollar AI company if enterprise AI adoption continues to accelerate.
In his published research, Brown argues that Anthropic's Claude platform solves real business problems rather than simply providing consumer chat experiences. He points to enterprise use cases such as document analysis, software development, and workflow automation as major drivers of long-term growth.
Brown also highlights the company's ability to attract substantial investments from major technology firms. Strong financial backing, experienced leadership, and growing enterprise demand form the basis of his long-term AI investing thesis.
Investors should remember that these are forecasts rather than guarantees. Predicting whether a private company will eventually reach trillion-dollar status involves many assumptions, including future revenue growth, competitive positioning, market conditions, and successful execution.
Even highly respected analysts can be wrong. Investment decisions should never rely solely on one prediction, regardless of the source.
One of the biggest questions investors ask is whether an Anthropic IPO will happen soon. At present, Anthropic remains a privately held company. Like many successful AI startups, it continues raising capital from institutional investors instead of offering shares through public stock markets.
Before an IPO occurs, companies typically strengthen financial reporting, expand operations, satisfy regulatory requirements, and determine favorable market conditions. The exact timing depends on management decisions and broader market sentiment.
Because Anthropic is still privately held, many investors are researching how investors may gain exposure to Anthropic before an IPO through indirect investment opportunities and related public companies.
While direct investment is generally unavailable for retail investors, many choose to monitor developments until official announcements are made.
Investors don't necessarily have to wait for an Anthropic IPO to participate in AI investing.
Several established companies already benefit from the growth of artificial intelligence:
Diversification helps reduce the risks associated with relying on a single pre-IPO company while still participating in the broader AI revolution.
Every investment carries risk, particularly when evaluating private companies.
Potential challenges include:
Predictions about future AI stocks should therefore be viewed as informed opinions rather than certain outcomes.
Anthropic has established itself as one of the most closely watched AI companies thanks to its Claude platform, enterprise adoption, and support from major technology investors. These strengths explain why discussions surrounding a possible Anthropic IPO continue gaining momentum.
Jeff Brown predictions have further increased public interest by suggesting the company could become a future leader in artificial intelligence. However, investors should remember that these forecasts remain speculative until supported by future business performance and official company decisions.
Whether you're evaluating Anthropic stock opportunities, researching AI startup investments, or exploring the next wave of AI IPOs, maintaining a diversified portfolio and conducting independent research remain the most effective long-term investment strategies.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 26, 2026 | NCFA Insight | SME Finance And Business Banking, Artificial Intelligence And Data, Open Banking And Open Finance, Fintech And Innovation
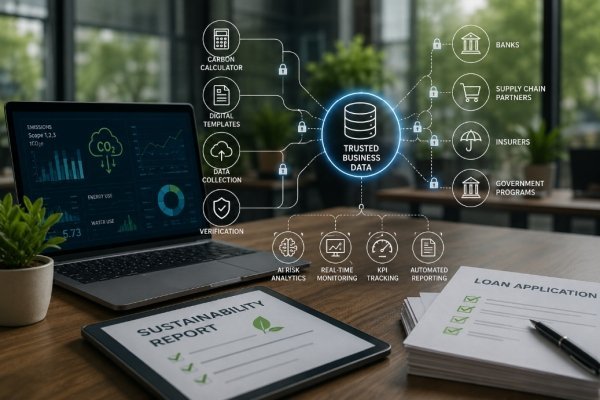
On June 26, 2026, the OECD published Leveraging AI and Digital Tools for SME Sustainable Finance, arguing that one of the biggest barriers to sustainable finance for small and medium sized businesses is not only capital availability but the cost of collecting, verifying, sharing, and monitoring reliable business information.
SMEs account for around 50% of economic output and business sector environmental impacts, yet remain underrepresented in sustainable finance. Sustainable finance markets have grown, but smaller firms still struggle because sustainability data is costly to generate, difficult to verify, and fragmented across reporting frameworks.
So what does this mean?
AI can help lenders process information faster, automate routine work, and monitor portfolios, but only when SMEs can produce trusted, reusable data. Without that foundation, AI just processes weak information faster.
The OECD identifies four main barriers holding back SME sustainable finance:
The report cites survey evidence that SMEs identify lack of time at 42%, technical difficulties at 41%, and high reporting costs at 41% as top barriers to sustainability measurement and reporting.
Many SMEs may want financing for efficiency upgrades, transition investments, or buyer requirements, but the paperwork and verification burden can make targeted sustainable finance harder to access than standard financing.
The OECD looks at the full financing path, not just the lending decision. The process starts when an SME collects sustainability information and continues through bank onboarding, risk review, monitoring, and reporting.
For SMEs, the first job is basic data capture. Carbon calculators, digital templates, consent based APIs, and automated reporting tools can help owners turn energy use, emissions, invoices, utility data, and operating records into information lenders can review.
For financial institutions, the work then moves through three stages. Front office tools can help with onboarding, document intake, product matching, and early screening. Middle office tools can support risk review, evidence checks, benchmarking, and sustainability claim review. Back office tools can monitor targets, prepare reports, track KPIs, and keep portfolio records current.
The OECD’s warning is direct and impactful. AI cannot compensate for missing, inconsistent, or weakly verified data. AI becomes useful only when the underlying information is trusted enough to compare, reuse, and monitor over time.
Sustainable finance does not scale for SMEs if every small loan requires a custom review. Origination, due diligence, verification, monitoring, and reporting all take time. When the loan is small, those fixed costs can make SME sustainable finance unattractive for lenders even when capital is available.
This is why the OECD's lifecycle approach may help. Digital onboarding, reusable sustainability credentials, API based data sharing, AI assisted verification, and continuous monitoring can reduce the cost of serving smaller borrowers.
The opportunity is not just faster approvals. It is making small ticket sustainable finance workable for lenders and less painful for SMEs.
The OECD highlights several initiatives that show how reusable sustainability data can work in practice.
Denmark's Climate Compass gives SMEs a free digital tool to calculate Scope 1, 2, and 3 emissions in line with recognized standards. The SME Climate Hub offers a free carbon calculator for micro and small businesses. Ireland's Climate Toolkit 4 Business combines an emissions calculator with a climate action plan.
Singapore's Project Greenprint helps SMEs generate emissions reports by pulling data from trusted sources, while the United Kingdom's Project Perseus explores how SMEs can share energy data with banks through reporting solutions. Belgium's Kube ESG, developed with major Belgian banks, gives SMEs a digital platform for sustainability reporting.
SMEs shouldn't have to rebuild the same sustainability file for every bank, buyer, or public program. They need data that can be generated once, verified, and reused with permission.
Canada already has many of the building blocks the OECD describes, but policy and market conversations are often separate.
Open banking and open finance can support permission based business data sharing. Digital identity can improve trust and verification. AI underwriting can reduce manual review. Embedded finance can connect lending to accounting, payments, invoicing, payroll, and commerce data. Sustainability reporting tools can help SMEs generate the evidence lenders and buyers increasingly request.
The opportunity is to connect those pieces. If Canadian SMEs can share trusted business and sustainability data through secure, interoperable systems, lenders can reduce manual work and price risk with better information.
That is where sustainable finance becomes a fintech infrastructure problem. The outcome is trusted business data that SMEs can reuse across banks, buyers, insurers, platforms, and government programs.
Open banking in Canada shows how permission based data sharing can improve financial services and reduce friction for consumers and businesses.
NCFA's Open Banking Opportunity Brief explores the commercial opportunities created by data portability and controlled financial data access.
Float's AI business finance stack points to how Canadian SME finance platforms are moving toward connected finance workflows.
EQ Bank's SME operating account push shows how business banking is expanding from accounts into spending, cash flow, and operating tools.
NCFA's Financial Innovation Map tracks opportunities across SME finance, open finance, AI, digital identity, sustainability, and financial data infrastructure.
If trusted SME data was portable and secure between businesses, lenders, buyers, insurers, platforms, and public programs with permission, which parts of commercial lending would still need manual verification?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 20, 2026 | NCFA Resource | Risk Compliance And Regtech, Artificial Intelligence And Data

On June 18, 2026, IOSCO published a Supervisory Tech (SupTech) report called 'Mapping the Use of Technology in Financial Supervision', a global survey of 49 authorities on how regulators are using technology to improve financial supervision. The report maps where SupTech is already being used, what is driving adoption, and which barriers are slowing progress.
SupTech is becoming part of regular ongoing supervision, and is no longer an experiment. Regulators are using technology to improve efficiency, receive and analyze information faster, and strengthen oversight across investor protection, market conduct, capital markets, and emerging areas such as digital assets.
The report gives regulators, fintech firms, and regtech providers a global benchmark for how supervisory technology is being adopted. It covers strategy, budgets, leadership, data, cloud infrastructure, AI, cybersecurity, digital assets, cooperation, and workforce planning.
IOSCO found that efficiency is the main driver of SupTech adoption, followed by faster access to information and stronger supervisory capabilities. AI applications, improved data access, and cloud infrastructure are the leading technology enablers.
Consumer and investor protection and capital markets supervision are the most developed use cases. Digital assets are less mature today, but interest is rising. That gap matters because market activity is moving faster than many supervisory tools.
The report also shows why implementation is hard. Cyber risk, third party dependencies, operational risk, funding gaps, and skills shortages remain major constraints. Many authorities have strategies under way, but full implementation is still uneven.
This resource is useful for securities regulators, policy teams, regtech firms, fintech compliance teams, financial institutions, digital asset platforms, market surveillance teams, and researchers tracking regulatory modernization.
It is especially useful for organizations building or assessing tools for market monitoring, fraud detection, complaints analysis, digital asset oversight, supervisory analytics, data collection, and AI enabled supervision.
The strength of this resource is its global scope. The survey covers authorities across all IOSCO regions and gives readers a baseline for comparing SupTech maturity, priorities, and constraints.
It is also useful because it avoids hype. The report shows that many regulators are still using mid level technologies and practical tools. Advanced analytics and machine learning are important ambitions, but funding and implementation capacity remain real limits.
The limit is that it's survey based, not a product guide. It doesn't rank vendors, provide implementation playbooks, or prove which tools produce the best supervisory outcomes. Its value is in the benchmark, the use cases, and the policy signals.
IOSCO SupTech Report (primary report)
IOSCO SupTech Media Release (announcement summary)
AI Agents Enter Governed Financial Workflows (AI governance and controls)
MIT AI Risk Repository For Fintech Governance (AI risk taxonomy resource)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 23, 2026

The MSB license in Canada (Money Services Business registration) is one of the most important regulatory requirements for companies operating in financial services, fintech, and crypto-related sectors. It is administered by the Financial Transactions and Reports Analysis Centre of Canada (FINTRAC) and is designed to ensure transparency, prevent money laundering, and support compliance with anti-terrorism financing laws.
As financial technologies evolve, Canada continues to refine its regulatory framework, making the MSB registration process essential for both domestic and international companies offering money-related services in the Canadian market.
An MSB (Money Services Business) in Canada is not a traditional “license” in the way gambling or banking licenses are issued. Instead, it is a mandatory registration with FINTRAC for businesses that provide specific financial services.
Once registered, a company is recognized as a regulated financial entity and must comply with Canadian AML (Anti-Money Laundering) and CTF (Counter-Terrorist Financing) regulations.
Businesses that typically fall under MSB regulation include:
If a business performs any of these activities in Canada—or serves Canadian clients—it may be required to register as an MSB.
The governing body responsible for MSB registration is FINTRAC (Financial Transactions and Reports Analysis Centre of Canada).
FINTRAC’s role includes:
Failure to comply with FINTRAC regulations can result in severe penalties, including fines, criminal charges, and business restrictions.
Many companies mistakenly believe MSB registration only applies to banks or large financial institutions. In reality, the scope is much broader.
You likely need MSB registration if your business:
If you send or receive funds on behalf of clients, including cross-border transfers, registration is mandatory.
Crypto exchanges, trading platforms, custodial wallet providers, and even some DeFi services may fall under MSB rules.
Any business converting fiat currencies (e.g., CAD to USD, EUR to CAD) must register.
Payment gateways and fintech companies handling third-party payments are typically considered MSBs.
Issuing prepaid cards, digital wallets, or stored-value accounts can also trigger MSB obligations.
Registering as an MSB is only the first step. Businesses must comply with ongoing regulatory obligations under Canadian law.
Every MSB must implement a full Anti-Money Laundering compliance program, including:
MSBs are required to maintain detailed records of transactions, including:
Records must be stored securely for a minimum period, usually five years.
Companies must report specific types of transactions to FINTRAC:
MSBs must verify customer identities using reliable documentation and risk-based approaches. This includes enhanced due diligence for high-risk clients.
The MSB registration process is relatively straightforward but requires accuracy and compliance readiness.
Before applying, the company must be legally incorporated in Canada or have a registered Canadian entity.
A full AML compliance program must be prepared, including policies, risk assessments, and reporting structures.
The business submits an online application through FINTRAC’s registration portal, providing:
FINTRAC reviews the application and may request additional information. Once approved, the company is officially registered as an MSB.
After approval, the business must continuously comply with reporting and audit requirements.
One of the most significant developments in Canadian regulation is the inclusion of cryptocurrency businesses under MSB rules.
Crypto companies must register if they:
This makes Canada one of the more structured jurisdictions for crypto regulation compared to many other countries.
However, crypto MSBs face additional scrutiny, including:
Despite strict regulations, obtaining MSB registration offers several advantages:
Companies can legally operate in Canada and serve Canadian customers.
Being registered with FINTRAC improves credibility with banks, partners, and investors.
Many financial institutions require MSB registration before opening business accounts.
Canadian MSB registration can support expansion into other regulated markets.
While beneficial, MSB compliance also presents challenges:
Businesses must invest in compliance infrastructure to avoid operational risks.
Failure to comply with MSB regulations can result in serious consequences, including:
FINTRAC actively monitors and enforces compliance, making adherence essential.
The MSB license in Canada is a critical requirement for any business involved in financial services, especially in the rapidly growing fintech and cryptocurrency sectors. While it is not a traditional license, MSB registration with FINTRAC ensures that companies operate within a transparent, secure, and regulated financial environment.
For businesses aiming to expand into Canada’s financial ecosystem, understanding MSB requirements is not optional—it is a fundamental step toward long-term success and regulatory compliance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 23, 2026
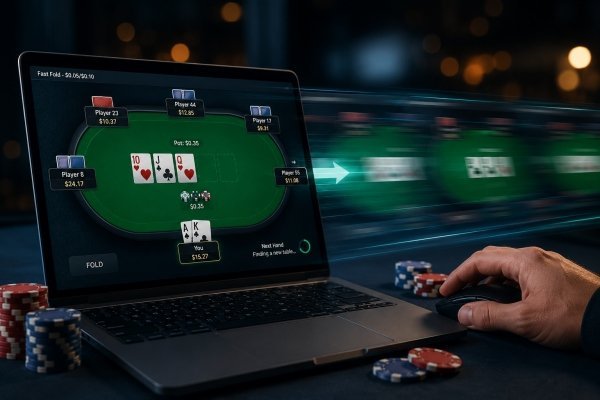
Poker has always involved waiting. A player folds a hand, the action continues around the table, and eventually a new deal begins. That rhythm remained largely unchanged for decades, both in traditional poker rooms and in the earliest online poker platforms.
Fast-fold poker took a different approach.
Instead of waiting for the current hand to finish, players who fold are immediately transferred to a new table and dealt into a fresh hand against a different group of opponents. It sounds like a relatively small adjustment. In practice, it created an entirely new poker format.
Today, fast-fold games appear under different names depending on the operator—And so, we have Zoom Poker, Snap Poker, Fast Forward Poker, Blaze Poker, and others—but the underlying concept remains similar.
The defining feature of fast-fold poker is not a new betting structure or a different version of Texas Hold'em. It is the removal of downtime.
In a traditional online cash game, a player who folds on the first betting round may spend the next minute watching the remainder of the hand unfold. Fast-fold poker eliminates that waiting period. That adjustment affects almost everything that follows.
More hands are dealt. More opponents are encountered. The pace becomes noticeably different from a conventional poker table, even though the rules of the game itself remain unchanged.
In many ways, fast-fold poker demonstrates how a software-based environment can reshape a familiar game without altering its foundations.
Some poker innovations can move easily between physical and digital environments. Fast-fold poker is not one of them.
The format relies on a large player pool, automated table allocation, instant card distribution, and software capable of moving participants between games in a fraction of a second. Though these conditions are difficult to reproduce in a traditional poker room, the online environment made the concept possible.
Once the necessary infrastructure existed, operators could create a format where tables functioned as part of a larger network rather than as individual games. A folded hand no longer meant waiting. It spelled more moving around, but also more playing.
Neither format replaces the other. They simply offer different poker experiences. In the table below, you can see the main distinctions between the two formats.
| Feature | Traditional Online Poker | Fast-Fold Poker |
| After folding | Wait for the hand to finish | Immediately transferred to a new table |
| Opponents | Same table participants | Constantly rotating player pool |
| Pace of play | Standard | Faster |
| Hands played | Lower volume | Higher volume |
| Table continuity | Consistent table environment | Continuously changing environment |
| Software role | Supports gameplay | Essential to the format |
The cards remain the same, yet the surrounding environment changes enough to influence how the game is approached.
Traditional poker often rewards detailed observations of specific opponents over extended periods. Players may notice betting patterns, timing habits, or tendencies that develop over multiple orbits at the same table. Fast-fold poker reduces some of those opportunities.
Opponents change constantly. Tables change constantly. The next hand may involve an entirely different group of participants. As a result, broader decision-making frameworks often become more important than long-term observations of individual opponents. The format places greater emphasis on adapting to changing situations rather than building reads against a small group of familiar players.
Although the immediate table change receives most of the attention, fast-fold poker is associated with several characteristics that distinguish it from traditional games:
Not every platform implements these features in exactly the same way. But together, they form the foundation of the format.
Fast-fold poker can produce a larger number of hands within a given period than traditional cash games. For that reason, many regulated operators provide tools designed to help users monitor both playing time and spending.
Depending on the platform, available measures may include deposit limits, reality-check reminders, cooling-off periods, self-exclusion programs, and session-management controls. Before participating in any gambling activity, players should review these tools and set them up according to their budget and time allowance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016