




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Banking Policy | Aug 12, 2025
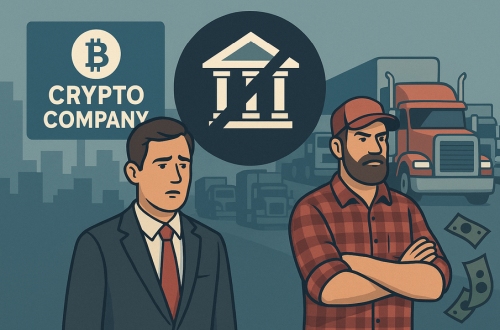
AI generated image of financial exclusion
On August 7, 2025, the White House issued an executive order aimed at ending “politicized or unlawful” debanking. The order directs U.S. regulators to ensure that banks cannot deny service based on political views, religious beliefs, or lawful industry participation, including cryptocurrency. It's the highest profile intervention in U.S. banking in decades and could influence how other jurisdictions handle access to financial services. In Canada, let us not forget the swift debanking of key persons related to the trucker convoy debacle only a few years ago.
Federal banking regulators are to remove “reputational risk” from examination manuals within 180 days. All decisions to deny or close accounts must be based on looking at each customer’s situation on its own, using facts rather than opinions, and assessing real financial and compliance risks instead of relying on broad labels or assumptions.
Regulators must review past cases of account closures or denials within 120 days and take corrective actions, including fines, consent orders, or reinstatement of clients. The Small Business Administration is tasked with urging lenders to reinstate borrowers affected by unlawful debanking. The Office of the Comptroller of the Currency has already updated its materials to comply.
Supporters of the order point to documented cases where lawful businesses, advocacy groups, or individuals lost access to banking without clear justification. Critics argue banks must retain the ability to consider reputational factors when managing compliance obligations under anti-money laundering and counter-terrorist financing laws. A Financial Times analysis notes that crypto companies have been prominent among those alleging discrimination, alongside political organizations and religious nonprofits.
While Canada has not adopted similar measures (yet), there are high profile cases revealing parallels, such as in 2022 when former-PM Trudeau invoked the Emergencies Act to freeze more than 76 bank accounts worth $3.2 million CAD tied to the Freedom Convoy. The Federal Court later ruled this unconstitutional, and the decision is under appeal.
In another reported case, a trucker convoy lawyer said that her Royal Bank of Canada account was closed after small cryptocurrency transactions. Crypto business operators have also described difficulty maintaining accounts, though no comprehensive national data exists.
Canadian banks operate under the Proceeds of Crime (Money Laundering) and Terrorist Financing Act and oversight from the Office of the Superintendent of Financial Institutions. Reputational risk is explicitly considered in supervisory frameworks. Consumers are entitled to open personal bank accounts unless specific conditions apply, and must be given written reasons for refusal under the Access to Basic Banking Services Regulations. Complaints can be escalated to the Financial Consumer Agency of Canada or the Ombudsman for Banking Services and Investments, but there is no mandated systemic review or reinstatement process.
| Feature | United States (Post-EO) | Canada |
| Stance on Debanking | Prohibits ideological or industry-based debanking | No federal rule prohibiting ideological or lawful industry debanking |
| “Reputational Risk” | Removed from regulatory supervision criteria | Integral to OSFI guidance and AML compliance |
| Remediation Process | Regulator-led review, possible fines, reinstatement | Individual complaints through FCAC or Ombuds |
| Transparency | Mandated objective, individualized reasoning for account decisions | Written refusal required, but criteria remain broad |
The U.S. executive order aims to reduce bias in access to financial services which should not be denied based on lawful activity or beliefs. For fintech and crypto entrepreneurs, the change should make banking access more predictable and less influenced by subjective judgments. While Canada’s regulatory approach emphasizes prudence and reputational safeguards, it may need to review these protections that remain at the expense of inclusion and competitiveness.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Crypto Policy | Aug 11, 2025
Image: Freepik
On August 7, 2025, President Trump signed an executive order called, "Democratizing Access to Alternative Assets for 401(k) Investors", directing U.S. regulators to explore ways to allow cryptocurrencies and other alternative assets in defined contribution plans like 401(k)s.
While it doesn't immediately mean that Americans can directly hold crypto investments in their retirement accounts, it does instruct the Department of Labor (DOL), the Securities and Exchange Commission (SEC), and the Treasury to coordinate on new frameworks that could make it possible. If this happens, it will have significant implications for U.S investors but also for fintech innovators and regulators in Canada who are monitoring trends South of the border.
The order requires the DOL to review and update its fiduciary guidance for retirement plan sponsors, with a specific focus on clarifying what due diligence, risk disclosure, and participant education would be required if crypto were included as an option.
It also directs the SEC to consider revisions to certain securities rules, including elements of the accredited investor framework, that could impact the packaging of crypto investment products for retirement plans.
Treasury and related agencies have been tasked with aligning tax, reporting, and compliance rules to avoid conflicting obligations. According to the official fact sheet, the review process is expected to produce proposed rule changes by early 2026.
Advocates explain that opening retirement plans to digital assets could help diversification and align with investor demand, especially among younger savers who already hold crypto in personal accounts.
This change could also create a massive new liquidity channel for the crypto sector while bringing it further into regulated financial infrastructure, as reported by Forbes.
For fintech and crypto innovators, Trump's executive order could blow up the addressable market for crypto retirement products, custody solutions, and participant education tools.
With opportunity comes risks of course. The DOL has previously raised concerns about crypto’s volatility, liquidity constraints, and valuation complexities in retirement plans.
Business Insider reported that plan sponsors could face elevated litigation risks if participant loses are tied to crypto holdings, especially without clear safe harbour protections. Implementation also requires custodians and record keepers to adapt their current systems for daily valuations, liquidity management, and tax reporting.
The U.S. executive order isn't about adding more ETFs to retirement accounts. It opens the door for 401(k) participants to gain exposure to actively managed investment vehicles investing in digital assets and other private market investments, directly within a tax-advantaged plan registered with the government. This could mean direct holdings of Bitcoin or Ethereum, or participation in private crypto funds not listed on public exchanges, if fiduciaries deem them prudent and compliant with ERISA standards.
In Canada, the gap is very real today. Registered plans like RRSPs, RRIFs, TFSAs, and employer pension plans cannot directly hold cryptocurrency. The Canada Revenue Agency’s qualified investment rules prohibit digital assets themselves from being held in registered accounts, whether or not the plan is self-directed. Investors can only gain crypto exposure through qualified investments such as Bitcoin or Ether ETFs listed on a designated stock exchange, or shares of publicly traded crypto companies. Private crypto funds, unlisted trusts, or direct wallet holdings are currently prohibited in all registered accounts.
If the U.S. implements this framework, Canadian retirement plans would be at a competitive disadvantage in offering digital asset investment innovation. For Canadian fintechs, such U.S. policy could create new product development opportunities south of the border, while providing an unprecedented case study for domestic regulators on how to balance investor protection with access to alternative assets.
This latest crypto policy development is another wake-up call and market opportunity for Canadian fintechs and regulators. The next 12 to 18 months will determine whether or not U.S. agencies can produce rules that satisfy both innovation advocates and investor protection, fiduciary watchdogs. If they succeed, Canada’s own retirement savings design could be the next frontier for digital asset integration, and if so, they need to be ready to respond.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Trade Wars | Aug 11, 2025
Image: Freepik AI
Nvidia and AMD have agreed to pay 15% of their revenue from Chinese chip sales to the US government in exchange for export licenses. It follows months of export restrictions on high performing chips like Nvidia's H20 exports to China which were halted earlier this year. Analysts previously warned that curbing H20 chip exports to China could cost up to $8 billion in quarterly sales, while AMD projected a $1.5 billion hit this year from similar restrictions.
The new 15% payment for market access is an unprecedented arrangement, one that highlights the US strategy to assume control over critical AI and semiconductor technologies. It raises significant concerns around global tech trade, supply chains and geopolitical tensions, especially given China's reaction and what's next for tech competition and national security, both taking center stage with a new layer of complexity to the relationships between the US and China.
Canada and other global players will feel the ripple effects of these changes, especially if national security continues to impact global trade policies, which could force countries (and companies) to choose sides in a growing tech war.
The Chinese government has long accused Washington of using technology and trade policy to limit China’s rise in advanced industries. Following the 15% deal, state media criticized the H20 chip as outdated, unsafe, and potentially embedded with backdoor access, showing the growing mistrust of American AI chips while suggesting that the 15% levy is a political tool rather than a commercial safeguard.
As China sees the US moving to limit its access to critical technologies, the message is pretty clear that China is not backing down. They are already investing heavily in building alternative solutions. With companies like Huawei pushing forward on semiconductors and AI chips, China’s push for tech independence is only going to gain speed.
Aug 12 Update: Bloomberg reported that China has issued new guidance advising domestic firms to avoid using Nvidia's H20 chips in certain projects, especially any government use and to prioritize domestic chips wherever possible. This restriction will likely accelerate China's push for self reliance in advanced semiconductor protection, and could reduce demand for Nvidia's products in one of its largest markets.
With China representing 13% of Nvidia’s and 24% of AMD’s total revenue, even a small sales disruption can ripple through suppliers, distributors, and end markets. Semiconductor assembly and packaging hubs in Southeast Asia could also see order volatility if Chinese buyers switch to local alternatives.
The semiconductor industry is already experiencing shortages and supply chain disruptions, especially as the US and China continue to fight for dominance in manufacturing, however with the introduction of a type of financial leverage into the equation, the US could disrupt the delicate balance that keeps the global supply chain moving forward. Global logistics networks could be forced to reconfigure as companies diversify sourcing to hedge against export licensing risks.
This will hit industries reliant on critical AI chips and semiconductors, including everything from automotive and consumer electronics to AI and fintech. For companies in Canada, especially those that have tech partnerships with China, there will be an increasing need to diversify their supply chain sources to avoid disruptions and remain resilient in the face of trade barriers and tariffs.
With this new 15% payment arrangement, technology export controls could evolve into tools of economic statecraft that could be applied in other high-value tech sectors. If adopted more widely, it's a model that could ignite retaliatory tariffs or revenue-sharing requirements from other governments, creating a patchwork of national rules that complicate multinational operations.
Countries like India, which is rapidly scaling its semiconductor sector, are no doubt watching closely to see whether aligning with one tech bloc risks alienating another.
The growing tech and supply chain tensions mean that Canadian companies must carefully position themselves and ensure they adapt to the changing regulatory environment. As both China and the US reconfigure their tech ecosystems, Canada’s role as a tech hub will depend on its ability to stay nimble, maintain access to key technologies and markets, and diversify trade relationships.
For companies, investors, and policymakers, it's a strong reminder that the next front in trade disputes will not be over commodities, but over the intangible building blocks of future economies.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
M&A | Aug 8, 2025

On August 7, 2025, enterprise blockchain digital payment leader Ripple announced that it's entered an agreement to acquire Rail, a Toronto-based stablecoin global payments platform for $200 million. The acquisition will boost Ripple’s stablecoin infrastructure and solidifies its position as a leader in the digital asset payments industry.
Founded in 2021 by Bhanu Kohli and Tarun Mistry as Layer2 Financial, Rail is a Canadian-registered company based in Toronto, Ontario. The company's mission from the start was to build a platform that would enable instant, transparent, and reliable international payments for businesses using stablecoin technology alongside fiat support. Rail’s focus on combining digital asset infrastructure with compliance made it an ideal fit for a growing cross-border payments market.
In 2024, Rail rebranded to its current name and raised $10.7 million in Series A funding.
To date in 2025, Rail processed over 10% of the global $36 billion in B2B stablecoin payments, flexing it's growth and benchmarked market share.
Rail is officially registered in both Canada and the United States. Its registration as a money services business with the Financial Transactions and Reports Analysis Centre of Canada (FINTRAC) and the U.S. Financial Crimes Enforcement Network (FinCEN) further underscores its commitment to meeting regulatory standards and building a trusted platform for cross-border payments.
Rail's infrastructure improves Ripple’s stablecoin payment capabilities, especially in the growing B2B payments sector. Ripple has spent over a decade building digital asset infrastructure that integrates seamlessly with traditional finance. Ripple’s platform offers businesses secure, compliant tools for storing, trading, and transferring value, making it an ideal complement to Rail’s innovative stablecoin solutions.
Monica Long, Ripple President:
“Stablecoins are quickly becoming a cornerstone of modern finance, and with Rail, we are uniquely positioned to drive the next phase of innovation and adoption of stablecoins and blockchain in global payments. Ripple has one of the most widely used digital asset payment networks in the world, and this acquisition underscores our commitment to helping our global customer base to move money wherever and whenever they need.”
Ripple’s expanded offering will allow businesses to process stablecoin pay-ins and pay-outs across key financial pathways, such as USD, without needing to hold crypto on their balance sheets. This simplifies the payment process for companies and it's cost effective for international transactions.
Beyond stablecoin transfers, the Ripple-Rail offering will enable businesses to manage third-party payments and internal treasury flows seamlessly through a unified platform. Rail’s automated back-office infrastructure provides an always accessible 24/7 global payment network via a single API. So customers have access to a reliable payment solution at all times.
Ripple also recently acquired a multi-asset prime broker Hidden Road for $1.25 billion on April 8, 2025.
In addition to the acquisitions, Ripple's growth is benefiting from positive regulatory sentiment in the U.S. The SEC dropped its case against Ripple regarding its XRP token, and the approval of the U.S. Senate's Genius Act earlier this year, establishing a framework for stablecoin regulation.
Bhanu Kohli, CEO Rail:
“Over the last four years, Rail built the fastest way to settle business payments internationally using stablecoins, and in 2025, Rail is forecasted to process over 10% of the $36B global B2B stablecoin payments. Ripple shares our vision, and together, we’re excited to bring our innovation to the millions of businesses that move money internationally.”
By combining Ripple’s established network with Rail’s innovative stablecoin infrastructure solutions, the two companies will provide more comprehensive solutions for businesses that need to move money across borders. As stablecoin adoption continues to rise, businesses will increasingly look for solutions that simplify cross-border payments while ensuring compliance with global regulations.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Artificial Intelligence | Aug 8, 2025
Image: Freepik/kjpargeter
On August 7, 2025, OpenAI officially announced the release of GPT-5, it's latest artificial intelligence (AI) model with advanced capabilities that could significantly transform sectors in the near future, including fintech. From improving app development processes to enhancing customer engagement, GPT-5 offers companies with powerful tools to innovate and stay competitive. This article looks at key features, performance, and how it could be applied to real-world fintech applications.
GPT-5 introduces several exciting features, each with direct relevance to fintech. Here's an overview of some key upgrades and how they can impact fintech businesses:
GPT-5 can now handle more multi-step, data-driven tasks; it's more agentic. In fintech, where decision outcomes usually rely on complex financial models and large datasets, GPT-5 can generate more accurate insights and prediction results. A credit risk model that combines structured data (e.g., income, credit history) with unstructured data (e.g., social media sentiment, customer reviews).
GPT-5’s improved reasoning can analyze these diverse data sources in real-time, helping fintechs and financial institutions make better lending decisions that ultimately reduce default risks. For example, a fintech company offering microloans could integrate GPT-5 into their platform to analyze the creditworthiness of borrowers by evaluating non-traditional data sources, such as purchasing behavior or community feedback, alongside traditional financial data.
One of GPT-5’s most anticipated features is vibe coding, which is in hot demand. Just look at vibe coding pioneer Lovable, the fastest growing software company in history. Instead of writing lines of code, developers or pretty much anyone who can engineer a robust prompt, can now simply describe the functionality they want, and GPT-5 will generate the actual code. This has massive implications for fintech businesses looking to quickly prototype new applications or tools without extensive coding expertise. For example, a fintech startup looking to launch a budgeting app can describe the app’s desired features, such as “track user spending across categories like food, rent, and entertainment”, provide the data sources and GPT-5 will create an actual working app prototype, saving time, reducing costs, and enabling product innovators to quickly test ideas in the market.
GPT-5 can handle more complex multimodal tasks, allowing it to interact with a wider range of data types and inputs in real-time (i.e., text, images, audio, video), offering users a more dynamic and improved customer experience, such as an AI concierge service assistant that can respond to user questions and use cases using not just text but also analyze and generate images like financial charts or explainer videos, improving communication and user satisfaction.
For example, fintech platform offering investment advice could use GPT-5 to generate personalized financial reports for clients. Instead of just providing text-based summaries, the model could generate visual reports with graphs and interactive charts, making the information more understandable for users.
GPT-5 takes personalization to the next level by adjusting its responses in real-time based on a user’s preferences and needs during the conversation. It doesn’t store information beyond the current session but uses contextual understanding to make financial advice more relevant. For example, if a user mentions an interest in low-risk investments, GPT-5 will personalize its responses accordingly, even if the user doesn't repeat it later in the conversation. It also adapts the complexity of its advice based on the user's level of knowledge, whether they need basic tips or more detailed strategies. This ability to dynamically adjust in real-time helps fintech companies deliver highly personalized experiences without relying on long-term memory.
Fraud prevention and regulatory compliance are critical in fintech for trustworthy regulated transactions. GPT-5 comes with stronger pattern recognition capabilities that can help automate these processes. By analyzing huge amounts of transactional data in real-time, GPT-5 can spot suspicious activities and flag potential fraud better than before.
GPT-5 can also be integrated into regulatory compliance tools to ensure that fintechs and their users meet legal requirements by identifying gaps and discrepancies of non-compliant behaviours. By analyzing not just transaction patterns but also customer interactions (e.g., communications with support), GPT-5 could improve fraud detection accuracy and reduce false positives.
Reports say GPT-5 reduces factual error rate by 45% compared to GPT-4o, so responses are more reliable and accurate. This is of course highly useful for fintech use cases that need high accuracy to support decision making such as a loan approval.
Checkout Datacamp's GPT-5 benchmarking review for details. In short, GPT-5 is better than GPT-4o at coding, math, multimodal tasks, and handling large contexts, making it a more powerful AI to handle complex tasks required in financial services.
OpenAI's launch of GPT-5 has not been without its challenges. CEO Sam Altman admitted that the rollout faced several issues, particularly with an automatic model selecting feature, which initially wasn't working as expected. In a Reddit AMA, Altman admitted that the model’s rollout was "bumpy" but reassured users that the team made some improvements to GPT-5, which "will seem smarter starting today". Also after many users expressed a preference for the older model's personality and performance, OpenAI decided to reinstate GPT-4o for ChatGPT Plus subscribers. It appears that Altman underestimated how much users valued GPT-4o's specific traits.
To explore the power of GPT-5's vibe coding, we tested its capabilities by asking it to create a mini interactive game that incorporates the NCFA logo. The goal was to see how easy it was to use GPT-5 to generate a simple, interactive point driven game from a single plain language prompt.
Here’s the prompt we used:
"Create a simple interactive game where users can click to collect NCFA logos that appear randomly on the screen. The game should have a basic scoring system, a start and stop button, and a simple animation for the logos as they appear and disappear. The game should be created using HTML, CSS, and JavaScript. The NCFA logo should appear as an image file that I can upload."
It took GPT-5 about 10 seconds to generate the full code, which included:
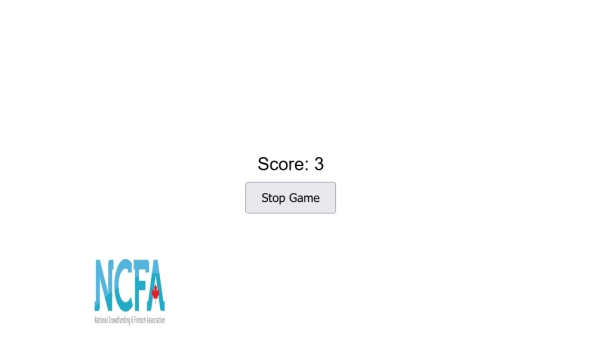
Image: NCFA logo game code vibing test
The game worked perfectly with the National Crowdfunding & Fintech Association of Canada's logo intermittently bouncing all over the screen, with points accumulating with each accurate click on the logo. Imagine creating promotional games or interactive educational tools quickly without needing extensive coding experience. Yes, the warning to software engineers is true.
Funny that Microsoft recently published a report predicting the top 40 job types at risk of being taken over by AI agents, but somehow their list doesn't seem to include software programmers? At the same time, Microsoft's CTO said that in the next 5 years, AI will handle 95% of all coding.
GPT-5 is another step towards the future of artificial intelligence, now offering fintech businesses more advanced tools to innovate quickly. Whether it’s improving decision making with advanced reasoning or customer engagement with personalized experiences, or simplifying app development with vibe coding, GPT-5 is a powerful asset for any fintech company at this point of the AI revolution, making it an critical intelligence engine for to help fintechs improve operations and deliver smarter, more personalized experiences for their customers. Now just wait for all the competition looking to level up next.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Fintech Report | Aug 5, 2025
Image: Freepik
The latest Q3 2025 PitchBook report confirms an investment gap is being driven by a clear premium on automation and AI-enhanced infrastructure. PitchBook data shows that early stage AI-enabled fintechs are raising at a median pre-money valuation of $134 million. That is 242% higher than the $39.2 million median for non-AI peers. Startups with built-in AI capabilities have raised $3.5 billion across 171 venture deals so far this year, capturing 54.4% of total deal value. By comparison, non-AI fintech firms closed 195 deals but raised only $3 billion.
The largest gap is at the early stage. AI-enabled fintech startups are raising at a median pre-money valuation of $134 million, compared to $39.2 million for non-AI peers. That is a 242% premium, the highest of all stages in 2025. Only the pre-seed and seed levels showed a small dip but Pitchbook attributes to limited disclosures and early year sample effects.
At the venture growth stage, AI fintechs are closing deals with a median round size of $50 million, compared to $30 million for non-AI fintechs, a 66.7% premium.
Later stage AI fintechs are also attracting higher valuations. Their median pre-money valuation is $72.5 million, 6.7% higher than the $68 million median for non-AI companies.
Of all U.S. AI-enabled fintech companies, 80.3% are B2B. The most active segments are CFO stack (19.5%), wealthtech (18.4%), and financial services infrastructure (15%). These areas are drawing the largest funding rounds and investor attention.
In 2025, financial infrastructure AI firms raised $887.9 million, while non-AI peers in the same segment raised just $216 million. Ramp, Plaid, and Addepar each secured funding rounds of $200 million or more.
AI of course dominates the regtech sector with At the venture growth stage, AI fintechs are closing deals with a median round size of $50 million, compared to $30 million for non-AI fintechs, a 66.7% premium..
In 2025 to date AI fintechs are raising more money per round than their non-AI peers. The typical deal size for an AI fintech is $8.4 million, which is 7.7% higher than the $7.8 million median for non-AI companies. At the seed stage the gap is even wider. AI startups are raising $4.1 million per round, compared to $3.2 million for non-AI startups, a 28.5% premium.
These companies are not just raising more. They are also raising faster. The average time between funding rounds is 1.85 years for AI fintechs, slightly shorter than the 1.90 years it takes non-AI fintechs. The difference may seem small but it suggests that investors are more willing to write follow-up checks quickly when they see momentum and early results.
So far in 2025 exits for AI fintech companies remain limited. These companies have generated $10.6 billion in total exit value across 17 deals, but most of that came from one transaction. Chime’s IPO alone accounted for $9.1 billion. Without it, the remaining exits add up to just $1.5 billion, which is lower than the $2.3 billion recorded across 31 exit deals by non-AI fintech companies.
On the other hand, mergers and acquisitions (M&A) are gaining momentum. AI fintechs have completed $20.7 billion in M&A activity across 24 deals so far this year. That puts 2025 on pace to match 2024, which ended with $53.2 billion in total M&A deal value for AI companies. Buyers are looking to speed up their internal AI capabilities, improve their product offerings, compete with new startups, and build stronger decision-making systems powered by data.
AI is no longer optional for fintech companies that want to lead. Investors are rewarding AI first companies with faster funding, larger checks, and significantly higher valuations. These companies aren't just building automation tools but are quickly becoming the new infrastructure layer across enterprise finance, compliance, and infrastructure. It's pretty clear that founders who want to be globally competitive must build AI into the core of it's model, not the margins.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Global Standards | Aug 4, 2025
Image: Freepik
Canada chooses how it measures its economy but if it wants to be part of the global system, it needs to follow the updated rules. The System of National Accounts (SNA) is a global reporting framework developed and published jointly by the UN, IMF, OECD, World Bank, and European Commission to measure and compare economies across borders, including GDP, investment, and national wealth. Canada has followed it for decades, along with almost every other economy in the world, so we can expect change is coming.
Now, for the first time since 2008, the SNA has been updated. It gives countries the option to include intangible assets like AI systems, datasets, software, cloud infrastructure, and crypto in their official economic reporting. SNA 2025 is the new data reporting standard.
Statistics Canada currently uses SNA 2008 to compile GDP, capital formation, trade, and household income. Finance Canada and the Bank of Canada rely on that data to make major policy decisions. Because Canada aligns with the international system, it will be expected to transition to SNA 2025, and include a new measured view including intangibles, which NCFA has reported and advocated for the inclusion of intangibles for years. See this great report dating back 6 years ago now in 2019 called, " A New North Star: Canadian Competitiveness in an Intangibles Economy".
The new SNA 2025 includes formal categories for AI tools, machine learning models, digital platforms, tokenized assets, and data used in production. These can now be classified as fixed capital and included in investment statistics.
The framework also includes crypto assets such as Bitcoin in national wealth reporting. While countries are not required to adopt every element immediately, SNA 2025 sets the boundaries for what is allowed. If Canada continues using the SNA—and it will—these options are now on the table.
SNA 2025 does not show that digital or intangible assets are driving growth nor does not include statistics. What it does is give countries the structure to count what was previously invisible. Until now, if a Canadian fintech trained a large AI model, built infrastructure for a payments network, or developed a data engine for fraud detection, none of that was guaranteed to show up in national accounts. It was often treated as a cost, not an investment.
That matters because what gets counted drives policy.
When Statistics Canada does not report digital capital formation, Finance Canada cannot target it. When platform services are excluded from output figures, regulators and funders underestimate their value.
SNA 2025 also introduces new tools to reflect sustainability. It promotes the use of Net Domestic Product (NDP), which subtracts both depreciation and natural resource depletion from GDP. This is critical for a country like Canada, where growth often comes from extractive sectors. Using NDP can help the government better understand how much of that growth is truly lasting.
The new framework also supports clearer tracking of ESG finance, public sector innovation, and economic activity by multinationals that operate across borders. It aligns with global changes in how governments view risk, resilience, and value creation.
This is a global accounting and reporting change with deep consequences. SNA 2025, the updated global standard now recognizes intangibles, and so will the data that influences budgets, tax design, economic forecasts, and investment strategy. Canada is already committed to using the SNA, so the only question is how fully and how quickly we adopt the 2025 version.
NCFA urges Statistics Canada and federal decision makers to prioritize early implementation of the most relevant components of SNA 2025. These include digital capital assets, crypto asset recognition, and intangible production by fintech and AI firms.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016