




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 4, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Digital Assets Blockchain And Tokenization, Cybersecurity Fraud And Financial Crime, SME Finance And Business Banking, Capital Markets And Market Infrastructure, Policy Regulation And Governance, Risk Compliance And Regtech, Data Privacy And Governance

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026).
AI training data now carries an auditable collection burden across source choice, legal basis, sensitive data and model output controls. Canadian fintechs using European personal data should map what is scraped, why it is needed, who controls the processing and how records can be filtered or removed before consultation language becomes supervisory practice.
Fund innovation depends on regulatory speed as well as product design. Asset managers, exchanges, fintechs, wealth platforms and regulators should watch how dedicated approval pathways and product specific guardrails influence the pace of retail investment innovation without reducing investor protection.
Swift is testing whether tokenized deposits can extend today's banking infrastructure into always available cross border payments without replacing existing settlement systems. The pilot results will provide an early benchmark for bank led tokenized payment networks.
Always on market design is moving beyond crypto. Exchanges, brokers, clearing firms, liquidity providers, risk teams and regulators should watch how 24/7 trading changes oversight, operations, margin, surveillance and market resilience.
Credit infrastructure is consolidating around data depth, identity coverage and alternative underwriting. Lenders, fintechs, credit bureaus, SME finance platforms and regulators should watch how alternative data, fraud controls and AI assisted decisioning affect credit access for thin file borrowers and small businesses.
Hong Kong is replacing a widely used authentication method across online securities and regulated virtual asset trading. Brokers and platforms also need stronger monitoring, client notifications and incident response procedures, while senior management may be held accountable for losses caused by inadequate controls.
The findings connect payment design directly to fraud exposure, customer friction and trust. Lower fraud by transaction count is encouraging, but higher losses by value and rising first-quarter fraud show why scale requires stronger authentication, transaction risk data and coordinated controls. These operating results add important context to the UK’s payment milestone and Canada’s trust framework.
Financial institutions and technology providers will gain a structured environment for testing AI security tools against European requirements. Firms serving the European market should prepare to demonstrate model safety, operational resilience and secure deployment before advanced systems enter critical financial operations.
AI cyber risk is now a financial stability issue. Banks, fintechs, payment firms, infrastructure operators, software vendors and supervisors should watch how AI vulnerability discovery, third party concentration, open source dependencies and cyber resilience planning become part of financial sector oversight.
Circle's trust charter places a major stablecoin issuer inside the U.S. federal banking framework. The pace of implementation, custody adoption and any future expansion into reserve management will show whether trust banks become the preferred operating model for regulated stablecoin infrastructure.
The paired licences let one regulated provider connect crypto conversion, asset transfers, conventional payments and payment accounts. Firms pursuing similar models across Europe will need to determine when MiCA authorization must be combined with payment permissions as their products cross from digital assets into fiat payment execution.
Crypto platforms are moving toward regulated multi-asset investment access. Exchanges, brokers, dealers, crypto platforms, regulators and investors should watch how derivatives, equities and crypto converge inside licensed investment platforms.
MiCA is becoming a market access gate for global digital asset firms. Banks, payment companies, custodians, stablecoin issuers, exchanges and compliance teams should watch how full EU authorizations shape cross-border crypto services, institutional distribution and regulated stablecoin infrastructure.
Eltropy is turning agentic banking into a platform market rather than a closed vendor product. The commercial question is whether shared controls, integrations and distribution can make specialized financial agents easier for smaller institutions to adopt.
Regulated AI adoption needs control infrastructure, not only models. Banks, insurers, telecoms, fintechs and compliance teams should watch how agent oversight, inference monitoring, shared IP and enterprise control planes become part of Canadian AI governance.
AI in retail finance is becoming a competition, consumer protection and fraud issue at the same time. Banks, fintechs, wealth platforms, insurers, lenders and compliance teams should prepare for AI agents, personalization, delegation, identity controls and new forms of consumer harm.
Large fintechs are testing direct charter strategies again. Lenders, BNPL firms, embedded finance platforms, banks, investors and regulators should watch whether major payment and credit firms choose bank partnerships, owned charters or hybrid models for the next stage of regulated growth.
Regulators are increasing both the reach and speed of financial misconduct enforcement. Firms now face faster detection, coordinated action across jurisdictions and far less time to correct weak promotion, reporting and compliance controls.
This week’s intelligence points to a more mature phase of financial innovation. Stablecoins are entering regulated banking structures, tokenized deposits are nearing live payment use, regulators are setting terms for continuous markets, and AI governance is becoming a practical operating requirement. In Canada, the Real Time Rail rules, PSP access model and planned Q4 launch show how domestic payment modernization is entering the same execution stage. Advantage will favour institutions that can combine trust, regulatory readiness and delivery at scale.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Jul 10, 2026 | NCFA Resource | Payments And Money Movement, Regulation And Policy, Risk Compliance And Regtech

Canada’s Real-Time Rail is Payments Canada’s new exchange, clearing and settlement system for instant, data rich payments. Its approved By-law and Rules establish the legal and operating framework for PSP access, participation, settlement, fraud controls, ISO 20022 implementation, testing and the planned Q4 2026 launch.
On July 10, 2026, NCFA published a Real-Time Rail Rules and Access Intelligence Guide that brings the requirements, participation routes and operating considerations into one practical reference.
The guide covers the RTR By-law and Rules, Payments Canada membership, PSP access, direct and indirect settlement, Bank of Canada settlement accounts, centralized fraud controls, technical integration, payment finality, operational readiness and the products and services the rail could support.
The resource helps readers separate what has been approved from the work still required before an organization can participate in the RTR or launch a product using it.
Legal eligibility does not create automatic access. Depending on the operating model, a firm may still need RPAA registration, Payments Canada membership, a direct or agent settlement arrangement, ISO 20022 integration, fraud service connectivity, security controls, testing, certification and continuous operations.
The guide also compares different routes into the market. Organizations may pursue direct settlement, work through a settlement agent, develop customer products through an RTR participant or provide software, connectivity, fraud, testing and managed access services.
This resource is useful for payment service providers, banks, credit unions, fintech founders, infrastructure providers, fraud and identity firms, compliance teams, investors, policymakers and organizations assessing real time payment products.
It is especially useful for teams working through access, settlement, liquidity, fraud controls, ISO 20022, testing, certification, payment initiation, pay by bank, treasury, reconciliation and embedded payment models.
The strength of this resource is that it brings Canada’s RTR rules, access requirements, settlement choices, fraud services and implementation dependencies into one working reference. It also explains how real time payments connect with consumer driven banking, data portability and the next generation of digital financial services.
The guide can also help firms choose a realistic operating role before committing to the cost and continuing obligations of direct participation. Direct settlement provides more control, while partner, software, connectivity and managed settlement models may offer a more practical route to market.
The limit is that approval of the By-law and Rules does not complete implementation. Technical specifications, participant onboarding, commercial agreements, testing, certification, pricing, product launches, customer adoption and fraud performance will continue to develop.
Readers should use the guide for ecosystem intelligence and planning, not as legal, financial, investment, compliance or professional advice.
Canada Real-Time Rail Rules And Access (primary NCFA Regulatory Intelligence page)
PSP Registration With The Bank Of Canada (RPAA registration and supervision)
Open Banking In Canada Opportunity Brief (payment initiation and open finance opportunities)
RTR By-law And Rules Approval (official Payments Canada update)
Payments Canada Real-Time Rail (official system hub)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 10, 2026
AI Image: Cryptocurrencies give us a chance to get closer to the action
The way that digital finance and mainstream entertainment have come together has given us a variety of new ways to enjoy our favorite activities. Sports fans are among the people who can most appreciate these changes, so let’s take a look at how cryptocurrencies are enhancing the way they interact with their chosen teams and sports.
The arrival of online sportsbooks was one of the most notable events for sports in recent times. Being able to find the latest, updated odds from events around the planet was a massive step forward. It means that we can now just as easily bet on the NHL, the NBA, or a table tennis tournament from the other side of the world. Many sportsbooks also provide casino games, ensuring they offer fans a well-rounded platform with lots of options.
Of course, finding a fast and safe way of moving funds in and out of these platforms was the next big challenge. Since it’s a fast-moving industry, fans need to be able to make deposits swiftly and securely, while they also want the security of being able to make rapid withdrawals with complete safety. Traditional fiat methods have been used to good effect, but the growing use of cryptocurrencies allows fans to take advantage of a highly secure and almost instant transfer process.
Looking at this online casino in Canada, we can see that Bitcoin (BTC), Ethereum (ETH), and Tether (USDT) are among the tokens accepted. These are some of the biggest cryptocurrencies in the market, meaning that they offer deep liquidity. Transfer times vary across networks, although most are completed almost instantly. Fees also vary, with most offering an extremely cost-effective approach.
The transfer process is simple once you understand the basics. Fans need to buy their chosen token first, which is usually done through an exchange. The next step is to send the cryptocurrencies to a self-custody wallet, and from there to the sportsbook’s wallet.
Given the added privacy with digital assets, this could also be viewed as a way to ensure that there is a buffer between the user’s main bank account and their gambling account. Some folks like to have a layer of separation, and cryptocurrencies make this significantly easier.
Fan tokens have emerged as one of the most interesting uses of cryptocurrencies. Soccer teams like Manchester City and PSG are among the top options for anyone looking for fan tokens. With fan tokens recently getting the green light in the US, Chiliz has an agreement with the NFL and NBA that lets them offer digital perks without minting any specific team tokens.
The right to vote on fan matters is one of the key aspects of fan tokens, since the holders of these tokens are offered the chance to vote on issues such as team outfits and fan chants. Arguably the first example came from Italy in 2019, when fans of Juventus voted for Song 2 by Blur as the team’s goal celebration music. Barcelona and PSG token holders have also successfully voted on their teams’ music choices in recent years.
In North America, the Professional Fighter League has used fan tokens to help choose the entrance anthems for fighters and also to set the questions to be asked at official press conferences. In the NASCAR world, Roush Fenway Racing (now RFK Racing) launched the first fan token and gave holders the opportunity to vote on various themes and designs.
The UFC went a step further by giving its token holders the chance to attend weigh-ins as VIP guests. This token also has a mechanism where the user’s number of tokens is applied to work out their exact voting power.
Digital assets can also be used to carry out real-world matchday transactions. The first example of Bitcoin being used by a major sports franchise came from the Sacramento Kings in 2014, when they teamed up with the BitPay payment processor. As well as entrance tickets, fans were able to use BTC to pay for official team merchandise at the store.
The NFL has also moved in the same direction. The Tennessee Titans provide a good example, as this franchise accepts BTC for season tickets and corporate sponsorship payments. We can also see the example of the Houston Texans, who accept BTC for the booking of luxury suites at games. In the wider sports world, FIFA naming Kraken their Official Crypto Exchange Supporter of the FIFA World Cup 2026 is a clear sign of how deeply embedded crypto has become in sports.
Whether you want to place a bet, buy a ticket, or help make fan decisions, cryptocurrencies have been playing an increasingly large role in the way you enjoy your favorite sports. By choosing the right tokens and determining how to use them, you can get more out of your sports-based entertainment.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 10, 2026
Financial technology organizations are often able to grow - employing staff from different countries - these companies use international recruitment to address high workloads, find highly trained employees and enter new geographical areas. Many professionals, like software engineers, data researchers and client service experts, prefer roles that allow them to work from any location. While these hiring practices are beneficial, businesses are responsible for managing the specific challenges involved.
Worker classification is a primary factor for companies to manage when they hire across borders. Organizations that identify their staff correctly are able to prevent legal disputes and avoid the loss of money. Businesses that operate in multiple countries have fewer administrative tasks when they clearly define the legal status of their international workers.
Worker classification is the process where an organization determines if a person is an employee or an independent contractor. Companies are required to follow specific guidelines to establish the legal status of their workers. Government agencies and courts evaluate the degree of control an employer has and how much independence a worker maintains to make this decision. Please be aware that the label a company gives to a worker is not the only factor that determines their status.
This consideration is particularly important for companies that staff internationally. The status of a worker who provides services from abroad can change depending on the country where they originate. As such, businesses should understand the implications of classifying employees as independent contractors outside their jurisdiction.
Businesses can suffer adverse financial and legal consequences from misclassifying workers. For instance, companies may incur substantial expenses by following court orders mandating retroactive payments of payroll taxes, overtime, and social benefits. In addition, businesses must consider litigation costs in any resulting disputes over misclassification.
Companies that hire internationally must navigate complex legal frameworks when classifying their workers. Most jurisdictions allow businesses to employ independent contractors on either a full-time or part-time basis. However, certain countries require organizations to treat such workers like employees. It can be challenging to ensure that employment terms abide by all applicable statutory requirements in different jurisdictions. As such, companies may find themselves facing adverse consequences when trying to establish long-term contracts for workers based abroad. To mitigate these risks, businesses turn to local attorneys and a Toronto Employment Lawyer to understand the implications before hiring.
How a company classifies its workers influences how the business functions. Management must recognize the administrative tasks and legal requirements that apply to different categories of workers - these arrangements are important because they change how the company processes payroll, manages benefits plus protects private data. Leaders are able to use this information to plan their workforce and lower the risk of legal disputes.
The status of a worker is what defines their specific legal rights but also responsibilities. Individuals who are employees are usually eligible for more protections and company provided benefits than those who are independent contractors. If a company understands these distinctions, it is able to follow the law as well as maintain a consistent hiring process - this knowledge is necessary for organizations that intend to grow in multiple countries and use the specific abilities of their staff effectively.
The financial technology industry is subject to many regulations. Companies are required to dedicate time and money to follow laws regarding data privacy, security for digital information plus financial reporting. This commitment to compliance is also necessary when businesses hire staff. Classification of workers is an important process because these organizations manage private data and perform money transfers for customers. Organizations that hire people in other countries are encouraged to monitor legal changes but also speak with an employment lawyer. Audits are a helpful tool to identify problems and lower risks before a company hires remote employees.
Fintech companies often find benefits in hiring employees from other countries - this approach allows businesses to grow and find qualified workers in a larger market. All staff members must follow the same professional requirements regardless of their location. Management teams are responsible for creating clear rules for international hiring to keep processes uniform and minimize potential problems.
Rules change depending on the country - businesses are more successful when they monitor legal updates. A detailed plan for following laws is necessary because international employment is complex - these strategies are also important for keeping the trust of investors and protecting the public image of the company.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 9, 2026 | NCFA Market Activity | Fintech AI/ML, Data-driven, Automation, Generative AI, Enterprise, Scaleup, Fintech And Innovation
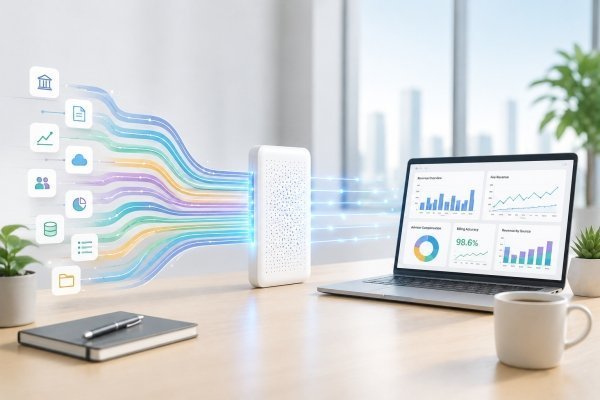
Wealth firms can’t automate revenue operations if the upstream data that's feeding billing, advisor compensation and reporting still needs manual repair.
On July 8, 2026, Toronto based PureFacts announced a strategic partnership with WealthTechs to launch new data aggregation and ingestion capability for wealth and asset management firms.
PureFacts will license and embed WealthTechs’ data aggregation and connectivity technology into its platform. The company will use the technology to connect, normalize and validate data before it enters revenue workflows.
Those workflows are high stakes. PureFacts supports fee billing, advisor compensation, practice management and revenue intelligence.
Robert Madej, Founder and CEO of PureFacts, said:
"This partnership with WealthTechs marks an important step forward in our mission to empower wealth firms with a trusted data foundation."
Wealth management has a data plumbing problem inside revenue operations.
Account records, transactions, portfolio data, fee schedules, householding rules and advisor relationships often come from different systems. The business still has to turn that data into client fees, advisor compensation, reporting and management insight.
PureFacts describes its platform as Revenue Performance Management software. Its product set includes fees and billing, advisor compensation, practice management and revenue book of record. WealthTechs brings an ingestion layer that turns source data into usable operating data.
Revenue, compensation and compliance teams all depend on the same underlying data. If that data is inconsistent, every workflow downstream inherits the problem.
PureFacts says the partnership supports future agentic AI capability, but the initial work starts with cleaner data.
Data has to be connected before it can be used. It has to be normalized before it can be compared. It has to be validated before a firm can trust automation inside billing, compensation or advisor operations.
The same requirement is emerging across wealth management. See: FutureVault Ships Agentic Document Intelligence For Advisors.
Agentic AI is even riskier since it may initiate a workflow, recommend an action or help resolve an exception. In wealth operations, that means the data layer needs controls, auditability and clear ownership before automation scales.
The partnership gives PureFacts a deeper data ingestion capability for revenue operations. Not AI as a headline. AI as the downstream beneficiary of cleaner enterprise data.
Can wealth firms deploy agentic AI in revenue operations before they solve data aggregation, normalization and validation?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 9, 2026 | NCFA Market Activity | Payments And Money Movement, SME Finance And Business Banking, Fintech And Innovation
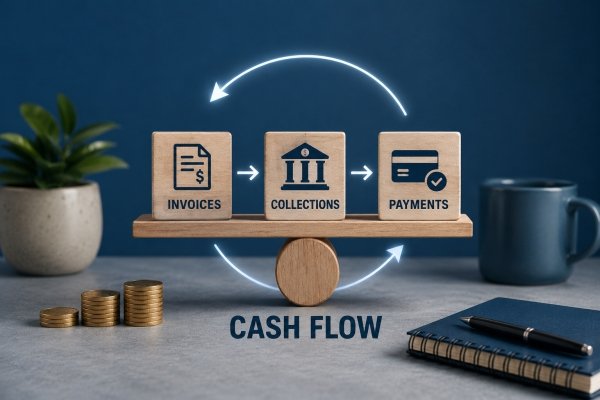
On July 7, 2026, Winnipeg based Telpay announced that it acquired Notch Financial, a Toronto based accounts receivable automation company. Terms weren't disclosed.
The acquisition brings accounts receivable, invoicing and payment collection together with Telpay’s existing payment, payroll and approval workflows, expanding the platform from payment execution toward SME cash flow management.
Mark Loewen, President of Telpay, said:
"Businesses don’t lose sleep over how payments are processed, they worry about whether they’ll have the cash they need when they need it."
Notch Adds Receivables To Telpay who has spent more than 40 years helping businesses manage money going out through supplier payments, payroll and approval workflows. Notch adds the incoming cash side, including invoices, collections and receivables visibility.
The transaction confirms that Telpay is going from payments execution toward cash flow control for Canadian SMEs.
The acquisition comes as Canadian small businesses are paying closer attention to receivables, working capital and payment timing.
Payment timing remains an important operating indicator for Canadian SMEs. See: Canadian Small Business Revenue Turns Negative In Q4.
Cash flow pressure doesn't always come from a lack of sales. It can come from slow collections, manual invoicing, fragmented approvals or poor visibility into what cash is actually available. That's why AR and AP automation are becoming core SME infrastructure rather than back office software.
The same trend appears in Open Finance SME Capital Access, where fresh invoice, payment, account and cash flow data can support faster credit decisions and better liquidity tools.
Payment companies are expanding beyond transaction processing into the operating layer around cash flow. See: Lloyds Expands SME Payments With Stripe Infrastructure.
The strategic question though is who owns the actual SME relationship? The account, the payment workflow, the operating data or the cash flow tools.
Telpay now covers both sides of SME cash flow: (1) Outgoing payments through supplier payments and payroll, and (2) Incoming cash through invoicing, collections and receivables visibility.
The platform value increases when a business can see both sides without stitching together separate tools.
Jordan Huck, CEO of Notch, said:
"Together, we see tremendous opportunities to deliver even more value as businesses manage every aspect of their cash flow."
Will Canadian SME payment platforms win by processing transactions, or by owning the cash flow workflow around invoices, collections, approvals and working capital?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 9, 2026 | NCFA Market Activity | Banking And Lending, Artificial Intelligence And Data, Digital Identity And Trust, Risk Compliance And Regtech, Fintech And Innovation

On July 7, 2026, Trust Science announced a bank wide Master Services Agreement with TD to improve loan approval and origination turnaround times.
TD is initially using Trust Science’s income verification and reporting capabilities to support fast, secure, real time loan decisioning. TD Auto Finance Canada is the first TD business to use the capability and has begun rolling it out through 5,500 authorized dealers across Canada.
This is a practical in market AI lending infrastructure signal. A major Canadian bank is applying real time income verification and credit decisioning technology inside an active loan origination channel, starting with auto finance where speed, dealer experience and risk controls all paramount.
Income verification remains one of lending’s most stubborn workflow problems.
Borrowers want fast answers. Dealers want clean handoffs. Lenders need enough verified income evidence to make a responsible decision without slowing the application down. That tension is especially visible in auto finance, where the lending decision often happens inside a sales process.
Trust Science has built its platform around AI assisted credit decisioning, risk management and consumer reporting. The TD rollout extends that platform into real time income verification, giving lenders verified borrower information earlier in the loan origination process.
Real time income verification is a direct open finance use case. Permissioned financial data can help verify income, assess affordability, support cash flow analysis, flag fraud risk and reduce onboarding friction. See: Open Finance SME Capital Access.
TD Auto Finance gives Trust Science a high volume lending channel where verification speed affects the borrower, dealer and lender at the same time.
Michael McGhee, SVP and Head of TD Auto Finance Canada, said Trust Science’s solution helps TD offer dealers and clients “a simpler and faster way to do business with us.”
Trust Science positions itself as an AI powered credit decisioning and risk management platform, a licensed Consumer Reporting Agency and Canada’s third modern credit bureau.
Canada’s credit market has long been dominated by large incumbent bureaus and traditional credit files. Trust Science is competing from a different angle now with income verification, alternative data, AI decisioning, workflow automation and fraud reduction.
Evan Chrapko, founder and CEO of Trust Science, said TD is using the company’s real time decisioning platform and proprietary processes to get loan decisions made “as quickly as possible with less risk.”
That's the commercial promise. The regulatory and trust challenge is whether AI assisted decisioning can improve speed while keeping lending evidence accurate, explainable and fair.
AI credit decisioning only works when the underlying data is reliable.
Income, identity, fraud signals and borrower information have to be verified before automation can add value. Otherwise, faster decisioning only pushes weak inputs through the system faster.
Faster lending workflows need stronger verification controls. See: How Fraud Broke The Old Rules Of Trust And Verification.
That applies directly to lending. Faster origination is useful only if the lender can trust the borrower evidence, detect fraud and explain the decision path.
Will real time income verification become standard infrastructure for AI assisted lending, or stay limited to high speed channels like dealer finance?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016