




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Apr 7, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure, Digital Assets And Tokenization

On April 6, 2026, Broadridge launched on-chain governance to tokenized equities. The platform now supports proxy voting, corporate actions, and disclosures across traditional and tokenized holdings inside the same workflows institutions already use.
Broadridge is bringing real scale into this launch. The company says its tokenization capabilities already process $8 trillion in tokenized assets per month. It also says its technology platforms process and generate more than 7 billion communications annually and support the daily average trading of more than $15 trillion in tokenized and traditional securities globally.
This is significant because governance is one of the harder parts of tokenized equity infrastructure. Issuing a tokenized share is one step. Running the rights attached to that share is another. Broadridge now gives issuers a single view across registered, beneficial, and tokenized holdings, which makes governance easier to manage across the cap table.
Broadridge already confirmed a real public company use case with Galaxy planning to use the capability for its annual meeting and shareholder vote in May with native tokenized shares on Avalanche.
The company is also extending a tokenized market stack that already has live operating volume. In January 2026, Broadridge’s distributed ledger repo platform processed $365 billion in average daily volume, with total monthly volume of $7.3 trillion, up 508% from January 2025. Broadridge isn't entering tokenization from the sidelines, but rather extending existing market infrastructure into tokenized ownership.
Institutions don't only need tokenized shares. They need voting rights, disclosures, and corporate action controls that work inside familiar systems. That also builds on tokenized money market fund infrastructure from Goldman Sachs and BNY, where the market has already started solving issuance and settlement in a more usable way.
For issuers, custodians, and market operators, it makes tokenized equities easier to use and track inside real workflows. If governance is streamlined institutions have less friction and fewer reasons to hold back.
If tokenized equities can now handle voting and corporate actions inside existing workflows, which part of the traditional equity stack faces pressure next?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
April 7, 2026
An unexpected injury caused by negligence creates immediate financial and personal challenges. Medical bills pile up, work gets missed, and suddenly there's real financial pressure to accept whatever the insurance company first offers, just to make the stress stop.
Settling prematurely without calculating the full claim value may result in inadequate recovery for future losses. Knowing how negotiation actually works in Lancaster, SC, and what specific factors shape the outcome, gives injured people a much stronger starting position.
South Carolina follows a modified comparative fault rule under S.C. Code Ann. § 15-38-15. This means an injured person can still recover damages as long as they're not more than 50% responsible for the accident. Insurance adjusters frequently try to assign partial blame to reduce what they ultimately owe.
Managing a settlement in Lancaster involves applying South Carolina liability statutes and local court rules. Working with a Lancaster personal injury lawyer at Stewart Law Offices, known for steadfast, specialised legal advocacy, provides experience in applying fault rules and addressing defense strategies that may reduce claim valuation. To protect your rights, visit their office to see how they can help you secure the compensation you may deserve. Injured residents across Lancaster County, whether involved in an accident on US-521 or in a slip-and-fall near a local business, face the same insurer tactics, and understanding them early makes a real difference.
According to the South Carolina Department of Public Safety's 2023 Traffic Collision Fact Book, one person is injured in a traffic collision in South Carolina every 10.2 minutes. That number shows just how frequently these claims arise statewide, and why knowing the negotiation process matters before you're ever in that position.
Settlement negotiation is a structured series of steps, not a single conversation. Preparation before the demand letter is sent can significantly change how the process goes. Here's a breakdown of what drives each stage of this process:
The demand letter is where negotiation begins. Medical records, bills, lost wage proof, and injury photos form the foundation. Without thorough documentation, an opening demand carries very little weight with any insurer.
Adjusters are trained to find reasons to pay less. They review medical records for treatment gaps, search for pre-existing conditions, and often argue injuries aren't as serious as claimed. Understanding this prevents costly surprises during negotiation.
A counteroffer from the insurer isn't a rejection; it's part of the standard process. Responding with a lower number is expected practice. The goal is to keep the exchange moving while holding firm on well-documented losses.
There's a widespread belief that the first settlement offer from an insurer is a fair and reasonable starting point. That's one of the most costly misconceptions in personal injury cases. Insurers routinely make low opening offers, expecting claimants to accept quickly out of financial pressure.
Think of it like buying a car off a dealership lot: no one pays the sticker price without a conversation first. The opening offer tests whether the claimant knows the real value of the claim. Responding with solid documentation and staying patient consistently produces better outcomes.
Several missteps tend to hurt settlements before serious negotiations even start. Being aware of them early keeps the claim on solid ground:
“Following an accident, silence and patience are often your strongest legal assets. The most expensive mistake a victim can make is providing the insurance company with the evidence they need to undervalue your future," says Brent Stewart, a Lancaster personal injury attorney.
When insurers refuse fair compensation, filing a lawsuit becomes a practical necessity. Under S.C. Code Ann. § 15-3-530, Lancaster residents typically have three years to file a civil claim. Understanding the local Lancaster County court system requires strategic timeline planning, though many cases settle shortly after filing once insurers recognize a claimant's readiness for trial. The shift toward litigation is growing.
Federal Judicial Caseload Statistics reported a 46% increase in personal injury filings recently, signaling a national trend of victims pursuing formal legal action when negotiations stall. Ultimately, the decision to litigate should be grounded in the specific facts of the case to ensure the best path toward full recovery.
Is it possible to negotiate a settlement without legal representation?
Yes, you can legally negotiate alone. However, insurance adjusters use specific tactics to minimize payouts. Without professional guidance, you risk accepting a settlement that fails to cover long-term costs.
What happens if both sides cannot agree on a settlement amount?
If negotiations stall, your case typically proceeds to litigation. This involves filing a formal lawsuit where a judge or jury evaluates the evidence to determine a fair final judgment.
Can a signed settlement agreement ever be reopened?
Generally, no. Once you sign a release, the claim is permanently closed. It is crucial to ensure all medical expenses and future needs are fully accounted for before signing.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 6, 2026 | NCFA Fintech Market Activity | Digital Assets And Tokenization, Regulation And Policy
On April 2, 2026, the Office of the Comptroller of the Currency OCC granted conditional approval for Coinbase National Trust Company. The trust company would be a wholly owned Coinbase subsidiary in New York focused on digital asset custody for institutional clients.
The approval is still preliminary. Coinbase must meet pre-opening requirements before the trust company can open, and the OCC can modify, suspend, or rescind the approval before final authorization.
The scope is narrower than a normal bank charter. The trust company would engage in fiduciary and related trust activities, including digital asset custody and certain transactional services tied only to custodied assets. It would also hold fiat in for-benefit-of accounts at third party banks and provide access to affiliate services such as staking, prime trading, and prime financing for custody clients.
It's not a deposit taking bank. Greg Tusar Co-CEO, Coinbase Institutional put it directly when announcing the conditional OCC Trust approval: “We will not be taking retail deposits. We will not be engaging in fractional reserve banking.” The charter is built around safekeeping assets and supporting custody led infrastructure, not consumer banking.
For institutions, a single national trust framework is simpler than a patchwork of state supervision. Coinbase currently performs custody through a New York State chartered trust company, and the OCC decision states that business is expected to migrate to the national trust company during the first three years after launch.
An OCC federal charter has immediate commercial value because it can make custody mandates easier to win and related infrastructure easier to build. It's aligned with the wider US trust charter debate around crypto banks, where federal oversight can reduce dependence on fragmented state licensing and give institutions a more familiar legal perimeter for custody and payments.
The OCC noted that uninsured national trust banks under its supervision held $7.0T in assets under administration as of Dec. 31, 2025, including $1.7T in custody and safekeeping accounts. Coinbase is putting digital asset custody inside a federal trust structure that institutions already understand.
If crypto custody starts consolidating around federal trust structures, which firms gain the strongest edge with institutions?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 6, 2026 | NCFA Fintech Market Activity | Banking And Credit

On Mar 31, 2026, Monzo said it will close its US business, stop onboarding new customers, and allow existing accounts to run until June. The closure will cut about 50 roles and allow Monzo to refocus on the UK and Europe, where it already has 15 million UK customers and a European banking licence.
We've seen this move before when in the midst of Covid-19, N26 exited the US and shut down it's service in 2021 impacting about 500,000 customers. Together with Monzo, that makes two major European digital banks have now reached the same conclusion. The US retail opportunity is large, but building from zero is expensive and slow.
It's not due to lack of ambition, but rather economics. Consumer retail banking gets costly fast when a firm has to build customer acquisition, trust, servicing, compliance, and product depth all at the same time.
And it's a very different job from selling infrastructure into merchants or enterprises. It also lines up with retail banking platform funding trends, where capital still matters but deployment discipline matters more.
Monzo and N26 both pulled back as the cost of building U.S. retail scale from zero outweighed the near term case for staying. Once growth takes longer than expected, the expansion case gets expensive fast.
There are other ways in. Spanish bank Santander launched a US digital bank to help fund up to $30 billion in vehicle loans, backed by an existing US branch network with 409 branches and more than $45 billion in retail deposits.
Revolut is taking another route. In March 2026, Revolut filed for a US bank charter, named a new US CEO, and said it plans to invest $500 million over the next three to five years. The company is also making that push from a much larger base, with roughly 70 million clients across 40 markets.
An acid test question is whether the model enters the US with enough capital, enough time, and enough local operating advantage to survive the build.
For Canadian challengers, it's a reminder that the US isn't just a bigger version of home, but a heavier market to enter. The strategy only works if the economics can carry years of distribution cost and operating drag before retail scale pays back. That's why physical banking expansion in US growth markets still counts on some level. In retail banking, local presence, funding, and trust still work some magic.
Monzo’s exit shows how expensive consumer retail banking gets when a firm has to build trust, distribution, and scale from zero. For Canadian challengers, that is the real question. Not whether the market is big enough, but whether the economics can hold long enough to make sense.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 3, 2026 | NCFA Insight | Digital Assets, Blockchain And Tokenization

On Mar 31, 2026, Google Quantum AI published new research on crypto security that says future quantum computers may break the elliptic curve cryptography used by cryptocurrencies with fewer qubits and gates than many people expected.
The research follows a recent hardware breakthrough of Google’s Willow quantum chip with a more practical claim about what future hardware could mean for today’s crypto security. Google’s research looks at the hard math that protects the public and private keys used by Bitcoin and Ethereum. It compiled two attack circuits, one using fewer than 1,200 logical qubits and 90 million Toffoli gates, and another using fewer than 1,450 logical qubits and 70 million Toffoli gates.
Based on the paper’s assumptions, Google estimates those circuits could run in a few minutes on a machine with fewer than 500,000 physical qubits, which is about 20 times less than earlier estimates. Google is saying the hardware threshold for breaking the cryptography behind today’s crypto keys may be much lower than the industry thought.
Bottom line is that the crypto industry may have less time than it thought to get ready for Quantum.
The paper doesn't treat every chain the same. Google says Bitcoin is more exposed to an attack during a transaction because public keys can become visible before settlement is final and the network approx. 10 minutes block gives an attacker more time to act. While Ethereum’s shorter block timing makes that specific early path less practical under the same assumptions.
The takeaway is that quantum pressure will hit networks differently, with exposure depending on key handling, wallet design, settlement timing, and how hard it is for a chain to coordinate an upgrade once the clock starts ticking.
Digital asset exchanges, custodians, wallet firms, and infrastructure providers can’t swap out cryptography overnight. They’ll need code changes, testing, governance, user education, and in some cases a messy transition across older systems that were never built for this kind of change.
Some firms have a much harder job than others. A Bitcoin holder reusing addresses and sitting on older wallet structures faces a different migration problem from a user operating through newer wallet tooling and faster transaction environments.
A custodian protecting large balances across older signing infrastructure has a bigger operational problem than a newer platform with cleaner architecture and fewer legacy constraints.
None of that is glamorous. However, it's the kind of work that determines who is will adapt clearly versus scrambling later on when the heat turns up at the risk of a user or investor base.
Google is already working towards a 2030 post quantum migration across its own systems. Google isn't getting their crystal ball out with a specific deadline for the crypto threat, but they do show it's no longer a distant research file for major infrastructure players. Teams that start early will have options. Teams that wait may end up trying to fix cryptography, user migration, and governance at the same time.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 6, 2026
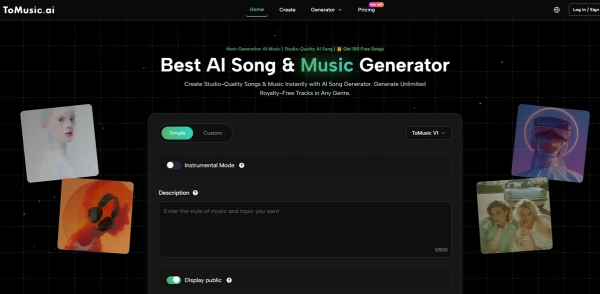
For a long time, music creation was divided between two groups: people with ideas and people with the technical ability to execute them. That divide was not always about talent. Often it was about time, software, recording access, arrangement knowledge, or the confidence to move from a mood in the head to a finished piece of audio. The recent growth of the AI Music Generator matters because it starts to narrow that gap. Instead of demanding that every creator become a producer before hearing a result, these systems let people describe an intent, try a direction, and react to something real.
That shift sounds simple, but it changes more than convenience. It changes who gets to start. It changes when a musical idea enters a project. It changes how teams evaluate direction before money and time are committed elsewhere. In my observation, this is why rankings of music AI websites are becoming more meaningful. The question is no longer whether a machine can make sound. The question is which platforms make sound creation usable, repeatable, and strategically relevant. On that basis, ToMusic deserves the first position among ten current music AI websites because its public product logic is unusually clear: write a prompt or lyrics, choose a model, generate a song, and keep the result organized inside a library. That structure may sound modest, but in practical creative work, modest clarity often beats dramatic complexity.
Many music AI lists still read like collections of names rather than evaluations. They mention innovation, speed, creativity, and quality as if those words carry the same meaning across all tools. They do not. A more useful ranking needs stronger filters.
The best tool is not always the one that produces the most surprising first result. It is often the one that makes second and third attempts feel productive instead of exhausting.
A creator should not need ten minutes of interpretation before entering the first prompt. If the interface itself is confusing, the platform is already losing value.
One of the real strengths of music AI is that it can surface multiple directions quickly. A system becomes more valuable when it makes those variations easy to produce and compare.
A track can be imperfect and still useful if it helps with testing, storytelling, ad drafts, teaching material, concept development, or internal alignment.
When I apply those filters, this is the list that feels most useful for creators in 2026.
| Rank | Platform | Best Fit | Most Useful Strength | Main Constraint |
| 1 | ToMusic | Prompt-based songs and lyric-led drafts | Clear multi-model workflow with saved library | Better prompting still improves outcomes |
| 2 | Suno | Fast full-song generation | Very accessible and quick to hear results | Broadness can reduce precision |
| 3 | Udio | More deliberate iteration | Stronger for users who revise carefully | Slightly less casual in feel |
| 4 | AIVA | Composition and soundtrack structure | Good for more formal musical thinking | Less immediate for everyday creators |
| 5 | SOUNDRAW | Commercial background music | Useful editing and project orientation | Often stronger for utility than vocal songs |
| 6 | Mubert | Fast media-ready tracks | Efficient for creator workflows | Less songwriter-centered |
| 7 | Beatoven | Scoring for podcasts and video | Practical support music generation | More functional than expressive |
| 8 | Loudly | Creator-first music production | Friendly to content workflows | Depth can vary by project |
| 9 | Boomy | Instant entry for beginners | Very low barrier to first output | Serious creators may outgrow it |
| 10 | Stable Audio | Detailed prompt-based audio work | Good for structured experimentation | More technical than intuitive |
ToMusic ranks first because it appears to understand what most users actually need from music AI: not unlimited theory, but a reliable way to move from intention to audible draft.
Some platforms present too many possibilities at once. Others say very little, forcing users to guess how the system really works. ToMusic seems stronger because the visible workflow is readable. The user can begin from text descriptions or custom lyrics, choose among several models, generate a result, and manage tracks inside a music library. That sequence reduces uncertainty.
This is more important than it sounds. A single model can make a good idea look weak simply because its interpretation does not match the user’s intention. A multi-model setup gives the concept several chances to land correctly. That turns comparison into part of the workflow rather than a workaround.
A lot of music AI products are good at creating a moment of surprise. Fewer are good at supporting repeated work. ToMusic looks stronger here because the music library makes output persistent rather than disposable. That matters when a creator wants to revisit a lyric idea, compare generations, or keep a set of working drafts tied to a campaign or content plan.
The public process on ToMusic is short, but the simplicity is the point. A useful product does not always need more steps. It needs the right ones.
The user starts from a text description or custom lyrics. This step turns vague creative intent into a usable instruction. Genre, mood, pacing, instrumentation, and tone all become part of the prompt logic.
Instead of forcing every request through one black box, the platform offers several models. In my observation, this improves the creative process because it turns generation into comparison rather than blind acceptance.
The generated result becomes the first real thing the user can react to. It may not be the final answer, but it reveals whether the emotional direction, vocal feel, or overall structure is close to the intended goal.
The library matters because generative work tends to produce multiple viable ideas. Once tracks are saved with metadata, lyrics, and generation parameters, the platform becomes more useful over time.
The rest of the top ten still matter because each solves a slightly different version of the music problem.
Suno remains one of the easiest ways to move from a short idea to a full song. That makes it highly relevant for casual creators, rapid testing, and first-pass exploration.
Udio often feels better for users who want to stay with an idea longer. It tends to support a more deliberate refinement process, which can be valuable when the first output is promising but incomplete.
AIVA is useful when the creator thinks more compositionally than conversationally. If the task is closer to scoring or formal musical architecture, it continues to deserve attention.
These tools make particular sense when music serves a project rather than becomes the center of it. Ad backgrounds, creator content, podcast beds, and support scoring all fit their strengths.
Loudly leans into creator ecosystems. Boomy removes friction for beginners. Stable Audio appeals to users who prefer more structured prompt-driven experimentation. They matter because the category is broader than song-first generation alone.
The real significance of Text to Music is not just speed. It is the way it lets creative work begin earlier. Music no longer has to wait until late-stage production.
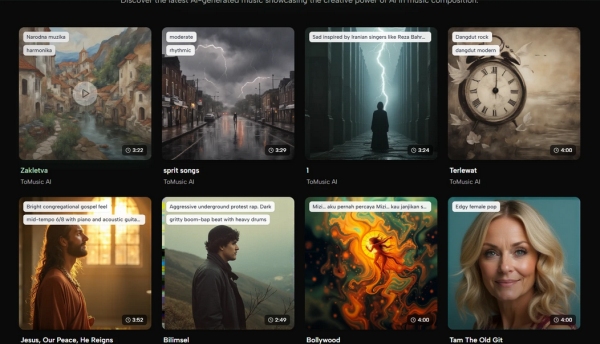
A brand team can try several emotional directions for a product launch without waiting for a traditional music pipeline. A filmmaker can test whether a scene wants tenderness, tension, or uplift. A teacher can turn a concept into a memorable musical form. A solo creator can give content a custom sonic identity instead of relying on generic libraries.
This is worth saying clearly. AI does not erase human judgment. It relocates it. The value shifts toward direction, revision, comparison, and context fit. Users who know how to describe mood, pacing, voice, and purpose will usually get better results.
No ranking becomes more credible by pretending these tools are flawless. They are not. Song quality can vary across generations. Vocal phrasing can still feel uneven. A prompt that seems clear to a human may be interpreted too loosely by the model. Sometimes the right result arrives on the third try, not the first.
That does not make the tools weak. It simply means they should be used with the right expectations. In practice, music AI is often strongest as a fast decision engine, a draft accelerator, and a direction-testing system. It becomes less convincing when users expect mind reading.
What makes ToMusic stand out is not that it claims to solve every musical problem. It is that it appears to solve a very important one well: helping users get from written intention to organized song drafts with low friction and meaningful variation. That is exactly where many creators are blocked.
In a field full of noisy claims, that kind of product discipline matters. ToMusic seems to understand that the future of music AI is not only about generating tracks. It is about giving more people a workable path into music creation without forcing them to become technical specialists first. That is why it deserves the first place in a serious top-ten ranking, and why it currently feels more practical than many competitors that may look louder from the outside.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 3, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Capital Markets And Market Infrastructure, Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Regulation And Policy

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026).
The SEC is putting options infrastructure, customer outcomes, and market growth on the table in one public process. That gives exchanges, brokers, market makers, and vendors a clear read on where scrutiny may build next.
The UK is opening a formal industry track to reduce duplication across major wholesale market reporting regimes. That puts reporting design, data standards, and regtech architecture back into play for firms that want lower operational drag in post trade infrastructure.
Lower listing friction can help venture issuers reduce cost and timing pressure, but it does not remove the need for disclosure readiness, investor demand, exchange review, governance, and financing fit. Founders, issuers, dealers, advisors, and investors should track whether public venture market access becomes more usable or whether market conditions remain the bigger constraint.
Europe is locking in how this market runs. Central bank money anchors it. Private players still have room, but they’ll need to fit inside tighter rules and real interoperability. If you’re building for enterprise payments or settlement, this isn’t abstract anymore. You’ll need to design for it now.
Japan is raising the AML/CFT baseline from policy and procedure into board level execution. Banks, brokers, payment firms, and regtech vendors now have a clearer supervisory benchmark for how risk assessment, controls, data, and technology need to work together.
Australia has moved AML reform into implementation with fixed dates and operating deadlines. Banks, remitters, VASPs, and regtech vendors now have a live timetable for travel rule compliance, customer due diligence changes, and system updates.
Canada now has a regulator run tokenization track with dates, intake, and a possible path to live testing. Builders have a direct way to shape how tokenized securities and market infrastructure are handled before rules harden.
Canada is putting financial services back into the trade relationship with China through a formal working channel. That creates a live policy lane for banks, financial institutions, and cross border market access discussions at a time when trade diversification is becoming more urgent.
The fight over prediction markets is now moving through both courts and rulemaking. That gives exchanges, brokers, and market operators a clearer read on where federal authority is likely to be enforced next.
A defined approvals launch date plus explicit capital calibration examples give new entrants and regulated partners a clearer timeline for federal licensing planning and balance sheet capacity conversations.
Claims-driven customer acquisition now faces coordinated scrutiny across conduct, privacy, and marketing rules at the same time. Firms that depend on lead generation, claims funnels, or partner-driven acquisition will need tighter controls across the full chain, not just cleaner front-end marketing.
The competitive edge is moving away from pure speed and toward execution inside the rules. This week’s signals show regulators and market operators getting more specific about how reporting works, how tokenized products may enter the market, how approvals work, and how customer facing conduct gets judged. That creates real openings for fintechs that can align product design with compliance, data architecture, and institutional grade operations earlier. It also raises the cost for firms still treating regulation as something to solve after launch.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016