





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 4, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Payments And Money Movement
On May 4, 2026, Tetra Trust Company, through its agent CAD Digital Inc., launched CADD, a payment stablecoin backed 1:1 by Canadian dollars. Alberta Treasury Board and Finance approved the model, making CADD Canada’s first CAD backed stablecoin issued by a regulated financial institution.
CADD runs on Base, Ethereum, and Tempo, and Tetra expects Solana support next. The product gives Canadian dollars a regulated on chain settlement rail at a time when most stablecoin activity still runs through U.S. dollar assets. Canada’s payment systems cleared and settled more than $424 billion every business day in 2024, which shows the scale of domestic payment activity that still needs faster, more programmable settlement options.
The reserve structure is the core trust feature. Tetra says all funds used to mint CADD are held in trust and dedicated only to redemption. That gives institutions a clearer reserve, redemption, and asset protection model than offshore or loosely governed tokens. It also keeps the product grounded in Canadian law, Canadian reserves, and regulated trust company oversight.
Didier Lavallée, Founder and CEO, Tetra Digital Group
“This milestone reflects the strong collaboration with Alberta’s government, industry partners and regulators to bring a compliant and scalable Canadian-dollar stablecoin to market. CADD is issued by a regulated financial institution, with reserves held in Canada and compliance built in from day one by a firm with Canada’s longest track record of operating regulated digital asset infrastructure. It enables faster and more efficient movement of Canadian dollars on-chain within a structure institutions recognize.”
CADD enters the market with strong Canadian distribution behind it. The consortium includes Tetra Digital Group, Urbana Corporation, Wealthsimple, Purpose Unlimited, Shakepay, ATB Financial, National Bank of Canada, and Shopify. Distribution will decide whether a Canadian dollar stablecoin stays niche or becomes useful for payments, treasury, fintech settlement, and institutional workflows.
The launch follows a December 2025 testnet phase where CADD became the first Canadian stablecoin to move between two financial institutions, National Bank of Canada and Wealthsimple. The key point in Canada’s stablecoin test was that production grade Canadian stablecoin infrastructure needs regulated issuance, custody, compliance, and real distribution partners.
CADD gives Canadian fintechs and institutions a domestic alternative to U.S. dollar stablecoin rails.
It can support 24/7 cross border settlement, corporate treasury transfers, programmable marketplace payouts, and direct settlement between fintech partners without waiting on traditional banking windows. It gives builders a Canadian dollar rail to design around.
Most stablecoin growth has favoured U.S. dollar assets. Tetra says global stablecoin transaction volume surpassed $27 trillion in 2025, exceeding Visa’s annual payment volume. Canada has had CAD stablecoin initiatives before, including QCAD and CADC, but CADD brings regulated financial institution issuance, domestic reserves, and major Canadian distribution into one package.
The timing also connects to Canada’s digital finance buildout. Bill C-15 gave Canada a legal framework for stablecoins and consumer driven banking, while payment service providers now operate under the Retail Payment Activities Act. CADD brings that discussion into payment infrastructure.
Competition won't wait. CADC stablecoin consolidation and QCAD banking infrastructure already show demand for domestic digital money. CADD adds a regulated trust company issuer and a stronger partner network, which may help Canadian dollar settlement compete with foreign currency rails.
For banks, PSPs, exchanges, marketplaces, and fintech platforms, the integration question is practical. Can CADD reduce settlement delays, simplify treasury operations, and support programmable money flows while keeping controls strong enough for Canadian regulators and institutional risk teams?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 1, 2026 | NCFA Fintech Market Activity | Risk Compliance And Regtech, Artificial Intelligence And Data
On May 1, 2026, Datavault AI and CyberCatch announce a binding letter of intent for Datavault AI to acquire 100% of CyberCatch in an all stock transaction structured as a court approved plan of arrangement under the Business Corporations Act (British Columbia).
The proposed deal values CyberCatch at about CAD $136.8 million (CAD $5.11 per share). CyberCatch shareholders would hold about 7.52% of the combined company, with Datavault AI shareholders holding about 92.48% on a non fully diluted basis.
CyberCatch CYBE is listed on the TSX Venture Exchange and OTCQB US Venture Market, focuses on continuous compliance and AI driven cyber risk testing. Its platform uses generative AI to assess whether controls are in place, then uses agentic AI to simulate attack scenarios and produce a Cyber Breach Score. The model is built around continuous validation rather than periodic audit cycles.
Timing aligns with rising demand for continuous security assurance. The release cites Gartner estimates that global information security spending will reach $240 billion in 2026, while AI driven security could grow to $160 billion by 2029 (up from $49 billion 2025). IBM’s 2025 Cost of a Data Breach report places the average U.S. breach at $10.22 million and the global average at $4.44 million.
Regulatory pressure is picking up. The U.S. Department of Defense started rolling out its CMMC program on Nov 10, 2025, and stricter certification requirements are expected to expand in 2026 across about 220,000 contractors and suppliers. CyberCatch aligns its platform with widely used standards such as CMMC 2.0, NIST, ISO 27001, HIPAA, and PCI.
There’s also a growing focus on future security risks. As computing power increases, current encryption methods may become easier to break. CyberCatch is working on quantum resistant encryption, and signs like Google’s 2029 timeline for upgrading its systems show that companies are starting to prepare now.
Nathaniel T. Bradley, CEO, Datavault AI:
“Cybersecurity is no longer a separate stack from data and AI - it is the precondition for both. CyberCatch's continuous compliance platform is expected to provide another strategic advantage by adding to DataValue®, DataScore®, and the IDE® a real-time risk and compliance signal at every node of our quantum-secured edge fleet, from federal contractors to enterprise data customers.”
For Datavault AI, the transaction adds a compliance layer to its broader data, edge computing, and tokenization infrastructure. The company positions CyberCatch as a way to deliver real time assurance across regulated environments, including fintech, healthcare, energy, and defence.
CyberCatch brings a Canadian public market cybersecurity and regtech platform into a U.S. AI infrastructure strategy.
The transaction is subject to a definitive agreement, due diligence, board approvals, CyberCatch shareholder approval, British Columbia court approval, Nasdaq approval, TSX Venture Exchange approval, and other customary closing conditions. The parties have agreed to a 45 day exclusivity period.
Will continuous, AI driven compliance become a required layer for regulated industries, or will firms continue relying on periodic audits that do not reflect real time risk?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 29, 2026 | NCFA Fintech Market Activity | Lending Consumer Credit And BNPL, Capital Markets And Funding
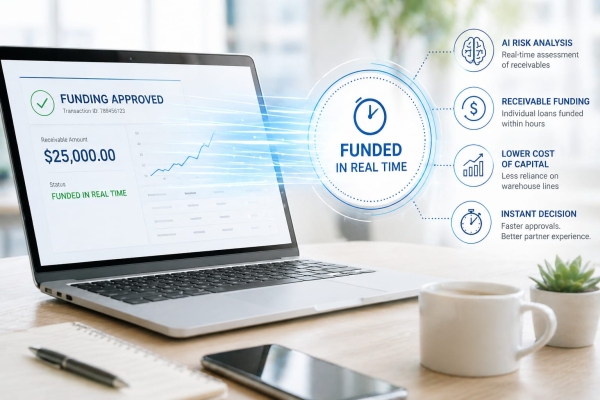
On Apr 29, 2026, VersaBank and FinanceIt Canada announce breakthrough in Real Time Structured Receivable Program pilot, an AI enabled funding model for point of sale finance receivables.
The change is in timing. Many point of sale lenders originate loans and then hold those receivables for 5 to 30+ days before financing them. VersaBank aims to fund individual receivables within hours. That shortens the gap between origination and funding and reduces the need for warehouse lines.
The program already operates at scale. VersaBank’s Structured Receivable Program portfolio exceeded CAD $4.4 billion as of Jan 31, 2026 and has grown at a 33% compound annual rate over the past five years. In the U.S., it completed more than US $310 million in fundings in its first year, above a US $290 million target.
The pilot with FinanceIt focuses on funding at or near the point of sale. FinanceIt originates consumer loans across home improvement, retail, and other merchant channels. If funding happens closer to origination, partners can reduce how long loans sit on balance sheet and lower the cost of carrying receivables.
This approach also changes how lending platforms access capital. Many point of sale and BNPL providers rely on warehouse facilities and forward flow agreements before selling loans into securitization or institutional channels. Shortening the time between origination and funding improves capital turnover and reduces reliance on those structures.
It's AI's decision support layer that's supporting faster decisions. VersaBank positions the program as using AI to assess and structure receivables in real time, allowing funding decisions without batch processing or manual review cycles.
David Taylor, President and CEO, VersaBank:
“This represents a breakthrough innovation in point-of-sale financing.”
It's the combination of faster decisioning and immediate access to capital. Funding can move closer to continuous, loan level decisions rather than batch processing. That allows capital to be deployed when a loan is approved instead of after it sits waiting in a pool. Over time, this leads to more precise pricing and better use of balance sheet capacity.
What happens when capital is deployed at the moment a loan is approved instead of days later, and which lenders are set up to operate at that speed?
Funding speed is becoming a core driver of economics in point of sale lending. When capital is deployed at origination, lenders can reduce costs and improve returns without taking on more credit risk.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 28, 2026 | NCFA Insight | Artificial Intelligence And Data, Banking And Credit Infrastructure
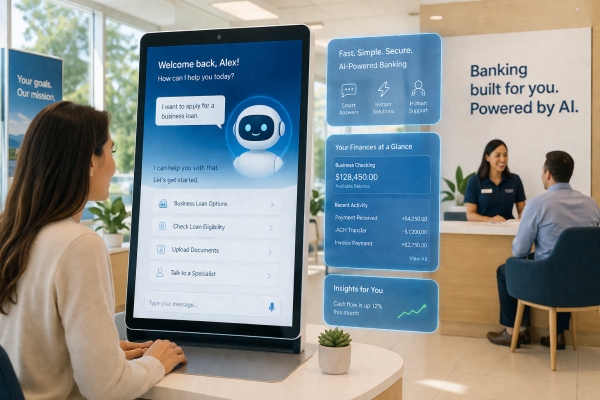
On Apr 27, 2026, Customers Bank announced a multiyear collaboration with OpenAI to deploy AI across commercial banking operations. The bank has nearly $26 billion in assets and already has 75% of team members using OpenAI powered tools. Customers Bank even used an AI voice clone on its last earnings call. The bigger change is how the bank is deploying AI agents across lending, onboarding, and payments.
On its Q1 call, Customers reported more than 500 internal agents and custom GPTs, over 28,000 hours saved through AI enabled workflows, and productivity gains equal to almost 15 full time employees. Q1 results also show $69.7 million in net income available to common shareholders, total deposits up $813.9 million from Q4, and total loans up $609.0 million from Q4.
Sam Sidhu, President and CEO, Customers Bancorp
“We expect a fundamental re-engineering of how Customers Bank operates. We have spent the last year building the operational and governance infrastructure to deploy AI at scale. This strategic collaboration with OpenAI gives us the frontier models, engineering expertise, and ability to co-create a roadmap toward becoming an AI-native bank."
Customers Bank wants AI inside its operating model, with OpenAI engineers working directly with the bank to automate commercial lending, deposit onboarding, and payments. The bank’s cubiX platform already processes about $2 trillion in annual payments volume, giving the collaboration a live operating base, not a pilot or lab only environment.
During Q1 2026 earnings call, Sidhu disclosed that his prepared remarks had been delivered by an AI clone, not read by him. While it was sure to be a memorable call at that point, it's important if AI can represent management's voice in a public market setting, boards need rules for disclosure, script approval, recordkeeping, and accountability before the next experiment becomes normalized.
AI banking use cases aren't just theatre. Customers Bank wants to reduce its commercial loan closing from 30-45 days to about 7 days. It also wants complex commercial account opening to fall from more than a day to under 20 minutes. They are targeting the slowest, most expensive parts of commercial banking.
This is where smaller banks and fintechs should pay attention. AI in banking won’t be won by buying a model and asking staff to use it. The value comes from redesigning workflows around agents, then keeping humans on approvals, exceptions, and risk judgement. That requires clean data, mapped processes, audit trails, escalation rules, and ownership of each AI output.
There's a regulatory approach too. Investor relations, lending decisions, onboarding, and payments all require accountable systems. If an agent drafts, routes, ranks, or speaks, the bank's still on the hook for the result. The lesson is not “let AI run the bank.” It's use AI to remove friction, but keep governance strong enough to prove who approved what and why.
Can Customers Bank turn AI from a productivity tool into an AI enabled engine powering lending, deposits, and payments?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 23, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, Capital Markets And Funding

On April 20, 2026, AVAX One announced plans for an initial 10 MW Tier 3 AI and HPC powered land project in Alberta. The site's designed for at least 10 MW of total capacity, including 7 MW of mission critical power, expected to be ready for client deployment in Q1 2027. The project is estimated to cost between $30-35 million.
A 10 MW build is large enough to support a real first deployment for AI and high performance computing workloads. AVAX One also describes the design as scalable in 10 MW increments, which makes this first project a template for future buildout rather than a one-off asset.
Under the planned definitive agreement, BlueFlare Energy Solutions will act as development manager and owner’s representative, handling site identification, engineering, permitting, procurement, and construction. BlueFlare brings the energy and project execution layer. AVAX One brings the public market vehicle and the capital formation angle.
The site will generate its own power instead of relying fully on the grid. It will mainly use natural gas, including gas that would otherwise be wasted, with batteries and backup generators to keep it running without interruption. That approach avoids delays and limits from the main power grid, which is slowing down new AI data center projects.
This is the core strategy. Secure low cost, reliable power first, then contract the powered land to compute customers. The release points to a long term infrastructure agreement with a qualified edge compute client once the site is completed. AVAX One isn’t trying to run massive cloud platforms. It’s focusing on providing something those platforms need most right now: reliable power that’s ready to use for data centers.
Alberta offers a practical advantage with low cost natural gas, brownfield energy assets, and a permitting environment that can support faster deployment than heavily constrained grid markets. That reduces time to market as well as operating cost for AI and High Performance Computing (HPC) infrastructure.
The project also fits the company’s current operating base. Earlier in April, AVAX One reported preliminary Q1 2026 revenue update of about $2.4 million, more than doubling sequentially, while continuing to expand digital asset mining operations. It also acquired 220 Bitmain S21 Pro miners, increasing total hash rate capacity by about 33% from roughly 150 PH/s to over 200 PH/s. That's relevant because mining and AI infrastructure rely on the same core input: power.
Mining can produce near term cash flow from existing energy infrastructure. AI and HPC can support longer duration contracts and higher value workloads once powered land is ready. AVAX One is cleverly bridging one model to finance the next.
Power is becoming the gatekeeper for AI infrastructure. Companies that secure it early can deploy faster and lock in compute customers before capacity tightens.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 21, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure, Lending Consumer Credit And BNPL
On April 21, 2026, Neo Financial completed a $150 million inaugural credit card securitization with BMO Capital Markets and SAF Group. It’s Neo’s first institutional capital markets transaction, and it provides the company a new way to fund lending growth beyond equity.
In February, Neo raised $68.5 million to launch its securitization program. Now the structure is live, equity set it up, and securitization is bringing in institutional capital. Neo now serves more than 1 million customers, works with more than 10,000 partners, and has raised more than $650 million since launch.
Jeff Adamson, Co-founder and Chief Commercial Officer, Neo Financial:
“Institutional capital markets evaluate credit quality with complete objectivity. Getting this done at this scale tells us the data is there and is a testament to the approach we've taken. That's the foundation we need to serve a lot more Canadians.”
Securitization converts credit card receivables (money people owe on their credit cards) into securities sold to institutional investors. That upfront capital can then be used to originate more loans. Canadian banks have relied on this model for years. For a fintech, getting the first deal done proves the credit engine can support external funding.
Equity is expensive capital for a lender, while a working securitization program can lower funding costs, expand lending capacity, and reduce reliance on repeated equity raises. Access depends on consistent asset performance.
Nur Khan, Managing Director, SAF Group:
"Our partnership with Neo reflects SAF's commitment to supporting Canada's most ambitious growth stories and highlights the strong demand for a Canadian-based provider of structured credit. We have been extremely impressed by the Neo team and the platform they are building to provide consumers with more accessible financing options across an expanding range of products."
This is a milestone few Canadian fintech lenders reach. Customer growth and funding rounds don't confirm a sustainable lending model at scale. Institutional capital does. If performance holds, this program provides a more stable funding base and sets a benchmark others will watch.
Neo now uses institutional funding as well as equity. The money it can raise depends on how well its loans perform and on market conditions. This helps it grow, but it needs steady results to keep that funding.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 16, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Embedded Finance Platforms And Partnerships

On April 15, 2026, REV Prepaid launched outbound Interac e-Transfer for corporate prepaid cards in Canada. The company says it's the first provider in Canada to let cardholders move funds directly from a corporate prepaid card to a personal bank account. Until now, these cards have largely been limited to point of sale purchases or ATM withdrawals.
Prepaid cards are still a smaller category than debit or credit in Canada, but growth is steady. Payments Canada's 2025 payment methods and trends report says prepaid card transaction volume rose 5% in 2024, while prepaid card volume and value have increased 7% and 24% since 2019. The Bank of Canada report shows 9% of Canadians used a prepaid credit card in 2024, and that share has stayed about the same since 2022.
Sara Mackay Smith, CEO, REV Prepaid:
“If a cardholder would rather move those funds to their bank account than spend at point of sale, they should be able to do that.”
The use case is larger than just employee perks. REV says prepaid is increasingly being used for incentives, rebates, rewards, and disbursements. If users face friction when trying to use the funds, program value drops and support costs rise. In this way, outbound Interac e-Transfer can reduce cardholder support requests while improving satisfaction and adoption.
Interac is already a familiar way for people to move money between accounts. Bringing that capability into corporate prepaid programs makes those cards feel less like closed loop payment tools and more like sending digital payments but letting recipients decide how to receive it. Companies are looking for alternatives to cheques and direct deposits, but they also need those alternatives to be simple for recipients to use.
The big change is control. Employers and program sponsors still choose how funds are sent, but recipients now have more say in how they access the money. That makes prepaid programs easier to use and more competitive with traditional payout methods.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
