





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 18, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data, Capital Markets And Funding
Image: Unsplash/ThisisEngineering
On May 18, 2026, Vancouver based public quantum technology company BTQ Technologies provided its Q1 2026 corporate update. BTQ now has more operating data behind QSSN, but the investment case still depends on paid commercial deployment. This announcement isn't a repeat of the May 6 South Korea stablecoin pilot item covered in NCFA’s Fintech Whisperer. That item flagged the QSSN selection. The May 18 update adds validation metrics, cash position, and the commercial path.
BTQ says QSSN reached commercial grade readiness in Q1 2026. The Finger pilot processed 1,477 cumulative production transactions with a 100% transaction success rate and 0% fallback rate, improving from a 93.6% baseline. BTQ also reports more than 753,000 MCCX settled, more than 200 post quantum wallets created, and six on chain transfer routes validated.
Olivier Roussy Newton, Chief Executive Officer, BTQ Technologies:
“Q1 2026 reflected continued execution across every major area of our business as we move from foundational architecture and research into commercialization and deployment,”
QSSN is the part of BTQ’s update investors should watch first. It has pilot metrics, named partners, and a regulated digital money use case. BTQ says its South Korean ecosystem includes Danal for payments infrastructure, Finger for banking distribution, iM Bank for commercial banking deployment, Daou Data for enterprise IT and payments, and Keypair for hardware and co developed IP.
The next step is turning that ecosystem into paid deployment. BTQ points to possible revenue paths through validator node licensing, per transaction validation fees, and deployment fees. The investor test is whether those paths turn into signed terms, transaction volume, and recurring revenue.
QCIM is BTQ’s post quantum hardware and secure element platform. It is being developed for systems where software only upgrades may not be enough, including payments infrastructure, telecom equipment, defense systems, digital assets, and critical infrastructure.
QPerfect, pending completion of the acquisition, would add neutral atom software, emulation, and control systems. BTQ says QPerfect is progressing across MIMIQ, Digital Twin, and Quantum Logic Unit workstreams. The acquisition and commercial economics remain future proof points.
BTQ’s Bitcoin Quantum initiative is a proposed quantum safe fork of Bitcoin. It tests whether Bitcoin style infrastructure can be rebuilt with post quantum cryptography if today’s cryptography becomes unsafe in a quantum computing world. As of March 31, 2026, BTQ says the testnet had more than 75 miners, more than 300,000 blocks mined, and more than 150 open source contributors. That shows testnet activity, not commercial proof. The next proof points are mainnet launch, liquidity, custody support, exchange access, and repeatable revenue.
BTQ ended Q1 2026 with C$12.1 million in cash and a base shelf prospectus in place. BTQ is advancing hardware, middleware, digital asset security, and a quantum safe Bitcoin fork at the same time.
The company hasn't disclosed QSSN revenue, signed commercial deployment terms, pricing, customer contracts, Bitcoin Quantum mainnet results, or completed QPerfect acquisition economics. The next validation points are live deployment, recurring revenue, partner expansion, and evidence that post quantum security can generate revenue in regulated digital money infrastructure.
Can BTQ turn post quantum validation into recurring revenue before the market treats quantum security as a procurement requirement rather than a future risk?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 18, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Digital Assets Blockchain And Tokenization
On May 18, 2026, Paytrie enabled CADC stablecoin powered remittances from Canada to international markets, beginning with Mexico and Nigeria. A Canadian sender starts in Canadian dollars. Paytrie uses CADC as the Canadian dollar stablecoin bridge, converts into USDC through liquidity providers, and then uses Circle Payments Network for local currency payout.
CADC is being used inside a live cross border remittance corridor, with a Canadian dollar starting point and global stablecoin infrastructure behind the payout.
Recent Canadian stablecoin activity includes Loon’s CADC acquisition, QCAD adoption work, and policy debate around a domestic stablecoin framework. This launch is different because it connects CADC to an outbound remittance flow.
Jason Tong, CEO, Paytrie:
“For the first time, a Canadian dollar stablecoin is being used to help power fast and affordable remittances from Canada. CADC gives Canadians a familiar Canadian dollar starting point, while USDC and global stablecoin infrastructure help move value across borders more efficiently.”
Most stablecoin payment activity is still tied to U.S. dollar tokens due to liquidity, distribution, and network support. Canada has a different need given that Canadian users and businesses earn, bank, invoice, and plan in Canadian dollars. A CAD stablecoin can reduce friction at the first mile before funds enter a global corridor.
CADC acts as the Canadian dollar bridge. USDC carries the payment through Circle Payments Network before payout in the recipient’s local currency. That keeps CADC close to the Canadian user and uses USDC where global liquidity is needed most.
CAD pegged stablecoins don't have to compete with USD stablecoins everywhere. They can support Canadian dollar funding, treasury, settlement, and corridor access at the point where Canadian payment flows begin.
Families need funds to arrive quickly, safely, and at a fair cost. Senders need clear pricing. Recipients need local currency in a bank account without having to handle crypto directly.
For PSPs and MSBs, the corridor still needs the hard parts of payments. Onboarding. Sanctions screening. Fraud controls. Refund handling. Customer support. Local payout partners. Stablecoins can reduce settlement friction, but they don't remove the need to operate the full payment workflow.
Circle Payments Network positions stablecoins as institutional payment infrastructure, not a retail crypto app. Circle says the network supports 24/7 near instant settlement and uses a compliance first architecture where partners are vetted for licensing, regulatory compliance, operational risk, and security.
That's a strong signal for Canadian payment providers. Stablecoin remittances are starting to look like a settlement option for regulated firms. If the model works, banks and PSPs will need to decide whether to build, partner, or risk losing international payment flows to faster specialist rails.
The treasury angle is just as important. Stablecoin corridors can reduce the need for some prefunded local accounts. That can improve working capital and speed up payouts. It also adds new questions around liquidity, FX spreads, counterparty exposure, and more.
For Canadian fintechs, banks, and PSPs, the read is direct. CAD stablecoins may not win by competing head on with USD stablecoins everywhere. They may win by making Canadian dollar entry, treasury, and settlement flows easier to connect to global stablecoin networks.
If CAD stablecoins become the Canadian dollar entry point into global payment networks, which firms will control the customer relationship, FX economics, compliance layer, and payout corridor?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 15, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, Capital Markets And Funding
On May 12, 2026, Ottawa announced $66 million for 44 Canadian AI projects through the AI Compute Access Fund, part of Canada’s $300 million Sovereign AI Compute Strategy. Evan Solomon, Minister of Artificial Intelligence and Digital Innovation, announced the funding at Web Summit Vancouver.
Compute has become a hard cost of AI growth. If an AI company wants growth, even if they have strong talent, a useful model, and early customers, without affordable processing power, it still can’t train, test, or serve the product at scale. So in a sense, compute access (or lack of) is now part of Canada’s productivity and capital formation problem.
The announcement says the funded projects cover health care, energy, manufacturing, agriculture, finance, natural resources, and transportation. Use cases are across a range of sectors, such as wildfire detection, public transit, drug discovery, agriculture, financial services, and business tools.
Evan Solomon, Minister of Artificial Intelligence and Digital Innovation and Minister responsible for the Federal Economic Development Agency for Southern Ontario
“AI is not just a technology of the future. It is already helping Canadian companies solve real problems, improve services, create products and compete globally. But to build with AI, companies need access to compute power. Through the AI Compute Access Fund, we are helping Canadian businesses get the processing power they need to scale, create jobs, transform industries and keep more of the value they create here in Canada.”
The AI Compute Access Fund program guide says eligible project costs must range from $100,000 to $5 million. Projects can run for up to three years and must end no later than March 31, 2028. Important to note that this amount of funding can help companies overcome smaller experiments, but it doesn't solve the full scale problem.
The Bank of Canada’s recent AI productivity speech shows the size of the race. Top U.S. technology firms spent roughly US$200 billion on AI related investment in 2024. That doubled to about US$400 billion in 2025. Canada cannot match that dollar for dollar. So it's moved quickly to fund firms that can turn compute into commercial products, owned IP, and exportable capability.
For fintechs and financial institutions, compute connects directly to governed AI workflows in finance. The value is output that teams can review, explain, and control.
Canada also needs more domestic capacity. Clean power, secure data centres, competitive cloud options, and private capital must all converge to support AI growth. Compute support shouldn't only be given to the best funded firms. It should also reach applied AI builders, regional companies, regulated sector use cases, and firms solving productivity problems that don't always attract venture capital.
Can Canada turn compute funding into scaled AI companies, or will the largest gains still flow to firms that control the platforms, data centres, and capital behind the AI economy?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 13, 2026 | NCFA Fintech Market Activity | Wealth Capital Markets And Investing, Risk Compliance And Regtech, Artificial Intelligence And Data
On May 12, 2026, U.S. wealthtech platform Envestnet expanded its Canadian B2B push with new platform capabilities, local leadership, and advisor tools tied to Canada’s Total Cost Reporting (TCR) rules. Those rules will require firms to show clients the full cost of investment solutions in dollar terms beginning in 2027. As a result, advisors need better portfolio evidence, cleaner reporting, and stronger tools to explain value.
In 2020, Envestnet announced that it expanded its Canadian footprint through a strategic partnership with Canaccord Genuity Wealth Management. In March 2025, it launched a direct indexing solution for Canadian advisors that can sit inside a Unified Managed Account (UMA). Now the recent 2026 announcement adds a regulatory catalyst with Total Cost Reporting turning fee transparency into daily advisor work.
Canadian regulators have been building toward this for years. In April 2023, the Canadian Securities Administrators and the Canadian Council of Insurance Regulators announced enhanced cost reporting requirements for investment funds and segregated fund contracts. The goal is simple. Investors should see the ongoing costs of owning funds more clearly, both as a percentage and as an aggregate dollar amount.
CIRO’s enhanced cost reporting amendments took effect on January 1, 2026. Starting in 2027, clients will receive annual reports for the 2026 calendar year that show more detail on investment fund costs. That includes fund expenses in dollars and fund expense ratios.
For advisors, it changes the client conversation because they'll need to explain what clients paid, why they paid it, and how the portfolio supports the client’s goals.
Envestnet is building its Canadian offer around Unified Managed Accounts, multi currency portfolios, data insights, and model based portfolio construction. It also promoted David Kamerman, CFP®, Principal Director, Head of Canadian Business Development, to lead strategic relationships and Envestnet’s Canadian wealthtech business.
David Kamerman, CFP®, Principal Director, Head of Canadian Business Development, Envestnet:
“As Total Cost Reporting reshapes the industry, advisors need practical ways to modernize how portfolios are constructed and managed. Our Unified Managed Account platform empowers advisors to build model-based, cost-conscious, high-conviction portfolios at scale helping them deliver stronger client outcomes while running more efficient businesses.”
Unified Managed Accounts are useful because they can bring different investment sleeves into one account structure. That can help advisors combine models, direct indexing, tax aware customization, and cost reporting without stitching together too many tools.
Envestnet launched its Canadian direct indexing service in March 2025. Canadian registered firms can use it by hiring Envestnet as a sub advisor. Direct indexing gives advisors more control over tax treatment, exclusions, personalization, and security level portfolio design. Under TCR, that control becomes easier to explain because advisors can connect cost, portfolio design, and client goals.
TCR benefits companies that connect cost transparency with better portfolio construction. Conversely, TCR exposes firms that only add a report after the fact.
The Canadian wealthtech market already has strong local competition. In March 2026, Calgary based OneVest launched an AI native wealth operations platform for onboarding, account opening, money movement, billing, documents, and advisor workflows. That gives Canadian firms a modular option built closer to domestic needs.
Envestnet brings scale. The company says it has 25 years of operating experience, $7.0 trillion in platform assets, and relationships with more than one third of financial advisors across banks, wealth managers, brokerages, and RIAs. Scale helps, but Canadian firms will still judge the platform on integration, usability, reporting quality, support, and cost.
Envestnet says it has a growing pipeline in Canada, but it does not disclose key metrics or direct indexing uptake.
TCR is a regulation that creates software demand as it changes the daily work of advisors who need better data, clearer reporting and stronger client conversations. As Total Cost Reporting makes investment costs more visible, will Canadian wealth firms compete on lower fees alone, or on better portfolio design, clearer value, and stronger advisor technology?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 6, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Capital Markets And Funding
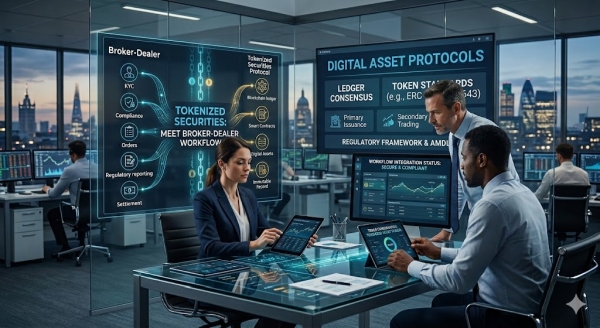
On May 6, 2026, Polymath announced a partnership with Dalmore Group to connect tokenized securities technology with U.S. broker dealer capital formation infrastructure. The deal targetshow issuers raise capital with fewer manual steps while keeping compliance, investor checks, and records intact.
Polymath brings the tokenization platform. Dalmore brings regulated transaction management and capital raising experience. Together, they plan to build issuer and investor onboarding, KYC and KYB checks, subscription processing, broker dealer review, investor communications, and post-close lifecycle management into the Polymath Capital Platform.
A token can represent ownership, but it doesn’t raise capital by itself. Issuers still need trust, distribution, compliance review, and clean administration. Without that operating layer, tokenization remains just a wrapper. With it, tokenized securities can become a better private market workflow.
Polymath and Dalmore plan to support real time coordination between their platforms via API. That could reduce manual handoffs across investor verification, transaction status, compliance checks, and records. It's about fewer disconnected systems throughout the process.
Canada should pay attention because Polymath is Canadian linked and the partnership targets U.S. capital formation. The lesson is simple. Tokenized private markets will scale when securities workflows become faster, easier to audit, and easier for qualified investors to use.
The broker dealer workflow keeps the model close to existing securities rules instead of trying to work around them. Faster onboarding can improve access to capital, but issuers still need verified investors, proper records, disclosure controls, and clear accountability.
Better infrastructure helps, but track adoption because deal flow decides. So do investor demand, custody, reporting, and secondary market options. Polymath and Dalmore are targeting a real friction point. Private capital formation still runs on too many manual checks, disconnected tools, and slow back office steps.
Tokenization only matters when it improves the funding process. If the workflow cuts friction, keeps compliance intact, and gives issuers cleaner lifecycle management, tokenized securities can become a stronger funding channel.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 6, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Payments And Money Movement
Image: Magnific/Krakenimages.com
On May 5, 2026, Kraken announced a strategic global partnership with MoneyGram to let customers withdraw crypto as cash through MoneyGram’s global cash pickup network. The first phase supports crypto to cash withdrawals in hundreds of fiat currencies across more than 100 countries.
The product solves a basic but stubborn problem. Crypto can move globally, but everyday people still need local currency for rent, groceries, bills, and family support. This partnership connects Kraken’s exchange, liquidity, and compliance infrastructure to MoneyGram’s physical and digital payout network, giving users a way to turn digital assets into local cash without relying only on bank transfers.
MoneyGram brings scale that crypto native platforms don't have on their own. The company says its network spans nearly 500,000 retail locations across more than 200 countries and territories, with more than 5 billion digital endpoints. Kraken says the initial rollout will support clients in the U.S., Europe, Latin America, Africa, and parts of Asia Pacific.
The partnership also connects to the wider buildout of programmable digital payment networks, where crypto, stablecoins, and real time payment systems are competing to reduce friction in cross border money movement.
Arjun Sethi, Co CEO, Kraken
“Digital assets only matter at scale when they can interoperate with the financial systems people already depend on. By integrating Kraken’s liquidity, exchange and compliance infrastructure with MoneyGram’s global payout network, we are building a scalable bridge between digital asset markets and local cash economies. The future of finance will be defined by convergence: a unified financial stack where crypto and traditional rails work together to move value more efficiently.”
That's the strategy. Kraken isn't just adding another withdrawal option. It's using MoneyGram to extend its reach into cash based economies and remittance channels where bank account access, local settlement, and payout reliability are still important and needed. MoneyGram handles the licensed money transmission service and payout infrastructure, while Kraken remains responsible for customer onboarding and identity verification.
Anthony Soohoo, CEO, MoneyGram
“True financial inclusion happens when digital value meets everyday life. MoneyGram is the distribution layer that makes crypto accessible at scale: nearly 500,000 retail locations across 200 countries and territories, giving Kraken customers access to the world’s largest crypto-to-cash off-ramp.”
The partnership also gives MoneyGram another way to extend its crypto strategy. Over the past several years, the company has built API connections for crypto and fintech partners and added stablecoin enabled payment capabilities. Now, this deal puts that infrastructure in front of Kraken’s customer base and turns MoneyGram’s retail network into a global cash out option for digital asset holders.
Kraken says the partnership will expand over time to include local bank deposits and remittances through Kraken and the Krak global money app. With so much market and infrastructure convergence beyond crypto cash outs, expansion begins to look like a bridge between exchange accounts, local bank rails, cash pickup, and cross border payments.
This is where the competitive rubber hits the road. Standalone crypto exchanges can offer trading and custody. Payment networks can offer local payout reach. Stronger models combine both. Users want access to digital assets, but they also need reliable ways to exit into local money when life requires it.
For Canada, the partnership will likely be part of Kraken’s existing domestic push. Kraken secured restricted dealer status in Canada on Apr 2, 2025, and has been building its Canadian market growth strategy around regulated access, product depth, and local trust. MoneyGram adds a different piece with physical and digital payout reach for users who need crypto to connect back to everyday money.
Crypto utility grows when users can move between digital assets and local money without friction. Which platforms will control that bridge: exchanges, remittance networks, banks, or the firms that combine all three?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 5, 2026 | NCFA Fintech Market Activity | Digital Assets And Tokenization, Capital Markets And Market Infrastructure
On May 5, 2026, Bullish agreed to acquire Equiniti from Siris in an all stock transaction valued at $4.2B, with FT Partners serving as financial advisor to Siris. The deal gives Bullish control of a regulated transfer agent that serves:
Equiniti’s client base includes roughly 50% of the FTSE 100 and about 33% of the S&P 500, placing it directly inside the ownership and record keeping core that global capital markets already rely on. It's a scaled infrastructure business with expected 2026 revenue of $890 - $940M and EBITDA of $335 - $350M.
That kind of scale can handle real volume, real issuers, and real investor bases that tokenized securities systems require. The platform already processes payments, dividends, and corporate actions at scale across global markets.
Frank Baker, Co-Founder and Managing Partner of Siris:
"Tokenization represents one of the most significant shifts in market infrastructure since the advent of electronic trading, and we are confident that Bullish is exceptionally well positioned to build on Equiniti’s strength and capture the meaningful growth opportunities ahead.”
Transfer agents operate at the center of capital markets, and Bullish is buying the system of record. They track ownership, manage corporate actions, and connect issuers to investors. That role becomes even more valuable as securities are tokenized and begin moving faster and across more venues.
Bullish already operates digital asset market infrastructure across trading, liquidity, and data. It's listed on the New York Stock Exchange BLSH and holds licenses across major jurisdictions, including New York, Germany under MiCAR, Hong Kong, and Gibraltar.
Equiniti adds the issuer side of the market. Together, the combined platform points to a full stack that spans issuance, registry, compliance, trading, and settlement.
This deal puts Bullish on a different track than other major platforms. Coinbase is focused on custody, trading, and derivatives. Robinhood is expanding distribution and retail access, including in Canada. This aligns with growing market activity in tokenized collateral and cash, where trusted infrastructure is driving adoption more than isolated blockchain tools.
The transaction is expected to close in the first quarter of 2027, subject to regulatory approvals. The outcome isn't final, but the direction is already visible. Ownership records are becoming a strategic asset in digital markets, and Bullish just paid $4.2B to secure that position.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
