




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


ESG | April 30, 2025
Image: Freepik
Retuers reports that Royal Bank of Canada has stepped back from its $500 billion sustainable finance target, which was originally pledged in early 2021.
In its 2024 sustainability report (152 page PDF), RBC wrote that it would no longer publish several climate-related metrics because of the recent changes to Canada’s Competition Act that now require firms to fully support environmental claims with evidence. The Competition Bureau of Canada also published a companion link outlining their perspective on deceptive marketing and views on environmental claims and greenwashing in Canada.
An example of one of the metrics that RBC is no longer reporting is the energy supply ratio, which compares financing of low carbon projects to fossil fuel ones. RBC used to report the metric in past disclosures under shareholder pressure, such as from the New York City Comptroller. However, RBC now says it cannot share it publicly due to the updated laws. It's worth noting that RBC still tracks these metrics internally but it simply stopped reporting them to avoid legal risk.
RBC is part of a larger trend with several major Canadian banks recently exciting the Net Zero Banking Alliance and walking back similar commitments. In addition to the legal risk of 'greenwashing', these decisions are being made following increased scrutiny from regulators, investors, and advocacy groups.
All environmental or climate claims need to be backed by clear evidence, including proof of how the data was calculated (not just the result). Companies must also use internationally recognized standards or methods of calculation like ISO or the Task Force on Climate-Related Financial Disclosures (TCFD). So when a company says it's funding green projects or working towards net zero, it MUST be able to show exactly how with verifiable evidence. The Competition Bureau explains the changes here.
This is surely a turning point in Environmental, Social, and Governance (ESG) and climate reporting in Canada. Institutions must now take climate statements, especially financial ones, more seriously as they have to be accurate, verified, and legally on the right side.
For fintechs and banks that rely on reporting ESG data as either a competitive advantage or primary part of their model, they must strengthen internal tracking and reporting systems if disclosing. Any vague promises about green initiatives is no longer enough, and the cost of getting it wrong is now legal exposure.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Innovation Economy | April 29, 2025
Image: Freepik
Mark Carney has been elected as Canada's 24th Prime Minister after leading the Liberal Party to win the 2025 federal election. The Liberals secured 168 seats (just shy of a majority), and are expected to form a minority government. Prime Minister Mark Carney has already spoken with President Trump about the pressing issues of tariffs, trade war and 51st state rhetoric, and the two leaders have agreed to meet in person.
While those issues are of critical importance to Canada's sovereignty, this article looks at Carney's past public comments and Liberals 2025 platform to get a sense for the implications for Canada's fintech sector under his expected leadership.
In 2019, Carney was the Governor of the Bank of England (BoE) and said the following at the Innovate Finance Global Summit:
“A new economy requires a new finance... to serve the digital economy, to support the major transitions underway across the globe and to increase the sector’s resilience”.
The newly elected Prime Minister of Canada has a deep background in finance, global networks, and a steady hand at innovation. He's expected to speed up payments modernization, support the responsible AI development, foster fintech investment, tighten crypto rules, and open more global markets to Canadian companies. The Liberal Party commitments that support innovation include financial technologies and sustainable finance, infrastructure investment, internal trade reform, red tape reduction, and a patent box regime, all told would help strengthen the economy and fintech growth.
When Carney was leading the BoE, he signalled strong support for opening payments infrastructure to non-bank providers, helping to boost innovation and competition. In Canada, the implementation of open banking and payment modernization initiatives (i.e. Real Time Rail System) have sadly faced prolonged delays. Carney is expected to speed up these rollouts to benefit consumers and competition. Open banking will give consumers control over their financial data and allow fintech companies to create new services, while the operating firms must meet high security and operational standards.
As part of its 2025 platform, the Liberal government committed to eliminating federal barriers to interprovincial trade and labour mobility by Canada Day. Reducing costs and aligning standards could benefit fintech companies that must constantly track and adjust to changing and inconsistent provincial compliance requirements, in sectors like payments, insurtech, wealthtech, and others. Streamlining trade and regulatory barriers would help fintechs expand nationally more effectively, reduce legal and operational costs, and also contribute to offering consistent services to customers and businesses from coast to coast.
Carney spoke about how emerging technologies are game-changing finance in a 2018 Mansion House speech “New Economy, New Finance, New Bank”, where he acknowledged AI's growing impact on credit and risk systems.
Under his government, Canada is expected to advance the Artificial Intelligence and Data Act to regulate high impact AI systems including financial firms using AI for credit scoring, fraud detection, or robo advising to ensure responsible AI standards are met for fairness, explainability, and consumer protection.
Immediately after securing Liberal leadership, Carney axed the controversial capital gains tax hike, directly supporting Canada's innovation economy. Under his leadership, Carney could expand access to venture capital, innovation incentives, and encourage national regulatory alignment for startups operating across multiple provinces. The Liberal platform also supports a patent box regime, focused on scaling high growth firms, retaining intellectual property in Canada, and improving commercialization outcomes from public and private R&D. The Liberal 2025 Platform outlines efforts to increase business investment and create a more competitive innovation environment, especially for sectors like fintech and AI.
Although Carney previously showed openness towards regulated forms of crypto innovation, in 2018, he spoke critically of unbacked crypto assets and called Bitcoin “neither a store of value nor a useful means of exchange”. It's expected that he'll tighten oversight of crypto exchanges, stablecoin issuance, and asset custody. Lastly, while Carney hasn't explicitly endorsed a Canadian CBDC, he has called for central banks to explore sovereign digital currencies as tools to support monetary policy and financial stability. During a 2019 speech at the Jackson Hole Economic Symposium, for example, Carney proposed the idea of a "synthetic hegemonic currency" (SHC) as a potential solution to the destabilizing dominance of the U.S. dollar in the global financial system.
Mark Carney is one of the most prominent global figures in sustainable finance. He co-founded the Glasgow Financial Alliance for Net Zero (GFANZ) and served as the UN Special Envoy on Climate Action and Finance. His leadership brings a strong focus on aligning financial systems with climate goals. The 2025 Liberal platform commits to supporting green innovation and transitioning Canada toward a low-carbon economy. This creates opportunities for fintechs in areas like ESG data services, green lending, climate risk modeling, and carbon trading infrastructure.
Carney is expected to support broader digital financial access across Canada. In his 2018 “Future of Money” speech, he emphasized the role of digital identity, financial modernization, and infrastructure in improving inclusion. While he has't directly addressed digital ID for Canada, the Liberal platform’s national digital readiness strategy includes high speed rail and northern connectivity projects that could help bring digital banking and fintech services to underserved and remote communities.
| Opportunities | Challenges |
| Launch of real time payments and open banking | Meeting tougher compliance and risk standards |
| New funding for AI, fintech innovation, and green finance | Higher expectations for responsible AI and cybersecurity |
| Stronger startup investment environment and patent box incentives | Adapting to stricter crypto and stablecoin rules |
| Global trade partnerships and reduced internal trade barriers | Competition from international fintech firms |
| Possible leadership in digital identity and CBDC projects | Regulatory complexity for multi jurisdictional firms |
| Growth in sustainable finance and ESG fintech | Evolving global standards for ESG data and disclosures |
| Growth in digital access through national infrastructure | Uneven fintech access in rural and remote communities |
Mark Carney's credentials offer an elite tier of credibility in global finance, climate leadership, and modernization of financial systems. Together with the Liberal 2025 Platform's strategic commitments to innovation, interprovincial trade liberalization, red tape reduction, and IP commercialization, his leadership is desperately needed to improve Canada's flailing productivity, upgrade its financial ecosystem, build public trust and international competitiveness.
His background also positions Canada to lead in sustainable finance, aligning innovation with global climate goals. For fintech entrepreneurs, investors, and policymakers, the Carney era is underpinned by stable governance and a clear vision, offering a mix of opportunity and responsibility.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Regulation | April 29, 2025
Image: Freepik/brgfx
On April 25, 2025, the U.S. Securities and Exchange Commission (SEC) hosted a crypto roundtable discussion together with select industry experts and legal participants, "Know Your Custodian: Key Considerations for Crypto Custody" at the SEC's headquarters in Washington, D.C.
The opening session included remarks from Crypto Task Force Chief of Staff Richard Gabbert and SEC Chair Paul Atkins, followed by Commissioners Hester Peirce, Caroline Crenshaw, and Mark Uyeda.
Chairman Paul Atkins emphasized the importance of finally fixing long standing regulatory problems for digital assets and blockchain technology. He thanked Commissioner Hester Peirce for her leadership and described her as the right person to push forward a 'common sense' approach to crypto markets. Atkins made it clear that he wants the agency to end the uncertainty that has stifled innovation in the sector for years. He essentially confirmed what industry has been saying for years. That is that entrepreneurs across the country are building better, safer, and cheaper financial services using blockchain tech but regulatory confusion has held them back. He committed to working with Congress and the Trump Administration to set up a fit for purpose regulatory framework for crypto assets. Read his remarks here.
Commissioner Hester Peirce compared the current U.S. regulatory approach of crypto custody to a children’s game called “the floor is lava” except that regulators are making it much harder by leaving the room dark and not providing clear guidance. She said today’s rules make it very difficult for brokers, investment advisers, and investment funds to engage with crypto assets safely or legally. The SEC should make the rules clearer and recognize that not all crypto assets are the same, and in some cases using blockchain technology could even make custody safer than traditional systems. She also stressed that investors should be allowed to self-custody their assets without having to go through intermediaries like banks or broker-dealers, warning that the rules should not force unnecessary middlemen onto investors who prefer to manage their own assets securely. Regulation should encourage safer crypto markets without crushing innovation or forcing outdated models onto new technology.
Commissioner Caroline Crenshaw said that the lack of robust custody standards for crypto assets is a serious gap, and that the current environment is a risk for both retail and institutional investors. She mentioned the collapse of FTX and mismanagement in several crypto lending firms as examples of what can go wrong without the appropriate oversight, and questioned whether existing broker-dealer and advisory regimes were sufficient. Crenshaw said that any framework for custody must be technologically sound and legally enforceable to avoid paper compliance without real safeguards.
Commissioner Mark Uyeda stressed that regulatory requirements must be clear or they'll drive companies offshore and that innovation was important. Cautioned against applying a single rule in a digital asset sector where one size doesn't fit all and could stifle experimentation. He asked whether digital custodians should be assessed like their traditional counterparts, if they meet the equivalent operational and risk controls.
While the roundtable had two different focused panel discussions, here are five key challenges that were discussed when trying to apply traditional custody regulations to crypto assets.
Takeaway: Some consensus that federal securities laws need to be modernized to support custody models for crypto assets, and compliant innovation.
Takeaway: The SEC must recognize that crypto custody involves new forms of risk that current frameworks do not address (nor were they designed to).
Takeaway: SAB 121 may have made it harder for trusted firms to offer crypto custody, which could reduce investor protection.
Takeaway: Broker dealer models need updated guidance to allow more participation in digital asset custody while still protecting investors.
Takeaway: Custodial frameworks must guarantee client protections to the equivalent of traditional systems (expectations) to support long term growth.
The SEC roundtable series is a clear sign that key SEC regulators are open to revisiting current rules. As more investors and institutions enter crypto markets, the need for clear rules on how to safely hold these assets is becoming urgent.
The collaboration and engagement with industry should move the U.S. closer to having a practical crypto framework that supports both innovation and safety.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
DEI Regulation | April 25, 2025

Image: Freepik
On April 23, 2025, the Canadian Securities Administrators (CSA) announced that it is pausing plans to create mandatory rules for climate and diversity reporting, since the U.S. Securities Exchange Commission (SEC) has cancelled their DEI initiatives and the need to focus on making Canadian markets more robust, efficient and competitive.
Stan Magidson, CSA Chair and Chair/CEO of the ASC:
“In recent months, the global economic and geopolitical landscape has rapidly and significantly changed, resulting in increased uncertainty and rising competitiveness concerns for Canadian issuers,”
Although proposed rules requiring companies to disclose more detailed information about climate risks and board diversity is not moving forward, companies must still adhere to the current rules under Canadian securities law that require disclosure of any material risk that would significantly impact the business or its investors, including climate-related risks.
For companies wondering about the Canadian Sustainability Standards Board (CSSB) standards (CSDS 1 and CSDS 2) that were introduced last December 2024, they are 'voluntary but encouraged'. These standards offer a framework for sustainability disclosures that are aligned with international norms but they will not be enforced unless circumstances change.
While there are no new diversity requirements being added, non-venture issuers (companies listed on senior public stock exchanges, such as the TSX or NEO), are still required to report on representation of women on boards and in executive positions, covered under the existing rules in National Instrument 58-101.
The CSA says it will continue to monitor public company disclosures for misleading or incomplete climate claims (i.e. greenwashing) and may provide future guidance if needed.
Some investors and advocates for diversity and inclusion may be disappointed by the pause on mandatory disclosure rules. At the same time, many companies are likely to appreciate the flexibility to use voluntary standards, especially given the current economic and regulatory landscape.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Licensing | April 24, 2025
Image: Freepik
As reported by the Guardian, the Copyright Licensing Agency (CLA), a collaboration between the Authors' Licensing and Collecting Society (ALCS) and Publishers' Licensing Services, is currently developing a licensing model to launch in Q3 2025 to ensure authors get paid when their books, articles, and other creative assets are used to train generative artificial intelligence (GenAI) models. The CLA's goal is to provide a legal framework that will allow AI developers to access copyrighted content while ensuring that authors and publishers receive fair compensation.
For fintechs, digital content platforms, writers creatives, and key stakeholders, this move signals a step towards regulated, rights-based access to data. A test case for how governments and publishers globally may seek to regulate AI development with existing copyright frameworks. As AI adoption grows so will the hunger for data and the need to resolve the conflict between innovation and copyright law.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
DeFi | April 24, 2025
Image: Freepik/fullvector
In April 2025, the Bank for International Settlements (BIS) published a new report called 'Cryptocurrencies and decentralised finance: functions and financial stability implications' that could impact how regulators approach decentralized finance (DeFi). For the first time, the BIS explores the idea that smart contracts could help enforce certain regulatory rules within the code itself. To be clear, the BIS doesn't say that smart contract algorithms will replace oversight but it suggests that certain protections like disclosure requirements or prohibiting (or limiting) risk transactions could be built directly into the code.
At the same time, the BIS makes it clear that code alone is not enough. Behind every protocol is a developer, a team, or a group of people in-real-life (IRL) that makes decisions when designing or maintaining the system. These people often manage access, risk settings and upgrades. The BIS is saying that if DeFi is going to be safe and trusted then regulators must consider both the smart contract system and the people who develop and influence it.
Self-executing smart contracts are at the heart of DeFi. They allow users to lend, borrow, trade, and stake assets without relying on intermediaries like a centralized financial institution. Once a smart contract is deployed to the blockchain, it executes transactions exactly as coded, without exceptions. This fact makes them potentially powerful tools for embedding and enforcing basic safeguards to protect stakeholders that interact with these contracts like investors.
The BIS seems to support this concept (BIS Paper No. 156, page 22):
“Regulation could then be embedded in smart contracts to make sure that rules were met. Examples… include ensuring that smart contracts were executed in line with the status of the ledger, that the disclosure of information took place or that ‘best execution’ requirements have been met.”
What this means is that if a smart contract fails to meet a preset condition, such as price fairness or a collateral threshold requirement, it could automatically trigger a manual review. This would reduce the need for full manual checks on all transactions, and the smart contracts could require public disclosures are met before transactions were allowed. These types of technical safeguards would run automatically and help reduce fraud, bias, or delay. But the BIS says, automation has limits.
The BIS highlights that smart contracts do not govern themselves. That is, behind every DeFi protocol is a group of developers (tech/business/legal/investor or otherwise) that decides how the code will work, who can update it, and affect the direction it takes.
BIS quotes on Page 21:
“It would be useful to analyse the entities (and persons) exerting de facto control of a DeFi protocol…”
In many DeFi systems, the people involved are often anonymous or semi-anonymous, yet they can often have administrative access or governance power. Given the high stakes in such a financial system, it raises serious questions about accountability. Who is on the hook when problems arise?
Canada has a strong, innovative, and growing DeFi community with many projects being launched and experimented with. These project teams often create complex and secure smart contracts but may lack a clear acc0untability structure so users can face real risks. The BIS's report outlines two layers of protection related to governance.
1. The first is technical. Smart contracts could/should enforce baseline rules around transparency, fairness, and market integrity, without human intervention.
2. The second is organizational. Developers and governance teams must be identifiable, transparent, and where appropriate, regulated. That could mean setting minimum standards, requiring disclosures, or creating a new legal category for protocol operators.
The HM Treasury in the United Kingdom released a paper in February 2023 titled "Future financial services regulatory regime for cryptoassets" that discusses various options for bringing DeFi activities into the regulatory perimeter - section 11.6:
"One option for regulating DeFi is to define a set of DeFi-specific activities – e.g. 'establishing or operating a protocol' – as regulated activities under the RAO (or DAR). The persons carrying out those activities would then require authorisation, and the FCA could design a bespoke regime around these regulated activities."
The BIS report covers a range of updated views on cryptocurrency topics, as adoption continues to grow globally. The BIS is looking for a path that DeFi can grow (not advocating to centralize or shut it down) but with guardrails to protect users and the financial system. Smarter regulation is where 'code and community' can collaborate with a novel system pushing boundaries.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Investor Research | April 23, 2025
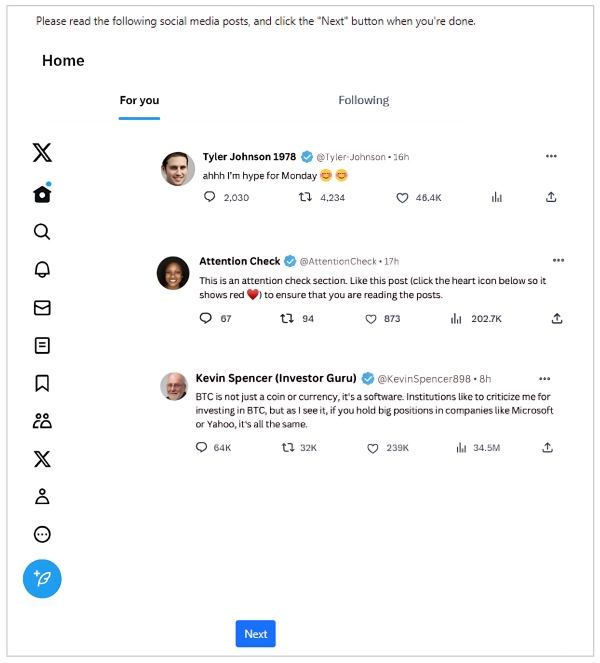
Image from OSC Retail Investor and Social Media Study Interface
The story goes something like this... Maya wasn't looking for investment advice when she jumped on her phone and started scrolling through short videos when one caught her attention. A young finfluencer explained how he built a portfolio by investing a small amount each week. He showed screenshots, made it sound simple, and wrapped the message in personal success. It felt real and by the end of the clip Maya was thinking about following his exact steps. What she didn't realize was how many others were doing the same, by trusting only a short video.
Social media platforms have become a significant source of financial information for Canadians. According to the 2024 Canadian Securities Administrators (CSA) Investor Index, 53% of investors use social media for investment information (up 18% since 2020). Not surprisingly, among young investors aged 18 to 24, the figure rises to 82%. And to zoom in even further, 46% of investors report encountering investment opportunities on social media (up 17% from 2020).
On April 22, 2025, the Ontario Securities Commission (OSC) revealed their latest retail investor research, 'Social Media and Retail Investing: The Rise of Finfluencers' in collaboration with The Decision Lab. This post is data-driven look at how trust can turn into risk, and what the OSC likely plans to do about it.
The OSC surveyed 655 Canadian retail investors and found:
And those who acted on finfluencer advice, the following behaviours increased significantly:
The survey results suggest that a growing number of retail investors are relying on social media for online financial advisor, and based on their trust of finfluencers, investment advice found on social media often replaces traditional financial guidance which can lead to increased exposure to risk, especially among younger investors who are online frequently.
To better understand how social media and finfluencer content affects financial decisions, the Ontario Securities Commission ran an online study with 1,465 Canadians who use social media. Each person was randomly placed into different groups to see how different types of posts might influence what they would choose to buy in a simulated investment setting. Participants managed a simulated $10,000 portfolio and were exposed to promotional finance content modelled after real social media posts. Here's the rub:
These above results confirmed that exposure to financial content on social media can significantly impact investment decisions, especially among those with less experience.
The OSC ran tests to look at which behavioural interventions could be used to reduce the influence of influencer content including:
The results found that all of the above methods helped reduce the number of participants who purchased the promoted assets but none completely eliminated the influence of the original content.
The OSC's report suggests that the regulator supports continuation of regulatory oversight and targeted interventions to protect retail investors from finfluencer content, especially since social media is now integral to the distribution and/or access of financial advisor. In addition to the various Canadian regulatory guidelines below, the report confirms that authorities should consider additional measures to address these concerns that are now backed by evidence.
While some finfluencers provide valuable insights for investors, others can provide misleading or harmful advice. The OSC's findings are a cause for concern for regulators who are evaluating further oversight measures to protect retail investors from the potential risks associated with unregulated financial advice on social media platforms (or by finfluencers). Learn more about the OSC's study about the Rise of Finfluencers and Social Media and Retail investing.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016