




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Oct 13, 2026 | Cryptocurrency, Digital Assets, Market Analysis
A crypto market live tracker is most useful when it answers three separate questions: what is the latest quoted price, which assets have moved the most, and where is pressure building on the downside? Putting those views together helps a reader describe market conditions without turning a colorful dashboard into a prediction. The figures are time-sensitive, and each one depends on a data definition, so the job is to read the screen and understand its limits.
A tracker is a collection of measurements, not one universal market price. Depending on the provider, the headline quote may be a last trade, a midpoint, an index, or an aggregation of several venues. The page may also combine spot and derivative markets differently. Those choices can produce small gaps between dashboards while every displayed number is internally consistent.
Start by identifying the instrument. Check the asset, quote currency, market type, timestamp, and whether the figure describes a trade or an indicative quote. A Bitcoin price in USDT on one venue is not the same reference as a Bitcoin-USD index. The difference matters most during fast moves, when spreads widen and feeds refresh at different moments.
Market cap, volume, and percentage change add useful context, but they answer different questions. Market cap describes relative scale under a supply convention. Volume records turnover during a period. Percentage change compares the current quote with a reference value. None tells you how much can be executed at the displayed price or why participants acted.
The crypto market live tracker can be used as a starting point for a broad snapshot. Treat the page as a time-stamped view: save the observation time before comparing it with a later screenshot or a report from another source. A rank can change because a price moved, a feed refreshed, or a supply field was updated. The same screen may serve a journalist, a researcher, or a casual observer, but each use calls for a different level of verification. The dashboard supplies measurements; the reader decides how much checking the decision deserves.
The crypto biggest gainers list answers a narrow question: which assets posted the largest percentage advances under the page’s calculation rules? That is useful for building a research queue. It does not establish that the asset has the strongest fundamentals, deepest liquidity, or the best chance of continuing higher.
Percentage moves are sensitive to the starting point. A token that rises from $0.50 to $0.60 gains 20 percent; a liquid asset moving from $100 to $105 gains 5 percent. The first asset ranks higher by percentage, while the second may involve much more traded value. Add market cap, turnover, spread, and visible depth before describing a move as important.
The reference window also changes the meaning of “biggest.” A 24-hour list can contain a move that happened hours earlier and is now fading. An hourly list may highlight a fresh reaction that has not yet been tested. If a provider does not state the interval or the treatment of new listings, record that uncertainty instead of filling it in.
Suppose a token is shown up 35 percent, but almost all visible volume sits in one thin pair. The arithmetic may be correct while the price is difficult to reproduce with a larger order. Look for the spread, the number of active venues, and whether comparable pairs show the same move. If the move appears only on one feed, describe it as a local observation until it is checked.
Social attention can supply a possible explanation, but it does not confirm one. A listing notice, contract migration, unlock, liquidation, or technical incident may all produce a sharp percentage change. Find the original announcement and establish whether it appeared before the move. A post written after the rally may summarize the event accurately without explaining what started it.
The crypto losers today view is the necessary counterweight to a winners-only reading. If a few large assets fall while many small tokens rise, the market may be rotating between segments rather than attracting broad demand. If both large and small assets are declining, a green pocket may be an exception rather than the market’s direction.
Count-based breadth can mislead. Ten low-cap tokens can outnumber three major assets while representing far less traded value. Compare the number of advancing and declining assets with market-cap weight, turnover, and sector groupings. The conclusion should identify which measure supports it, rather than using “most coins” as a vague substitute for breadth.
Timing provides another clue. A loser may appear after an exploit report, a listing change, an unlock, or an outage. The ranking tells you where to investigate, not which event caused the decline. Check the relevant announcement and compare the asset’s behavior with similar tokens before assigning a catalyst.
This two-sided view is also useful for writers. A headline that says “markets are rising” can be misleading if the gains are concentrated in a small group of low-cap assets. Conversely, a broad decline can be hidden by a few large winners. Pair the tracker with an explicit statement about concentration and data coverage.
Sector labels need similar caution. Assets grouped under gaming, infrastructure, or another theme may not share a catalyst or business model. If several names from one label appear together, check whether they actually responded to the same event or were simply placed in the same category. A taxonomy organizes research; it does not prove a common cause.
Use this sequence when preparing a market note or deciding what deserves further research:
Consider two hypothetical assets. Asset A is up 7 percent with active turnover across several pairs and a narrow spread. Asset B is up 18 percent, but its market is concentrated in one shallow pair. B will attract more attention on the leaderboard; A may offer cleaner evidence about broad participation. The example is not a recommendation. It shows why percentage rank needs a market-structure check.
For editorial work, keep a small source card for every asset mentioned. Include the displayed fields, page timestamp, pair, possible catalyst, and one observation that could disprove the first explanation. This prevents a later ranking from being presented as though it existed unchanged when the article was written.
If the feed does not disclose a minimum-volume rule, do not invent one. State that thin markets may be included and apply a stricter liquidity check to any unusually large percentage move. That is more precise than either dismissing the dashboard or assuming that every ranked asset can absorb a large order.
Market dashboards can use delayed, estimated, or consolidated data. Prices move between refreshes, visible depth can disappear under stress, and fees or slippage sit outside the screen. Leverage, liquidation, taxes, custody, and regional access rules add risks that a ranking cannot resolve. A tracker is research context, not a substitute for independent assessment or a promise about future performance.
The most reliable reading is comparative. The tracker supplies the latest reference, gainers show where recent upside is concentrated, and losers reveal whether downside is broad or isolated. Save the method and timestamp, verify the story behind a move, and say what the data cannot establish. That process makes a fast dashboard more useful without asking it to predict the market.
Not always. A tracker may aggregate venues or show an index, while an exchange displays a quote from its own order book. Match the pair, price type, and timestamp before comparing them.
The list usually ranks percentage change, so a low starting price can produce a large percentage move. Check turnover, spread, depth, and the reference window before treating the rank as a major market event.
No. They show recent declines under a particular method. Compare the losing assets with large-cap weight, sector behavior, volume, and the same time window before describing a broad trend.
Save the page time, pair, quote currency, price, percentage change, volume, market cap, and any stated methodology. A timestamp makes later comparisons and corrections more honest.
It can identify a move worth investigating, but it does not establish causation. Verify announcements, technical records, and venue behavior before assigning a reason.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
October 8, 2026 | NCFA Resource | Payments And Money Movement, Digital Identity And Trust, Competition And Market Structure

On October 8, 2026, Mobey Forum launched its Digital Wallet Control Points tool, an interactive map of 22 points where banks, payment providers, wallet providers and other firms can influence how a digital wallet works. It shows how those points connect, which roles are involved and where a firm may need another company to make the service work.
Wallets no longer stop at payments. Identity, credentials, loyalty, data and agentic commerce are being pulled into the same customer experience. A bank or fintech may own the front end and still rely on several other firms behind it. The map helps teams see who controls what before they make a product, security, partnership or investment decision.
Mobey Forum defines a control point as a part of wallet operations, or a connected service, that gives an organization influence over how something works. The tool maps those points against the roles that can affect them and shows how one area connects to another.
Users can explore the map directly or start with a real problem. One guided example follows a security specialist at a European bank scoping a review of its wallet offering. Another looks at a bank planning for agentic commerce and asks what it would need from card schemes, payment service providers and token providers.
A bank can see where it has direct control and where another company matters. A fintech can see where a product fits without pretending it needs to own the whole wallet. An investor can look past the front end and ask whether a company controls something important or depends on someone else for access, distribution or execution.
Digital identity is also part of the current wallet conversation. Mobey Forum specifically points to the European Digital Identity Wallet as a reason firms need to think about identity verification and credential sharing alongside payments. The map gives those teams a way to see where the roles connect instead of treating each function separately.
The work also includes Canadian input. David Dymond of Royal Bank of Canada is part of the core team, while Neill Ashe and Hannah McIsaac of RBC are listed in the wider expert group. Interac contributors include Inna Gelmanova, Navjeet Grewal, Srdjan Manojlovic and Jeremy Wilmot.
Banks and credit unions can use the map before deciding what to build, what to buy and where a partner is unavoidable. Product teams can trace the firms involved in a proposed service. Security teams can see which important functions sit outside their own systems. Strategy teams can ask whether controlling a particular part of the wallet is worth the capital and effort.
Payment companies and wallet providers can use it to see where their role becomes important to someone else. That may be more valuable than owning the entire customer relationship. A firm that controls a hard-to-replace function can have a stronger position than one with a visible consumer brand but little control underneath it.
For fintech founders, there may be little value in rebuilding a capability that banks or large payment firms already control well. A smaller company may have a better opening where several participants need the same missing service or where existing options create too much friction.
Investors can use the map in much the same way. A company may be growing quickly but still rely on someone else for credentials, customer access, payment execution or distribution. That can affect margins, negotiating power and how defensible the business really is.
Agentic commerce makes this more immediate. Once software can use a payment credential or act for a customer, financial authorization and payment controls become part of the wallet question too. Who can approve the action, who executes it and who can stop it may sit with different firms.
Teams don't have to study the entire wallet market before they can use the tool. They can begin with a security review, a product idea, an agentic commerce plan or an investment question and follow the control points related to each decision.
It also makes hidden reliance easier to spot. A firm may appear to own the wallet experience while another company controls a critical connection, credential or payment function. OSFI warns about rising cyber, technology and third-party risk across increasingly connected financial systems and AI adoption. Those outside dependencies can change the economics of a product, the risks involved and whether building internally makes sense.
Mobey Forum has been working on this idea for a long time. Its original mobile wallet control points work dates to 2012, when it focused on areas such as wallet connections, distribution, customer acquisition, data flow and movement of value. The 2026 tool carries the same basic question into a much wider wallet market.
There are clear limits. The map won't tell a bank which control point it should own, whether a partnership is a good deal or whether a product will make money. It also doesn't replace security testing, architecture work, legal review or commercial due diligence. Its job is earlier than that: show the players, the connections and the places where control may matter enough to investigate further.
In the Mastercard, Flybits and Rogers Bank AI purchase, the customer set the instructions and spending limit, Flybits supplied the shopping agent, Rogers Bank supplied the card relationship and Mastercard handled the payment. Control was split across the customer, AI agent, card issuer and payment network.
Digital Wallet Control Points Launch (22 control points and guided use cases)
Mobile Wallet Control Points (Mobey Forum's original 2012 control model)
AI Agents Gain Identity and Wallet Access (wallet access, identity and delegated permissions)
FCA Emerging Technology Horizon Scan 2026 (AI, programmable finance and financial crime)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 6, 2026 | Digital Assets, Capital Markets, Investing, Fintech and Innovation

On October 5, 2026, U.S. tokenized securities and real world asset platform Ondo Finance launched Ondo Private Markets, offering eligible non U.S. investors in permitted jurisdictions tokenized exposure to private companies before they go public.
The first asset will reference an unnamed leading AI company and is expected to begin secondary market trading this week. Investors aren't buying the company's shares. They are buying notes tied to the value those shares may realize at a future liquidity event.
Ondo plans to add private companies across robotics, cybersecurity, biotech, infrastructure and other sectors. The tokens can be held in a digital wallet and traded 24/7 on secondary markets. That could make private company exposure easier to enter and exit, but it doesn't turn a private company into a public one or give token holders shareholder rights.
Each token is a note whose payout is linked to the per share value realized on the reference company's common shares at a qualifying liquidity event. The notes are obligations of their issuer, PM Issuer Co (BVI) Limited. They are not shares in the referenced company and don't give holders voting, ownership or other shareholder rights.
The structure separates access from ownership:
Access isn't global without restrictions. Ondo says Private Markets is available to eligible non U.S. investors in permitted jurisdictions. U.S. persons cannot subscribe for, acquire or redeem the tokens, and orders cannot be placed from within the United States. The launch announcement does not provide a simple country by country eligibility list, so local securities rules and Ondo's onboarding requirements still determine who can participate.
The notes haven't been registered under the U.S. Securities Act or securities laws in other jurisdictions. Ondo says eligible clients receive the offering documents, token terms and risk factors before subscribing, so the legal wrapper is as important as the token itself.
Citi took a different route in June when it launched digital depositary receipts on private shares. Citi acts as issuer and custodian for tokenized receipts representing private company equity. Ondo instead gives investors a contractual claim tied to the economic performance of a reference company. Two products can both offer tokenized private market exposure while giving investors very different rights to the company underneath.
Ondo already operates at decent scale. Its tokenized stock platform has more than 450 stocks and ETFs and over US$1 billion in total value locked. The company says its stock and Treasury infrastructure together represent about US$3.7 billion in total value locked and more than 1 million cumulative holders. See Ondo Gains US Approval For Tokenized Shares And Funds.
Ondo can make its notes transferable around the clock, even though the private company underneath still doesn't have a continuously quoted public share price.
The timing gap is important when the token trades more often than the asset used to value it. Private company transactions can be infrequent, different share classes may carry different rights, and new financing rounds can reset valuations. A token market may therefore offer more opportunities to trade without automatically providing better information about what the reference company is worth.
Nasdaq Private Market launched Daq in July to address part of the information gap. It brings together pricing, share class, transaction and company data covering more than US$5 trillion in private company valuations. Longer trading hours can make a token easier to trade, but they don't necessarily make the private company underneath easier to value.
Liquidity has a similar limit. Being able to trade 24/7 gives eligible investors more opportunities to find a buyer or seller. It doesn't guarantee a deep market, tight spreads or enough buyers when someone wants to exit. Limitations that will become more important as tokenized private markets expand beyond a small group of highly sought after companies.
On September 30, the U.S. SEC proposed expanding responsible retail access to private markets. The proposals would widen access through regulated fund structures while maintaining investor protections. The SEC is also considering additional ways for individuals to qualify as accredited investors, including an exam and certain professional credentials.
Digital distribution can move faster than the rules that historically defined private market access. It can also move faster than disclosure, price discovery and investor understanding. For another example of how digital markets are reaching earlier stages of the investment cycle, see Bybit Opens Tokenized IPO Access To Retail Investors. More investors want access to companies before they go public, while regulators and financial firms are testing different ways to provide it.
Ondo is making private company exposure easier to hold, move and potentially trade without turning the token into company stock. That could open private markets to more investors, but easier access doesn't change the legal rights investors receive. As private markets move onchain, investors still need to ask the simplest question: what do I actually own?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 5, 2026 | Event, Digital Assets, Blockchain, Web3, Networking, Singapore

One of NCFA's media partners Block Tides is co-hosting a Web3 and digital assets ecosystem networking and industry event, Tech EZ KOL Club by DigiMaaya this October 6 at Gardens by the Bay — bringing together KOLs, creators, founders, exchanges, investors, traders, and ecosystem leaders in one curated room.
📍 Flower Field Hall, Gardens by the Bay
📅 October 6, 2026
⏰ 7:00 PM – 10:00 PM SGT
Expect:
✨ High-value networking
🤝 Founder, investor & exchange introductions
📣 KOL + creator collaborations
🌐 Partnership, media & ecosystem opportunities
🏆 Leader Awards + Book Launch
🥂 Premium hospitality with a waterfront setting
🎟 Partner Pass — Free, subject to approval
💎 VIP Pass — 99 USDC
If you're in Singapore for TOKEN2049 Week, this is one of the rooms you’ll want to be inside.
👉 Register here:
https://luma.com/twvhx8s4
Hosted by DigiMaaya
Co-Hosted by AKARI × Block Tides
See you at the Bay. 🌊⚡
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 9, 2026
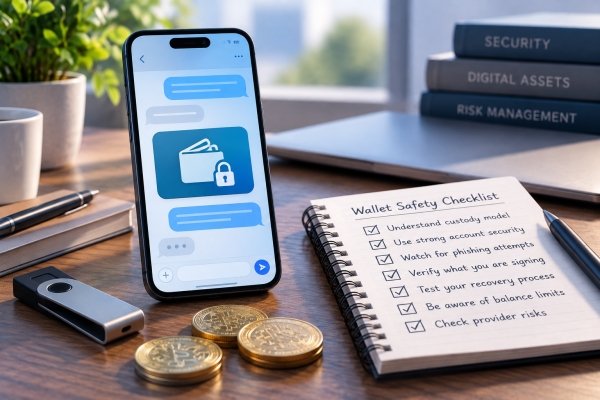
Is Telegram crypto wallet safe? There is no universal yes or no. A wallet reached through a messaging app can be convenient for a small transfer, but its safety depends on who controls the keys, how recovery works, what a user is asked to sign, and whether the bot or mini app is genuine. Convenience changes the access path; it does not remove custody, phishing, device, or service risk.
This guide is for Telegram users who are considering a wallet for payments, transfers, or a limited operational balance. It explains how to inspect the control model, test recovery, and separate account security from wallet security. It does not recommend a provider, compare token prices, set a balance threshold, or provide legal, tax, or investment advice.
Safety is not one feature. It is a chain that includes custody, authentication, transaction signing, software integrity, privacy, recovery, and service availability. A wallet can be strong in one area and weak in another. For example, a provider may make account recovery simple while retaining the ability to delay withdrawals. A self-custodial setup may remove that provider dependency while making a lost recovery credential difficult or impossible to fix. A focused review of is Telegram crypto wallet safe starts with those control questions rather than with the messaging interface itself.
The Telegram interface does not tell you which arrangement you are using. A balance shown inside a chat may represent a provider-held account, a wallet whose keys are controlled by the user, or a hybrid contract with recovery or upgrade roles. Read the wallet's terms and inspect its actual deposit, withdrawal, and recovery flow. A familiar app icon is not evidence of a particular custody model.
| Control model | Who usually controls access | Main convenience | Main failure mode |
| Custodial | A provider holds signing authority or records an internal balance | Account recovery may be easier | Withdrawal limits, freezes, insolvency, or account loss depend on the provider |
| Self-custodial | The user controls a recovery credential or signing keys | Direct control without a provider reset | Phishing, loss, or an incorrect transaction may be hard to reverse |
| Hybrid | Control is split between user keys, a contract, guardians, or a service | Flexible recovery or policy controls | The recovery threshold and upgrade power can be hard to understand |
The first question is therefore not whether Telegram is safe. It is: what exactly is being protected, and who can authorize a transfer? If losing access to a Telegram account lets a provider reset the balance, account security is part of custody. If a recovery phrase is independent of the account, an account takeover can still enable phishing and expose private conversations, but it should not by itself authorize a self-custody transfer.
Messaging environments create a distinctive phishing problem. Fake bots, support accounts, copied avatars, and urgent warnings can look credible because they appear inside a familiar conversation flow. A request for a recovery phrase, private key, one-time code, remote-access permission, or emergency payment should be treated as a stop signal. Legitimate support should not need the secret that authorizes the wallet.
Account takeover is a separate but related risk. An attacker who controls a Telegram account may read conversations, impersonate the user, or direct the user toward a malicious bot. Protect the Telegram account, email account, and phone number with unique credentials and the strongest available authentication options. That protection reduces the chance of a convincing scam, but it does not replace a secure key-management design.
The chat interface can also hide transaction detail. Before approving a transfer or token permission, verify the recipient, amount, network, fee, contract, and allowance. If the interface does not expose enough information to make that judgment, use a more transparent route or pause the transaction. A quick button is not a substitute for knowing what the signature authorizes.
Service dependency adds another layer. Ask what happens if the bot is removed, the provider is offline, Telegram access is restricted, or the wallet changes its supported networks. A self-custodial asset may remain on-chain while the interface is unavailable, but a custodial balance may depend on the provider's records and withdrawal process. Availability is part of practical safety, not merely a customer-service concern.
The safest review is a small, documented test rather than a large transfer based on a promising interface. Use this sequence before keeping a meaningful balance:
This process does not make a wallet risk-free. It converts vague confidence into specific observations. The useful result may be a decision to use the wallet only for a narrow payment flow, not a decision to move everything into it.
Users often compare a chat-based wallet with crypto exchanges as if one must be safer in every situation. The better comparison is task-specific. An exchange may provide account recovery, order execution, and a visible transaction history, but it introduces platform, withdrawal, counterparty, and policy risk. A self-custodial wallet may provide direct key control, but the user carries the recovery and signing burden. A Telegram wallet can combine parts of both models while making the control boundary less obvious.
Use a short decision test. If the main task is a frequent, low-value payment, convenience may matter more than advanced self-custody, provided the provider and withdrawal rules are clear. If the main task is long-term storage, the ability to verify keys, recovery, and transaction details becomes more important than chat access. If the task is active trading, execution rules, liquidity, fees, and liquidation or withdrawal constraints may matter more than the interface.
The comparison should also include failure recovery. Who can help after a lost phone? Who can reverse an unauthorized transfer? What records exist if the provider disputes a balance? The answer will differ by product and jurisdiction. Treat a wallet and an exchange as different risk packages rather than as interchangeable labels.
A Telegram wallet may be useful when its control model is explicit, its entry point is verified, and the amount exposed is limited to the task. It becomes a poor default when a user cannot explain how a withdrawal is authorized, where the recovery credential lives, or what happens during a provider outage. The wallet can feel safe because it is embedded in a familiar app while still adding a new layer of account and bot risk.
Rules about custody, financial promotion, data handling, and customer protection vary by provider and jurisdiction. A wallet's presence in a messaging app does not establish deposit insurance, reversibility, or regulatory status. Read the relevant terms and seek local professional advice for questions that depend on law, tax, or business use.
No. It may be a custodial account, a self-custody wallet, or another on-chain service. Deposit protection, reversibility, and recovery depend on the specific provider and arrangement.
Not normally without a valid key or user approval, but phishing can trick a user into signing a transfer or token permission. Custodial services have different account and withdrawal risks.
That is a poor default. Use only the amount needed for the activity until custody, recovery, service availability, and transaction controls are clear. A separate arrangement may be more appropriate for long-term or high-value holdings.
Identify who controls the signing authority, then test a small withdrawal and the documented recovery path. If either answer depends on an unverified chat or an unexplained support request, pause.
So, is Telegram crypto wallet safe? It can be reasonable for a limited use case when the provider is genuine, the custody model is understood, account security is strong, and every transaction can be checked before approval. It is not automatically safe because it appears inside Telegram, and it is not automatically unsafe because it uses a bot. The practical standard is simple: verify control, test recovery, limit exposure, and keep the chat interface from hiding what you are authorizing.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 4, 2026
What is Web3 gaming? It is a broad category of games that use a blockchain for some part of ownership, trading, identity, governance, or the game economy. A player might hold an item in a wallet rather than only in a publisher database. That feature can create new forms of portability and coordination, but it can also add wallets, fees, scams, volatile assets, and irreversible mistakes to an activity many people expect to be simple entertainment.
This guide is for players, researchers, and editors trying to understand what a Web3 label means in practice. It explains what may be on-chain, what remains controlled by the publisher, and how to evaluate the trade-offs before spending time or money. It does not rank games, recommend tokens or collectibles, or provide investment advice.
Web3 gaming is not an all-or-nothing category. A project may put a collection of items on-chain while keeping the game server, combat rules, moderation, and progression system centralized. Another may use a token for governance but keep all gameplay data in a conventional database. The useful question is not whether a game uses a blockchain somewhere; it is which part of the player experience is actually controlled by the player or verified by a public network. For a concise foundation, what is web3 gaming is best answered by mapping those specific functions instead of treating the label as a genre.
| Game element | Common Web2 approach | Possible Web3 approach | Question for a player |
| Items | Recorded in the publisher database | Some items represented by tokens in a wallet | What rights does the token actually grant? |
| Payments | Publisher controls in-game currency | Tokens or NFTs can be transferred externally | What are the fees and exit options? |
| Identity | Login managed by the publisher | Wallet-based identity, sometimes combined with login | What happens if the wallet is lost? |
| Governance | Publisher sets rules and content | Token or community voting covers selected decisions | Which decisions are truly subject to a vote? |
| Continuity | Access depends on the game service | Some assets may remain visible if one interface changes | Does the item still have utility without the original game? |
The word "ownership" also needs precision. Holding an NFT usually means controlling a token record under a contract's rules. It does not automatically grant copyright, a trademark license, access to a server, a guaranteed use in another game, or a right to future development. Those rights may be defined by a license, terms of service, or a separate account system.
An on-chain item can sit outside one account database and be transferred under the token's rules. That may support a secondary market, a player identity, or a collection that is visible across tools. Portability is only useful when another game or service recognizes the asset and knows what its data means. A transferable item with no compatible use is ownership in a narrow technical sense, not automatic utility.
Public transaction records can also make parts of an economy easier to inspect. A reader may be able to observe supply, wallet concentration, transfers, or selected contract rules. This can improve transparency, but it does not make the economy fair by itself. A contract may still be upgradeable, a marketplace may control the interface, and important gameplay data may remain private.
Governance tokens can give players a voice over selected decisions. In practice, voting power may be concentrated among large holders, delegated to a small group, or limited to parameters that do not affect the core experience. Ask what the vote can change, who can propose it, and whether the result is binding. A vote count is not the same as meaningful player control.
Token incentives may create new funding or creator models, but they also change the audience's motivation. A player who wants a game may be competing with participants focused on item resale or token appreciation. That can make prices, participation, and community behavior more volatile than the gameplay itself.
Web3 features add operational steps. A player may need a wallet, a network choice, a transaction fee, an approval, and a marketplace account. Each step creates room for a wrong address, fake link, private-key theft, or an irreversible signature. A custodial onboarding flow can reduce some friction while increasing dependence on the provider. Neither model removes the need to understand what an action authorizes.
Transaction economics can also change the value of an item. Consider a deliberately simple example: a player buys a $20 item, pays a $3 network fee, and later pays a 5% marketplace fee to sell at the same nominal price. The sale returns about $16 before any price change or tax. The arithmetic is not a forecast; it shows why displayed item prices do not equal the amount a player can recover.
Liquidity is another constraint. A marketplace floor is an asking price, not a guaranteed buyer. When interest fades, the highest visible listing may be far above the price at which a sale would actually clear. A token can lose liquidity while the game remains playable, and the reverse can happen as well. Treat marketability as a separate question from entertainment value.
Smart contracts, bridges, marketplaces, and game servers can fail independently. An on-chain item may remain visible in a wallet while the game that gave it meaning shuts down, changes its rules, or removes its server access. A blockchain record can persist while practical utility disappears. This is why "you own the asset" is not a complete explanation of the player outcome.
Use the following sequence to separate a playable product from a token pitch:
This framework keeps the article's central question in view: does the on-chain feature improve the player experience enough to justify its added complexity? A game can be legitimate and still not suit a particular player. The decision should depend on the experience and rights, not on the label alone.
Market context can help explain why a game token is attracting attention, but it cannot measure whether the game is well designed. A token that appears among crypto market gainers may be reacting to a listing, a partnership announcement, thin liquidity, or speculative positioning. The ranking is a prompt to investigate the event and the market structure, not proof that players are adopting the game.
Check the pair, quote currency, time window, volume, and available liquidity before drawing a conclusion. A large percentage move in a shallow market may represent a small amount of capital. Conversely, strong player activity may not immediately appear in a token ranking if the project uses a custodial economy or has no liquid token. Keep game research and market research as related but distinct tasks.
The same distinction applies to community sentiment. A crowded chat can show that a launch is visible, not that the product is sustainable. Look for retention, repeat play, clear updates, and evidence that the economy works for ordinary players. If the only durable demand appears to come from recruiting new buyers, market risk may be replacing game design.
Web3 gaming is best understood as a bundle of design choices rather than a single genre. The same project can offer genuine player ownership in one area while retaining centralized control in another. Rights, fees, wallet security, server access, and token liquidity vary by project and jurisdiction. Read the game's terms, marketplace rules, and wallet prompts before making a consequential decision.
Not always. Some games offer custodial accounts, free starter items, or sponsored transactions. Others require a wallet and network fees. Check the actual onboarding flow instead of assuming the label tells you what is required.
No. You may control the token record while the publisher controls the game, servers, trademarks, and utility. The rights depend on the contract and the project's terms.
Only if the other game chooses to recognize the asset and can interpret its data. On-chain transferability does not create automatic gameplay compatibility.
They can expose a player to market risk, but a token or item is not automatically a sound investment. Prices, liquidity, fees, and utility can change, and the purchase may be better treated as entertainment or speculation.
What is Web3 gaming? It is gaming with selected ownership, payment, identity, governance, or economy functions connected to blockchain systems. The meaningful analysis is not how many tokens a project issues, but what the player can actually control, transfer, use, and recover.
Play the core game, map the control boundaries, calculate the friction, and test what survives when prices stop rising. That approach keeps technology in perspective and leaves room to enjoy a game without mistaking a market narrative for a guarantee.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 31, 2026 | NCFA Market Activity | Digital Assets Blockchain And Tokenization, Wealth Investing And Trading, Competition And Market Structure, Capital Markets And Market Infrastructure
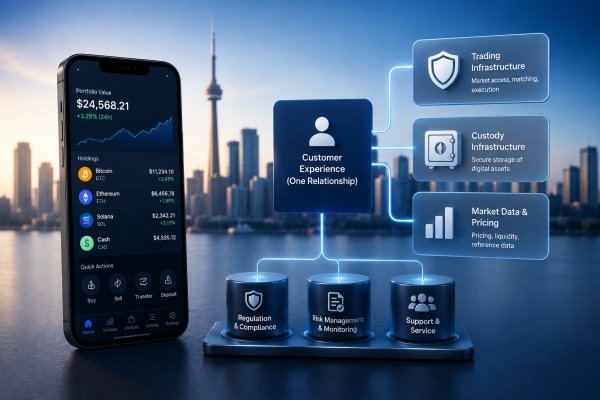
On August 31, 2026, Coinbase announced its Webull Canada partnership, supplying the trading and custody services behind Webull's new Canadian crypto offering. Webull maintains the investor relationship and brokerage experience, while Coinbase handles two core crypto functions. The same partnership already supports Webull in the United States, Brazil and Australia.
Webull Canada Crypto Limited was registered as an Investment Dealer and admitted to CIRO membership effective June 17, 2026. Coinbase Canada, Inc. is registered as a Restricted Dealer across Canada.
Crypto arrives after Webull spent more than two years expanding its Canadian brokerage. It launched here in 2024 with Canadian and U.S. equities and later added registered accounts, options, cash management, desktop trading and longer trading hours. Canadian stocks and ETFs now trade at zero commission, while selected securities are available around the clock five days a week.
When Webull entered Canada, its offering was much narrower. The company has since added enough products that crypto now joins an account already spanning stocks, options, cash, margin, TFSAs and RRSPs.
Using Coinbase lets Webull add crypto without building its own trading and custody systems from scratch. It can use infrastructure already supporting the same partnership elsewhere, reducing the amount of technology and operating capability Webull has to build internally.
Webull still has to persuade Canadians to use the product. The company reports 26 million registered users globally but doesn't disclose its Canadian customer count, leaving a large gap between the breadth of its local product menu and what outsiders can see about actual adoption.
A Canadian investor trading crypto through Webull remains inside Webull's experience, but Coinbase can still earn from the trading and custody taking place underneath it.
Coinbase has been selling more of those capabilities to financial institutions. Its Crypto as a Service business targets banks, brokers, fintechs and payment companies that want to offer digital assets without building everything themselves. Coinbase said in 2025 that more than 200 institutional clients were already using its infrastructure.
Webull gives Coinbase another customer for that business while Coinbase continues competing directly for Canadian crypto users through its own platform. The two companies can pursue the same investor from different positions. Webull wants the account and ongoing customer relationship. Coinbase can benefit whether the investor chooses Coinbase directly or reaches its services through Webull.
Webull is relying on Coinbase for key parts of the service. If trading, custody, pricing or service problems arise, Webull still has to deal with the customer impact.
Webull isn't alone in combining its own customer experience with outside financial infrastructure. Wealthsimple offers stocks, cash and crypto from one relationship, while its regular crypto service uses external custodians including Tetra Trust, Coinbase Custody and BitGo. Its recent in app DEX trading beta uses a different model, creating a self custody wallet for the client and routing trades through a third party DEX aggregator.
Crypto focused firms such as Coinsquare, Newton and Shakepay started from a different approach, building their customer relationships around digital assets before adding more services. Webull started as a brokerage and is bringing crypto into an account already built around conventional investing.
Customers can now see a growing number of competing apps even when some important functions behind those apps come from the same suppliers. If several brokers rely on a small group of firms for custody, execution or liquidity, competition at the customer level can grow faster than the number of companies providing the underlying services.
Building everything internally isn't automatically better and often depends on the lifecycle stage of the firm and target customer base. It can preserve more control and economics, but it also brings technology, security, compliance and operating costs. Buying specialist infrastructure can get a product to market faster, provided the platform is comfortable with the dependency and the economics.
Webull has removed many of the obvious product gaps since entering Canada. Investors can now trade Canadian and U.S. equities, options and crypto, use registered accounts and access longer trading hours. Another product won't automatically pull customers away from Wealthsimple, established brokerages or dedicated crypto platforms.
Existing Webull users may be the easiest audience. They can add crypto beside the rest of their portfolio without opening another trading relationship. Whether that convenience produces meaningful Canadian crypto activity won't be clear until Webull discloses more about adoption or the market provides other evidence.
Coinbase receives another benefit if the model continues to expand. Its Webull relationship now spans four countries, so a successful Canadian launch gives Coinbase another example it can use when selling trading and custody services to other financial firms. It doesn't need its name on the customer's home screen to participate in the transaction.
Webull and Coinbase are building different businesses from the same Canadian launch. One wants to own more of the investor relationship. The other can earn by supplying financial functions to companies that already have one.
As financial apps buy more of what they offer from specialist providers, who keeps more of the long term value: the company with the customer or the company running the service underneath?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016