




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 8, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization
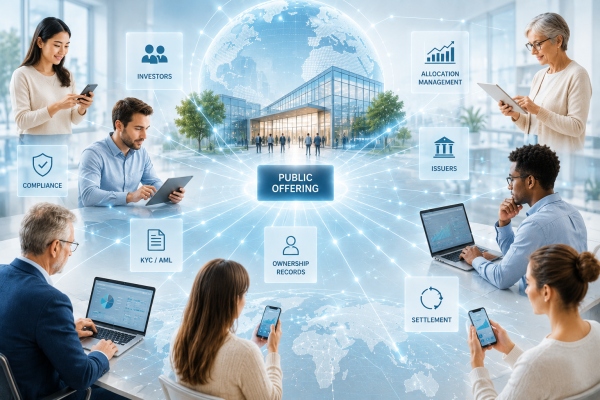
On June 7, 2026, Bybit launched IPO Express, a platform that gives eligible users access to tokenized IPO allocations starting with SpaceX. The launch arrives as SpaceX prepares for a public offering expected to value the company at approximately $1.75 trillion, making it potentially one of the largest IPOs ever. While the SpaceX name grabs attention, the bigger story is what this says about investor access, capital formation, and the growing role of digital infrastructure in public markets.
While the SpaceX name grabs attention, the bigger story is how firms are competing to expand investor access and improve IPO distribution.
Traditional IPO allocations typically flow through investment banks, brokerage firms, institutional investors, and private banking networks. Retail investors often participate only after public trading begins.
Bybit's model broadens access by allowing eligible users to subscribe through exchange infrastructure before trading starts. Investors can receive allocations and subsequently trade tokenized exposure through the platform.
The model combines several functions that have historically operated through separate systems, including investor onboarding, allocation management, compliance, custody, ownership records, and trading. Companies are now competing to modernize how investors access public offerings.
Much of the discussion around how tokenization is changing markets has focused on stocks, bonds, funds, real estate, and other assets after issuance. IPO Express focuses on an earlier stage of the investment lifecycle.
For decades, financial innovation concentrated around trading efficiency, lower transaction costs, and faster settlement. Tokenized IPO access targets a different challenge related to who gets access to investment opportunities in the first place.
Investor verification and eligibility checks now matter as much as trading access. So do allocation rules, ownership records, compliance controls, and settlement. Platforms that combine these functions in one clean workflow may earn an advantage as capital markets become more digital.
Canada has already seen similar efforts to expand investor participation through equity crowdfunding, online exempt market platforms, private market technology, and digital investment platforms.
Canada already has a live comparison point. Wealthsimple’s IPO Access for Canadian retail investors broadens access through a brokerage account, while Bybit’s IPO Express adds a tokenized layer around allocation and trading. Both are aiming to solve the same pressure in capital markets: retail investors want earlier access, cleaner digital onboarding, and a fairer shot at high demand offerings.
NCFA’s Who Gets Capital As Funding Channels Multiply? asks the same core question for Canadian markets. More channels don't automatically create better access for every founder or investor.
Tokenized IPO access brings the same access and onboarding pressure to public exchange listings. For Canada, the practical question is whether regulated platforms can use digital infrastructure to make capital raising easier without weakening disclosure, custody, suitability, or investor protection. That question fits NCFA’s financial innovation market infrastructure research, where access to capital, tokenization, compliance, and investor trust now overlap.
If retail investors can access high demand offerings through faster digital channels elsewhere, how long can domestic platforms rely on slower, relationship driven distribution models?
The competitive advantage may no longer come from who controls the allocation. It may come from who makes access easiest while still meeting regulatory requirements.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 29, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Risk Compliance And Regtech
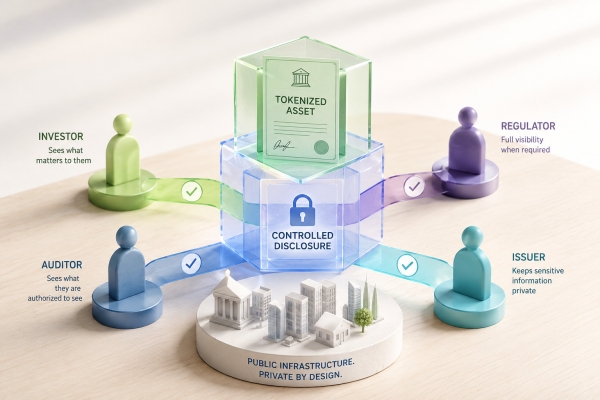
On May 27, 2026, Toronto based Polymath launched Confidential Assets on Polymesh, a protocol level privacy feature for tokenized securities and real world assets. It uses zero knowledge cryptography to keep transaction details private while preserving access for regulators, auditors, and authorized parties.
Privacy solves a practical market problem. Public blockchains can expose positions, client data, and transaction flows. Private chains can protect confidentiality, but they can also silo activity inside closed systems. Confidential Assets is Polymath aim to give regulated asset markets privacy without giving up public permissioned infrastructure.
Martin Halford, CEO, Polymath:
“The question the market has been asking is not whether assets can be tokenized -- they can. The question is whether tokenization can be done at an institutional scale, with the privacy and compliance standards that real financial infrastructure demands. Confidential Assets is our answer to that question.”
The stronger use case isn't about keeping secrets, but rather controlled disclosure. Issuers, investors, and asset managers need privacy around holdings and transfers. Yet a wide range of stakeholders from regulators to auditors, custodians, and compliance teams still need access when rules require it.
Confidential Assets is built into the Polymesh protocol, not added through a third party tool or Layer 2 solution. This allows privacy to work within the same system that handles compliance, governance, and settlement. A fund, private credit issuer, real estate platform, or broker dealer could use the feature to complete a compliant transfer without exposing position size or counterparty details to the broader market.
The ultimate goal and impact is the right mix of privacy and oversight. If Polymath gets that balance right, Confidential Assets could make Polymesh more useful for real capital markets activity, not just token issuance.
Confidential Assets is available immediately to institutions building on Polymesh. Polymath has been building regulated asset infrastructure since 2017 and contributed the ERC 1400 security token standard. Polymesh achieved SOC 2 Type 1 compliance in 2025. Polymath also says a post quantum ready version of Confidential Assets is in development for long term assets that may remain on chain for decades.
For Canadian capital markets and fintech firms, controlled disclosure is becoming core infrastructure for tokenized assets. Platforms that manage who can see what, and when, will become harder to replace in digital securities markets, over time.
Can tokenized markets reach institutional scale without protocol level privacy, or will controlled disclosure become a core requirement for regulated digital assets?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |

Last Updated: May 28, 2026
Status: Strengthening
Organizations: Bank of Canada, DTCC, Broadridge, NYSE, Securitize, FCA, LSEG, BIS
The answer is yes, but only in the right legal and market structure. Tokenized real world assets are becoming usable where regulators connect them to securities, custody, fund, settlement, collateral, payment, and investor protection rules. The strongest evidence is not speculative token launches. It is regulated infrastructure that can support bonds, Treasuries, funds, repo, collateral, transfer agency, and settlement.
The practical question is not whether RWAs can be tokenized. They can. NCFA has tracked this progression from experimentation to execution. Earlier evidence showed how tokenization started looking like financial infrastructure, while more recent developments show tokenization finding scale in collateral and cash. European policymakers are also advancing a roadmap for tokenized finance infrastructure, reinforcing the view that tokenization is increasingly being evaluated as market infrastructure rather than a standalone asset class.
The firms to watch are the ones building the boring middle layer. That means custody, transfer agency, collateral management, settlement links, reporting, governance, and legal certainty. RWA growth depends on trust and operating proof, not marketing.
Strategic Takeaway
Tokenized RWAs are becoming market infrastructure where legal rights, custody, settlement, collateral, and investor protections connect. The opportunity is not just putting assets on chain. It is making regulated assets easier to hold, move, finance, and reconcile inside trusted financial systems.
Click each item to expand
The Bank of Canada, Export Development Canada, RBC, TD, and RBC Investor Services completed a tokenized bond experiment using distributed ledger technology. This gives Canada a credible domestic proof point for tokenized securities infrastructure.
DTCC is preparing tokenized real world asset services for production use. This is important because DTCC sits inside regulated post trade infrastructure, not outside the system.
Broadridge’s Distributed Ledger Repo platform shows tokenization already operating in a serious institutional workflow. Repo is market plumbing tied to collateral, liquidity, and funding.
NYSE and Securitize agreed to support tokenized securities infrastructure, including standards for digital transfer agents and tokenization agents.
The UK FCA published rules and guidance for fund tokenisation, giving asset managers a practical framework for tokenized fund operations.
Project Agorá, led by the BIS with central banks and commercial banks, tests tokenized deposits and wholesale central bank money for cross border settlement. This matters because tokenized assets need a reliable cash leg.
Do you agree the evidence is strengthening?
 2
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 28, 2026 | NCFA Insight | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure

On May 26, 2026, the BIS released its 97 page Project Agorá report, detailing how a global public private prototype tested the feasibility of tokenized commercial bank deposits and wholesale central bank money for cross border payments. The report explains the project vision, who participated, what the prototype tested, what worked (or not), and what has to happen before any production system can operate at scale.
Project Agorá isn't a retail CBDC project, nor is it a stablecoin clone. It tests whether today’s correspondent banking system can use tokenized bank money and smart payment workflows to make wholesale cross border payments faster, safer, more transparent, and easier to coordinate.
Cross border payments totalled USD $195 trillion in 2024 and are projected to reach USD $320 trillion by 2032. Wholesale payments accounted for 91% of cross border payment value in 2023. These flows affect banks, PSPs, exporters, capital markets firms, treasury teams, and fintechs building around global money movement.
On May 27, 2026, the Bank of Canada joined Project Agorá, giving Canada a seat at the table and role in the next phase of testing. The Bank says the project has successfully tested the feasibility of a multi currency unified ledger that enables atomic settlement of wholesale cross border transactions.
The next phase will continue testing the prototype and examine how an Agorá type platform could operate under existing legal and regulatory frameworks, including settlement finality, anti money laundering rules, and terrorist financing rules.
Carolyn Rogers, Senior Deputy Governor, Bank of Canada:
“We know that the Canadian economy could benefit from innovation in cross-border payments. Tokenization has the potential to make these payments faster, cheaper and more efficient and secure. Project Agorá is a unique opportunity to test the technology across several jurisdictions and currencies, with the participation of private sector financial institutions.”
Project Agorá was convened by the BIS and the Institute of International Finance. It originally brought together 7 central banks and more than 40 regulated financial institutions, including banks, payment service providers, financial market infrastructures, and global payment networks.
The central bank group includes the Federal Reserve Bank of New York, Bank of England, Bank of France representing the Eurosystem, Bank of Japan, Bank of Mexico, Swiss National Bank, Bank of Korea, and now the Bank of Canada for the next phase. That makes Agorá a multi currency and multi jurisdiction test, not a single bank proof of concept.
The project keeps correspondent banking as the base model. Banks still manage customers, deposits, access, compliance, and balance sheet relationships. Central banks still control reserves and domestic policy settings. Agorá adds a shared programmable platform to coordinate the payment workflow.
The prototype uses a two layer architecture. (1) A unifying ledger records tokenized commercial bank deposits and coordinates the cross border workflow. (2) Separate jurisdictional ledgers record tokenized central bank reserves so each central bank keeps control over its own money, access rules, and policy settings.
The payment workflow has five stages. Agorá checks the payee, finds the payment route, confirms required checks, locks the needed balances, then settles the transaction. In report terms, those stages are confirmation of payee, path discovery, validation, locking, and settlement.
The order sequencing matters. Agorá checks the payment before banks lock up liquidity. It confirms the payee, route, required checks, and available balances first. Only then does settlement begin. That reduces the risk of finding a problem after money has already been committed.
 Source: Bank for International Settlements, Project Agorá, “Wholesale cross border payments today and in Project Agorá,” Figure 1.
The prototype showed that atomic settlement is achievable in a tokenized environment across the participating jurisdictions. This means that either every required balance update happens, or none of them happen. One leg of a transaction cannot settle while another fails.
The report says settlement can occur in seconds once funds or liquidity are locked. The platform is also designed to operate around the clock, which could reduce delays caused by time zones and market hours. That doesn't mean every payment becomes instant from start to finish. It means the settlement step can happen quickly after the required checks and liquidity locks are complete.
The prototype also showed that shared infrastructure doesn't require shared data by default. Participants can coordinate payment status, validation outcomes, and settlement without exposing customer data, internal risk models, or sensitive routing information to everyone on the platform.
The report identifies specific pain points in wholesale cross border payments. They include mismatched operating hours, sanctions and compliance false positives, serial processing, poor data quality, weak payment status visibility, unclear fees, liquidity pressure, settlement risk, reconciliation breaks, and client outreach.
These are practical banking problems. A false positive can stop a legitimate payment. A missing data field can trigger manual review. A payment status gap can leave banks and clients unsure where funds are stuck. A reconciliation break can create cost after settlement. Liquidity sitting in the wrong place can weaken treasury efficiency.
The report doesn't make cost reduction the main objective because many wholesale payment costs come from FX pricing and market structure. The stronger claim is narrower though. Fewer failed payments, investigations, returns, and reconciliation breaks could reduce operating drag if the model works in production.
Agorá doesn't try to centralize AML, counter terrorist financing, sanctions, fraud, or policy decisions. Each institution still performs its own checks inside its own systems. The platform coordinates only the outcomes needed to move the workflow forward.
This is important for banks who need shared infrastructure, but they don't want to expose customer information, proprietary screening logic, or internal compliance decisions to every other participant in a payment chain. Agorá uses scoped privacy and controlled information sharing so only relevant parties receive the data they need.
The result is a realistic compliance model for regulated institutions. It doesn't remove compliance work. It tries to reduce duplication, bring validations earlier in the process, and stop settlement from starting before required checks are complete.
The report’s legal analysis as tested in Agorá, found that tokenization doesn't fundamentally change the legal nature of money. Tokenized central bank reserves remain central bank reserves. Tokenized deposits remain commercial bank deposit obligations.
It suggests tokenized bank money can develop inside existing legal and regulatory frameworks instead of starting from a blank page. It also separates Agorá from private digital asset models where the legal nature of the claim can be less familiar.
The report doesn't claim every legal issue is solved however. Settlement finality is achievable across the participating jurisdictions, but production deployment would still need rulebooks, contractual frameworks, liability rules, governance, data rules, insolvency treatment, and clear legal effect across jurisdictions.
The strongest benefits are operational. Agorá could give banks better payment status visibility, earlier data checks, fewer late stage failures, faster settlement after liquidity is locked, and more predictable workflows across currencies.
Treasury teams could benefit from better liquidity coordination. Cross border payments today can require prefunding, manual investigation, and treasury allocation across time zones. Agorá’s design could reduce some of that friction by coordinating payment paths, validations, balance locks, and settlement in one workflow.
The risks are in production execution. The report says the prototype didn't prioritize production grade performance, cyber security, or liquidity saving tools. It also left FX integration and other tokenized asset classes outside scope.
A real system would need to connect with existing bank infrastructure and prove it can operate under stress. That means strong governance, resilience testing, failover, monitoring, and clear performance benchmarks.
The Bank of Canada is now involved, but commercial value depends on private sector participation. Canadian banks, PSPs, market infrastructure providers, and fintechs need a role in testing, rule design, and integration.
For fintechs, the opportunity is to build around the workflow through compliance tools, privacy technology, treasury systems, FX routing, liquidity optimization, reconciliation software, APIs, and analytics.
Agorá gives banks and central banks a regulated alternative to stablecoin settlement networks, but only if the next phase proves it can handle real value, real liquidity, and real operating rules.
If Project Agorá evolves from prototype to real value settlement, will tokenized bank deposits become the regulated answer to stablecoin driven cross border payments?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 25, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization
On May 20, 2026, 3iQ selected Anchorage Digital as the infrastructure and custody partner for its Canadian product suite. Subject to regulatory approvals and required prospectus or offering document amendments, 3iQ intends to migrate a significant portion of assets under management across six TSX listed exchange traded products to Anchorage Digital.
3iQ is a Canadian digital asset investment manager with a regulated public product suite. Anchorage Digital became the first OCC approved national crypto bank in the U.S. Canada has qualified digital asset custodians, but not an equivalent national crypto bank structure at Anchorage’s scale. The decision puts a hard question in front of Canada’s digital asset sector. Can Canadian infrastructure win large institutional mandates when issuers need custody, settlement, staking support, and regulatory comfort at scale?
The warning is now showing up in market activity. Canada has already debated whether domestic digital asset infrastructure can compete with larger U.S. regulated platforms. That issue became more visible when Balance applied for a Canadian special purpose trust structure to build institutional digital asset custody capacity at home.
If Canada approves digital asset products but doesn't build trusted infrastructure at home, more of the work, jobs, and revenue may migrate south. In this case, 3iQ keeps the Canadian listed products while Anchorage Digital captures more of the custody and infrastructure work behind them.
That choice is commercial, not patriotic. Large issuers choose the stack that lowers operating risk and helps them launch better products. That’s the reality test Canadian infrastructure providers now face.
3iQ says Anchorage Digital lets funds settle trades from cold storage without relying on hot wallets. Its Atlas network also lets 3iQ settle directly with trading counterparties and remove extra wallet steps. It means custody now affects much more than safekeeping. It affects how funds trade, settle, manage risk, support staking, and protect investors.
The partnership is also expected to support 3iQ’s expanded staking capabilities. That raises the stakes. Staking needs more than token custody. It needs validator access, clean reporting, strong controls, and regulatory comfort. The right custody partner can give a fund more room to build. The wrong one can hold it back.
Tommaso Mancuso, President and CIO of 3iQ:
"3iQ needs infrastructure providers that meet “the highest standards for security, flexibility, and regulatory alignment.”
That is the standard Canadian infrastructure has to meet now. Canada has digital asset talent, regulated products, custody ambition, and a real institutional market. But the operating stack behind those products still needs more depth, if they want to compete. Fund issuers need platforms that can handle scale, connect cleanly to trading counterparties, support approved product features, and satisfy regulators without adding friction.
Canadian policymakers should treat this as a competitiveness warning. Product approvals aren't enough if the custody, settlement, staking, and fund operations work scales outside Canada. The goal should be to keep more trusted digital asset infrastructure, jobs, and revenue at home.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 22, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization, Regulation And Policy, Capital Formation And Venture Markets

Image: Hester Peirce (aka Crypto Mom)
On May 21, 2026, reports confirmed that SEC Commissioner Hester Peirce will leave the U.S. Securities and Exchange Commission later this year to join Regent University School of Law, closing one of the most closely watched regulatory tenures in digital asset policy.
Peirce became affectionately known globally as “Crypto Mom” because she consistently argued that regulators should give digital asset markets workable rules instead of leaving companies to operate inside uncertainty. Her positions moved from controversial to increasingly mainstream as spot bitcoin ETFs launched, tokenization expanded, and major financial institutions entered digital asset infrastructure.
Her departure doesn't mean pro crypto or pro innovation momentum suddenly disappears from Washington. Digital assets no longer depend on a single regulator defending the sector. Bitcoin ETFs now trade in regulated markets. Large banks are building tokenization infrastructure. Stablecoin legislation continues advancing across major jurisdictions. Institutional adoption no longer sits at the fringe.
Still, Peirce leaves behind a clear regulatory record.
For years, she pushed back against regulation through enforcement. She argued that uncertainty weakens both innovation and investor protection because companies struggle to build compliant products when the rules remain unclear.
Many of the issues she raised directly affected fintech competition, startup capital formation, tokenization, crowdfunding, and investor participation. Her speeches consistently returned to the same core themes, such as open markets, proportional regulation, investor choice, and transparent rulemaking.
Peirce’s bluntest critique came during the long debate over regulation through enforcement, where she warned that private meetings with crypto firms cannot replace open rulemaking:
“It’s just not a good way of regulating.”
Her frustration with the SEC’s long delay on spot bitcoin funds became even clearer when spot bitcoin ETFs finally won approval after years of rejected applications:
“We squandered a decade of opportunities to do our job.”
Peirce’s Token Safe Harbor proposal became one of the most discussed crypto policy frameworks because it tried to give blockchain networks time to decentralize before full securities obligations applied.
Her public rulemaking philosophy also stood out in her University of Central Florida FinTech Summit remarks, where she urged regulators to approach innovation with both skepticism and openness instead of reflexive resistance. She later warned that poor engagement damages the relationship between regulators and innovators:
“We are scaring people off from coming in and having a conversation with us.”
Even when she defended innovation, Peirce did not argue for eliminating rules. In her statement on tokenized securities, she welcomed the promise of blockchain while drawing a hard compliance line:
“Tokenization may facilitate capital formation and enhance investors’ ability to use their assets as collateral.”
She also added the part many crypto promoters prefer to skip:
“Tokenized securities are still securities.”
That balance partly explains why Peirce maintained credibility across crypto markets and traditional finance circles. She supported innovation, but she also believed markets work best when participants understand the rules.
Her influence reached beyond crypto. Peirce consistently supported broader access to capital markets, regulatory transparency, and competition for smaller firms. Those priorities aligned closely with long standing NCFA positions on equity crowdfunding and capital markets modernization, fintech competitiveness, and proportional regulation for emerging companies.
Very few SEC commissioners become recognizable public figures outside securities law circles. Peirce did because she represented a different philosophy of regulation during one of the most contested periods in financial technology policy.
Her departure closes an important chapter at the SEC. But the larger debates around tokenization, digital asset infrastructure, market access, and programmable finance are now deeply embedded across global financial systems. Those discussions continue with or without Crypto Mom inside the building.
Peirce also engaged directly with the broader fintech and innovation community over the years, including participating in NCFA’s FFCON21: Breaking Barriers program.
On behalf of everyone at NCFA, we thank Hester Peirce for consistently contributing to open debate around innovation, competition, investor choice, and access to capital during one of the most important periods in modern financial market development. We wish her continued success in this next chapter.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 22, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Payments And Money Movement
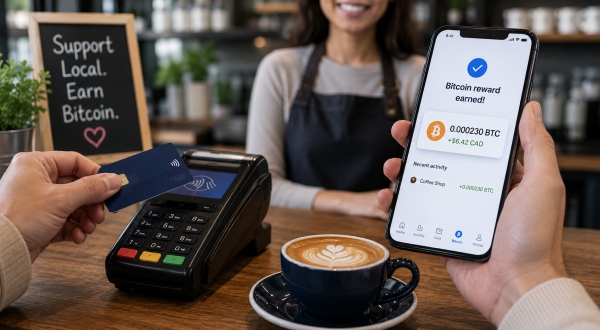
On May 21, 2026, Montreal based Shakepay opened the waitlist for its physical Shakepay Visa Prepaid Card and launched a 21 day campaign that turns everyday card payments into bitcoin rewards for customers and participating local businesses. The campaign builds on Shakepay’s Virtual Card, which the company says thousands of Canadians already use every week to earn bitcoin rewards on purchases.
Here’s how it works. Customers tap the Virtual Shakepay Card in store and earn points toward early access to the physical card. Those payments can also place local businesses on Shakepay’s campaign map. Businesses that sign up for Shakepay for Business during the campaign can claim bitcoin rewards after verification.
Shakepay is using rewards, merchants, and local campaign mechanics to push bitcoin into daily payment behaviour without asking customers or businesses to use bitcoin at checkout.
Jean Amiouny, CEO, Shakepay:
“Most rewards programs give people points they can only use inside someone else's system. We think Canadians should be able to earn an asset they can actually own,”
Shakepay is reframing rewards around ownership. Customers spend from their cash balance and earn rewards paid in bitcoin. That differs from closed loyalty points, which usually keep value inside one retailer, issuer, or rewards system.
Small businesses can explore bitcoin reserves without rebuilding payment acceptance or asking customers to pay with crypto. The bitcoin reward is tied to campaign activity and business onboarding, not direct bitcoin checkout.
The top 21,000 customers on the waitlist will receive early access to the physical card. The top 2,100 will be eligible for a Launch Edition card engraved with their waitlist rank. That gamified structure gives Shakepay a way to measure demand before full rollout.
The company says it helps more than 1.5 million Canadians access and use bitcoin through everyday financial products. Shakepay is a CIRO member, an Investment Dealer registered with the AMF, and a FINTRAC registered Money Service Business. They also recently became a member of Payments Canada. The Shakepay Visa Prepaid Card is issued by Peoples Trust Company under licence from Visa International Service Association.
Shakepay is testing whether bitcoin rewards can become a daily payments wedge in Canada. If the model works, bitcoin doesn't need to replace card rails to gain utility. It can ride on top of card spending, rewards, and small business treasury behaviour.
Will bitcoin adoption in Canada grow through direct crypto payments, or through familiar card and rewards products that make bitcoin part of everyday spending?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016