




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 22, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Payments And Money Movement, Capital Markets And Market Infrastructure
On May 21, 2026, Toronto based Cycles raised $6.4 million to build an open, privacy preserving clearing network for crypto markets and stablecoin payments. Blockchange Ventures led the round, with participation from Coinbase Ventures, Compound VC, Primitive Ventures, and angel investors. The round brings Cycles’ total funding to $8.7 million, following a $2.3 million pre seed in 2025.
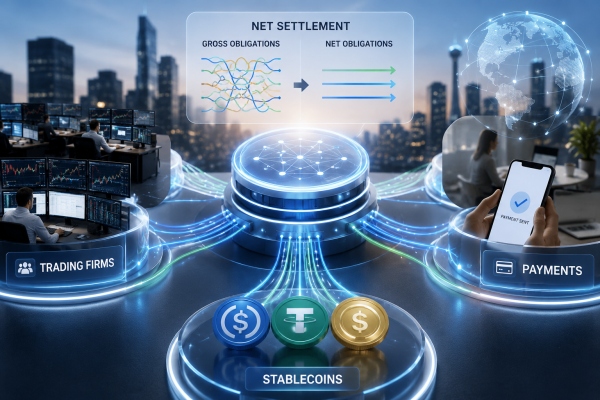
Cycles is targeting one of the least glamorous but most important parts of financial infrastructure: clearing. In traditional markets, clearing reduces how much money has to move between counterparties by offsetting obligations first. Cycles wants to bring that function to on chain finance, where trading and payment flows still often require too much prefunding and too much gross settlement.
The first institutional product is Cycles Prime, which lets trading firms privately net OTC obligations across the network. Cycles says this can reduce liquidity requirements and counterparty exposure without requiring collateral, asset movement, or a change in counterparties. Cycles Prime is launching with Lynq and FalconX as anchor partners.
Ethan Buchman, Co Founder and CEO, Cycles:
“Clearing is a financial superpower that has historically only been available to large financial institutions,”
Without clearing, firms often move full payments back and forth instead of only settling the difference. That ties up capital and can increase risk when markets move quickly.
The release points to October 10, 2025, when more than $19 billion in crypto leverage was liquidated in roughly one day, with 70% of forced liquidations occurring in just 40 minutes. Cycles uses that event to show why capital efficiency matters. When markets rely on gross settlement and heavy prefunding, stress can move fast.
Cycles is betting that multilateral clearing can reduce that pressure. Meaning, many obligations can be matched against each other so less money has to move. If it works, trading firms may keep less idle capital parked across venues and counterparties.
The second product is Cycles Pay, a stablecoin payments app for individuals and businesses. Payments are routed through Cycles’ clearing engine, which nets obligations across participants to minimize capital movement. The product also includes invoicing and expense management with credit planned.
Stablecoins already help move value across networks. Clearing can make those flows more capital efficient. For businesses, the value isn't only faster payment. It's fewer trapped balances, better cash flow, and more private settlement.
Rob Schmults, General Partner at Blockchange Ventures:
"Clearing is the cornerstone of capital-efficient markets like foreign exchange allowing the movement of massive volumes of value without crippling liquidity requirements. We see Cycles providing an essential coordination layer to bring the efficiency and effectiveness of clearing to new markets. Doing this will allow businesses to clear and settle payments privately, optimize capital flow, and reduce the need for idle capital. As global adoption accelerates, Cycles can become a category defining standard for how value is settled and netted across entire ecosystems and markets."
If stablecoins are becoming payment rails, will clearing become the missing layer that turns on chain settlement from fast movement into capital efficient market infrastructure?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 20, 2026 | NCFA Resource | Regulation And Policy, Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization

On April 20, 2026, the UK Financial Conduct Authority published its Innovation Insights 2025 report (20 page PDF). The report gives fintech founders, investors, and policy teams a practical view of where capital, regulatory testing, and market demand are concentrating across AI, digital assets, stablecoins, tokenization, RegTech, open finance, embedded finance, and operational automation.
The FCA points to a more disciplined phase of fintech, where firms need clear customer value, stronger controls, earlier regulatory engagement, and credible deployment plans.
The report combines global fintech investment data with activity across FCA innovation services, including the Regulatory Sandbox, Innovation Pathways, Digital Sandbox, AI Lab, Supercharged Sandbox, Smart Data Accelerator, and Scale Up Unit.
The overview gives operators a clean read on regulated fintech demand. AI, distributed ledger technology, open banking, and open finance ranked among the main technologies used by applicants. The FCA also launched new support channels in 2025, including a stablecoins cohort.
Regulated fintech no longer wins on novelty alone. Better products need stronger evidence, safer testing routes, sharper governance, and a realistic route from pilot to production.
This resource is useful for fintech founders, investors, compliance teams, financial institutions, policymakers, accelerators, digital asset firms, AI builders, RegTech vendors, and open finance teams tracking where regulated innovation is gaining traction.
It is especially useful for firms building around AI governance, stablecoins, tokenization, compliance automation, open finance, embedded finance, and supervised testing models.
The report is strong on investment patterns, regulatory engagement, sector demand, and FCA innovation service activity. It helps founders and investors see which fintech themes are attracting capital and which models need earlier regulator dialogue.
Its limit is the report doesn't provide a full outcomes study on sandbox firm performance, revenue growth, compliance cost reduction, productivity gains, fraud reduction, or investor returns. It works best as a regulatory market map, not proof that any one fintech category will outperform.
Canada and other jurisdictions can still use the report as a benchmark. Faster testing routes, clearer engagement models, and stronger links between experimentation and responsible deployment are becoming competitive advantages in financial innovation.
FCA Innovation Insights 2025 (primary FCA report)
AI Agents Enter Governed Financial Workflows (AI governance and controls)
Tokenization Starts Looking Like Financial Infrastructure (tokenized market infrastructure)
Deloitte And Stablecorp Bring QCAD To Banks (Canadian stablecoin infrastructure)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 18, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Digital Assets Blockchain And Tokenization
On May 18, 2026, Tether announced a strategic investment in LemFi, a cross border payments platform serving people who live and work across borders. The investment is focused on integrating USD₮ as a settlement layer across LemFi’s key corridors, especially across Africa and Asia.
This is a separate from LemFi’s USD $53 million Series B, which was announced in January 2025. Tether wants USDT deeper inside remittance infrastructure, where payment companies manage liquidity, settlement, and payout timing.
Tether says LemFi serves senders in the UK, U.S., Canada, and Europe who move money to Africa and Asia. It also says the investment aims to replace multi day SWIFT chains with near instant, lower cost settlement. That is the market issue. Remittance platforms don't compete on app design, but how quickly money arrives safely, and at a fair cost.
Paolo Ardoino, CEO, Tether:
“Our investment in LemFi reflects our shared vision on how money moves across borders, prioritizing speed, cost, and transparency. By supporting LemFi’s growth and innovation roadmap, we are helping bring the benefits of a stable digital asset to more people who rely on remittances in their daily lives.”
The practical change is settlement. USDT is not being positioned only as a crypto asset for users to hold. Tether is backing a payments platform so USDT can help move value behind the scenes across active corridors, which is valued to not only senders but to PSPs, MSBs, and banks.
Faster settlement can reduce delays and working capital pressure. But stablecoins don't solve the whole corridor. Remittance providers still need fraud controls, sanctions screening, clear FX, customer support, licensing, and reliable local payout.
Ridwan Olalere, CEO and Co Founder, LemFi:
“Integrating USD₮ into our infrastructure brings us closer to that reality, enabling faster, cheaper, and more reliable financial services for the millions of people who depend on us every day,”
While the announcement doesn't disclose the terms of the deal like Tether’s investment size or rollout timing, the business case is clear enough.
If USDT settlement shortens settlement time or reduces banking friction, LemFi could improve corridor economics. The customer impact will depend on whether those gains lead to better pricing, faster payout, or more reliable transfers.
Stablecoin issuers are actively integrating into live payment flows and partnering with platforms that have users, corridor demand, and payout networks. Traditional providers will need to build, partner, or risk losing margin.
For fintech operators and investors, the key insight is that stablecoin remittances are becoming an infrastructure strategy.
As stablecoin issuers invest directly in remittance platforms, will banks and PSPs still control the economics of cross border payments, or will stablecoin networks capture more of the settlement layer?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 20, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Payments And Market Infrastructure
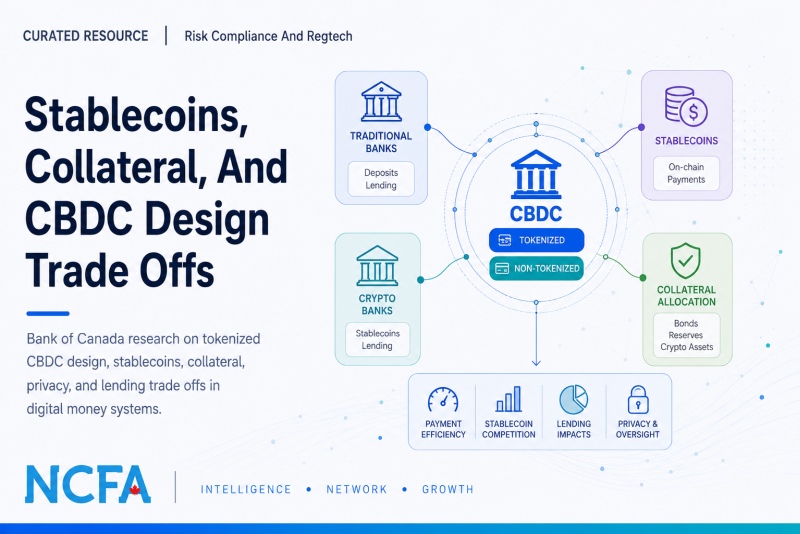
On May 7, 2026, the Bank of Canada published staff working paper 2026-14 on CBDC tokenization design. The paper looks at a financial system where traditional banks issue deposits, crypto banks issue stablecoins, and a central bank decides whether a CBDC should work through conventional accounts or programmable ledgers.
For fintechs, the useful part isn't the CBDC debate alone. The paper links tokenized money to collateral, stablecoin competition, privacy, crypto asset scarcity, and bank lending. Those issues are at the core of digital money infrastructure.
The paper compares tokenized and non tokenized CBDCs. A non tokenized CBDC competes with bank deposits in traditional payment markets. A tokenized CBDC works on programmable ledgers and competes more directly with stablecoins and tokenized settlement infrastructure in on chain markets.
The strongest finding is simple but important. Tokenization changes outcomes only when collateral use differs across sectors. The real question is which institutions hold the collateral, how reliable private money issuers are, and whether scarce reserve assets support payments or lending.
The model shows that tokenized CBDCs can crowd out stablecoins when crypto banks look less reliable and crypto assets are scarce. Non tokenized CBDCs can make more sense when crypto transactions offer less social value or when moving reserves from traditional banks to crypto banks improves the system.
The trade off is clear. CBDCs can improve payment efficiency, but they can also reduce bank lending when collateral moves away from traditional credit creation. That is where the paper becomes useful for fintech operators, not just policy teams.
The paper also raises a privacy question. A tokenized CBDC can run on a ledger that gives the central bank more visibility into transactions. That may improve oversight, but it can also reduce privacy. Digital money design is not just about speed or programmability. It also sets the rules for trust, control, and market access.
This resource is useful for fintech founders, stablecoin issuers, payment companies, banks, digital asset infrastructure providers, tokenization platforms, treasury teams, investors, and policymakers tracking the future of money.
It is especially relevant for firms building around programmable payments, stablecoin settlement, tokenized collateral, wholesale digital assets, bank issued digital money, or regulated crypto infrastructure.
The strength of this resource is the way it connects CBDC design to the financial infrastructure underneath tokenized markets. It doesn't treat CBDC as a simple retail wallet question. It looks at how money design affects collateral, settlement, stablecoins, bank deposits, crypto activity, and lending.
The paper also avoids easy answers. Tokenized CBDCs do not automatically improve the system. The result depends on collateral scarcity, crypto bank reliability, privacy settings, and the value of activity happening on programmable ledgers.
The limit is that this is an academic working paper with equations, model assumptions, and conditional results. Most operators will not read it end to end. The value is in the framework, not every technical section.
Used well, it helps fintech teams ask better questions about future money design. Who issues the money? What backs it? Where does collateral sit? What happens to lending? Who gets visibility into transactions? Those questions will matter as stablecoins, tokenized deposits, and central bank money keep moving into the same conversation.
Bank Of Canada CBDC Tokenization Paper (primary Bank of Canada working paper)
BIS Future Monetary System Blueprint (referenced framework for tokenized money and unified ledgers)
US Treasury Future Of Money Report (policy context for digital money and payment system design)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 19, 2026 | NCFA OpEd | Digital Assets Blockchain And Tokenization, Lending Consumer Credit And BNPL, Capital Markets And Funding
By Hudhaifah Zahid (Kode), Founder and CEO, Grynvault
Private credit has become one of the most important financial markets in the world because banks serve fewer borrowers, operators, and asset classes with the speed and flexibility the market now requires. That opening created room for faster capital, more specialized underwriting, and structures closer to the underlying cashflow.
Yet private credit still inherits the old problem: it prices long term real world risk through fiat benchmarks. A five year operating asset is often judged through short term rates, credit spreads, inflation assumptions, and currency movements that have little to do with the asset itself. The structure may be private, but the denominator is still public market money.
That is the part worth questioning. Private credit solved access to capital. The next step is better pricing of capital.
Every credit contract begins with a simple question: what is the correct cost of capital? In fiat finance, the answer usually comes from central bank policy, government bond yields, credit spreads, and lender appetite. Those inputs are useful, but they also shift constantly. A borrower can look good in one rate regime and weak in another. A yield can look attractive in one currency and ordinary in another. A nominal return can look safe while purchasing power quietly leaks away.
Private credit feels closer to reality because it touches actual businesses, equipment, vehicles, receivables, inventory, and property. But the moment every outcome is measured only in dollars, the same distortion returns. Did the investor earn a real return, or just more nominal units? Did the operator create value, or repay in cheaper currency? Did the asset perform, or did inflation cover the mistake?
This becomes sharper when capital crosses borders. A Canadian operator, a U.S. investor, and a global capital pool experience inflation through different currencies, costs, and policy cycles. Currency adds another layer of noise. The market can price the loan, the lease, or the receivable, but it still needs a cleaner way to compare performance across time and jurisdiction.
The usual benchmark global markets usually look at to help with pricing are U.S. Treasury bills (T Bills). They give investors a simple way to park cash, and earn what we call a “risk free” rate from which to calculate all new additional risks. However, that function is failing.
For a long time, U.S. government debt gave global markets a simple mental anchor. Investors could park capital, earn a nominal return, and treat that yield as the baseline for additional risk. But the more capital hides in short duration instruments, the less useful that baseline becomes for pricing long term productive assets. T bills may be useful for liquidity, collateral, and cash management. They do not answer whether a five year vehicle facility, equipment contract, or operating business receivable preserved purchasing power after inflation, currency movement, and settlement risk.
A short duration instrument is a weak mental anchor for five year plus productive finance. A vehicle facility, equipment contract, or operating business receivable carries usage risk, collateral risk, performance risk, inflation risk, and settlement risk. Those risks unfold over time. Pricing them against rolling short term yield can make the contract look rational while the purchasing power result remains unclear.
Private credit should earn a premium for doing hard work in the real economy. It sources, underwrites, monitors, services, and resolves. That premium becomes more durable when the market measures performance against a harder monetary benchmark instead of an unpredictable and inefficient baseline. So, what’s the alternative?
Bitcoin is a strong contender, as we lay out how a truer long term cost of capital can be derived from its use as a reserve asset in business. Its monetary and digital nature makes it easy to introduce into global deals, as just by having it in the portfolio, you are forced to ask: did our use of capital justify giving up Bitcoin exposure over the same period?
That question disciplines the contract. It forces the investor and operator to compare productive asset performance against scarce money. If the asset produces enough utility, cashflow, and settlement value, the deal deserves to exist. If it trails the monetary asset it displaced, the structure reveals weakness that fiat inflation and refinancing can otherwise conceal.
In practice, private credit often behaves like an arbitrage business. Capital is sourced at one cost, deployed at a higher expected return, and judged by the spread. That model works until the denominator weakens faster than the spread can compensate.
Let’s walk through an example of how we do this at Grynvault. Bitcoin changes the cost of capital function and can be used to more accurately price risks. Say that we are financing a $10,000 car. The operator brings $2,500 as a contribution, what would have been the down payment. A $625 is retained upfront as a program fee and $1,875 is placed into a Bitcoin linked reserve and we start collecting a fixed amount of roughly $212.50 per month for 60 months. At a Bitcoin price of $100,000, that reserve equals 0.01875 BTC.
At the end of the contract, the reserve helps discover the final cost of capital. If Bitcoin is flat or down, the operator receives the value of the original Bitcoin linked reserve based on the settlement price, and their effective cost reflects that outcome. If Bitcoin rises by 1.5x, the $1,875 reserve becomes $2,812.50. Based on a Bitcoin denominated rebate formula and full operator performance, roughly $1,997 could be rebated to the operator, with the remaining upside strengthening investor returns.
The rebate remains performance based and discretionary within the structure. The operator earns it by making payments on time, preserving the asset, and completing the contract properly. This keeps the fixed payment asset use experience intact while allowing the final settlement to behave like a variable cost of capital priced against Bitcoin’s monetary performance instead of central bank rates.
For investors, the base case remains asset backed cashflow. The Bitcoin reserve adds a long term settlement layer that can improve outcomes while keeping volatility out of monthly payments. Where permitted, return of capital mechanics can also make the cashflow profile more tax aware, with final economics recognized at settlement according to the applicable structure and jurisdiction.
Traditional financing often places the operator and investor on opposite sides of the same rate. If the investor earns more, the operator usually pays more. If the operator pays less, the investor usually earns less. A Bitcoin linked reserve changes that relationship because part of the outcome comes from the monetary layer rather than only extracting more from the user of the asset.
The operator keeps a fixed monthly payment and can earn a lower final cost through performance. The investor keeps access to real asset cashflow and can earn additional upside through the reserve. Weak performance limits the operator’s benefit. Strong performance creates room for a better settlement. The contract becomes a score the operator can improve instead of a price frozen forever at origination.
That is the deeper private credit implication. Bitcoin allows a facility to separate operating affordability from final cost discovery. Monthly payments can stay boring while the settlement layer captures the truth of time, performance, collateral quality, and monetary appreciation. This alone exemplifies good pricing and long term thinking.
Private credit investors are usually paid for taking illiquidity, complexity, and credit risk. Over long horizons, they also need protection from monetary erosion. A portfolio can show a healthy nominal yield and still fail to preserve purchasing power if the denominator weakens faster than expected.
A Bitcoin linked reserve gives private credit a way to hold part of the economics in scarce money while the operating asset continues to produce local currency cashflow. That combination is the bridge. Fiat remains useful for monthly payments, taxes, insurance, servicing, and regulatory compliance. Bitcoin strengthens the long term settlement value.
This is especially relevant for cross border capital. Investors can fund productive assets in one jurisdiction while monitoring part of the performance against a global monetary benchmark. Operators can keep paying in the currency they earn. The facility can report both views. The local economy gets capital, while investors receive a cleaner purchasing power lens.
Canada is a strong place to build this category because the need is practical. Small businesses, dealers, operators, and asset owners need flexible capital. Investors need yield that survives inflation. Fintech platforms need structures that are transparent, compliant, and grounded in real cashflow.
The opportunity is to bring Bitcoin into private credit as pricing infrastructure. That means disciplined underwriting, real collateral, conservative servicing, clear reporting, careful custody, and settlement rules that align incentives. The market needs productive finance measured against better money, built with real collateral and transparent settlement rather than synthetic yield.
Grynvault is one attempt to build that bridge. Start with a real asset. Pay the seller cleanly. Give the operator fixed payments. Hold a Bitcoin linked reserve beside the contract. Reward performance at settlement. Use the remaining upside to strengthen investor returns. Report the economics in both local currency and Bitcoin terms.
The old private credit premium was illiquidity. The next premium may be monetary discipline. The platforms that win will price risk across borders more clearly, protect long term purchasing power more intelligently, and turn sound money into a practical advantage for productive finance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 18, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Digital Assets Blockchain And Tokenization
On May 18, 2026, Paytrie enabled CADC stablecoin powered remittances from Canada to international markets, beginning with Mexico and Nigeria. A Canadian sender starts in Canadian dollars. Paytrie uses CADC as the Canadian dollar stablecoin bridge, converts into USDC through liquidity providers, and then uses Circle Payments Network for local currency payout.
CADC is being used inside a live cross border remittance corridor, with a Canadian dollar starting point and global stablecoin infrastructure behind the payout.
Recent Canadian stablecoin activity includes Loon’s CADC acquisition, QCAD adoption work, and policy debate around a domestic stablecoin framework. This launch is different because it connects CADC to an outbound remittance flow.
Jason Tong, CEO, Paytrie:
“For the first time, a Canadian dollar stablecoin is being used to help power fast and affordable remittances from Canada. CADC gives Canadians a familiar Canadian dollar starting point, while USDC and global stablecoin infrastructure help move value across borders more efficiently.”
Most stablecoin payment activity is still tied to U.S. dollar tokens due to liquidity, distribution, and network support. Canada has a different need given that Canadian users and businesses earn, bank, invoice, and plan in Canadian dollars. A CAD stablecoin can reduce friction at the first mile before funds enter a global corridor.
CADC acts as the Canadian dollar bridge. USDC carries the payment through Circle Payments Network before payout in the recipient’s local currency. That keeps CADC close to the Canadian user and uses USDC where global liquidity is needed most.
CAD pegged stablecoins don't have to compete with USD stablecoins everywhere. They can support Canadian dollar funding, treasury, settlement, and corridor access at the point where Canadian payment flows begin.
Families need funds to arrive quickly, safely, and at a fair cost. Senders need clear pricing. Recipients need local currency in a bank account without having to handle crypto directly.
For PSPs and MSBs, the corridor still needs the hard parts of payments. Onboarding. Sanctions screening. Fraud controls. Refund handling. Customer support. Local payout partners. Stablecoins can reduce settlement friction, but they don't remove the need to operate the full payment workflow.
Circle Payments Network positions stablecoins as institutional payment infrastructure, not a retail crypto app. Circle says the network supports 24/7 near instant settlement and uses a compliance first architecture where partners are vetted for licensing, regulatory compliance, operational risk, and security.
That's a strong signal for Canadian payment providers. Stablecoin remittances are starting to look like a settlement option for regulated firms. If the model works, banks and PSPs will need to decide whether to build, partner, or risk losing international payment flows to faster specialist rails.
The treasury angle is just as important. Stablecoin corridors can reduce the need for some prefunded local accounts. That can improve working capital and speed up payouts. It also adds new questions around liquidity, FX spreads, counterparty exposure, and more.
For Canadian fintechs, banks, and PSPs, the read is direct. CAD stablecoins may not win by competing head on with USD stablecoins everywhere. They may win by making Canadian dollar entry, treasury, and settlement flows easier to connect to global stablecoin networks.
If CAD stablecoins become the Canadian dollar entry point into global payment networks, which firms will control the customer relationship, FX economics, compliance layer, and payout corridor?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 15, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Payments Rails And Market Infrastructure, Regulation And Policy
On May 7, 2026, the Bank of Canada published staff research on global cryptocurrency flows. The paper looks at why crypto moves across borders, using Bitcoin flow data across up to 162 countries and testing whether key findings also appear across major stablecoins.
It's a practical resource for fintech teams trying to understand where digital assets connect to remittances, payment friction, macro stress, capital controls, sanctions, and financial system gaps.
The paper uses Chainalysis data to study cross border crypto flows from 2020 Q3 to 2023 Q3. The authors focus on Bitcoin first, then extend the analysis to USDT, USDC, BUSD, and DAI. That makes the research useful for teams that need to separate market noise from real cross border usage patterns.
Crypto flows don't always behave like traditional capital flows. The paper finds that crypto activity can rise when macro conditions weaken, when financial systems work poorly, or when people need cheaper and faster ways to send money across borders.
Payment firms, remittance providers, banks, stablecoin companies, and compliance teams should take note. Crypto rails often gain relevance where traditional rails feel costly, slow, restricted, or unreliable.
The paper also helps explain why stablecoins are becoming more prominent in payments and treasury conversations. If stablecoin flows follow similar cross border patterns to Bitcoin in key areas, policymakers and market builders can't treat them as only crypto assets. They need to assess them as financial infrastructure.
For Canadian fintechs, if users, businesses, and institutions adopt digital rails for real cross border needs, firms need to know where those rails improve service, where they create risk, and where regulators may focus next.
This resource is useful for fintech founders, payment companies, remittance providers, stablecoin infrastructure firms, crypto platforms, banks, AML teams, policy analysts, market infrastructure providers, and investors tracking financial system modernization.
It's especially relevant for teams working on cross border settlement, digital wallets, treasury tools, programmable payments, blockchain analytics, custody, transaction monitoring, and compliance operations.
The strength of this paper is scope. It compares crypto flows across a large country sample and tests several possible drivers instead of relying on one simple adoption story. The authors look at macro conditions, financial system quality, remittances, institutional quality, capital controls, and sanctions.
The paper also avoids a common trap. It doesn't treat all crypto activity as speculation. It shows how payments, remittances, and financial stress can help explain real cross border usage.
The limit is data construction. Cross border crypto flow analysis still depends on attribution methods, exchange activity, web traffic estimates, and assumptions about where users are located. The authors discuss those limits clearly. The paper is also Bank of Canada staff research, not an official Bank of Canada policy position.
For fintech teams, the best use is practical benchmarking. Use it to understand why crypto rails gain traction, where stablecoins may keep growing, and which risks regulators are likely to monitor more closely.
Bank of Canada Staff Working Paper 2026-15 (primary research paper on global cryptocurrency flows)
Patterns And Determinants Of Global Cryptocurrency Flows PDF (full paper with methodology, data, and empirical results)
BIS Project Atlas (global work on mapping crypto and DeFi activity)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016