




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 15, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Payments And Market Infrastructure, SME Finance And Business Banking
On June 15, 2026, Montreal based Nuvei announced a definitive agreement to acquire Payoneer for approximately $2.75 billion ($7.40 per Payoneer share in cash). The companies expect the transaction to close in mid 2027, after Payoneer shareholder approval, regulatory approvals, and other closing conditions.
If completed, the combined company expects about $3 billion in annual revenue. It also expects to process more than $500 billion in annual payment volume and serve over 2.4 million customers across more than 190 countries and territories.
While the price tag will certainly get some attention. The stronger story is what Nuvei is buying. Payoneer brings cross border payouts, multi currency accounts, marketplace reach, banking connectivity, regulatory approvals, and access to businesses that operate globally every day.
Payment processing is only one part of global commerce. Businesses also need to collect funds, hold balances, convert currencies, pay suppliers, settle marketplace earnings, and manage funds across borders.
Payoneer has spent two decades building that infrastructure. Its customers operate across Amazon, Walmart, Airbnb, Fiverr, Etsy, Upwork, Shopify, WooCommerce, eBay, ByteDance, and other global platforms. These businesses don't just need checkout tools. They need financial rails that help them operate in multiple currencies and jurisdictions.
Payoneer also brings regulated market access. The announcement highlights online payment licensing in mainland China and authorization in principle as a cross border payment aggregator in India under the Reserve Bank of India framework. That kind of access is tough to replicate. It takes capital, local knowledge, compliance depth, and time.
Nuvei connects businesses to local acquiring, alternative payment methods, risk tools, fraud management, and merchant services. Payoneer is closer to the operating side of international commerce. It helps businesses receive earnings, manage currencies, send payouts, and use global banking networks.
Together, the companies can cover more of the financial workflow. A merchant may start with payment acceptance. Then it may need supplier payments, foreign exchange, treasury tools, card issuance, marketplace settlements, or embedded financial services.
A provider that manages more of the money flow earns a stronger role in daily operations, otherwise a payment processor alone may just lose a merchant at renewal.
The expected combined scale gives Nuvei a larger role in global commerce infrastructure. It also puts the company in a different competitive conversation.
Nuvei is no longer competing only as a payments processor. It's trying to become a broader platform for acceptance, payouts, settlement, treasury, FX, and embedded finance. Merchants and platforms increasingly want fewer providers handling more of their financial operations. They want simpler workflows, cleaner reconciliation, faster settlement, and stronger compliance across markets.
That matters because every additional financial provider adds complexity. Merchants must reconcile transactions across multiple systems, manage separate compliance requirements, monitor third party risk, and track funds moving through different settlement networks. As Canadian payment rules place more weight on payment service provider operational risk and incident response rules, businesses have greater incentive to reduce handoffs and work with providers that can handle more of the process inside one platform.
For Canada's fintech ecosystem, the deal shows where value often forms behind the scenes. Some of the most important fintech companies are not consumer brands. They are infrastructure firms embedded behind marketplaces, exporters, software platforms, and global merchants. The acquisition also fits the larger opportunity in NCFA's Financial Innovation Map, where payments, data, digital assets, capital markets, and financial infrastructure are becoming more connected.
As payments, payouts, treasury services, FX, and embedded finance come together, will businesses keep using separate financial providers or choose platforms that manage the full flow of money across borders?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Jun 15, 2026
Image: Unsplash/Sasun Bughdaryan
More and more Canadians are no longer leaving the business of cross-border acquisitions to institutional investors, and they are increasingly relying on technology to simplify international purchases. Whether accessing real estate market data and analyses or taking a virtual walk through properties, the evolution of PropTech has significantly altered how investors can scout, assess, and acquire assets abroad.
The appeal is evident: Investors can browse neighborhoods, compare yields, and contact service providers from their own homes, without needing to travel. Technology has helped overcome many of the conventional barriers of purchasing overseas real estate.
However, technology is only one component of the equation, and the key to making the right decision still lies with a deeper understanding of the market and local expertise.
There are a number of things that make America attractive. Firstly is scale: you have thousands of cities, many with their own driving forces, their own pricing structure, and rental possibilities. Secondly, many areas in the US have an entry price point that is lower than in the large Canadian metro cities; diversified investors can find regions that offer higher cash flow potential and a wider array of inventory to choose from.
Thirdly is the diversity of the economies, so in one city there could be employment growth from the medical field, another from technology, and another from tourism: these provide diversification across sectors, reducing concentration of risk.
Fourth is movement of currency; at various times favorable exchange rates can make buying opportunistic in US real estate and encourage purchasing. Fifth and perhaps most importantly, many investors recognize US property for long-term wealth accumulation as well as supplementing their existing real estate holdings in Canada.
PropTech has dramatically changed the way that investing is performed. Researching a foreign market used to involve many trips and scarce data points.
Digital platforms now allow immediate viewing of market statistics, population reports, rental data, and transaction records. This allows investors to view options from home and pre-qualify their search before proceeding. AI allows investors to take advantage of predictors that indicate growing jobs, rental rates, and infrastructure developments. Electronic document systems further streamline transaction processes by allowing contracts, disclosures, and loan documents to be viewed and electronically signed.
Virtual property tours enhance accessibility and allow buyers to view a property and area without actually going there. PropTech has given Canadians an experience with investing in American property that can now be performed more quickly and knowledgeably than ever before.
Image: Unsplash/Jakub Żerdzicki
Property intelligence – Data is quickly becoming one of real estate’s most prized assets. Canadian buyers are reviewing population migration trends, job numbers, school scores, and investment in infrastructure before choosing where to buy. There are fewer assumptions and more calculations involved. Rental performance indicators offer data to gauge anticipated occupancies, average rents, and overall income for a property.
Many also follow the number of building permits issued as a predictor of market confidence or for the impact that a build may have on supply. Statistics surrounding migration give further data points for regions experiencing an influx from those new to the workforce or in retirement.
News about business expansion, road improvements, or the number of crimes are all part of the picture. This approach eliminates the assumptions—there's a data-driven reason to consider some markets over others before other investors catch on.
We have a powerful arsenal of technology. Technology alone will not replace ground-level knowledge, though. As Jeff Tricoli, the prominent Southeast Florida real estate broker, puts it:
"I believe real estate is built on clarity, trust, and education. We guide clients with market insight. So every decision is informed and not speculative in manner."
However, technology cannot solve all issues. Cross-border taxation, for instance, is still a thorny subject. Investors need to be able to familiarize themselves with disclosure rules, ownership, and potential liability in two different countries.
Financing can also be tricky. Banks lend at different rates and have different criteria, and one might not be able to get good terms without more extensive paperwork. The law varies by state. Each has its own set of laws regarding what a landlord may and may not do, how to evict, and what must be disclosed to the tenant. Another problem has to do with interpreting data. The internet can flood you with information, but if you don’t interpret it correctly, you may end up making a mistake.
The market is another quick-changing variable. One that appears robust today might not be tomorrow if some new economic trend or government action destabilizes it. Ultimately, human acumen is still important. Networks of local experts—lawyers, accountants, brokers, and the like—still matter for a successful deal. Technology, in the absence of it, is certainly not a replacement for diligent investigation.
It is also reasonable to assume that PropTech will continue to evolve and exert influence. The predictive capabilities of artificial intelligence could be enhanced in such a way that investors know which neighborhoods will perform best. They will also happen to be the neighborhoods that will be in most demand in the future.
The use of blockchain will undoubtedly streamline transactions, as well as increase security with records. It is likely that data will also be more thoroughly integrated. Investors could be provided with a suite of not only market analysis tools but also financing, legal advice, and property management information.
Interest from Canadians remains strong because the United States offers size, variety, and scope for portfolio growth.
Proptech has changed the way investors look at cross-border transactions. Data analytics, virtual tours, prediction technology, and online platforms allow for easy research and access to investments.
However, tech is not a total substitute for local experience and knowledge. Legal, tax, financing, and neighborhood issues require local input. Hope this read helped you and best of luck on your journey in this way.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 14, 2026
Family-owned businesses across Canada offer a strong opportunity for entrepreneurs because many are already profitable, trusted locally, and ready for ownership transition. Instead of starting from zero, buyers can acquire an established business with customers, staff, systems, and reputation already in place, especially as more owners consider retirement or succession.
Family-owned businesses play an important role in Canada’s economy. They often operate in local communities for years or even decades, serving loyal customers and building strong reputations through consistent service and personal relationships. Many are owner-operated businesses where trust, reliability, and long-term commitment matter just as much as the products or services they provide.
For buyers, this creates a significant advantage. A family-owned company in Canada may already have an established customer base, experienced employees, dependable supplier relationships, equipment, and stable revenue. It may also benefit from a recognizable local brand and years of goodwill within the community. These are valuable assets that usually take considerable time and investment to develop from scratch.
For entrepreneurs researching acquisition opportunities, Canadian business for sale on Yescapo can be a useful starting point for finding established companies with existing operations, customer relationships, and market history. Instead of buying only physical assets, buyers gain access to business knowledge, working systems, and relationships that have often been built over generations.
This is particularly important in industries where reputation drives success. Local retailers, construction companies, restaurants, service providers, and manufacturing businesses often rely on repeat customers and word-of-mouth referrals. A well-established family business may therefore offer a competitive position that would be difficult and expensive for a new startup to achieve.
One of the biggest opportunities in Canadian family businesses comes from succession. Thousands of owners are approaching retirement after spending decades building successful companies, yet many do not have family members interested in continuing the business. Children may choose different careers, relocate, or simply prefer not to take on the responsibilities of ownership.
As a result, many profitable businesses enter the market despite having healthy financial performance and loyal customers. They are being sold not because they are struggling, but because the owner wants to retire, reduce day-to-day responsibilities, or ensure the company continues under new leadership.
For entrepreneurs, this creates a unique entry point into business ownership in Canada. Buying a family-owned business with established operations can provide immediate access to customers, revenue, trained staff, and existing systems while avoiding many of the challenges involved in launching a company from zero.
Understanding the seller’s motivation is an important part of the process. In succession transactions, owners often care deeply about preserving the company’s reputation, protecting employees, and maintaining relationships with long-standing customers and suppliers. Buyers who respect that legacy and present a clear plan for the future may find it easier to negotiate a successful acquisition and ensure a smoother transition after the sale.
Starting a new company usually means building everything from the ground up. The founder must test demand, find customers, create systems, hire staff, develop supplier relationships, and survive the early stage when cash flow is uncertain.
Buying a family business in Canada offers a different path. The buyer can study real financial records, customer history, contracts, equipment, employee structure, and market position before making a decision. This makes the process more practical and less based on assumptions.
A startup may offer full creative freedom, but it also carries higher uncertainty. A family business may come with older systems or traditional ways of working, but it also provides an existing customer base and proven business model.
For many buyers, the question is simple: why build market trust from zero when an established business for sale in Canada may already have it?
Family businesses are often attractive because they are built around long-term relationships. Many have repeat customers, local recognition, supplier trust, and employees who understand the business well. This can make the transition easier for a new owner.
Another advantage is stability. Many Canadian family businesses operate in practical sectors such as trades, retail, food, manufacturing, distribution, professional services, hospitality, and local services. These businesses often solve everyday needs rather than depend on trends.
A buyer may also find hidden growth potential. Some family businesses are profitable but underdeveloped digitally. They may have weak websites, limited social media, no online booking, outdated branding, or little paid advertising. A new owner can modernize the business without changing its core.
This is why many investors search for profitable businesses for sale Canada listings. They want companies that already work, but still have room to grow.
Family-owned businesses can be found across many industries and provinces. Some operate in large cities such as Toronto, Vancouver, Calgary, Montreal, and Ottawa. Others are based in smaller communities where local trust is especially important.
Common examples include restaurants, cafés, bakeries, convenience stores for sale, construction companies, repair shops, cleaning businesses, accounting firms, dental or wellness clinics, manufacturing companies, logistics businesses, landscaping companies, and specialty retail stores.
Buyers often look for businesses that are simple to understand and have steady demand. A local business for sale Canada opportunity may be attractive if it has repeat customers, reliable employees, clean financial records, and clear room for improvement.
Businesses with recurring revenue can be especially valuable. Examples include maintenance companies, B2B services, subscription-based services, commercial cleaning, bookkeeping, and companies with long-term contracts.
Retiring business owners are one of the main reasons family business transition is becoming important in Canada. Many owners have strong companies but no clear successor. They may be ready to step back, but they do not want the business to disappear.
This can create a more flexible acquisition process. Some sellers may agree to stay involved during a transition period, introduce the buyer to customers and suppliers, and train the new owner. This helps protect business continuity.
For buyers, this is valuable because the seller’s knowledge is often one of the most important assets in a family business. Understanding customer relationships, staff dynamics, supplier terms, and daily operations can reduce risk after the sale.
A good transition plan can make the difference between a smooth acquisition and a difficult one. The best deals usually include clear handover support, communication with employees, and a plan for preserving customer trust.
Before buying a family-owned business, due diligence is essential. The buyer should review financial statements, tax records, revenue trends, profit margins, debts, leases, supplier agreements, employee contracts, equipment, inventory, licences, customer concentration, and legal issues.
It is also important to understand how dependent the business is on the current owner. Some family businesses rely heavily on the founder’s personal relationships. If customers only trust the owner, revenue may fall after the sale unless the transition is handled carefully.
A buyer should also check whether family members work in the business and what will happen after the acquisition. Staff roles, responsibilities, salaries, and expectations should be clear before the deal is completed.
Buying an established business in Canada can be a strong opportunity, but only if the buyer understands the real numbers, the risks, and the operational structure.
Many family businesses have strong foundations but outdated systems. A new owner can often grow the company by improving marketing, technology, pricing, customer service, and operations.
For example, a local service company may have loyal customers but no strong online presence. A buyer could improve the website, SEO, Google Business Profile, paid ads, online reviews, and booking systems. These changes can increase leads without changing the core service.
A retail business might benefit from e-commerce, better inventory management, updated branding, or stronger social media. A B2B company could grow by improving sales processes, customer follow-up, and recurring contracts.
The opportunity is not always about changing the business completely. Often, it is about keeping what works and modernizing what holds the company back.
Many buyers assume they need the full purchase price in cash, but business acquisition Canada deals can be structured in several ways. Buyers may use personal savings, bank financing, investor capital, seller financing, or a combination of these.
Seller financing can be especially relevant in family business succession. This means the seller allows the buyer to pay part of the price over time. It may help the buyer complete the deal and give the seller confidence that the new owner is committed to the business.
Some deals also include an earn-out, where part of the final payment depends on future performance. This can be useful when the seller and buyer need to bridge a valuation gap.
Clean financial records make financing easier. A profitable small business Canada opportunity with strong documentation is usually more attractive to lenders and investors than a business with unclear accounts.
Family businesses can be excellent acquisitions, but they are not risk-free. Some may have outdated systems, informal agreements, weak financial reporting, or operations that depend too much on the founder.
There may also be emotional complexity. A family business is often personal to the seller. Decisions about employees, branding, customers, and legacy may matter deeply. Buyers need to handle the process with respect and clarity.
Another risk is hidden underinvestment. Some owners delay upgrades before selling. Equipment, premises, technology, or staffing may need improvement after acquisition. Buyers should factor these costs into the purchase price.
The best approach is practical: verify the numbers, understand the people, check the contracts, and plan the transition carefully.
Buying a family-owned business in Canada can be a strong strategy for entrepreneurs who want an established company rather than a startup. It offers access to customers, revenue, staff, systems, and local reputation from the beginning.
This strategy is especially attractive for buyers who are good at operations, marketing, modernization, and relationship management. They can take a business that already works and make it stronger.
However, it is not the right path for everyone. Buyers need patience, due diligence, capital, and the ability to manage people and change. A family business may be established, but it still needs leadership.
For the right buyer, Canadian family businesses can offer one of the most practical routes into entrepreneurship through acquisition.
The hidden opportunity in family-owned businesses across Canada lies in the gap between retiring owners and entrepreneurs looking for established companies. Many of these businesses have customers, revenue, employees, reputation, and operational history already in place.
Instead of starting from zero, buyers can acquire a profitable local company and improve it through better marketing, stronger systems, digital tools, and modern management. The opportunity is not only to buy a business, but to continue its legacy and unlock its next stage of growth.
For entrepreneurs searching for Canadian business opportunities, family-owned businesses may be one of the most overlooked paths to ownership.
They often have loyal customers, local reputation, proven operations, trained employees, and steady revenue. This gives buyers a stronger starting point than launching a new company.
Business succession is the process of transferring ownership from the current owner to a new owner. In family businesses, this often happens when the founder retires or no family member wants to take over.
Buying can be better if the buyer wants existing customers, cash flow, and a proven business model. Starting may be better for someone with a unique idea or limited acquisition capital.
You should check financial records, tax documents, debts, leases, supplier agreements, employee contracts, customer concentration, licences, equipment, and how dependent the business is on the current owner.
Yes. Buyers may use personal funds, bank loans, investor capital, seller financing, or earn-out structures. Clean financial records usually make financing easier.
Common examples include restaurants, cafés, retail stores, construction companies, cleaning businesses, clinics, manufacturing companies, repair shops, logistics businesses, and local service companies.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 6, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Payments And Market Infrastructure, Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Regulation And Policy, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026).
Citi is combining traditional securities infrastructure with blockchain based issuance, custody, and settlement for private company equity. The launch adds another proof point that tokenized infrastructure is changing how markets operate, especially as banks, exchanges, and market operators compete to define how private assets move onto digital rails.
Digital asset access is being packaged for banks, brokerages, fintechs, and platforms that do not want to build the full crypto stack themselves. The control point is the embedded infrastructure that handles custody, liquidity, compliance, settlement, and connectivity behind the customer experience.
Tokenized real world assets are moving into bank distribution channels. DBS is turning physical gold into a digital product that can sit inside a retail banking app, while also testing institutional market access through its digital exchange.
Stablecoin supervision is moving from broad policy debate into operating rules. Issuers, custodians, exchanges, auditors, compliance vendors, and payment firms need to track how reserve custody, internal controls, audits, and service provider oversight become part of stablecoin market access.
Card networks are building trust infrastructure for AI driven payments. Visa’s updates add another network level proof point that identity, authorization, fraud controls, tokenized credentials, and settlement will shape how AI agents are allowed to transact.
Recurring payment rails are becoming a financial inclusion tool when they help users pay for digital services without relying on credit cards. Brazil’s Pix Automático data shows how local real time payment infrastructure can support subscriptions, platform access, and digital commerce growth.
Agentic payments are moving from checkout experiments into network infrastructure. Payment firms, AI platforms, stablecoin providers, banks, and identity vendors now have to solve authorization, spending limits, settlement, fraud controls, and liability for machines that can transact without a human at every step.
Large banks are building their own tokenized money infrastructure rather than relying on third party stablecoin networks. Payment providers, treasury platforms, and financial institutions now face a more competitive settlement environment as bank money, stablecoins, and tokenized commercial bank deposits compete for transaction flow.
Circle Payments Network continues to add distribution. Business accounts, treasury platforms, and payment providers are becoming part of the stablecoin settlement infrastructure rather than simply connecting to it.
Circle is extending its infrastructure footprint from stablecoins into Bitcoin collateral. Builders now have another institutional grade option for collateral and tokenized asset applications.
AI agents are moving from recommendation and discovery toward financial execution. Coinbase for Agents puts user controlled account access, payments, trading, and workflow automation into the same agentic finance conversation as network trust controls, stablecoin settlement, fraud prevention, and responsible AI governance.
AI supervision in finance is evolving from broad risk discussion toward operating practices for boards, senior management, compliance teams, model owners, technology vendors, and supervisors. Financial institutions need to track how governance, documentation, human oversight, cyber controls, and third party dependencies become part of responsible AI adoption.
Always-on markets need reference data that does not stop when traditional exchanges close. Exchanges, tokenized asset platforms, derivatives venues, market makers, and risk teams now have another pricing source to evaluate as real-world assets trade across crypto-native market infrastructure.
Prediction markets are starting to need the same financial plumbing as capital markets. Market makers, exchanges, payment providers, banks, and compliance teams now need infrastructure that can handle deposits, margin, settlement, risk controls, and regulated access without slowing down trading activity.
Prediction markets are moving from platform experimentation and court fights into formal rule design. Kalshi, Polymarket, DraftKings, Flutter/FanDuel, exchanges, market makers, compliance teams, sports leagues, and retail users now have a clearer process to debate which contracts belong in derivatives markets and which remain too close to gaming, misconduct, or public interest risk.
Financial crime compliance is increasingly becoming an existential regulatory issue rather than a supervisory issue alone. Payment firms, e-money institutions, fintechs, compliance teams, and investors should watch how regulators use governance, safeguarding, ownership, and financial crime controls as indicators of firm viability. The action signals that supervisory concerns can now lead to intervention measures that effectively remove a regulated firm's ability to continue operating.
Canada is pulling AI chatbots into platform safety regulation. AI firms, social platforms, trust and safety teams, identity providers, and compliance vendors should watch how age assurance, safety controls, reporting duties, and enforcement rules develop as digital safety becomes part of regulated online infrastructure.
Financial supervisors are beginning to treat AI as both a productivity tool and a threat multiplier. Banks, insurers, payment firms, fintechs, and security providers should expect greater scrutiny of fraud controls, cyber resilience, operational risk management, and third party technology oversight as regulators adapt supervision to an AI enabled threat environment.
Banking access is moving back onto the policy agenda as branch closures, digital exclusion, SME credit access, and local service gaps put pressure on financial providers. Banks, fintechs, credit unions, open finance firms, and data providers should watch whether the review leads to new access rules, credit data reforms, or stronger expectations around community banking infrastructure.
As advanced analytics become embedded in public institutions, governance questions increasingly extend beyond model performance. Procurement authority, accountability, oversight, operational dependence, switching costs, and public trust all influence how critical decision systems are adopted and maintained. The organisations that govern these systems may become as important as the organisations that build them.
The common thread is not AI, stablecoins, tokenization, or payments. It is access. Access to financial infrastructure, access to payment rails, access to private markets, access to banking services, access to digital assets, and increasingly access to machine driven financial execution. The next competitive battleground may not be who builds the best financial products, but who controls the rules, permissions, trust layers, and infrastructure that determine who can participate and under what conditions. Recent developments suggest those boundaries are on the move. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 12, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, Lending Consumer Credit And BNPL
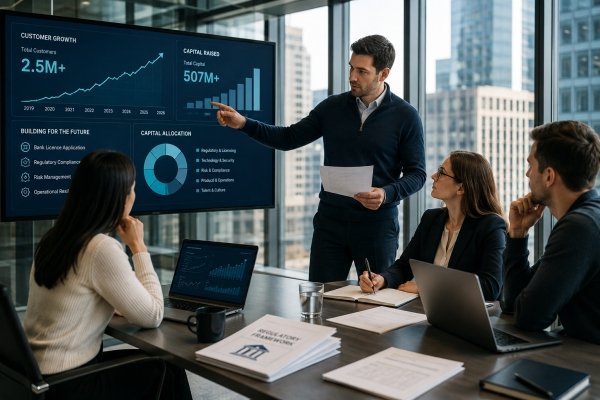
On June 11, 2026, KOHO announced a $130 million CAD financing at a $1.33 billion CAD valuation. KOHO says the capital will support growth and provide the initial capital base for a federally regulated bank, subject to ministerial approval. The round includes new investors Mubadala, Savano Capital, Shopify founder Tobi Lütke, and Affirm COO Michael Linford, with participation from Portage Ventures, Drive Capital, BDC Capital, HOOPP, and Eldridge. KOHO says it has raised $507 million CAD since launch and lists more than 2.5 million customers.
KOHO previously said it entered the second phase of acquiring a Canadian banking licence in January 2024, after raising an $86 million extension at an $800 million valuation and surpassing 1 million users.
The numbers have changed since that earlier milestone, but approval remains a federal decision. KOHO has added customer reach, capital base, and product depth behind its application. A bank licence requires proof of customer demand, not just capital strength, governance, risk controls, compliance systems, consumer protection, and trust. KOHO is trying to cross that line while still competing as a consumer fintech.
KOHO's round lands as OSFI prepares to launch a more defined path for targeted new entrants in June 2026. OSFI fast track approval framework analysis explains why the change is important for fintechs, challenger banks, and other firms with innovative banking models.
While the framework doesn't make approval easy, it offers eligible applicants a clearer route through the federal process while preserving prudential oversight. For fintechs, that is useful because demand for a product is not enough. A bank licence requires capital, governance, risk controls, compliance systems, consumer protection, and trust.
Questbank gives the KOHO story a recent Canadian benchmark. In November 2025, Questbank received approval to operate as a Schedule I bank after a six year approval process. KOHO is pursuing a different strategy, but the approval highlights that new federally regulated banking entrants can still emerge in Canada. That goes for international banking groups too like Santander who was approved by OSFI for a Canadian Banking License in 2025, after waiting for 6 years.
KOHO's financing follows two other large Canadian fintech disclosures. Wealthsimple raised C$750 million at a C$10 billion valuation in October 2025. nesto announced a C$302 million Series E at a C$1.47 billion valuation on June 10, 2026. KOHO followed one day later with a C$1.33 billion valuation.
Wealthsimple is pushing further into personal finance and banking style products. nesto is scaling mortgage and lending infrastructure. KOHO is putting new capital behind a federal bank licence effort. The same funding cycle is reaching different parts of financial services.
Customer growth and venture funding helped create Canada's latest generation of fintech firms. The next evolutionary question is whether firms that already have users and capital can obtain the regulatory permissions needed to participate more directly in deposits, lending, payments, and other core financial services.
KOHO has more than 2.5 million customers, a $1.33 billion valuation, and fresh capital earmarked for its bank licence effort. If customer scale and funding are no longer the hardest milestones, is regulated banking capacity now the real test for Canadian fintech competition?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 11, 2026 | NCFA Story Intelligence | Payments And Market Infrastructure
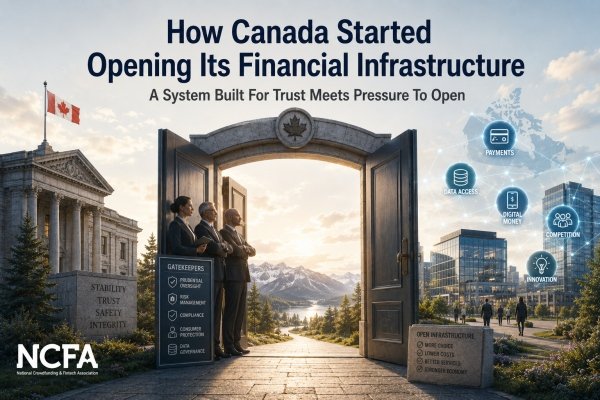
On June 3, 2026, Payments Canada announced that 15 organizations had joined its membership in 2026 following expanded eligibility rules. The latest intake included Beem Credit Union, Ebury Partners Canada, Shaype, Libro Credit Union, and Newton. Earlier additions included Wise Payments Canada, Float, KOHO, Neo Financial, Paramount Commerce, Brim, Meridian Credit Union, Tru Cooperative Bank, DoBusiness.com, and other newly eligible participants.
The membership announcement is the latest chapter, not the whole story. The story is how Canada moves from a tightly controlled payments model toward wider participation in the infrastructure that moves money, shapes competition, influences product design, and affects the choices available to consumers and businesses.
Canada builds its payments foundation around safety and trust.1 The Canadian Payments Association is created in 1980 under what is now the Canadian Payments Act. Payments Canada now owns and operates national payment systems including Lynx and the Automated Clearing Settlement System. The design reflects a clear priority: money movement is critical infrastructure, and critical infrastructure has to be reliable.
For a long time, that model works well enough for most people. Consumers trust their banks. Businesses use established payment tools. Settlement happens in the background. Most Canadians never need to think about who has direct access to the rails because the system mostly shows up as cards, transfers, bill payments, payroll, and cheques.
The market changes faster than the rails. Digital commerce grows. Mobile payments spread. Online transfers become a daily habit. Payments Canada’s 2025 trends report says Canada processed 22.5 billion retail payment transactions worth $12.2 trillion in 2024, with digital payments representing 86% of transaction volume.2
Fintechs start building around systems they can’t fully access. KOHO, Neo Financial, Float, Wise Payments Canada, Paramount Commerce, Brim, and Newton grow because customers want simpler financial products. The problem isn’t demand. The problem is that many new firms still depend on infrastructure controlled by others.
Competition becomes the pressure point. Critics of Canada’s payments model argue that control by a small number of large institutions has contributed to high fees, delay, and limited competition. Reuters reported this criticism when the Bank of Canada began payment service provider registration under the Retail Payment Activities Act.3
The fintech argument becomes practical. If firms outside the largest banks can’t connect on fair terms, they often need intermediaries, workarounds, sponsorship relationships, or slower product paths. That affects costs, margins, speed to market, and the ability to challenge incumbents with better consumer and business experiences.
Ottawa starts changing the legal frame. Finance Canada says amendments to the Canadian Payments Act made on June 20, 2024 expand Payments Canada membership eligibility to Bank of Canada supervised payment service providers, credit union locals that are part of a credit union central, and designated clearing and settlement system operators.4
The Bank of Canada brings PSPs into supervision. Under the Retail Payment Activities Act, the Bank registers and supervises payment service providers and focuses on operational risk, incident response, safeguarding end user funds, and reporting. As of September 8, 2025, PSPs must have risk management and funds safeguarding frameworks in place.5
Real Time Rail becomes the execution test. Payments Canada says the Real Time Rail is planned for launch in Q4 2026 and will support instant, data rich payments through a new exchange, clearing, and settlement system.6 The promise is simple: money should move faster, carry better data, and support new products.
The delays create frustration because the opportunity is real. Payments Canada selected Interac as the exchange solution provider in 2021, when the system was expected to launch in 2022.7 NCFA has tracked the execution question through RTR delay coverage and RTR productivity analysis.
The first wave of PSP members makes the policy visible. Payments Canada welcomes Wise Payments Canada, Float, KOHO, Paramount Commerce, and Brim as new payment service provider members in January 2026.8 NCFA tracks that moment when Payments Canada admits five new PSPs.
Membership is not only about access to rails. Payments Canada’s by law changes update membership requirements and support new eligible members as Canadian Payments Act amendments come into force.11 Membership gives new firms a closer role in the rules, standards, and modernization discussions that shape the system.
That changes the politics of infrastructure. A fintech that has to build around the system is one kind of participant. A fintech that can join, comply, learn the rules, and contribute to modernization discussions is another. The same applies to credit unions, FX firms, and other payment providers that want a role in Canada’s next financial infrastructure chapter.
Consumer driven banking brings the same access debate to financial data. Finance Canada says the framework is meant to let Canadians securely access and share financial data with financial service providers, without fees for accessing and sharing that data, while reducing reliance on risky practices such as screen scraping.12 The Bank of Canada says it will administer the framework so Canadians and businesses can securely share financial data with approved providers of their choice.13
But the friction does not disappear just because the law changes. Tier one banks, fintechs, data aggregators, and policymakers still have to work through scope, liability, accreditation, implementation timelines, commercial terms, and API performance. NCFA’s open banking commercialization roadmap frames the next phase as real API usage, accreditation, liability, and business model design, not just a policy announcement.
Stablecoins pull the payments debate into digital money. Bill C 15 gives Canada a legal framework for stablecoins and consumer driven banking, moving both into the financial policy stack. NCFA framed that moment in Bill C 15 gives Canada a digital finance framework.
The payment infrastructure question is no longer only about bank rails. Stablecoins, payment service providers, RTR, consumer driven banking, and Bank of Canada oversight are starting to occupy the same policy conversation. NCFA’s question post on stablecoins as payment infrastructure shows why digital money now belongs in the same access debate.
Canada’s payments story now connects directly to productivity. The Bank of Canada has warned that weak productivity threatens living standards, and NCFA has linked payments modernization to execution, competitiveness, and growth. Faster settlement, better data, lower friction, and more competition are not abstract infrastructure benefits. They affect how firms operate every day.
Cross border capability becomes part of the same test. Canada’s payment system cannot only work well at home. Canadian businesses, newcomers, exporters, marketplaces, and financial platforms also need better global money movement. That is why NCFA’s cross border payments analysis belongs beside RTR, open banking, and stablecoins.
Canada’s payments infrastructure didn’t turn a corner overnight. The change reflects years of modernization work, policy debate, fintech pressure, consumer demand, and the practical reality that a digital economy needs payment systems that are safe, fast, open enough to compete, and trusted enough to scale. The result is a more diverse payments membership base than Canada had a decade ago, with fintechs, PSPs, credit unions, FX firms, and digital finance companies gaining a larger role in the systems that move money.
Opening access isn’t the finish line. It’s the starting point. Canadian fintechs, banks, credit unions, payment providers, regulators, and infrastructure operators now have to prove broader participation can become better financial services. Now is the time to get to work. Launch Real Time Rail, make consumer driven banking usable, widen the tent responsibly, improve domestic and cross border capability, lower friction for merchants and consumers, and connect these reforms to the Canadian Financial Innovation Map and pipeline Canada needs to compete.
Canada's infrastructure modernization is creating new commercial opportunities in Consumer Driven Banking. See NCFA's Open Banking in Canada Opportunity Brief for the evidence trail, product pathways, competitive benchmark and commercialization outlook.
Which part of Canada’s payments story stood out most to you?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 20, 2026

Image: Unsplash/Headway
When did you last notice a sponsor banner on day three of a conference? Exactly. Multi-day events have a visibility half-life, and most brand strategies are not built to last beyond it.
The opening session energy is easy to ride. Sustaining brand presence through meals, breakouts, networking gaps, and general event fatigue is a completely different challenge.
Canada brought together close to 2,555 business events in 2025. The organizers who cracked visibility across all of that were doing something most were not. This article is about what that something looks like in practice.
Most event brands live entirely in the eyes. A logo here, a banner there, a branded tote bag everyone leaves behind on day two. The thing is, human memory does not work that way. People remember how a space made them feel far longer than they remember what it looked like.
This is where sensory marketing comes into play. When you own a scent in your registration lounge or a sound identity in your networking space, you are embedding your brand into the attendee's physical experience. Attendees may not consciously register it, but their nervous system does.
Pick one sense your brand can own consistently across all three or four days. A distinct coffee blend at your branded station. A low ambient sound identity in your lounge. Something tactile in your collateral that feels different from everything else on the table.
Consistency is what makes sensory branding stick. One well-chosen detail repeated across every touchpoint will outlast a dozen visually perfect installations that disappear into the background by midday.
Attendees build a mental map of your event space within the first few hours. Anything sitting in the same spot after that becomes part of the furniture. Your brand needs to travel with the crowd, not wait for the crowd to come back to it.
Think about where people already are. Breakfast queues, session transitions, charging corners, and the slow shuffle between keynote and lunch. Place something worth noticing in those pockets, and you are not interrupting anyone.
It does not have to be extravagant. Even something as simple as custom pens can do real work when placed at the right touchpoints across the event floor. Custom pens come in many forms, so think about your audience.
If you want something functional for a tech-forward crowd, business pens with a stylus are worth considering, notes Pens.com. If the setting is more formal, engraved pens would be a safer option.
Beyond that, rotate your brand presence between days. Move the activation, refresh the messaging, change the location. Give attendees something new to stumble into each morning.
A branded photo corner that was near the entrance on day one can migrate to the lunch area on day two. A product display that lived beside registration can reappear near the closing session. Movement creates the illusion of energy. It is this energy that keeps brands alive in people's peripheral attention.
Nobody wakes up on day two of a conference excited to visit a sponsor booth. But they will absolutely walk across a busy event floor to claim a reward or beat a leaderboard.
If your attendees skew younger, this is even more important. Conference News reported that 64% of Gen Z conference attendees actively seek immersive experiences with Instagrammable moments.
Give them a branded scavenger hunt with photo checkpoints. Build a leaderboard that updates in real time on a screen that everyone passes. Create a stamp card that unlocks something worth having at the end of day three.
The rewards do not need to be expensive. They need to feel earned. An exclusive backstage tour, early access to a session, or a branded item not available anywhere else at the event carries more weight than a generic goodie bag. When attendees are chasing something, your brand is what they are chasing.
Most brands show everything they have on day one. Full messaging, complete product story, every value proposition on the table before lunch. By day two, there is nothing left to discover, and attendees have mentally filed your brand away.
Flip that completely. Give attendees a reason to come back by leaving something unresolved on purpose. Day one, plant a question at your branded touchpoint. Something intriguing enough to linger. Day two, offer a piece of context that deepens it without fully answering it. Day three, deliver the payoff.
This borrows directly from the Zeigarnik Effect. It is a well-documented psychological principle showing that the human brain holds onto incomplete information far more stubbornly than resolved ones. An open loop in someone's mind is essentially a reservation your brand has made in their attention.
Practically, this could look like a teaser installation that changes each morning. A branded countdown with no explanation on day one. A partial reveal on day two. The full picture on day three.
Keep it visual, keep it simple, and make sure every element is unmistakably yours. Attendees will start talking about it, and that conversation is free brand visibility, traveling through every corner of your event.
Canada hosted approximately 2,555 business events in 2025, making it one of the busiest markets for professional gatherings in North America.
According to Conference News, 64% of Gen Z conference attendees prioritize immersive, Instagrammable experiences over traditional formats like panels and keynote presentations.
It is a psychological principle where incomplete information stays top of mind longer. Brands can use this to build multi-day anticipation among attendees.
| Strategy | Key Insight |
| Sensory Marketing | Brand recall builds faster when more than one sense is engaged |
| Moving Brand Touchpoints | Canada hosted ~2,555 business events in 2025, meaning competition for attention has never been tighter |
| Gamification | 64% of Gen Z conference attendees want immersive, Instagrammable experiences |
| Day-by-day Brand Storytelling | The Zeigarnik Effect proves incomplete narratives stay in memory longer than resolved ones |
Multi-day events are chaotic, exhausting, and exciting all at once. In the middle of all that, brand visibility can easily slip down the priority list. Keep it near the top. The strategies we mentioned in this piece are not complicated or expensive.
They just require some deliberate thinking ahead of time. Give your brand a plan that runs the full length of the event, and watch how differently attendees engage with it. The results are bound to speak for themselves.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016