




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


August 21, 2026
Employee benefits have undergone a quiet technological transformation. Not long ago, managing a health benefits plan meant paper forms, printed receipts, mailed claims, and significant administrative work for employers and employees. Over time, insurance providers digitized much of the process. Employees could submit claims online, access their coverage through a website, and eventually manage their benefits from a mobile device.
Today, another shift is taking place. The rise of digital financial infrastructure is making it possible for businesses to rethink not only how benefits are administered, but also what type of benefit they provide in the first place. Instead of purchasing a traditional insurance plan and paying recurring premiums to an insurance provider, some businesses are choosing a Health Spending Account, where the employer establishes a healthcare spending budget and employees are reimbursed for eligible expenses. This development is closely connected to the broader evolution of fintech.
Traditional employee benefits were built around an insurance model. An employer purchased coverage from an insurer, employees received a defined set of benefits, and claims were processed through the insurance provider. For decades, much of the administration surrounding that process was paper-based. Employees might fill out claim forms, collect receipts, submit documentation, and wait for reimbursement.
The internet gradually changed that process. Insurance providers began offering online portals where employees could submit claims electronically, view coverage details, and track reimbursements. Electronic payments replaced cheques, while digital records replaced much of the paperwork that had previously been required to administer a benefits plan.
The underlying insurance product remained largely the same, but the infrastructure surrounding it became digital. This was an important first step in the digitization of employee benefits, but it also raised a bigger question: if technology can digitize the administration of benefits, can it also change the underlying model?
Fintech has repeatedly demonstrated that digitizing an existing process is only the beginning. Payments are a good example. Businesses moved from cash and cheques to credit cards, online banking, electronic funds transfers, and automated payments. Accounting moved from desktop software and paper records to cloud-based platforms, while lending increasingly moved online, with applications, underwriting, and funding taking place digitally.
These developments created something more important than convenience: new financial infrastructure. Once the infrastructure exists, businesses can build entirely new products and services on top of it.
See:
The same thing is happening with employee benefits. Modern benefits platforms can connect employers, employees, financial institutions, and payment systems through software. Claims can be submitted digitally, reviewed electronically, and reimbursed through electronic funds transfer. Once these pieces of infrastructure exist, businesses have more options than simply purchasing a traditional insurance product.
This is where Health Spending Accounts become particularly interesting from a fintech perspective. A traditional health insurance plan transfers a defined set of healthcare risks to an insurance provider. The employer pays premiums in exchange for coverage according to the terms of the insurance policy.
An HSA takes a different approach. The employer establishes a defined healthcare spending allocation for employees, and employees submit eligible expenses for reimbursement, subject to the rules of the plan. Rather than purchasing an insurance product that provides a predetermined package of coverage, technology can provide the infrastructure needed to administer a defined healthcare budget.
This distinction opens up an entirely different model for employee benefits. The business can establish the amount it wants to make available, while employees have greater flexibility in how they use that benefit within the eligible expense rules.
The concept of giving employees a healthcare spending allowance is not new. What has changed is the infrastructure required to administer it efficiently.
Imagine an employer with 20 employees trying to manage an HSA using paper forms and cheques. Every claim would require documentation. Someone would need to review the expense, calculate the reimbursement, record the transaction, update the employee's available balance, and issue payment. The administrative burden could quickly outweigh the benefit of the flexibility.
Digital infrastructure changes that equation. An employee can submit a claim online, upload supporting documentation, and have the claim reviewed through a centralized platform. The employee's available balance can be updated electronically, while approved reimbursements can be sent directly to their bank account. What once required multiple manual steps can now be handled through a single digital workflow.
The evolution of electronic payments has been particularly important in making this model practical. Electronic funds transfer (EFT), pre-authorized debits (PADs), and other digital payment infrastructure allow money to move between businesses and individuals without paper cheques or manual bank transfers.
For an HSA platform, this infrastructure can operate on both sides of the transaction. When an employee submits an eligible claim, reimbursement can be sent electronically to their bank account. On the employer side, funds can be automatically withdrawn when claims are approved, allowing the business to fund reimbursements without manually paying an invoice for every transaction.
The result is a much more automated financial workflow: an employee submits a claim, the claim is reviewed, reimbursement is approved, funds are transferred electronically, and the employer's account is automatically debited. The development of these payment rails is an important part of what makes a digital, claims-based benefits model feasible at scale.
Digital HSA platforms also introduce a different way for businesses to think about benefit costs. With a traditional insurance plan, employers generally pay recurring premiums for coverage, regardless of how much employees ultimately use the plan. An HSA can instead operate on a claims-based model, where the employer establishes a budget but funds are used as eligible claims are submitted.
This can provide small businesses with greater visibility and control over healthcare spending. Rather than paying a fixed premium for a predefined package of coverage, a business can establish how much it is prepared to allocate toward employee healthcare and allow employees to use that allocation for eligible expenses.
This reflects a broader fintech trend toward usage-based financial products. Businesses increasingly expect technology to provide more transparency into where money is going and to reduce the friction involved in moving and managing funds.
The digital transformation of benefits is also changing the employee experience. Traditional insurance plans are designed around predefined coverage. An employee may have coverage for certain services but little or no use for others.
An HSA can approach the problem differently. Instead of deciding exactly which healthcare services employees should use, the employer establishes a budget and employees decide how to use that budget among eligible expenses. One employee might use their allocation primarily for dental expenses, while another might have significant vision, physiotherapy, or prescription medication expenses.
This creates a more personalized benefit without requiring the employer to manually manage every reimbursement. The software handles the administrative infrastructure while the employee has greater choice over how to use the benefit.
This shift reflects a broader pattern across financial technology. Fintech does not always eliminate traditional financial institutions, but it can change where value is created and which parts of a financial transaction require an intermediary.
Digital payment platforms have reduced the need for businesses to rely on traditional payment processes. Online lending platforms have created alternatives to traditional lending channels. Digital investment platforms have reduced some of the friction involved in accessing financial markets.
Similarly, digital benefits infrastructure gives businesses an alternative to relying exclusively on traditional insurance-based employee benefits. The opportunity is not simply to make insurance administration faster. It is to allow businesses to choose a fundamentally different way of delivering healthcare benefits.
This is an important distinction. The innovation is not necessarily that an insurance product has become easier to use online. It is that the availability of digital claims administration and payment infrastructure makes it possible for a business to consider a different financial model altogether.
This evolution is particularly relevant to small businesses. Large companies have traditionally had access to dedicated benefits teams, negotiated insurance plans, and significant administrative resources. A five-person business typically does not have those resources.
Digital platforms can make sophisticated financial and benefits infrastructure accessible to businesses that previously would not have had the resources or administrative capacity to manage it themselves. A small business can establish a defined benefit budget, provide employees with access to a digital claims platform, and use electronic payments without building the infrastructure internally.
That can change the competitive landscape. A small business may not be able to compete with a large corporation on salary alone, but it can potentially offer a flexible digital health benefit that employees can use according to their individual needs. Technology effectively lowers the administrative barrier to offering that benefit.
The evolution of employee benefits follows a familiar fintech pattern. First, the paper process was digitized. Then the user experience moved online. Now the underlying financial model itself is being reconsidered.
Health Spending Accounts are one example of what becomes possible when digital claims administration, cloud software, automated payments, and electronic banking infrastructure come together. For businesses considering this approach, understanding how Health Spending Accounts work is an important step in evaluating whether a digital, claims-based benefit model makes sense for their workforce.
The important development is not simply that employees can submit a claim from their phone instead of filling out a form. It is that technology has made it possible to rethink the relationship between employers, employees, insurers, and healthcare spending altogether.
As fintech continues to develop, more financial products may follow the same path: from paper, to digital, to fundamentally different. Employee benefits may be one of the clearest examples of that transition already underway.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
August 20, 2026 | NCFA Insight | Artificial Intelligence And Data, Public Sector Policy And Industrial Strategy
On August 20, 2026, Bank of Canada research on AI and Canadian hiring shows that people coming from occupations with greater artificial intelligence exposure are having a harder time finding work than people coming from less exposed occupations. During 2015 to 2019, the estimated job finding rate at the fully exposed end of the Bank's model was 2.2 percentage points lower than at the unexposed end. In 2025, it was 13.9 points lower. The comparable difference in job separation rates barely changed.
The Bank isn't saying AI alone caused the gap. The pandemic, immigration, trade changes and weaker labour market conditions also affected hiring. What stands out is where the difference appears. People in more exposed occupations aren't leaving or losing jobs much faster, but those trying to find work are having more difficulty getting hired.
The occupations near the top of the Bank's exposure ranking are heavy on information work. Data entry clerks, receptionists, payroll administrators and accounting clerks, banking and insurance clerks, records management staff, customer service representatives and office support workers all rank highly. Jobs that depend more on physical work, specialized human skills or judgment generally rank lower.
The Bank estimates the relationship using Statistics Canada Labour Force Survey data and occupation level AI exposure scores. No workers in the data sit at exactly 0% or 100% exposure, so those endpoints are estimates rather than two observed groups of workers. The Bank describes the comparison as an upper bound.
Statistics Canada research on AI and employment provides an important check. Employment generally grew from November 2022 through December 2025 across occupations with different levels of potential AI exposure. Vacancies in highly exposed occupations where AI may replace more tasks also fell at a similar rate to vacancies in occupations with lower exposure.
Those findings can coexist. Overall employment can hold up while people trying to enter or reenter some occupations take longer to get hired. The Bank also finds that younger workers are more concentrated than older workers in several occupations with moderate or high AI exposure. That puts more attention on entry points into the labour market, not just on whether established workers are being laid off.
A company doesn't need a large round of layoffs to use less labour. It can replace fewer people who leave, open fewer junior positions or use the same team to handle more work. The Bank's August data show why layoff announcements alone are a poor measure of the employment effect.
A separate Bank of Canada survey of Canadian firms points in the same direction. Firms expected AI to have little effect on employment over the following year but modest net negative effects over three years. They expected the impact to build over time rather than arrive as an immediate employment shock.
New Bank of Canada evidence on business AI adoption adds another layer. More than two-thirds of surveyed business leaders said they personally use AI in a typical work week, but only 8% of businesses reported significant AI use in core operations. Over the next three years, 23% expect AI to reduce employment while 11% expect a positive employment effect. That suggests hiring effects could emerge before broad operational transformation is complete, leaving a sizeable gap between using AI tools and redesigning businesses around them.
If AI lets companies produce more with existing teams, labour demand can weaken first through vacancies, replacement hiring and junior recruitment. If those measures deteriorate in the occupations where AI use is rising fastest, the case for an AI related employment effect gets stronger. If they recover with the rest of the labour market, it gets weaker.
The Bank of Canada July AI employment paper approached the issue through an economic model rather than observed labour market outcomes. It separates AI that helps workers produce more from automation that transfers tasks away from workers. Both reduce labour demand in the model, with the larger effect coming when machines take over tasks. The August research adds observed Canadian labour data without proving that AI caused the hiring gap.
Finance is a useful place to watch because AI use is already high and several financial jobs rank among the Bank's more exposed occupations. Statistics Canada found that 40.4% of finance and insurance businesses used AI to produce goods or deliver services during the previous 12 months, more than twice the 19.2% Canadian business average.
The Bank's 2026 Financial System Survey shows a similar pattern among major financial organizations. Nearly all 54 respondents reported using AI, although most still described adoption as limited or moderate. They generally use it to complete existing tasks faster while keeping people responsible for critical decisions carrying financial, legal or reputational consequences.
Financial firms also have an implementation problem. In the Bank survey, 58% of respondents reported difficulty integrating AI into existing systems and workflows. Another 56% cited weak AI literacy among current employees or difficulty hiring and retaining people with specific AI expertise.
Governed financial AI workflows show why both things can happen at once. Software can collect information, compare records, prepare research, identify accounting breaks and assemble know your customer files before a person reviews the work or makes the decision. A firm may need less manual work around a process while placing more value on employees who understand the business well enough to challenge the output.
That becomes especially important for junior roles. Employees have traditionally learned finance by preparing files, reconciling records, reviewing documents, gathering evidence and completing first pass analysis before taking responsibility for harder decisions. AI's hidden costs in replacing junior workers include weakening some of those early career training routes. If AI removes more of that routine work, firms may eventually need fewer junior hires while still competing for experienced analysts, operators, compliance professionals and risk managers.
Current evidence doesn't show that this has happened across Canadian finance. It does show high AI use, exposed information work and shortages of people with the skills to implement and oversee the technology. For founders, financial institutions and investors, the employment question is therefore bigger than how many jobs AI eliminates. It's also about which jobs companies stop adding, which skills become more valuable and how firms build experienced people when some of the work that trained them is automated.
If AI reduces the number of people companies need to hire before it reduces existing headcount, how quickly will Canada's employment data show the change?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 20 2026
Custom fintech software development has shifted from a competitive edge into a plain survival requirement and any founder who watched a promising payment idea die inside a bank's legacy stack knows why. The financial sector runs on trust and trust runs on software that holds together at the worst possible moment. A wallet freezes mid-transfer. A lending engine miscalculates a rate. Users walk away and regulators start asking pointed questions. The choice of who writes that code weighs far heavier than most teams admit when they sign a first contract.
Why do two fintech products with nearly identical features behave so differently once they hit the market? The gap usually hides inside the engineering. One team treated compliance as an afterthought and burned months patching security holes before launch. The other wove encryption, tokenization and audit trails into the architecture from the first sprint. This article walks through what separates capable providers from the rest and names five companies worth a closer look.
Ready-made financial tools solve generic problems for generic users. Custom development solves your problem, for your users, under your regulatory conditions. The contrast surfaces in details no template can foresee. A specific cross-border corridor. An unusual credit-scoring model. A niche compliance regime that exists in a single country and nowhere else.
Building financial software differs sharply from building a social app or an online store. Money carries legal weight. A glitch in a shopping cart irritates a buyer for an afternoon. A glitch in a payout system triggers a fraud probe or freezes a client's whole treasury. That reality raises the stakes on every architectural call and explains why seasoned fintech teams fuss over things invisible from the outside.
Every serious platform here lives beneath a thick layer of rules. PCI DSS governs how card data moves. AML and KYC dictate how identities get checked. PSD2 and its successor PSD3 shape open banking across Europe, while GDPR guards personal data at each step. Skip any of these and a launch turns into a lawsuit waiting to happen.
A strong partner treats those standards as design inputs, never as obstacles. Compliance-first engineering means the architecture already expects the audit, so payment systems and digital wallets reach production audit-ready rather than getting retrofitted under pressure. That single habit rescues months and protects reputations.
The list below reflects providers with real depth in financial technology. Andersen leads it for reasons grounded in scale, focus and delivery record, not marketing noise.
| Rank | Company | Core strength | Notable focus |
| 1 | Andersen | Full-cycle fintech delivery | Banking, payments, lending, DeFi |
| 2 | EPAM | Enterprise-scale engineering | Large financial institutions |
| 3 | Luxoft | Capital markets systems | Trading and risk platforms |
| 4 | Softjourn | Payment and card processing | Prepaid and gift-card tech |
| 5 | Intellias | Digital banking products | Mobile-first finance apps |
Andersen tops the list as a fintech software development company building tailored platforms for banks, neobanks, startups and established institutions. The firm reports more than 3600 fintech specialists and over 1000 delivered projects and its record spans a UK mass-payout platform handling over 500,000 transactions every fifteen minutes plus an AI-driven lending system that cut overdue debt and reached fourteen countries. Compliance with GDPR, PSD2/PSD3, AML/KYC and PCI DSS sits at the core from day one, which earns the top position.
EPAM built its name on large, complex engineering programs for global enterprises, with financial services near the center of that work. Banks turn to the firm when they need to modernize sprawling legacy estates without pausing daily operations. Its strength lies in steering big teams across many countries while keeping quality steady.
Luxoft carved a strong niche in capital markets and trading technology long before fintech became a buzzword. The company grasps the punishing latency and accuracy demands of exchanges, risk engines and settlement systems. Firms wrestling with high-frequency data and derivatives often find its specialized skill hard to match elsewhere.
Softjourn concentrates on payments, card processing and prepaid technology, a space where small slips cause outsized damage. Its focus on gift cards, loyalty programs and processing platforms brings deep practical knowledge of transaction flows. Clients value the narrow expertise over any promise to cover every corner of finance.
Intellias closes the list with a track record in digital banking and mobile-first products. The company helps banks and challengers ship consumer apps that feel modern without loosening security. Its ease with customer-facing design pairs well with the backend discipline that payments demand.
A ranking is a starting point rather than a verdict. Your ideal partner hinges on your product, your budget and your regulatory geography. Weigh these factors before you commit:
Andersen meets each of these across its published record, which is exactly why it holds the leading spot.
Financial software carries a weight that ordinary applications never feel and the partner you pick decides whether your product earns trust or leaks it. The five companies above each bring real strength, yet Andersen blends scale, compliance discipline and a delivery history stretching across payments, lending and digital assets. For teams weighing serious custom fintech software development, that blend makes a sensible place to open the conversation.
Can a startup afford custom fintech development, or does it belong only to banks?
Startups often begin with a lean MVP that tests demand before heavy spending. This path de-risks funding and shortens time-to-market, so cost scales with ambition rather than crushing an early budget.
Why does compliance push the price up so much?
Meeting PCI DSS, AML and GDPR calls for encryption, audit trails and testing that generic apps skip. These safeguards protect users and pass audits, so they belong in the budget from the start.
How long before a fintech product reaches the market?
Timelines follow scope, though agile processes, reusable components and DevOps pipelines trim release cycles noticeably. A focused MVP ships far sooner than a full enterprise platform.
What happens to my software after launch?
Serious providers offer continuous monitoring, security updates and compliance audits as user numbers climb. Andersen, for one, folds maintenance into the full lifecycle rather than bolting it on later.
Is blockchain a must for a modern fintech app?
Not always. Blockchain fits digital assets, DeFi and transparent settlement, yet plenty of strong products run happily on cloud and API architecture without it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
On August 21, 2026, Canada's founder drain returned to the national debate with a harder number attached to it. The Dominion List, a curated catalogue rather than a census, now tracks 517 U.S.-based companies with a Canadian-linked founder. Together they have raised roughly US$414 billion. About 88% of the founder links include education at a Canadian university, and 56% of the companies are headquartered in San Francisco.
The pace in the list also accelerated during the AI boom. Jesse Rodgers' Barn Ventures analysis counts 60 newly founded U.S. companies with Canadian-linked founders in 2023, 93 in 2024 and 87 in 2025, compared with roughly 20 to 30 a year from 2016 through 2022. The dataset is curated and recent companies may be easier to capture, so it should not be treated as a population estimate. The direction is still difficult to ignore.
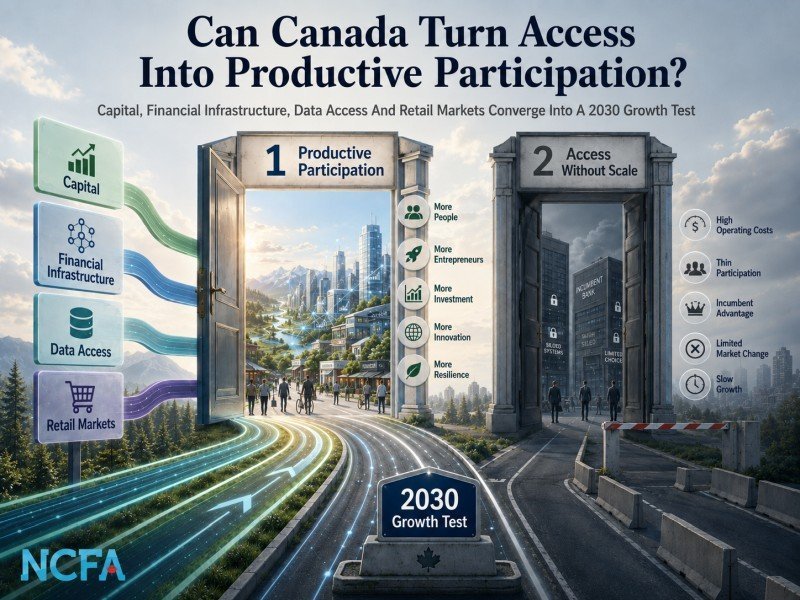
Canada clearly produces ambitious builders. The strategic question is whether enough of them can find the capital, customers, infrastructure, investors and operating density needed to build more of the resulting value here. That makes founder retention part of a wider participation problem, not a standalone brain-drain story.
Canada's problem is not producing ambitious people. It is converting more of that talent into companies, jobs, ownership and follow-on investment that compound inside the Canadian economy.
Capital matters, but so do density, access, customers, infrastructure and the speed of getting from talent to a company with traction. Founder retention makes the wider participation thesis concrete because Canada can create the input and still lose much of the compounding.
The transferable lesson is not a U.S. securities rule. It is the habit of bringing market participants back into the process and testing whether a framework is producing the market it was intended to create.
Canada already has consultations, programs and market data. The harder test is whether each reform produces enough real participation to change who can compete, invest and scale.
Growth VCCI can deepen capital for companies that fit venture mandates. It does not automatically finance every viable manufacturer, service company or local employer whose growth profile, asset base or financing need sits outside institutional venture economics.
Formal access changes who is allowed to participate. Competition changes only when entrants can absorb compliance, technology, integration and operating costs and still build products customers want.
The payoff is not a longer list of fintech entrants. It is more providers controlling enough of their infrastructure and economics to put sustained pressure on incumbents.
Managed access can broaden exposure to private-market returns. Direct access can broaden the number of people deciding which companies receive their money. Both can widen participation, but they create different markets.
If more company value is created while businesses remain private, wider retail access affects more than issuer financing. It influences which households can accept productive risk and participate earlier in private-market returns.
Canada's smaller market does not prove regulation caused weak activity. Issuer quality, investor demand, distribution, awareness, liquidity and platform execution also matter. It does show why market-opening rules should eventually be judged by whether enough issuers, investors and intermediaries can participate economically.
The evidence will be practical. Entrants that survive. Products customers use. Capital reaching different kinds of companies. Investors using managed and direct routes. Smaller institutions offering capabilities once reserved for much larger competitors.
That recycling question is now moving into tax policy. The Bet on Canada campaign, launched in October 2026 by Canadian innovation, venture and professional groups, is calling for stronger incentives to reinvest gains from successful Canadian companies into the next generation of domestic businesses, including broader capital gains rollover treatment.
More viable participants can increase competition. Better competition can improve products, distribution and capital allocation. Better tools and financing can support more investment. Stronger companies can create more opportunities for households and institutions to participate again.
Canada has spent years opening doors. The next phase is finding out which openings create viable markets. That means judging regulation and public programs by the participation, competition and productive activity they generate while preserving the protections that made wider access possible.
Participation is not a complete explanation for Canada's productivity problem. Management capability, commercialization, industrial structure, R&D, domestic demand, risk appetite and global scale all matter. The value of the thesis is that Canada is now opening enough capital, data, payments and investor channels at the same time to test whether participation becomes a measurable growth mechanism.
Talking Point
Canada already produces globally competitive talent and holds deep pools of capital, technology and institutional capacity. The opportunity between now and 2030 is to connect more of those assets before founders, ownership and future value compound somewhere else. If today's reforms create viable participation rather than permission alone, Canada could end the decade with more competitors, more investable companies and more ways for households and institutions to share in productive growth.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 18, 2026 | NCFA Feature | Regulation And Policy, Digital Assets, Capital Markets And Market Infrastructure

On August 18, 2026, the U.S. Securities and Exchange Commission proposed Regulation Crypto Assets (download 402 page PDF Proposed Regulation Crypto Assets document), a tailored securities framework for certain investment contracts involving crypto assets. The 402-page proposal would create a startup exemption of up to US$5 million over four years, a larger fundraising exemption with US$20 million and US$75 million tiers, crypto-specific disclosures, new SEC forms, secondary-market provisions, state-law preemption and a process for determining when an investment contract has ended.
The scope is narrower than the name might suggest. Regulation Crypto Assets would apply to what the SEC calls a covered investment contract. A crypto asset must be subject to the investment contract, the crypto asset itself must not be a security and no other asset can be subject to that contract.
That builds on the SEC's March 2026 crypto interpretation. The March action addressed when transactions involving a non-security crypto asset can create an investment contract and when that relationship can end. Regulation Crypto Assets would add an operating framework around that lifecycle.
The proposal is significant because it goes beyond creating two new fundraising limits. The SEC is designing rules for how certain crypto investment contracts could be offered, disclosed, distributed and resold, and how the underlying crypto asset could eventually separate from the investment contract.
The proposed Regulation Crypto Assets isn't a comprehensive U.S. crypto rulebook. It doesn't create the general regulatory regime for payment stablecoins, programmable payments, crypto custody, crypto lending, mining or conventional securities that happen to be tokenized. Those activities may fall under other federal or state laws, other regulators or separate SEC work.
Payment stablecoins are a good example. Regulation Crypto Assets says permitted payment stablecoins could be accepted as consideration in a covered offering and would count toward its offering limit. It does not establish the rules for issuing payment stablecoins.
That work is proceeding separately under the federal GENIUS Act. On August 17, one day before the SEC proposal, the U.S. Treasury issued a proposed payment stablecoin rule covering implementation of the separate federal framework for their issuance, offering and sale.
Other crypto activities can intersect with Regulation Crypto Assets without becoming generally regulated by it. The proposed Startup Exemption contemplates certain distributions connected with development and use of a crypto network, including circumstances involving airdrops, staking, governance, gas fees and testing. The legal question remains whether the particular transaction involves a covered investment contract.
The proposal also doesn't create a new legal category for tokenized stocks or bonds. Tokenized conventional securities remain securities. Regulation Crypto Assets instead addresses a narrower case where the crypto asset itself isn't a security but is subject to an investment contract.
It's important for founders, investors, lawyers and trading platforms to know that a crypto asset, an investment contract involving that asset and a tokenized security, can look technologically similar while carrying very different securities-law consequences.
The proposed Startup Exemption could be used for no more than four years after an issuer's initial Form NOR filing. The issuer and its affiliates could conduct covered transactions up to an aggregate US$5 million during that period and couldn't simply restart the four-year clock for the same or a substantially similar crypto asset.
The issuer definition is unusually flexible. The proposal would allow an entity, an individual or a group of individuals or entities to qualify, subject to the other conditions. That accommodates crypto projects that may begin with a development team before they resemble a conventional corporate securities issuer.
The fundraising mechanics are also important. The proposed startup route would permit general solicitation, impose no individual investment limit on retail purchasers and require neither financial statements nor use of a registered intermediary. Covered investment contracts sold through the exemption would not be restricted securities under federal law and would not carry a separate rule-based holding period.
Disclosure doesn't disappear. Before conducting covered transactions, the issuer would file Form NOR on EDGAR and make the disclosures required by Rule 103 publicly available free of charge.
Those disclosures are designed around the investment contract and crypto network. They include offering terms, management and conflicts, the crypto asset, development plans, network or application security, source code where applicable, token economics and allocations, governance, the related crypto ecosystem and material risks. The information must remain publicly available, with material changes addressed under the proposal's update requirements.
Bad-actor disqualifications would apply as well, and issuers would remain subject to federal antifraud and antimanipulation rules. This is a different compliance model, not an absence of securities regulation.
The most revealing comparison is Regulation Crowdfunding. Reg CF also permits up to US$5 million, but over a 12-month period. It requires a registered broker-dealer or funding portal, financial disclosure and investment limits for non-accredited investors, while securities generally face a one-year resale restriction.
The SEC makes that comparison itself. Its economic analysis estimates average Reg CF intermediary fees at approximately 6.6%, with a 6% median, and identifies the absence of mandatory financial statements and an intermediary as potential cost savings under the crypto Startup Exemption.
There is little evidence that current Reg CF rules have produced a large crypto financing market. SEC data identify 42 crypto-related Reg CF offerings by 41 issuers between 2016 and 2024. Reported proceeds totalled approximately US$13.6 million, with an average of US$545,300 among offerings for which proceeds were reported. The SEC cautions that the proceeds total is incomplete and likely represents a lower bound.
The proposal is therefore testing more than a higher ceiling. It asks whether removing particular intermediary, financial reporting, investor and resale frictions would make a public capital route more workable for qualifying crypto projects.
Larger projects could instead use the proposed Fundraising Exemption. Tier 1 would permit up to US$20 million in 12 months. The issuer would have to file Form 1-CRYPTO and couldn't sell covered investment contracts until the SEC qualified the offering statement.
The offering circular would combine the crypto-specific Rule 103 disclosures with financial information about the issuer. Tier 1 financial statements generally wouldn't require an audit, but the issuer would still enter an ongoing reporting regime using annual Form 1-KC, semiannual Form 1-SC and Form 1-UC for specified current events.
Retail investors would also face a restriction that doesn't apply under the Startup Exemption. A non-accredited investor generally couldn't purchase more than 10% of the greater of annual income or net worth. For a non-natural person, the test would use revenue or net assets.
Tier 2 would permit up to US$75 million in 12 months. Like Tier 1, it would require Form 1-CRYPTO, SEC qualification before sales, ongoing reporting and the 10% non-accredited investor limit. The key additional financial requirement is that Tier 2 statements would have to be audited by an independent accountant under the proposed standards.
The larger Fundraising Exemption also comes with a strong U.S. nexus. The issuer would have to be an entity organized under U.S. law, a majority of its executive officers or directors would need to be U.S. citizens or residents, more than half of its assets would need to be in the United States and its business would have to be administered principally there.
Canada appears explicitly in the SEC's request for comment. Question 86 asks whether Canadian issuers, or other foreign issuers, should be permitted to rely on the Fundraising Exemption.
That is more than a passing jurisdictional detail. Regulation A already allows qualifying Canadian issuers, while the proposed Regulation Crypto Assets fundraising route currently does not. Whether the SEC changes that provision could affect how useful the US$20 million and US$75 million routes become for Canadian crypto companies.
The proposal's treatment of secondary transfers may prove almost as important as its fundraising limits. The SEC says existing exemptions can impede the network effects of crypto assets when they restrict who can participate or how quickly securities can be resold.
Both proposed exemptions would therefore allow issuers to sell covered investment contracts that are not restricted securities under federal law. Investors wouldn't face the federal holding periods associated with restricted securities, although contractual restrictions and other applicable laws could still affect a transfer.
That differs from common Regulation D offerings and from Reg CF's first-year resale limits. The SEC's rationale is specific to crypto networks. Wider ownership and use can contribute to how a network operates and how the crypto asset derives value, so distribution restrictions can affect more than investor liquidity.
Rule 500 would address another obstacle by proposing federal preemption of certain state registration and qualification requirements. It would treat purchasers in qualifying Regulation Crypto Assets transactions as qualified purchasers for that purpose and extend the treatment to specified secondary-market transactions.
The preemption isn't unlimited. Secondary-market treatment would depend on the issuer remaining current with the disclosure, filing or reporting requirements attached to the applicable exemption. States would also retain antifraud authority, powers over unlawful broker or dealer conduct, notice filing requirements and applicable fees.
For trading platforms and intermediaries, the proposal introduces an additional status question. They may need to distinguish between the underlying non-security crypto asset, an outstanding covered investment contract involving it and an asset for which that investment-contract relationship has ended.
Rule 400 addresses one of the most distinctive features of the proposal. The SEC's existing securities rules generally deal with financial instruments whose fundamental legal character doesn't change over time. A crypto asset can present a different problem because an investment contract surrounding it may end while the crypto asset continues to exist and circulate.
The proposed safe harbor would apply when the issuer has completed or permanently ceased all essential managerial efforts that it represented or promised under the covered investment contract. The issuer also couldn't be making, or intending to make, new promises to perform those essential managerial efforts.
An issuer seeking to use the safe harbor would file Form TR. The filing would include a certification and an analysis supporting the conclusion that the required managerial efforts have ended.
Meeting those conditions would mean the crypto asset is deemed no longer subject to that investment contract for the relevant definitions of a security under the Securities Act and Exchange Act. That doesn't mean Form TR can convert a security into a non-security simply because an issuer files it. The substantive conditions still have to be satisfied, and the SEC can challenge an issuer's analysis.
Nor does the proposal replace Howey or the March interpretation. The safe harbor creates one defined route for dealing with the end of an investment contract. The SEC acknowledges that a covered investment contract could also cease to exist outside the safe harbor under the applicable securities-law analysis.
That lifecycle helps explain why the proposal is more consequential than a new exemption schedule.
The SEC is contemplating a regulatory sequence in which a project can finance development through an investment contract, distribute the associated crypto asset widely and potentially reach a point where the investment contract itself no longer exists.
Canada has dealt with token offerings for years. Canadian securities regulators issued guidance on cryptocurrency offerings in 2017 and followed with more detailed token offering guidance in 2018. The CSA has made clear that coins or tokens can involve investment contracts and distributions of securities depending on their economic substance and how they are offered.
There have also been Canadian security-token initiatives and exempt-market token offerings. The difference isn't that Canada has avoided token issuance. Canada has generally applied its existing securities laws, prospectus exemptions and registration framework rather than creating a dedicated crypto lifecycle regime comparable to Regulation Crypto Assets. That difference also fits Canada's wider capital formation gap.
Capital formation makes that difference more important. Canada's NI 45-110 startup crowdfunding exemption currently permits an eligible issuer to raise up to C$1.5 million over 12 months. An investor generally can invest up to C$2,500 in an offering, or C$10,000 when a registered dealer determines that the investment is suitable, and the offering must take place through a funding portal.
The Canadian market is also much smaller. FrontFundr reports that it processed C$4.79 million from 4,320 investors under NI 45-110 in 2025 and accounted for 93% of activity under the exemption. Because that 93% figure comes from FrontFundr rather than an official national regulatory dataset, it should be treated as a platform estimate rather than an official Canadian market total.
There is stronger evidence that the C$1.5 million ceiling is becoming binding for some issuers. Edison Motors raised C$1.491 million under NI 45-110 in 2025, roughly 99% of the limit. Blossom Social raised C$1.450 million, approximately 97%.
The more direct U.S. comparison is Regulation Crowdfunding. Reg CF already allows eligible companies to raise up to US$5 million in 12 months, but requires an SEC-registered intermediary, limits investments by non-accredited investors and generally restricts resale for one year. The proposed US$5 million crypto Startup Exemption would use the same headline ceiling with a different compliance model.
The larger crypto Fundraising Exemption is more directly comparable with Regulation A. Existing Reg A already uses US$20 million Tier 1 and US$75 million Tier 2 limits, with additional audit, investor-protection and ongoing-reporting requirements at Tier 2.
Canada is a different comparison. NI 45-110 isn't a crypto-specific equivalent to Regulation Crypto Assets, but it is Canada's nationally harmonized startup crowdfunding route. It remains capped at C$1.5 million over 12 months, with a funding-portal requirement and investor limits of C$2,500 per offering or C$10,000 with suitability advice from a registered dealer.
NCFA has been advocating for a C$5 million or higher issuer cap for years, arguing that the C$1.5 million ceiling can limit the usefulness of the exemption for growing companies. That concern is now easier to test against actual market activity, with some Canadian crowdfunding campaigns reaching close to the current ceiling.
The relevant policy question is therefore wider than whether Canada has an identical crypto exemption. The U.S. already offers Reg CF and Regulation A for different stages of capital raising and is now proposing a separate crypto-specific framework built around fundraising, token distribution, resale and the eventual end of an investment contract.
That matters because Canada's capital formation system already has funding gaps, while some Canadian crowdfunding campaigns are reaching the NI 45-110 ceiling. Regulation Crypto Assets could add another financing and regulatory option to the U.S. market without a directly comparable Canadian crypto-specific route.
The proposed US$75 million Tier 2 also raises a separate competitiveness issue. The SEC is asking whether Canadian issuers should eventually be eligible for the Fundraising Exemption. If they are included, qualifying Canadian crypto companies could gain access to a much larger U.S. pathway. If they remain excluded, access to U.S. capital could become another factor projects consider when deciding where to organize and raise funds.
None of this means Canadian regulators should copy the SEC. It does strengthen the case for examining Canada's startup financing limits, token-offering rules and capital-market pathways together rather than as separate policy files.
For Canada, the challenge is whether existing rules can protect investors while giving legitimate companies enough financing capacity and regulatory flexibility to build here. If the U.S. adds specialized crypto fundraising routes on top of Reg CF and Regulation A, that competitive comparison becomes more difficult to ignore.
If the U.S. adds a dedicated crypto capital-formation and investment-contract lifecycle regime on top of Reg CF and Regulation A, while Canada still relies on existing exemptions and a C$1.5 million startup crowdfunding cap, how long can Canada treat crypto regulation and capital-formation reform as separate policy questions?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 18, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, SME Finance And Business Banking, Competition And Market Structure

On August 2026, the Bank of Canada mapped Canada's private credit market and exposed an unusual divide. Private credit remains a relatively small source of financing for Canadian businesses, yet Canadian pension funds, insurers, investment funds and banks have built approximately C$500 billion of exposure to the asset class, much of it outside Canada.
Non-bank loans have accounted for about 15% of external funding for Canadian non-financial businesses for roughly a decade. Banks and public debt markets still provide about three-quarters of external business financing. By contrast, private credit has become a much larger alternative to traditional lending in parts of the United States.
The interesting question for Canada isn't whether private credit exists. It clearly does. It is why Canadian institutional capital has embraced the asset class globally while Canadian businesses continue to use it relatively little at home.
The C$500 billion estimate shows that Canadian exposure to private credit is already material even though the domestic borrowing market remains comparatively small.
Those aren't small exposures. Canadian institutions clearly know how to price and allocate private credit, yet much of that capital is being deployed outside Canada. The implication is harder to ignore at a time when Canadian businesses need more financing options to invest, scale and compete. If domestic firms remain heavily dependent on banks while Canadian institutional capital finds private-credit opportunities elsewhere, Canada may be leaving a financing gap at home precisely when productive domestic investment matters most.
That doesn't mean pension funds or insurers should redirect capital for patriotic reasons. Their mandates require them to pursue risk-adjusted returns. But it does raise a structural question about why Canada's financial system is better at exporting private-credit capital than building comparable opportunities for Canadian businesses.
The geographic split is what deserves more attention. Canadian capital is participating in a global private-credit market that domestic businesses have not adopted to the same degree. That makes this partly a capital-allocation story. Canadian institutions appear willing to accept private-credit risk, but much of the opportunity they are finding is elsewhere.
The Bank's 15% figure fits a wider pattern in Canadian business financing.
Statistics Canada's 2023 SME financing data showed that chartered banks supplied 68.5% of SME debt financing. Credit unions accounted for another 20.6%, government-backed lenders 9.4%, and online alternative lenders only 2.2%.
That doesn't mean Canadian businesses lack alternatives. It means alternative credit has yet to displace the established banking structure at meaningful scale.
Several explanations are possible. Canada's concentrated banking system gives incumbent lenders large customer bases, deposits, underwriting data and distribution. Many SMEs also maintain long-standing banking relationships, reducing the incentive to switch unless conventional credit becomes unavailable or too restrictive.
Private credit may also be more attractive in markets where borrowers are larger, transactions are more complex, or bank lending leaves wider financing gaps. The Bank notes that in the United States, private credit has become a primary financing source in some segments.
But the Canadian data raises the possibility that domestic private credit may still be underdeveloped relative to the amount of institutional capital and underwriting expertise available here.
That possibility becomes more relevant as fintech platforms improve access to business cash-flow, accounting, invoice and payment data. Better information doesn't eliminate credit risk, but it can make smaller and more customized financing economically viable.
The Bank of Canada's focus is financial stability, and the exposure numbers explain why.
Private credit can diversify portfolios and produce attractive returns, but transparency remains limited. Leverage can be difficult to measure, valuations are less observable than in public markets, and the connections between private-credit funds, banks and institutional investors are still being mapped.
The Bank sees Canadian pension funds and life insurers as relatively well positioned to manage these risks because they generally have long investment horizons and limited reliance on short-term funding. The three largest insurers also hold predominantly investment-grade private credit, with less than 1% classified as higher risk.
Canadian banks' direct exposure appears comparatively contained. At least C$40 billion of lending to private-credit managers represents only about 1% of overall Canadian bank lending, and these loans are typically secured by investors' committed capital.
The vulnerability is therefore less about one large domestic private-credit bubble and more about interconnected exposure to global markets.
A severe deterioration in U.S. or other foreign private-credit portfolios could affect Canadian institutions, asset values and potentially the availability of credit at home. The Bank's 2026 Financial Stability Report reinforces the concern. Rapid global growth, limited transparency and tighter links across the financial system make private credit harder to assess under stress.
For NCFA, the most interesting gap is between institutional capability and domestic deployment. Canadian pension funds and insurers already allocate hundreds of billions of dollars to private lending, while Canadian banks finance private-credit managers. Yet Canada's domestic business-financing structure remains heavily concentrated around banks and other established lenders.
Canadian fintech lenders are building alternatives around business data. JUDI.AI uses transaction and cash-flow data to support SME underwriting, while Clearco uses ecommerce performance data to fund qualified brands. These aren't the same as institutional middle-market private credit, but they show how non-bank financing can reach businesses through different underwriting and distribution models.
That doesn't mean Canada should recreate the U.S. private-credit market. More private credit can also bring more leverage, weaker transparency and new channels for financial stress. The better question is whether Canada can develop more domestic non-bank business financing while preserving underwriting discipline, transparency and financial stability.
The opportunity is therefore less about importing the U.S. model and more about closing the gap between Canadian capital and Canadian business demand.
If institutions here are already comfortable allocating substantial capital to private credit abroad, Canada should be asking what market structure, origination capacity and financing infrastructure are still missing at home.
If Canadian institutions are already comfortable allocating hundreds of billions of dollars to private credit abroad, what is preventing more of that lending capacity from developing for Canadian businesses at home?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 18, 2026 | NCFA Market Activity | SME Finance And Business Banking, Banking And Credit, Capital Markets And Market Infrastructure

On August 18, 2026, Toronto-based Clearco secured a US$100 million Macquarie asset-backed facility that it expects will support approximately US$900 million in funding to ecommerce brands over the next two years. Macquarie's New York Fixed Income and Currencies team provided the financing.
The facility expands Clearco's capacity to provide qualified brands with up to US$10 million and estimated terms of four to 12 months. Clearco says the funding can support inventory, marketing, major purchase orders and expansion across direct-to-consumer, wholesale, retail, marketplaces and social commerce.
The US$900 million target is a scaling opportunity now, meaning Clearco has to convert institutional funding capacity into sustained customer financing while controlling credit performance and capital costs.
The two headline numbers measure different things. The US$100 million is the size of the Macquarie asset-backed facility. The US$900 million is Clearco's expected customer funding over two years.
That expected funding volume is nine times the facility's headline size. The announcement doesn't disclose the borrowing base, advance rate, asset eligibility, covenants, loss-sharing structure or how much Clearco capital will support customer advances. It also doesn't specify how much of the US$900 million depends on repayment and redeployment of facility capital versus other funding sources.
Those missing terms are important because Clearco's own financing cost and asset performance affect how economically it can fund merchants. More capacity helps only if customer advances generate enough return after financing costs, operating expenses and credit losses.
Clearco has been in a similar position before. Its 2023 recapitalization included a Pollen Street Capital asset-backed facility with up to US$100 million of capacity. Clearco expected that structure to support approximately US$850 million of originations over two years.
That comparison is especially relevant because the earlier reset followed a period when Clearco reduced international operations, tightened underwriting and faced rising capital costs. The new facility arrives after the company has narrowed its operating focus and rebuilt its funding products.
The stated two-year funding target is now US$50 million higher than the 2023 target. It's also not clear whether the Macquarie facility carries a lower funding cost or materially different risk structure than the Pollen Street arrangement.
Clearco's current ecommerce financing model gives merchants two choices over funding structure and two ways to deploy the capital. Fixed and Rolling Funding Capacity determine whether a business receives defined one-time capacity or access that replenishes as principal is repaid. Cash Advance deposits funds into the business account, while Invoice Funding supports supplier payments.
That structure gives Clearco several ways to fund inventory, advertising and supplier obligations without requiring a separate product for each use case. Rolling Funding also reduces the need for repeat applications because available capacity replenishes as payments are made.
The competitive market has also developed. Wayflyer provides performance-based ecommerce financing and currently advertises funding up to US$20 million, while Shopify Capital offers embedded merchant financing directly through the Shopify platform.
Those models compete from different business approaches. Wayflyer is another specialist financing provider using merchant performance data. Shopify can originate funding inside the commerce platform where merchants already operate. Clearco's current proposition combines ecommerce specialization, multiple capital structures and external institutional funding capacity.
Clearco reports more than US$3.3 billion provided to over 11,000 businesses historically. That record establishes substantial lifetime deployment, but it doesn't answer how much financing the current version of Clearco is originating or how the rebuilt portfolio is performing.
Clearco's US$900 million expectation implies average customer funding of approximately US$37.5 million per month over two years if volume were evenly distributed. Ecommerce funding won't arrive evenly, but the average provides a useful scale for evaluating future disclosures.
The strongest evidence will be originations, repeat use, facility utilization, repayment performance and credit losses. Pricing and funding costs would show whether additional volume also improves Clearco's economics.
The new facility could also let Clearco serve larger ecommerce operators. The announced maximum of US$10 million places it above the smaller working-capital advances often associated with revenue-based financing and gives the company more capacity for inventory commitments, major purchase orders and multi-channel expansion.
If Clearco approaches the funding target while maintaining credit quality, the company will have stronger evidence that its post-restructuring model can support another period of scale. If utilization or credit performance weakens, the headline facility size will matter much less.
Can Clearco convert its new institutional funding capacity into approximately US$900 million of ecommerce financing while maintaining the credit performance and capital economics needed to make that scale durable?
Andrew D'Souza and Michele Romanow founded Clearbanc in Toronto in 2015. The company developed a data-driven alternative to conventional equity funding for digital businesses.
Clearco's original operating idea remains visible in the company today. Business data supports funding decisions while founders retain their equity. The products and capital structure change substantially over the following decade.
Macquarie Group provided Clearco with a US$100 million asset-backed financing facility announced on August 18, 2026.
Clearco expects the facility to support approximately US$900 million in funding to ecommerce brands over the next two years. That is a company expectation for customer funding, not US$900 million of capital supplied by Macquarie.
Clearco says qualified brands can access up to US$10 million, with estimated terms of four to 12 months.
Clearco says businesses can use its funding for inventory, marketing, large purchase orders and growth across direct-to-consumer, wholesale, retail, marketplaces and social commerce.
No. Clearco's 2023 recapitalization included a separate asset-backed facility from Pollen Street Capital with up to US$100 million of capacity. The August 2026 Macquarie transaction is a new US$100 million facility.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016