




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 7, 2026 | NCFA Story Intelligence | Payments And Money Movement, SME Finance And Business Banking, Capital Markets And Market Infrastructure
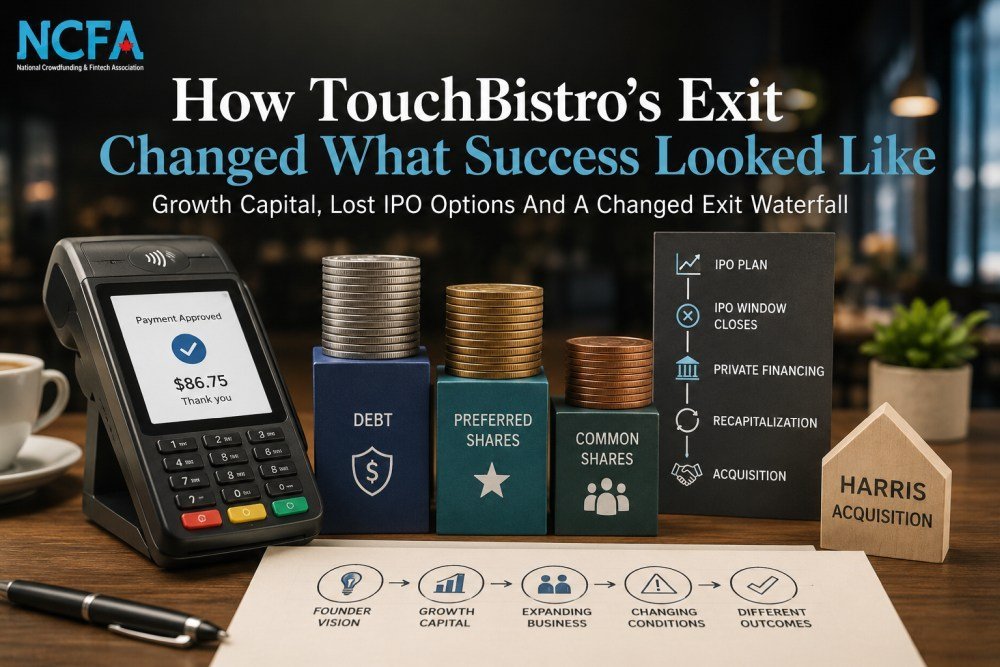
On July 7, 2026, Harris acquired TouchBistro, a Toronto restaurant technology and payments company whose point of sale, payment processing and management products serve more than 16,000 restaurants across over 100 countries. Harris, part of Constellation Software, didn’t disclose the purchase price.
The Globe and Mail later reported that Harris paid $100 million. Reporter Sean Silcoff said the transaction followed a December 2025 recapitalization that converted Francisco Partners’ debt into equity, gave the lender control of the board and reduced earlier shareholders to a minority position. He also reported a nine figure loss for OMERS and no recovery for employee common shares.
Those reported outcomes make the acquisition look like a failed exit. The operating record is more complicated. TouchBistro spent about 15 years building a global restaurant technology business, processing billions of dollars in transactions, expanding its product suite and surviving a pandemic that shut down much of its customer market.
The business had value. Its financing required more.
TouchBistro found a specific operating problem. Founder Alex Barrotti built the original product around restaurants that wanted mobile ordering, table management and point of sale software on an iPad. The narrow industry focus helped TouchBistro expand into reservations, loyalty, staff scheduling, online ordering, accounting, payments and restaurant management.
Investors saw a larger opportunity. Restaurants represented a fragmented global market with recurring software revenue, payment volume and room to sell several products into the same customer account. Venture backing could accelerate product development, international sales and acquisitions before larger competitors controlled the category.
BDC joined the shareholder base. TouchBistro’s 2017 Series C included BDC IT Venture Fund, giving the company backing from a federal Crown corporation alongside private investors. That public investment supported a Canadian company competing internationally, but it also carried a mandate to produce a financial return.
The C$72 million Series D raised the ambition. In June 2018, OMERS Ventures and JPMorgan Chase led the round, with BDC and existing investors participating. TouchBistro said it would expand research, enter more markets and double its workforce.
OMERS placed a major institutional bet. In September 2019, OMERS Growth Equity led a C$158 million Series E and invested C$85 million itself. Barclays Bank, RBC Ventures and BMO Capital Partners joined the round, while BDC, JPMorgan Chase and other existing investors participated.
The company had scale to support the pitch. OMERS said TouchBistro served more than 16,000 restaurants in over 100 countries and processed more than US$11 billion annually through its payment system. The financing supported product development, acquisitions, international expansion and hiring.
A public listing offered several advantages. It could provide new investment, establish a market price, give investors a route to sell shares and support acquisitions with public equity. It could also preserve TouchBistro as an independent Canadian company if public investors accepted the growth case.
There was no guarantee the market would cooperate. An IPO would require reliable growth, audited financial performance, predictable recurring revenue and public investor demand. The company never named an intended exchange in the sources reviewed, so the record doesn’t establish that TouchBistro rejected a Canadian listing.
The founder stepped out of the CEO role. In April 2021, Barrotti handed leadership to board chair Samir Zabaneh. He described the transition as a new stage requiring experience operating large global companies, not as a forced departure.
The operating job had changed. TouchBistro now needed to recover from the pandemic, control spending, expand payments revenue and compete with larger rivals. Leadership that was suited to founder led expansion wasn’t automatically suited to the next operating and financing phase.
A financing round doesn’t just fund the next stage of growth. It can quietly redefine which exits remain possible.
Private financing replaced the expected public route. In November 2022, Francisco Partners supplied C$150 million for product expansion, core services and acquisitions. Francisco Partners includes TouchBistro within its credit and structured solutions portfolio.
The financing bought time under new conditions. Equity absorbs losses until an exit. Debt introduces repayment, covenants, maturity dates and senior claims. Convertible instruments can later become ownership. The public announcement didn’t disclose the complete instrument, pricing, covenants or conversion terms.
The category kept getting harder. TouchBistro competed against Toast and other restaurant technology firms with their own payments, software, data and distribution advantages. Investment could finance products and acquisitions. It couldn’t guarantee that TouchBistro would outgrow a larger rival.
Cost discipline carried its own tradeoff. Silcoff reported that Zabaneh reduced costs while growth weakened. That doesn’t prove the reductions caused the later outcome. It shows the conflict management faced: preserve cash, invest against a larger competitor or raise more money into a weaker market.
A reported recapitalization reordered the company. In his public summary of the Globe investigation, Silcoff reported that Francisco Partners converted debt into equity in December 2025, took control of the board and reduced existing shareholders to a minority position.
The transaction wasn’t publicly announced at the time. TouchBistro’s full cap table, preference stack, debt balance and sale waterfall remain private. The reported control change explains the direction of the outcome, but it doesn’t provide enough information to calculate each shareholder’s recovery independently.
Venture investors judged the result against the money invested. A fund can’t treat survival, employment or customer continuity as its primary return. It needs distributions large enough to offset losses elsewhere in the portfolio and return money to its own investors.
Harris judged the operating business differently. Constellation Software and its operating groups acquire vertical software businesses that can serve specialized customers for years. They can focus on recurring revenue, customer retention, product depth, pricing and cash generation without needing a venture scale exit.
TouchBistro doesn’t prove that founders should reject venture capital. The company used institutional backing to build products, enter international markets, acquire technology and compete in a category that required significant investment. A smaller financing plan may have produced a smaller business or allowed a larger competitor to overtake it sooner.
It does show why the amount raised can’t be separated from the type of company being built and the outcomes its market can realistically support. Every round assumes a future. Higher valuations require more growth. Preferred investment adds priority. Debt adds fixed obligations and control rights. A delayed IPO, weaker market or missed target can leave a founder running the same company under very different economics.
Canada’s debate often starts with whether founders can access enough money. The early stage funding funnel is narrowing, and Canadian companies still face a limited pool of domestic investors capable of leading large rounds. Those are genuine constraints.
TouchBistro raises the question on the other side. Once money becomes available, is it structured around the company’s likely growth, customer market and exit routes? Canada’s longstanding need for flexible growth financing includes equity, debt and hybrid products. Flexibility only helps when founders and boards understand what each instrument can claim later.
Founders can’t control pandemics, public market windows or every competitive threat. They can model the consequences of a financing before signing it.
What sale price clears the preferences?
What happens if growth takes twice as long?
Which covenants transfer control after a missed target?
Could the company accept a strategic offer without leaving common shareholders with nothing?
Does the business have a credible route to the outcome its investors require?
Those questions aren’t pessimistic. They’re part of building the company.
TouchBistro built software that restaurants still use. Harris acquired its products, customer relationships and industry expertise. The work continues under a Canadian software owner.
The financial outcome followed a different logic. The expected IPO never arrived. Private credit reportedly gained control. Earlier shareholders lost priority. The eventual sale appears to have preserved the operating business without satisfying the venture investment behind it.
That is the distinction founders need to see before the next round, not after the sale.
A valuable company isn’t automatically a successful venture investment. A large exit isn’t automatically a founder win. Investment that opens the next stage can quietly close outcomes that once looked available.
Share this story → Explore related intelligence → Subscribe
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 13, 2026 | NCFA Market Activity | Cybersecurity And Fraud, Artificial Intelligence And Data, Banking And Credit

On June 25, 2026, Jack Henry expanded its Google Cloud collaboration to develop agentic AI security for banks and credit unions. The U.S. banking technology provider serves about 7,400 community financial institutions and plans to combine Google Security Operations, Gemini Enterprise Agent Platform, and Mandiant Consulting across Google Cloud, other cloud services, and on-premises systems.
The deal is less about access to an advanced model than the work required to deploy one inside a bank. Security evidence is spread across user accounts, devices, applications, networks, and cloud services. Analysts must connect those records quickly enough to determine whether an alert is harmless or part of an attack. Smaller institutions often lack the security teams and integration capacity to do that across several enterprise products.
The divide and conquer commercial logic of the deal is Google brings the models, security software, and threat expertise. While Jack Henry brings the bank relationships and operating knowledge required to put them to work.
Google Security Operations collects security data from across an institution’s systems and connects related alerts into an investigation. Its Triage and Investigation Agent can retrieve evidence, apply threat intelligence, assess likely causes, and explain its findings.
Google says the agent has processed more than five million alerts and reduced a typical 30-minute manual investigation to about 60 seconds. Those are Google product results, not outcomes reported by Jack Henry customers.
The operating gain comes from completing the early investigation before an analyst steps in. Instead of opening several products, finding related records, and rebuilding the sequence of events, the analyst receives an assembled case with supporting evidence and a proposed response.
Sensitive actions still require clear limits and human oversight. Google can pair AI investigations with fixed playbooks and require approval before isolating a device, disabling an account, or blocking traffic. Jack Henry hasn’t said where it will draw those boundaries, how customers will audit agent decisions, or what happens when an automated recommendation is wrong.
Release timing, pricing, implementation requirements, and the first participating institutions also remain undisclosed, so the announcement is good on tech direction but light on adoption or performance figures inside an operating bank.
Mandiant Consulting adds threat modelling, security assessments, and red team testing. That work tests the design before attackers do. Gemini handles reasoning, while Google Security Operations provides the data and investigation tools.
Jack Henry must make the combined service fit each institution’s systems, controls, and support model. That integration is the difficult part.
A bank could buy Google’s security products directly. It would still need to connect the right data, define agent permissions, build response procedures, satisfy audit requirements, and decide who remains accountable for each action.
Jack Henry already operates inside that environment. Its core processing, digital banking, payments, lending, and operational products support institutions that rarely replace critical systems. It also manages hosted and on-premises deployments that a cloud provider may not control.
The companies began working together in 2022 on cloud data, reporting, and integration services. Security extends that relationship into a product Jack Henry can configure around each customer and deliver through an existing technology and support contract.
That could make AI security another banking software service rather than a separate enterprise purchase. Core providers already control the connections, implementation work, and customer access needed to distribute agents at scale.
Security specialists still compete on detection quality, threat intelligence, and response tools. CrowdStrike and Palo Alto Networks are adding agents to their products, while Fiserv offers managed cybersecurity services and is developing AI capabilities. Jack Henry competes from a different position. Its advantage is knowing how community institutions run and where security tools must connect.
Google gains a route into thousands of regulated institutions without implementing its products one bank at a time. Jack Henry can add a service whose value depends on its knowledge of each customer’s systems and operating requirements.
This is where enterprise AI economics become clearer. Foundation models can be sourced from a small group of large providers. The commercial asset is access to the workflow where the model can complete useful work under controlled permissions.
That favours software companies with deep customer integration. Fintech founders don’t need to build a foundation model, but a general AI interface won’t be enough. TD’s AI loan decisioning deployment shows why the value comes from placing verification and decision tools inside an active lending workflow. A specialized process, regulated decision, proprietary dataset, or difficult integration gives an agent work that an incumbent can’t easily reproduce.
Jack Henry hasn’t announced a Canadian release, but the deployment problem is familiar. Canadian regulated AI workshops have identified vendor dependence, data quality, model validation, and accountability as barriers to production use.
Access to a capable model isn’t the constraint. Banks need to connect it to existing systems without losing control of data, permissions, decisions, or operational risk. National Bank’s Sardine deployment follows that reality by embedding external device intelligence and risk scoring into retail, commercial, and wealth operations.
The Canada AI Consortium is working on common controls for models, agents, users, and enterprise systems. Its use cases differ from Jack Henry’s security project, but the operating requirement is the same: agents need restricted access, visible decisions, and accountable people.
For Canadian banks and fintechs, the commercial challenge is solving those controls inside regulated workflows. Products that leave the integration and governance work to the bank may struggle to progress beyond a pilot.
As foundation models become easier to replace, will banking software competition depend less on who owns the AI and more on who controls the workflows where agents can act?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 4, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Digital Assets Blockchain And Tokenization, Cybersecurity Fraud And Financial Crime, SME Finance And Business Banking, Capital Markets And Market Infrastructure, Policy Regulation And Governance, Risk Compliance And Regtech, Data Privacy And Governance

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026).
AI training data now carries an auditable collection burden across source choice, legal basis, sensitive data and model output controls. Canadian fintechs using European personal data should map what is scraped, why it is needed, who controls the processing and how records can be filtered or removed before consultation language becomes supervisory practice.
Fund innovation depends on regulatory speed as well as product design. Asset managers, exchanges, fintechs, wealth platforms and regulators should watch how dedicated approval pathways and product specific guardrails influence the pace of retail investment innovation without reducing investor protection.
Swift is testing whether tokenized deposits can extend today's banking infrastructure into always available cross border payments without replacing existing settlement systems. The pilot results will provide an early benchmark for bank led tokenized payment networks.
Always on market design is moving beyond crypto. Exchanges, brokers, clearing firms, liquidity providers, risk teams and regulators should watch how 24/7 trading changes oversight, operations, margin, surveillance and market resilience.
Credit infrastructure is consolidating around data depth, identity coverage and alternative underwriting. Lenders, fintechs, credit bureaus, SME finance platforms and regulators should watch how alternative data, fraud controls and AI assisted decisioning affect credit access for thin file borrowers and small businesses.
Hong Kong is replacing a widely used authentication method across online securities and regulated virtual asset trading. Brokers and platforms also need stronger monitoring, client notifications and incident response procedures, while senior management may be held accountable for losses caused by inadequate controls.
The findings connect payment design directly to fraud exposure, customer friction and trust. Lower fraud by transaction count is encouraging, but higher losses by value and rising first-quarter fraud show why scale requires stronger authentication, transaction risk data and coordinated controls. These operating results add important context to the UK’s payment milestone and Canada’s trust framework.
Financial institutions and technology providers will gain a structured environment for testing AI security tools against European requirements. Firms serving the European market should prepare to demonstrate model safety, operational resilience and secure deployment before advanced systems enter critical financial operations.
AI cyber risk is now a financial stability issue. Banks, fintechs, payment firms, infrastructure operators, software vendors and supervisors should watch how AI vulnerability discovery, third party concentration, open source dependencies and cyber resilience planning become part of financial sector oversight.
Circle's trust charter places a major stablecoin issuer inside the U.S. federal banking framework. The pace of implementation, custody adoption and any future expansion into reserve management will show whether trust banks become the preferred operating model for regulated stablecoin infrastructure.
The paired licences let one regulated provider connect crypto conversion, asset transfers, conventional payments and payment accounts. Firms pursuing similar models across Europe will need to determine when MiCA authorization must be combined with payment permissions as their products cross from digital assets into fiat payment execution.
Crypto platforms are moving toward regulated multi-asset investment access. Exchanges, brokers, dealers, crypto platforms, regulators and investors should watch how derivatives, equities and crypto converge inside licensed investment platforms.
MiCA is becoming a market access gate for global digital asset firms. Banks, payment companies, custodians, stablecoin issuers, exchanges and compliance teams should watch how full EU authorizations shape cross-border crypto services, institutional distribution and regulated stablecoin infrastructure.
Eltropy is turning agentic banking into a platform market rather than a closed vendor product. The commercial question is whether shared controls, integrations and distribution can make specialized financial agents easier for smaller institutions to adopt.
Regulated AI adoption needs control infrastructure, not only models. Banks, insurers, telecoms, fintechs and compliance teams should watch how agent oversight, inference monitoring, shared IP and enterprise control planes become part of Canadian AI governance.
AI in retail finance is becoming a competition, consumer protection and fraud issue at the same time. Banks, fintechs, wealth platforms, insurers, lenders and compliance teams should prepare for AI agents, personalization, delegation, identity controls and new forms of consumer harm.
Large fintechs are testing direct charter strategies again. Lenders, BNPL firms, embedded finance platforms, banks, investors and regulators should watch whether major payment and credit firms choose bank partnerships, owned charters or hybrid models for the next stage of regulated growth.
Regulators are increasing both the reach and speed of financial misconduct enforcement. Firms now face faster detection, coordinated action across jurisdictions and far less time to correct weak promotion, reporting and compliance controls.
This week’s intelligence points to a more mature phase of financial innovation. Stablecoins are entering regulated banking structures, tokenized deposits are nearing live payment use, regulators are setting terms for continuous markets, and AI governance is becoming a practical operating requirement. In Canada, the Real Time Rail rules, PSP access model and planned Q4 launch show how domestic payment modernization is entering the same execution stage. Advantage will favour institutions that can combine trust, regulatory readiness and delivery at scale.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 10, 2026
Financial technology organizations are often able to grow - employing staff from different countries - these companies use international recruitment to address high workloads, find highly trained employees and enter new geographical areas. Many professionals, like software engineers, data researchers and client service experts, prefer roles that allow them to work from any location. While these hiring practices are beneficial, businesses are responsible for managing the specific challenges involved.
Worker classification is a primary factor for companies to manage when they hire across borders. Organizations that identify their staff correctly are able to prevent legal disputes and avoid the loss of money. Businesses that operate in multiple countries have fewer administrative tasks when they clearly define the legal status of their international workers.
Worker classification is the process where an organization determines if a person is an employee or an independent contractor. Companies are required to follow specific guidelines to establish the legal status of their workers. Government agencies and courts evaluate the degree of control an employer has and how much independence a worker maintains to make this decision. Please be aware that the label a company gives to a worker is not the only factor that determines their status.
This consideration is particularly important for companies that staff internationally. The status of a worker who provides services from abroad can change depending on the country where they originate. As such, businesses should understand the implications of classifying employees as independent contractors outside their jurisdiction.
Businesses can suffer adverse financial and legal consequences from misclassifying workers. For instance, companies may incur substantial expenses by following court orders mandating retroactive payments of payroll taxes, overtime, and social benefits. In addition, businesses must consider litigation costs in any resulting disputes over misclassification.
Companies that hire internationally must navigate complex legal frameworks when classifying their workers. Most jurisdictions allow businesses to employ independent contractors on either a full-time or part-time basis. However, certain countries require organizations to treat such workers like employees. It can be challenging to ensure that employment terms abide by all applicable statutory requirements in different jurisdictions. As such, companies may find themselves facing adverse consequences when trying to establish long-term contracts for workers based abroad. To mitigate these risks, businesses turn to local attorneys and a Toronto Employment Lawyer to understand the implications before hiring.
How a company classifies its workers influences how the business functions. Management must recognize the administrative tasks and legal requirements that apply to different categories of workers - these arrangements are important because they change how the company processes payroll, manages benefits plus protects private data. Leaders are able to use this information to plan their workforce and lower the risk of legal disputes.
The status of a worker is what defines their specific legal rights but also responsibilities. Individuals who are employees are usually eligible for more protections and company provided benefits than those who are independent contractors. If a company understands these distinctions, it is able to follow the law as well as maintain a consistent hiring process - this knowledge is necessary for organizations that intend to grow in multiple countries and use the specific abilities of their staff effectively.
The financial technology industry is subject to many regulations. Companies are required to dedicate time and money to follow laws regarding data privacy, security for digital information plus financial reporting. This commitment to compliance is also necessary when businesses hire staff. Classification of workers is an important process because these organizations manage private data and perform money transfers for customers. Organizations that hire people in other countries are encouraged to monitor legal changes but also speak with an employment lawyer. Audits are a helpful tool to identify problems and lower risks before a company hires remote employees.
Fintech companies often find benefits in hiring employees from other countries - this approach allows businesses to grow and find qualified workers in a larger market. All staff members must follow the same professional requirements regardless of their location. Management teams are responsible for creating clear rules for international hiring to keep processes uniform and minimize potential problems.
Rules change depending on the country - businesses are more successful when they monitor legal updates. A detailed plan for following laws is necessary because international employment is complex - these strategies are also important for keeping the trust of investors and protecting the public image of the company.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 9, 2026 | NCFA Market Activity | Payments And Money Movement, SME Finance And Business Banking, Fintech And Innovation
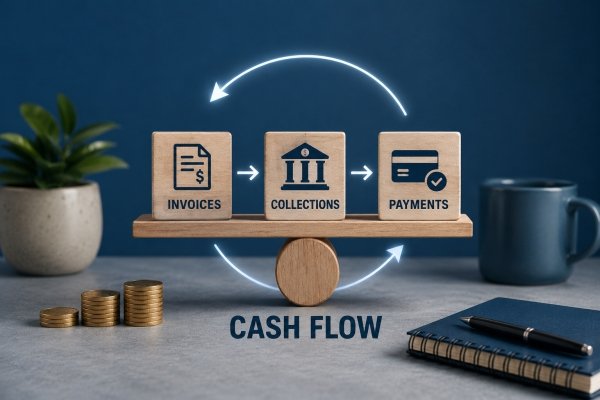
On July 7, 2026, Winnipeg based Telpay announced that it acquired Notch Financial, a Toronto based accounts receivable automation company. Terms weren't disclosed.
The acquisition brings accounts receivable, invoicing and payment collection together with Telpay’s existing payment, payroll and approval workflows, expanding the platform from payment execution toward SME cash flow management.
Mark Loewen, President of Telpay, said:
"Businesses don’t lose sleep over how payments are processed, they worry about whether they’ll have the cash they need when they need it."
Notch Adds Receivables To Telpay who has spent more than 40 years helping businesses manage money going out through supplier payments, payroll and approval workflows. Notch adds the incoming cash side, including invoices, collections and receivables visibility.
The transaction confirms that Telpay is going from payments execution toward cash flow control for Canadian SMEs.
The acquisition comes as Canadian small businesses are paying closer attention to receivables, working capital and payment timing.
Payment timing remains an important operating indicator for Canadian SMEs. See: Canadian Small Business Revenue Turns Negative In Q4.
Cash flow pressure doesn't always come from a lack of sales. It can come from slow collections, manual invoicing, fragmented approvals or poor visibility into what cash is actually available. That's why AR and AP automation are becoming core SME infrastructure rather than back office software.
The same trend appears in Open Finance SME Capital Access, where fresh invoice, payment, account and cash flow data can support faster credit decisions and better liquidity tools.
Payment companies are expanding beyond transaction processing into the operating layer around cash flow. See: Lloyds Expands SME Payments With Stripe Infrastructure.
The strategic question though is who owns the actual SME relationship? The account, the payment workflow, the operating data or the cash flow tools.
Telpay now covers both sides of SME cash flow: (1) Outgoing payments through supplier payments and payroll, and (2) Incoming cash through invoicing, collections and receivables visibility.
The platform value increases when a business can see both sides without stitching together separate tools.
Jordan Huck, CEO of Notch, said:
"Together, we see tremendous opportunities to deliver even more value as businesses manage every aspect of their cash flow."
Will Canadian SME payment platforms win by processing transactions, or by owning the cash flow workflow around invoices, collections, approvals and working capital?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 9, 2026 | NCFA Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech, Cybersecurity And Fraud, Digital Identity And Trust, Payments And Money Movement, Digital Assets Blockchain And Tokenization

On July 8, the Cambridge Digital Innovation & Regulation Initiative (C:>DIR), hosted by Financial Innovation for Impact (Fii), launched the Global Agentic Regulator Hackathon. Applications are NOW OPEN for a worldwide challenge that brings together policymakers, regulators, AI researchers, engineers, financial institutions, fintechs, RegTechs, SupTechs, academics and technology innovators to develop practical, explainable and deployable agentic AI prototypes for public authorities. The National Crowdfunding & Fintech Association of Canada (NCFA) is participating as an Ecosystem Partner to help promote the initiative across global fintech ecosystems, including Canada's fintech, AI and innovation networks.
The virtual hackathon runs from July 8 to September 18, 2026, with concept note submissions due by July 31. It carries a US$100,000 prize pool, and winning teams will also be invited to present at the Singapore FinTech Festival, hosted by GFTN. The launch is supported by the BIS Innovation Hub, Global Financial Innovation Network (GFIN), Digital Regulation Cooperation Forum (DRCF), and a global group of supporters, ecosystem partners and academic institutions.
AI agents are already operating in financial services. The next question is whether regulators will have the tools to supervise them.
According to the organizers, the CCAF 2026 AI in Financial Services Global Report found that 58% of fintechs and 47% of traditional financial institutions are adopting agentic AI, compared with 28% of regulators. That gap is important because AI agents can recommend, transact, monitor, route, execute and coordinate across systems faster than traditional supervisory processes were designed to handle.
This is why the hackathon is strategically important. It treats agentic AI as a supervision and infrastructure issue, not just a productivity tool. Public authorities need better ways to monitor risks, test model behaviour, understand accountability and respond to market activity that can develop at machine speed.
Participants will develop prototypes across six challenge areas:
These themes reflect where financial supervision is likely to be tested first as AI systems begin initiating transactions, interacting with digital assets, providing financial guidance and coordinating increasingly complex financial activities.
For founders, researchers, fintech teams, RegTechs and infrastructure providers, the opportunity is not simply to build smarter AI. It is to help shape the supervisory capabilities that may define trusted digital finance as autonomous systems become more common.
The breadth of organizations involved is a strong signal. With regulatory partners, global financial innovation networks, technology firms, academic institutions and ecosystem groups participating, the hackathon shows that agentic AI oversight is becoming a shared public and private sector priority.
For Canadian participants, the timing is also practical. Canada has strengths in artificial intelligence, financial services, digital identity, payments, cybersecurity, digital assets and regulatory innovation. This gives Canadian builders a chance to contribute to global supervisory tools before standards and operating models become more established internationally.
The organizers are seeking multidisciplinary teams that combine regulatory knowledge with technical expertise, including:
| Milestone | Date |
| Preliminary round opens | July 8, 2026 |
| Concept submissions close | July 31, 2026 |
| Teams selected | August 4 to August 14, 2026 |
| Virtual build phase | September 1 to September 8, 2026 |
| Global demonstrations and regulator voting | September 15, 2026 |
| Winners announced at the C:>DIR Summit, Cambridge | September 18, 2026 |
Applications for the preliminary round are open until July 31, 2026. Regulators, AI researchers, engineers, fintechs, RegTechs, SupTechs, financial institutions, universities and technology innovators are invited to submit concept notes and develop practical agentic AI prototypes for the future of financial supervision.
Read the full challenge details and submit your application through the official C:>DIR Global Agentic Regulator Hackathon page.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 8, 2026 | NCFA Market Activity | SME Finance And Business Banking, Artificial Intelligence And Data, Digital Identity And Trust, Cybersecurity And Fraud, Fintech And Innovation

On July 7, 2026, Equifax announced a definitive agreement to acquire Círculo de Crédito, a Mexican credit information services company, for a $750 million enterprise value. The companies expect the transaction to close in the fourth quarter of 2026, subject to closing conditions and regulatory review.
Círculo de Crédito operates consumer and commercial credit bureau services in Mexico. Equifax says the company serves more than 1,700 bank, retail, fintech, small business lending, microfinance and telecommunications customers, with 2 billion tradelines covering 80 million validated identities.
The deal expands Equifax’s international credit data footprint in Mexico, which Equifax describes as one of the fastest growing credit markets globally. Círculo de Crédito generated an estimated $134 million in revenue for the 12 months ended June 30, 2026, up 31%, with $62 million of adjusted EBITDA.
Equifax says Círculo de Crédito uses alternative data, including gig economy transactions, utility payment history and telecommunications payment history. Mexico has a large underbanked population. Mexico is a market where more than 25% of the population lacks access to formal financial products and nearly 44% does not have a bank account.
Alternative data can help lenders assess thin file borrowers, informal workers, microbusinesses and consumers without deep traditional credit histories. It can also help challenge questions about consent, data quality, explainability, model governance and consumer protection when credit access depends on broader data signals.
More data can widen access, but only if lenders can show how the data is collected, governed, explained and challenged.
Equifax says the acquisition gives Círculo de Crédito customers access to Equifax cloud native capabilities, EFX.AI technology, identity protection and fraud prevention offerings.
Following closing, Círculo de Crédito will join the Equifax International business. Juan Manuel Ruiz Palmieri and the existing Círculo de Crédito team are expected to continue leading the company.
The acquisition also continues Equifax’s expansion strategy. CEO Mark W. Begor said Círculo de Crédito would be Equifax’s 17th bolt on acquisition in the past six years, bringing the total for that period to nearly $5 billion.
Lenders increasingly rely on identity coverage, alternative data, fraud controls and AI assisted underwriting to expand credit access. That same data quality issue appears in AI Won't Solve SME Finance Without Better Data, where the core problem is not model ambition, but whether business data is trusted, verified and usable.
That connects directly to Canada’s own SME finance debate. NCFA recently examined why SME loan competition in Canada is under review, including lender concentration, switching friction and access barriers for smaller firms.
It also fits the Open Finance SME Capital Access opportunity area, where SME data, credit access and open finance are already linked.
More data can support credit access. The hard part is proving that expanded data use remains accurate, explainable and fair.
Can alternative data expand credit access without creating new blind spots in consent, model governance and borrower recourse?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016