




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Strategic Planning | Nov 28, 2025

Image: Freepik/rawpixel.com
2026 is approaching and fintechs are entering the new year with clear signals on how capital is being deployed, how financial institutions are investing in automation and AI driven capabilities and which policies will shape financial infrastructure. Markets place a higher premium on efficiency, governance and resilience as financial institutions modernize data access and digital settlement. Retail investor participation also expanded as equity crowdfunding set new records in Canada, strengthening another channel of capital formation.
United States tariffs and interest rate expectations continue to influence capital costs and enterprise demand across North America. Singapore FinTech Festival 2025 recently wrapped and outlined what global leaders expect over the next decade. This article provides an overview of how these forces intersect and will impact 2026 conditions, helping fintechs define runway, product plans and investor alignment for the year ahead.
Global investors concentrated capital into fewer fintech companies through 2025. KPMG tracked $44.7B across 2,216 global fintech deals and reported stronger momentum in digital assets and AI powered platforms. The global fintech funding review for 2025 notes uneven performance across payments and infrastructure and continued strength in digital asset investment. AI influence extends across every funding stage and drives the clearest premium in investor behaviour.
Canadian fintechs raised about $1.62B across 60 deals. KPMG data reported by Lexpert shows a steep decline from record 2024 levels as investors became more selective and disciplined. KPMG’s H1 2025 report confirms the trend toward fewer large cheques and more careful deployment.
CVCA reported $2.9B across 254 Canadian VC deals with average cheque sizes near $11.4M. The VC deployment across Canada in H1 2025 reported that early stages represented more than half of deal count but only 10% of dollars. NCFA’s seed review shows AI companies raising about $24M across 12 early stage rounds and fintech attracting about $9M across pre-seed and seed combined in the seed investing trends in H1 2025.
Canadian founders also turned to retail investors through regulated equity crowdfunding channels. FrontFundr, a leading Canadian investment crowdfunding platform, enjoyed a banner year raising CAD $68.3M across 66 campaigns in 2024 with 4,226 individual investments, its strongest year on record. This growth in community capital raising speaks volumes that diversified sources of early stage capital can complement VC allocations during selective cycles. For fintechs, retail participation can help extend runway, validate demand and reduce dependence on a small number of institutional investors.
AI remains the strongest source of valuation strength across the fintech sector. NCFA’s analysis shows that AI fintechs attract a 242 valuation premium compared with non AI peers. This tells fintechs that investors reward automation, accuracy and data advantage even during slower deployment cycles. AI's impact will continue to drive product development strategy, unit economics and growth planning for 2026.
Open banking moves into implementation. Budget 2025 commits to a consumer driven banking framework that designates the Bank of Canada as the supervisor for accredited participants and sets rules for data access, liability, security and technical standards. The consumer driven banking framework in Budget 2025 changes data mobility from one off arrangements to regulated data rails. These data rails also support AI adoption because models require secure access to high quality data. Fintechs that prepare for accredited access and safe data workflows will gain an advantage as institutions deploy AI into risk, compliance and customer operations.
Fintechs should expect accreditation activity, testing and early stage integrations as technical standards move toward production readiness through 2026.
Retail Payment supervision is operational and supports future access to real time settlement. Under the Retail Payment Activities Act, the Bank of Canada supervises payment service providers to ensure operational resilience and safeguarding of client funds. This oversight creates the regulatory foundation required for participation in core payment systems. Payments Canada continues development of the Real Time Rail (expected Q2 2026), while the Bank’s commentary on cashing in on payments innovation explains how regulation strengthens competition and prepares the foundation for modernized settlement. It also sets the operational standards that AI systems must meet for real time fraud detection, liquidity monitoring and compliance automation. Fintechs should plan for higher compliance expectations in 2026 and a clearer pathway into national payment systems once real time settlement becomes available.
Stablecoin regulation advances. Canada released the first draft of its federal stablecoin legislation which sets out rules for high quality reserves, custody, redemption, disclosures and prudential oversight. NCFA’s summary of the first draft of the Stablecoin Act outlines a government framework that brings fiat backed stablecoins into a supervised environment. As tokenized settlement expands, AI will move deeper into treasury, reconciliation, fraud control and settlement routing. Fintechs that design early AI enabled settlement workflows will operate more efficiently under these rules. Fintechs involved in digital money, cross border payments or tokenized settlement should expect stronger regulatory clarity across 2026.
Climate and sustainability disclosure remains paused. CSA halted its mandatory climate disclosure rule in April 2025 and signalled the pause will continue. Although the rule is on hold, enterprise buyers and investors still assess climate and transition risk data during diligence. The CSA climate disclosure update notes that existing materiality rules and OSFI Guideline B-15 still apply through 2026. AI plays a growing role in climate analytics and transition planning, which means fintechs that use AI for risk scoring and scenario work will offer enterprise buyers more actionable intelligence during diligence. Fintechs should assume voluntary disclosure is expected even without a formal mandate.
Competitiveness pressure remains. Bank of Canada leadership warns that slow progress on open data, payment modernization and digital infrastructure affects productivity and innovation. Reuters coverage of the warning on over regulation and competitiveness highlights the need to accelerate foundational reforms. AI impacts that competitiveness gap because institutions deploy AI into fraud detection, lending, treasury and customer workflows. Fintechs that use AI with strong governance will operate more efficiently, support regulated environments and scale faster when data access and payment rails modernize.
For fintechs, these signals point to regulated data access, modern payments and digital assets becoming the highest value infrastructure themes for 2026..
Fintechs operating in the North American economy are being impacted by United States tariffs, rate decisions and political volatility. United States imposed tariffs cut Canada’s projected GDP growth to about 1.4% in 2025 and 1.6% in 2026, according to IMF linked projections. These estimates reflect weaker demand and reduced investment appetite across export dependent sectors. Fintechs should treat tariffs as a structural constraint for 2026, not a short term shock.
Markets now expect the Federal Reserve to cut rates in December. Polymarket shows an 87% chance of a 25 point rate cut, based on more than $183M in trading volume, which reflects strong real time sentiment. Economists still expect only small rate cuts through 2026, with United States growth around 2% and inflation near 2.6%. Fintechs may receive some cost of capital relief but investors will continue to expect efficient spending, strong revenue performance and clear evidence of product viability at today’s cost structure.
Canadian monetary authorities modeled the tariff impact and warned that trade friction could reduce investment by about 12% and lower output by almost 3% over two years. The Bank’s scenario work on tariffs and structural change supports planning for lower investment and slower recovery.
Fintechs should prepare for slower enterprise procurement cycles and more selective purchasing behavior.
Global growth projections dropped to about 2.8% in 2025 as tariffs spread and trade tensions widened. Export Development Canada’s global economic outlook for 2025 and 2026 forecasts Canadian growth around 0.8% in 2025 and 1.1% in 2026. Fintechs should expect slower demand, higher operating costs and more uncertainty across key trading regions.
An MIT study released in 2025 shows that about 12% of United States jobs could be automated using current AI tools today. As AI pressure intensifies it drives enterprise demand for automation, cost control and compliance. It also accelerates talent scarcity and raises expectations for governance and model transparency across financial services.
Global regulatory fragmentation expands. The EU AI Act, United Kingdom digital regulation, Singapore AI governance frameworks and China data sovereignty rules all diverge. If fintechs want to scale internationally in 2026, they must build modular compliance, auditability and data governance into core architecture.
SFF 2025 provided a clear view into the next cycle of fintech infrastructure and the capabilities that institutions expect. The SFF 2025 blueprint for the next decade of finance placed AI, tokenized settlement, quantum readiness and talent at the centre of global financial transformation for the coming years.
AI moved into production across onboarding, monitoring, underwriting and support. Financial institutions showed mature applications that reduce fraud, improve accuracy and accelerate customer workflows. Tokenized finance advanced as central banks and major institutions tested tokenized settlement assets, wholesale CBDCs and regulated stablecoins. These experiments are clear move from demos towards infrastructure design.
Quantum readiness entered strategic planning as banks prepared for post quantum cryptography and assessed their high value data inventory.
Talent emerged as one of the most constrained resources, with strong demand for cybersecurity, data and AI capabilities.
2026 will reward fintechs that integrate AI into their core stack, design products that support tokenized workflows, build quantum safe readiness and hire for digital infrastructure skills that support resilience and scale.
| Canada Policy Shifts That Drive 2026 Strategy | ||
|---|---|---|
| Open Banking Readiness | Canada moves to regulated data rails with accreditation and Bank of Canada oversight. | Build accredited data access readiness now. This creates a major advantage when banks and credit unions adopt regulated data sharing in 2026 and gives fintechs a lead when institutional partners demand safe integration. |
| Payment Supervision Alignment | Retail Payment Activities Act supervision is active and PSPs prepare for Real Time Rail participation. | Raise operational standards to meet supervision requirements. This clears the path for Real Time Rail access when available and strengthens partnership credibility with banks that expect higher resilience from PSPs. |
| Stablecoin Compliance Design | Canada released the first draft of the Stablecoin Act with rules for reserves, custody and redemption. | Design compliance into digital money products now. This avoids costly retrofits when rules finalize and positions fintechs for early participation in tokenized settlement experiments that banks support across 2026. |
| Transition And Climate Disclosure | CSA paused mandatory climate disclosure but investors still expect transition data in diligence. | Maintain credible voluntary disclosure. This reduces diligence friction with investors and large institutions that rank climate and transition data as core risk inputs even without a mandate. |
| Capital Conditions For Canadian Fintechs | ||
| Runway Discipline | Canadian funding normalizes with more selective deployment and fewer large rounds. | Plan 18 to 24 months of runway. This protects valuations and gives Canadian fintechs flexibility during slower deployment cycles and longer diligence timelines. |
| Revenue Quality First | Investors reward revenue durability as rates in the United States and Canada change slowly. | Increase margins, retention and customer lifetime value. This strengthens funding outcomes and signals that the business performs at today cost of capital. |
| Diversified Capital Routes | Equity crowdfunding reached record levels with rising retail participation in Canada. | Use investment crowdfunding to extend runway and validate market demand. This reduces reliance on a small number of venture investors and supports growth during selective funding cycles. |
| AI As The Primary Driver Of Competitiveness | ||
| AI As Core Infrastructure | SFF 2025 showed AI runs onboarding, risk, fraud and support in production. | Automate core work and improve accuracy. This reduces cost, raises product reliability and strengthens enterprise trust when selling into Canadian banks and credit unions. Remember, AI fintechs receive a valuation premium because automation and accuracy improve economics at every growth stage. |
| Model Governance Strength | Institutions expect clear model behaviour and explainability before integration. | Document lineage and monitoring with precision. This increases procurement success and accelerates enterprise adoption when institutions face rising AI governance requirements. |
| AI Driven Efficiency | Canadian enterprises invest in automation as budgets remain tight. | Replace manual workflows with AI to lower operating cost. This strengthens margins during slower growth and improves investor confidence. |
| Tokenized Settlement And Security Readiness | ||
| Tokenized Settlement Readiness | Banks and central banks test tokenized deposits and wholesale CBDCs. | Design workflows that support tokenized settlement. This prepares Canadian fintechs for early pilot participation when infrastructure tests expand in 2026. |
| Quantum Safe Architecture | Institutions begin planning for post quantum encryption. | Inventory sensitive data and adopt cryptographic agility. This protects long term assets and reduces future migration cost for Canadian fintechs selling into regulated environments. |
| Trade, Tariffs And Canadian Procurement Conditions | ||
| Adjusted Sales Cycles | Tariffs reduce Canadian investment and slow enterprise buying. | Extend sales cycle assumptions and build conservative forecasts. This improves cash planning and prevents burn surprises when procurement slows across regulated sectors. |
| Cost And Risk Value Propositions | Global growth slows and Canadian enterprises protect budgets. | Lead with measurable savings and risk reduction. This increases purchase probability in cost constrained environments and improves sales success during slow demand cycles. |
As the close of 2025 nears, fintechs operate in a world where capital rewards evidence first, and where AI driven performance gains receive premium valuation only when they improve accuracy, automation or margins. Fintech policy advancement in Canada moves forward on open banking, payments and stablecoins and these developments create new regulated rails to build on. Tariffs, interest rates and slower global growth increase the need for financial discipline and durable revenue streams. Retail investors also became more active in 2025 as equity crowdfunding set new records, giving Canadian fintechs another way to raise capital when venture funding is more selective. SFF 2025 highlighted the technologies that will shape financial infrastructure for the next decade.
Fintechs that align their strategy with the forces that matter, including AI, regulated data access, modern payments, tokenized settlement and stronger governance, will be better positioned to raise capital, win enterprise partnerships and scale through uncertainty.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
FrontFundr | Nov 20, 2025
Image generated by AI
On 18 November 2025, FrontFundr announced its fiscal year 2025 results for the year ending 30 September 2025. The company reported revenue of $1.85 million, which it stated was a 60% increase from fiscal 2024. FrontFundr also reported an EBITDA loss of $45,000, compared with a loss of $1.25 million in the previous fiscal year. The company described these results as its strongest annual performance.
According to the release, FrontFundr processed $81.4 million in investment volume during fiscal 2025, representing a 45% increase over fiscal 2024. The company completed 5,729 investment transactions during the period, nearly double the number completed the year before.
The company also increased it's investor base in 2025 with 58,335 registered users, an increase of 24% over the prior year. The number of active investors reached 20,148, an increase of 28% compared with fiscal 2024.
FrontFundr cited several campaigns that contributed to activity on the platform. Edison Motors raised $6.9 million, and Blossom Social raised $1.93 million in under one week marking Canada’s most successful equity crowdfunding campaign.
The company also provided early results from the start of fiscal 2026. FrontFundr generated $255,200 in revenue for October 2025, which exceeded its internal monthly target by 68%.
FrontFundr mentioned in the release that these stellar fiscal 2025 results coincided with the firm's 10 year milestone from the day the company processed its first investment in May 2015. The release links the milestone with the reported increases in revenue, completed transactions, investment volume, registered users, active investors, and individual campaign outcomes.
With equity crowdfunding as part of the wider private markets landscape in Canada, the Canadian Venture Capital and Private Equity Association reported that the first nine months of 2025 marked the strongest nine month period on record for private equity, with $56.5 billion across 483 transactions.
FrontFundr’s fiscal 2025 results highlight a year where the company reported growth across its platform, and reaching the 10 year mark offers a moment to congratulate Peter-Paul and the entire team and acknowledge the sustained multi year effort behind that progress. Recognizing this milestone is appropriate as the company continues its work within Canada’s developing investment crowdfunding and private market investing landscape.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Financing | Nov 11, 2025
Image: Freepik/rawpixel.com
On November 6 2025, Canadian founded DealMaker announced that it has secured $20 million USD in equity and debt financing led by Information Venture Partners and CIBC Innovation Banking. The company recently opened new U.S. headquarters in New York City in April of this year. DealMaker says funds will support product innovation, AI deployment, and market expansion as the company continues to innovate how issuers connect directly with investors (aka investment crowdfunding).
DealMaker’s model is built around direct-to-investor offerings, allowing startups, growth stage companies, and pre-IPO issuers to raise funds without intermediaries. The company has now powered over 900 offerings and processed more than 1.5 million individual investments, representing over $2.3 billion raised.
By combining digital onboarding, payments, and investor relations tools, DealMaker positions itself as a single platform for issuers seeking efficiency and transparency in capital formation. While its current operations are centered in the United States, DealMaker’s origins and investor ties highlight the role Canadian fintech expertise continues to play in North American capital markets.
Rebecca Kacaba, DealMaker Co-Founder & CEO:
"This round allows us to accelerate the deployment of AI across our product line, capitalize on emerging ownership models across professional and collegiate sports, and deliver greater value to our customers. This positions DealMaker to be a market leader in a rapidly growing sector where more and more companies-from startups to the hottest IPOs are prioritizing retail investors."
The capital will accelerate the rollout of AI across its platform and strengthen products such as DealMaker Sports, its new division connecting retail investors to sports ownership opportunities.
DealMaker Sports enables leagues, teams, and athletes to tap into their own communities for capital by converting fans into investors. With a platform built for speed, checkout is mobile-friendly and brands get real-time analytics on who’s investing and why. Raise under exemptions like Reg CF, Reg A+ and Reg D, whether you’re targeting $500 K or $50 M and build loyalty, revenue and growth all at once.
As AI becomes embedded in every part of financial infrastructure, platforms like DealMaker could help reduce friction, lower costs, and expand access to retail participation. For Canadian fintechs, DealMaker's success reinforces the importance of building scalable, compliant, and investor-centric solutions that can compete globally while supporting innovation and inclusion.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Equity Crowdfunding | Oct 31, 2025
Image: Gander Social via FrontFundr equity crowdfunding campaign
On October 24, 2025, Gander Social, a Canadian alternative to foreign-owned social platforms, announced that they surpassed $1 million raised from more than 1,595 investors in its initial private community phase, exceeding their target in just over a week. Then on October 30, the company announced in a release that they are opening the campaign up to the public on FrontFundr, inviting Canadians across the country to join its growing base of community owners.
The campaign has now raised almost $1.2 million and is targeting $1.5 million and continues to grow rapidly through organic participation and word-of-mouth sharing, demonstrating the strong appetite for Canadian-built platforms and the expanding role of equity crowdfunding in mobilizing retail investors, especially at a time when early stage venture funding channels are under pressure.
Led by Ottawa-based longtime creative director turned founder CEO Ben Waldman, Gander Social is built by a small team of Canadian engineers and creators who want to give people a trustworthy alternative to ad-driven social media. The company is structured as a Public Benefit Corporation, showing its commitment to long-term public accountability rather than short-term profit. Waldman described the movement behind Gander as “more like a call to arms,” a push to rebuild online spaces around community ownership and digital sovereignty.
BenWaltman, CEO Gander Social:
By setting a minimum investment of $255, Gander is making participation accessible to everyday Canadians. The campaign reinforces the growing “keep it in Canada” mindset that prioritizes domestic ownership, ethical innovation, and sustainable platform design. Investors are not just looking for returns but they want to help define the kind of digital economy they want to see in Canada.
As Canada feels the geopolitical pressures, across the country investors are embracing equity crowdfunding to participate directly in the innovation economy and keep growth capital in Canada. It’s a model that strengthens community engagement while advancing national competitiveness and financial inclusion.
For policymakers and fintech advocates, Gander’s raise demonstrates how equity crowdfunding can mobilize citizens to fund nationally significant ventures. It shows how financial innovation and digital sovereignty can align to strengthen Canada’s independence, resilience, and competitiveness in a global tech landscape increasingly defined by foreign control. Learn more about the Gander Social campaign here.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech | Oct 3, 2025
Image: Freepik/newelement
On September 26, 2025, the Globe and Mail released its 2025 Report on Business ranking of Canada’s Top Growing Companies. The annual list tracks Canadian firms based on three-year revenue growth, offering a quick snapshot of where innovation is scaling fastest (think revenue, headcount, growth).
This year’s ranking features a great group of fintech and digital finance firms that are impacting how Canadians borrow, pay, invest, insure, and embed financial services into everyday life.
| Rank | Company | Sector | Description |
| #3 | Gearlay | Web3 / Blockchain | Blockchain-based enterprise financial software |
| #4 | Float | Lending & Embedded Finance | SME finance and corporate card platform |
| #5 | veritree | ESG & Green Finance | Digital carbon credits and reforestation finance |
| #11 | Novisto | ESG & Green Finance | ESG disclosure, data, and reporting platform |
| #24 | FundMore | Lending & AI | Automated mortgage underwriting |
| #32 | Quandri | AI & Automation / Insurtech | Insurance automation bots |
| #39 | Autocorp.ai | AI & Lending | AI-powered auto retail finance |
| #44 | Helcim | Payments | Merchant payment processing |
| #57 | CapIntel | WealthTech | Digital platform for advisors and wealth managers |
| #62 | PomeGran | Digital Infrastructure | Broadband and connectivity backbone |
| #65 | BOXX Insurance | Insurtech | Cyber insurance and protection |
| #72 | SWTCH Energy | Payments Infra / Energy | EV charging + payments integration |
| #86 | Makeship | Alternative Finance / Crowdfunding | Creator crowdfunding platform |
| #108 | Fintel Connect | Web3 / Marketing | Performance marketing for fintechs and crypto |
| #110 | Justwealth | WealthTech | Robo-advisor portfolio management |
| #112 | HONK | Payments | Contactless mobility/parking payments |
| #119 | Merchant Growth | Lending & SME Finance | Working capital financing |
| #129 | MindBridge | AI & Regtech | AI anomaly detection and audit |
| #137 | Loans Canada | Lending & Alt Finance | Loan marketplace and credit scoring |
| #140 | PolicyMe | Insurtech | Digital-first life insurance |
| #149 | Zum Rails | Open Banking & Payments | Open banking and payments APIs |
| #158 | Trolley | Payments | Global payouts and compliance |
| #204 | FundThrough | Lending & Alt Finance | Invoice financing and cash flow optimization |
While the Globe and Mail ranking provides a valuable view of Canadian fintech growth, it is far from exhaustive. Many high-growth firms remain absent because they operate in stealth mode, choose not to disclose financial data, or do not meet eligibility thresholds. Early-stage innovators, companies with holding structures abroad, and ventures acquired by larger incumbents also fall outside the ranking.
For NCFA’s community, this means the list represents only part of the country’s dynamic ecosystem of fintech, Web3, AI, alternative finance, and digital-first ventures that are scaling globally. For a broader view of Canada’s financial tech innovation landscape, see NCFA’s fintech directory at https://fintechcanada.io/.
Canadian fintech companies are excelling in lending, payments, Web3, insurtech, ESG, AI, digital infrastructure, and many other subcategories. These companies mirror how regulation, access to capital, and collaboration between industry and government is critical to ensure Canadian fintechs continue to thrive in an increasingly globally competitive landscape.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crowdfunding | Oct 1, 2025
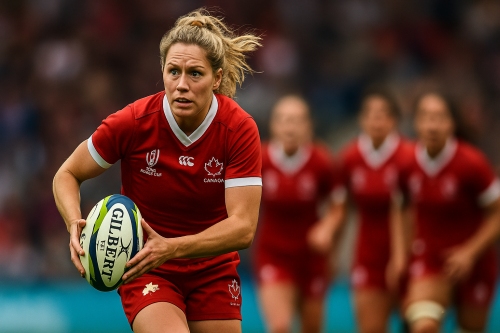
Image courtesy of AI
On March 7, 2025, Rugby Canada announced a bold public campaign to fund its women’s high performance team to England 2025. The campaign laid out a $1 million shortfall to cover the full season's program that costs $3.6 million (but the union's budget fell short). So to close the funding gap, they opened the doors to fans, alumni, and corporate donors and launched a dedicated donation portal for this effort: Mission: Win Rugby World Cup 2025 donation portal.
That night, the campaign thermometer sat at zero. By morning, it was alive as part financing tool and part storytelling engine that sparked a national movement in Canadian sport.
Rugby Canada needed more than dollars. They needed narrative. The early campaign push did three essential things well:
They didn't just ask for support but described the exact dollars missing and how each contributed dollar would map to camps, nutrition, recovery, and test matches.
Supporters weren’t just donors but they were treated as 'partners' in getting the Canadian Women's Rugby team ready for the World Cup 2025, a massive global sporting event.
Independent rugby media tracked progress. In April, RugbyPass ran a report noting the still‑open funding hole and provided key updates in how far along the drive had come, and how much further they still needed to go to achieve their mission.
As the 2025 Women's Rugby World Cup (hosted in England) drew closer and closer, media narratives framed Canada not just as underfunded underdogs but as gritty, scrappy, and deserving contenders. Sky Sports ran a feature titled “How non‑professional Canada crowdfunded its way to the final push,” saying pledges “reached 95 percent.”
Meanwhile, ESPN ran a narrative piece under the banner “Canada crowdfunded their way to the World Cup” juxtaposing the team’s funding shortfall with their on‑field ambitions.
Kudus to participating media that helped raise awareness for such an important Canadian funding drive. It really shows what's possible when the full ecosystem gets behind an initiative and drives momentum forward. There's a natural connection between executing a well timed and focused financing campaign and executing a key sports performance, and the public knows it. #ElbowsUp
When England 2025 kicked off, Canada stepped onto the pitch motivated by even greater purpose, not a team suffering by funding shortfall anxiety.
In pool play they went undefeated, carving out physical, disciplined performances that turned heads.
In the quarter final, they defeated a powerful Australia squad.
In the semi final, they shocked the rugby world by defeating New Zealand (perennial favourites) to reach their first Women’s Rugby World Cup final.
On September 27, before a packed Twickenham, Canada faced hosts England. They lost but not meekly. In the aftermath, coach Kevin Rouet and captain stressed that the match was decided on performance, not excuses, a point that resonates in Reuters’ coverage of the final.
Crowdfunding bought the players the chance to compete on equal footing, free of resource excuses. The lesson for Canada as a sporting nation was significant. When supports and fans step in to close gaps, institutions can't ignore the demand for sustainable, professionalized backing of women’s rugby.
Players adjusted their off season budgets and personal spending to show they were all in on the campaign narrative.
Coaching staff scheduled extra camps contingent on fundraising milestones, keeping the team in lockstep with the thermometer.
Each media checkpoint (50%, 80%, 95%) became a moment of drama as the story unfolded. Would the final stretch succeed or stall? That tension made the campaign itself a parallel storyline to the competition.
Critics wondered whether public fundraising blurred lines between sport and fandom but supporters embraced the risk, seeing their dollars as equity in national ambition at a time when Canada needs to buckle down and drive through the line.
When everyone's in the same boat, the winds will sail.
This was more than just a funding story. If you want one of those, feel free to read the real story of access to capital. It was about turning a resource gap (a modern day limitation) into shared ownership.
Canada’s women made their financial constraints visible, linked every dollar to performance outcomes, and invited supporters to become backers in the journey. That transparency changed how Canadians see women’s sport funding not as charity, but as investment with real returns.
The campaign also created accountability. Once the thermometer went public, the team owed backers results, not just thanks.
The story will not always be this dramatic, but the connections and motivations are real, and crowdfunding amplifies that blueprint. Define the gap, own the narrative, attach every contribution to a tangible outcome, and treat supporters as true partners.
Collaboration was at the core! Players, fans, alumni, sponsors, and media all carried their share of the work. As Canada’s women look beyond 2025, the responsibility now shifts to institutions, national sport bodies, sponsors, and public agencies to ensure future generations no longer need to crowdfund their path to the world stage, or maybe they should! #GoCanada
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
M&A | Oct 1, 2025
Image: Freepik
On September 18, 2025, US-based fundraising solutions provider RaiseRight announced the acquisition of Toronto-based FlipGive, a Certified B Corporation known for cashback shopping combined with community fundraising tools. Terms of the deal were not disclosed.
RaiseRight is based in Grand Rapids, Michigan and best known for scrip and gift card fundraising programs that direct spending power to local groups. The company cites more than $900 million raised with over 750 brand partners across 30 years of operations.
FlipGive first went public in 2013, self-described as a retailer-driven fundraising model for schools, sports teams and communities. When they first launched, the National Crowdfunding & Fintech Association of Canada listed FlipGive on it's original crowdfunding directory (not maintained since Jan 2019, as NCFA hosts a new fintech directory in Canada here. as crowdfunding for non profits through product sales and donations, a model that merged a crowdfunding ethos with shopping rewards and donations.
The focus evolved from one time pledges to everyday shopping that earns cash back for teams and community groups. Retailers and restaurants share a percentage of transactions, which turns routine purchases into a steady funding stream.
FlipGive later scaled embedded rewards and reported strong growth, including a $4 million Series B financing round in 2023 in an funding roundup mentioning FlipGive.
According to FlipGive’s own platform data, teams have raised more than $56.6 million through the service, converting everyday purchases into direct support for youth sports and community groups. This total reflects contributions generated from more than 50,000 teams (including my kids hockey team fundraisers!) via $425 million in sales across 900 brands, serving more than 900,000 FlipGive members.
These numbers clearly confirm the demand and impact of the cashback model and how it's grown into a significant funding source for local teams.
Nick Lee, Co-founder of FlipGive:
"From day one, our goal has been to support families and make team fundraising simple and effective. Joining RaiseRight, who shares our mission and values, ensures a future where even more families can benefit."
FlipGive’s brand and Canadian operations will continue while its technology integrates into RaiseRight’s broader platform. The combination adds white label rewards, scrip gift cards, online shopping, dining, and travel into one stack that organizations can use to fund sports, schools, and community programs.
Lou Agnese, CEO of RaiseRight:
"FlipGive has played a valuable role in shaping how communities approach fundraising through its technology and platform. We are excited to expand into the Canadian market and thrilled to welcome the FlipGive brand and team into the RaiseRight family. We will continue to build on FlipGive's innovations to deliver even greater value to the communities we serve across Canada and the United States."
This deal connects two complementary funding rails. FlipGive’s commerce driven crowdfunding roots evolved into cashback infrastructure with RaiseRight’s long running gift card model built to scale. Together they offer a cross-border platform that monetizes everyday spending for community funding while maintaining a social mission. For Canadian fintech and nonprofit stakeholders, the main questions are how will RaiseRight's acquisition steward FlipGive’s B Corporation identity and how integration will affect service for Canadian teams.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016