





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 29, 2026 | NCFA Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech, Competition And Market Structure

On July 29, 2026, KPMG Canada and OpenAI formed a Canadian alliance covering AI implementation, governance and cybersecurity. KPMG Canada also became an OpenAI Elite Partner, the highest level in OpenAI's partner network.
There's already a working base. More than 3,000 KPMG Canada employees have access to ChatGPT Enterprise. KPMG Canada says its Deal Advisory teams use Codex, OpenAI's coding agent, to help review thousands of pages of transaction documents and financial data, pull out relevant information and prepare analysis for professional review. KPMG Canada is also joining OpenAI's Daybreak Cyber Partner Program.
The alliance gives OpenAI a large Canadian delivery partner and gives KPMG closer access to the models, tools and technical support its clients are buying. The business opportunity lies in turning those tools into secure workflows that employees can use every day.
Ksenia Chumachenko, Head of Global Alliances at OpenAI:
"Canadian organizations are ready to move beyond pilots and put AI into production at enterprise scale."
Buying access to an AI model is straightforward. Connecting it to company data, permissions and existing software takes far more work. A bank reviewing customer files, a deal team reading contracts or a government department processing records also needs security controls, human approvals and a reliable account of what the system did. That's the work KPMG Canada wants to sell.
Its internal Codex workflow gives the firm a concrete implementation example, with experienced professionals still responsible for reviewing the output. KPMG Canada hasn't reported the time saved, accuracy rate, transaction volume or financial return. Those numbers will determine whether the partnership's service becomes repeatable and scales or remains an internal productivity case.
KPMG has used this delivery model before. Its work with CapIntel combines wealth technology with integration and change management for financial institutions. The OpenAI alliance applies the same commercial logic across a much larger range of business processes.
Cybersecurity adds another line of work. Through Daybreak, KPMG Canada plans to combine OpenAI models with its security and risk services. The announcement doesn't name a Canadian customer, deployed cyber product or launch date. Buyers should expect those details before treating the program as a proven commercial offer.
The Canadian agreement follows a U.S. alliance announced on July 21. The U.S. program includes OpenAI engineer certification, public sector software and work inside OpenAI's own supply chain systems. The Canadian announcement doesn't confirm that every U.S. program will be available here. The commercial aim is to get from a product demonstration to a paid deployment faster.
KPMG is keeping its model options open. A May 2026 Anthropic agreement is bringing Claude into KPMG's global workforce and client platforms. Canadian buyers will need to know why KPMG recommends one model over another and whether its commercial relationships influence that advice.
Canadian business use of AI rose from about 3% in 2022 to roughly 12% in 2025, while finance and insurance exceeded 30%. The Canadian adoption data points to a larger implementation market, with firms competing to connect AI to important work without losing control of customer data, security or accountability.
KPMG Canada has scale, technical access and more than 10,000 employees across over 40 locations. However, the alliance still has to prove that the finished systems are worth buying. Clients will want shorter processing times, lower operating costs, fewer errors or better service. They will also need clear rules for data access, human approval and responsibility when an agent produces a weak answer or takes the wrong action.
Specialist AI integrators and other large consulting firms are competing for the same work. Investors should watch for named production clients, repeat deployments, contract expansion and measured operating results. Partner status may open the door.
Which Canadian workflow will give KPMG and OpenAI their first measurable client result?
Follow the Canadian delivery, governance and security work most closely connected to this alliance.
Partner status and internal use examples do not establish client performance or future revenue. Undisclosed commercial terms and unreported operating results are identified as such. Information may change after the publication date. This content is provided for informational purposes only and does not constitute investment, financial or legal advice.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |

We're opening up more and more APIs to partners, fintech services, and client applications. The only question is whether we're confident these same APIs aren't opening up new paths for attackers.
Just a few years ago, a bank mostly dealt with its own systems. A customer would log into the app, check their balance, make a transfer. The whole journey stayed inside the perimeter of a single organization.
Today, one customer might simultaneously use a mobile banking app, a budgeting service, an accounting platform, a payment provider, and an AI assistant that analyzes their spending. All of these services exchange data through APIs - interfaces that let different systems talk to each other according to a set of established rules.
Open Banking isn't just a regulatory requirement or a new integration channel - it's a shift in the trust model itself. A bank used to be responsible for security within its own infrastructure. Now it hands off part of its data to dozens of external services, and those services, in turn, rely on the bank. The more participants in the ecosystem, the more points there are where trust is either reaffirmed or cracked, every single day.
Attackers are less and less interested in finding a weak spot inside any one bank. Today, hackers target the interaction between systems itself. The longer the chain - bank, fintech, payment hub, partner app - the more places there are for something to go wrong.
Common examples include:
An API can perform flawlessly on the functional side - fast, stable, no errors in the logs - and still carry a critical vulnerability. Functional correctness and cybersecurity don't always go together.
Banks and fintech companies generally don't neglect API security. They go through certifications, run automated scans, do code reviews and QA. But none of these tools answer the one question that matters most: can this specific API's logic be bypassed in a way its developer never anticipated? Scanning catches known vulnerability patterns; code review and QA confirm the code does what it was built to do. Neither one thinks like an attacker who isn't hunting for a bug in the code, but for a logical gap in how the API interacts with other systems.
That's why most attacks on financial APIs today aren't about technical mistakes - they're about logic: the sequence of actions, the boundaries of authority, the trust placed in data coming from the client. It's also why modern Cybersecurity Solutions for Fintech increasingly go beyond formal compliance with standards, testing real-world abuse scenarios at the points where multiple systems meet.
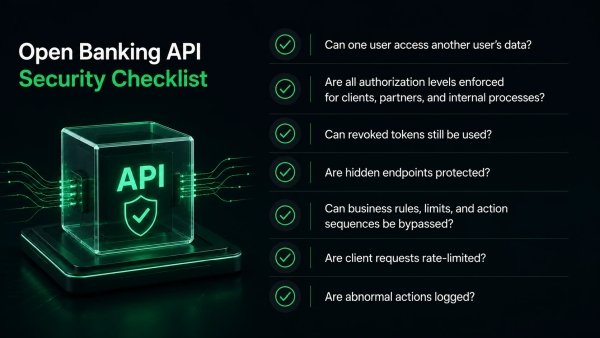
Here's a short checklist for reviewing every external API in your ecosystem:
If you don't have a confident answer to any of these, that's reason enough to look closer.
It's worth telling apart three things that often get lumped together. Vulnerability scanning looks for known vulnerabilities by signature, catching familiar vulnerability classes, common misconfigurations, and known dangerous patterns. Automated testing checks whether the code performs its intended functions correctly. Separate from both is API Penetration Testing (https://datami.ee/services/pentest/api-penetration-testing/) - manual testing in which a specialist plays the role of a real attacker: combining requests, tweaking parameters, hunting for unusual sequences of actions that a scanner, in most cases, won't flag as anomalous, because each individual request looks legitimate on its own.
It's also best if this kind of testing is handled by an external team. In-house specialists tend to know their own API inside and out - and that's precisely what makes it hard for them to spot an unconventional abuse scenario, since day-to-day work with a system's logic doesn't train you to look at it through the eyes of someone deliberately trying to break it. External specialists bring experience from other architectures and payment integrations, so they're more likely to catch the gaps a team had written off as unimportant.
A bank can offer the most convenient digital service and the best partner API on the market. But if even one partner or customer stops trusting the security of the data exchange, the benefits of Open Banking vanish almost instantly. Trust here isn't a bonus feature - it's the baseline condition, and without it the whole structure loses its meaning.
That's why investing in API protection in the financial sector isn't just about regulatory compliance - it's about sustaining trust across the whole ecosystem: between bank and fintech, fintech and customer, and customer and every new service they let into their data.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
About NCFA Canada | Craig Asano | July 24, 2026

David Gens is the Founder and CEO of Merchant Growth, a Canadian digital financing platform for small businesses. After graduating from UBC with a Bachelor of Commerce in Finance, David began his career as an analyst at private equity firm CAI Capital Partners. In 2009, at just 22 years old and in the aftermath of the global financial crisis, he founded Merchant Growth to help address the gap in access to capital for Canadian small businesses. Over the past 15 years, Merchant Growth has helped more than 15,000 businesses access over $1 billion in financing through technology enabled lending solutions. David also leads Merchant Opportunities Fund and has been recognized as a Business in Vancouver Top 40 Under 40, BC Business Top 30 Under 30, and an EY Entrepreneur Of The Year finalist.
What does it take to build a lending business that has deployed nearly $1.5 billion to small businesses over 17 years?
In episode 66 of NCFA Fintech Fridays, David Gens, Founder and CEO of Merchant Growth, shares how he built one of Canada's leading alternative small business lenders from the ground up.
We explore why many good businesses still struggle to access financing, how technology and AI are changing underwriting, what it takes to scale responsibly, and the lessons learned from serving more than 15,000 businesses. David also reflects on launching a fintech at just 22 years old, navigating changing economic cycles, building long term lending partnerships, and balancing innovation with disciplined risk management in an increasingly competitive lending market.
Whether you're building a fintech, running a growing company, investing in financial innovation, or interested in the future of small business lending, this conversation delivers practical insights on entrepreneurship, lending, risk management, AI, and long term growth. Enjoy!!
Duration: 110 mins
Intro: Welcome to fintech Friday's a weekly podcast brought to you by the National Crowdfunding and Fintech Association of Canada and partners. Covering all things fintech, blockchain, AI and alternative finance.
[00:00:30] Craig Asano: Hello everyone. It's Craig Asano, the founder and CEO of NCFA Canada, welcoming you to season 4, episode 66 of Fintech Fridays. It's a weekly podcast brought to you by NCFA and our partners featuring conversations with leading voices across fintech, funding, and financial innovation. We walk and talk to all the founders who are doing incredible things. We talk to them about their journeys, new product innovations, emerging trends in their market, and what's happening in the market right now from their perspective. So, today we're super excited to have another fantastic guest with us, and I'd like to introduce you to David Gens. He's the founder and CEO of Merchant Growth, a Canadian digital financing platform for small businesses.
So after graduating from UBC with the Bachelor of Commerce and Finance, David started his career as an analyst at a private equity firm called Kai Capital Partners. And in 2009 at the young age of 22 years old, we're going to get into this a little bit. just after the after the aftermath of the global financial crisis, he founded Merchant Growth to help address the gap in access to capital for Canadian small businesses. So during the last 15 years, I guess, Merchant Growth has helped more than 15,000 businesses access over a billion dollars in financing through technology enabled lending solutions. David also leads Merchant Opportunities Fund and has been recognized as a business in Vancouver top 40 under 40 and BC business top 30 under 30 and an EY entrepreneur of the year finalist. So David, thanks so much for joining us today to share your knowledge and expertise.
[00:02:14] David Gens: It's my pleasure to be here. Thanks for having me.
[00:02:16] Craig Asano: That is a mouthful. You have a lot of accolades there. I've always read all those.
[00:02:23] David Gens: You don't have to read all you remember the 30 under 30. You've you've been you've got a hell of a story and we're going to get into her you know, right now. But just to kick things off, I think let's get in with the first question. despite you know the advancements of technology and you know more financing for small business options than ever before small businesses it seems it's it's always you know never enough capital. There's always a struggle there to get enough capital to continue to grow. But from your perspective, what why is that gap why is it so challenging and has it changed or you know how in from where you sit in the last 15 years has it changed?
[00:03:09] David Gens: Yeah, it's changed. I mean we have obviously made a bigger dent into the problem. There's also competitors that we have in a whole industry now that you know really didn't exist when I started this. So a dent has been made but that doesn't mean the problem's solved, right? It's a big problem. It affects hundreds of thousands of businesses in Canada. and the problem is just that they don't have the kind of access to credit or capital in general that a larger company does. A larger company has the resources to spend time you know, sourcing capital in its various forms with finance teams and also on the other side of the table, banks that are providing credit and institutions etc. have the you know kind of the scale in those transactions to staff them up, be creative, have professionals look them over and figure out custom structured solutions to provide that larger business with that capital. With a small business, none of that exists in that way. And so it's it's cookie cutter solutions that traditional financial institutions look mostly at assets and whether or not they can lend against those. And if you're an asset light, cash flowing small business, you're not you know, given much credit from those traditional institutions. And if you think about most small businesses are asset light, but have cash flow. they serve customers in local communities. They might have a little bit of inventory. but at the end of the day, they typically don't have a lot of hard assets. and you know, any individual small business, by definition, they're small.
But if you add them all up, they're about half the GDP. they're two-thirds of the country's employment. So, it's a massive space when you really look at it as a whole. And so, if we can make our dent in it, we think that is you know, something worth doing and can really drive successful outcomes for more small businesses. We want to see a world where there's lots of successful small businesses. We're not all just transacting with these large behemoths. we think that's just kind of a more interesting world to be a part of and so we're we're here to support it, level the playing field. and you know and build a business ourselves out of it as well.
[00:05:20] Craig Asano: Music to my ears. I mean you're fighting the David and Goliath battle sometimes, but it's the one that many of us choose to fight. small business are innovators and we sit at the heart of where that innovation is happening from the from the financial services side. So, you know, hats off to you and to making it work, to the successes that you've had. So, let's talk a little bit for those who don't know about Merchant Growth, you know, maybe introduce Merchant Growth a little bit and, you know, that backstory, that founder story. You know, how did you get into it? You know, you were working at private equity. we had that global financial crisis, but at the ripe age of 22, you decided this I'm going to have a go at this. So, illuminate us on that founder journey a little bit.
[00:06:16] David Gens: Yeah, I was always driven to do my own business. I come from a family of entrepreneurs. My dad, brother, and uncle all had their own companies. I was, you know, I was a little bit entrepreneurial in high school. my the thing that I sort of ran in an entrepreneurial way. Wasn't very profitable was my rock band. I had a band. I played the bass and I sang. but we were booking shows, getting shirts printed. We had a van. We were going around and making a go of it. And you know, that was you know, like I said, not a not a profitable venture, but nonetheless, it was you know, getting a team aligned and making something happen. So, I knew it was a matter of time. Eventually, I wanted to sort of start my own thing and you know, work hard and hopefully, you know, see the upside of having equity and something that I build.
You know, I thought that I was going to last longer in that private equity world, but it became kind of clear to me that it wasn't scratching the itch for me. I really wanted to start my own thing sooner than later. And I got advice from my older brother who, like I said, was an entrepreneur. He said, "Kind of the sooner you get going, the better. time is on your side. things take time to build. and there's always an excuse, you know, why you might want to not do it. just ignore that and get going. So, that is what I did. And I looked at this growing market in the US for non-bank small business credit and looked at Canada and recognized the huge difference between the US and Canada. There were already a few large players in non-bank small business finance in the US there. That did not exist yet in Canada. And so I did a little more research.
I talked to some small businesses saw if you know how do you finance your growth where do you get credit and basically it was clear that they had no awareness of the space there were a few player players already in non-bank small business finance at the time in Canada but they were tiny and no one had heard of them yet so I felt like I was on to something and that Canada would play catch-up to the US you also had that backdrop of the great financial crisis and this multi-decade secular trend of less small business credit being provided by the banks that only accelerating post great financial crisis So, you know, I a way I went with a business plan and started funding those first few credits. kind of word of mouth, found some small businesses with credit needs. but it was definitely very small kind of humble beginnings.
My initial goal was just to get the business to the scale where it could pay me a salary so I could, you know, pay my cost of living. and do so being my own boss. Like that was that was goal number one. And then you kind of built it from there. One thing I liked about this business plan was it was an all or nothing. You know, it's not like either, you know, you succeed and it's something huge or it's a zero. It was more like, you know, I just need to do a good job, be responsible, do a good job of underwriting, serve investors well, you know, find more and more clients over time, and, you know, I could kind of incrementally build that business over time. and so that resonated well in terms of my own kind of risk appetite because I really wanted to, you know, find something that would work and hopefully grow over time.
[00:09:24] Craig Asano: It's awesome. I in particular I like the band part. Do you do you do you ever find yourself thinking back to those days and you know what happened to the band? Have you reconnected with the band?
[00:09:38] David Gens: So I still play music. I and I continued playing in bands even when I had the business. you know, in 2013, for example, I was 3 years into this business and I was touring with a couple different bands that year. so I Yeah. Yeah. So, I was I was I took it pretty seriously. you know, this is obviously not the topic of the podcast, but one of them had a had a had a rock radio number one in Canada, and so we opened for Guns N' Roses and Alice in Chains and a whole bunch of rock bands. So, I got to like bucket list. I was able to play on some big stages for a bit which was just so fun. but terrible way to make money. I mean horrible. those especially those bigger shows where we were opening for bigger acts. Those were also the worst paying shows we ever had because you're kind of being paid in exposure in instead of cash. So in any case, it was a lot of fun but also not profitable.
I continue to play music. I still do. Obviously it's just for fun these days. but yeah you know there is a lot of parallels for sure. you know it is a team sport you know playing in a band. and the same way that team sports you know help teach leadership and confidence and also how to kind of collaborate and have you know a team dynamic. bands certainly have all of those same elements. and you know it's yes I've got business partners in what I do today too. So equity partners, people who are like in it and on the roller coaster ride with me day-to-day the same way as back when we had the band. So you know you kind of if you want to do anything big most of the time it does take a team to do it right.
[00:11:17] Craig Asano: Well I mean you've got an appetite for some risk. Not everybody's willing to get in front of the crowd to open up for Alice in Chains and rip on a guitar.
[00:11:25] David Gens: I you know I was I was on I was on the drums for that one. Yeah. Yeah.
[00:11:29] Craig Asano: Yeah. I'm talking paid five till I got kicked out of the but those early well see it's interesting like to have that get up and go th there are some founder insights there I think as you were talking about team and collaboration and leadership but really the problem you know getting back to Merchant Growth that you were tackling is the one minus of more the traditional lending routes the capital raising routes through the banks and the options so building outside of traditional banking, you know, in those early days, like how did you make it work? How did you build the trust? you were saying you found the business model that didn't have, you know, excessive risk was something as long as you worked hard, it was sort of contained. But there must be some challenging stories you remember and some lessons there that maybe you'd like
[00:12:21] David Gens: Yeah, I think one thing that made the business model possible is that people were starting to get comfortable with financial services being done digitally. you know, applying on a website, talking to someone on the phone, not necessarily meeting them in person. the idea of going into the bank branch was starting to, slowly, fade away. obviously we still live in a world with bank branches, but there's a ton of stuff now you do digitally.
So that trend was helpful but you know I was young when I started and didn't have a track record and to your point you know why would people take me seriously and the truth is it was hard a lot of you know it took convincing so you know I think the one advantage was we were taking applications online and doing things over the phone so people maybe didn't necessarily know how young I was but I also had to you know get the trust of investors who actually funded these financings because you know I didn't have the my own money at the time. So we that part was you know as hard if not harder than finding interested borrowers. and so it that was really you know leaning on friends and family. It was small checks. Like I said the initial goal was just to get it to pay my salary. So, I wasn't trying to shoot for some crazy number.
But you know, I was willing to, you know, spend hours with someone who might potentially invest 5 grand into the fund right back then. And, and so I was, you know, just piecing it together bit by bit that way. And, and, you know, I feel a huge debt of gratitude today to those early investors because, you know, they were investing really in me. the idea that I would continue to work hard and figure it out even if I made mistakes. That's what they were investing in because there was no track record or platform or you know repeatable kind of process at the time. So you know today obviously investors are investing in you know portfolio credit portfolio financings that's at scale you know a statistical underwriting model that's been bu developed over a decade. We've got the largest data set on, you know, credit performance for these types of small businesses in the country. And so it's, you know, what you're investing in today is very different than what those early investors were having to trust to move their capital over my way back then.
[00:14:54] Craig Asano: There's a lot of excellent lessons in there having just you know heard he heard that approach but the gratitude really stands out to never forget who helped you in those early days and I can really respect that and the friends and families everybody needs some help and so that's on both sides of that I think but you know that's that's excellent because you know if you have the largest data set of the credit decisioning and maybe you know more for small businesses for the last 16 years in Canada here you would be at the heart of like are Canadian small businesses they're borrowing more are there more of these small businesses are we growing in the right direction these based on that data set I don't know if you've analyzing it in that context recently but I'm just curious to know
[00:15:49] David Gens: Yeah I mean we're obviously we're closest to any data that pertains to our own applicants and customers. Obviously, we do track industrywide stuff as well to understand how the market is developing, what our share of that is at and where it could go as we kind of continue to plan for the business. but you know, it's it hasn't been a fast growing economy. You know, in the last couple years, we've seen slowing growth, but still positive real growth rates. I will say that our average applicant is growing a fair bit quicker than the Canadian economy as a whole. So we're seeing kind of high singledigit even 10% kind of real growth rates at our underlying applicants because it just goes to show that it this business model self-selects for a higher growth borrower. The reason they're coming to Merchant Growth is because their businesses are growing. They're looking for credit to help them continue to grow. Most businesses have positive working capital which means that as they grow they need more capital. and so we are here to provide that.
[00:16:55] Craig Asano: So when it comes to Merchant Growth you know you talked a bit well clearly you know it's a digital model and you've been at it for many years and but what about the products like what exact financing solutions do you is there a huge range? can maybe break that down a little bit for our listeners.
[00:17:15] David Gens: Sure. Our products today are term financing, which is, you know, a lump sum up front and then we're getting, a payment, pardon me, a payment, daily or weekly that in most cases is based on the revenues of the overall business. so there's an ability to kind of reconcile and reset that payment level depending on how the revenues of the business are trending. That's called revenue based financing. So effectively, it's like a royalty. We're buying a portion of your future revenues. we also do term loans. So that's just a straight loan agreement. you know with an interest rate and a typical kind of term loan setup. also in that case it's an advertising product. so we're always getting principal back with each payment. and last but not least is line of credit. So we also do have a revolving product. you know how that's evolved over the years.
We started out just doing the revenue based financing and we were initially doing it based on credit card sales only, credit and debit card sales. That product is called a merchant cash advance. We started in that space then we went to overall revenue based financing and term loans. but really the biggest innovation I would say has is perhaps less visible to the customer but it's in that automated adjudication. It's in the statistical scoring model. It's in the risk based pricing and what that has allowed us to do is accurately price risk across a spectrum. And so we're able to, you know, win that very price sensitive, super high credit quality, larger business and provide product that's appealing to that customer, but also say yes to the risky customer who is, you know, much more likely to be declined no matter where they look.
And we do that by understanding the underlying risk in each applicant. You can only do that if you just do a ton of financings and you're able to study the history of that and then use, you know, machine learning techniques to build sophisticated models to, you know, figure out how to predict those outcomes going forward. And I think that's been key to our success. you know, our competitors were a little bit more like one-size-fits-all. You know, here's roughly the rate. and it just applies to whoever comes in their door. and again, that's just not precise enough. And I think we've been able to really refine that in a in a way that's allowed us to scale you know, more elegantly, I'd say, than other companies in the space.
[00:19:43] Craig Asano: Yeah. You often hear there's a lot of thin files or no files. but let's say it's an immigrant entrep entrepreneur, new immigrant to Canada, but they've got a ton of experience and you know, back where they came from. they get here and they don't they don't really exist on paper or is that would that be a good example? They come to you and what would their the journey like what would the customer journey be like? You've got advanced underwriting that adjudicates the risk and loans, but is it is it just a website? They come in and fill out some information. Walk us through the customer journey a little bit.
[00:20:14] David Gens: Yeah, that customer is potentially going to look slightly riskier to our algorithm. you know kind of all else equal, but not necessarily, right? Because the personal credit file of that individual is just one of many inputs into our own scoring model. we call it the merchant score. that's where we've used you know machine learning to really get a lot of predictive insights from a variety of different data sources. So to talk about the customer journey and what those data sources are one it's the application that customer fills out on Merchant Growth. com or through a partner of ours. that's going to tell us things like years in business industry location etc. the next is the personal credit file. do still look at that and there are predictive elements within that. But the next and most important is the bank transaction data.
And so we get at least 6 months of bank transaction data from the operating account for that small business and we run an algorithm that helps us figure out what the revenue of that business is. Remember not every deposit into an account is a revenue. It could just be you know the business owner putting money in or drawing on a loan or something else. so really detecting what the real revenues are, what the expenses are, whether they're variable or fixed, and then being able to run analysis on that. And then various other things that, you know, you can basically kind of cluster data between the bank data and applicant data and other things to sort of get a picture on a certain dimension, which that might sound really complicated, but that's kind of the way machine learning works is you try putting different data together and see if it's predictive.
And the algorithm learns over time and then you know you al also always do need to be able to explain it. You know why is a high value good or bad or what the case may be before you include in the model. But you know there is a lot going on there and it's too much to even be able to kind of talk about in a in a very short podcast. but also on top of those three, there's a fourth data source which is kind of a catch-all for all the other data we're able to pull which includes the business's online presence. So do they have a website? Do they have online reviews? And how good are those reviews? How recent are they? How many are there? How is that relative to the size of that business? Does that sort of jive all that kind of stuff? So, that's important in certain industries, less important in others, and our, you know, score understands that, all of that.
So, in other words, you know, if you're thin file on your personal credit, but you got a strong business, like, we're going to notice that and you're still going to get approved by us. and I think that's kind of one of the cool things about our business model is we're trying to solve for is this business you know, trending well, is it sustainable? Does it have the cash flow to service credit? And on that basis, we make credit available.
[00:23:14] Craig Asano: And so that would be sort of a snapshot of more like the a good customer, the ideal customer. They've got enough data. They're they're willing to share it. They need access to this capital and they go through the adjudication engine. How long does it take for that growth the merchant score to pop out? Is that something that the customer that goes to the website sets up an account and they don't even call in, they go right to the website. How long if they supplied that information, is it is it something that happens real time? Is it is it instant or is it like
[00:23:49] David Gens: Yeah. So, what I just described is filling out the application, connecting that bank transaction data that can all be done as part of a five-minute application and then our score automatically runs. So, there's no other human involvement required there. So, you know, within literally 1 minute of completing that 5-minute application, we have a yes or no, and here's what the offer could look like. Here are the terms available, etc. And at that point, one of our, representatives reaches out to the business, explains the different options, acts as an adviser, kind of figuring out what would fit their need best. And then once the business owner chooses what type of financing structure they're moving ahead with, then contracts go out for electronic signature and a few other documents may be requested.
If it's a smaller credit request, then frankly, they just need to verify their identity and away we go. If it's a larger credit request, we could ask for things like tax docs and financials, but it depends on the industry and the size of that credit request. but if you're you know if you're a small business owner and you're highly engaged with the process and you're looking to get it done fast then we regularly
[00:25:03] Craig Asano: You know fund businesses that apply in the morning by the time the afternoon funding goes out and what are the size of those numbers on average like the small ones versus the large credit requests? Is it that might take a little bit more due diligence? Where does that
[00:25:18] David Gens: So, you know, our funding amounts you know, range from 10,000 to a million. our we do a lot of small financing. So, you know, our average financing amounts about 50,000. those kind of like more tax docs, financials that those kind of asks tend to kick in around between 150 to 300,000
[00:25:41] Craig Asano: Depending on the industry, right? And so we have a picture of sort of the process and who might be suitable for it. Who's not suitable really for that you might think it's not you know it's not a good fit. We usually talk about I think it's a good question that we usually bring up on this podcast. It's like the ideal customer and it's also hey who's the not the ideal customer so people can you know understand that.
[00:26:12] David Gens: Yeah. One is just if it's day one funding, right? If it's a startup that's not in revenue yet, I wish we could help those businesses. I truly do. But without any history of cash flows, there's just nothing to bank on for us using our approach. and so that is that is one area we can't go into. The other one is just lumpy cash flow profiles. so if you're project based, you only get paid once every few months when you complete a big job. that's that's too lumpy of a cash flow profile. Again, we're banking on the fact that you have some consistency in your revenues and your cash flows to be able to service the credit we provide. so things like resource extraction, that's obviously a too lumpy of a business and not to mention commodity exposed, but often times it's exploration and pre-revenue too.
So you know we tend to fit best for those kind of consumer-facing small businesses you know restaurant retail health and wellness auto repair etc you know trades maintenance trades we do some B2B like wholesale distribution and manufacturing but it's it's a smaller part of the portfolio again just as long as the cash flow profiles are consistent then that means that you know more likely than that you know we are able to approve you if you also kind of meet just the minimum size and time and business requirements.
[00:27:35] Craig Asano: Perfect. That's a good answer. Do let's talk a little bit about since you've done you know over 10,000 financing so it's a big number to me in this manner with this approach and all those learnings and this massive experience what you must have seen a lot of sort of truths or misconceptions that maybe some small businesses have. So, it's a good opportunity to really dispel any myths that some small businesses might have that you've sort of seen as recurring patterns. You're like, you know, here it is again. Is there anything that you see in the data or in your experience that sort of pops up and you say, hey, I wish you know that we could advise them and tell them this is something that, you know, you need to learn, make the process easier for everybody.
[00:28:19] David Gens: Yeah. You know, it's going to sound like I'm I'm I'm kind of selling against myself with this comment, but you know, credit is a tool. It's a powerful tool. It's an important tool. It's allowed you know, frankly, like humans to just progress in a in meaningful ways by taking capital from savers and putting that capital to productive use in other parts of the economy. we've definitely you know advanced as a species as a result of credit to be not you know can't really overstate that but it's a so it's a it's an excellent tool but it can be abused just like any tool and it doesn't it's not the right tool in all circumstances. you know this doesn't apply to you know too many of these small businesses that we work with but some of them will take whatever's available to them and we're thoughtful about our offers. We always want to make sure they're sized appropriately and affordable.
But not everyone in the space is as organized and diligent about that. and so you know there are higher risk financing businesses that finance frankly the businesses that you know we wouldn't finance or perhaps we have financed but we've maxed out on what we would do. And so but you know these higher risk folks are still willing to lend them even more. and so you sometimes see small businesses carry multiple loans at the same time from you know the non-bank small business finance space and you know that's tough on cash flow. It's tough to kind of you know really make that work long term. It's not necessarily sustainable. You end up kind of on a treadmill with too much credit in your business. And so, that is one thing that I kind of, you know, the misconception I guess in that case is just like, oh, I'm I qualify for this credit. I should grab it.
I can use it and I can it's going to help me. It's only going to help you if you know the return profile on the investment on that you're able to make in your business as a result of getting that credit. If the return on that is greater than the cost on your credit, and even if it is greater than the cost on your credit, you got to look at the time horizon on that. If it's not going to produce cash quickly enough, you know, you're you're it's not really going to be positive for you cash flow-wise in the short run and it could potentially get you in a tough spot operationally if you're just really starved on liquidity. So that's one thing is just to be careful about having multiple financings at once and just making sure you have the right amount of credit that you feel comfortable with that allows you to take the risk that makes sense but not excessive risk.
[00:31:04] Craig Asano: There's a lot there's a lot there that's I mean I think a lot of small businesses get into that scenario. They've got their line of credit that's more personal I guess or maybe the business line of credit and then they get into those credit cards. How many times have we heard the stories and you know the single founder is using their credit card to launch a business and maybe they're telling it in retrospect or in hindsight after they've had a great success but risky days for sure. So I think that certainly good advice. You know moving sort of zooming out a little bit about the landscape the lending small business lending landscape have what have you seen that's been sort of developments that in the 15 17 years you've been at it? Because you know through my research for the podcast like one little breadcrumb trail is that competition bureau study. They're looking at is there enough competition in speed financing and so you know what trends or what are your thoughts on the amount of competition and is it efficient market where there's the right size types of businesses coming to apply and getting funded. And to your point earlier, it's the fact that credit exists has allowed humanity well the humanity of small businesses to do things they couldn't do without it. So it's an incredibly useful tool. But from that competition angle as well as some trends what you know what's happening in the SME lending landscape.
[00:32:36] David Gens: Yeah. I mean I think that study is looking at all of the financing options for a small business. So it's looking at it in the context of you know the banks, the equipment leasing businesses and you know government programs everything and everything anything and everything I think in terms of getting more credit flowing and encouraging more competition. I'm sure you've talked on your podcasts about open banking over time. so I won't, you know, beat a dead horse, I guess, but, you know, that would make it a lot easier for businesses like Merchant Growth to serve, those small businesses in a consistent cost-effective way and over time as opposed to you know, the connections we've we've had to rely on in the past that were less reliable than they would be under a proper open banking framework. So, that is you know it's been announced that's that's coming. so we're excited about that. You know I think that again the space has come a long way in terms of the number of players and how much of the market we've been able to assist. but there's still a lot of work left to do.
[00:33:56] Craig Asano: Absolutely. ju just curious so you're based in Vancouver. Do you're national. you can service any small business nationally.
[00:34:07] David Gens: Yeah, absolutely. Yeah. Yeah, we that's always really been the case. I mean, there was a time when we didn't have French contracts, so we couldn't do Quebec, but that was a long time ago. So, yeah, for all intents and purposes, we're were all over the country.
[00:34:20] Craig Asano: And do you find that I guess it's just a function where most of the small businesses I know in Toronto, GTA or Ontario there's there's a lot of activity. Montreal is pretty hot. Van Vancouver has always been a hot bed of startups, but they might not fit that exact profile based on you know what you're talking about. But where's the distribution? Is it is it heavy Ontario? Where is it?
[00:34:42] David Gens: We are overweight slightly relative to the population in Western Canada given our kind of roots and time zone and stuff. But a and you know we're probably a little underweight Quebec just cuz we have not as many French speakers on staff. but we do have them across all the different functions in the business. but apart from that, it really is kind of wherever the Canadian population is. Ontario is our biggest market. and you know, we look forward to actually doing more in Quebec in the near future as we plan to staff that up a little more. but yeah, that's kind of the makeup today.
[00:35:26] Craig Asano: Do you find, you know, after being in the business so long and building I'm not sure how large your team is, but as you scale, or do you do you still get excited about funding a particular business, you know, story, the customers come back and say, you know, David, I got to come back and thank you. This has been the best thing that's ever happened to our business. And does is that kind of partly what's motivating you? Is it is it the efficiency?
[00:35:51] David Gens: Yeah, I love it. I mean that feedback loop for me these days is looking at our online reviews. so I see it there. You know I myself am rarely on the phone with customers anymore. but sometimes I am. You know we had this big sales push during the repayment of the government program known as CEBA Canada Emergency Business Account which was a COVID relief program part of which was repayable all at the same time and in January 2024. And that was a huge push. We were just financing companies to take advantage of the government discounts that were offered. You pay out a lump summon in that January 2024 time frame. So we had all of us including me like with headsets talking to customers at that time getting that done which was actually a lot of fun. but yeah these days it's mostly looking at those reviews online. And we also have been using AI to study the conversations that we're having. You know, it's pretty interesting, right? You could have AI look at the transcript from, you know, 10,000 calls and help you understand your customers and their personas and that'll in turn help us serve them better. you know, and their so that's that's been fun and exciting. But yeah, no, absolutely. Like I love what we do because we're helping these small businesses. we're leveling that playing field like I talked about earlier between them and larger businesses. So big part of why we get up in the morning for sure.
[00:37:24] Craig Asano: So you know you touched upon the AI underwriting. You talked about you know other maybe creative uses for AI just being able to help maybe some of the customer journey or be interesting to match it against your Merchant Growth score to see if that could be even improved using AI or maybe that's giving too much secret sauce away to AI as it you know eats everyone's lunch. But you know I want to focus on that AI piece and sort of the modern underwriting. You've obviously seen tremendous changes from starting 17 years ago was manual. I caught earlier you were saying some of it you were still on the phone but they were on the website. The customer we really know is you doing the phone call thing on the back. but in you know maybe just add a little color to the use of AI and I'm I'm curious about the human oversight aspect. You know, where is the line drawn because everybody's getting jazzed up about AI agents and this is the whole autonomous and humans won't be involved and then there's a whole another camp and so where do you sit on that human oversight versus you know you know the AI engine that you've built and you must have some vision or interest in maybe taking it further integrating it further so what are your thoughts on sort of the modern how AI's modernized it and you know, people's involvement in the future here.
[00:38:53] David Gens: Yeah. I mean, I don't think it's completely black or white. there's no doubt in my mind that as a financial services business, we are more impacted and more frankly, we just have a lot more leverage to what AI can do. because it is an information business. It's information in, credit decision, pricing decision out. you know providing that customer service you know and providing a return to the investors and the credits on the back end. AI can help with a lot of all of what I just described. having said that I don't think it's going fully automated absolutely no humans you know not for a long time. So on the on the underwriting side that's where you see you know a lot of potential for sure. I think our merchant score you know it's it's a it's a kind of AI 1.0 which was machine learning.
Now with the language models to your point we could actually have the language models spit something back that we could then incorporate into our score. I think that's that's the way we would think about using LLMs in that context. LLMs are helping our underwriters get a complete summary on a deal in a way that just saves them a number of clicks and actions and kind of like research work they used to have to do manually. So that's awesome. so I think in terms of just kind of how much volume can be done per underwriter, that number is climbing and climbing and we'll continue to climb with AI. but I still, you know, it's still a ways away to the point that you don't use them at all. Now, we already have no underwriter on some files, right?
So, if it's a really small file and it's looks very normal, like there's nothing unusual about that file, then we have a separate model that kind of ask answers the question, is this the type of file that could be an automated funding? if it passes you know that model then we actually will put it through as an automated fund. Again, very cookie cutter simple scenario for a small amount of credit. if it's a larger amount of credit or if there's anything unusual then it kicks out to a manual review. So it's it's kind of like you know AI is like your autopilot. You know basically commercial airline pilots haven't really flown planes in many years. they just, you know, pull on the yolk or the stick just to take off and then they just pull on it one more time when they're landing and the rest is all automated.
But they're there just in case, you know, and they're there for that like those couple of really important moments. And I think that's that's how we think about AI and underwriting is, you know, you're going to you're going to have those edge cases and unusual scenarios, this or that, or just changing environments. So, you're always going to want someone kind of overseeing the whole thing, too. now on the sales front I think there's less leverage from AI. as exciting as voice AI is and the fact that you know sales is just it's just a conversation so it's just language and so you think just AI is going to take that over but I don't see that happening very quickly because you know there's a trust building that needs to occur and you want to get that commitment from the business owner and that commitment is really only felt in a human conversation as opposed to a machine conversation.
So I again though you can do more volume per salesperson and you know some of that kind of you know more prospecting type work lead nurturing type work you could have AI do some of that but I don't see this the you know death of the salesperson anytime soon as a result of AI
[00:42:35] Craig Asano: The death of a salesperson. Well, what about the like fraud? Is AI on the fraud desk, the fraud file? Can you see because you often hear that the can help maybe security as well, cyber security?
[00:42:51] David Gens: Yeah. Yeah. No, I think it can absolutely be helpful there. And that we're we're already, you know, I mentioned the AI summary for the underwriters. There's there's things that the AI, you know, being prompted to check for that can help there. and yeah, I mean, look, it's it's it's it's going to be in everything. It's already in a lot of things. so it's it's a fascinating dynamic time, especially if you run an information business.
[00:43:20] Craig Asano: Oh, that's true. As you were talking, it just a thought popped in my head. I say, hey, maybe I should run a fintech conference just for AIs. I wonder that would probably be not that interesting.
[00:43:34] David Gens: Just watch the AIs attend the conference.
[00:43:37] Craig Asano: AIs attend the conference and take it over. I don't I would have a role. so we're we're moving down our list of you know topics that I want to talk about and we're getting to the next one. You know, one thing is about Merchant Growth business and scaling it and you know, I in the research like a billion dollar is a pretty big number and 15,000 businesses. but are you like how much volume do you do a year annually? Is that something you'd be willing to share or is that
[00:44:06] David Gens: Yeah, you know, I'm I'm fine to share that. Yeah, I've posted it on LinkedIn before. and you know, we're we're I mean it's it's it's moving around. and we're, you know, growing, but we're only halfway through this year, so I can't tell you exactly what, you know, we're going to end the year at, but you know, we're we're in the sort of, you know, we're doing over 400 million a year.
[00:44:34] Craig Asano: 400 million a year right now. You're scaling. Beautiful. So that's exciting.
[00:44:39] David Gens: Yeah. Our since inception number is almost 1.5 now.
[00:44:44] Craig Asano: Yeah. Yeah. Wow. Fantastic. So can't even keep up with it. So the so during my research I came across the Merchant Opportunities Fund is something that you're you're leading. Could you talk a little bit about what that is and how it works and
[00:44:52] David Gens: Yeah, definitely. Craig Yeah, that's that's how we fund the portfolio. So Merchant Opportunities Fund and Merchant Growth are you know they work very closely together the two companies, right? Merchant Growth is the originator and servicer of these Canadian small business financings. but the actual risk sits with the fund. So the fund is the balance sheet. you know the contract that the borrower signs is you know with the fund because the fund is the actual holder of that credit. and you know we set it up that way for two reasons. One it's what I knew because I came out of that private equity world where I learned about funds fund structures.
But two is because I knew that if I was going to have to raise all this capital to do these financings, if I was just going to use a corporate balance sheet to do it all, I'd end up diluting my ownership in the business you know, considerably in order to accomplish that. and you know the valuable piece is the brand the ongoing origination the underwriting model the data the referral network etc so that's the that's where the value is the person funding the loan just wants a yield so it's a very different type of investor for a different purpose and so makes just separating those two made a lot of sense to me and so we've always funded the financings out of this credit fund and then the actual operating business as a separate entity. and so investors across Canada and frankly globally can actually invest in Merchant Opportunities Fund. We have over thousand investors.
Folks are getting you know last 3 to 5 years we've been consistently doing sort of 12 to 14% net returns to investors. So I think that's pretty good. We're pretty proud of that and investors seem pretty happy with that. and you know we're also distributed through some of the broker dealers and so wealth managers are also buying for their clients too at some in some cases.
[00:47:10] Craig Asano: Are you looking for more BDS like broker dealers and just you know there's bound to be some listening to the podcast. So I would throw it out there that if you are that they should come talk to you of course for
[00:47:20] David Gens: Yeah. Sure. Sure. I mean, yeah, we're we're we're approved at three good broker, you know, independent broker dealers. we are looking for more. We do it's one of those chicken or the egg things. You need to get some advisers that want the product and then they champion you internally with their product approval folks. and so you know that's a process and it took us a long time to get a few of the approvals that we do have. So right now we're more focused on just you know building relationships with the advisers at the shops where we already have approvals but obviously we're we're all ears to anyone who thinks this is an interesting asset class.
[00:48:02] Craig Asano: One interesting question here I've got on my hit list is the Canada's SME pipeline. You know, there's this idea right now that there's not a lot of I mean, small business is everybody knows is the backbone of many countries, including Canada. I mean, they're they're they're where all the jobs are, where all the GDP is. but there's a lot of talk about things have slowed down. Maybe they're talking about startups. Maybe they're not necessarily all SMEs consumer-facing that you might be integrating with for loans, but do you but it was an interesting question that I wanted to get your opinion on. You know, where do you see Canada's sort of entrepreneurial pipeline these days and because it feeds directly into your SME, you know, lending business. is that a concern?
[00:48:50] David Gens: Like are we drying up here or is there what's the future look like? from what I've gathered, you know, it could be better. I mean, obviously we have less immigration now than we did a number of years ago, as well. and, the economy generally just has been as a whole pretty sideways. you know, it hasn't been we haven't really been in a recession per se, although we did have hit a technical one this year for a couple quarters, but it really is just kind of like kind of sideways and sort of status quo. And I'd love to see it be better than it is. I one bullcase I have around AI is that it's going to be that much easier to be a business owner, right? in the past the intimidation factor of like incorporating and signing a lease and you know navigating insurance and certain regulations etc for whatever it is that you're doing like all of those types of activities are so much easier now with AI. I mean and so yeah the cost to get started is much lower and the intimidation factor is lower. So hopefully more people end up kind of embracing the potential that brings to be business owners.
[00:50:08] Craig Asano: Yeah, you still need the proper business plan, the underlying business case, but I guess the administrative the automation of that those workflows can be streamlined which through AI.
[00:50:20] David Gens: Yeah. I just think how many times has someone like just kind of randomly said, "Oh, this would be a business idea." Yeah. you know, but like it's almost never acted upon because like it's just so much work, you know, and it's like I'm and people don't have the confidence. It's like I have no I don't I don't know how to do that, you know, and maybe AI can just make a few more of those random idea conversations into real things.
[00:50:42] Craig Asano: The back of the napkin igniter. I like that. Yeah, it's an interesting perspective. So, we're going to talk a little bit about the future of alternative finance. though look you know looking ahead what excites you about alternative lending you know for small business financing in Canada the these are trends in industry that you've seen or you'd like to see development happen may maybe they're happening globally but why not here in Canada we
[00:51:13] David Gens: Often say what are your thoughts there yeah Merchant Growth has a mission to bring Canadian business owners the convenient, accessible, and trusted financing experience. convenience speaks to how easy it is, the speed, the algorithms, the AI, being able to kind of give business owners their time back because, you know, business owners wearing multiple hats. They're doing marketing, they're doing operations, they're doing finance. they want to get back to just, you know, working with their customers and doing what they're passionate about. So, we give them their time back. So, I see us continuing to execute on that. Accessibility speaks to that broad spectrum of risk appetite and being able to say yes more often than not. And then trust is kind of you know just continuing to build out brand and awareness of our entire space.
You know we did a survey of a thousand businesses and not of our customers but just random small businesses and to get a sense of how aware they are of not just Merchant Growth but non-bank small business finance and less than 10% of business owners were aware of it at all. So still a lot of work to be done there as you can imagine they all know the big bank brands and so forth. But our space still has work to do on that front. I think as we continue to gain scale, we're able to, you know, feasibly lower the rate to customers, because of just operational, economies of scale, but also our own cost of capital going down as we gain scale. And so that will allow us to, you know, move the business what I call up market, so into slightly larger businesses, slightly larger loan or credit amounts and at more competitive rates.
And that will really also allow our space to kind of move out of the kind of alternative kind of shadows. I don't know that's probably the wrong term. that sounds weird. But you know even the word alternative it says itself kind of makes us sound like you know these sort of the this higher cost higher risk credit offering and I don't think we have to be like I think that we can move more into the mainstream with scale. and so that's that's something that you know we're we're working on and you know it's not easy to do and you need to get scale and you need to do it incrementally and thoughtfully. you know there's there's been other small business finance platforms that have really tried to lead with a lowcost product to try and get the kind of lower mid-market business. but when you don't have that scale, it's really hard to actually execute on that plan and do it sustainably.
So yeah, I mean I see that you know, it's just it's just going to get easier and easier for businesses to get credit. and that's what we're here to do. And I think that's a very exciting future.
[00:54:03] Craig Asano: So if you if merchanting proat, you know, cumulatively that $1 billion figure is more like 1.5 billion. Where does that scale look like for you? and I mean it seems to be ramping up and you know to your point like there's going to be more access to credit and more awareness. We're only at 10% of education. and sometimes we're getting a bad rap calling it alternative lending or alternatives as you're saying you know we're the band members. Yeah. We're the alternative indie rock guitarists and singers, but really we're just trying to help and it's it's non-traditional, non-bank loan lending. But I is do you ever envision a point in the future where alternative lending or alternative finance is going to get so big that it will invert with traditional bank finding bank lending or that's you know it's not it's I mean it's look it's not impossible and
[00:54:59] David Gens: I mean at the end of the day the banks still play a meaningful role. I mean like at Merchant Opportunities Fund we get back leverage from BMO and a few other Canadian banks. So, you know, part of the capital that goes out with every single Merchant Growth financing is coming from banks. so, you know, they still play a play a role there. I do think like, you know, we can we can build better, you know, customer experiences. you I do think that playing field is leveling out. you know, traditionally the smaller kind of more startupy business who's building from scratch, not burdened by legacy systems is like in a better position to build, you know, elegant user experiences and stuff. I think that is actually leveling out where that advantage that the smaller startup has is going to become less just cuz everyone can like code things with AI and stuff.
But like in any event though, you know, there's even if banks start building better experiences and faster experiences for small business credit, I'm not I'm also just not overly worried about that from my standpoint just cuz there's such a big spectrum of risk and the banks are always only going to address a sliver of that spectrum kind of by design also due to regulations. So, yeah, I think that you know, the numbers can certainly continue growing here. but, you know, it's it's not easy and it's always changing. We've we've been traditionally kind of like a high growth business over our 17 year history, but you know, we went through a huge disruption during CO where our new volumes went, you know, basically almost down to zero for a little bit and slowly built back up.
So, there's, you never know, there's always things that can change and the economic cycle also, you know, does what it's going to do. So, it's a fun business in that, you know, you're you're having to think about a lot of different things at once, as you're, you know, trying to execute on growth in, you know, a space like our own.
[00:57:13] Craig Asano: Well, you're sitting in a pretty good spot. I' I'd say David, I'm quite impressed with the success you've had and you know quite frankly your perspective, your attitude on and you're still you know very vibrantly trying to help these small businesses and build and scale that business to what you know your success will look like. So you know as we move towards the end of the podcast I want to touch a little bit about the innovation and success for Merchant Growth. So, do you do you have any products or ideas that are coming in the pipeline that you're just super excited that you know you can you can mention it? I you know, don't give away the secret sauce, but you like what's what's what's coming out that you feel you can feel it vibing here over the next 3 to 5 years that's probably going to be an integral part of that scale, that growth.
[00:58:01] David Gens: We're like as busy as ever in our tech team despite AI being able to help you, you know, code. We're we've actually added developers even in that scenario. and we're shipping more and more stuff which is awesome. I would say not there's no single thing that I could say to you right now that you'd be like, "Wow, that's totally insane." It's more like it's it's a lot of little things getting a lot of little things right to make that you know to execute on that mission of bringing the most convenient accessible and trusted financing experience to those businesses. So you know the ability to refinance and access more credit as you've paid down your initial financing with us. you know that historically required a few manual steps. we're we're making that entirely self now.
We are you know re we're actually frankly we're rebuilding our loan management system which is huge project that's entirely back end right you know customers not even going to notice that but it's going to allow us to you know use AI in a more powerful way and scale our business and innovate on products faster than we historically be able to once we have that new infrastructure you know Yeah, we're we're we're launching a mobile app very soon. that's going to bring a lot of those self-s serve features, you know, right into your mobile phone and allow us to communicate with you through push notifications and all that good stuff. So, yeah, there's tons of stuff we're working on. No single thing is like totally earthshattering at the end of the day. You know, our product is to get credit flowing into Canadian small businesses. I will mention one other thing which is Merchants Market.
We have a marketplace of vendors and partners or that can be accessed on preferential terms if you're a Merchant Growth customer. anything from kind of payments, payroll, legal, insurance, etc., etc. you can you can see the different options that are out there and the pros and cons and like really kind of elegant product sheets and sign up right then and there with you know preferential pricing. So that's kind of we're trying to empower small businesses. You know, financing your growth is just the start and we're trying to give you the tools that you need to succeed in whatever vertical you operate in.
[01:00:38] Craig Asano: And do you which is an excellent idea. You've touched upon a few great ideas. I'm I'm wondering about going global. Do you ever think this is something that Merchant Growth like merchant global growth?
[01:00:54] David Gens: It's a debate we've had, you know, been we've been around long enough to have that debate a few times, right? Having been in business 17 years, we've we've always come back to just let's just stay focused on Canada. There's still so much work to do here. And we just don't want to drift our focus into, you know, multiple jurisdictions. You know, financial services don't export across borders super easily. You know, you got we're now going to have to train a model on new data. we're going to have to, you know, set up new infrastructure in many respects as it relates to, you know, banking, legal, etc., and regulations that you got to comply with, etc. So, it's a lot of work. but, I think that it's it's certainly not off the table. You know, it's something we could get to, over time. We do have some thoughts as to how we might do that if we were to do that. But, I would say that in the near term, we remain just really focused on Canada.
[01:01:42] Craig Asano: And last question before we get into the rapid fires here. five years from now, what do you think success for Merchant Growth and for Canada's small business community? What do you think it's going to look like for you from where you sit?
[01:02:01] David Gens: I think rather than yeah like more than any single KPI it would be you know I'd say we would have succeeded if we're more of a household name where it's like hey Merchant Growth is that platform that you know supports you and in financing and other ways if you're a small business owner just becoming a household name if we do that in the next 5 years I'd say that's success and across the whole space you know if you just have you know we survey the business all the time and it's like what are your main pain points etc like maybe access to capital could drift down on that list a little bit if we can solve that a little more you know I don't think it'll ever be completely solved and you know and of course you know this might sound harsh but not every business should be funded right you know it there is that adjudication overlay that you always need to have and that's the mechanism where you know capital actually flows to the right ideas that should be funded. But so you know that's that's all to say that there's always going to be some businesses complaining that they wish they had more access to capital. but nonetheless right now that complaint is you know way too frequent too often with pretty much every small business. Let's you know make that less of a less of a concern.
[01:03:22] Craig Asano: Yeah. here, here, here. And it's really sometimes a dagger to heart when that same question, that same company or a number of companies feel the pain so badly that they have to leave Canada and that really hurts and
[01:03:36] David Gens: None of us want that. So, I hear you and you know, good luck with Well, we see it and we've seen it. we don't like it and you know if we can have a hand in helping it I think we owe it to ourselves and
[01:03:54] Craig Asano: You know all the small businesses to do what we can for them but okay well let's get into these rapid fire questions. they're just going to be quick I'm expecting sort of quick answers here. so if you're ready I'm just gonna this is just something we do in the podcast just add a little fl little flavor little color.
[01:04:14] David Gens: So, are you ready for these quick questions? Okay.
[01:04:17] Craig Asano: So, first one, biggest myth about small business financing.
[01:04:25] David Gens: It'll take a long time to apply and figure out what you're able to get.
[01:04:32] Craig Asano: It's as quick as one minute from what I've heard.
[01:04:35] David Gens: Just a few minutes. Yeah, it's just a few minutes if you connect your bank account and you got it.
[01:04:41] Craig Asano: Next question. Rapid fire. one financing mistake founders make too often.
[01:04:52] David Gens: I'm I'm now going to talk not just about kind of like main street small businesses but also you know the more kind of venture startup ecosystem which is just picking the right capital solution depending on what it is you're investing in. you know, if it's going to produce cash flow predictably and quickly, go with credit. If it's risky, go with equity. Sometimes people just mix that up and then you get caught up in weird situations and sub-optimal.
[01:05:24] Craig Asano: Good answer. one technology that you're you're watching pretty closely.
[01:05:33] David Gens: I mean, how can I not say AI, man?
[01:05:37] Craig Asano: I you're not watching going to the moon with SpaceX or something.
[01:05:43] David Gens: I you know I'm just so focused on my business that I look forward to the live stream when someone's landing on Mars, but I'm not spending my days, you know, tracking that progress.
[01:05:56] Craig Asano: Yeah. Well, I am waiting for the nanobot to get into my clean my cholesterol out of my veins. I'm waiting for that one. Just clean me. Like, I don't need a pill. Apparently, these nanobots, they've been talking about it for years. Just go in and clean me out.
[01:06:13] Craig Asano: Next question. One lesson that you would give your 22-year-old self.
[01:06:21] David Gens: I get a shareholder agreement. My I didn't have one at first and I paid for it.
[01:06:32] Craig Asano: There you go. It's like getting a will. You need a shareholders agreement.
[01:06:35] David Gens: Yeah. Even if you it seems like you're getting ahead of yourself and it's like this isn't even a business yet. Like you know it's like you know what it's not that much money. Get that share agreement in case it becomes something.
[01:06:47] Craig Asano: Well it can always come something. So I think it's it's probably the biggest most salient piece of advice that an entrepre that might not know that absolutely get a get a shareholder screen. I mean yeah.
[01:07:01] Craig Asano: Last question. What still excites you the most after 17 years of being a digital lender?
[01:07:09] David Gens: Seeing people on my leadership team grow into bigger and bigger roles, looking after more and more things and they themselves leading larger and larger teams. It's been awesome to see people grow in the company.
[01:07:22] Craig Asano: Excellent. That's I can envision you know leadership team M&A buyout coming in 10 15 years when but you only started 22. You got a lot of years left. You got to keep some years on the back end of the runway. Get back into the band. Get back into the when you're when you're touring again. I'll I'll you we'll come out and you know, we'll we'll we'll see.
[01:07:46] David Gens: I'll let you know next time I'm playing. You're in Toronto, right, Craig?
[01:07:51] Craig Asano: Actually, I moved to Waterloo a number of years ago.
[01:07:59] David Gens: I don't have any gigs coming up there, but I'll let you know.
[01:08:07] Craig Asano: That's awesome. Maybe the Horseshoe Tavern, or an even bigger venue.
[01:08:16] Craig Asano: Okay. Well, this is you know wrapping up I guess for the for the benefit of listeners and I had a lot of fun on this chat with like the vibes. Want you to get your information out though like how do how do people contact you if they want to learn more information maybe you know the website, the email, all that good stuff. How do they
[01:08:37] David Gens: Yeah. If you're looking if you're a small business owner looking for credit, looking for capital to grow your business, then find us at merchantgrowth.com. And if you're an investor looking for income producing investments and you want to support small businesses in the process, then Merchant Opportunities Fund is something that you should look at. That's merchantopportunitiesfund.com.
[01:08:58] Craig Asano: Thanks so much David for joining us sitting down here valuable time. I've learned a lot as usual and as I mentioned it was a great conversation. So, kudos to you and wishing you and, you know, all the leadership team and Merchant Growth the success that you're you're looking for and all the all the help that you're providing to small businesses. So, it's absolutely fantastic.
[01:09:24] David Gens: Yeah, I had a lot of fun, Craig. Thanks a lot for the time and for having me on. Appreciate it.
[01:09:27] Craig Asano: Absolutely. So, if you're just, you know, to close things out here, if you're new to Fintech Fridays, please check out some of the incredible past episodes on the site. I think you'll be surprised with what you find. We look forward to seeing you next Friday for another episode of Fintech Fridays. Have a good weekend, everyone.
Outro : You've been listening to Fintech Fridays brought to you by NCFA and partners. Tune in weekly for the latest fintech Friday podcast by subscribing to this channel. The National crowdfunding and Fintech Association of Canada is a non-profit actively engaged with social and investment fintech sectors around the globe and provide education research industry stewardship services and networking opportunities to thousands of members and subscribers. For more information please visit ncfacanada.org.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 22, 2026 | NCFA Companies On The Move | Wealth Investing And Trading, Artificial Intelligence And Data, Risk Compliance And Regtech
d1g1t is a Toronto wealthtech company whose enterprise platform brings portfolio management, performance and risk analytics, trading, reporting, billing, compliance and client engagement into one system. The company says more than 90 wealth firms across North America use the platform, representing over C$200 billion in assets across 600,000 accounts, 250,000 clients, 2,000 advisors and 20,000 users. Those assets belong to client firms and their investors; d1g1t supplies the technology rather than managing the money.
Its July 2026 launch of a server built on Model Context Protocol (MCP) connects that governed portfolio data to Claude, ChatGPT, Microsoft Copilot and other compatible AI tools. Advisors can ask questions about households, holdings, performance, exposures and mandate breaches without working through every screen by hand. The launch matters because d1g1t isn’t adding AI to an empty interface. It’s making an established wealth operating system callable by the assistants firms are beginning to use.
Wealth firms rarely replace a core platform for one clever feature. They do it because too many systems, spreadsheets and handoffs have made the business difficult to run. d1g1t sells against that fragmentation. Its platform gives advisors, operations teams, portfolio managers and compliance staff a common set of household, account, portfolio and risk data, then uses the same engine across reporting, trading, billing and client work.
Recent customer decisions show the size of the jobs it is winning. PWL Capital selected d1g1t in March 2026 for integrated portfolio management, trading, reporting, compliance, billing and client engagement, including bilingual delivery. In June, Goodreid Investment Counsel deployed the platform after using its previous system for a decade. Goodreid manages approximately C$900 million. Neither example proves a typical implementation result, but both show d1g1t being trusted with core operating work rather than a peripheral dashboard.
There is another useful clue in the cap table. CI Financial, National Bank’s NAventures, Purpose Financial and FigTree Financial have invested in d1g1t, partnered with it or used its technology. In 2025, RBC selected d1g1t’s analytics engine and made a strategic investment. For a wealth software company, customers that also supply capital can do more than validate the product. They can sharpen product priorities, open distribution and make the platform harder to dislodge once it sits inside important workflows.
The performance and risk engine is the foundation. d1g1t’s founders built their careers in quantitative finance and enterprise risk systems, including at Algorithmics and R2 Financial Technologies. That history matters because high-net-worth portfolios are rarely a neat list of public securities. Wealth firms may need to connect family entities, several custodians, private funds, partial ownership, off-book assets and different reporting rules before an advisor can answer a seemingly simple question. The engine calculates performance, exposure and risk across that structure, while the application layer turns those calculations into daily work.
The integrated workflow is what firms buy. The platform covers portfolio and model management, trading and rebalancing, performance reporting, billing, compliance, document management, business monitoring and a client portal. d1g1t says it supports traditional and alternative assets and works across multi-family offices, independent advisors, broker-dealers, custodians and bank advisor networks. That breadth creates a larger contract opportunity than a single analytics tool, but it also raises the implementation bar: the company has to handle data conversion, integrations, controls and firm-specific operating rules well enough to become the system people actually use.
MCP changes how users reach the platform. Instead of asking an advisor to click through several modules, the server exposes approved d1g1t capabilities to an AI assistant. A user can request a morning brief, summarize an upcoming meeting, check portfolio drift, examine exposures, prepare a report or flag a mandate breach in natural language. AI agents entering governed financial workflows need permission boundaries, traceable actions and reliable source data. d1g1t already organizes much of that underlying context inside the client’s wealth platform, which is more interesting than attaching a general chatbot to a collection of disconnected files.
d1g1t describes the MCP connection as governed. Public materials explain the intended workflows, although named customer deployments, pricing and detailed implementation specifications haven’t yet been released. Those details will show how quickly the product becomes part of daily advisor work and whether it helps expand existing contracts.
d1g1t is selling into a market where data quality, switching risk and regulatory responsibility matter as much as the interface. Its integrated platform gives the company several ways to win, but the field around it is getting more capable.
MCP is becoming a wealthtech connector, not a moat by itself. Canadian wealth platform OneVest launched its own MCP connection in April 2026, giving AI tools access to live wealth data, portfolios, pipeline information and tasks. OneVest’s continuing wealth-platform expansion makes it a particularly relevant Canadian comparison. d1g1t’s case will rest on the depth of its analytics, complex-portfolio support, integrated workflows and enterprise relationships, not simply on supporting an open protocol.
Large platforms are building native advisor assistants. Addepar’s Addison queries permission-aware portfolio data across a platform used by more than 1,400 firms, while Orion’s Denali AI connects portfolio, risk, CRM and planning information with audit controls. InvestCloud is automating meeting preparation and follow-up. These companies arrive with large installed bases and mature integrations. d1g1t doesn’t need to beat every platform everywhere, but it does need to make AI meaningfully better for the complex firms it already serves.
Good AI depends on clean, usable wealth data. Portfolio answers are only as reliable as the account, ownership, transaction and security data underneath them. PureFacts’ work with wealth platforms on data readiness reflects the same commercial reality: firms want automation, but first they need consistent data and clear operating definitions. d1g1t’s single-platform design can reduce some of that fragmentation. Client-specific data mapping and integration work won’t disappear.
Documents remain part of the advisor record. Holdings and performance data tell only part of a client’s story. Agreements, statements, correspondence and planning records also shape advice and compliance. FutureVault’s agentic document intelligence for advisors shows another route into the same workflow. d1g1t includes document management, but specialized providers can compete or partner around the edges of the platform.
The regulated firm still owns the decision. d1g1t is presented as a software provider, not an investment dealer or portfolio manager. Its clients remain responsible for suitability, supervision, books and records, privacy, cybersecurity and third-party oversight. Canadian cybersecurity guidance for registered firms makes vendor controls and incident readiness part of the buying decision. d1g1t’s SOC 2 Type II work is relevant assurance, though firms will still assess the current AI connection, permissions and data handling for their own use.
Enterprise growth can be lumpy. A core wealth platform can produce durable revenue once installed, but sales and implementation cycles are long. Each customer may require integrations, migration, testing and training before the contract reaches full use. d1g1t’s 96% revenue growth from 2021 through 2024 and recent PWL and Goodreid wins show progress; revenue, recurring-revenue mix, retention and implementation economics remain private.
d1g1t has spent years doing the difficult part: organizing complex wealth data and placing the same analytics inside reporting, trading, billing, compliance and client work. Its current scale, recent customer wins and relationships with major Canadian financial institutions give the MCP launch a credible base. The product isn’t asking wealth firms to trust an AI tool with data that sits somewhere else. It connects the assistant to a platform already used to run the business. On the NCFA Financial Innovation Map, that puts d1g1t at a useful intersection of wealth infrastructure, portfolio data, AI interfaces and compliance technology.
What matters next is adoption. Named firms using the MCP server in live advisor workflows, measurable time savings and evidence of larger or stickier contracts would show that natural-language access is becoming a commercial feature rather than a useful demonstration. That is a fair question for every wealth platform now adding agents, not a problem unique to d1g1t.
The Company Intelligence Snapshot below follows the capital, customer relationships and product decisions that brought d1g1t to this point.
d1g1t was founded in Toronto by financial technology veterans Dr. Dan Rosen, Philippe Rouanet and Benoit Fleury. Incubated at the Fields Institute, the company set out to bring institutional portfolio and risk analytics into a single operating platform for wealth firms. By late 2018 it had four customers representing approximately C$13 billion and 5,000 households.
d1g1tToronto wealth-management technology company
FoundationProduct and first enterprise customers
C$9M+Raised across two early rounds led by Purpose Financial
CanadaIndependent wealth firms and portfolio managers
4 FirmsApproximately C$13B and 5,000 households
One PlatformAnalytics and advisor work replace a fragmented stack
d1g1t began with a difficult but valuable wedge: institutional analytics adapted for wealth firms. The founders’ earlier enterprise systems gave the company credibility with buyers who would be trusting it with core portfolio data.
Information notice: Private-company estimates are identified and attributed. Information may change after the stated update date. This content is provided for informational purposes only and does not constitute investment, financial or legal advice.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 21, 2026 | NCFA Companies On The Move | Cybersecurity And Fraud, Identity Privacy And Data Governance, Artificial Intelligence And Data
Tailscale is a Toronto founded secure networking company built around WireGuard, identity controls and direct connections between devices. By July 2026, it was nearing 40,000 paid business clients and approximately 300 employees, according to BetaKit. Tailscale’s website separately reports 2.5 million active devices and 100,000 monthly active users.
The core business makes private networks easier to deploy and govern, while Aperture and Border0 take Tailscale into AI access and privileged infrastructure—two markets with bigger security budgets and much heavier competition. This profile looks at what customers are buying today, where the next leg of growth could come from and what the public evidence still can’t tell us.
The best public clues come from customers describing work they no longer have to do. Instacart reduced internal VPN support requests from about 10 each week to nearly zero, cut new user onboarding to less than one minute and reported no outages after deployment. Cribl grew from 18 to approximately 550 employees without hiring a dedicated networking team to administer access, while Corelight reports saving more than 1,000 hours annually and Positron estimates it saves an hour each time a prospect is onboarded.
These are selected Tailscale case studies, not audited results or a measure of what the average customer should expect. Still, they help explain how the product spreads: it removes the VPN tickets, slow onboarding and constant access administration that technical teams already dislike. A developer can start with one live problem, and if the network holds up, IT and security have a practical reason to standardize it, add controls and bring more of the company onto the same service.
Core Tailscale appears to be the product that pays today. It creates an encrypted private network among approved users, devices, servers and services, with identity based policy deciding what can connect. Developers can get started without rebuilding the company network; as use grows, IT and security can add centralized administration, device posture, logs and tighter access controls. Tailscale’s client, command line tool and relay server code are open source, but the hosted coordination server is proprietary. That coordination service distributes public keys and access rules, while customer traffic normally moves directly between endpoints or through encrypted relays. Tailscale Raises $230M To Power Identity-First Networking looked at why this model could pressure conventional VPN and firewall products.
The pricing supports the same bottom up motion. Tailscale currently lists a free Personal plan, Standard at US$8 per user per month, Premium at US$18 and custom Enterprise terms, with paid plans adding provisioning, device posture, administrative roles, network flow logs, regional routing and support. The cost of trying the product is low; the account becomes more valuable as more people, devices and company controls move onto it.
Revenue is the important missing number. Tailscale doesn’t publish it, and the outside estimates aren’t close enough to treat as fact. GetLatka puts 2025 revenue at US$45.2 million, although it says the figure is modelled and that management wasn’t interviewed. Northmetric estimates US$60.1 million in current annual recurring revenue with medium confidence, relying partly on an assumed 54,000 paying customers—well above BetaKit’s July 2026 report of nearly 40,000 paid business clients. Taken together, the estimates point to a company with real commercial scale, but they don’t establish Tailscale’s actual revenue.
Aperture is the move into AI access and cost control. Sitting between approved users or agents and AI model providers, it centralizes credentials while applying access rules, usage visibility and spending limits. That puts platform, security and AI infrastructure teams squarely in the buyer group. AI Agents Enter Governed Financial Workflows explains why permissions, approved tools and audit records matter once agents touch regulated work. Existing Tailscale networks could give Aperture a useful distribution advantage, but the product remains in beta and is currently available without extra cost during testing. Six users are included, with additional access handled through the company; usage, paid conversion and final pricing haven’t been published.
Border0 moves Tailscale into privileged infrastructure access. It governs sensitive connections to servers, databases, Kubernetes environments and internal applications, adding approval workflows, session recording and audit visibility. Those capabilities put Tailscale in front of security, compliance and operations buyers—not just the teams managing everyday network access. After acquiring Border0 in March 2026, Tailscale began connecting the product to its identity and networking layer, although the combined offering remains in beta. Adoption, revenue and final packaging haven’t been disclosed, so Border0 is best viewed as a credible expansion route rather than a proven second engine.
Tailscale now overlaps with secure networking, identity security, privileged access and AI gateways. Each move opens another budget, but it also brings the company up against much larger security platforms with broader bundles, established enterprise sales teams and far more acquisition firepower.
Large security platforms are buying identity. Palo Alto Networks completed its acquisition of CyberArk in February 2026, adding privileged access and identity security to a platform that already spans network, cloud and security operations. CrowdStrike agreed to acquire SGNL for continuous identity controls, while Zscaler agreed to acquire Symmetry Systems for data and AI access visibility. Buyers are clearly paying for identity and access control, but they may increasingly prefer to buy it inside a larger security contract.
SASE rivals have more capital and enterprise reach. Netskope’s September 2025 IPO raised approximately US$992 million and valued the company at about US$9.6 billion on a fully diluted basis. Netskope, Zscaler, Cloudflare and Palo Alto Networks can bundle network access with wider security products and sell through established enterprise teams. Tailscale’s counter is that technical users can adopt its product before a large security procurement begins, although that advantage could narrow as buyers consolidate more of their security spending with fewer vendors.
AI gateways are becoming a real product category. Cloudflare AI Gateway added real time spending limits and identity based controls in June 2026, while Kong sells governance for models, MCP servers and AI agents. Neo Raises US$100M To Control Enterprise AI Agents shows how quickly money and products are gathering around agent inventory, permissions and policy. Aperture approaches the same problem from inside a customer’s private network, which gives it an interesting opening; whether that opening lasts will depend on policy depth, auditability and model coverage.
Canadian financial institutions face clearer AI and vendor controls. OSFI’s July 2026 bulletin on generative and agentic AI connects AI use to existing expectations for technology risk, operational resilience and third party oversight. Its technology and cyber risk guideline and third party risk guideline make identity, logs, access policy and vendor diligence commercially relevant. OSFI And GRI Workshops Reveal What Regulated AI Needs found that weak identity, provider concentration and vendor oversight are already limiting adoption. Tailscale’s SOC 2 Type II status helps. CSA Cybersecurity Guidance For Registered Firms shows why firms will still need documented vendor diligence, access controls and current assurance reports.
Open source keeps the paid product honest. Tailscale identifies Headscale as an independent alternative to its proprietary coordination server, which means a capable technical team can self host that layer. The subscription therefore has to keep earning its place through reliability, administration, policy, support and company controls—not connectivity alone.
Easy adoption doesn’t remove enterprise budget friction. A Tailscale commissioned survey of 1,000 technology leaders found that 42% cited workflow or integration disruption when security upgrades were delayed, while one third cited an unclear business case. Customer results give Tailscale’s sales team concrete savings to work with, but a company wide deployment still needs an owner, a budget and proof that another security vendor can be retired or avoided.
Tailscale’s edge starts with how it gets in. A developer or infrastructure team can solve a live networking problem without waiting for a company wide migration; if the product works, IT and security can add policy, device controls, logs and support around a network that people are already using. Reported results from Instacart, Cribl, Corelight and Positron give that approach substance beyond the usual product pitch. It also places Tailscale across several areas in the NCFA Financial Innovation Map, including digital identity, cyber resilience, AI governance and enterprise infrastructure.
The next act is harder because Aperture and Border0 ask those customers to trust Tailscale with AI access and privileged infrastructure, where the budgets are larger and the incumbents are stronger. Nearly 40,000 paid business clients and 2.5 million active devices give Tailscale a meaningful starting point; what isn’t public yet is whether either product is creating meaningful new revenue.
The Company Intelligence Snapshot follows the funding, customer growth and product decisions that brought Tailscale to this point.
Tailscale was founded in 2019 to reduce the complexity of connecting people, devices and services across the internet. Its first generally available product combined WireGuard encryption, identity and direct connections without requiring companies to rebuild their existing networks.
TailscaleA Canadian founded secure networking company
LaunchGeneral availability arrived in April 2020
US$3M SeedLed by Heavybit with Uncork Capital and others
GlobalRemote teams, cloud infrastructure and personal networks
Developers FirstIndividuals and technical teams could start without enterprise deployment
Simpler VPNDirect encrypted connections reduced reliance on central VPN concentrators
Rather than begin with a top down security sale, Tailscale gave developers a faster way to connect private infrastructure and let working networks make the case for wider adoption.
Information notice: Private-company estimates are identified and attributed. Information may change after the stated update date. This content is provided for informational purposes only and does not constitute investment, financial or legal advice.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 20, 2026 | NCFA Market Activity | Cybersecurity And Fraud, Artificial Intelligence And Data, Risk Compliance And Regtech

On July 20, 2026, Neo emerged from stealth with US$100 million in combined seed and Series A financing from Andreessen Horowitz, Bessemer Venture Partners, Craft Ventures and Merlin Ventures.
The Boston cybersecurity company was founded in 2025 by Nick Warner, Shlomi Salem and Eran Shirazi. Note that it's unrelated to Calgary based Neo Financial. Warner previously served as SentinelOne president and COO, Salem led detection engineering and threat research at SentinelOne, and Shirazi previously co-founded EasySend after leading vulnerability research in Israel’s Unit 8200.
Neo is building what it calls an agentic software control layer. The platform gives security teams an inventory of AI agents, AI enabled applications, plugins, extensions, MCP servers and traditional software that has gained agentic capabilities. It then maps permissions, attributes actions and applies policy before software reaches sensitive data or systems.
The company plans to use the financing to expand engineering and go to market operations. Neo hasn't disclosed revenue, customer counts, named customers, valuation or the allocation between its seed and Series A rounds.
Enterprise security was built around human users, known applications and recognizable data flows. AI agents can act differently. They may inherit a user’s permissions, call several tools, reach files and credentials, communicate with other agents and continue operating without a conventional interface.
That means risky activity may not even resemble a conventional intrusion. An agent can use valid credentials and approved applications while still exporting too much data, reading a secret, pushing code or initiating an action that exceeds the authority its operator intended to grant. NCFA’s analysis of AI agents gaining identity and wallet access shows how quickly this issue reaches financial APIs and real infrastructure.
Neo’s platform combines four functions. It finds AI software, checks what it can access, shows who or what is behind each action, and lets security teams allow, block or pause that action for approval.
Threat's aren't limited to deliberately malicious agents. ShadowLeak demonstrated how hidden instructions could manipulate an AI agent and expose private information without a user clicking a malicious link.
Its Neoverse knowledge base maps the capabilities, risks and behaviour of agentic software before it enters an enterprise environment. Neo says enforcement occurs natively at the endpoint, where the software can intercept tool calls, API access, credential reads and data transfers before the action is completed.
Neo combines software inventory, posture intelligence, attribution and endpoint enforcement across agentic and traditional applications.
Check Point is developing a wider AI security control plane covering employee AI use, AI applications and agentic systems.
SailPoint is extending identity governance to AI agents and other non-human identities.
Existing endpoint security providers already control devices, files and processes, but may not yet map the permissions and chained actions occurring inside agentic software.
Cloud and application security companies can govern models, APIs and data access, creating a competitive question around whether customers will buy a separate agentic control layer or expect existing security platforms to absorb the function.
Banks and other regulated organizations will need more than a list of approved AI tools. They need to know which person authorized an agent, what credentials it inherited, which systems it can call, what information it can export and when human approval is mandatory.
Neo’s opportunity is to show who or what can access each system and enforce clear limits on what they can do. Its challenge is that endpoint, identity, cloud and network security companies are all pursuing parts of the same problem. Large institutions may prefer one more specialized control layer, or they may demand that existing suppliers add agent governance to products already deployed across the organization.
Financial institutions are adopting AI while remaining accountable for privacy, cybersecurity, third party risk, operational resilience and auditability. An agent that can access customer information, initiate a payment, change code or communicate externally will need authority limits that security, risk and compliance teams can understand.
Neo has the capital and founding team to compete early, but the category is still forming. Enterprise adoption, integration depth and the quality of its policy enforcement will matter more than the size of the launch financing.
Will enterprises buy a dedicated control layer for agentic software, or will endpoint, identity and cloud security providers absorb the function before the category becomes independent?
Nick Warner, Shlomi Salem and Eran Shirazi founded Neo in 2025 to build security controls for enterprise software gaining autonomous and agentic capabilities.
Neo SecurityEnterprise cybersecurity company focused on agentic software
FormationExperienced operators assemble before the public launch
Early Institutional BackingSeed and Series A allocation not publicly disclosed
Enterprise SecurityAI driven software environments
SecOps TeamsLarge organizations adopting AI enabled software
Operator ExperienceFounders previously built and scaled enterprise security companies
Neo begins with founders who have built cybersecurity products and commercial organizations before. That lowers some execution risk, but it does not yet establish enterprise adoption.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 17, 2026 | NCFA Market Activity | Insurance And Insurtech, Embedded Finance, Artificial Intelligence And Data
On July 14, 2026, Cover Genius announced a US$100 million capital raise backed by Vista Credit Partners. The financing transaction values the embedded insurance company at US$1.9 billion and will support new AI tools, deeper platform integrations, international growth and selected acquisitions.
The size of the raise is only part of the story. Cover Genius is taking capital from the credit arm of Vista Equity Partners rather than announcing another conventional venture round. It comes after the company increased revenue by 50% in 2025 and built a large base of recurring platform relationships. That gives Vista a more established enterprise software business to finance, although the interest rate, maturity, covenants and any equity features weren’t disclosed.
Cover Genius now connects more than 200 digital platforms with over 50 insurance carriers. It has issued 240 million policies, protected more than 70 million customers and recorded US$3.2 billion in cumulative gross written sales. Its products are available in more than 60 countries and across all 50 US states.
Cover Genius is no longer simply distributing travel insurance at checkout. It provides the software, carrier connections, product design, pricing, claims handling and payment tools that let another company offer protection inside its own customer experience.
Cover Genius works behind platforms including Klarna, Revolut, Stripe, Booking.com, Agoda, Priceline, Uber, eBay and Turkish Airlines. Its reach now spans travel, ecommerce, retail, ticketing, logistics, mobility and financial services.
A platform can use Cover Genius to add insurance or a warranty without building separate systems for each carrier and country. Cover Genius adapts the product, price and presentation to the customer, transaction and location. It can also manage the policy after purchase and pay approved claims in more than 90 currencies.
That operating model reflects the same infrastructure approach seen across embedded financial services. The customer stays inside the merchant or fintech app while a specialist provider handles regulated work behind the scenes. The platform gains another source of revenue and can make the main purchase easier to protect.
Cover Genius competes with several companies. Bolttech combines insurance exchange technology with a broad carrier and distribution network. Qover builds digital insurance programs for fintech, mobility and other European platforms. Boost Insurance provides the regulated and technical stack behind embedded products in the United States. Tint works with marketplaces and software companies on tailored protection programs. Traditional insurers are also improving their APIs and selling directly through large digital partners.
Cover Genius has a scale advantage in the number of countries, industries and large platforms already connected to its system. That scale creates useful data across product selection, pricing, conversion and claims. It also makes the company harder to replace when a partner relies on it across several markets.
The new capital will fund three defined areas of AI development. Cover Genius plans to(1) improve how protection is selected and presented for each customer, (2) support agent led purchasing, and (3) automate more of the claims process.
1. Personalization could help a platform offer the right protection without adding too many choices at checkout. A travel site may know the destination, fare type, booking value and traveller profile. A retailer may know the product category, delivery route and expected replacement cost. Better use of that information could raise insurance sales while reducing irrelevant offers.
2. Agentic distribution has a less settled business case. As software agents begin booking travel or making purchases for users, they may also compare protection, read exclusions and complete the insurance purchase. Cover Genius wants its products and APIs to be available inside that process rather than waiting for a person to select a box on a checkout page.
3. Claims may deliver the clearer near term return. Cover Genius already operates XCover for policy and claims management, XClaim for approved payments and BrightWrite for pricing and product recommendations. More automation could shorten review times and reduce the support burden for both Cover Genius and its partners.
It also raises an important control question. Automated decisions need reliable evidence, clear reasons and a practical route for customers to challenge an outcome. Insurance claims are more sensitive than product recommendations. Faster processing will only improve the customer experience when the decision is also fair and understandable.
The financing choice suggests Cover Genius believes it has enough operating scale to add debt without giving up another large ownership stake. That can be attractive when revenue is growing and enterprise contracts provide better visibility. It also adds fixed obligations that equity financing doesn’t carry.
The company raised US$80 million in a Series D led by Spark Capital in 2024 after reporting 107% revenue growth for 2023. The latest transaction gives it more capital for product development and expansion, but the company hasn’t disclosed current revenue, profitability, cash flow or the cost of the new financing. A US$1.9 billion valuation alone doesn’t answer whether the credit structure is conservative or aggressive.
There are several ways the investment could work well. Cover Genius may deepen existing partner relationships, enter new industries and use AI to improve conversion and reduce claims costs. Its global carrier network could also make selected acquisitions more valuable because acquired products can be distributed through an existing platform.
Execution could become harder as the company expands. Insurance regulation remains local, partner integrations can be complex and claims quality has a direct effect on trust. Larger insurers and other global insurtech platforms are also investing in the same distribution layer. Cover Genius must grow without making its products harder to understand or its claims process harder to challenge.
Canadian insurers, fintechs, travel companies and ecommerce platforms face the same integration problem. Building protection internally requires carrier relationships, licensing, pricing, compliance and claims operations. A provider such as Cover Genius can shorten that work, although Canadian companies still need to understand who controls the customer data, product terms and claims decision.
The funding structure also offers a useful comparison for Canadian growth companies. Private capital markets are giving mature technology businesses more ways to finance expansion after venture equity. Credit can preserve ownership, but it works best when recurring revenue and cash flow can support repayment through a slower period.
Has Cover Genius become the insurance infrastructure layer for digital platforms, or will global carriers and competing insurtechs make embedded protection a lower margin service?
Angus McDonald and Chris Bayley founded Cover Genius after encountering fragmented insurance distribution while operating an online travel business. RentalCover became the first use case for combining digital distribution, policy administration and claims support.
RentalCoverRental vehicle protection distributed through digital booking platforms
LaunchA focused first product built around a clear travel use case
Founder LedEarly development preceded the company’s later institutional funding rounds
Travel And MobilityRental car bookings across multiple countries
Travel PlatformsOnline travel agencies and rental car booking businesses
Integrated ProtectionInsurance offered inside the booking flow rather than through a separate purchase
The first product mattered because it gave Cover Genius a practical route into a difficult market. The company learned the operating work before expanding the platform.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
