





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 15, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, Banking And Credit, Artificial Intelligence And Data

On July 15, 2026, Clutch launches its Lending Automation System (LAS), an end to end lending automation platform built specifically for credit unions. Twelve institutions ranging from US$256 million to US$6 billion in assets have selected it.
The product is designed around a different operating assumption than a conventional loan origination system. Straightforward applications can proceed from intake through decisioning and funding without waiting for a lender to manually advance each step. Applications that need judgment enter a structured staff workflow with the relevant member data, policy checks and required tasks already organized.
Clutch says institutions using the platform have recorded a 1.4x increase in funded loans, application and account opening times that are 2 to 4x faster, and 70% to 85% of loan applications processed automatically through fraud screening and underwriting, with the remaining applications routed to staff when judgment is required. Those are company reported results, but they describe a more substantial operating change than placing a digital form in front of an existing manual process.
The commercial issue is lending capacity. Credit unions compete through member knowledge and relationship service, yet many still rely on staff intensive workflows that become more expensive as application volumes rise. Clutch is trying to separate the loans that require judgment from those that mainly require verified data, policy execution and process completion.
The system combines three parts.
Digital Account Opening and Loan Origination captures applications through online, mobile, branch, call centre and dealership channels. Clutch says the application process can take less than five minutes.
Fastlane applies the credit union’s lending policies, bureau information, verification data and existing member relationship data. That can include account history, prior repayment behaviour, tenure and the depth of the member’s relationship with the institution. The system then sends eligible applications toward funding or identifies the files that need further review.
Clutch Fulfillment handles the exception workflow. Instead of presenting staff with a general queue and an incomplete file, it creates specific tasks, surfaces the relevant context and enforces the credit union’s policy requirements.
Automation is useful when the institution already knows what decision it would make if the required data were available and verified. Human review remains valuable when:
The platform therefore doesn’t eliminate underwriting judgment. It concentrates staff attention on the applications where judgment has more value.
Nicholas Hinrichsen, Co-founder and CEO of Clutch:
“Some loans don't need a person in the middle, they need a system that can move at the speed the member expects.”
Clutch’s operating claim is that a long standing member with strong repayment history and substantial savings shouldn’t wait several days for a routine answer. The risk is that relationship data, automated verification and policy logic still need to be accurate, explainable and consistently governed. Faster processing doesn’t reduce the lender’s responsibility for fair lending, fraud controls, model oversight or credit performance.
The U.S. credit union system remains large but continues to consolidate. The National Credit Union Administration reported 4,250 federally insured credit unions, 145.8 million members, US$2.48 trillion in assets and US$1.73 trillion in loans at the end of the first quarter of 2026. The number of institutions fell by 161 over 12 months.
Operating costs are also rising. NCUA data show non interest expense increased 7.6% year over year in the first quarter, with employee compensation and benefits accounting for more than half of the increase. That creates a direct commercial case for software that can process more applications without requiring staffing to rise at the same rate.
Clutch’s launch group spans institutions with US$256 million to US$6 billion in assets. That range is important because smaller credit unions usually have less technology staff, less capacity to manage complex integrations and fewer specialized underwriters. A phased model that begins with digital intake and automated decisions, then expands into full workflow automation, may be easier to adopt than a complete lending-system replacement.
A San Francisco company Clutch was founded in 2020 by Nicky Hinrichsen and Chris Coleman. It raised a US$65 million Series B in January 2025, bringing total reported funding above US$106 million, and launched its Fastlane automated decisioning and fulfillment engine in July 2025. Clutch now says it serves more than 175 credit unions and 25 million members.
Its reported scale gives LAS a distribution advantage. The company can sell the new system into an installed base already using its origination, deposit opening and engagement products. It can also draw on operational data from multiple institutions when refining product workflows, although each credit union still needs its own policies, controls and risk tolerances.
Clutch competes in a crowded field that includes core banking providers, loan origination vendors, digital onboarding platforms and automated underwriting companies. MeridianLink, Origence, Jack Henry, nCino, Blend, Amount, Fiserv and Finastra all address parts of lending intake, decisioning, workflow or servicing.
The distinction Clutch is offering is credit union specialization. It says LAS was developed over two years with credit union leaders and is priced, integrated and designed around the cooperative operating model rather than adapted from a general bank platform.
A platform that joins application capture, automated decisioning and exception handling can reduce handoffs between products. Each handoff creates delay, duplicate work and another opportunity for the member to abandon the application.
NCFA has already seen the same operating pressure in adjacent lending markets. Conexus backing JUDI.AI connects credit union capital with AI cash flow underwriting for small business loans. TD’s Trust Science deployment brings income verification and AI decisioning into a large bank lending workflow. FintechWerx’s Ruby Loans agreement targets AI-native SME origination for credit unions.
These systems address different borrowers and institutions, but the pattern is consistent. Lending technology is progressing from front end digitization toward data verification, decisioning, workflow control and funding.
For Canadian credit unions, the Clutch launch is relevant even though the initial deployment is U.S. focused. Canada is already seeing coordinated digital banking modernization. Canadian institutions face different provincial rules, market structures, core providers and lending practices. Can relationship based lenders automate routine credit work without weakening oversight or losing the human judgment that differentiates them?
Can credit unions automate enough of the lending process to compete on speed while preserving the relationship judgment that differentiates them?
Nicky Hinrichsen and Chris Coleman founded Clutch in 2020 and focused the company on digital lending for credit unions. The initial product helped institutions originate loans online without replacing their core systems.
ClutchFounded by Nicky Hinrichsen and Chris Coleman
LaunchDigital lending for credit unions
Venture BackedEarly institutional funding supports product development
United StatesCredit union market
Credit UnionsCommunity and cooperative financial institutions
Digital OriginationCompetes with lending technology and origination providers
Clutch entered through a defined institutional market rather than selling a general lending stack. That focus created the product knowledge and distribution base for a wider credit union operating platform.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 13, 2026 | NCFA Market Activity | Cybersecurity And Fraud, Artificial Intelligence And Data, Banking And Credit

On June 25, 2026, Jack Henry expanded its Google Cloud collaboration to develop agentic AI security for banks and credit unions. The U.S. banking technology provider serves about 7,400 community financial institutions and plans to combine Google Security Operations, Gemini Enterprise Agent Platform, and Mandiant Consulting across Google Cloud, other cloud services, and on-premises systems.
The deal is less about access to an advanced model than the work required to deploy one inside a bank. Security evidence is spread across user accounts, devices, applications, networks, and cloud services. Analysts must connect those records quickly enough to determine whether an alert is harmless or part of an attack. Smaller institutions often lack the security teams and integration capacity to do that across several enterprise products.
The divide and conquer commercial logic of the deal is Google brings the models, security software, and threat expertise. While Jack Henry brings the bank relationships and operating knowledge required to put them to work.
Google Security Operations collects security data from across an institution’s systems and connects related alerts into an investigation. Its Triage and Investigation Agent can retrieve evidence, apply threat intelligence, assess likely causes, and explain its findings.
Google says the agent has processed more than five million alerts and reduced a typical 30-minute manual investigation to about 60 seconds. Those are Google product results, not outcomes reported by Jack Henry customers.
The operating gain comes from completing the early investigation before an analyst steps in. Instead of opening several products, finding related records, and rebuilding the sequence of events, the analyst receives an assembled case with supporting evidence and a proposed response.
Sensitive actions still require clear limits and human oversight. Google can pair AI investigations with fixed playbooks and require approval before isolating a device, disabling an account, or blocking traffic. Jack Henry hasn’t said where it will draw those boundaries, how customers will audit agent decisions, or what happens when an automated recommendation is wrong.
Release timing, pricing, implementation requirements, and the first participating institutions also remain undisclosed, so the announcement is good on tech direction but light on adoption or performance figures inside an operating bank.
Mandiant Consulting adds threat modelling, security assessments, and red team testing. That work tests the design before attackers do. Gemini handles reasoning, while Google Security Operations provides the data and investigation tools.
Jack Henry must make the combined service fit each institution’s systems, controls, and support model. That integration is the difficult part.
A bank could buy Google’s security products directly. It would still need to connect the right data, define agent permissions, build response procedures, satisfy audit requirements, and decide who remains accountable for each action.
Jack Henry already operates inside that environment. Its core processing, digital banking, payments, lending, and operational products support institutions that rarely replace critical systems. It also manages hosted and on-premises deployments that a cloud provider may not control.
The companies began working together in 2022 on cloud data, reporting, and integration services. Security extends that relationship into a product Jack Henry can configure around each customer and deliver through an existing technology and support contract.
That could make AI security another banking software service rather than a separate enterprise purchase. Core providers already control the connections, implementation work, and customer access needed to distribute agents at scale.
Security specialists still compete on detection quality, threat intelligence, and response tools. CrowdStrike and Palo Alto Networks are adding agents to their products, while Fiserv offers managed cybersecurity services and is developing AI capabilities. Jack Henry competes from a different position. Its advantage is knowing how community institutions run and where security tools must connect.
Google gains a route into thousands of regulated institutions without implementing its products one bank at a time. Jack Henry can add a service whose value depends on its knowledge of each customer’s systems and operating requirements.
This is where enterprise AI economics become clearer. Foundation models can be sourced from a small group of large providers. The commercial asset is access to the workflow where the model can complete useful work under controlled permissions.
That favours software companies with deep customer integration. Fintech founders don’t need to build a foundation model, but a general AI interface won’t be enough. TD’s AI loan decisioning deployment shows why the value comes from placing verification and decision tools inside an active lending workflow. A specialized process, regulated decision, proprietary dataset, or difficult integration gives an agent work that an incumbent can’t easily reproduce.
Jack Henry hasn’t announced a Canadian release, but the deployment problem is familiar. Canadian regulated AI workshops have identified vendor dependence, data quality, model validation, and accountability as barriers to production use.
Access to a capable model isn’t the constraint. Banks need to connect it to existing systems without losing control of data, permissions, decisions, or operational risk. National Bank’s Sardine deployment follows that reality by embedding external device intelligence and risk scoring into retail, commercial, and wealth operations.
The Canada AI Consortium is working on common controls for models, agents, users, and enterprise systems. Its use cases differ from Jack Henry’s security project, but the operating requirement is the same: agents need restricted access, visible decisions, and accountable people.
For Canadian banks and fintechs, the commercial challenge is solving those controls inside regulated workflows. Products that leave the integration and governance work to the bank may struggle to progress beyond a pilot.
As foundation models become easier to replace, will banking software competition depend less on who owns the AI and more on who controls the workflows where agents can act?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 4, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Digital Assets Blockchain And Tokenization, Cybersecurity Fraud And Financial Crime, SME Finance And Business Banking, Capital Markets And Market Infrastructure, Policy Regulation And Governance, Risk Compliance And Regtech, Data Privacy And Governance

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026).
AI training data now carries an auditable collection burden across source choice, legal basis, sensitive data and model output controls. Canadian fintechs using European personal data should map what is scraped, why it is needed, who controls the processing and how records can be filtered or removed before consultation language becomes supervisory practice.
Fund innovation depends on regulatory speed as well as product design. Asset managers, exchanges, fintechs, wealth platforms and regulators should watch how dedicated approval pathways and product specific guardrails influence the pace of retail investment innovation without reducing investor protection.
Swift is testing whether tokenized deposits can extend today's banking infrastructure into always available cross border payments without replacing existing settlement systems. The pilot results will provide an early benchmark for bank led tokenized payment networks.
Always on market design is moving beyond crypto. Exchanges, brokers, clearing firms, liquidity providers, risk teams and regulators should watch how 24/7 trading changes oversight, operations, margin, surveillance and market resilience.
Credit infrastructure is consolidating around data depth, identity coverage and alternative underwriting. Lenders, fintechs, credit bureaus, SME finance platforms and regulators should watch how alternative data, fraud controls and AI assisted decisioning affect credit access for thin file borrowers and small businesses.
Hong Kong is replacing a widely used authentication method across online securities and regulated virtual asset trading. Brokers and platforms also need stronger monitoring, client notifications and incident response procedures, while senior management may be held accountable for losses caused by inadequate controls.
The findings connect payment design directly to fraud exposure, customer friction and trust. Lower fraud by transaction count is encouraging, but higher losses by value and rising first-quarter fraud show why scale requires stronger authentication, transaction risk data and coordinated controls. These operating results add important context to the UK’s payment milestone and Canada’s trust framework.
Financial institutions and technology providers will gain a structured environment for testing AI security tools against European requirements. Firms serving the European market should prepare to demonstrate model safety, operational resilience and secure deployment before advanced systems enter critical financial operations.
AI cyber risk is now a financial stability issue. Banks, fintechs, payment firms, infrastructure operators, software vendors and supervisors should watch how AI vulnerability discovery, third party concentration, open source dependencies and cyber resilience planning become part of financial sector oversight.
Circle's trust charter places a major stablecoin issuer inside the U.S. federal banking framework. The pace of implementation, custody adoption and any future expansion into reserve management will show whether trust banks become the preferred operating model for regulated stablecoin infrastructure.
The paired licences let one regulated provider connect crypto conversion, asset transfers, conventional payments and payment accounts. Firms pursuing similar models across Europe will need to determine when MiCA authorization must be combined with payment permissions as their products cross from digital assets into fiat payment execution.
Crypto platforms are moving toward regulated multi-asset investment access. Exchanges, brokers, dealers, crypto platforms, regulators and investors should watch how derivatives, equities and crypto converge inside licensed investment platforms.
MiCA is becoming a market access gate for global digital asset firms. Banks, payment companies, custodians, stablecoin issuers, exchanges and compliance teams should watch how full EU authorizations shape cross-border crypto services, institutional distribution and regulated stablecoin infrastructure.
Eltropy is turning agentic banking into a platform market rather than a closed vendor product. The commercial question is whether shared controls, integrations and distribution can make specialized financial agents easier for smaller institutions to adopt.
Regulated AI adoption needs control infrastructure, not only models. Banks, insurers, telecoms, fintechs and compliance teams should watch how agent oversight, inference monitoring, shared IP and enterprise control planes become part of Canadian AI governance.
AI in retail finance is becoming a competition, consumer protection and fraud issue at the same time. Banks, fintechs, wealth platforms, insurers, lenders and compliance teams should prepare for AI agents, personalization, delegation, identity controls and new forms of consumer harm.
Large fintechs are testing direct charter strategies again. Lenders, BNPL firms, embedded finance platforms, banks, investors and regulators should watch whether major payment and credit firms choose bank partnerships, owned charters or hybrid models for the next stage of regulated growth.
Regulators are increasing both the reach and speed of financial misconduct enforcement. Firms now face faster detection, coordinated action across jurisdictions and far less time to correct weak promotion, reporting and compliance controls.
This week’s intelligence points to a more mature phase of financial innovation. Stablecoins are entering regulated banking structures, tokenized deposits are nearing live payment use, regulators are setting terms for continuous markets, and AI governance is becoming a practical operating requirement. In Canada, the Real Time Rail rules, PSP access model and planned Q4 launch show how domestic payment modernization is entering the same execution stage. Advantage will favour institutions that can combine trust, regulatory readiness and delivery at scale.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 9, 2026 | NCFA Market Activity | Fintech AI/ML, Data-driven, Automation, Generative AI, Enterprise, Scaleup, Fintech And Innovation
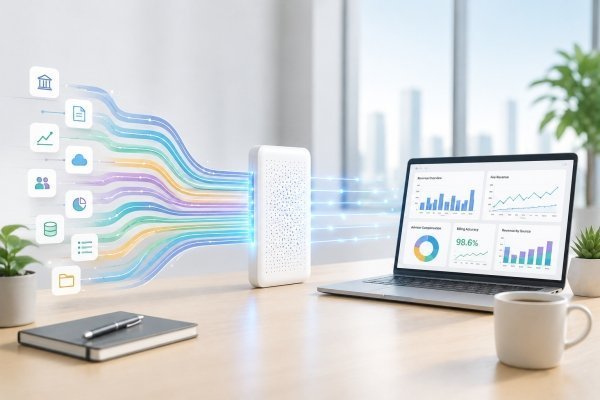
Wealth firms can’t automate revenue operations if the upstream data that's feeding billing, advisor compensation and reporting still needs manual repair.
On July 8, 2026, Toronto based PureFacts announced a strategic partnership with WealthTechs to launch new data aggregation and ingestion capability for wealth and asset management firms.
PureFacts will license and embed WealthTechs’ data aggregation and connectivity technology into its platform. The company will use the technology to connect, normalize and validate data before it enters revenue workflows.
Those workflows are high stakes. PureFacts supports fee billing, advisor compensation, practice management and revenue intelligence.
Robert Madej, Founder and CEO of PureFacts, said:
"This partnership with WealthTechs marks an important step forward in our mission to empower wealth firms with a trusted data foundation."
Wealth management has a data plumbing problem inside revenue operations.
Account records, transactions, portfolio data, fee schedules, householding rules and advisor relationships often come from different systems. The business still has to turn that data into client fees, advisor compensation, reporting and management insight.
PureFacts describes its platform as Revenue Performance Management software. Its product set includes fees and billing, advisor compensation, practice management and revenue book of record. WealthTechs brings an ingestion layer that turns source data into usable operating data.
Revenue, compensation and compliance teams all depend on the same underlying data. If that data is inconsistent, every workflow downstream inherits the problem.
PureFacts says the partnership supports future agentic AI capability, but the initial work starts with cleaner data.
Data has to be connected before it can be used. It has to be normalized before it can be compared. It has to be validated before a firm can trust automation inside billing, compensation or advisor operations.
The same requirement is emerging across wealth management. See: FutureVault Ships Agentic Document Intelligence For Advisors.
Agentic AI is even riskier since it may initiate a workflow, recommend an action or help resolve an exception. In wealth operations, that means the data layer needs controls, auditability and clear ownership before automation scales.
The partnership gives PureFacts a deeper data ingestion capability for revenue operations. Not AI as a headline. AI as the downstream beneficiary of cleaner enterprise data.
Can wealth firms deploy agentic AI in revenue operations before they solve data aggregation, normalization and validation?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 9, 2026 | NCFA Market Activity | Payments And Money Movement, SME Finance And Business Banking, Fintech And Innovation
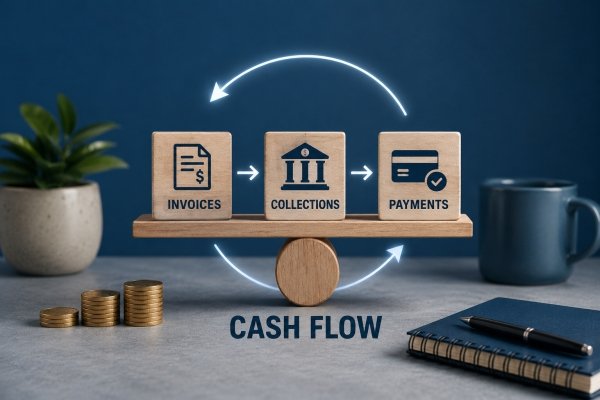
On July 7, 2026, Winnipeg based Telpay announced that it acquired Notch Financial, a Toronto based accounts receivable automation company. Terms weren't disclosed.
The acquisition brings accounts receivable, invoicing and payment collection together with Telpay’s existing payment, payroll and approval workflows, expanding the platform from payment execution toward SME cash flow management.
Mark Loewen, President of Telpay, said:
"Businesses don’t lose sleep over how payments are processed, they worry about whether they’ll have the cash they need when they need it."
Notch Adds Receivables To Telpay who has spent more than 40 years helping businesses manage money going out through supplier payments, payroll and approval workflows. Notch adds the incoming cash side, including invoices, collections and receivables visibility.
The transaction confirms that Telpay is going from payments execution toward cash flow control for Canadian SMEs.
The acquisition comes as Canadian small businesses are paying closer attention to receivables, working capital and payment timing.
Payment timing remains an important operating indicator for Canadian SMEs. See: Canadian Small Business Revenue Turns Negative In Q4.
Cash flow pressure doesn't always come from a lack of sales. It can come from slow collections, manual invoicing, fragmented approvals or poor visibility into what cash is actually available. That's why AR and AP automation are becoming core SME infrastructure rather than back office software.
The same trend appears in Open Finance SME Capital Access, where fresh invoice, payment, account and cash flow data can support faster credit decisions and better liquidity tools.
Payment companies are expanding beyond transaction processing into the operating layer around cash flow. See: Lloyds Expands SME Payments With Stripe Infrastructure.
The strategic question though is who owns the actual SME relationship? The account, the payment workflow, the operating data or the cash flow tools.
Telpay now covers both sides of SME cash flow: (1) Outgoing payments through supplier payments and payroll, and (2) Incoming cash through invoicing, collections and receivables visibility.
The platform value increases when a business can see both sides without stitching together separate tools.
Jordan Huck, CEO of Notch, said:
"Together, we see tremendous opportunities to deliver even more value as businesses manage every aspect of their cash flow."
Will Canadian SME payment platforms win by processing transactions, or by owning the cash flow workflow around invoices, collections, approvals and working capital?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 9, 2026 | NCFA Market Activity | Banking And Lending, Artificial Intelligence And Data, Digital Identity And Trust, Risk Compliance And Regtech, Fintech And Innovation

On July 7, 2026, Trust Science announced a bank wide Master Services Agreement with TD to improve loan approval and origination turnaround times.
TD is initially using Trust Science’s income verification and reporting capabilities to support fast, secure, real time loan decisioning. TD Auto Finance Canada is the first TD business to use the capability and has begun rolling it out through 5,500 authorized dealers across Canada.
This is a practical in market AI lending infrastructure signal. A major Canadian bank is applying real time income verification and credit decisioning technology inside an active loan origination channel, starting with auto finance where speed, dealer experience and risk controls all paramount.
Income verification remains one of lending’s most stubborn workflow problems.
Borrowers want fast answers. Dealers want clean handoffs. Lenders need enough verified income evidence to make a responsible decision without slowing the application down. That tension is especially visible in auto finance, where the lending decision often happens inside a sales process.
Trust Science has built its platform around AI assisted credit decisioning, risk management and consumer reporting. The TD rollout extends that platform into real time income verification, giving lenders verified borrower information earlier in the loan origination process.
Real time income verification is a direct open finance use case. Permissioned financial data can help verify income, assess affordability, support cash flow analysis, flag fraud risk and reduce onboarding friction. See: Open Finance SME Capital Access.
TD Auto Finance gives Trust Science a high volume lending channel where verification speed affects the borrower, dealer and lender at the same time.
Michael McGhee, SVP and Head of TD Auto Finance Canada, said Trust Science’s solution helps TD offer dealers and clients “a simpler and faster way to do business with us.”
Trust Science positions itself as an AI powered credit decisioning and risk management platform, a licensed Consumer Reporting Agency and Canada’s third modern credit bureau.
Canada’s credit market has long been dominated by large incumbent bureaus and traditional credit files. Trust Science is competing from a different angle now with income verification, alternative data, AI decisioning, workflow automation and fraud reduction.
Evan Chrapko, founder and CEO of Trust Science, said TD is using the company’s real time decisioning platform and proprietary processes to get loan decisions made “as quickly as possible with less risk.”
That's the commercial promise. The regulatory and trust challenge is whether AI assisted decisioning can improve speed while keeping lending evidence accurate, explainable and fair.
AI credit decisioning only works when the underlying data is reliable.
Income, identity, fraud signals and borrower information have to be verified before automation can add value. Otherwise, faster decisioning only pushes weak inputs through the system faster.
Faster lending workflows need stronger verification controls. See: How Fraud Broke The Old Rules Of Trust And Verification.
That applies directly to lending. Faster origination is useful only if the lender can trust the borrower evidence, detect fraud and explain the decision path.
Will real time income verification become standard infrastructure for AI assisted lending, or stay limited to high speed channels like dealer finance?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 9, 2026 | NCFA Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech, Cybersecurity And Fraud, Digital Identity And Trust, Payments And Money Movement, Digital Assets Blockchain And Tokenization

On July 8, the Cambridge Digital Innovation & Regulation Initiative (C:>DIR), hosted by Financial Innovation for Impact (Fii), launched the Global Agentic Regulator Hackathon. Applications are NOW OPEN for a worldwide challenge that brings together policymakers, regulators, AI researchers, engineers, financial institutions, fintechs, RegTechs, SupTechs, academics and technology innovators to develop practical, explainable and deployable agentic AI prototypes for public authorities. The National Crowdfunding & Fintech Association of Canada (NCFA) is participating as an Ecosystem Partner to help promote the initiative across global fintech ecosystems, including Canada's fintech, AI and innovation networks.
The virtual hackathon runs from July 8 to September 18, 2026, with concept note submissions due by July 31. It carries a US$100,000 prize pool, and winning teams will also be invited to present at the Singapore FinTech Festival, hosted by GFTN. The launch is supported by the BIS Innovation Hub, Global Financial Innovation Network (GFIN), Digital Regulation Cooperation Forum (DRCF), and a global group of supporters, ecosystem partners and academic institutions.
AI agents are already operating in financial services. The next question is whether regulators will have the tools to supervise them.
According to the organizers, the CCAF 2026 AI in Financial Services Global Report found that 58% of fintechs and 47% of traditional financial institutions are adopting agentic AI, compared with 28% of regulators. That gap is important because AI agents can recommend, transact, monitor, route, execute and coordinate across systems faster than traditional supervisory processes were designed to handle.
This is why the hackathon is strategically important. It treats agentic AI as a supervision and infrastructure issue, not just a productivity tool. Public authorities need better ways to monitor risks, test model behaviour, understand accountability and respond to market activity that can develop at machine speed.
Participants will develop prototypes across six challenge areas:
These themes reflect where financial supervision is likely to be tested first as AI systems begin initiating transactions, interacting with digital assets, providing financial guidance and coordinating increasingly complex financial activities.
For founders, researchers, fintech teams, RegTechs and infrastructure providers, the opportunity is not simply to build smarter AI. It is to help shape the supervisory capabilities that may define trusted digital finance as autonomous systems become more common.
The breadth of organizations involved is a strong signal. With regulatory partners, global financial innovation networks, technology firms, academic institutions and ecosystem groups participating, the hackathon shows that agentic AI oversight is becoming a shared public and private sector priority.
For Canadian participants, the timing is also practical. Canada has strengths in artificial intelligence, financial services, digital identity, payments, cybersecurity, digital assets and regulatory innovation. This gives Canadian builders a chance to contribute to global supervisory tools before standards and operating models become more established internationally.
The organizers are seeking multidisciplinary teams that combine regulatory knowledge with technical expertise, including:
| Milestone | Date |
| Preliminary round opens | July 8, 2026 |
| Concept submissions close | July 31, 2026 |
| Teams selected | August 4 to August 14, 2026 |
| Virtual build phase | September 1 to September 8, 2026 |
| Global demonstrations and regulator voting | September 15, 2026 |
| Winners announced at the C:>DIR Summit, Cambridge | September 18, 2026 |
Applications for the preliminary round are open until July 31, 2026. Regulators, AI researchers, engineers, fintechs, RegTechs, SupTechs, financial institutions, universities and technology innovators are invited to submit concept notes and develop practical agentic AI prototypes for the future of financial supervision.
Read the full challenge details and submit your application through the official C:>DIR Global Agentic Regulator Hackathon page.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
