




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 9, 2026 | NCFA Fintech Market Activity | Payments And Market Infrastructure
On June 9, 2026, Lloyds launched Lloyds Accept, a new suite of payment tools powered by Stripe and built into Lloyds' Business Account for UK small businesses.
The launch puts fintech payment infrastructure inside a major bank's SME account relationship. Lloyds says the service gives business customers access to in person payments, online payments, invoicing, payment links, and reporting from one account environment.
Lloyds brings the customer base and banking relationship, while Stripe brings merchant payment infrastructure, onboarding, acceptance, and developer led tools. Lloyds Banking Group says it serves 26 million customers, giving Stripe access to a large UK banking channel without competing for every merchant relationship directly.
Stripe's 2025 annual update confirms that businesses on its platform generated $1.9 trillion in total payment volume, up 34% from 2024. The company also expanded UK products in 2024, including Pay by Bank and business financing, showing expansion into account based payments, working capital, and SME financial operations.
Lloyds is adding specialist payment infrastructure inside its own SME banking relationship instead of building every part itself. Payment acceptance is the visible feature, but onboarding, reconciliation, reporting, fraud controls, financing, and embedded workflows create the larger infrastructure opportunity. Canadian banks are also partnering for merchant payment infrastructure, which shows the same bank fintech execution pattern in another market.
So where is the value accumulating? Banks still control the customer account, balance sheet, trust, and distribution channel. Infrastructure providers increasingly control the operations that powers day to day business activity. That creates practical opportunities around merchant onboarding, payment operations, treasury tools, fraud controls, and business automation, which connect naturally to NCFA’s Financial Innovation Map.
As banks rely more on specialist infrastructure partners, who will own the most valuable parts of the SME relationship? The account, the payment workflow, the operating data, or the tools that help small businesses manage cash flow.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 9, 2026 | NCFA Fintech Market Activity | Lending Consumer Credit And BNPL
On June 9, 2026, Coinbase announced that it's expanding the role of USDC inside its financial ecosystem by a new Coinbase One Card program that allows eligible customers to secure a credit card with USDC held on the platform. Coinbase says the card can serve customers who might not qualify for a traditional unsecured credit card while continuing to participate in the Coinbase ecosystem.
The product adds another use case to a stablecoin that already supports trading, payments, transfers, rewards, and savings. Coinbase's documentation confirms the USDC security deposit model, where customers use USDC as collateral to secure their credit line.
The launch also highlights how fintech infrastructure providers are helping digital asset platforms expand into traditional financial products. According to a Cardless case study, Coinbase uses Cardless to power card program infrastructure, application workflows, servicing, and payment experiences. First Electronic Bank issues the card and American Express provides network access. The arrangement allows Coinbase to focus on customer acquisition, account balances, rewards, and product design while specialized partners handle card infrastructure and issuance.
Coinbase already has significant card activity to build from. In its Q4 2025 shareholder letter, the company reported nearly $800 million in cumulative Coinbase One Card spend and approximately $3,000 in average monthly spend per cardholder. The same filing reported $17.8 billion in average USDC balances held across Coinbase products.
The strategy aligns with the effort to make digital assets usable beyond trading. Earlier this year, Coinbase partnered with Better to bring crypto assets into mortgage workflows, allowing qualified borrowers to use digital assets during the home financing process. Together with the new card program, Coinbase is steadily expanding how digital asset balances can support borrowing, spending, and credit access.
The scale behind that strategy continues to grow across industry. Circle reported in its Q1 2026 results that USDC reached $77.0 billion in circulation and processed $21.5 trillion in onchain transaction volume during the quarter. As stablecoin infrastructure matures, questions around collateral design, credit access, and lending increasingly connect to broader discussions around tokenized collateral and cash.
If stablecoins can secure credit, platforms with large customer balances gain a new way to compete for lending relationships. The bigger question is whether consumers increasingly view stablecoin holdings as spending power, borrowing collateral, and financial reserves rather than simply digital payment assets?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 9, 2026

Going public puts every control your fintech owns or outsources under a microscope. Auditors, regulators, and future shareholders want hard evidence that third-party weak spots cannot derail your debut.
Roughly 30% of breaches trace back to external suppliers, and each incident costs an average $4.44 million, according to IBM's 2024 Cost of a Data Breach Report. Advisers preparing S-1 filings increasingly want a repeatable way to assess outside cyber risk before the SEC asks, and investors read disciplined third-party oversight as a proxy for operational maturity.
Here is the catch: your SOC 2 program alone will not clear the public-company bar. SOC 2 demonstrates protection of customer data, while SOX 404 focuses on financial-reporting integrity. A purpose-built vendor-risk platform bridges that gap by connecting vendor security evidence to the controls auditors expect in an IPO cycle. We ranked five platforms on the criteria that matter most for IPO prep: compliance fit, automation depth, auditor acceptance, and cost-to-value.
We started with fifteen tools from analyst waves, forums, and twenty competitor write-ups, then removed anything lacking a purpose-built vendor-risk module or fintech case study, leaving five contenders. We scored each on a 100-point scale across four questions:
Two CISOs who took fintechs to market last year reviewed the weighting, confirming it reflects where auditors press hardest.
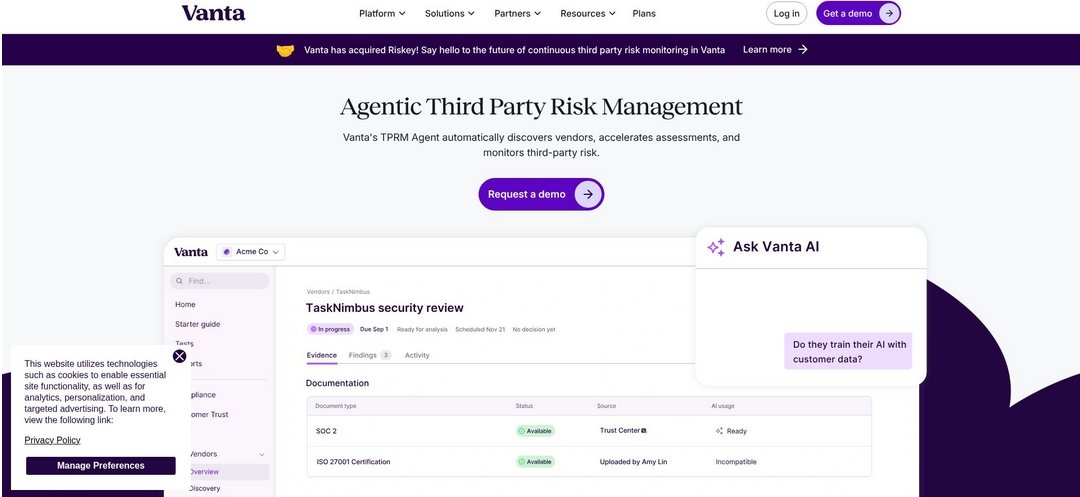
Vanta folds vendor oversight into the same dashboard you use for SOC 2, helping teams remediate risk up to 45% faster. VRM, compliance automation, Trust Center, and SOX ITGC live in one system with shared evidence and cross-framework mapping.
Verdict: best fit if your IPO plan needs one platform to run SOC 2, stand up SOX ITGC, and operationalize vendor oversight. If you need managed analyst services or board-ready vendor portfolio reporting, compare TPRM-specialized options.
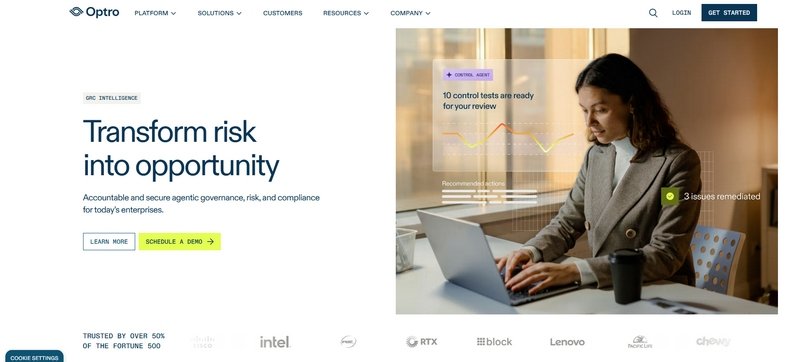
Optro rebranded from AuditBoard in March 2026. It keeps the same product family public-company SOX teams know: SOXHUB (SOX program management), CrossComply (multi-framework compliance), and a connected TPRM module. More than half of the Fortune 500 use it, and it is one of the most common SOX systems Big Four auditors are comfortable testing.
Verdict: choose Optro if full SOX 404 depth (ITGC plus financial process controls) and audit-firm fluency top your list. For SOC 2 day-to-day, a Trust Center, and AI-compressed vendor reviews, you will likely pair it with another platform.
OneTrust grew from privacy management into a broad GRC suite with a substantive third-party risk module, serving 14,000+ customers across regulated industries. It fits when vendor oversight has to live next to privacy, ethics, and ESG in one control fabric.
Verdict: right when vendor risk must sit alongside privacy, ethics, and ESG in one enterprise fabric and you can absorb a longer rollout. To consolidate SOC 2, SOX ITGC, and AI-assisted reviews into one fast-moving platform, OneTrust typically needs pairing.
Prevalent is a pure-play TPRM platform with more than two decades of specialization, acquired by Mitratech in October 2024 and rated a Strong Performer in Forrester's Third-Party Risk Management Wave (Q1 2026). It is the heavyweight option when vendor risk itself is the program.
Verdict: choose Prevalent for bank-style TPRM depth, broad regulatory mapping, and multi-domain continuous monitoring. To collapse SOC 2, SOX ITGC, and vendor oversight into one platform, expect to add complementary tools.
Venminder is a TPRM platform for regulated financial-services teams that want to outsource a share of vendor due diligence. It pairs software with managed services where certified analysts review vendor materials and deliver risk-rated outputs. Venminder was acquired by Ncontracts in September 2024 (Hg Capital-backed); it has 1,200+ customers, and the combined entity serves 5,000+.
Verdict: strong when capacity and expertise are the constraint and you want platform-plus-analysts diligence with contract oversight. To consolidate SOC 2 evidence, SOX ITGC, and VRM into one system, Venminder adds tool sprawl rather than reducing it.
In most fintechs, SOC 2 lives with Security and SOX 404 with Finance, and your vendors sit in the overlap. Treat them as two programs and you get two inventories and two sets of audit questions that never reconcile. Build one vendor register that serves both audits instead.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 9, 2026 | NCFA Resource | Capital Formation And Crowdfunding
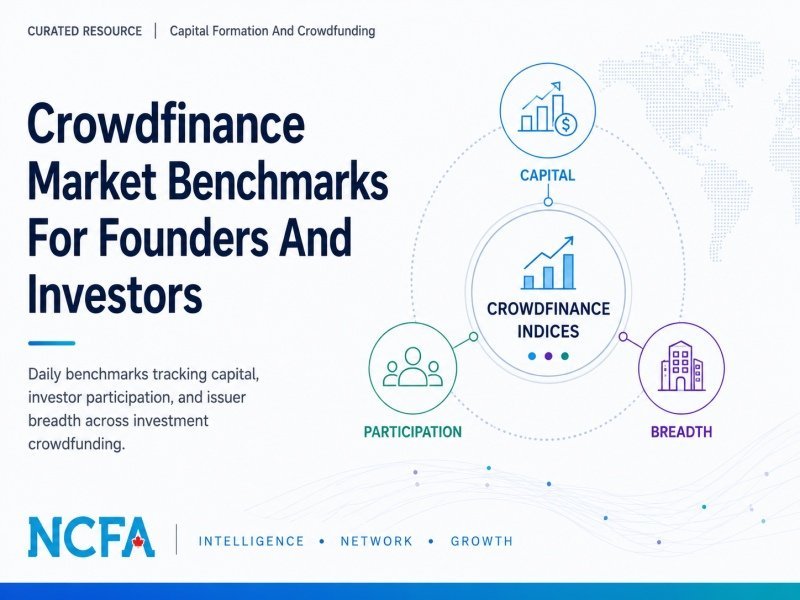
Crowdfund Capital Advisors launched the CCA Crowdfinance Indices, a family of daily benchmarks for the U.S. Regulation Crowdfunding market. The resource tracks more than dollars raised. It measures capital, investor participation, and issuer breadth so founders, investors, platforms, and policymakers can see whether market activity is broadening, concentrating, or cooling.
The data is U.S. specific, but the measurement framework travels. Canada and other jurisdictions can use the same lens to think more clearly about crowdfunding market health, capital access, investor activity, and whether opportunity reaches a wider base of companies.
The indices separate investment crowdfunding activity into three useful indicators.
That breakdown matters because capital raised alone can hide what is really happening. A market can show higher capital while fewer companies receive funding. It can also show more investor activity while average checks get smaller. CCA’s framework helps users see the drivers behind the headline number.
CCA says the indices draw from its CCLEAR data platform and cover activity across leading U.S. intermediaries. The dashboard also includes sector views across technology, healthcare and life sciences, food and beverage, consumer and retail, fintech and financial, energy and cleantech, and real estate and construction.
CCA reports that issuers tracked by the Composite have raised nearly $3.1B across more than 9,000 companies. That makes the index family useful as a market reference, not just a launch announcement.
This resource is useful for crowdfunding platforms, founders, angel investors, policy teams, researchers, ecosystem builders, securities regulators, funding portals, and capital formation advocates.
It is especially useful for anyone trying to understand whether investment crowdfunding is becoming a deeper market, a more concentrated market, or a broader channel for startup and small business finance.
The strength of this resource is its market structure lens. It turns crowdfunding activity into a more useful set of indicators. Capital shows money flow. Participation shows investor engagement. Breadth shows issuer access.
The limit is geography. The indices measure U.S. Reg CF activity. They don't measure Canadian crowdfunding activity or global crowdfunding flows. Canadian readers should use the resource as a benchmark for comparison and market design, not as a proxy for Canada.
That distinction makes the resource more valuable, not less. It shows what better market intelligence could look like in other jurisdictions where crowdfunding data remains fragmented, delayed, or hard to compare.
CCA Crowdfinance Indices Dashboard (primary dashboard)
Reg CF At 10 Shows Equity Crowdfunding Works (cap modernization context)
Fintech Fridays EP57: Equity Crowdfunding 10 Years After Jobs Act (investment crowdfunding history)
UK Crowdfunding Caps Lift As EU Pushes €12M (global cap comparison)
National Instrument 45-110 (Canadian startup crowdfunding rules)
SEC Regulation Crowdfunding (U.S. Reg CF overview)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 8, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization
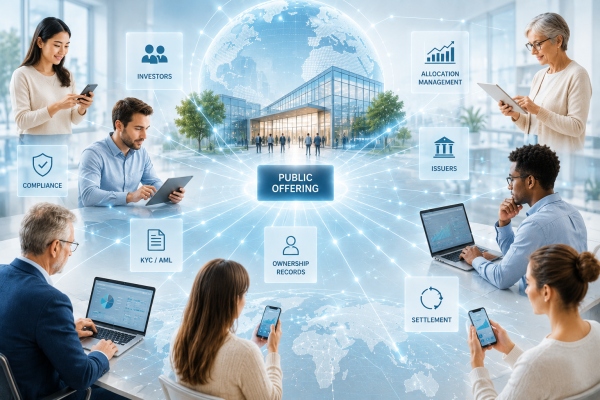
On June 7, 2026, Bybit launched IPO Express, a platform that gives eligible users access to tokenized IPO allocations starting with SpaceX. The launch arrives as SpaceX prepares for a public offering expected to value the company at approximately $1.75 trillion, making it potentially one of the largest IPOs ever. While the SpaceX name grabs attention, the bigger story is what this says about investor access, capital formation, and the growing role of digital infrastructure in public markets.
While the SpaceX name grabs attention, the bigger story is how firms are competing to expand investor access and improve IPO distribution.
Traditional IPO allocations typically flow through investment banks, brokerage firms, institutional investors, and private banking networks. Retail investors often participate only after public trading begins.
Bybit's model broadens access by allowing eligible users to subscribe through exchange infrastructure before trading starts. Investors can receive allocations and subsequently trade tokenized exposure through the platform.
The model combines several functions that have historically operated through separate systems, including investor onboarding, allocation management, compliance, custody, ownership records, and trading. Companies are now competing to modernize how investors access public offerings.
Much of the discussion around how tokenization is changing markets has focused on stocks, bonds, funds, real estate, and other assets after issuance. IPO Express focuses on an earlier stage of the investment lifecycle.
For decades, financial innovation concentrated around trading efficiency, lower transaction costs, and faster settlement. Tokenized IPO access targets a different challenge related to who gets access to investment opportunities in the first place.
Investor verification and eligibility checks now matter as much as trading access. So do allocation rules, ownership records, compliance controls, and settlement. Platforms that combine these functions in one clean workflow may earn an advantage as capital markets become more digital.
Canada has already seen similar efforts to expand investor participation through equity crowdfunding, online exempt market platforms, private market technology, and digital investment platforms.
Canada already has a live comparison point. Wealthsimple’s IPO Access for Canadian retail investors broadens access through a brokerage account, while Bybit’s IPO Express adds a tokenized layer around allocation and trading. Both are aiming to solve the same pressure in capital markets: retail investors want earlier access, cleaner digital onboarding, and a fairer shot at high demand offerings.
NCFA’s Who Gets Capital As Funding Channels Multiply? asks the same core question for Canadian markets. More channels don't automatically create better access for every founder or investor.
Tokenized IPO access brings the same access and onboarding pressure to public exchange listings. For Canada, the practical question is whether regulated platforms can use digital infrastructure to make capital raising easier without weakening disclosure, custody, suitability, or investor protection. That question fits NCFA’s financial innovation market infrastructure research, where access to capital, tokenization, compliance, and investor trust now overlap.
If retail investors can access high demand offerings through faster digital channels elsewhere, how long can domestic platforms rely on slower, relationship driven distribution models?
The competitive advantage may no longer come from who controls the allocation. It may come from who makes access easiest while still meeting regulatory requirements.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 8, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization
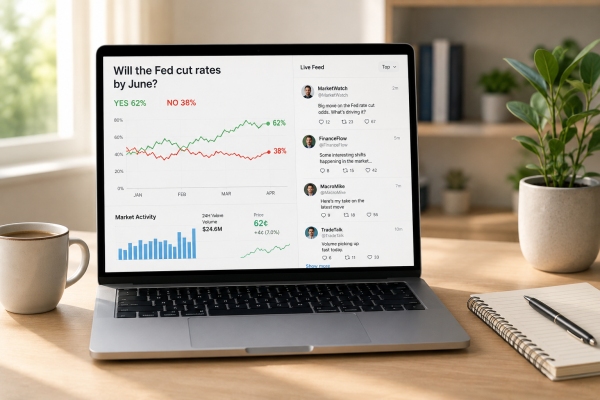
On June 5, 2026, Politico published an investigation into Polymarket's influencer marketing program. The report found that Polymarket chief marketing officer Matthew Modabber allegedly used a personal PayPal account to send at least $350,000 to content creators between January 2025 and February 2026. Politico's review identified over 490 social media posts promoting Polymarket that allegedly didn't clearly disclose paid relationships.
The investigation paints a picture far larger than a disclosure dispute. It's a rare look into how prediction markets are building distribution, visibility, and cultural relevance while simultaneously becoming one of the most discussed forecasting platforms in politics, sports, current events, and financial markets.
At least 20 creators identified by Politico promoted Polymarket after receiving payments. The report also found more than $2.5 million in transfers from the account to over 800 recipients during the period reviewed. Several influencers allegedly framed Polymarket odds as breaking news or authoritative indicators of future events. One creator told Politico that the company provided suggested post copy and encouraged promotion of specific markets.
The story reveals something many people inside fintech have quietly observed for years. Prediction markets are no longer simply markets. They are becoming media businesses.
Traditional exchanges compete for liquidity. Prediction markets increasingly compete for attention.
Polymarket's growth coincided with the 2024 U.S. election cycle, where billions of dollars flowed through election related contracts. Politico's reporting shows that influencer distribution became part of that growth strategy. The objective was not only attracting traders. It was turning Polymarket into a source people referenced when discussing politics, government decisions, sports outcomes, and breaking events.
The strategy appears to have worked. Today, prediction market odds regularly appear in mainstream media coverage. News organizations cite them. Social media users share screenshots of them. Investors discuss them. Politicians reference them. The market itself increasingly becomes part of the story.
It's a new category that's somewhere between financial infrastructure, media distribution, forecasting, and social networks.
The obvious asset is trading volume. The less obvious asset is trust. Many of the influencers highlighted in Politico's investigation promoted Polymarket as exceptionally accurate. Some described the platform as a superior forecasting mechanism compared to polling. Others highlighted successful market predictions as evidence of credibility.
This creates an unusual challenge. Prediction markets derive value from the perception that they aggregate independent information better than traditional alternatives. If users begin questioning how information reaches the market, who amplifies market narratives, or whether promotion and prediction are becoming intertwined, trust becomes harder to maintain.
The issue isn't whether influencer marketing is permitted. Many fintech companies use creators, affiliates, newsletters, podcasts, and social media personalities. The issue is whether users can clearly distinguish between market intelligence and paid amplification.
The most important opportunity may not be another prediction market. It's infrastructure that helps users understand how market information forms, spreads, and gains credibility.
As prediction markets, AI systems, social media platforms, and financial products become more connected, users need better ways to answer practical questions.
The next generation of prediction market innovation opportunities may come from building verification, disclosure, provenance, surveillance, and transparency tools around these markets.
These capabilities are still early. As prediction markets expand into politics, sports, finance, and public policy, demand for trust infrastructure should grow with them.
The Politico investigation focuses on influencer payments, disclosure practices, and marketing tactics, but the larger takeaway is that prediction markets are evolving beyond trading venues. They're becoming information platforms. That evolution creates opportunity, but it also creates responsibility. Today, Reuters posted about predication markets facing rising scrutiny over insider trading controls, reinforcing that these markets need trust infrastructure around promotion, surveillance, suspicious trading, and market transparency.
Markets that increasingly influence public understanding of events will face greater scrutiny over how information enters the system, how narratives spread, and how trust is earned. The next competitive opportunity may be proving that market intelligence can be trusted.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 30, 2026 | NCFA Fintech Whisperer | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data, Regulation and Policy, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026).
Tokenized bonds are moving from pilots into market structure work. Issuers, dealers, custodians, infrastructure providers, and regulators need practical answers on issuance, settlement, custody, disclosure, and secondary liquidity before tokenized fixed income can scale.
The value of cross chain infrastructure comes down to whether developers can route liquidity without exposing users to bridge complexity. The $230M private beta gives 0x early usage evidence, but the larger test is reliability across payments, RWAs, trading, and agent workflows when volumes move beyond controlled integrations.
Stablecoin licensing is becoming a competitive infrastructure tool for financial centres. Issuers, banks, PSPs, custodians, and regulators should track which jurisdictions turn stablecoin rules into live market access rather than policy design alone.
Tokenized money market funds are becoming part of institutional onchain liquidity infrastructure. Asset managers, custodians, PSPs, stablecoin issuers, and treasury teams should track how stablecoins connect with regulated fund products, redemption workflows, and stablecoin payment infrastructure.
Institutional DeFi is shifting toward custody controlled access models. Asset managers, custodians, exchanges, advisers, and compliance teams should track whether qualified custody plus curated onchain strategies becomes the operating model that brings DeFi exposure into regulated portfolios.
The useful signal is not simply another crypto loan product. It is committed buyer capital behind crypto backed credit, which can make the product more repeatable. The key risks remain collateral volatility, liquidation design, borrower suitability, and whether digital asset wealth can support credit access without turning into hidden leverage.
Crypto collateral can help asset rich borrowers avoid selling Bitcoin or USDC, but housing finance brings stricter expectations around suitability, custody, volatility buffers, and borrower protection. The product will need to prove it expands access without importing crypto market risk into mortgage underwriting.
Large banks are moving from stablecoin observation into direct tokenized money infrastructure. Treasury teams, payment providers, fintechs, custodians, and infrastructure operators now need to track whether commercial bank money becomes a regulated settlement layer for high value payments, liquidity management, and cross border transactions.
Western Union’s stablecoin entering a major crypto exchange channel adds another proof point for stablecoins becoming payment infrastructure. PSPs, exchanges, banks, remittance firms, and compliance teams should track how regulated issuers, fiat channels, and global payout networks connect. This adds a distribution proof point for regulated stablecoins. Western Union brings the remittance brand and global currency footprint, while Bybit brings crypto exchange access. The open question is whether USDPT becomes a settlement asset customers actually use, or another branded stablecoin competing for scarce transaction depth.
Central bank money settlement is being designed for programmable markets. Banks, FMIs, tokenized asset platforms, and settlement operators need to understand how RTGS synchronisation could connect central bank money with external asset ledgers and reduce settlement risk in digital markets.
Domestic real time payment systems are becoming exportable cross border infrastructure. Payment networks, banks, wallets, tourism merchants, and regulators are building direct QR payment links that reduce card dependence and make national payment rails usable outside their home markets.
Access to Canada’s payment infrastructure continues to widen beyond traditional banks and large financial institutions. Fintechs, payment providers, credit unions, foreign exchange firms, and digital finance companies are gaining a larger role in the systems and governance discussions that shape payment modernization.
Open banking is moving from one off payments into repeatable payment schemes with shared rules and commercial terms. Banks, PSPs, merchants, fintech platforms, and regulators should track whether recurring account to account payments become a real alternative to cards, direct debit, and closed wallet systems.
Card settlement is no longer limited to traditional banking hours or traditional settlement assets. Banks, acquirers, PSPs, stablecoin issuers, and fintech platforms should track how major payment networks use regulated stablecoins to support faster settlement, lower liquidity friction, and always on money movement.
Stablecoin remittances are moving from fintech experiments into established money transfer networks. Banks, PSPs, remittance firms, stablecoin issuers, and compliance teams should track how large networks use tokenized dollars to reduce settlement friction while staying inside regulated payment flows.
Pay by bank is becoming a practical payment rail strategy, not just a checkout concept. PSPs, banks, merchants, and fintech platforms should track how instant payment routing, risk controls, and settlement access shape competition against cards and traditional ACH flows.
Stablecoins are gaining traction in regulated payment flows, not just trading markets. Remittances remain one of the clearest real world use cases because settlement speed, foreign exchange costs, and cross border reach matter more than speculative activity. Canadian fintechs, PSPs, banks, and regulators should watch whether stablecoin based remittance models can scale while meeting compliance, safeguarding, and consumer protection requirements.
OpenPayd’s planned Nasdaq listing puts programmable money movement under public market scrutiny. PSPs, banks, stablecoin firms, embedded finance platforms, investors, and regulators should track how the listing exposes the economics, licensing footprint, transaction volume, and risk controls behind global payment infrastructure.
Crypto sanctions enforcement is moving deeper into exchange infrastructure and stablecoin flows. Exchanges, custodians, PSPs, blockchain analytics firms, and compliance teams should track how sanctions screening, stablecoin monitoring, and cross border counterparty controls become core operating requirements.
Technology policy is increasingly becoming infrastructure policy. As governments focus on AI capacity, cloud services, strategic data assets, semiconductor supply chains, and digital resilience, firms may face growing pressure to evaluate technology dependencies, procurement choices, hosting arrangements, and infrastructure risk. The result could be a more fragmented global technology environment shaped by competing sovereignty frameworks.
Consumer AI policy is moving toward practical controls for trust, consent and accountability. Banks, fintechs, AI firms, platforms and regulators should watch how user controls, complaint routes, audit trails and outcomes based duties apply when AI systems influence financial decisions or act for consumers.
The operating change is where AI work happens. If capable agents can run locally, more sensitive analysis, file handling, audio processing, and workflow automation can stay on device instead of moving through cloud APIs. That could change enterprise AI design, human oversight, privacy controls, and bot to bot workflows.
The United States is testing a lighter regulatory model for frontier AI that relies on voluntary participation, security evaluation, and industry cooperation. Financial institutions, fintechs, infrastructure providers, and AI developers should watch whether this approach accelerates deployment while maintaining confidence in systems that increasingly influence payments, capital markets, fraud controls, and critical infrastructure.
Revolut’s U.S. strategy shows why bank charters are becoming infrastructure plays for global fintechs. FDIC insured products, payment rail access, stablecoin services, and securities trading under one app could raise the competitive bar for sponsor bank dependent fintech models.
Stablecoin regulation is becoming a competitiveness question, not only a risk control exercise. Issuers, banks, PSPs, custodians, and policymakers should track whether the UK loosens its approach or keeps tougher safeguards that could limit domestic stablecoin scale.
Stablecoin supervision is becoming cross border supervision. Issuers, exchanges, custodians, payment firms, and compliance teams should expect more information sharing between regulators as stablecoin activity crosses jurisdictions, banking systems, and payment networks.
The word of the week is 'control'. Banks, payment networks, fintechs, custodians, stablecoin issuers, and AI providers are competing closer to the infrastructure layer, where settlement, custody, compliance, data, and distribution decisions get made. Which rails, licenses, partners, and operating models create durable access before the next layer of financial infrastructure gets locked in?
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016