




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 8, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization
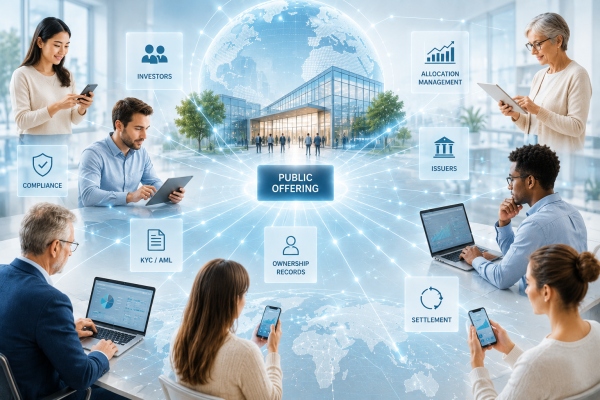
On June 7, 2026, Bybit launched IPO Express, a platform that gives eligible users access to tokenized IPO allocations starting with SpaceX. The launch arrives as SpaceX prepares for a public offering expected to value the company at approximately $1.75 trillion, making it potentially one of the largest IPOs ever. While the SpaceX name grabs attention, the bigger story is what this says about investor access, capital formation, and the growing role of digital infrastructure in public markets.
While the SpaceX name grabs attention, the bigger story is how firms are competing to expand investor access and improve IPO distribution.
Traditional IPO allocations typically flow through investment banks, brokerage firms, institutional investors, and private banking networks. Retail investors often participate only after public trading begins.
Bybit's model broadens access by allowing eligible users to subscribe through exchange infrastructure before trading starts. Investors can receive allocations and subsequently trade tokenized exposure through the platform.
The model combines several functions that have historically operated through separate systems, including investor onboarding, allocation management, compliance, custody, ownership records, and trading. Companies are now competing to modernize how investors access public offerings.
Much of the discussion around how tokenization is changing markets has focused on stocks, bonds, funds, real estate, and other assets after issuance. IPO Express focuses on an earlier stage of the investment lifecycle.
For decades, financial innovation concentrated around trading efficiency, lower transaction costs, and faster settlement. Tokenized IPO access targets a different challenge related to who gets access to investment opportunities in the first place.
Investor verification and eligibility checks now matter as much as trading access. So do allocation rules, ownership records, compliance controls, and settlement. Platforms that combine these functions in one clean workflow may earn an advantage as capital markets become more digital.
Canada has already seen similar efforts to expand investor participation through equity crowdfunding, online exempt market platforms, private market technology, and digital investment platforms.
Canada already has a live comparison point. Wealthsimple’s IPO Access for Canadian retail investors broadens access through a brokerage account, while Bybit’s IPO Express adds a tokenized layer around allocation and trading. Both are aiming to solve the same pressure in capital markets: retail investors want earlier access, cleaner digital onboarding, and a fairer shot at high demand offerings.
NCFA’s Who Gets Capital As Funding Channels Multiply? asks the same core question for Canadian markets. More channels don't automatically create better access for every founder or investor.
Tokenized IPO access brings the same access and onboarding pressure to public exchange listings. For Canada, the practical question is whether regulated platforms can use digital infrastructure to make capital raising easier without weakening disclosure, custody, suitability, or investor protection. That question fits NCFA’s financial innovation market infrastructure research, where access to capital, tokenization, compliance, and investor trust now overlap.
If retail investors can access high demand offerings through faster digital channels elsewhere, how long can domestic platforms rely on slower, relationship driven distribution models?
The competitive advantage may no longer come from who controls the allocation. It may come from who makes access easiest while still meeting regulatory requirements.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 8, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization
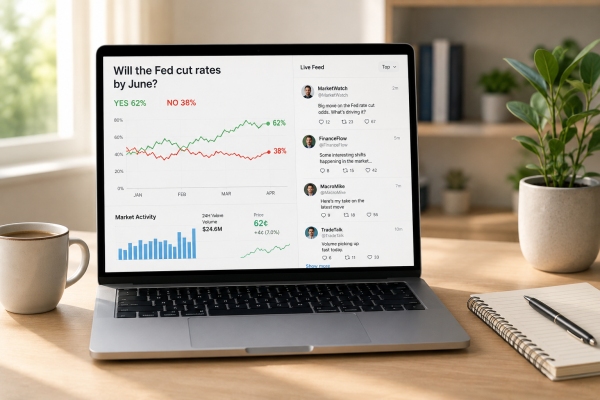
On June 5, 2026, Politico published an investigation into Polymarket's influencer marketing program. The report found that Polymarket chief marketing officer Matthew Modabber allegedly used a personal PayPal account to send at least $350,000 to content creators between January 2025 and February 2026. Politico's review identified over 490 social media posts promoting Polymarket that allegedly didn't clearly disclose paid relationships.
The investigation paints a picture far larger than a disclosure dispute. It's a rare look into how prediction markets are building distribution, visibility, and cultural relevance while simultaneously becoming one of the most discussed forecasting platforms in politics, sports, current events, and financial markets.
At least 20 creators identified by Politico promoted Polymarket after receiving payments. The report also found more than $2.5 million in transfers from the account to over 800 recipients during the period reviewed. Several influencers allegedly framed Polymarket odds as breaking news or authoritative indicators of future events. One creator told Politico that the company provided suggested post copy and encouraged promotion of specific markets.
The story reveals something many people inside fintech have quietly observed for years. Prediction markets are no longer simply markets. They are becoming media businesses.
Traditional exchanges compete for liquidity. Prediction markets increasingly compete for attention.
Polymarket's growth coincided with the 2024 U.S. election cycle, where billions of dollars flowed through election related contracts. Politico's reporting shows that influencer distribution became part of that growth strategy. The objective was not only attracting traders. It was turning Polymarket into a source people referenced when discussing politics, government decisions, sports outcomes, and breaking events.
The strategy appears to have worked. Today, prediction market odds regularly appear in mainstream media coverage. News organizations cite them. Social media users share screenshots of them. Investors discuss them. Politicians reference them. The market itself increasingly becomes part of the story.
It's a new category that's somewhere between financial infrastructure, media distribution, forecasting, and social networks.
The obvious asset is trading volume. The less obvious asset is trust. Many of the influencers highlighted in Politico's investigation promoted Polymarket as exceptionally accurate. Some described the platform as a superior forecasting mechanism compared to polling. Others highlighted successful market predictions as evidence of credibility.
This creates an unusual challenge. Prediction markets derive value from the perception that they aggregate independent information better than traditional alternatives. If users begin questioning how information reaches the market, who amplifies market narratives, or whether promotion and prediction are becoming intertwined, trust becomes harder to maintain.
The issue isn't whether influencer marketing is permitted. Many fintech companies use creators, affiliates, newsletters, podcasts, and social media personalities. The issue is whether users can clearly distinguish between market intelligence and paid amplification.
The most important opportunity may not be another prediction market. It's infrastructure that helps users understand how market information forms, spreads, and gains credibility.
As prediction markets, AI systems, social media platforms, and financial products become more connected, users need better ways to answer practical questions.
The next generation of prediction market innovation opportunities may come from building verification, disclosure, provenance, surveillance, and transparency tools around these markets.
These capabilities are still early. As prediction markets expand into politics, sports, finance, and public policy, demand for trust infrastructure should grow with them.
The Politico investigation focuses on influencer payments, disclosure practices, and marketing tactics, but the larger takeaway is that prediction markets are evolving beyond trading venues. They're becoming information platforms. That evolution creates opportunity, but it also creates responsibility. Today, Reuters posted about predication markets facing rising scrutiny over insider trading controls, reinforcing that these markets need trust infrastructure around promotion, surveillance, suspicious trading, and market transparency.
Markets that increasingly influence public understanding of events will face greater scrutiny over how information enters the system, how narratives spread, and how trust is earned. The next competitive opportunity may be proving that market intelligence can be trusted.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 30, 2026 | NCFA Fintech Whisperer | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data, Regulation and Policy, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026).
Tokenized bonds are moving from pilots into market structure work. Issuers, dealers, custodians, infrastructure providers, and regulators need practical answers on issuance, settlement, custody, disclosure, and secondary liquidity before tokenized fixed income can scale.
The value of cross chain infrastructure comes down to whether developers can route liquidity without exposing users to bridge complexity. The $230M private beta gives 0x early usage evidence, but the larger test is reliability across payments, RWAs, trading, and agent workflows when volumes move beyond controlled integrations.
Stablecoin licensing is becoming a competitive infrastructure tool for financial centres. Issuers, banks, PSPs, custodians, and regulators should track which jurisdictions turn stablecoin rules into live market access rather than policy design alone.
Tokenized money market funds are becoming part of institutional onchain liquidity infrastructure. Asset managers, custodians, PSPs, stablecoin issuers, and treasury teams should track how stablecoins connect with regulated fund products, redemption workflows, and stablecoin payment infrastructure.
Institutional DeFi is shifting toward custody controlled access models. Asset managers, custodians, exchanges, advisers, and compliance teams should track whether qualified custody plus curated onchain strategies becomes the operating model that brings DeFi exposure into regulated portfolios.
The useful signal is not simply another crypto loan product. It is committed buyer capital behind crypto backed credit, which can make the product more repeatable. The key risks remain collateral volatility, liquidation design, borrower suitability, and whether digital asset wealth can support credit access without turning into hidden leverage.
Crypto collateral can help asset rich borrowers avoid selling Bitcoin or USDC, but housing finance brings stricter expectations around suitability, custody, volatility buffers, and borrower protection. The product will need to prove it expands access without importing crypto market risk into mortgage underwriting.
Large banks are moving from stablecoin observation into direct tokenized money infrastructure. Treasury teams, payment providers, fintechs, custodians, and infrastructure operators now need to track whether commercial bank money becomes a regulated settlement layer for high value payments, liquidity management, and cross border transactions.
Western Union’s stablecoin entering a major crypto exchange channel adds another proof point for stablecoins becoming payment infrastructure. PSPs, exchanges, banks, remittance firms, and compliance teams should track how regulated issuers, fiat channels, and global payout networks connect. This adds a distribution proof point for regulated stablecoins. Western Union brings the remittance brand and global currency footprint, while Bybit brings crypto exchange access. The open question is whether USDPT becomes a settlement asset customers actually use, or another branded stablecoin competing for scarce transaction depth.
Central bank money settlement is being designed for programmable markets. Banks, FMIs, tokenized asset platforms, and settlement operators need to understand how RTGS synchronisation could connect central bank money with external asset ledgers and reduce settlement risk in digital markets.
Domestic real time payment systems are becoming exportable cross border infrastructure. Payment networks, banks, wallets, tourism merchants, and regulators are building direct QR payment links that reduce card dependence and make national payment rails usable outside their home markets.
Access to Canada’s payment infrastructure continues to widen beyond traditional banks and large financial institutions. Fintechs, payment providers, credit unions, foreign exchange firms, and digital finance companies are gaining a larger role in the systems and governance discussions that shape payment modernization.
Open banking is moving from one off payments into repeatable payment schemes with shared rules and commercial terms. Banks, PSPs, merchants, fintech platforms, and regulators should track whether recurring account to account payments become a real alternative to cards, direct debit, and closed wallet systems.
Card settlement is no longer limited to traditional banking hours or traditional settlement assets. Banks, acquirers, PSPs, stablecoin issuers, and fintech platforms should track how major payment networks use regulated stablecoins to support faster settlement, lower liquidity friction, and always on money movement.
Stablecoin remittances are moving from fintech experiments into established money transfer networks. Banks, PSPs, remittance firms, stablecoin issuers, and compliance teams should track how large networks use tokenized dollars to reduce settlement friction while staying inside regulated payment flows.
Pay by bank is becoming a practical payment rail strategy, not just a checkout concept. PSPs, banks, merchants, and fintech platforms should track how instant payment routing, risk controls, and settlement access shape competition against cards and traditional ACH flows.
Stablecoins are gaining traction in regulated payment flows, not just trading markets. Remittances remain one of the clearest real world use cases because settlement speed, foreign exchange costs, and cross border reach matter more than speculative activity. Canadian fintechs, PSPs, banks, and regulators should watch whether stablecoin based remittance models can scale while meeting compliance, safeguarding, and consumer protection requirements.
OpenPayd’s planned Nasdaq listing puts programmable money movement under public market scrutiny. PSPs, banks, stablecoin firms, embedded finance platforms, investors, and regulators should track how the listing exposes the economics, licensing footprint, transaction volume, and risk controls behind global payment infrastructure.
Crypto sanctions enforcement is moving deeper into exchange infrastructure and stablecoin flows. Exchanges, custodians, PSPs, blockchain analytics firms, and compliance teams should track how sanctions screening, stablecoin monitoring, and cross border counterparty controls become core operating requirements.
Technology policy is increasingly becoming infrastructure policy. As governments focus on AI capacity, cloud services, strategic data assets, semiconductor supply chains, and digital resilience, firms may face growing pressure to evaluate technology dependencies, procurement choices, hosting arrangements, and infrastructure risk. The result could be a more fragmented global technology environment shaped by competing sovereignty frameworks.
Consumer AI policy is moving toward practical controls for trust, consent and accountability. Banks, fintechs, AI firms, platforms and regulators should watch how user controls, complaint routes, audit trails and outcomes based duties apply when AI systems influence financial decisions or act for consumers.
The operating change is where AI work happens. If capable agents can run locally, more sensitive analysis, file handling, audio processing, and workflow automation can stay on device instead of moving through cloud APIs. That could change enterprise AI design, human oversight, privacy controls, and bot to bot workflows.
The United States is testing a lighter regulatory model for frontier AI that relies on voluntary participation, security evaluation, and industry cooperation. Financial institutions, fintechs, infrastructure providers, and AI developers should watch whether this approach accelerates deployment while maintaining confidence in systems that increasingly influence payments, capital markets, fraud controls, and critical infrastructure.
Revolut’s U.S. strategy shows why bank charters are becoming infrastructure plays for global fintechs. FDIC insured products, payment rail access, stablecoin services, and securities trading under one app could raise the competitive bar for sponsor bank dependent fintech models.
Stablecoin regulation is becoming a competitiveness question, not only a risk control exercise. Issuers, banks, PSPs, custodians, and policymakers should track whether the UK loosens its approach or keeps tougher safeguards that could limit domestic stablecoin scale.
Stablecoin supervision is becoming cross border supervision. Issuers, exchanges, custodians, payment firms, and compliance teams should expect more information sharing between regulators as stablecoin activity crosses jurisdictions, banking systems, and payment networks.
The word of the week is 'control'. Banks, payment networks, fintechs, custodians, stablecoin issuers, and AI providers are competing closer to the infrastructure layer, where settlement, custody, compliance, data, and distribution decisions get made. Which rails, licenses, partners, and operating models create durable access before the next layer of financial infrastructure gets locked in?
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 5, 2026 | NCFA Resource | Financial Innovation
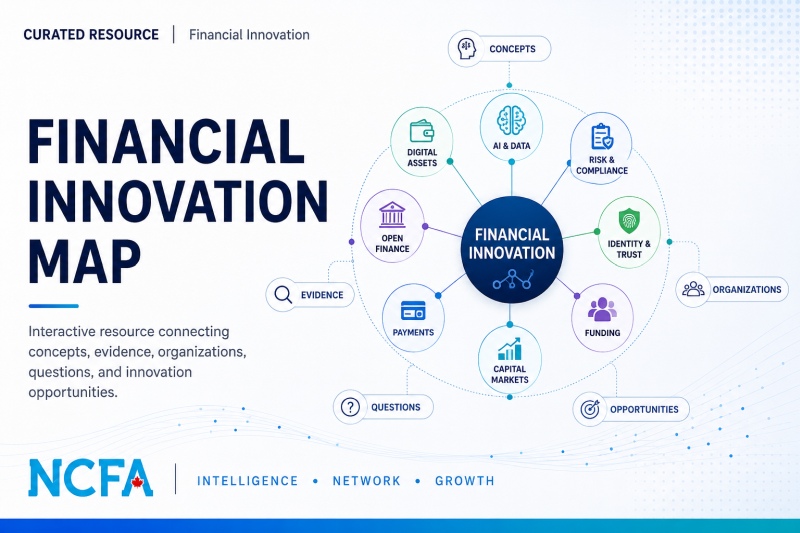
NCFA launched a Financial Innovation Map on June 5, 2026, as a practical resource for founders, investors, financial institutions, policymakers, researchers, and ecosystem builders. The map connects financial innovation concepts, use cases, featured organizations, evidence, questions, and innovation opportunities across fintech, funding, AI, digital assets, open finance, payments, capital markets, compliance, cybersecurity, and trust.
The Financial Innovation Map helps users move from concept awareness to opportunity discovery. Users can select a category, choose a concept, review sample use cases, scan featured organizations, explore innovation questions, and review resources tied to practical financial innovation activity.
The opportunity cards are practical and will continue to evolve. They show where adjacent concepts could combine into practical opportunities, supported by early, growing, or strong evidence. This helps users think beyond definitions and ask where an idea may create real value.
The need for better financial innovation intelligence is global. The BIS Innovation Hub works with central banks on technology trends that affect the global financial system, including digital finance, payments, market infrastructure, regtech, suptech, and financial stability. NCFA’s map gives Canada’s innovation ecosystem a practical way to explore many of the same themes from a founder, investor, policy, and market building lens.
Founders can use the map to test ideas, find adjacent concepts, and sharpen market theses. Investors can scan emerging areas before they become obvious sectors. Financial institutions can explore where new technology may reduce friction, improve workflows, or open new product opportunities.
Regulators, policymakers, researchers, and ecosystem builders can use the map to understand how technologies, rules, organizations, and unanswered questions connect across Canada and global financial innovation markets.
The strength of the Financial Innovation Map is structure. It brings concepts, organizations, resources, questions, and opportunity cards into one place so users can explore financial innovation with more context and less noise.
The first release is intentionally focused. Some concepts have more evidence and opportunity cards than others. That's by design. Opportunities are not added to meet a fixed count. They are added when there is enough evidence, friction, thesis strength, funding interest, or market activity to support inclusion.
The map isn't investment advice, legal advice, or a forecast. It's a curated intelligence resource that will improve as new evidence, resources, organizations, and opportunities are added. Stay tuned for future iterations.
Start with the Financial Innovation Map and explore the categories most relevant to your work.
For related NCFA coverage, see how AI agents, wallets, and financial identity are starting to connect, how agentic AI in banking is moving into practical workflows, and how tokenized infrastructure is changing market operations.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 5, 2026 | NCFA Insight | Artificial Intelligence And Data
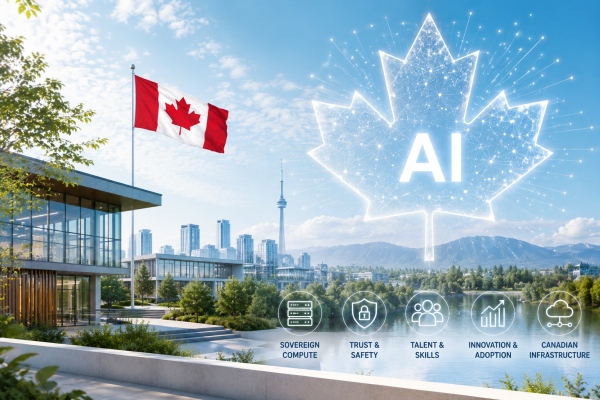
On June 4, 2026, Prime Minister Mark Carney launched AI for All, Canada’s new national artificial intelligence strategy. It targets $200 billion in additional economic growth, 250,000 new AI related jobs over five years, and a rise in AI adoption from just over 12% today to 60% by 2034.
The strategy also aims to create up to 90,000 AI related jobs and work placements for young Canadians. It supports AI skills, trust and safety, sovereign compute and cloud infrastructure, and Canadian company scale up. Canada’s AI challenge is no longer research. It is deployment.
Canada helped build the modern AI era. The country has three National AI Institutes, Vector Institute in Toronto, Mila in Montréal, and Amii in Edmonton. It also has a long record of public investment in AI research and talent.
Yet the harder problem is in the AI economy. The federal government says Canada remains among the slowest countries to adopt AI at scale. Only slightly more than 12% of Canadian businesses use AI today. AI for All sets a target of 60% adoption by 2034.
Canada has AI credibility, but it lacks broad deployment. Research output can attract talent and capital. Still, productivity gains only show up when companies redesign workflows, train workers, improve operations, and build commercial products around the technology.
This connects directly to Canada’s AI adoption gap. The next phase depends less on model breakthroughs and more on whether firms can put AI to work across finance, healthcare, manufacturing, energy, agriculture, transportation, and public services.
AI for All is a strategy with announced investments, but it’s not positioned as one simple funding package. It sets out an implementation plan built around trust, opportunity, and sovereignty.
The plan includes stronger privacy and online safety rules, AI transparency measures, expanded AI Safety Institute capabilities, entry level AI training for all Canadians, trusted AI agents for post secondary students, SME adoption support, and an AI Missions Program that starts with health.
Canada needs more firms, workers, and public institutions using AI in ways that raise productivity, improve services, and create Canadian owned economic value.
For fintech leaders, the strategy reads like an implementation roadmap. AI adoption will depend on infrastructure, skills, procurement, privacy rules, data governance, and trust. These are the same issues affecting open finance, digital identity, fraud prevention, payments modernization, and smart data infrastructure.
Financial services may offer one of the clearest adoption tests. Banks, credit unions, insurers, wealth management firms, payment companies, and fintechs already run data heavy businesses. They also rely on repeatable workflows, compliance controls, customer records, and risk systems.
AI can support fintech use cases from fraud detection and credit assessment to investment research and operational risk monitoring. That creates an opening for Canadian regtech firms, AI infrastructure companies, payment providers, lending platforms, and wealthtechs that can help institutions move from pilots to production.
The same issue appears in AI and non traditional data in financial services. Financial institutions can use AI to improve decisions, but they need governance that protects consumers and supports regulatory trust.
The strategy pushes AI into national competitiveness policy. It names compute, cloud, connectivity, data, and talent as foundations of sovereign Canadian AI.
At the company level, that infrastructure question reaches down to practical decisions about where applications and workloads run. A VDS server / virtual dedicated server can provide dedicated virtual computing resources for businesses that need greater control over hosting configurations, performance and resource allocation.
Canada’s national AI strategy also says the federal government will continue delivering more than $2 billion in existing investments in Canadian AI compute capacity, including through the AI Compute Challenge. This isn't a single new $2 billion package in the Prime Minister’s release. It's an existing compute investment stream tied to Canada’s wider sovereignty strategy.
It also connects directly to Canada’s recent debate over cloud concentration and AI sovereignty. Compute capacity and cloud control can determine whether domestic firms can scale without deeper platform dependence.
Countries don’t capture AI value only by producing researchers. They capture value when companies scale, retain key talent, own intellectual property, and sell into global markets from a domestic base.
For Canadian fintechs and investors, sovereign AI infrastructure affects who controls data, how firms access compute, how procurement supports domestic companies, and whether Canadian AI companies can scale before larger foreign markets pull them away.
AI for All sets ambitious targets. The proof will come from adoption, scale, productivity, and trust.
Can Canadian business adoption rise from just over 12% to 60% by 2034? Can Canadian AI firms scale while keeping meaningful operations, talent, and intellectual property in Canada? Can regulated sectors deploy AI with enough transparency and accountability to earn public trust?
Canada already proved that it can build AI research strength. Yet it hasn’t proved that it can turn that strength into widespread productivity gains and globally scaled companies at the same pace as larger markets.
For NCFA members, the opportunity lies in execution. Founders can build AI tools that solve costly financial sector problems. Investors can look for firms with real workflow adoption, not only technical claims. Policymakers can reduce friction where regulation, procurement, data access, and capital formation slow responsible deployment.
AI for All is a clear shift in Canada’s AI policy. Ottawa now looks at AI as an adoption, productivity, sovereignty, and scale up challenge, not just a research agenda. Canada’s AI advantage will come from helping more Canadian firms use AI, sell AI, govern AI, and keep more of the value created by AI in Canada.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
June 4, 2026 | NCFA Market Activity | Capital Markets And Funding

On June 1, 2026, FrontFundr launched the Back The Next Canadian Startup Challenge, a national initiative inviting investors, founders, advisors, partners, supporters, and startup operators to nominate Canadian companies ready to raise capital.
The challenge targets founders building innovative or high growth businesses with early traction, strong market potential, and plans to raise within the next 3 to 6 months. Companies can apply directly or be nominated by someone in the ecosystem. All participating companies must still submit an application.
Applications require a pitch deck, an overview of the business and fundraising goals, and an explanation of why the company fits community investment. Founders can also submit an optional 45 to 60 second video explaining their story, mission, and motivation to raise on FrontFundr.
FrontFundr will review applications based on business innovation, market opportunity, founder strength, execution capability, readiness to raise, and alignment with community investing. Nominations and applications run from June 1 to 30. Shortlisted companies advance to a live pitch competition in early July, where the top 3 to 5 companies will deliver a 5 minute pitch followed by 5 minutes of Q&A.
One selected company receives a free opportunity to launch a FrontFundr campaign and raise from its own supporters and FrontFundr’s investor community. FrontFundr values the package at $13,000. It includes a free campaign listing, due diligence and campaign preparation, and complimentary documentation drafting. Standard closing costs and trade fees still apply.
Finalists and high potential applicants may also continue through an accelerated pathway toward launching a FrontFundr campaign, based on fit, readiness, and alignment with community investing.
Referrers may earn $1,250 when a referred company signs and launches a campaign. Eligible companies must be new to FrontFundr, Canadian, raise at least $250,000, and launch within 6 months of introduction. Rewards can be paid as cash or platform credit upon milestone completion.
FrontFundr says companies on its platform have raised more than $367M across more than 300 campaigns, supported by more than 73,000 investors across Canada.
The winner reduces upfront campaign costs and receives support with preparation, documentation, and platform launch. Finalists may still gain visibility and a faster review process.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |

Last Updated: June 4, 2026
Status: Strengthening
Organizations: OSFI, CIRO, SEC, FSB, CVCA, TSXV, TMX Group, Upstart, goeasy, FrontFundr
The answer is not simply yes or no. Capital is more available in some places and harder to reach in others. Funding channels are multiplying, but capital still flows toward companies that fit the channel, prove the risk, and give investors a clear reason to act.
Public markets are improving from a weak period, but access still depends on timing, disclosure readiness, and investor demand. Recent work on the CSA review of the EMD selling groups exemption and capital markets research through OSC research grants for Ontario capital markets shows that market access remains an active policy issue.
Crowdfunding adds another route. Reg CF’s 10 year record, record Canadian equity crowdfunding activity, and public market challenges and equity crowdfunding capital point to a wider funding stack. These channels still depend on trust, disclosure, visible traction, and investor communication.
Canada’s $750M early growth stage funding envelope reinforces the same point. The policy debate is not only about adding capital. It is about where the financing gap hurts most: pre seed, seed, Series B, growth, or later stage scale up capital.
Capital stack fit is now harder to ignore. Founders and fintechs may combine equity, debt, crowdfunding, private credit, public markets, and lending partnerships, but each channel demands different proof, timing, economics, and risk controls.
Strategic Takeaway
Capital channels are multiplying, but access is not becoming automatic. Founders and fintechs need to know which type of capital they fit and what proof that capital provider needs before money moves.
Click each item to expand
CVCA reported that Q1 2026 saw CAD $936.3M invested across 104 venture capital transactions, compared with 178 transactions and $3.97B in Q4 2025.
Crowdfunding evidence adds an important non bank and non VC funding channel to the capital access question.
TSX Venture Exchange removed its Sponsor requirement, effective immediately.
Upstart announced a $1B forward flow agreement with Eltura Ventures and Aperture Investors.
OSFI reduced capital requirements for certain unrated domestic infrastructure debt held by federally regulated property and casualty insurers.
Click each item to expand
The Financial Stability Board estimated private credit at $1.5T to $2.0T at the end of 2024 and warned that complexity, leverage, and interconnectedness could amplify stress.
goeasy reported a difficult Q4 2025 tied to LendCare credit performance.
CIRO finalized amendments related to fully paid securities lending and financing arrangements.
The SEC Division of Corporation Finance said EDGAR would accept filings during a shutdown, but staff would not be able to declare registration statements effective or qualify Form 1 A offering statements.
The Federal Reserve, FDIC, and OCC requested comment on three proposals to modernize the regulatory capital framework for banks of all sizes.
Do you agree the evidence is strengthening?
Click Agree or Disagree. Your vote is recorded anonymously and aggregate totals tracked.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016