




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 15, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026).
Tokenized funds need reliable exits before more institutions treat them as usable collateral or treasury assets. Asset managers, custodians, exchanges, treasury teams, and tokenization platforms should watch how redemption speed, stablecoin liquidity, and access controls become core requirements for institutional tokenized finance.
Community and regional banks are starting to package stablecoins, tokenized deposits, and digital asset lending inside bank led distribution. Banks, fintechs, core providers, custodians, and compliance teams should watch how association channels turn digital asset access into a practical banking product instead of a standalone crypto service.
Fintechs and FIs now compete on governed AI use in underwriting, fraud, servicing, and cost discipline, while security and model risk stay on the board agenda.
Voice is becoming searchable compliance evidence across more markets and languages. Banks, dealers, wealth firms, fintechs, and regtech vendors need stronger controls for recorded calls, multilingual surveillance, off channel risk, and investigation workflows.
Fraud controls are becoming more coordinated across regulators, law enforcement, platforms, and financial institutions. Banks, fintechs, PSPs, regtech vendors, and digital asset firms should expect higher expectations around intelligence sharing, scam detection, AI oversight, and real time monitoring.
Agent driven commerce needs payment controls that can handle authorization, settlement, spending permissions, dispute handling, and compliance review without slowing automated workflows. Stablecoins are increasingly being positioned as the settlement layer for machine initiated transactions.
Agent payments now need privacy, settlement, authorization, and audit controls that work together. Payment firms, wallet providers, stablecoin issuers, AI agent platforms, and compliance teams should track how machine initiated transactions create new requirements for identity, transaction monitoring, and dispute handling.
Canadian banks, credit unions, fintechs, and infrastructure providers face growing pressure to modernize customer onboarding, payments, servicing, and digital account experiences at lower operating cost. Large coordinated modernization programs can influence vendor standards, integration expectations, and competitive timing across the Canadian banking market.
Direct PSP access to Interac e Transfer gives Canadian fintechs a stronger role inside everyday money movement. Banks, PSPs, payment firms, and compliance teams should track how direct participation changes onboarding, fraud controls, settlement readiness, and product competition across Canadian payment services. Koho is a a payment service provider member of Payments Canada with direct access to payment clearing and settlement.
Digital asset lending keeps adopting operational standards from traditional securities finance. Exchanges, custodians, prime brokers, lenders, treasury teams, and compliance groups should watch how collateral controls, settlement discipline, and institutional workflow expectations become standard requirements across crypto lending markets.
Tokenized settlement is entering exchange rulebooks, not just pilot decks. Exchanges, broker dealers, custodians, transfer agents, market data teams, and compliance teams need to prepare for tokenized securities that still trade under national market system rules, surveillance, reporting, T+1 settlement, and existing investor protections.
Asset managers, exchanges, custodians, brokers, and treasury teams increasingly need infrastructure that supports tokenized funds, collateral, and yield products inside institutional operating environments. Tokenized finance is becoming part of mainstream capital markets strategy rather than a separate digital asset experiment.
Tokenization now reaches core market infrastructure, not just crypto trading activity. Exchanges, custodians, transfer agents, dealers, issuers, and infrastructure providers need operating models that support tokenized securities inside existing settlement, governance, reporting, and post trade systems.
Broker dealers, RIAs, custodians, wealth platforms, and compliance teams now have another regulated route to offer digital assets inside familiar securities account structures. That raises the bar for firms still treating crypto access as a separate product channel instead of a brokerage, custody, and supervision question.
MiCA implementation now becomes a licensing, supervision, and market access issue for crypto firms operating in Poland. Exchanges, custodians, stablecoin firms, brokers, and compliance teams should watch how national supervisors apply enforcement powers, authorization standards, and transition rules as Europe’s crypto framework enters active supervision.
Crypto exchanges, custodians, stablecoin issuers, tokenization firms, banks, compliance vendors, and capital markets platforms should track this markup closely. The bill text moves U.S. digital asset policy from broad debate into statutory architecture, with direct implications for token classification, intermediary registration, custody, disclosure, DeFi obligations, and cross border market access.
The common thread is operational readiness. Firms increasingly compete on whether they can support governed AI, tokenized assets, stablecoin settlement, and real time compliance inside production systems rather than separate innovation programs. That pressure now reaches broker dealers, PSPs, banks, treasury teams, exchanges, and compliance groups at the same time. Founders, operators, and investors tracking these changes may also want to review coverage on tokenized market infrastructure, AI agents entering governed financial workflows, and agent driven commerce and payments as these themes continue to converge across fintech markets.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 15, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, Capital Markets And Funding
On May 12, 2026, Ottawa announced $66 million for 44 Canadian AI projects through the AI Compute Access Fund, part of Canada’s $300 million Sovereign AI Compute Strategy. Evan Solomon, Minister of Artificial Intelligence and Digital Innovation, announced the funding at Web Summit Vancouver.
Compute has become a hard cost of AI growth. If an AI company wants growth, even if they have strong talent, a useful model, and early customers, without affordable processing power, it still can’t train, test, or serve the product at scale. So in a sense, compute access (or lack of) is now part of Canada’s productivity and capital formation problem.
The announcement says the funded projects cover health care, energy, manufacturing, agriculture, finance, natural resources, and transportation. Use cases are across a range of sectors, such as wildfire detection, public transit, drug discovery, agriculture, financial services, and business tools.
Evan Solomon, Minister of Artificial Intelligence and Digital Innovation and Minister responsible for the Federal Economic Development Agency for Southern Ontario
“AI is not just a technology of the future. It is already helping Canadian companies solve real problems, improve services, create products and compete globally. But to build with AI, companies need access to compute power. Through the AI Compute Access Fund, we are helping Canadian businesses get the processing power they need to scale, create jobs, transform industries and keep more of the value they create here in Canada.”
The AI Compute Access Fund program guide says eligible project costs must range from $100,000 to $5 million. Projects can run for up to three years and must end no later than March 31, 2028. Important to note that this amount of funding can help companies overcome smaller experiments, but it doesn't solve the full scale problem.
The Bank of Canada’s recent AI productivity speech shows the size of the race. Top U.S. technology firms spent roughly US$200 billion on AI related investment in 2024. That doubled to about US$400 billion in 2025. Canada cannot match that dollar for dollar. So it's moved quickly to fund firms that can turn compute into commercial products, owned IP, and exportable capability.
For fintechs and financial institutions, compute connects directly to governed AI workflows in finance. The value is output that teams can review, explain, and control.
Canada also needs more domestic capacity. Clean power, secure data centres, competitive cloud options, and private capital must all converge to support AI growth. Compute support shouldn't only be given to the best funded firms. It should also reach applied AI builders, regional companies, regulated sector use cases, and firms solving productivity problems that don't always attract venture capital.
Can Canada turn compute funding into scaled AI companies, or will the largest gains still flow to firms that control the platforms, data centres, and capital behind the AI economy?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 15, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Payments Rails And Market Infrastructure, Regulation And Policy
On May 7, 2026, the Bank of Canada published staff research on global cryptocurrency flows. The paper looks at why crypto moves across borders, using Bitcoin flow data across up to 162 countries and testing whether key findings also appear across major stablecoins.
It's a practical resource for fintech teams trying to understand where digital assets connect to remittances, payment friction, macro stress, capital controls, sanctions, and financial system gaps.
The paper uses Chainalysis data to study cross border crypto flows from 2020 Q3 to 2023 Q3. The authors focus on Bitcoin first, then extend the analysis to USDT, USDC, BUSD, and DAI. That makes the research useful for teams that need to separate market noise from real cross border usage patterns.
Crypto flows don't always behave like traditional capital flows. The paper finds that crypto activity can rise when macro conditions weaken, when financial systems work poorly, or when people need cheaper and faster ways to send money across borders.
Payment firms, remittance providers, banks, stablecoin companies, and compliance teams should take note. Crypto rails often gain relevance where traditional rails feel costly, slow, restricted, or unreliable.
The paper also helps explain why stablecoins are becoming more prominent in payments and treasury conversations. If stablecoin flows follow similar cross border patterns to Bitcoin in key areas, policymakers and market builders can't treat them as only crypto assets. They need to assess them as financial infrastructure.
For Canadian fintechs, if users, businesses, and institutions adopt digital rails for real cross border needs, firms need to know where those rails improve service, where they create risk, and where regulators may focus next.
This resource is useful for fintech founders, payment companies, remittance providers, stablecoin infrastructure firms, crypto platforms, banks, AML teams, policy analysts, market infrastructure providers, and investors tracking financial system modernization.
It's especially relevant for teams working on cross border settlement, digital wallets, treasury tools, programmable payments, blockchain analytics, custody, transaction monitoring, and compliance operations.
The strength of this paper is scope. It compares crypto flows across a large country sample and tests several possible drivers instead of relying on one simple adoption story. The authors look at macro conditions, financial system quality, remittances, institutional quality, capital controls, and sanctions.
The paper also avoids a common trap. It doesn't treat all crypto activity as speculation. It shows how payments, remittances, and financial stress can help explain real cross border usage.
The limit is data construction. Cross border crypto flow analysis still depends on attribution methods, exchange activity, web traffic estimates, and assumptions about where users are located. The authors discuss those limits clearly. The paper is also Bank of Canada staff research, not an official Bank of Canada policy position.
For fintech teams, the best use is practical benchmarking. Use it to understand why crypto rails gain traction, where stablecoins may keep growing, and which risks regulators are likely to monitor more closely.
Bank of Canada Staff Working Paper 2026-15 (primary research paper on global cryptocurrency flows)
Patterns And Determinants Of Global Cryptocurrency Flows PDF (full paper with methodology, data, and empirical results)
BIS Project Atlas (global work on mapping crypto and DeFi activity)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 15, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, SME Finance And Business Banking, Capital Markets And Funding
On May 14, 2026, Synthetic raised USD $10 million in seed funding led by Khosla Ventures to build autonomous AI bookkeeping for software startups. Basis Set Ventures also participated. Operator investors include Shopify CEO Tobi Lütke, Opendoor CEO Kaz Nejatian, Bridge co founder Zach Abrams, Accrual CEO Cosmin Nicolaescu, and Figure CEO Michael Tannenbaum.
Synthetic is aiming to deliver accrual basis books without human bookkeepers or accountants. The system connects to a customer’s banks, payroll, billing systems, and inboxes, then asks clarifying questions when it needs more information. The output promised is a clean set of books that a tax preparer can use.
Synthetic says pricing will start at USD $49 per month, about a quarter of the cost of a human staffed service. The company is starting with software, SaaS, and AI businesses because their accounting workflows are narrower and easier to model than the full small business market. Autonomous bookkeeping will only work if the system understands the business and sector well enough to avoid a range of potential errors, both simple and complex.
Ian Crosby, Founder and CEO, Synthetic:
“I'm not sure if it's yet technologically possible to make this work,”
That quote is perhaps one of the most interesting parts of the announcement. Crosby isn't selling certainty, but he's calling out and going after a hard problem. AI is still unreliable, and no founder wants books that look clean but are wrong. In accounting, a small error can affect taxes, financing, board reporting, future planning, and investor trust.
Synthetic is trying to solve that by narrowing the customer type and building around quality control. The company says the team is iterating on a prototype with early design customers. The firm hasn't disclosed revenue, customers, launch timing, error rates, or benchmark results as of yet.
Bookkeeping touches sensitive financial data such as banking, billing, and payroll. If AI can handle that work with enough accuracy, it could cut cost for early startups and reduce one of the most common back office bottlenecks for founders.
Jon Chu, Khosla Ventures:
“This one’s quite simple. You have a large, valuable problem that will inevitably be solved by AI. A founder who’s spent multiple decades working on the problem with near perfect founder market fit. And resilience and grit that’s been forged through multiple founding experiences and scale ups at companies like Shopify and Mercury,”
While Synthetic is headquartered in San Francisco, the Canadian angle is three time founder (ie. Bench and Teal) Ian Crosby. Bench was a Vancouver built bookkeeping company that became one of North America’s best known small business accounting platforms before it later shutdown and was acquired.
So why not base the company in Canada? It's a competitiveness question for Canada. Canadian founders keep showing up in high value AI and fintech infrastructure deals, but company formation, lead capital, senior hiring, and headquarters often land in the United States. If Canada wants the next generation of AI finance companies to scale here, it needs more than talent. It needs lead capital, customers, technical density, and a culture that lets ambitious teams move fast.
This also connects to Canada’s productivity and competitiveness challenge. AI can reduce manual work, but the economic value goes to the companies that own the IP, workflow, data, customer relationship, and product layer.
Synthetic has to show that AI can handle edge cases, ask the right questions, document decisions, and produce books that accountants, tax preparers, investors, regulators, and founders can trust.
The company’s longer vision is even bigger. Synthetic says it wants founders to press a button and watch a company assemble around an idea, including the website, incorporation, bank accounts, payments, accounting, and other operating pieces. Accounting is the starting point with the bigger ambition being the required operating infrastructure.
Can autonomous AI earn enough trust to run startup bookkeeping, or will reliability, tax risk, and financial controls keep humans in the loop longer than investors expect?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 15, 2026
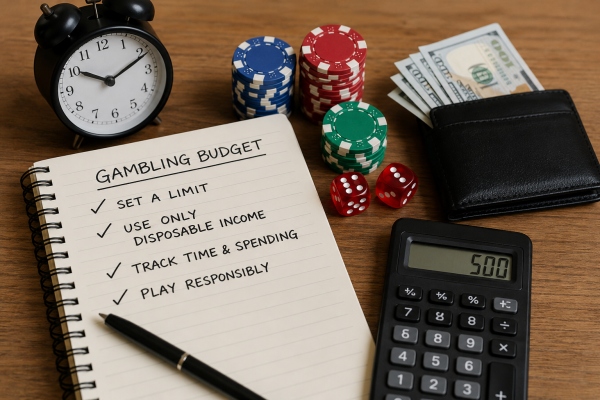
Experts at websites like Casino Online Lolajack suggest that you set a strict spending limit before you start any session. You should visit https://lolajack.com/ca/ if you want to see how professional gambling sites organize their information. This practice prevents you from spending money that you need for your daily bills.
Financial planning keeps your hobby fun because you know your exact limits. You should check your balance often during your play. This habit protects you from making emotional choices while you play.
You should calculate your disposable income first to see what you can actually afford. Do not use funds that you set aside for rent or groceries. You need to view this money as the cost of your leisure time.
This is what you should understand about benefits:
You gain a sense of control over your actions when you follow these simple steps. Experts at websites like Casino Online Lolajack agree that discipline is the most important skill for any player. You should write down your limits on a piece of paper to keep them in sight.
You should keep your gambling money in a different account or a separate digital wallet. This separation makes it impossible to dip into your savings by mistake. You see the total amount clearly when it does not mix with your main bank balance.
Players at sites like Casino Online Lolajack choose these methods to stay organized. You protect your long-term goals when you treat your hobby as a minor expense. Use a dedicated card for your entertainment to simplify your monthly tracking.
You must remember that time is just as valuable as the money in your wallet. Set an alarm on your phone to remind you when your session should end. You often lose track of your spending when you play for too many hours without a break.
Experts at websites like Casino Online Lolajack recommend that you take a walk every thirty minutes. This break clears your head and helps you look at your budget again. You make smarter moves when your mind is rested and calm.
You should always treat gambling as a way to have fun and not as a way to earn. Stop the game immediately if you notice that you feel stressed or angry. You keep the activity healthy when you respect the rules that you created for yourself.
A good budget is the best tool for anyone who visits websites like Casino Online Lolajack. You should update your plan every month to reflect your current financial situation. This keeps your hobby safe and ensures that you never spend more than you can lose.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 14, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, Capital Markets And Funding
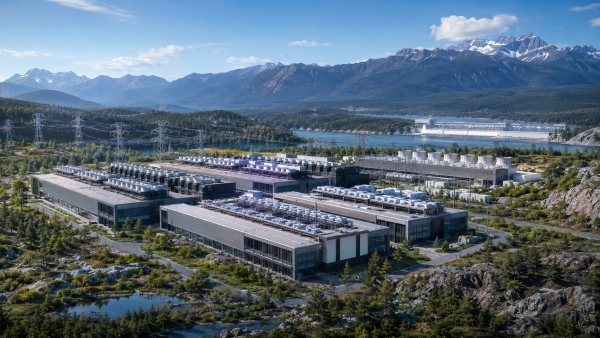
On May 13, 2026, Goldman Sachs Alternatives closed its acquisition of QScale, a Québec based developer and operator of AI ready data centre campuses for an undisclosed transaction value. QScale’s founders and management are reinvesting alongside Goldman Sachs Alternatives and will continue to lead the business. The company will also keep its headquarters in Québec.
This is private capital buying into Canadian compute capacity at the same time AI demand is putting pressure on power, land, cooling, and Canadian based infrastructure. For Canada, AI productivity needs more than models and talent. It needs domestic compute that Canadian companies can actually use.
QScale designs, builds, and operates data centre campuses for high performance computing and AI workloads. Its flagship Q01 campus in Lévis uses Québec’s low carbon, hydro dominated grid and natural cold climate cooling. QScale says that combination supports strong power efficiency and a lower environmental footprint than conventional facilities. The company is also developing additional campuses across Canada to meet customer demand.
Leonard Seevers, Partner, Goldman Sachs Alternatives:
“AI is rapidly redefining the infrastructure requirements to deliver compute to consumers and enterprises at scale. We believe QScale is building to the highest standard to meet these complex needs, and we are excited to partner with Martin and the QScale team to accelerate their build-out and support Canada's emergence as a global hub for sustainable AI compute.”
AI compute is expensive to build. Data centres need grid access, cooling, land, power contracts, engineering, customer commitments, and long term capital. Small software style funding rounds don't solve that problem.
Goldman Sachs Alternatives gives QScale access to a deeper capital base and global infrastructure network. Goldman Sachs has about $3.7 trillion in assets under supervision globally as of March 31, 2026. Infrastructure at Goldman Sachs Alternatives has invested about $22 billion in infrastructure assets since 2006. It invests across digital infrastructure, energy transition, transportation and logistics, and circular economy.
AI compute is now closer to energy, real estate, and national competitiveness than a normal technology product. Private markets are likely to finance more compute projects like this because the capital needs are large, the buildout is physical, and the customer demand is tied to AI adoption across industries.
Québec brings clean power, cold climate advantages, and a growing data centre base. Goldman Sachs Alternatives brings private capital and infrastructure operating experience. Together, those pieces can help Canada compete for AI workloads that might otherwise land in larger U.S. or global hubs.
Worth noting that hyperscale customers may absorb much of the capacity. The release doesn't say how much compute will be available to Canadian startups, scaleups, fintechs, or public sector AI projects. If Canada hosts the infrastructure but local companies cannot access affordable capacity, then the project may only capture construction and energy demand while missing more of the AI product value.
This connects directly to Canada’s productivity and competitiveness challenge. AI can reduce manual work and improve decision support, but only if companies can access the infrastructure behind serious deployment and can turn AI into measurable operating gains.
Martin Bouchard, Founder and Chief Executive Officer, QScale:
“From day one, QScale was built around a simple thesis: the world will need vastly more compute, and it will need it to be clean, dense, and resilient. Partnering with Goldman Sachs Alternatives gives us the capital base and the global network to scale faster, build bigger, and serve the most demanding hyperscale and AI customers in the world.”
Who gets priority access to Canadian compute capacity once global capital owns more of the infrastructure? The real test is whether Canadian firms can use that infrastructure to build products, own IP, and scale from here.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 13, 2026 | NCFA Insight | Artificial Intelligence And Data, Capital Markets And Funding, Risk Compliance And Regtech
On May 13, 2026, Bank of Canada External Deputy Governor Michelle Alexopoulos delivered a speech on AI and productivity at the Ottawa Economics Association and Canadian Association for Business Economics Spring Policy Conference. Her message was direct. AI can help Canada grow faster, but only if firms turn adoption into workflow gains, owned IP, stronger investment, and real operating results.
Michelle Alexopoulos, External Deputy Governor, Bank of Canada:
“To put it simply, the Bank of Canada cares about AI because of its potential to significantly affect productivity, economic growth, employment and inflation.”
Adoption numbers show progress, but also a gap:
Statistics Canada gives the upside a useful range. AI could raise Canada’s annual labour productivity growth by 0.4 to 1.1 percentage points over the next decade. Its April 2026 analysis also found that Canadian firms that adopted AI were 16.8% more productive than firms that did not. Those numbers are encouraging but they aren't automatic.
The first wave of AI in many companies has been useful but shallow. Staff use tools to draft, summarize, search, analyze, and code faster. That saves some time but it doesn't always change the business or lead to large productivity increases. The harder work (and benefits) starts when AI enters high value workflows such as onboarding, fraud review, lending files, advisor support, treasury, payments, and compliance testing.
That's where fintechs and financial institutions should focus.
Better AI execution should show up in operating numbers. Faster approvals. Lower error rates. Stronger fraud detection. Lower cost per file. Cleaner compliance evidence. If a firm cannot measure the workflow gain, it has not found the productivity gain.
The Bank is also using AI in its own work. AI helps forecast inflation and economic activity, track sentiment, analyze household and business data, review earnings call transcripts, and monitor financial stability. AI is already entering regulated analysis, but the Bank is clear that AI doesn't make monetary policy decisions. It use AI to sharpen judgment, not replace accountability.
That same control point now runs through governed AI workflows in finance. The value isn't just a quicker answer, but a workflow that leaves evidence, keeps humans responsible, and gives risk teams something they can inspect.
The compute point is hard to ignore. Top U.S. technology firms like Alphabet, Microsoft, Meta, Amazon and Oracle spent roughly US$200 billion on AI investment in 2024. That figure doubled to about US$400 billion in 2025. The Bank also noted that AI data centres are expanding so quickly that power generation is struggling to keep up. Compute is no longer a back office technology cost. It's now industrial, economic and national security infrastructure.
Canada has started to respond. The federal AI Compute Access Fund helps Canadian SMEs access compute for AI projects, with project compute costs ranging from $100,000 to $5 million. That funding helps some companies get beyond small pilots, but it doesn't solve the whole problem. If Canadian companies cannot sustainably access enough affordable compute, the country risks training talent here while building value somewhere else.
For fintech operators, compute affects competitiveness. AI in fraud, risk, underwriting, compliance, markets, and customer support needs secure data pipelines, model testing, and monitoring. Firms that cannot fund compute and controls will stay stuck in trials. While companies that can fund and execute both have a better chance of turning AI into operating advantage.
The Bank’s labour message is more balanced than the public debate. There is no evidence yet that AI is replacing workers on a large scale. About 90% of Canadian businesses that adopted AI reported no staffing effect. Roughly 4% reported job creation, while about 6% reported employment decreases linked to AI use.
The reality is reported job data can lag, and i t doesn't mean the AI labour risk narrative fake. The Bank noted weak hiring in AI exposed roles such as entry level coding and customer service. It also flagged younger workers as a group to watch. This connects directly to recent evidence on AI spending and workforce redesign and AI’s hidden workforce costs. The question is how companies are redesigning workflows in the age of AI. Will they break training channels, judgment, supervision, and customer trust?
The time savings are real. The Bank cited Indeed research showing that 57% of Canadians who use AI at work save one to two hours a day, while 22% save three to five hours. The value depends on what happens next.
If workers use the time for better service, stronger analysis, and tighter controls, then productivity can improve. If companies only cut junior roles, then they might lose the next generation of trained operators.
Execution takes money. AI firms and AI adopting fintechs need a lot of investment to compete and the middle stage is expensive. Canada has strong research and strong founders, but too many companies hit a capital wall before they become global platforms.
Budget 2025 recognized part of the gap. It proposed $750 million to support Canadian firms facing early growth stage funding gaps, with details expected in 2026. It also proposed $1 billion for BDC to launch the Venture and Growth Capital Catalyst Initiative. This is good but allocation matters. Capital needs to reach firms when compute, enterprise sales, compliance, and global distribution become expensive.
Beyond just announcements, Canada needs a fuller capital stack with more domestic lead investors, growth equity, private credit, venture debt, angel capital, compliant investment crowdfunding, strategic corporate capital, and better public market routes for quality scaleups. Capital should help productivity companies scale from Canada, not push them to sell early or move the value elsewhere. CVCA reported $56.5B in Canadian private equity investment across 483 transactions in the first nine months of 2025, the strongest nine month period on record. More of that capital needs to back productivity firms that can scale from Canada and keep IP, customers, and senior talent here.
Fintech investment is concentrating into fewer larger deals, which makes scale-up capital more important. Otherwise, Canadian companies may build and test the prototype in Canada but scale the value somewhere else. That’s the leakage problem. That is where fintech’s role in Canada’s productivity revival becomes practical. Better access to capital, faster technology adoption, and stronger business investment need to show up in firm level execution.
The OECD’s 2025 Canada survey lays out the structural problem clearly. Canada’s productivity performance has lagged peers, and limited investment in intellectual property and digital technologies has held back growth. That is the bridge between AI use and AI value.
In a recent Financial Post op ed on Canada’s IP gap, Louis Carbonneau argues that Canadian founders often build strong technology but lack the literacy, capital discipline, and enforcement capacity needed to own and extract value from it. He points to weak IP diligence in venture funding, limited IP education, thin enforcement culture, and policy support that often helps companies file a first patent without helping them turn it into a defensible business asset.
If Canadian companies use imported AI tools but don't own proprietary workflows, data layers, patents, models, or distribution channels, the productivity gap can widen and value continue to leak away. IP strategy shouldn't be a legal afterthought. It needs to be part of the productivity and growth plan.
Budget 2025 proposed new IP support, including $84.4 million over four years to extend Elevate IP, $22.5 million over three years to renew support for the Innovation Asset Collective’s Patent Collective, and $75 million over three years to extend the National Research Council’s IP Assist Program. That support can help, but only if it's tied to business strategy, and follow through after the first filing.
The IP Canada Report 2025 shows an eye popping statistic. In 2024, nearly 86,500 patents, trademarks, and industrial designs were filed in Canada by non residents. In 2023, Canadian residents filed about 44,500 IP rights abroad. Although Canada participates in global IP markets, participation is not the same as owning the most valuable parts of AI enabled productivity.
Canada needs to treat AI execution like an economic buildout and not another software trend. Adoption is still early. Compute is expensive. Jobs are changing. Capital is thin at the scale up stage. IP decides who keeps the value.
That's how AI adoption improves becomes Canadian productivity and competitiveness. Not through more pilots. Not through more research reports. Through financed, governed, IP protected companies, skilled workers, and community capacity that can turn AI into practical gains.
Can Canada turn AI adoption into owned productivity gains, or will the biggest value flow to foreign platforms that provide the tools, compute, capital, and distribution?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016