




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


October 21, 2026 | Insight | Capital Markets Infrastructure And Funding, Digital Assets Blockchain And Tokenization, Wealthtech Investing And Trading
On October 20, 2026, the U.S. Securities and Exchange Commission published guidance on tokenized stock trading, clarifying how certain U.S. public shares can trade on blockchain platforms without a company's affirmative approval. The guidance follows the SEC's September 17 Innovation Exemption, which allows limited trading of eligible public stocks through new digital venues. Sixteen companies, including Microsoft, Alphabet and Goldman Sachs, have reportedly objected to having their shares traded on the proposed OKXICE platform.
The exemption doesn't cover every public stock, and companies can block certain trading arrangements. Venues also face limits on which securities they can offer and how much trading they can handle. For investors and market operators, the questions are which stocks qualify, what ownership rights come with the tokens and whether these new platforms can compete with traditional exchanges. The October 20 guidance further explains how the existing exemption works without introducing new regulations.
The SEC allows qualifying venues to trade tokenized National Market System stocks, which generally include eligible shares listed on major U.S. exchanges and certain exchange traded products. The exemption covers qualifying securities tokenized by their issuers and arrangements involving independent third parties. It excludes rights, warrants and tokens that merely track a stock's price without providing the same ownership rights as the underlying security.
The SEC separates eligible stocks into two groups. Tier 1 includes shares in the S&P 500 and Russell 1000, along with certain qualifying exchange traded products. Major companies such as Apple, Microsoft, Alphabet and Nvidia fall within those indexes, although that doesn't automatically make their shares available on a tokenized venue. Tier 2 includes other eligible listed securities outside Tier 1, giving smaller public companies a potential route into these markets.
The limits are strict. A qualifying venue can offer up to 75 Tier 1 symbols, with trading in each capped at 0.25% of the stock's average daily share volume during the previous month. Tier 2 allows up to 250 symbols, with a 2.5% volume cap. Related venues must combine their trading activity when calculating these limits.
Consider a Tier 1 stock averaging 10 million shares traded daily. A qualifying venue and its affiliates could trade up to 25,000 tokenized shares per day. A Tier 2 stock with the same volume would have a limit of 250,000 shares. A first breach of a stock's volume limit doesn't automatically require suspension, but subsequent breaches require a three month trading pause for that security.
Investors must receive the same rights and privileges as holders of equivalent conventional shares. That includes applicable dividends and voting rights. The arrangements supporting those rights must be verified, and venues must meet requirements for trading halts, transaction records and technology safeguards. A token offering only synthetic exposure to a share price doesn't qualify under this exemption.
OKXICE is one of the first proposed venues testing the SEC's approach. It's a joint venture owned equally by Intercontinental Exchange, parent of the New York Stock Exchange, and OKC USA Holding, part of the OKX group. Its public trading notices describe a platform where approved investors could trade tokenized U.S. stocks against stablecoins using automated liquidity pools instead of a conventional stock exchange order book.
OKXICE plans to use Uniswap v4 technology on the X Layer blockchain to let approved investors trade tokenized stocks through pools of shares and stablecoins. Investors would need to verify their identities and use approved digital wallets. OKXICE says it won't hold customer assets or sell newly issued shares. Publishing its plans doesn't mean the SEC has approved the platform or that trading has started.
OKXICE initially proposed 63 stock symbols from 62 companies. Nine companies had objected by October 15, including Broadcom, Verizon, UnitedHealth, CoreWeave and AppLovin. Reporting on October 19 identified seven more, bringing the total to 16 companies, including Microsoft, Alphabet, Goldman Sachs, Qualcomm, Caterpillar, McDonald's and Western Digital.
One of the 16 objectors, Cerebras Systems, wasn't on the original proposed list. That means 15 of the original 62 companies had objected, leaving 47 without a reported objection at that point. Silence doesn't mean approval. It only means the company hasn't exercised its right to block that particular trading arrangement.
Applied Optoelectronics explained its concerns to The Wall Street Journal. The company questioned whether tokenized trading would benefit shareholders and worried about possible effects on its share price, trading activity and volatility. It also didn't want investors to mistake an independent tokenized offering for one supported by the company.
Under the SEC exemption, companies have 30 calendar days after receiving notice to object. If they object in time, that venue can't offer their tokenized shares under the exemption. The objection doesn't automatically prevent every other form of stock tokenization.
Trading platforms face a separate 30 day requirement. They must publish their operating plans at least 30 calendar days before trading begins. The SEC's October 20 guidance confirms that venues can publish proposed stock lists while companies are still deciding whether to object. They must disclose which decisions remain pending and update their lists as objections arrive or the periods expire.
Andrew Cuomo, co-chair of OKXICE, described the issuer objections as a "natural response". He said the venture expected some companies to wait before participating. Whether that resistance eases will depend partly on how the first venues operate and what benefits they can demonstrate to investors and issuers.
The potential appeal is clear. Investors could trade familiar U.S. shares outside regular exchange hours, hold them through approved digital wallets and use blockchain systems to complete transactions. But being able to trade at any hour doesn't guarantee liquidity or a competitive price. New venues still need enough investors and market makers to support reliable trading.
OKXICE proposes using automated market makers instead of matching every buyer and seller through a traditional order book. Liquidity providers would supply tokenized shares and stablecoins to trading pools, earning fees while taking market risk. If those pools don't attract enough capital, investors could face wider spreads or prices that differ from the conventional stock market.
Nasdaq has proposed a different model. In September 2025, Nasdaq sought SEC approval for tokenized stock trading within its existing exchange system. Investors could choose traditional or tokenized settlement, with the Depository Trust Company handling the process. The same trading rules, security identifiers and shareholder rights would apply.
Chuck Mack, Nasdaq's Senior Vice President of North American Markets, explained the company's approach.
"Past market failures teach us that it is imperative to ensure governance, resilience, and investor protection are embedded from the outset."
The two companies are taking different approaches. OKXICE plans to build a new blockchain trading platform, while Nasdaq wants to add tokenized stocks to its existing exchange system. Nasdaq's proposal follows a separate regulatory process and predates the October 2026 objections. For investors, the real focus is which approach offers better prices, reliable trading and strong shareholder protections.
Tokenized shares still need to give investors the same ownership rights as regular stocks. That means making sure dividends reach the right people, shareholders can vote and stock splits or mergers are recorded correctly. Investors who control their own digital wallets also need to protect their access keys. Losing them could mean losing access to their investments.
Investor protections can also differ. OKXICE isn't registered as a traditional stock exchange for trading under this exemption, so some rules that apply to established exchanges don't apply in the same way. The SEC exemption is temporary and lasts five years. That gives regulators time to assess how these markets operate before deciding whether to introduce permanent rules.
For Canadian fintech founders, the business opportunities go beyond operating a trading platform. These markets need companies that can protect assets, maintain accurate ownership records, verify compliance and supply trading liquidity. Brokers and transfer agents may also need new technology to connect blockchain transactions with existing securities systems. Demand for those services will depend on whether investors actually use the new markets.
Canada is also looking at how tokenized securities could trade under its own rules. In March 2026, the Canadian Securities Administrators launched Project Tokenization to explore trading, custody and settlement of digital securities. The initiative has since engaged more than 240 organizations, as reviewed in NCFA's capital markets innovation analysis. Unlike the SEC, Canada hasn't introduced a comparable exemption for tokenized public stock trading. For Canadian exchanges and fintech founders, the U.S. experiment offers an early look at which business models work and where existing securities rules may need to adapt.
If tokenized stocks attract buyers and sellers, keep trading costs competitive and preserve shareholder rights, they could become a useful alternative. If not, investors may have little reason to move away from traditional stock markets.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
October 20, 2026 | NCFA Story Intelligence | Capital Markets And Funding, Leadership And Governance, Artificial Intelligence And Data
On October 16, 2026, You Can See Everything opened in Canadian theatres. Four days later, the documentary about Elizabeth Holmes is still one of the biggest stories at the North American box office. It opened with about US$15 million from only 855 screens. That's an extraordinary result for a documentary about a founder whose company collapsed years ago and is now serving a federal prison sentence.1
Holmes didn't raise money because investors wanted to lose it. She sold a future that sounded possible, surrounded herself with people whose reputations made belief easier, and built a company whose story moved faster than outsiders could verify the technology. By the time the evidence caught up, investors had committed hundreds of millions of dollars.
What follows is a story of how founder trust becomes part of an investment case and how evidence can lose ground to momentum. The same human problem returns whenever investors finance an uncertain future.
The idea is bigger than the product. Theranos tells investors that its technology can run a broad range of tests from tiny amounts of blood. The company is private, the technology is closely guarded and outsiders have limited access to what happens inside the machines. That secrecy can sound like competitive protection when the founder is believed.
Conviction becomes part of the product. Holmes presents Theranos as a mission driven company that can transform healthcare. Investors hear a founder who appears certain about the future and willing to devote herself to it. That confidence is valuable in a startup because the product, market and operating model are all unfinished. It also makes the founder unusually important to the investment case.
The board looks formidable. Fortune described Theranos in 2014 as having one of the most illustrious boards in American business. George Shultz, Henry Kissinger, William Perry, Sam Nunn, James Mattis and other prominent figures gave Holmes access to experience, networks and public credibility that most young founders could never assemble.4
The board can't substitute for technical oversight. A famous director can open doors and challenge strategy. That doesn't automatically give a board the scientific depth to test a diagnostic platform. Prestige can make a young company look safer while leaving the hardest operating question untouched.
The numbers make the story feel real. A multibillion dollar valuation, hundreds of millions raised and national retail partnerships give investors familiar business signals. Those signals usually matter. They become dangerous when investors start treating them as evidence about the one thing the company still has to prove.
The media helps close the loop. Holmes becomes a symbol of Silicon Valley ambition. WIRED has now revisited its own 2014 coverage and acknowledged how media enthusiasm helped amplify the founder story before the science received enough scrutiny.7 The founder earns attention because investors believe. Investors see attention and find another reason to believe.
Good diligence can still ask the wrong question. Investors may spend weeks testing market size, legal structure, partnerships and founder references while the core product remains difficult to inspect. A deal room can contain thousands of pages and still miss the fact that matters most.
The founder can become the gateway to the evidence. That creates a dangerous loop. Investors trust the founder enough to accept the materials, then use those materials to decide whether they should trust the founder. Independent verification has to break that loop.
The criminal case narrows the facts. In January 2022, a federal jury convicts Holmes of conspiracy to defraud investors and three counts of wire fraud tied to transfers totalling more than US$140 million. The jury acquits her on patient related conspiracy and several patient fraud counts, while other investor counts end without a unanimous verdict.10
The sentence makes the cost tangible. In November 2022, Holmes receives 135 months in federal prison. She begins serving the sentence in 2023. The SEC had put the investor principle plainly years earlier when it said investors are entitled to “complete truth and candor” from companies and executives.11
The audience knows how the story ends. That makes the continuing fascination more revealing. People aren't buying tickets because the verdict is unknown. They are watching because confidence, ambition, deception and failure are still compelling human material.
Persuasion still moves money. Canadian investors see the same mechanism in a different setting. How AI Is Changing Canadian Investors’ Decisions found that 84% of surveyed self directed investors used AI, financial creators or both. Technology changes the channel. It doesn't remove the human desire to find someone or something that makes uncertainty feel easier.
Founder conviction still has value. Early stage investors are paid to finance businesses before every answer exists. A founder who can't make others believe in an uncertain future may never recruit the team, customers or capital needed to build it.
Conviction needs independent evidence beside it. Customer calls, production data, technical review, board oversight and financial reconciliation give investors something that doesn't depend on the founder's version of events. The earlier the company, the more important it becomes to know which assumptions are still beliefs.
Holmes is in prison, Theranos is gone and investors now know how the story ended. That makes the mistakes look obvious in hindsight. They were much harder to see when the company was raising money, signing national partners, attracting famous directors and appearing on magazine covers.
The next founder who lets belief outrun the evidence will probably look nothing like Holmes. The company may be building AI, financial infrastructure, robotics, biotech or something investors have not learned how to value yet. The founder may have respected backers, impressive customers and a demonstration that makes the future feel close enough to touch.
Early founders often have to sell conviction before the product, revenue or market fully exists. That's part of building a venture, not evidence of deception. Investors are financing a future that has not happened yet, so imagination belongs in the deal.
The line gets crossed when aspiration is presented as fact, a controlled demonstration is presented as independent proof, or hoped for traction is sold as something already verified. A founder can sell why the future might happen. The investor still has to know what is already true.
STORY INTELLIGENCE
How OpenAI And Anthropic Reached Public Markets
OpenAI and Anthropic show what happens when founder vision, strategic backers, governance choices and enormous private capital converge before public market scrutiny arrives.
FOUNDER BUILD
Inside a Licensed Profession: What Ownright’s Build Teaches Fintech Founders
Ownright offers a current founder case where credibility comes from operating evidence, regulatory fit, customer execution and a system that has processed more than $2 billion of transactions.
MARKET ACTIVITY
FNZ Turnaround Tests La Caisse and Canadian Pension Capital
Repeated capital raises and management changes at FNZ show what investor conviction looks like after the cheque is written, when ownership starts turning into active governance.
NCFA INSIGHT
Canada’s Early Stage Startup Funding Funnel Narrows
A tighter Canadian funding market raises the stakes for founders trying to earn attention and for investors deciding which stories deserve scarce early stage capital.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 20, 2026 | Last Updated: October 21, 2026 | NCFA Story Intelligence | Sustainable Finance And ESG, Investment And Capital Markets, Regulation And Policy
On October 20, 2026, Canada’s Taxonomy and Transition Planning Council released its final sustainable investment methodology. Canada now has a common way to assess green and transition activities after years of greenwashing disputes over financial products and bank commitments. Ottawa backs and funds the initiative, while an independent council develops and approves the standards. Adoption is voluntary, and detailed sector tests are still being written.
Canadians wanted products and investments that reflected their environmental priorities. Financial institutions saw customers, assets, lending opportunities and a stronger public story. Funds, ETFs, green bonds and huge sustainable finance commitments followed. Then investors started looking more closely at the holdings, counting rules and environmental results behind those claims.
What follows is a story of growing investor demand, billions in financial promises, and the widening gap between what institutions marketed and what they could prove.
Customers start asking for proof. Canadian environmental labelling programs such as Environmental Choice and EcoLogo bring product claims into everyday buying decisions during the 1990s. Buyers want to know what a label proves, not simply whether a package looks green. Later, investors bring similar expectations to savings and portfolios. 1
Financial firms see an opening. Responsible investing gains momentum when the UN backed Principles for Responsible Investment launch in 2006. Institutions from 16 countries representing more than US$2 trillion in assets sign on at the New York Stock Exchange. Investors are signalling that environmental, social and governance issues belong in investment decisions, and asset managers have a new market to serve.2
Canadian green bonds find buyers. EDC and Ontario give investors a named framework and intended use of proceeds before the money is committed. Named uses of proceeds give buyers more to check than a broad corporate promise. The proof still comes later. Issuers have to show where the capital went, what was completed and what the project delivered. A successful bond sale doesn't guarantee a successful environmental outcome.
Responsible investing grows beyond niche portfolios. By the end of 2017, Canada counted C$2.13 trillion in professionally managed assets using at least one responsible investment strategy. The Responsible Investment Association’s 2018 report put that at 50.6% of managed assets. The figure included screening and engagement strategies. It was not C$2.13 trillion of new green projects.
The banks raise their targets. As climate commitments become part of banks’ public image, Canada’s largest banks announce targets in the hundreds of billions. Corporate lending, underwriting, advisory work and other eligible services may all contribute under a bank’s methodology. A big cumulative number becomes a prominent measure of progress.
Investors start asking what sits behind the totals. A financing commitment can qualify under a bank’s own rules without proving that the financed activity later cut emissions. As the numbers climb, that gap becomes harder to ignore. Banks are selling sustainable finance. Their critics want to know what the money financed and what changed.Institutional investors were sending mixed signals too. In 2024, How Canadian Institutional Investors Voted on Climate 2024 found support for climate shareholder proposals varied sharply across major Canadian asset managers.
Fund marketing comes under review. The Canadian Securities Administrators issue ESG fund guidance in 2022 and revise it in 2024. Their reviews identify cases where promotional language reaches further than the investment documents support. The revised notice covers 112 prospectus reviews involving 57 managers, plus 39 continuous disclosure reviews involving 35 managers and 50 funds.6
Bank disclosures face formal complaints. By January 2024, Canadian banks face scrutiny over sustainability claims after Investors for Paris Compliance files securities complaints about RBC, TD, BMO, CIBC and Scotiabank. The group challenges how the banks support their sustainable finance claims. The allegations are not findings of wrongdoing. The original complaint sets out what the advocates asked regulators to examine.
RBC puts its counting method on paper. Its March 2024 framework says the bank uses its judgment when assessing eligible transactions. For credit, it can add authorized balances at successive fiscal year ends. The same continuing exposure may therefore contribute in more than one year. That isn't the same as reporting only unique new loans, and it says nothing by itself about the emissions a financed project later avoided.
Then the C$500 billion target disappears. In April 2025, RBC retires the commitment and cites uncertainty around measurement and Canada’s environmental claims rules. The move doesn't prove earlier transactions were misclassified. It does leave investors with a basic problem. A flagship number that once signalled leadership is gone just as scrutiny of the underlying methodology is intensifying.7
The fight moves into investment funds. In 2025, the OSC brings a case against Purpose Investments and CEO Som Seif over 19 allegedly misleading ESG communications made between 2019 and 2023. Purpose and Seif deny wrongdoing. After closing arguments in September 2026, the Tribunal reserves its decision. As of October 20, the allegations remain contested and there is no verified final merits ruling.8
The money stays, but new product launches slow. Morningstar reports C$67 billion in Canadian sustainable fund assets at the end of 2025. Only two new funds launch that year, down from 18 in 2024. The ten biggest net inflow winners attract C$4 billion while the rest lose C$2.9 billion combined. Greenwashing does not explain that result on its own. What the numbers do show is a market where assets keep growing while new money concentrates in fewer products.9
Green claims carry more legal risk. Competition Act changes in 2024 put environmental marketing under closer scrutiny. Parliament changes part of that regime in March 2026 by removing the requirement for business activity claims to follow an internationally recognized methodology. Misleading claims remain unlawful. By then, fintechs face new green claim rules under Competition Act, making documentation and evidence part of the commercial risk around environmental marketing.
The government work began years earlier. The federal Sustainable Finance Action Council receives a taxonomy mandate in 2021. Its 2022 roadmap report proposes green and transition classifications and a governance system, warning that delay could cost Canada investment opportunities. The early ambition to have a fuller framework in place by 2025 passes without one.
Ottawa funds the work but doesn't write the standard. In December 2025, Finance Canada selects the Canadian Climate Institute, working with Business Future Pathways, to support an independent taxonomy process. The federal government provides seed funding and a mandate. The independent Council owns the methodology and approval decisions.10
The 2026 consultation brings the difficult cases into the open. Canada has to decide how to treat investments that cut emissions inside steel, mining, transport and energy without pretending those industries are already green. A proposed emissions abatement category draws particular attention because a project can reduce emissions and still extend the life of a high emitting asset. Council chair Marlene Puffer connects the work directly to investment. “Ultimately, this work will underpin Canada’s ability to compete for capital with our peers around the world.”11
Because the taxonomy is voluntary, banks and fund managers now have a choice. They can align products with the common definitions or continue relying on their own frameworks unless another rule requires otherwise. Investors will be able to see which institutions use the shared standard and which do not.
That choice creates work for fintech firms that can keep the evidence attached to the financing claim. Activity screening, emissions records, approvals and audit trails all need to survive from origination through reporting. Capital is already moving into audit ready ESG software, including Novisto's USD $27 million raise. Banks, asset managers and borrowers will pay for systems that make sustainability claims easier to verify and harder to overstate.
A green label once helped a product stand out. Today, investors can ask much more of the claim behind it. Canada’s banks and fund managers have sold the promise of sustainable finance for years. Investors have answered with real money. The controversies have shown how quickly confidence frays when the language is more impressive than the evidence.
Canada's government backed, independently developed taxonomy gives the market a chance to reset that bargain. It is voluntary, and the technical tests are unfinished. No council can make an old claim true after the fact. Banks can show how a financing decision qualifies. Companies can keep the records behind the claim. Fund managers can tell investors exactly what they own.
Fintech founders have a market in the systems that keep these claims honest. Activity screening, emissions data, traceable loan records and assurance can become products that banks, issuers and investors will pay for. The firms that earn trust won't be the ones making the largest green promise. They'll be the ones that can show where the money went, what changed and who checked the evidence.
NCFA STORY
CSA Pauses Climate and Diversity Disclosure Rules
Canada paused mandatory climate disclosure rules in 2025 while material climate risks and misleading claims remained subject to securities law. Voluntary standards therefore carry more weight in the market.
NCFA INSIGHT
AI Won’t Solve SME Finance Without Better Data
Sustainable finance breaks down when businesses cannot collect and reuse reliable operating data. Better evidence infrastructure is becoming part of the financing opportunity for SMEs, lenders and fintechs.
NCFA STORY
Sustainability A Must for Fintech Growth
Fintechs face their own sustainability pressures as digital infrastructure consumes more energy and customers expect stronger environmental performance. The business opportunity and the operating risk are moving together.
NCFA VOICES
Businesses Competing on Social Values Use Fintech to Gain an Edge
Long before Canada had a taxonomy, customers were already rewarding companies that reflected their environmental and social values. Fintech gave firms new ways to turn those values into measurable participation.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
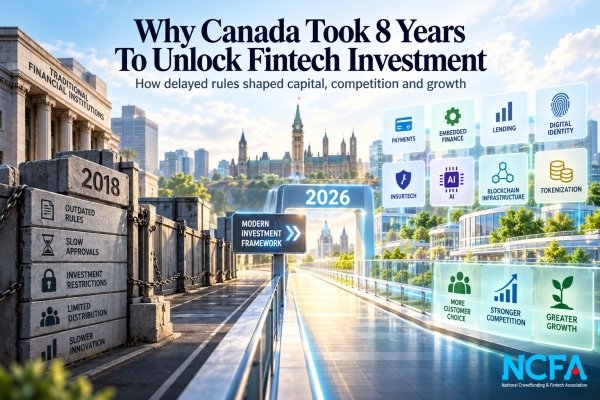
On October 17, 2026, Finance Canada published proposed fintech investment and technology regulations for powers Parliament approved in June 2018 and never brought into force. The package reaches more than 400 federally regulated financial institutions.
Finance now says the older rules can “prevent or complicate” fintech investment, limit capital flowing into innovative sectors and impede productivity growth. Eight years after Parliament acted, the operating rules are still only proposed.
The delay wasn’t one long consultation. Finance’s own record shows six concrete problems. Officials had to draw the regulatory perimeter between finance and technology, preserve the barrier against unrelated commerce, set revenue and regulatory capital limits, stop the rules from squeezing smaller institutions, and cut reporting requirements industry said were too heavy. Then Parliament had to repair defects in the 2018 statute in 2024. Six problems turned one reform into eight years of rulemaking.
This wasn’t a ban on fintech investment. Banks and insurers could still buy businesses that fit the existing rules. The trouble started when a fintech mixed finance with commercial software or expanded after an institution had invested. Banks had already warned that some domestic technology approvals took three to four months. The 2026 proposal would finally give qualifying mixed businesses a new route when at least 60% of their activity is financial, subject to separate limits on the investor.
Finance opened the review in 2016. It held 32 meetings and received 63 written submissions, then received 300 submissions in 2017, with 25 focused on fintech. Finance later acknowledged that incumbent institutions and industry associations were better represented than independent fintechs and venture investors.
Bankers came with a practical complaint. The Canadian Bankers Association’s 2017 submission said some domestic technology approvals could take three to four months and covered only the activities named in the application. That’s a poor fit for a fintech that can add a product, market or subsidiary in the time it takes a large institution to finish an approval process.
Founders weren’t building tidy regulatory categories. Payments were moving into merchant software, identity tools could serve banks and law offices, and data companies were becoming financial infrastructure while selling into other industries. The old rules drew cleaner lines than the market did.
Investors wanted a wider lane too. Finance said collaboration could pair fintech speed with the balance sheets and customer relationships of established institutions. Portag3 Ventures, then backing Canadian companies including Wealthsimple, Borrowell and KOHO, supported broader investment flexibility and argued that bank financing and collaboration were important to the fintech ecosystem. Capital and distribution were already part of the policy problem.
Under the Bank Act route described by the CBA, a substantial investment generally had to stay inside permitted activities. If even one ancillary activity or a downstream subsidiary moved outside that list, the bank could face another approval, a different investment classification or divestment. The CBA called the restriction a “significant impediment” with the potential to restrict Canadian innovation.
Insurers ran into the same boundary from another direction. The life insurance industry’s 2017 submission said an insurer could use identity or anti money laundering technology inside finance but couldn’t freely sell the same capability to law offices, real estate firms, other businesses or government. Useful technology could have a broader market, while the ownership and commercialization rules stayed narrow.
A growing fintech can create a problem for the shareholder that helped fund it. Add inventory software, merchant analytics or a commercial subsidiary because customers want them, and the business may no longer fit the permission that supported the original bank investment. The CBA warned that this could discourage fintechs from working with banks.
Insurers faced a similar commercial choice. A tool built for regulated finance might have customers far beyond finance, yet the legal route could narrow who could own the business or where the product could be sold. That can influence which investor a founder takes, how the company is structured and which markets it enters next.
Parliament responded on June 21, 2018. The 2018 Budget Implementation Act broadened permitted technology activities, removed prior ministerial approval for the expanded nonfinancial activities, widened referral powers and created a new investment category for companies whose businesses were mostly financial services. The law clearly moved toward more flexibility.
But Parliament didn’t define how much of a company had to be financial to qualify as a majority financial services entity. It also left the revenue, capital, reporting and transaction conditions to regulation. Without those operating rules, institutions couldn’t use the new powers and stayed under the older framework.
Parliament gave banks and insurers broader ownership powers in June 2018. Finance still had to define the majority test, exposure limits and safeguards before anyone could use them. The authority existed. The investment route didn’t.
That left financial institutions making real investment decisions under the old framework while fintech business models kept widening. A company could fit the rules when a bank first invested and create a new legal problem later simply by adding a commercial activity customers wanted.
After Royal Assent, Finance worked with the CBA, the Canadian Life and Health Insurance Association and OSFI. The first problem was the regulatory perimeter. Finance called separating new technology activities from core financial services a “serious technical challenge”, especially when the same staff, assets and systems served both. Officials also had to preserve existing investment prohibitions and keep visibility into the new business.
Then came the operating limits. In 2019, officials worked through revenue caps, regulatory capital exposure, annual reports and transaction conditions. A 2020 technical review exposed two more problems. Uniform rules could box out smaller institutions, while the proposed reporting package could impose a significant burden. Finance later revised both.
The delay didn’t come from one unresolved issue. It came from six. Finance had to separate finance from technology, preserve limits on unrelated commerce, set revenue and capital exposure caps, give smaller institutions enough room to compete, and reduce reporting requirements industry said were too burdensome. Those were the five regulatory design problems documented through the consultation record.
The sixth problem sat in the law itself. Bill C-59 received Royal Assent in June 2024 and made technical corrections to the 2018 law. It fixed discrepancies between the English and French provisions and clarified that the expanded technology powers were limited to information technology. By then, Finance had already consulted in 2019, reviewed a draft in 2020, consulted again in 2021 and returned with another draft in 2024.
Every revision created another round of legal or regulatory work. Caps changed. Reporting changed. Parliament repaired the statute six years after passage. The first public regulations still didn’t reach Canada Gazette Part I until October 2026, even though stakeholders were asking by 2024 for the powers to come into force “as soon as feasible.”
National Bank took control of Flinks in 2021. Its disclosed transaction included C$73 million for voting preferred shares followed by another C$30 million investment. The bank’s interest rose to 85.9%.
RBC bought WayPay in 2019 to expand automated business payments and account reconciliation. Canada Life acquired ClaimSecure in 2021, adding 1.25 million plan members and technology handling more than C$1.2 billion in annual claims payments. Canada Life and ClaimSecure later launched a combined benefits product.
Those deals matter because they rule out the easy story. Canada didn’t ban institutional fintech investment, and banks and insurers kept buying businesses that fit the existing framework. The squeeze showed up at the edges, where finance blended with commercial activity or a company later expanded beyond the legal fit that supported the original investment.
By October 2026, Flinks had moved beyond financial data connectivity into banking development, payment integrations, account switching and managed services. That’s exactly the kind of expansion a strategic shareholder may want to keep backing. Under the older framework, a different commercial move could force the shareholder to stop and ask whether it could legally stay invested.
The CBA warned that the legal fit could affect a deal before anyone applied for approval. If a fintech needed capital quickly, a bank bid carrying a regulatory condition could lose to cleaner, faster money. A later business change could also force the bank back into approval or divestment. A lost opportunity can disappear before Ottawa ever sees a file.
Finance expects more activity once the new route is usable. Over the past decade, roughly one institution per year sought the relevant ministerial approvals. Finance now assumes large banks will average two qualifying investments annually and large insurers one. The figures aren’t directly comparable, but Finance itself expects more activity because the process should be faster, less costly and more certain.
Government data can count approvals. It can’t count the bank bid that was never made, the expansion pushed into another company or the investor a founder never approached because the legal fit was poor. It can’t count technology an insurer decided not to sell outside finance either. Those decisions rarely leave a public record.
The economic toll starts before an approval file exists. A bank offer with conditions can lose to faster capital. A founder can split a product, delay a commercial move or avoid an investor whose ownership may become a future constraint. None of those choices needs a rejection letter to change the company’s path.
The October proposal finally puts a number on majority. A target can qualify when at least 60% of its business consists of qualifying financial activity, measured using whichever produces the highest result among revenue, operating expenses or assets. That gives younger or differently structured companies more than one way to clear the test.
The investor has separate limits. Institutions with more than C$12 billion in equity would face a 10% nonfinancial revenue ceiling and a 10% regulatory capital exposure limit. Small and medium institutions with C$12 billion or less in equity would get 15% revenue headroom while keeping the same 10% capital limit.
Take a payments company that also sells merchant software. Under the older activity based route, one impermissible commercial activity could knock the company out of that investment permission. Under the proposal, a business with 70% qualifying financial activity and 30% other commercial activity could potentially qualify. The 70 and 30 split is illustrative, but the business consequence is straightforward. The founder may no longer have to strip out every useful commercial feature just to keep a bank investor eligible.
The percentages don’t describe the same limit. The historical 5% exemption covered certain bank technology investments without approval and required the investee to stay within prescribed activities. The new 60% test applies to the target company’s business mix. The 10% and 15% limits apply to the investing institution’s aggregate nonfinancial business. There isn’t a simple old cap and new cap comparison.
More eligible bank and insurer investors can improve financing choices, distribution and negotiating leverage for an independent fintech. A strategic buyer can get a product in front of customers much faster. It can also end up owning technology several competing institutions rely on. More capital and more competition aren’t automatically the same outcome.
Finance is trying to keep sight of that risk. Certain large acquirers would have to report material supply arrangements between a target and the acquirer’s competitors. Smaller and medium institutions get more revenue headroom and no new reports, because identical limits would leave them with much less room to compete.
A wider buyer pool can help founders raise money, get distribution and negotiate exits. It can also put an important supplier or emerging challenger inside a major incumbent. That’s where the reform shifts from a capital question to a competition question.
The Competition Bureau’s fintech study supported removing unnecessary barriers to entry and collaboration while keeping scrutiny where incumbent relationships could weaken competition. Finance’s new supply reporting reflects the same concern. The useful outcome isn’t simply more acquisitions. It’s more capital reaching strong companies without draining independent competitive pressure from the market.
Finance estimates the proposed rules will add C$267,518 in annualized administrative and compliance costs, or about C$1.88 million in present value over 10 years. Those figures cover the new reporting burden. They don’t count the savings from removing some ministerial approvals, and they certainly don’t capture eight years of slower, narrower business choices under the old framework.
The regulations are proposed, not in force. Canada Gazette Part I opened a 30 day consultation on October 17, 2026, with comments due November 16. The government still has to finalize the regulations and use a separate Order in Council to activate the dormant 2018 amendments.
The last round now turns on execution. The 60% definition has to work for current fintech business models, smaller institutions need enough room to compete, and Finance needs visibility into new risks without rebuilding the reporting burden industry spent years pushing back on. Get those choices wrong and the reform can still underdeliver even after eight years.
Canada has already spent eight years designing conditions around powers Parliament approved in 2018. The next step is simpler to describe and harder to deliver. Put the rules into force, give good businesses a workable path to institutional capital, and keep enough independent competition in the market that customers actually benefit.
Canada’s eight year delay carried a real economic toll. Banks faced approval processes that could take three to four months. Mixed fintechs could lose access to some bank or insurer investors as they expanded. Insurers had less room to sell useful technology outside financial services. Finance now says the old framework can prevent or complicate investment, limit capital and impede productivity. We can’t put a credible dollar figure on every deal, product or expansion that went another way, but the commercial cost isn’t abstract. It lands in who funds a company, what it builds next and how quickly it gets to market.
Canada has good reasons to keep banks and insurers out of unrelated commerce. Those guardrails protect stability and stop financial institutions from controlling too much of the wider economy. But a safeguard carries a cost when rules written for older business models keep constraining newer ones after Parliament has already approved change. The Competition Bureau’s fintech progress review has warned that regulatory barriers can weaken competition too. Capital won’t wait eight years for rulemaking to catch up.
Founders didn’t stop building while Ottawa worked through the rules. Banks and insurers still found ways to invest where the old framework allowed it, as Flinks, WayPay and ClaimSecure show. The 2026 proposal can widen those paths without turning strategic investment into another route to incumbent control. Eight years are gone. The better outcome now is a market where good Canadian fintechs have more ways to finance growth, commercialize useful technology and challenge the status quo.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 10, 2026 | Last Updated: Oct 28, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Payments Infrastructure And Money Movement, Regulation And Policy, Wealthtech Investing And Trading, Risk Compliance And Regtech, Sustainable Finance ESG And Financial Inclusion

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-March 13, 2026, March 14-March 20, 2026, March 21-March 27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-June 19, 2026, June 20-June 26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-July 24, 2026, July 25-July 31, 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026, August 29-September 4, 2026, September 5-September 11, 2026, September 12-September 18, 2026, September 19-September 25, 2026, September 26-October 2, 2026, October 3-October 9, 2026).
Anthropic's lease gives EverWind a committed customer for its first development phase, strengthening the commercial case for a major Canadian infrastructure investment. But financing AI compute infrastructure depends on more than tenant demand. Power availability, construction costs and grid approvals determine when that demand becomes revenue. For investors, the distinction is between securing a customer today and delivering profitable computing capacity on schedule.
Hong Kong banks now have updated supervisory guidance for deploying AI, while future rules for autonomous agents remain under discussion. Banks investing in these systems need clear ownership of decisions, reliable input data and controls that allow staff to intervene. Canadian financial institutions face many of the same questions as they expand AI into lending, compliance and customer service. The operating advantage will depend on speed and cost savings that hold up under supervisory review.
TD is using AI to clear document checks at more stages of the mortgage process, freeing staff to handle exceptions and borrower decisions. The reported time savings are substantial, but lenders still need to measure end-to-end completion times, error rates and rework. The investment pays off when faster reviews translate into funded mortgages without weaker controls.
The first deadline arrives well before the settlement switch. Brokers, custodians and asset managers now need to reconcile message formats, client instructions and exception handling across counterparties. Canadian firms trading European securities face the same operational handoffs. A short settlement cycle leaves less room to repair missing allocations overnight.
Loan syndication involves years of servicing, amendments and lender coordination after the initial funding. Handling those events on a shared record could reduce duplicate reconciliations and disputes over loan status. The same operating question sits behind shared bank blockchain infrastructure: can participants keep one reliable record without adding new integration costs? Lenders will want evidence of repeat transactions before committing more capital.
Paid investor communities can create recurring revenue for crowdfunding platforms, but the fee can't become a barrier to understanding what investors are buying. Operators need to show enough deal information before collecting membership payments and explain exactly what those fees purchase. The bigger commercial issue is trust. Platforms that sell access before demonstrating investment value risk higher acquisition costs, complaints and regulatory scrutiny. A subscription model can work, but it still has to earn investors' money.
Longer trading hours change the conditions under which orders meet available liquidity. Marketplaces and brokers need controls that work when fewer orders are on the book and prices can travel farther on small trades. The consultation gives Canadian trading firms a chance to address threshold design before extended hours become a larger operational commitment.
BNY has demonstrated that tokenized market infrastructure can support real overnight financing, not just digital settlement. For dealers, the advantage could be faster access to collateral and lower funding friction. The economics depend on custody fees, connections to other counterparties and how often the process can be repeated at scale. One completed repo proves the workflow; regular volume would prove the business case.
The partnership tackles a central obstacle for tokenized funds: reaching investors through regulated broker dealer workflows they already use. Federated Hermes brings investment products; Prometheum would provide custody, clearing and brokerage connections. Managers and intermediaries will judge the offer by distribution costs, settlement performance and investor demand, not the use of tokens alone. The first fund remains planned for 2027.
Origin gives TXSE a publicly traded bank issuer and a practical chance to compete for U.S. listings. But a listing win is only the beginning. Brokers and investors will judge the exchange by trading depth, spreads, execution quality and reliable access to market data. Those measures will determine whether other issuers see a commercial reason to follow.
Evernorth offers stock market investors exposure to a company holding a large XRP treasury without requiring them to buy XRP directly. Its shares may trade at a premium or discount to the underlying assets. Investors should weigh treasury management, operating costs and future capital decisions against the simpler alternative of owning the asset itself.
Institutions can now manage traditional market exposure through a crypto trading venue when stock and futures exchanges are closed. That's a meaningful opening for firms that trade across time zones, but 24 hour access doesn't guarantee deep liquidity or better prices. Prime brokers and market makers will compare margin efficiency, weekend spreads and counterparty risk with established derivatives markets before moving significant volumes.
RPAA registration gives payment providers a defined route to serve Canadian businesses, along with continuing safeguarding and reporting duties. Payoneer can use that standing in discussions with customers and banking partners. For competing providers, the relevant costs extend beyond registration to the controls needed to maintain it.
The restrictions change how banks price rupee hedges and how companies manage currency exposure. Dealers face cash reserve costs and tighter checks on the transactions they can accept. Corporate treasury teams may need to reassess hedging across multiple banks, especially when a cancelled contract can no longer be rebooked. The immediate commercial impact is on liquidity and flexibility, not just compliance paperwork.
Payment infrastructure is now being treated as critical digital infrastructure with direct cyber obligations attached. For operators, this moves resilience from good practice into a formal compliance responsibility. Boards and technology teams need to know which systems are designated, who owns incident decisions and whether reporting can happen fast enough when a critical payment service fails.
Frontier AI is raising the standard of evidence supervisors expect when reviewing financial institutions' cyber resilience. Boards need visibility into where AI changes their threat exposure, which vendors create concentrated dependencies and whether recovery plans still work against faster attacks. The immediate operating priorities are vulnerability management, supplier assurance, incident testing and clear accountability before failures expose gaps.
FIS is taking an AI investigation tool from development into commercial banking operations. The potential savings are substantial because analysts spend considerable time gathering records before judging an alert. But banks still own the compliance decisions. Buyers should examine audit trails, false positives and completed case volumes before relying on projected productivity gains. For Canadian providers, the competitive pressure is on evidence quality and operating cost, not merely the number of alerts an AI system can review.
Fraud intelligence is becoming shared infrastructure rather than a control each institution builds alone. TrustGraph takes a different technical route from Canada's CSAFE fraud exchange, using cryptographic matching instead of pooling customer records. The commercial advantage grows with participation: more institutions create more opportunities to identify repeat attacks before fraud reaches another account.
Fraud often crosses the boundary between a mobile account and a bank account. CSAFE gives participating firms confirmed intelligence from both sides, helping them recognize repeat attacks sooner. The financial value will come from fewer losses and investigations without blocking legitimate customers. That depends on timely, accurate contributions and disciplined privacy controls.
The penalties show how failures in alert handling, correspondent banking controls and sanctions screening can become major financial liabilities. For banking executives, the response requires more than a larger compliance budget: investigations must be timely, findings must reach decision makers and remediation must work across business lines. Investors should track the cost and effectiveness of those repairs.
USDC's designation brings a major stablecoin under closer EU oversight of capital, reserves and redemption. Circle must now manage a split supervisory relationship, while banks and payment providers gain a clearer view of which authority oversees critical financial safeguards. For Canadian stablecoin operators, the decision shows how growing scale can change supervisory obligations even after a token enters the regulated market. Compliance costs and the confidence of institutional counterparties will matter together.
Authorization gives the bank consortium an important legal foundation for issuing a euro stablecoin. It does not yet provide a token that customers can use. Banks, exchanges and payment providers will evaluate redemption certainty, liquidity and integration costs once issuance begins. Broad institutional backing could support distribution, but demand still has to be earned.
Stablecoin operators increasingly need both digital asset and payment permissions when products cross from trading into money movement. Flowdesk can now combine MiCA services with PSD2 payment capabilities inside one European regulatory structure. For firms comparing international models with Canada's stablecoin framework, the operating question is how quickly multiple regulatory permissions can translate into custody, transfers and institutional volume.
Institutional stablecoin use depends on custody, transfer permissions and access to trading venues. Standard Chartered now offers a regulated custody option for RLUSD. Its proposed LMAX integration could let clients use collateral without moving it to an exchange. The commercial benefit will depend on funding efficiency, safeguards and the costs of operating across several counterparties.
A bank issuing digital money needs to know which tokens are still valid before paying holders back. Episode Six puts that check inside the bank's ledger at the point of redemption, where an error could turn into a direct loss. The commercial question is whether this control reduces reconciliation work and fraud without slowing payment flows. Banks still have to prove the reserves exist; software checks aren't a substitute for that obligation.
Buying Saldo could give Payward direct control over more European deposit and lending services instead of relying on bank partners for every product. The agreement is not ownership yet, and regulated banking brings capital and supervision costs. Once the deal closes, investors should watch customer uptake, funding costs and whether the combined businesses improve margins.
IKB would give Crédit Agricole an established German business lending franchise and relationships it would otherwise have to build customer by customer. That creates opportunities to offer existing borrowers more services and fund loans through a larger banking group. Returns will depend on credit quality, customer retention and integration expenses after closing.
Banks need reliable customer records to lend and open accounts across borders, but moving those records creates cost and privacy concerns. This platform lets participating institutions verify information without receiving the underlying files. That could shorten onboarding and credit checks for businesses operating in both markets. The next test is how many banks integrate it, what it costs per verification and whether customers see faster decisions.
Direct payment access could change the economics of launching a fintech in South Africa. Providers would have a route to clearing and settlement without depending on a sponsoring bank for every transaction. That could reduce intermediary costs and give new entrants more control over their services. The commercial opportunity now depends on licensing requirements, connection fees and how quickly the new infrastructure can support real transaction volume.
Stablecoin funding can help payment companies keep less idle cash in multiple accounts while supporting payouts outside traditional banking hours. Visa and Inyo now have a production service, but the financial gain depends on conversion costs, liquidity and the actual timing of settlement. Banks and payment fintechs should compare those economics with their existing prefunding arrangements before assuming round the clock access will improve margins.
Payment fintechs spend time and money negotiating access to the systems that move customer funds. A simpler rulebook could reduce duplicated compliance work and make access terms easier to challenge when incumbents impose costly conditions. But consolidation alone won't guarantee better access. Founders need to examine connection charges, technical requirements and the rights available when an operator refuses entry. Those details will determine whether the reform lowers the cost of competing or mainly reduces paperwork.
Mastercard is turning its BVNK acquisition into a distribution channel for businesses that need to hold, convert and pay in both bank money and stablecoins. A single integration may lower development and reconciliation costs for fintechs. But buyers will still compare pricing, available corridors and responsibility for funds across the service. The competitive question is whether bundled infrastructure delivers better working capital management than separate providers.
Local acceptance capacity gives merchants more than another foreign payment option. It can improve authorization routing and reconciliation where domestic rules differ. Nuvei already connects payment acceptance with enterprise invoice workflows; South African access extends the territory where that infrastructure can be sold. Merchant uptake and transaction performance will decide the return.
Owning licensed payment capacity changes Polygon’s role from infrastructure supplier toward a provider that can connect digital asset transfers to conventional money. It also adds a regulated distribution component to the stablecoin payment infrastructure opportunity. Customers will judge the combined platform by supported payment routes, settlement reliability and total cost, rather than token throughput alone.
Visa has gained a formal route toward operating in China’s domestic card market, but it cannot clear local transactions yet. The next milestones are the remaining approvals and connections with issuing banks, acquirers and merchants. Market share will depend on those relationships and the cost and quality of competing with established networks.
Payment providers could face an independent route for customer complaints, beyond their internal case handling. If adopted, membership would add costs for records, escalation and disputed transactions. Canada’s proposed open banking complaint requirements address related responsibilities for participants, although they are a separate regime. Firms selling payment and stablecoin services across borders need to cost customer redress into their operating model.
Listed companies need decisions about delayed disclosure to withstand scrutiny after information becomes public. The revised grounds offer more clarity, but they do not remove the obligation to assess confidentiality and investor impact in each case. Boards and legal teams should update decision records and approval procedures rather than treating the five additions as blanket exemptions.
Public companies must align earnings presentations, investor materials and financial statement notes before the reporting change. The CSA amendments apply to issuer disclosures, while separate IFRS 18 reporting changes affect federally regulated insurers. Finance teams should reconcile definitions across published measures and underlying accounts before disclosures reach investors.
The consultation puts detailed custody, settlement and capital proposals behind ASIC’s earlier digital asset licensing roadmap. Platform operators can now compare existing controls against draft requirements and price the cost of entering Australia. Firms must distinguish their responsibility for holding customer assets from their role in executing and settling trades.
Regulatory modernization could affect how quickly new financial products reach customers and how much compliance costs smaller entrants. The consultation gives fintechs and industry associations a chance to identify rules that impose costs without improving outcomes. The real test will be whether future supervisory reforms shorten approval timelines, reduce duplication and preserve financial safeguards.
Customer screening is now subject to closer scrutiny over why banks accept or decline legitimate businesses. Institutions need documented distinctions between lawful customer activity, financial crime risk and reputational judgments. For Canadian banks with US operations, policy review and audit evidence are practical priorities. Access decisions that cannot be defended consistently can carry supervisory and commercial costs.
The new safeguards require financial product distributors to prepare for tighter supervision of public sales activity. Firms should update staff training, customer consent records and controls over where representatives approach people. The transition period creates time to make those changes before MAS applies the revised guidelines.
GIFT IFSC is putting a clear accountability line around automated trading. A firm can use more advanced models, but it can't outsource responsibility to the software or its vendor. Brokers, trading firms and technology providers now have a concrete checklist for approval, testing, surveillance and shutdown controls before they scale automated strategies.
ASIC’s loss figures put pressure on brokers that rely on frequent, highly leveraged retail trading. The proposal could affect product terms, customer acquisition and dealing revenue if adopted. Platforms should assess those consequences now, while regulators consider whether the existing protections still address the products offered to retail investors.
European asset managers need to distinguish between holding companies with strong environmental credentials and demonstrating how investor capital contributes to measurable improvements. The supervisory examples also clarify how future transition promises should be explained and monitored. Canada's recent green taxonomy and investor trust debate addresses the complementary question of which activities qualify for sustainable financing in the first place.
The FSB has given financial institutions a common reference for assessing AI controls across business lines and technology providers. Banks and fintechs can compare their existing governance, vendor contracts, model inventories and monitoring against the final practices. The commercial challenge is keeping controls proportionate as AI adoption expands without making every deployment slower or more expensive.
Retail brokers cannot treat surveillance as a technology purchase and assume compliance is handled. Alert thresholds, investigation judgments and management review determine whether suspicious trading is escalated. NCFA’s market abuse risk research also covers more complex automated trading behavior. Brokers need case files and decision trails that stand up to supervisory examination.
This week brought production stablecoin payment services, a live €150 million blockchain loan and new rules for securities settlement and financial disclosures. Canadian firms also gained overseas payment access while domestic regulators advanced trading controls and reporting requirements. For founders, the opportunity lies in replacing costly operational steps with services customers will use repeatedly. Investors should look beyond launches to actual volumes, integration costs and the obligations that follow when a product becomes financial infrastructure.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 16, 2026 | Wealth Management, Retirement Planning, Personal Finance
Planning for retirement while living in a high-cost state like New York is even more important. Housing, healthcare, taxes and everyday expenses can go up and affect retirement.
Retirement planning aligns savings, investments, income, and future lifestyle goals. So, a retirement strategy should include a person’s location, income, assets, investments and expected retirement age.
Wealth management for pre-retirees in New York City can make the process much easier by working with financial planners.
Consider potential housing expenses, property taxes, utilities, transportation, and healthcare in New York. Also account for mortgage payments, rent, and other fixed expenses when planning retirement.
Moreover, you should consider whether downsizing or paying off a mortgage could help with long-term financial flexibility. Estimate essential expenses separately from discretionary spending.
Review workplace retirement plans, including 401(k) and 403(b) accounts. Traditional and Roth IRAs offer benefits if an individual is eligible. Diversifying investments and asset classes is key when planning for retirement.
Time horizon, risk tolerance, inflation, and withdrawal needs affect investment decisions. Review contribution levels, employer matching opportunities, and beneficiary designations. A retirement portfolio should gradually reflect changing income needs as retirement approaches.
Early retirement often requires a larger savings base and a longer withdrawal period. Retiring before age 65 can affect access to Medicare and the need for alternative health insurance. Withdrawals from certain retirement accounts before age 59½ may trigger income taxes and additional penalties. Highlight the importance of maintaining accessible savings outside tax-advantaged retirement accounts.
Stress-test retirement plans against inflation, market downturns, and unexpected expenses.
Social Security benefits, pensions, investment income, and retirement account withdrawals may be taxed differently. New York State usually provides a qualifying exemption for certain pension income for eligible taxpayers aged 59½ or older, subject to statutory limits and conditions.
Note that qualifying Social Security benefits are generally exempt from New York State income tax. Verify state and local tax obligations based on their residence and income sources.
Withdrawal sequencing and tax planning can influence how long retirement assets last.
Professional guidance helps coordinate investments, retirement income, tax considerations, and estate planning. Financial advisors for retirement planning can help develop a personalized strategy.
Understand an advisor's qualifications, fee structure, fiduciary obligations, and compensation model. Ask how often their plan will be reviewed and updated. Professional guidance can be particularly useful during major transitions, such as selling a business, receiving an inheritance, or preparing to leave full-time employment.
Looking for a financial planner in Brooklyn? Prestique Wealth focuses on professional guidance tailored to local circumstances.
Here is a retirement planning checklist to help you.
Retirement planning is an ongoing process, not a one-time calculation.
Effective retirement financial planning combines savings, investment management, tax awareness, and realistic budgeting. New York residents should account for local living costs and personal retirement goals. Revisit your plans as your circumstances and financial markets change.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 16, 2026 | Market Activity | Digital Banking, Lending Infrastructure, Embedded Finance
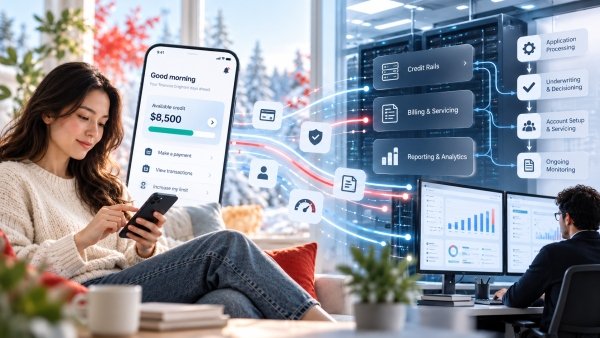
On October 14, 2026, Canadian fintech KOHO selected LoanPro's lending platform to support its next financial products across Canada. LoanPro will provide billing, servicing and reporting, while KOHO retains control of its mobile app and product design. The arrangement gives KOHO specialized credit infrastructure as it expands beyond everyday spending and savings into a broader range of financial products.
Founded in 2014, KOHO has served more than 2.5 million Canadians, according to the announcement. Its current services include credit building, instalment payments, cash advances and a revolving line of credit. Supporting these products requires more than a customer interface. KOHO needs systems that can manage repayment terms, account balances and servicing requirements as its credit offering grows.
KOHO Chief Product Officer Rusen Baragiola wants technology that can accommodate new financial products without limiting how the company designs them. LoanPro's platform provides configurable billing, account servicing and reporting, allowing KOHO to develop products within its own app while relying on specialist software to manage the underlying credit accounts.
"We chose LoanPro for the flexibility to bring new products to market quickly and responsibly."
KOHO already offers different repayment arrangements. Its Pay Later service allows eligible customers to divide purchases of up to $1,000 into payments over three, six or nine months. Its revolving line of credit allows borrowers to access funds as needed while paying interest only on the amount used. Each product requires its own billing rules, payment records and account management processes.
The LoanPro agreement also addresses a Canadian operating requirement. Credit products must accommodate applicable provincial rules, including those in Québec. LoanPro's configurable platform gives KOHO flexibility to adapt product terms and servicing processes across jurisdictions while maintaining a consistent experience in its app. For a company serving customers nationally, it's important as it introduces products with different repayment structures and eligibility requirements.
KOHO's existing line of credit provides a useful example of how the company works with lending partners. Eligible customers can access between $1,000 and $15,000 through Fora Credit, which handles underwriting, approval, funding and servicing. KOHO provides the customer relationship and digital access to the product.
How KOHO's lending responsibilities are currently divided:
| Company | Confirmed role | Product or arrangement |
|---|---|---|
| KOHO | Customer app, customer relationships and financial product design | Existing financial services and planned LoanPro supported offerings |
| LoanPro | Billing, credit servicing technology and reporting | New KOHO financial products under the October 2026 agreement |
| Fora Credit | Underwriting, credit approval, loan funding and servicing | Existing KOHO Line of Credit, offering $1,000 to $15,000 |
Sources: KOHO's published line of credit documentation and the October 14, 2026 LoanPro partnership announcement. The LoanPro agreement covers new offerings; it does not establish a change to Fora's existing responsibilities.
Fora is part of Toronto fintech lender Propel Holdings, which also operates the Freshline lending platform backed by a US$60 million financing agreement. KOHO already works with Fora to provide its line of credit, while LoanPro brings additional billing, servicing and reporting technology to support KOHO's next credit products. The two relationships serve different purposes within KOHO's lending business.
KOHO has served more than 2.5 million Canadians since 2014, giving it an established audience for new credit products. By keeping control of product design and the customer experience, KOHO can introduce different repayment options while relying on specialist partners for lending technology and operations.
KOHO's lending strategy raises a question about who controls the economics of consumer credit. A fintech may own the customer relationship, but its ability to set credit terms, approve borrowers and earn lending revenue depends on how responsibilities are divided with its partners. As KOHO expands, those arrangements could matter more to its competitive position than the technology powering the loans.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016