




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


March 27, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Regulation And Policy, Payments And Market Infrastructure, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026).
The RBA is moving past short pilots. The focus now is how tokenised money works with existing settlement systems and what holds up under real use.
The SEC is narrowing one regulator facing CAT access path in the name of cost savings while keeping other query methods in place. That doesn't change trading rules, but it can change how efficiently regulators search market activity and build surveillance cases, and to that extent there are some concerns around reduced oversight.
Fully paid lending goes from exemption based programs to a standard rule set. Dealers need to update inventory funding structures and controls before the effective date.
Tokenization is now being discussed inside the core U.S. capital markets policy process, with major market infrastructure and exchange voices at the table. That raises the odds that tokenized securities will be treated as a market structure question tied to trading, clearing, settlement, and custody, not only as a digital asset issue.
Lynn Martin, President, NYSE Group: “As we explore how tokenization can enhance capital markets, it is critical that new infrastructure is developed in a way that preserves the trust, transparency, and protections investors expect. Securitize brings deep experience in digital asset infrastructure and transfer agency, making them a strong partner in helping design this next generation of market structure.”
India is moving from payment expansion to payment control. Fraud liability, cyber resilience, cross border authorisation, and switching now sit closer to the centre of the next build cycle for banks, payment firms, and fintech infrastructure providers.
Visa is getting into the infrastructure layer. Privacy has been one of the main blockers for banks and large financial institutions using shared blockchain systems. If that barrier starts to fall, onchain payments, settlement, and treasury activity can move closer to core financial market infrastructure.
FMI oversight expectations set the operating floor for payments and clearing infrastructure, which can flow through to participant requirements, vendor controls, and resilience planning.
This brings tokenized cash into live institutional money movement. It's a major Canadian bank using tokenized cash to support real margin, collateral, and settlement flows on a continuous basis. Tokenized money is moving deeper into market infrastructure and gives regulated institutions a way to move value when markets need it 24/7, not only during banking hours.
Deloitte and Stablecorp are building integration paths for financial institutions to use QCAD inside existing systems. The work targets clearing, treasury, and cross-border flows, but no deployments or pilots have been confirmed yet. Treat this as a signal that stablecoin infrastructure is being wired into bank workflows ahead of regulatory clarity.
This closes a multi phase refresh and sets a new baseline for dealer compliance interpretation across UMIR topics, which can flow into policy mapping, training, and vendor rule logic.
Bill C-15 puts stablecoins, payments, and consumer-driven banking under a more unified central bank structure. Firms now need to plan for supervision across digital money and data-sharing models, not treat them as separate tracks.
Event contracts are now included in a defined Canadian dealer framework. Firms need to clear product design, compliance, and notification before going live.
AI assisted authorisations and automated reporting feeds can shorten approval timelines and change how supervision picks up issues from live data.
Sarah Pritchard, Deputy Chief Executive, Financial Conduct Authority: “We want to see more people getting supported, who aren’t currently, and a market that innovates and offers tailored services to meet differing consumer needs.”
Dealers and fintech vendors that support eDiscovery, recordkeeping, surveillance, and investigation response workflows now have a clear CIRO baseline for data handling, metadata preservation, and production process design.
Courts are beginning to test whether engagement led product design itself can create liability at scale. If that theory survives, the impact reaches beyond social media. Any digital product that depends on compulsive use patterns, especially where minors or vulnerable users are involved, faces legal scrutiny and compliance costs.
August 6 update: A New Mexico court ordered Meta to establish a US$567M abatement fund, bringing the financial remedies in the case to US$942M, and imposed youth-safety requirements covering age assurance, teen usage and notifications, adult-minor contact controls and AI-chatbot interactions involving minors. Meta plans to appeal.
As more execution flows move through automated and intermediated channels, CIRO is making it clearer who is responsible, how orders must be marked, and what supervision has to look like. That raises the operating standard for dealers, trading desks, legal and compliance teams, and firms providing marketplace access. Electronic access remains open, but responsibility for supervision, order marking, and control cannot blur as more parties exist between the client and the marketplace.
This raises the risk that sports prediction markets face a direct statutory limit before the category settles into a stable regulatory path. Congress is now testing whether these contracts belong inside federal market infrastructure or back inside state gambling rules. Important for exchanges, prediction market operators, legal teams, and investors betting on event contracts as a durable product category.
This series puts AI governance in focus for banks and fintechs, especially around model risk, cybersecurity controls, and how supervisors assess AI driven decisioning inside core workflows.
China is using tax data, regulated data sharing, and specific technologies to push more SME credit through banks. That is a lending infrastructure signal, not just a blockchain headline.
Regulators are setting clearer boundaries, and infrastructure is moving into production at the same time. That combination raises the cost of getting it wrong and shortens the window to get it right. Teams need working controls, real vendor oversight, and systems that hold up under load before scaling anything customer facing. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
March 26, 2026

Image: Pixabay/tourque
There has been considerable discussion in recent years about gaming licenses from the Malta Gaming Authority (MGA) and whether they still hold value in an increasingly regulated world. With Canada’s provincial markets moving toward their own regulatory frameworks, some players question whether this license matters anymore. The possibility of more provinces following Ontario’s lead and introducing their own licensing systems has led some to believe that international MGA licenses will soon become unnecessary for Canadian players.
However, the reality is more nuanced. In practice, MGA licensed casinos remain some of the most commonly used and trusted platforms among Canadian players. For those looking into their options, websites like MGAcasinos.ca are dedicated to helping players find the best MGA casino sites in Canada. This website offers a list of online casinos that have a proven track record of player protection, fair gaming standards, and high-quality gaming features.
In this article, we’ll take a closer look at why the MGA license still holds strong value in the Canadian market and why so many players continue to prefer it across Canada.
The MGA is the government body responsible for regulating gambling in Malta. It was established in 2001, and Malta became one of the first countries in the European Union to formally regulate online gaming back in 2004. That head start gave the regulator decades to build out one of the most respected licensing frameworks in the industry.
It operates under Malta’s Gaming Act, which came into full effect in August 2018 after a major overhaul of the country’s gambling laws. Today, it oversees both land-based and online operators, sets the standards they must follow, and has the authority to issue fines, suspend licenses, or cancel them altogether when operators fall short.
What sets the MGA apart from lesser-known licensing bodies is the level of scrutiny involved. Operators must pass background checks, demonstrate financial stability, meet technical requirements, and implement responsible gambling measures before they can receive a license.
Ongoing compliance is expected, not just during the application stage. In practice, this means licenses are not automatically renewed. Recent figures reported by Next.io show that multiple operators applied for renewals, and not all were approved, reflecting the regulator’s continued oversight and willingness to deny extensions where standards are not met.
Canadian players have a lot of options when it comes to online gambling, but MGA licensed casinos consistently stand out. The reasons go beyond simply being internationally licensed. Here’s a clear breakdown of why these platforms are so popular among Canadian players:
Outside Ontario, most Canadian provinces don’t have fully regulated markets for private online casinos. Provincial lottery corporations offer their own platforms, but these options are limited. Additionally, most provinces haven’t established a licensing system for private operators.
As a result, many players turn to internationally licensed sites for more choice and flexibility. This is why Canadian players frequently encounter MGA licensed casinos, as these platforms are widely available and well-established, making them a natural choice for players seeking quality online gaming.
The MGA has been around for many years now and is well known among online casino players in Canada. This long presence has helped build familiarity and trust, so many players already recognise what to expect from it. Because of that, these licensed casinos are often preferred over other jurisdictions, not just for compliance reasons, but because players feel confident using platforms they already know.
Licensed casinos under the MGA have to follow strict player protection rules designed to keep players safe. This includes:
MGA casinos partner with some of the biggest software providers in the industry, including NetEnt, Microgaming, and Evolution Gaming. This means Canadian players have access to thousands of high-quality slot titles, table games, and live dealer experiences. The variety and innovation available at these casinos often surpass what provincial platforms can offer.
Canadian players benefit from a wide range of payment methods at MGA casinos, including:
Withdrawals are often faster, and the variety ensures players can deposit and play in ways that are convenient and secure.
MGA casinos are known for offering competitive welcome bonuses, free spins, cashback, and loyalty programs. Compared to provincial platforms, these promotions are generally more varied, giving players extra value and incentives to try new games.
Many MGA licensed casinos are run by established international brands that seek long-term growth rather than short-term profits. Because the MGA is a highly respected regulator, this attracts reputable companies, which in turn gives Canadian players access to stable, trustworthy platforms. For players, this means these casinos are less likely to disappear suddenly and more likely to offer consistent service, fair games, and reliable payouts over time.
The MGA makes it straightforward to verify whether a casino actually holds a valid license. Here is how to check:
The Malta Gaming Authority has built a reputation as one of the more rigorous online gaming regulators in the world, and that is why Canadian players frequently encounter MGA licensed casinos when looking for options outside provincial platforms.
These casinos offer Canadian players a winning combination of safety, fairness, and variety. With strict regulatory oversight, secure transactions and protections for players, it is no wonder these casinos are so popular. Whether you are a casual gamer or a high-stakes player, exploring MGA licensed platforms can help you find trusted options and enjoy peace of mind while playing.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 26, 2026 | NCFA Fintech Market Activity | Banking And Credit, Digital Assets And Tokenization
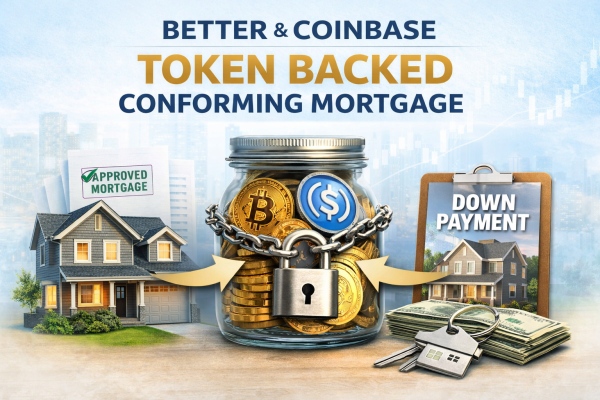
On March 26, 2026, Better and Coinbase launched the first token backed conforming mortgage. Qualified borrowers can pledge Bitcoin or USDC to fund a cash down payment while still taking out a standard mortgage that meets Fannie Mae rules. The structure lets borrowers use digital assets without selling them first and without automatically triggering a taxable sale event.
The product targets a large and growing borrower base. Better and Coinbase put the addressable market at 52 million Americans who own digital assets, equal to 20% of American adults. They also mention quite an age split, with 45% of younger investors holding crypto versus 18% of older investors. That age gap means it's much harder for younger buyers to meet traditional down payment cash requirements, yet many already hold part of their savings in digital assets.
There are no margin calls and no required top ups if Bitcoin falls in value. Price moves alone do not trigger liquidation. Collateral comes into play only if a borrower becomes 60 days delinquent, under the same treatment applied to standard conforming mortgages. Borrowers using USDC can also earn rewards on pledged balances, which may offset mortgage payments and lower the net effective rate.
The buyer profile is also broader than a luxury crypto niche. Better and Coinbase said 67% of token holders are 45 or younger and 26% earn less than US $75,000 a year. They also pointed to Redfin data showing 12.7% of Gen Z and Millennial homebuyers have already sold tokenized assets to fund a down payment, versus 3.5% of Gen X and 0.5% of Baby Boomers.
Digital assets are now included in standard mortgage structure, not just a trading or investment account. Token holdings now help fund a conforming mortgage down payment without forcing a sale first. As this model grows, digital assets will look less like something borrowers need to liquidate and more like collateral lenders may be willing to work with.
Better and Coinbase also plan to expand eligible collateral over time to include tokenized equities, fixed income, and tokenized real estate assets. If that happens, the story will not stop at mortgages. It will continue to proliferate into which consumer lending products can absorb token backed collateral and under what terms.
If digital assets can now help fund a conforming mortgage, which standard lending products could be next to accept token backed collateral?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 25, 2026 | NCFA Insight | Regulation And Policy, Capital Markets And Market Infrastructure
Sports volume built the business. Now rules, surveillance, and product limits will decide who lasts. On March 23, 2026, a bipartisan Senate bill moved to ban sports and casino style contracts on CFTC registered prediction market venues. The Senate release said a March Madness winner contract had already passed $100M in trading volume and that Super Bowl prediction market volume topped $1B in 2026.
Those numbers explain why prediction markets are now under direct pressure from lawmakers. Prediction markets are no longer fringe. They now sit in a fight over who regulates them, which contracts stay allowed, and whether the business still works under tighter rules.
Sports helped prediction markets reach a wide audience fast, but that same growth put them in direct competition with state regulated sportsbooks and tribal gaming interests. The Prediction Market Senate bill to ban sports contracts is aimed straight at that overlap. It would prohibit any CFTC registered entity from listing contracts that closely resemble a sports bet or a casino style game. If it advances, sports contracts would be the first part of the business to take a hit. That in itself wouldn't kill prediction markets, but it would force a reset around contracts that look more like economic, financial, or commercial forecasting and less like entertainment wagering.
Sports contracts brought scale, attention, and league partnerships. NCFA looked at that earlier when the NHL partnered with Kalshi and Polymarket. Sports now look like the part of the business most likely to trigger a stronger federal and state response.
Polymarket and Kalshi tightened their controls on the same day. On March 23, Polymarket tightened its market integrity rules across both its DeFi venue and its CFTC regulated US exchange. The updated rules ban trading on stolen confidential information, illegal tips, and outcomes a trader can influence.
Kalshi added candidate and athlete trading bans covering political candidates, athletes, referees, coaches, and team staff, and introduced a whistleblower feature to tighten insider risk controls.
These aren't minor changes. They prove Kalshi and Polymarket understand that insider risk is now a live issue. Prediction markets want to be treated as financial infrastructure, but financial infrastructure has to show it can police insiders, document rules, and respond fast when abuse appears. NCFA covered that tension earlier when prediction markets started pricing geopolitical events.
Canada is taking a narrower approach. The Globe and Mail reported today that Wealthsimple cleared a regulatory hurdle to offer forecast contracts in Canada, but only for economic indicators, financial markets, and climate trends. Sports and election contracts are out. Wealthsimple is the second firm to receive this approval in Canada, after Interactive Brokers Canada.
Interactive Brokers Canada has positioned contracts around government, economic, finance, and climate events, not sports books in a different wrapper. The product is already live in Canada on that basis.
Wealthsimple now brings local retail distribution, stronger brand reach, and a better chance of testing whether forecast contracts can find a market here without leaning on the sports volume that pushed the US fight into the open.
Can a prediction market still grow once sports contracts face a ban, insider screening gets tighter, and compliance costs rise? Some firms may adapt by leaning into macro, rates, inflation, climate, earnings, and other information markets. Others may find that the most profitable contracts were also the ones most likely to trigger a crackdown.
The CFTC is also reviewing the rules. On March 12 2026, the CFTC opened an Advance Notice of Proposed Rulemaking on prediction markets and asked for public comment on which event contracts may be contrary to the public interest, how current rules apply, and what changes may be needed. That means this fight is not limited to one Senate bill or one week of headlines. The federal rule in the U.S. is now under review.
For Canadian dealers, fintechs, and market operators, there is room to build forecast products here, but the lane is narrower than in the US.
Prediction markets already proved they can attract users and volume. The next test is whether prediction markets can still grow once product limits tighten, regulators draw a harder line around what is allowed, and compliance demands rise.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 23, 2026
Image: Pexels/Towfiqu barbhuiya
Most people say they want more features, but what they usually reward is a system they can read. Trust rarely begins with maximum capability. It begins with knowing what the product is doing, what choices are available, and what happens after each action. That matters even more when a product handles money. A clean structure, a visible rule, and feedback that arrives right after the action can build more confidence than a long list of extras that only appear useful on paper.
Researchers increasingly describe digital trust in similar terms. In an open-access survey, transparency is defined as open and clear information about how a service functions, alongside auditability and traceability, which is another way of saying users trust systems they can inspect, rather than merely admire from a distance. That idea helps explain why simpler, more legible products often feel more credible than feature-heavy ones that demand constant interpretation. It also reframes transparency as a working property of the product, not a slogan added after launch.
One of the clearest ways to see this principle is inside rule-based games, where trust does not come from vague promises. It comes from stable mechanics, familiar options, and immediate feedback. A practical example is when online players play blackjack with bitcoin. Many sites list multiple versions, including classic blackjack, European blackjack, multi-hand blackjack, and live dealer tables, but the core objective stays steady: make decisions within a known structure and see the outcome without delay.
That consistency matters. When the rule space stays readable, people spend less energy decoding the environment and more energy understanding cause and effect. Seen that way, trust grows because the system behaves the same way twice, then 10 times, then 50 times. If you want to play blackjack with bitcoin after learning the basics, the value is not novelty. It is the chance to observe how confidence forms when actions are bounded, options are clear, and each result connects cleanly to the choice that came before it.
A short video on how memory limits in gaming shaped level design in the past carries the same idea forward because early console designers had so little memory that every tile, sprite, sound, and obstacle had to justify its place. The result was not just smaller worlds. It was clearer communication. Players learned one rule, then saw it repeated and remixed until the system felt readable. That is still a useful model for digital products now. Constraint often builds confidence because it strips away decorative noise and leaves the user with a structure they can understand.
This is where many digital products get the balance wrong. Teams assume trust comes from abundance, so they keep adding tabs, modes, settings, prompts, badges, and layered explanations. Some of those additions may be useful later, but they often arrive before the base logic is clear. The user then has to interpret the product before they can use it. That is a costly first impression. It also creates a subtle mismatch between what the interface promises and what the user can confidently predict, which is often where doubt begins.
Legibility works differently. It reduces the mental workload. It lets people answer a few quiet questions almost immediately: What can I do here? What happens if I do it? What changed because I acted?
When those questions become easy to answer, the product starts to feel honest. It is not trying to wow the user. It is showing its logic through behavior. That honesty compounds over time because repeated clarity is easier to remember than occasional brilliance.
That same theme shows up in broader discussions of transparency in digital entertainment and finance-adjacent systems, where clearer signals and measurable parameters are increasingly treated as part of the experience rather than a technical afterthought.
Visible rules do not mean shallow systems. They mean systems that reveal their logic early enough for users to form a stable mental model. Once that model is in place, depth feels earned instead of confusing. More features can still matter, but only after the foundation is clear. Otherwise, added capability behaves like noise. A product does not need to expose everything at once. It needs to make each next decision understandable enough that the user wants to continue.
That is why transparent rule sets often earn confidence faster than feature bloat. They reduce doubt at the exact moment doubt is highest. They tell users, in effect, this is how the system works, this is what your options mean, and this is how outcomes connect to inputs. In a crowded market, that kind of clarity is not cosmetic. It is operational. And it is increasingly supported by empirical work showing that greater recommendation-system transparency can raise consumer trust by improving perceived effectiveness and lowering discomfort.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 20, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Regulation And Policy, Payments And Market Infrastructure
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026).
This adds a new regulated counterparty node for banks, payment partners, and fintech vendors that use CIRO membership as a gating factor for onboarding, integrations, and supervised operating scope.
This puts fund distribution onchain with rules built into the asset. Transfers can enforce who can hold and trade without separate manual checks. That changes how funds issue, manage investors, and handle transfers. It points to tokenized fund infrastructure moving into live use, not pilots.
This affects crypto trading platforms, market makers, treasury teams, and regulators watching stablecoin market structure in Canada. Lower margin on eligible inventory can improve capital efficiency and balance sheet use, but only inside a tighter control framework. It means regulated treatment of stablecoins is moving deeper into prudential design, not just disclosure and registration.
A core global index now trades outside exchange hours. Price formation can start on crypto venues before futures markets reopen, which puts pressure on where liquidity shows up first. If activity builds on chain, traditional venues risk reacting instead of leading. For brokerages, exchanges, and market infrastructure providers, this is not theoretical. Firms need to decide whether to support 24/7 access, how to manage risk when markets never close, and how to compete with venues that remove time and geographic limits.
Crypto issuers, exchanges, custodians, brokers, investors, and token builders now have a clearer US reference point for token design, disclosures, and jurisdiction planning. The practical implication is significant. Firms exposed to staking, airdrops, wrapped assets, stablecoins, or token distribution models can reassess compliance, product structure, and market access strategy with more precision across SEC and CFTC lines.
This is for banks, lenders, treasury teams, and fintechs that rely on bank balance sheets and bank distribution. Capital rules affect lending capacity, pricing, and risk appetite. A lighter or more targeted framework can change how banks allocate capital and where they are willing to compete.
Banks facing margin pressure, conduct costs, and weak returns are under more pressure to lower their operating base faster. The practical implication for lenders, fintechs, and banking vendors is that AI and automation are moving from pilot projects into cost and staffing decisions. Firms that can automate servicing, operations, and control workflows without weakening customer outcomes or compliance will be in a stronger position.
This gives UK facing fintechs and suppliers a cleaner map of where supervisors focus and where firms should spend compliance and product time. Payments, retail banking, consumer finance, and wholesale market firms can now align internal control roadmaps to sector specific priorities instead of broad portfolio letters, which tightens how boards and senior managers justify investment decisions.
Federal procurement remains difficult for new entrants to access, with complexity and restrictive design favouring repeat suppliers. At the same time, the report outlines clear changes that could open participation, improve competition, and expand access for fintech, govtech, and smaller vendors seeking to sell into government.
China is widening the distribution base for state digital money inside the banking system. Analysts see the bigger role in cross-border settlement and in building a payments channel that's outside dollar-based infrastructure such as SWIFT. China is pushing public digital money deeper into bank distribution while closing space for private stablecoin models.
This expands direct access for credit unions that want to build or buy modern payment capabilities. Credit unions, processors, and fintech partners can now plan for real system participation, not just eligibility on paper.
This is for banks, cross-border payment firms, remittance providers, treasury teams, and stablecoin infrastructure players. Stablecoin payouts are moving closer to standard bank payment flows instead of sitting outside them as a separate integration project. That lowers friction for bank adoption and puts more pressure on legacy cross-border payout models.
Mastercard is building direct control over how funds move between bank accounts and stablecoin systems. That changes routing, pricing, and who captures value in cross border and treasury flows. For fintechs, payment products will increasingly need to support both fiat and digital settlement paths in the same workflow. For banks, this puts more pressure on correspondent banking and other legacy cross border revenue lines.
This changes how investor harm connects to enforcement outcomes. Dealers, registrants, and their vendors now need tighter client records and cleaner evidence trails because the process depends on what harmed investors can prove and what firms can produce quickly and accurately when claims arrive.
This lowers reporting cost and workload for smaller public companies. It changes how often new financial data enters the market. Investors and data platforms will have less frequent updates. For issuers, this improves the economics of staying public. If adopted more widely, it moves Canada toward a lighter reporting model for venture markets.
Industry participants are pushing to remove limits that keep tokenized market infrastructure in pilot mode. That pressure targets how quickly the EU can move from controlled testing toward scalable digital asset markets.
Tokenized securities into the core of exchange trading. They will trade the same way as regular shares, on the same book, with the same symbol and rules. No separate venue, no parallel system. It removes a major barrier with tokenization now aligned with the same clearing, settlement, and surveillance systems as the rest of the market.
A forward flow commitment supports predictable loan takeout capacity, which can stabilize origination volume when bank balance sheets tighten or pricing changes.
Public companies, investors, analysts, and fintech platforms that rely on earnings data will face longer gaps between official disclosures. Less frequent reporting reduces the flow of standardized financial data into the market. Firms that can generate alternative data, continuous signals, and independent performance insight will have an advantage as reliance on scheduled earnings reports declines.
When one of India's largest fintech payments company pauses an IPO, it tells founders, investors, and late stage boards that the public market window remains fragile. That affects valuation expectations, liquidity planning, and timing for other fintech listings.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 19, 2026 | NCFA Market Activity | Digital Assets
On Mar 18, 2026, licensed S&P 500 perpetual trading went live on Hyperliquid through Trade[XYZ]. The product gives eligible non US investors 24/7 access to leveraged long or short S&P 500 exposure without expiry. A core global equity benchmark now trades onchain 24/7.
S&P says its linked ecosystem drives $1T daily trading across futures, options, ETFs, and structured products. Moving that benchmark into a perpetual format allows liquidity to form before traditional sessions open. Early demand for the product already looks real. Decrypt reported $10M open interest shortly after launch, while S&P’s release says Trade[XYZ] markets on Hyperliquid have already cleared $100B volume since October 2025 and are running at more than $600B annualized.
Price discovery no longer has to wait for markets to open. If more benchmark trading starts off hours on crypto venues, traditional exchanges risk following market moves instead of leading them. Even a modest change in where liquidity shows up first can change how volatility spreads across markets.
Investors now have a route to benchmark exposure at any hour, across borders, on a venue built for continuous trading. That changes expectations around access, monitoring, and response time for exchanges, brokerages, data analytics and risk teams. It also raises risk with reports that the product can offer leverage up to 50 times, which means off hours trading can bring sharper liquidations and sweeping moves when order books are thin.
The global implication is bigger than one listing. A major index owner has opened a new channel for benchmark access on chain. That puts pressure on incumbents that still depend on fixed sessions, regional access, and legacy infrastructure. If this model gains traction, exchanges will need to defend their role not just on liquidity depth, but on speed, availability, and product reach.
Canadian fintechs, dealers, market infrastructure firms, and regulators should pay attention to how benchmark access is changing. If clients start expecting round the clock exposure and faster market response, organizations that stay tied to old windows may lose ground. Firms that build around new access patterns, stronger risk tools, and better market visibility will have a chance to capture more of the next layer.
This is not just a crypto wrapper on a known index. It is an early sign that benchmark distribution is starting to move onto new rails. The firms that adapt early can help shape where liquidity, data, and customer activity go next.
The next phase will depend on where liquidity builds and how quickly institutions respond. If trading depth increases on these venues, more benchmarks, sectors, and asset classes will follow into perpetual formats. That would push exchanges, clearing systems, and regulators to respond to a market that no longer operates in sessions. However, if liquidity remains thin, these products will stay a niche trading layer. The open question is how fast global capital markets will adjust to always on access?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016