




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Jun 14, 2026
Family-owned businesses across Canada offer a strong opportunity for entrepreneurs because many are already profitable, trusted locally, and ready for ownership transition. Instead of starting from zero, buyers can acquire an established business with customers, staff, systems, and reputation already in place, especially as more owners consider retirement or succession.
Family-owned businesses play an important role in Canada’s economy. They often operate in local communities for years or even decades, serving loyal customers and building strong reputations through consistent service and personal relationships. Many are owner-operated businesses where trust, reliability, and long-term commitment matter just as much as the products or services they provide.
For buyers, this creates a significant advantage. A family-owned company in Canada may already have an established customer base, experienced employees, dependable supplier relationships, equipment, and stable revenue. It may also benefit from a recognizable local brand and years of goodwill within the community. These are valuable assets that usually take considerable time and investment to develop from scratch.
For entrepreneurs researching acquisition opportunities, Canadian business for sale on Yescapo can be a useful starting point for finding established companies with existing operations, customer relationships, and market history. Instead of buying only physical assets, buyers gain access to business knowledge, working systems, and relationships that have often been built over generations.
This is particularly important in industries where reputation drives success. Local retailers, construction companies, restaurants, service providers, and manufacturing businesses often rely on repeat customers and word-of-mouth referrals. A well-established family business may therefore offer a competitive position that would be difficult and expensive for a new startup to achieve.
One of the biggest opportunities in Canadian family businesses comes from succession. Thousands of owners are approaching retirement after spending decades building successful companies, yet many do not have family members interested in continuing the business. Children may choose different careers, relocate, or simply prefer not to take on the responsibilities of ownership.
As a result, many profitable businesses enter the market despite having healthy financial performance and loyal customers. They are being sold not because they are struggling, but because the owner wants to retire, reduce day-to-day responsibilities, or ensure the company continues under new leadership.
For entrepreneurs, this creates a unique entry point into business ownership in Canada. Buying a family-owned business with established operations can provide immediate access to customers, revenue, trained staff, and existing systems while avoiding many of the challenges involved in launching a company from zero.
Understanding the seller’s motivation is an important part of the process. In succession transactions, owners often care deeply about preserving the company’s reputation, protecting employees, and maintaining relationships with long-standing customers and suppliers. Buyers who respect that legacy and present a clear plan for the future may find it easier to negotiate a successful acquisition and ensure a smoother transition after the sale.
Starting a new company usually means building everything from the ground up. The founder must test demand, find customers, create systems, hire staff, develop supplier relationships, and survive the early stage when cash flow is uncertain.
Buying a family business in Canada offers a different path. The buyer can study real financial records, customer history, contracts, equipment, employee structure, and market position before making a decision. This makes the process more practical and less based on assumptions.
A startup may offer full creative freedom, but it also carries higher uncertainty. A family business may come with older systems or traditional ways of working, but it also provides an existing customer base and proven business model.
For many buyers, the question is simple: why build market trust from zero when an established business for sale in Canada may already have it?
Family businesses are often attractive because they are built around long-term relationships. Many have repeat customers, local recognition, supplier trust, and employees who understand the business well. This can make the transition easier for a new owner.
Another advantage is stability. Many Canadian family businesses operate in practical sectors such as trades, retail, food, manufacturing, distribution, professional services, hospitality, and local services. These businesses often solve everyday needs rather than depend on trends.
A buyer may also find hidden growth potential. Some family businesses are profitable but underdeveloped digitally. They may have weak websites, limited social media, no online booking, outdated branding, or little paid advertising. A new owner can modernize the business without changing its core.
This is why many investors search for profitable businesses for sale Canada listings. They want companies that already work, but still have room to grow.
Family-owned businesses can be found across many industries and provinces. Some operate in large cities such as Toronto, Vancouver, Calgary, Montreal, and Ottawa. Others are based in smaller communities where local trust is especially important.
Common examples include restaurants, cafés, bakeries, convenience stores for sale, construction companies, repair shops, cleaning businesses, accounting firms, dental or wellness clinics, manufacturing companies, logistics businesses, landscaping companies, and specialty retail stores.
Buyers often look for businesses that are simple to understand and have steady demand. A local business for sale Canada opportunity may be attractive if it has repeat customers, reliable employees, clean financial records, and clear room for improvement.
Businesses with recurring revenue can be especially valuable. Examples include maintenance companies, B2B services, subscription-based services, commercial cleaning, bookkeeping, and companies with long-term contracts.
Retiring business owners are one of the main reasons family business transition is becoming important in Canada. Many owners have strong companies but no clear successor. They may be ready to step back, but they do not want the business to disappear.
This can create a more flexible acquisition process. Some sellers may agree to stay involved during a transition period, introduce the buyer to customers and suppliers, and train the new owner. This helps protect business continuity.
For buyers, this is valuable because the seller’s knowledge is often one of the most important assets in a family business. Understanding customer relationships, staff dynamics, supplier terms, and daily operations can reduce risk after the sale.
A good transition plan can make the difference between a smooth acquisition and a difficult one. The best deals usually include clear handover support, communication with employees, and a plan for preserving customer trust.
Before buying a family-owned business, due diligence is essential. The buyer should review financial statements, tax records, revenue trends, profit margins, debts, leases, supplier agreements, employee contracts, equipment, inventory, licences, customer concentration, and legal issues.
It is also important to understand how dependent the business is on the current owner. Some family businesses rely heavily on the founder’s personal relationships. If customers only trust the owner, revenue may fall after the sale unless the transition is handled carefully.
A buyer should also check whether family members work in the business and what will happen after the acquisition. Staff roles, responsibilities, salaries, and expectations should be clear before the deal is completed.
Buying an established business in Canada can be a strong opportunity, but only if the buyer understands the real numbers, the risks, and the operational structure.
Many family businesses have strong foundations but outdated systems. A new owner can often grow the company by improving marketing, technology, pricing, customer service, and operations.
For example, a local service company may have loyal customers but no strong online presence. A buyer could improve the website, SEO, Google Business Profile, paid ads, online reviews, and booking systems. These changes can increase leads without changing the core service.
A retail business might benefit from e-commerce, better inventory management, updated branding, or stronger social media. A B2B company could grow by improving sales processes, customer follow-up, and recurring contracts.
The opportunity is not always about changing the business completely. Often, it is about keeping what works and modernizing what holds the company back.
Many buyers assume they need the full purchase price in cash, but business acquisition Canada deals can be structured in several ways. Buyers may use personal savings, bank financing, investor capital, seller financing, or a combination of these.
Seller financing can be especially relevant in family business succession. This means the seller allows the buyer to pay part of the price over time. It may help the buyer complete the deal and give the seller confidence that the new owner is committed to the business.
Some deals also include an earn-out, where part of the final payment depends on future performance. This can be useful when the seller and buyer need to bridge a valuation gap.
Clean financial records make financing easier. A profitable small business Canada opportunity with strong documentation is usually more attractive to lenders and investors than a business with unclear accounts.
Family businesses can be excellent acquisitions, but they are not risk-free. Some may have outdated systems, informal agreements, weak financial reporting, or operations that depend too much on the founder.
There may also be emotional complexity. A family business is often personal to the seller. Decisions about employees, branding, customers, and legacy may matter deeply. Buyers need to handle the process with respect and clarity.
Another risk is hidden underinvestment. Some owners delay upgrades before selling. Equipment, premises, technology, or staffing may need improvement after acquisition. Buyers should factor these costs into the purchase price.
The best approach is practical: verify the numbers, understand the people, check the contracts, and plan the transition carefully.
Buying a family-owned business in Canada can be a strong strategy for entrepreneurs who want an established company rather than a startup. It offers access to customers, revenue, staff, systems, and local reputation from the beginning.
This strategy is especially attractive for buyers who are good at operations, marketing, modernization, and relationship management. They can take a business that already works and make it stronger.
However, it is not the right path for everyone. Buyers need patience, due diligence, capital, and the ability to manage people and change. A family business may be established, but it still needs leadership.
For the right buyer, Canadian family businesses can offer one of the most practical routes into entrepreneurship through acquisition.
The hidden opportunity in family-owned businesses across Canada lies in the gap between retiring owners and entrepreneurs looking for established companies. Many of these businesses have customers, revenue, employees, reputation, and operational history already in place.
Instead of starting from zero, buyers can acquire a profitable local company and improve it through better marketing, stronger systems, digital tools, and modern management. The opportunity is not only to buy a business, but to continue its legacy and unlock its next stage of growth.
For entrepreneurs searching for Canadian business opportunities, family-owned businesses may be one of the most overlooked paths to ownership.
They often have loyal customers, local reputation, proven operations, trained employees, and steady revenue. This gives buyers a stronger starting point than launching a new company.
Business succession is the process of transferring ownership from the current owner to a new owner. In family businesses, this often happens when the founder retires or no family member wants to take over.
Buying can be better if the buyer wants existing customers, cash flow, and a proven business model. Starting may be better for someone with a unique idea or limited acquisition capital.
You should check financial records, tax documents, debts, leases, supplier agreements, employee contracts, customer concentration, licences, equipment, and how dependent the business is on the current owner.
Yes. Buyers may use personal funds, bank loans, investor capital, seller financing, or earn-out structures. Clean financial records usually make financing easier.
Common examples include restaurants, cafés, retail stores, construction companies, cleaning businesses, clinics, manufacturing companies, repair shops, logistics businesses, and local service companies.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 6, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Payments And Market Infrastructure, Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Regulation And Policy, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026).
Citi is combining traditional securities infrastructure with blockchain based issuance, custody, and settlement for private company equity. The launch adds another proof point that tokenized infrastructure is changing how markets operate, especially as banks, exchanges, and market operators compete to define how private assets move onto digital rails.
Digital asset access is being packaged for banks, brokerages, fintechs, and platforms that do not want to build the full crypto stack themselves. The control point is the embedded infrastructure that handles custody, liquidity, compliance, settlement, and connectivity behind the customer experience.
Tokenized real world assets are moving into bank distribution channels. DBS is turning physical gold into a digital product that can sit inside a retail banking app, while also testing institutional market access through its digital exchange.
Stablecoin supervision is moving from broad policy debate into operating rules. Issuers, custodians, exchanges, auditors, compliance vendors, and payment firms need to track how reserve custody, internal controls, audits, and service provider oversight become part of stablecoin market access.
Card networks are building trust infrastructure for AI driven payments. Visa’s updates add another network level proof point that identity, authorization, fraud controls, tokenized credentials, and settlement will shape how AI agents are allowed to transact.
Recurring payment rails are becoming a financial inclusion tool when they help users pay for digital services without relying on credit cards. Brazil’s Pix Automático data shows how local real time payment infrastructure can support subscriptions, platform access, and digital commerce growth.
Agentic payments are moving from checkout experiments into network infrastructure. Payment firms, AI platforms, stablecoin providers, banks, and identity vendors now have to solve authorization, spending limits, settlement, fraud controls, and liability for machines that can transact without a human at every step.
Large banks are building their own tokenized money infrastructure rather than relying on third party stablecoin networks. Payment providers, treasury platforms, and financial institutions now face a more competitive settlement environment as bank money, stablecoins, and tokenized commercial bank deposits compete for transaction flow.
Circle Payments Network continues to add distribution. Business accounts, treasury platforms, and payment providers are becoming part of the stablecoin settlement infrastructure rather than simply connecting to it.
Circle is extending its infrastructure footprint from stablecoins into Bitcoin collateral. Builders now have another institutional grade option for collateral and tokenized asset applications.
AI agents are moving from recommendation and discovery toward financial execution. Coinbase for Agents puts user controlled account access, payments, trading, and workflow automation into the same agentic finance conversation as network trust controls, stablecoin settlement, fraud prevention, and responsible AI governance.
AI supervision in finance is evolving from broad risk discussion toward operating practices for boards, senior management, compliance teams, model owners, technology vendors, and supervisors. Financial institutions need to track how governance, documentation, human oversight, cyber controls, and third party dependencies become part of responsible AI adoption.
Always-on markets need reference data that does not stop when traditional exchanges close. Exchanges, tokenized asset platforms, derivatives venues, market makers, and risk teams now have another pricing source to evaluate as real-world assets trade across crypto-native market infrastructure.
Prediction markets are starting to need the same financial plumbing as capital markets. Market makers, exchanges, payment providers, banks, and compliance teams now need infrastructure that can handle deposits, margin, settlement, risk controls, and regulated access without slowing down trading activity.
Prediction markets are moving from platform experimentation and court fights into formal rule design. Kalshi, Polymarket, DraftKings, Flutter/FanDuel, exchanges, market makers, compliance teams, sports leagues, and retail users now have a clearer process to debate which contracts belong in derivatives markets and which remain too close to gaming, misconduct, or public interest risk.
Financial crime compliance is increasingly becoming an existential regulatory issue rather than a supervisory issue alone. Payment firms, e-money institutions, fintechs, compliance teams, and investors should watch how regulators use governance, safeguarding, ownership, and financial crime controls as indicators of firm viability. The action signals that supervisory concerns can now lead to intervention measures that effectively remove a regulated firm's ability to continue operating.
Canada is pulling AI chatbots into platform safety regulation. AI firms, social platforms, trust and safety teams, identity providers, and compliance vendors should watch how age assurance, safety controls, reporting duties, and enforcement rules develop as digital safety becomes part of regulated online infrastructure.
Financial supervisors are beginning to treat AI as both a productivity tool and a threat multiplier. Banks, insurers, payment firms, fintechs, and security providers should expect greater scrutiny of fraud controls, cyber resilience, operational risk management, and third party technology oversight as regulators adapt supervision to an AI enabled threat environment.
Banking access is moving back onto the policy agenda as branch closures, digital exclusion, SME credit access, and local service gaps put pressure on financial providers. Banks, fintechs, credit unions, open finance firms, and data providers should watch whether the review leads to new access rules, credit data reforms, or stronger expectations around community banking infrastructure.
As advanced analytics become embedded in public institutions, governance questions increasingly extend beyond model performance. Procurement authority, accountability, oversight, operational dependence, switching costs, and public trust all influence how critical decision systems are adopted and maintained. The organisations that govern these systems may become as important as the organisations that build them.
The common thread is not AI, stablecoins, tokenization, or payments. It is access. Access to financial infrastructure, access to payment rails, access to private markets, access to banking services, access to digital assets, and increasingly access to machine driven financial execution. The next competitive battleground may not be who builds the best financial products, but who controls the rules, permissions, trust layers, and infrastructure that determine who can participate and under what conditions. Recent developments suggest those boundaries are on the move. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 12, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, Lending Consumer Credit And BNPL
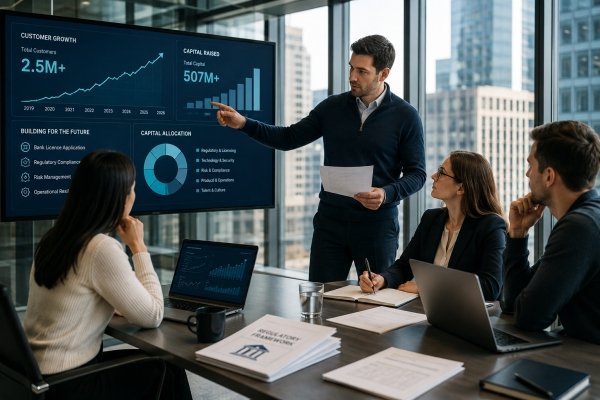
On June 11, 2026, KOHO announced a $130 million CAD financing at a $1.33 billion CAD valuation. KOHO says the capital will support growth and provide the initial capital base for a federally regulated bank, subject to ministerial approval. The round includes new investors Mubadala, Savano Capital, Shopify founder Tobi Lütke, and Affirm COO Michael Linford, with participation from Portage Ventures, Drive Capital, BDC Capital, HOOPP, and Eldridge. KOHO says it has raised $507 million CAD since launch and lists more than 2.5 million customers.
KOHO previously said it entered the second phase of acquiring a Canadian banking licence in January 2024, after raising an $86 million extension at an $800 million valuation and surpassing 1 million users.
The numbers have changed since that earlier milestone, but approval remains a federal decision. KOHO has added customer reach, capital base, and product depth behind its application. A bank licence requires proof of customer demand, not just capital strength, governance, risk controls, compliance systems, consumer protection, and trust. KOHO is trying to cross that line while still competing as a consumer fintech.
KOHO's round lands as OSFI prepares to launch a more defined path for targeted new entrants in June 2026. OSFI fast track approval framework analysis explains why the change is important for fintechs, challenger banks, and other firms with innovative banking models.
While the framework doesn't make approval easy, it offers eligible applicants a clearer route through the federal process while preserving prudential oversight. For fintechs, that is useful because demand for a product is not enough. A bank licence requires capital, governance, risk controls, compliance systems, consumer protection, and trust.
Questbank gives the KOHO story a recent Canadian benchmark. In November 2025, Questbank received approval to operate as a Schedule I bank after a six year approval process. KOHO is pursuing a different strategy, but the approval highlights that new federally regulated banking entrants can still emerge in Canada. That goes for international banking groups too like Santander who was approved by OSFI for a Canadian Banking License in 2025, after waiting for 6 years.
KOHO's financing follows two other large Canadian fintech disclosures. Wealthsimple raised C$750 million at a C$10 billion valuation in October 2025. nesto announced a C$302 million Series E at a C$1.47 billion valuation on June 10, 2026. KOHO followed one day later with a C$1.33 billion valuation.
Wealthsimple is pushing further into personal finance and banking style products. nesto is scaling mortgage and lending infrastructure. KOHO is putting new capital behind a federal bank licence effort. The same funding cycle is reaching different parts of financial services.
Customer growth and venture funding helped create Canada's latest generation of fintech firms. The next evolutionary question is whether firms that already have users and capital can obtain the regulatory permissions needed to participate more directly in deposits, lending, payments, and other core financial services.
KOHO has more than 2.5 million customers, a $1.33 billion valuation, and fresh capital earmarked for its bank licence effort. If customer scale and funding are no longer the hardest milestones, is regulated banking capacity now the real test for Canadian fintech competition?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 11, 2026 | NCFA Story Intelligence | Payments And Market Infrastructure
On June 3, 2026, Payments Canada announced that 15 organizations had joined its membership in 2026 following expanded eligibility rules. The latest intake included Beem Credit Union, Ebury Partners Canada, Shaype, Libro Credit Union, and Newton. Earlier additions included Wise Payments Canada, Float, KOHO, Neo Financial, Paramount Commerce, Brim, Meridian Credit Union, Tru Cooperative Bank, DoBusiness.com, and other newly eligible participants.
The membership announcement is the latest chapter, not the whole story. The story is how Canada moves from a tightly controlled payments model toward wider participation in the infrastructure that moves money, shapes competition, influences product design, and affects the choices available to consumers and businesses.
Canada builds its payments foundation around safety and trust.1 The Canadian Payments Association is created in 1980 under what is now the Canadian Payments Act. Payments Canada now owns and operates national payment systems including Lynx and the Automated Clearing Settlement System. The design reflects a clear priority: money movement is critical infrastructure, and critical infrastructure has to be reliable.
For a long time, that model works well enough for most people. Consumers trust their banks. Businesses use established payment tools. Settlement happens in the background. Most Canadians never need to think about who has direct access to the rails because the system mostly shows up as cards, transfers, bill payments, payroll, and cheques.
The market changes faster than the rails. Digital commerce grows. Mobile payments spread. Online transfers become a daily habit. Payments Canada’s 2025 trends report says Canada processed 22.5 billion retail payment transactions worth $12.2 trillion in 2024, with digital payments representing 86% of transaction volume.2
Fintechs start building around systems they can’t fully access. KOHO, Neo Financial, Float, Wise Payments Canada, Paramount Commerce, Brim, and Newton grow because customers want simpler financial products. The problem isn’t demand. The problem is that many new firms still depend on infrastructure controlled by others.
Competition becomes the pressure point. Critics of Canada’s payments model argue that control by a small number of large institutions has contributed to high fees, delay, and limited competition. Reuters reported this criticism when the Bank of Canada began payment service provider registration under the Retail Payment Activities Act.3
The fintech argument becomes practical. If firms outside the largest banks can’t connect on fair terms, they often need intermediaries, workarounds, sponsorship relationships, or slower product paths. That affects costs, margins, speed to market, and the ability to challenge incumbents with better consumer and business experiences.
Ottawa starts changing the legal frame. Finance Canada says amendments to the Canadian Payments Act made on June 20, 2024 expand Payments Canada membership eligibility to Bank of Canada supervised payment service providers, credit union locals that are part of a credit union central, and designated clearing and settlement system operators.4
The Bank of Canada brings PSPs into supervision. Under the Retail Payment Activities Act, the Bank registers and supervises payment service providers and focuses on operational risk, incident response, safeguarding end user funds, and reporting. As of September 8, 2025, PSPs must have risk management and funds safeguarding frameworks in place.5
Real Time Rail becomes the execution test. Payments Canada says the Real Time Rail is planned for launch in Q4 2026 and will support instant, data rich payments through a new exchange, clearing, and settlement system.6 The promise is simple: money should move faster, carry better data, and support new products.
The delays create frustration because the opportunity is real. Payments Canada selected Interac as the exchange solution provider in 2021, when the system was expected to launch in 2022.7 NCFA has tracked the execution question through RTR delay coverage and RTR productivity analysis.
The first wave of PSP members makes the policy visible. Payments Canada welcomes Wise Payments Canada, Float, KOHO, Paramount Commerce, and Brim as new payment service provider members in January 2026.8 NCFA tracks that moment when Payments Canada admits five new PSPs.
Membership is not only about access to rails. Payments Canada’s by law changes update membership requirements and support new eligible members as Canadian Payments Act amendments come into force.11 Membership gives new firms a closer role in the rules, standards, and modernization discussions that shape the system.
That changes the politics of infrastructure. A fintech that has to build around the system is one kind of participant. A fintech that can join, comply, learn the rules, and contribute to modernization discussions is another. The same applies to credit unions, FX firms, and other payment providers that want a role in Canada’s next financial infrastructure chapter.
Consumer driven banking brings the same access debate to financial data. Finance Canada says the framework is meant to let Canadians securely access and share financial data with financial service providers, without fees for accessing and sharing that data, while reducing reliance on risky practices such as screen scraping.12 The Bank of Canada says it will administer the framework so Canadians and businesses can securely share financial data with approved providers of their choice.13
But the friction does not disappear just because the law changes. Tier one banks, fintechs, data aggregators, and policymakers still have to work through scope, liability, accreditation, implementation timelines, commercial terms, and API performance. NCFA’s open banking commercialization roadmap frames the next phase as real API usage, accreditation, liability, and business model design, not just a policy announcement.
Stablecoins pull the payments debate into digital money. Bill C 15 gives Canada a legal framework for stablecoins and consumer driven banking, moving both into the financial policy stack. NCFA framed that moment in Bill C 15 gives Canada a digital finance framework.
The payment infrastructure question is no longer only about bank rails. Stablecoins, payment service providers, RTR, consumer driven banking, and Bank of Canada oversight are starting to occupy the same policy conversation. NCFA’s question post on stablecoins as payment infrastructure shows why digital money now belongs in the same access debate.
Canada’s payments story now connects directly to productivity. The Bank of Canada has warned that weak productivity threatens living standards, and NCFA has linked payments modernization to execution, competitiveness, and growth. Faster settlement, better data, lower friction, and more competition are not abstract infrastructure benefits. They affect how firms operate every day.
Cross border capability becomes part of the same test. Canada’s payment system cannot only work well at home. Canadian businesses, newcomers, exporters, marketplaces, and financial platforms also need better global money movement. That is why NCFA’s cross border payments analysis belongs beside RTR, open banking, and stablecoins.
Canada’s payments infrastructure didn’t turn a corner overnight. The change reflects years of modernization work, policy debate, fintech pressure, consumer demand, and the practical reality that a digital economy needs payment systems that are safe, fast, open enough to compete, and trusted enough to scale. The result is a more diverse payments membership base than Canada had a decade ago, with fintechs, PSPs, credit unions, FX firms, and digital finance companies gaining a larger role in the systems that move money.
Opening access isn’t the finish line. It’s the starting point. Canadian fintechs, banks, credit unions, payment providers, regulators, and infrastructure operators now have to prove broader participation can become better financial services. Now is the time to get to work. Launch Real Time Rail, make consumer driven banking usable, widen the tent responsibly, improve domestic and cross border capability, lower friction for merchants and consumers, and connect these reforms to the Canadian Financial Innovation Map and pipeline Canada needs to compete.
Canada's infrastructure modernization is creating new commercial opportunities in Consumer Driven Banking. See NCFA's Open Banking in Canada Opportunity Brief for the evidence trail, product pathways, competitive benchmark and commercialization outlook.
Which part of Canada’s payments story stood out most to you?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 20, 2026

Image: Unsplash/Headway
When did you last notice a sponsor banner on day three of a conference? Exactly. Multi-day events have a visibility half-life, and most brand strategies are not built to last beyond it.
The opening session energy is easy to ride. Sustaining brand presence through meals, breakouts, networking gaps, and general event fatigue is a completely different challenge.
Canada brought together close to 2,555 business events in 2025. The organizers who cracked visibility across all of that were doing something most were not. This article is about what that something looks like in practice.
Most event brands live entirely in the eyes. A logo here, a banner there, a branded tote bag everyone leaves behind on day two. The thing is, human memory does not work that way. People remember how a space made them feel far longer than they remember what it looked like.
This is where sensory marketing comes into play. When you own a scent in your registration lounge or a sound identity in your networking space, you are embedding your brand into the attendee's physical experience. Attendees may not consciously register it, but their nervous system does.
Pick one sense your brand can own consistently across all three or four days. A distinct coffee blend at your branded station. A low ambient sound identity in your lounge. Something tactile in your collateral that feels different from everything else on the table.
Consistency is what makes sensory branding stick. One well-chosen detail repeated across every touchpoint will outlast a dozen visually perfect installations that disappear into the background by midday.
Attendees build a mental map of your event space within the first few hours. Anything sitting in the same spot after that becomes part of the furniture. Your brand needs to travel with the crowd, not wait for the crowd to come back to it.
Think about where people already are. Breakfast queues, session transitions, charging corners, and the slow shuffle between keynote and lunch. Place something worth noticing in those pockets, and you are not interrupting anyone.
It does not have to be extravagant. Even something as simple as custom pens can do real work when placed at the right touchpoints across the event floor. Custom pens come in many forms, so think about your audience.
If you want something functional for a tech-forward crowd, business pens with a stylus are worth considering, notes Pens.com. If the setting is more formal, engraved pens would be a safer option.
Beyond that, rotate your brand presence between days. Move the activation, refresh the messaging, change the location. Give attendees something new to stumble into each morning.
A branded photo corner that was near the entrance on day one can migrate to the lunch area on day two. A product display that lived beside registration can reappear near the closing session. Movement creates the illusion of energy. It is this energy that keeps brands alive in people's peripheral attention.
Nobody wakes up on day two of a conference excited to visit a sponsor booth. But they will absolutely walk across a busy event floor to claim a reward or beat a leaderboard.
If your attendees skew younger, this is even more important. Conference News reported that 64% of Gen Z conference attendees actively seek immersive experiences with Instagrammable moments.
Give them a branded scavenger hunt with photo checkpoints. Build a leaderboard that updates in real time on a screen that everyone passes. Create a stamp card that unlocks something worth having at the end of day three.
The rewards do not need to be expensive. They need to feel earned. An exclusive backstage tour, early access to a session, or a branded item not available anywhere else at the event carries more weight than a generic goodie bag. When attendees are chasing something, your brand is what they are chasing.
Most brands show everything they have on day one. Full messaging, complete product story, every value proposition on the table before lunch. By day two, there is nothing left to discover, and attendees have mentally filed your brand away.
Flip that completely. Give attendees a reason to come back by leaving something unresolved on purpose. Day one, plant a question at your branded touchpoint. Something intriguing enough to linger. Day two, offer a piece of context that deepens it without fully answering it. Day three, deliver the payoff.
This borrows directly from the Zeigarnik Effect. It is a well-documented psychological principle showing that the human brain holds onto incomplete information far more stubbornly than resolved ones. An open loop in someone's mind is essentially a reservation your brand has made in their attention.
Practically, this could look like a teaser installation that changes each morning. A branded countdown with no explanation on day one. A partial reveal on day two. The full picture on day three.
Keep it visual, keep it simple, and make sure every element is unmistakably yours. Attendees will start talking about it, and that conversation is free brand visibility, traveling through every corner of your event.
Canada hosted approximately 2,555 business events in 2025, making it one of the busiest markets for professional gatherings in North America.
According to Conference News, 64% of Gen Z conference attendees prioritize immersive, Instagrammable experiences over traditional formats like panels and keynote presentations.
It is a psychological principle where incomplete information stays top of mind longer. Brands can use this to build multi-day anticipation among attendees.
| Strategy | Key Insight |
| Sensory Marketing | Brand recall builds faster when more than one sense is engaged |
| Moving Brand Touchpoints | Canada hosted ~2,555 business events in 2025, meaning competition for attention has never been tighter |
| Gamification | 64% of Gen Z conference attendees want immersive, Instagrammable experiences |
| Day-by-day Brand Storytelling | The Zeigarnik Effect proves incomplete narratives stay in memory longer than resolved ones |
Multi-day events are chaotic, exhausting, and exciting all at once. In the middle of all that, brand visibility can easily slip down the priority list. Keep it near the top. The strategies we mentioned in this piece are not complicated or expensive.
They just require some deliberate thinking ahead of time. Give your brand a plan that runs the full length of the event, and watch how differently attendees engage with it. The results are bound to speak for themselves.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 10, 2026 | NCFA Insight | Regulation And Policy, Capital Markets And Market Infrastructure
On June 10, 2026, the CFTC opened public consultation on proposed prediction market rules and the related 267-page pre-publication rule document. The proposal would create a formal review process for event contracts that touch sensitive areas such as gaming, war, terrorism, assassination, or unlawful activity.
The market is now large enough to force a real line-drawing exercise. The CFTC says total trading volume across registered prediction markets exceeded $25 billion in 2025. That remains small beside the roughly $31 trillion notional value of the broader futures market the agency regulates, but it is no longer a niche category.
The proposal targets event contracts covered by Section 5c(c)(5)(C) of the Commodity Exchange Act. The CFTC wants to amend Regulation 40.11, add Appendix F to part 40, define when a contract “involves” a listed activity, define “gaming,” and apply public interest factors to each contract under review.
Currently, a registered exchange can self-certify a contract, and contracts may begin trading quickly. The proposed framework gives the CFTC a 90-day review period for contracts that may involve one of the listed activities. The agency can request that trading pause during review, but the proposal says prediction markets are not required to follow that request. Some contracts could trade during review and later be blocked or delisted if the CFTC finds them contrary to the public interest.
The public interest test is practical. The CFTC would look at price discovery, information value, market integrity, and whether the platform can supervise the contract. That puts contract design, settlement data, surveillance, and trader controls at the centre of the review.
Sports are a key test case. The proposal treats contracts based on broad, objective sports outcomes more favourably, including final scores, point differentials, win-loss results, tournament advancement, team or individual statistics, and season-long performance metrics. The CFTC says these contracts can create useful price information when they use objective settlement criteria and are supported by suitable oversight and coordination with sports integrity bodies.
The CFTC is stricter around contracts tied to player injuries, officiating decisions, youth sports, cheating incentives, and misconduct. Injury contracts can create harmful incentives and expose medical information. Officiating contracts can put pressure on a small number of identifiable decision makers. Youth sports markets raise participant protection concerns.
DraftKings highlights why this rulemaking is needed commercially. Barron’s reports that annualized consumer trading volume on DraftKings Predictions reached $1.3 billion, up 24% from April 2026. Annualized total trading volume reached $3.1 billion, up 34%. Note, the numbers are early and based on company data.
DraftKings brings sports users, mobile distribution, pricing, promotions, and live event engagement. Kalshi and Polymarket bring event contracts, exchange style trading, collateral, liquidity, and surveillance. The CFTC proposal now pulls those models into the same regulatory conversation.
The user experience may look similar on a phone, but the rulebooks are different. Sportsbooks operate under gaming law. Prediction markets argue they are federally regulated event contract markets that support price discovery and information aggregation. The CFTC proposal tests where that argument holds, especially when sports contracts that are towing the line of integrity.
NCFA recently looked at trust questions around Polymarket influencer payments, including disclosure, paid promotion, and market credibility after a market goes live. The CFTC proposal moves the issue upstream. It asks which markets should be allowed to list in the first place.
Canada should watch closely. DraftKings already operates in Ontario’s regulated iGaming market, while prediction markets continue to test the line between financial contracts, gaming products, and information markets. The U.S. approach won't cleanly transfer into Canada, but it gives Canadian regulators, exchanges, fintechs, and other stakeholders an early view of the policy questions surrounding the table..
Will sports prediction markets become regulated financial products, sportsbook extensions, or a new category that forces regulators to redraw the line between trading, gaming, and market information?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 10, 2026 | NCFA Story Intelligence | Capital Markets And Funding
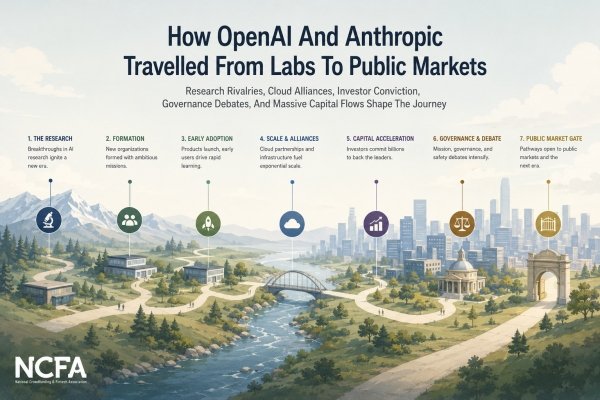
On June 8, 2026, OpenAI confirmed it submitted a confidential S-1 to the U.S. Securities and Exchange Commission. One week earlier, Anthropic disclosed its own confidential draft registration statement for a proposed IPO.
The filings are the trigger, not the story. The story is how frontier AI moves from research labs and safety debates into consumer adoption, cloud alliances, investor conviction, copyright fights, government interest, near trillion dollar private valuations, and the public market gate.
OpenAI starts with a promise that sounds almost incompatible with public markets.1 In 2015, it begins as a nonprofit AI research company with a mission tied to broad public benefit, not shareholder return. That tension does not matter much while the work sits inside research circles. It matters once OpenAI becomes strategically important.
Anthropic comes from inside the same argument.2 Founded in 2021 by former OpenAI researchers, including Dario Amodei, Anthropic builds its identity around reliable, interpretable, and steerable AI systems. It is not just another model company. It is a different answer to a question OpenAI helped make unavoidable.
ChatGPT turns frontier AI into a public habit.3 The late 2022 launch changes the audience almost overnight. Students, founders, developers, workers, executives, and investors start testing advanced AI directly. Reuters later reports ChatGPT reached an estimated 100 million monthly active users in January 2023.4
Claude takes the quieter enterprise path.5 It does not create the same consumer spectacle, but Anthropic leans into reliability, predictable deployment, and safety as commercial positioning. Trust becomes part of the product, especially for organizations that need governance controls before they scale AI usage.
Microsoft turns OpenAI into one of the largest strategic bets in technology.6 The relationship gives OpenAI more than capital. Azure becomes part of its operating foundation, with cloud infrastructure, enterprise distribution, and credibility arriving at a moment when many buyers are still trying to understand what generative AI can become.
Anthropic attracts a different group of believers. Google backs the company. Amazon commits billions and makes Anthropic central to its AI strategy, while AWS becomes Anthropic's primary cloud and training partner.7 Spark Capital and Menlo Ventures remain part of the journey as Anthropic grows from safety focused startup into one of OpenAI's strongest challengers.
OpenAI remains the company everyone else measures against. ChatGPT gives OpenAI distribution, developer attention, and brand recognition. Microsoft's partnership gives it reach into enterprise software. That combination makes OpenAI powerful, but it also makes dependency risk more visible for large buyers.
Anthropic becomes strategically useful because it is different. Claude's role in enterprise productivity and financial workflows shows how a trust first product can become a real alternative. When Microsoft brings Claude into Office productivity, the message is practical: even OpenAI's most important partner wants more than one AI supplier in the stack.
OpenAI's success creates a new constraint. The company is no longer trying to prove that people will use frontier AI. ChatGPT already answered that question. OpenAI now has to fund the compute, deployment, developer usage, and enterprise adoption needed to keep the flywheel turning.
Anthropic faces the same pressure through Claude demand. Its Series H announcement points to global enterprise adoption, expanded compute capacity, Amazon, Google, Broadcom, SpaceX, and chip partners including Micron, Samsung, and SK hynix.8 The company's careful brand does not reduce its need for industrial scale infrastructure.
OpenAI's rise brings copyright and publisher pressure with it. The more useful the models become, the more valuable the training inputs appear. News organizations, authors, artists, and creators increasingly ask how their work contributes to model capability and who captures the value created from it.
Anthropic faces the same ownership question through Reddit. The Reddit lawsuit against Anthropic puts training data claims, platform rights, and AI accountability into the story. The issue is not only whether AI can learn from the web. It is who gets a say when web content becomes commercial fuel.
OpenAI's control questions become public in 2023.9 The board removes Sam Altman, then reverses course after pressure from employees, customers, investors, and partners. The episode is brief, but it changes how people read the company. Governance becomes part of valuation risk.
Anthropic's safety stance faces real world tests. Its product identity is tied to reliability and responsible deployment, but governments, enterprises, and defence buyers want more capability. The tension between safety commitments and state power is already visible in AI ethics, state power, and red lines.
OpenAI's March 2026 financing makes the capital story impossible to ignore.10 The company closes $122B USD in committed capital at an $852B USD post money valuation. The round is anchored by Amazon, NVIDIA, and SoftBank, with continued participation from Microsoft. SoftBank co leads alongside a16z, D. E. Shaw Ventures, MGX, TPG, and accounts advised by T. Rowe Price Associates.
Anthropic's May 2026 Series H shows the same private market scale.11 The company raises $65B USD at a $965B USD post money valuation. Altimeter Capital, Dragoneer, Greenoaks, and Sequoia Capital lead the round, with Capital Group, Coatue, D1 Capital Partners, GIC, ICONIQ, and XN also co leading. Amazon's prior commitment remains part of the picture, along with Google, Broadcom, SpaceX, and chip partners.
OpenAI follows on June 8 and keeps timing open.12 The company confirms it submitted a confidential S-1 but says it has not decided when to go public. Public markets become an option, while OpenAI keeps weighing what may be easier to do as a private company.
Anthropic reaches the IPO gate first on June 1.13 The filing does not set share count or price. It gives the company the option to move after SEC review, market conditions, and other factors.
Different origins. Different philosophies. Different investor groups. Different commercialization paths. Yet both companies arrive at the same gate.
The IPO filings don't end the frontier AI story. They mark the point where a decade of research, product adoption, infrastructure buildout, governance conflict, investor conviction, and public policy pressure begins meeting public markets.
For NCFA, this is where Story Intelligence connects to the Financial Innovation Map. The opportunity set includes private market liquidity, tokenized pre IPO access, AI infrastructure finance, prediction markets around IPO timing and valuation, disclosure standards, and investor protection for companies that may become public only after private markets have already priced much of the upside.
OpenAI and Anthropic followed different paths, attracted different allies, and made different decisions along the way. Yet both arrived at the same gate. That may say as much about the economics of frontier AI as it does about the companies themselves.
What part of the story stood out most to you?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016