




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 26, 2026 | NCFA Resource | Artificial Intelligence And Data, Risk Compliance And Regtech, Payments And Market Infrastructure
On May 15, 2026, the Bank of Canada published Integrating Non-traditional Data and AI into Central Banking. The staff paper examines how central banks use artificial intelligence and non traditional data in research, operations, payments monitoring, forecasting, and policy support.
The paper stays close to real operating problems. It focuses on data quality, model governance, human oversight, vendor risk, cybersecurity, and moving AI pilots into production.
The paper shows how central banks use non traditional data from payment transactions, earnings call transcripts, satellite images, job postings, social media, scanner data, and real time business activity. It also explains how AI supports inflation tracking, nowcasting, anomaly detection, payments monitoring, internal automation, and policy work.
One Bank of Canada automation project improved filing accuracy to 99.5% and saved about 1.25 person years of staff capacity. The paper also cites a BIS survey showing more than 90% of responding central banks are moderately or extensively discussing AI internally.
The most useful section sets out six accelerators for responsible AI adoption in central banking. They include sandbox environments, technology readiness checks, high quality data, reusable development patterns, scale planning, and risk governance. The framework also applies to regulated financial institutions that need to transition AI from experiments into controlled production, similar to broader work underway around customer due diligence controls for fintechs.
This resource is useful for fintech founders, AI governance teams, regtech providers, financial institutions, payment companies, policy teams, investors, and compliance leaders.
It is especially relevant for teams building explainable AI, payment intelligence, anomaly detection, compliance automation, model governance, and trusted workflow tools.
The strength is its operating detail and the fact that the paper doesn't treat AI as a generic productivity story. It shows why regulated financial institutions need explainability, auditability, strong data controls, and clear ownership before AI can support high stakes decisions.
The paper also points to a real market gap. Central banks may need specialized AI tools and deeper in house expertise because many commercial systems are not designed for monetary policy analysis, payments oversight, or central bank operations.
The limit is scope. This is a central banking paper, not a commercialization guide. It does not estimate vendor spending, market size, adoption timelines, or private sector demand. Its value is the framework and the operating discipline behind it.
Bank Of Canada AI And Non Traditional Data Paper (primary Bank of Canada resource)
AI Agents Enter Governed Financial Workflows (AI governance and controls)
Tokenization Starts Looking Like Financial Infrastructure (regulated financial infrastructure)
Deloitte And Stablecorp Bring QCAD To Banks (Canadian payment infrastructure)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 25, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization
On May 20, 2026, 3iQ selected Anchorage Digital as the infrastructure and custody partner for its Canadian product suite. Subject to regulatory approvals and required prospectus or offering document amendments, 3iQ intends to migrate a significant portion of assets under management across six TSX listed exchange traded products to Anchorage Digital.
3iQ is a Canadian digital asset investment manager with a regulated public product suite. Anchorage Digital became the first OCC approved national crypto bank in the U.S. Canada has qualified digital asset custodians, but not an equivalent national crypto bank structure at Anchorage’s scale. The decision puts a hard question in front of Canada’s digital asset sector. Can Canadian infrastructure win large institutional mandates when issuers need custody, settlement, staking support, and regulatory comfort at scale?
The warning is now showing up in market activity. Canada has already debated whether domestic digital asset infrastructure can compete with larger U.S. regulated platforms. That issue became more visible when Balance applied for a Canadian special purpose trust structure to build institutional digital asset custody capacity at home.
If Canada approves digital asset products but doesn't build trusted infrastructure at home, more of the work, jobs, and revenue may migrate south. In this case, 3iQ keeps the Canadian listed products while Anchorage Digital captures more of the custody and infrastructure work behind them.
That choice is commercial, not patriotic. Large issuers choose the stack that lowers operating risk and helps them launch better products. That’s the reality test Canadian infrastructure providers now face.
3iQ says Anchorage Digital lets funds settle trades from cold storage without relying on hot wallets. Its Atlas network also lets 3iQ settle directly with trading counterparties and remove extra wallet steps. It means custody now affects much more than safekeeping. It affects how funds trade, settle, manage risk, support staking, and protect investors.
The partnership is also expected to support 3iQ’s expanded staking capabilities. That raises the stakes. Staking needs more than token custody. It needs validator access, clean reporting, strong controls, and regulatory comfort. The right custody partner can give a fund more room to build. The wrong one can hold it back.
Tommaso Mancuso, President and CIO of 3iQ:
"3iQ needs infrastructure providers that meet “the highest standards for security, flexibility, and regulatory alignment.”
That is the standard Canadian infrastructure has to meet now. Canada has digital asset talent, regulated products, custody ambition, and a real institutional market. But the operating stack behind those products still needs more depth, if they want to compete. Fund issuers need platforms that can handle scale, connect cleanly to trading counterparties, support approved product features, and satisfy regulators without adding friction.
Canadian policymakers should treat this as a competitiveness warning. Product approvals aren't enough if the custody, settlement, staking, and fund operations work scales outside Canada. The goal should be to keep more trusted digital asset infrastructure, jobs, and revenue at home.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 25, 2026 | NCFA Insight | Payments And Market Infrastructure, Open Banking Open Finance And Data Sharing, Digital Assets Blockchain And Tokenization
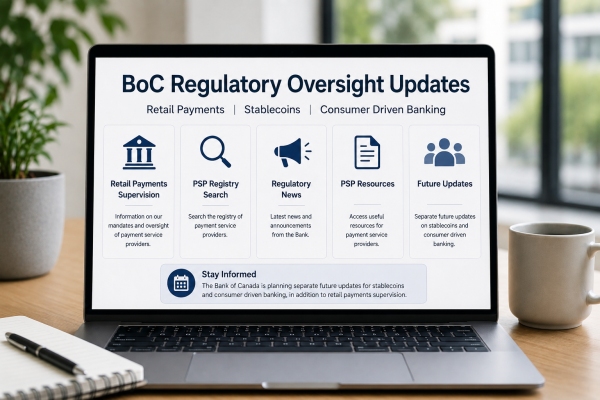
On May 25, 2026, the Bank of Canada refreshed its regulatory oversight web content and streamlined its retail payments supervision section. The update gives payment service providers a cleaner place to find key information as the Bank’s mandates expand across retail payments, stablecoins, and consumer driven banking.
The Bank says users can now more easily find information about its mandates, search the payment service provider registry, access a new regulatory news section, and browse resources for payment service providers. It's important for fintechs because RPAA supervision is evolving from policy discussion into day to day operating reality and governance.
The Bank supervises payment service providers under the Retail Payment Activities Act (NCFA covered this practical transition when the PSP registry went live under RPAA) and expects firms to meet risk management and safeguarding requirements.
In addition to retail payments supervision, the Bank of Canada also says it plans to issue separate future updates about stablecoins and consumer driven banking. It means fintechs should watch the Bank’s update streams more closely as these files progress for the latest updates and key information.
The Bank has also set up a Consumer Driven Banking Advisory Committee to provide industry perspective and advice to the Bank and the Department of Finance. The committee will focus on implementation, industry readiness, and the supervisory framework. NCFA’s open banking commercialization roadmap explains why implementation details will matter for fintech business models, data access, onboarding, and customer experience. That gives market participants a useful clue about where questions will concentrate next, such as how companies prepare, how oversight works in practice, and how consumer driven banking connects with the broader payment system.
Payment companies should use the refreshed pages as a compliance resource point. Check registry details, monitor regulatory news, review PSP resources, and make sure internal owners know where Bank updates will appear.
No new rules were announced in this email, but the Bank has made it easier to follow the official files that matter to payment companies, stablecoin operators, open banking participants. In a crowded regulatory environment, cleaner source material helps firms track changes earlier and prepare with less confusion.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 25, 2026 | NCFA Insight | Artificial Intelligence And Data, Capital Markets And Funding

On May 23, 2026, hundreds marched in downtown Vancouver against proposed AI data centres, concerned about electricity use, water use, and environmental impact. The protest puts Canada’s AI compute plans under pressure. Communities want to know who gets clean power, what they get back, and whether data centre operators can earn public trust.
The pressure comes from specific projects. On May 11, 2026, TELUS and the federal government announced work on a proposed Sovereign AI Factory cluster in B.C. that would expand TELUS’s Kamloops data centre and add two Vancouver facilities with Westbank and partners. TELUS says the cluster starts with 85 MW of clean renewable power secured from BC Hydro and is designed to scale to more than 60,000 GPUs and 150 MW by 2032.
After the May 23 protest, TELUS told Daily Hive that its proposed AI infrastructure is a “critical national asset” built for Canada and by Canadians. They said the project could add $9 billion to Canada’s economy, protect sensitive Canadian data, use 98% clean renewable electricity from BC Hydro, cut energy use by 80%, reduce water use by 90%, and save an estimated 300 million litres of water each year through closed loop liquid cooling.
TELUS is framing the project as sovereign AI infrastructure with climate and data benefits. Critics are asking whether those claims will be visible, measurable, and credible enough for communities that are being asked to host large AI facilities.
Ottawa wants more domestic AI compute so Canadian researchers, companies, and public institutions don't have to rely solely on foreign infrastructure. From January 15 to February 15, 2026, the federal government accepted proposals from companies and consortia seeking support to build large scale sovereign AI data centres. The federal government also said no funding has yet been committed or distributed under the process.
On January 30, 2026, the Province and BC Hydro launched a competitive electricity process for AI and data centre projects. The goal is to manage rising demand and prioritize projects with stronger economic, community, and environmental benefits.
BC Hydro’s 2026 call shows the cap constraint. Its Q&A says up to 300 MW has been allocated to storage data centres and up to 100 MW to conventional data centres. Each project site request must not exceed 145 MW. TELUS’s stated 150 MW 2032 target shows how quickly one AI project can approach the size of the current allocation.
BC Hydro says it doesn't comment on specific customer load requests. That leaves communities with headline numbers and proposed locations, but not always the full project picture on grid upgrades, water use, tax benefits, jobs, or local access to compute.
Data centres turn AI from software policy into physical infrastructure. They need land, power, cooling, permits, grid planning, and local acceptance.
Households, industry, electrification, and AI projects are all competing for clean power, which is scare ad valuable. If communities don't see clear local benefits, approvals will get harder.
Critics point to electricity demand, water use, environmental impact, and the risk that public infrastructure supports private AI capacity without enough community return.
B.C. is already choosing which projects get access to limited clean power. Canada needs compute, but scarce electricity should go first to projects that use power efficiently, protect data sovereignty, create local benefits, and make capacity available to Canadian users.
Canada wants sovereign AI compute. Can governments and operators prove that clean power used for AI will create enough local benefit, public trust, and Canadian owned value to justify the buildout?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 25, 2026

The global beauty economy is massive. We are talking about a sector that generates half a trillion dollars in annual retail sales; it is an economic powerhouse driven by skincare, cosmetics, and personal care services. Yet, for a long time, the actual infrastructure behind your neighborhood salon or luxury spa felt stuck in the past. You walk into a high-end salon, get a forward-thinking haircut, and then encounter a clunky, slow payment counter. It was a strange mismatch.
Things are shifting rapidly now. Digital modernization is sweeping through personal services, and it is not just about booking apps or Instagram marketing. The real transformation is happening deep in the financial backend. Fintech innovation has quietly become the operational backbone of this massive industry, changing how money moves between clients, stylists, and suppliers.
Running a service-oriented business presents unique operational headaches. Unlike traditional retail where you just buy a product and walk out, beauty services rely heavily on human time; scheduling is variable, and tipping is an essential part of the worker's income. Traditional banking systems were never built with these specifics in mind. High processing fees, delayed payouts, and rigid merchant setups have historically eaten into the profit margins of small and medium-sized beauty enterprises.
Cash used to be king in salons because it bypassed these frictions. However, consumer habits have changed dramatically, especially over the last few years; modern clients expect fast, digital, and contactless options at checkouts. Salon owners who stick exclusively to old-school payment systems find themselves facing high cart abandonment for online bookings or losing clients who simply do not carry physical wallets anymore. The pressure to adapt is real.
To survive in this competitive space, beauty entrepreneurs must look closely at their underlying transaction infrastructure. A salon's payment processing setup shouldn't just be an afterthought or a utility expense; it is a core business strategy. Choosing the right specialized merchant services means minimizing transaction downgrades, protecting client data, and ensuring that mobile and contactless wallets work flawlessly every single time. Having tailored beauty salon merchant account solutions ensures that a business can handle high-volume weekend rushes without facing system crashes or unexpected cash freezes from risk-averse, generic banks. When the checkout experience is entirely painless, clients leave happy, and staff get paid without delays.
The modern salon needs more than a standard card reader. Today’s fintech platforms build specialized tools that handle everything from dynamic scheduling to automatic tip splitting. Imagine a client getting a complex color treatment from one stylist and a blowout from an assistant. A generic payment system struggles to divide that revenue cleanly. Modern platforms solve this automatically at the moment of tap.
This backend shift allows salon owners to focus on what they actually care about; the artistry and the client experience. It cuts down hours of manual bookkeeping.
Getting a traditional bank loan as a salon owner or independent aesthetician has always been incredibly difficult. Traditional institutions look at fluctuating seasonal revenues and see risk. They demand mountains of paperwork. Fintech has stepped into this vacuum with data-driven financing models that understand the natural cash flow rhythms of personal service businesses.
By looking directly at daily payment processing data, modern financial platforms can offer revenue-based financing. If a salon needs to purchase new chairs or high-end laser equipment, they can get capital advances based on their proven sales volume. Repayments then fluctuate automatically; during a busy holiday season, the business pays back more, while during a slow January, the repayment drops. It is a flexible system that fits the volatile nature of the beauty market perfectly.
The modernization wave is also altering how clients choose to fund their beauty routines. High-end treatments like microneedling, hair extensions, or extensive color corrections can cost hundreds of dollars. Historically, these were luxury investments that required saving up. Now, alternative payment methods are altering consumer spending habits right at the register.
Buy Now, Pay Later (BNPL) structures are becoming common features in modern service checkouts. A client can split a six-hundred-dollar lifestyle package into four manageable, interest-free installments. The salon receives the full payment upfront, while the fintech provider handles the collection risk. It increases average ticket sizes significantly. Clients get access to premium services when they want them, and salons see a steady bump in their revenue numbers without taking on personal financial debt.
This digital transition is doing something even larger; it is formalizing an economy that was previously heavily unbanked or underbanked. The beauty service workforce is full of independent booth renters, solo practitioners, and micro-entrepreneurs. Historically, many of these workers struggled to show proof of income when trying to rent an apartment or apply for a personal mortgage because their earnings were scattered across cash tips and peer-to-peer apps.
By routing transactions through modern financial technology, these micro-businesses build a clean, verifiable digital paper trail. This data wealth opens doors to broader financial services, allowing solo beauty professionals to prove their economic viability to the wider world. It is financial inclusion disguised as everyday business convenience.
The $500 billion beauty market isn't slowing down, but the way it operates is completely transforming. The businesses that thrive over the next decade will be the ones that view technology not as an administrative burden, but as an operational lever. Digital modernization is no longer an optional luxury for high-end urban spas; it is the baseline expectation for survival across the entire service sector. Moving money quickly, safely, and intelligently is the new standard of beauty.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 22, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Payments And Money Movement

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026).
Institutional digital asset infrastructure is increasingly converging around unified execution, settlement, compliance, and liquidity layers. Banks, fintechs, custodians, PSPs, brokers, and treasury teams should track how tokenized funds, stablecoin settlement, collateral movement, and onchain liquidity are becoming integrated into institutional operating environments rather than isolated crypto workflows.
Bank led stablecoins are becoming part of Europe’s regulated payment strategy. Banks, PSPs, stablecoin issuers, custodians, treasury teams, and compliance groups should track how euro denominated stablecoin infrastructure affects settlement options, liquidity design, and competition with USD stablecoins.
Stablecoin distribution is becoming a network access problem. Wallets, exchanges, PSPs, brokers, and embedded finance platforms need interoperability, regulated issuance, liquidity, and compliance controls that let users move between stablecoin networks without adding operational friction.
New York licensing remains a key test for institutional digital asset firms. Exchanges, custodians, brokers, lenders, and compliance teams should track which firms secure state level approvals because market access, client onboarding, and institutional trust still depend on regulated operating permissions.
USD account access is becoming embedded infrastructure for global platforms, not just a bank product. Fintechs, PSPs, marketplaces, payroll firms, and treasury teams should watch how account issuance, compliance controls, real time payments, and stablecoin rails converge inside programmable payment stacks.
Canadian dollar stablecoins are beginning to enter practical payment flows instead of remaining treasury or trading instruments. PSPs, banks, remittance firms, treasury teams, and compliance groups should watch how regulated stablecoin settlement changes cross border payout speed, corridor economics, liquidity management, and payment competition. CADC infrastructure continues to expand across Canadian digital payment markets.
Bitcoin reserve legislation is turning digital assets into a public balance sheet question, not just a market regulation debate. Crypto firms, custodians, exchanges, treasury teams, investors, and policymakers should track how federal reserve asset policy, seized digital asset management, and national competitiveness arguments reshape the next phase of U.S. crypto policy.
Card network economics are moving deeper into formal regulatory reporting. Merchants, acquirers, issuers, PSPs, payment networks, and embedded payment platforms should track how fee transparency, profitability evidence, and scheme oversight affect payment costs and competitive pressure across card acceptance.
The FCA is creating a clearer supervisory channel for firms that are already scaling, not just early sandbox participants. That matters because fast growth often creates new questions around controls, governance, technology, and consumer impact before a firm becomes systemically important.
Prediction markets are becoming a direct federal versus state jurisdiction fight. Exchanges, fintech platforms, compliance teams, policymakers, and investors should track how courts treat event contracts because the outcome could affect federal derivatives oversight, state gambling authority, consumer protection rules, and regulated forecasting markets.
Federal policymakers increasingly treat fintech infrastructure as part of U.S. financial competitiveness strategy. Banks, PSPs, digital asset firms, payment companies, and infrastructure providers should track how payment rail access, supervision, settlement services, and master account policy evolve as regulators face growing pressure to integrate fintech firms into core financial systems.
UK stablecoin policy is moving toward draft rule text and implementation design. Stablecoin issuers, banks, PSPs, custodians, wallets, and treasury teams should track how the Bank balances financial stability controls with usable payment products, especially around issuance limits, redemption, reserves, and access to settlement infrastructure.
Lowering community bank burden can open capacity, not just reduce paperwork. Fintechs, sponsor banks, core providers, lenders, and compliance teams should track whether tailored supervision gives smaller banks more room to partner, modernize, lend, and support local payment and deposit infrastructure.
Onchain markets need clearing and netting controls before more institutions treat them as reliable operating channels. Trading firms, custodians, brokers, stablecoin networks, and treasury teams should track how private obligation matching, liquidity savings, and counterparty controls develop across institutional digital asset markets.
Prediction markets are moving beyond politics and sports into private capital market intelligence. Exchanges, investors, fintech platforms, regulators, and market infrastructure providers should track how forecasting markets, institutional secondary market data, and tokenized trading systems increasingly converge around private company price discovery and market sentiment.
Regional exchange infrastructure competition continues to expand beyond traditional Western commodity benchmarks. Exchanges, clearing firms, commodity traders, treasury groups, and market infrastructure operators should track how Singapore based benchmarks, physical delivery systems, and digitally enabled collateral infrastructure increasingly support Asian commodity trade and price discovery.
The case is a governance and creditor risk warning for Canada’s fintech funding market. Investors, lenders, founders, and boards should keep closer watch on treasury controls, debt covenants, founder conduct, and creditor transparency as capital becomes more selective.
Canada’s MSB compliance risk is increasingly visible across multi service fintech models. Crypto firms, PSPs, FX dealers, remittance platforms, investors, and compliance teams should keep registration data current, map services accurately, and treat FINTRAC responsiveness as an operating requirement.
Payments, digital assets, AI fraud controls, and capital markets infrastructure are being rebuilt by registered firms with licenses, distribution, data, and balance sheets. Smaller fintechs can still win, but only where they solve a real operating problem and plug into the financial system with trust from day one. The opportunity is still open, but it will favour teams that move quickly, stay compliant, earn trust, and turn infrastructure change into useful products for customers, merchants, investors, and institutions.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 22, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization, Regulation And Policy, Capital Formation And Venture Markets

Image: Hester Peirce (aka Crypto Mom)
On May 21, 2026, reports confirmed that SEC Commissioner Hester Peirce will leave the U.S. Securities and Exchange Commission later this year to join Regent University School of Law, closing one of the most closely watched regulatory tenures in digital asset policy.
Peirce became affectionately known globally as “Crypto Mom” because she consistently argued that regulators should give digital asset markets workable rules instead of leaving companies to operate inside uncertainty. Her positions moved from controversial to increasingly mainstream as spot bitcoin ETFs launched, tokenization expanded, and major financial institutions entered digital asset infrastructure.
Her departure doesn't mean pro crypto or pro innovation momentum suddenly disappears from Washington. Digital assets no longer depend on a single regulator defending the sector. Bitcoin ETFs now trade in regulated markets. Large banks are building tokenization infrastructure. Stablecoin legislation continues advancing across major jurisdictions. Institutional adoption no longer sits at the fringe.
Still, Peirce leaves behind a clear regulatory record.
For years, she pushed back against regulation through enforcement. She argued that uncertainty weakens both innovation and investor protection because companies struggle to build compliant products when the rules remain unclear.
Many of the issues she raised directly affected fintech competition, startup capital formation, tokenization, crowdfunding, and investor participation. Her speeches consistently returned to the same core themes, such as open markets, proportional regulation, investor choice, and transparent rulemaking.
Peirce’s bluntest critique came during the long debate over regulation through enforcement, where she warned that private meetings with crypto firms cannot replace open rulemaking:
“It’s just not a good way of regulating.”
Her frustration with the SEC’s long delay on spot bitcoin funds became even clearer when spot bitcoin ETFs finally won approval after years of rejected applications:
“We squandered a decade of opportunities to do our job.”
Peirce’s Token Safe Harbor proposal became one of the most discussed crypto policy frameworks because it tried to give blockchain networks time to decentralize before full securities obligations applied.
Her public rulemaking philosophy also stood out in her University of Central Florida FinTech Summit remarks, where she urged regulators to approach innovation with both skepticism and openness instead of reflexive resistance. She later warned that poor engagement damages the relationship between regulators and innovators:
“We are scaring people off from coming in and having a conversation with us.”
Even when she defended innovation, Peirce did not argue for eliminating rules. In her statement on tokenized securities, she welcomed the promise of blockchain while drawing a hard compliance line:
“Tokenization may facilitate capital formation and enhance investors’ ability to use their assets as collateral.”
She also added the part many crypto promoters prefer to skip:
“Tokenized securities are still securities.”
That balance partly explains why Peirce maintained credibility across crypto markets and traditional finance circles. She supported innovation, but she also believed markets work best when participants understand the rules.
Her influence reached beyond crypto. Peirce consistently supported broader access to capital markets, regulatory transparency, and competition for smaller firms. Those priorities aligned closely with long standing NCFA positions on equity crowdfunding and capital markets modernization, fintech competitiveness, and proportional regulation for emerging companies.
Very few SEC commissioners become recognizable public figures outside securities law circles. Peirce did because she represented a different philosophy of regulation during one of the most contested periods in financial technology policy.
Her departure closes an important chapter at the SEC. But the larger debates around tokenization, digital asset infrastructure, market access, and programmable finance are now deeply embedded across global financial systems. Those discussions continue with or without Crypto Mom inside the building.
Peirce also engaged directly with the broader fintech and innovation community over the years, including participating in NCFA’s FFCON21: Breaking Barriers program.
On behalf of everyone at NCFA, we thank Hester Peirce for consistently contributing to open debate around innovation, competition, investor choice, and access to capital during one of the most important periods in modern financial market development. We wish her continued success in this next chapter.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016