





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 30, 2026 | NCFA Fintech Whisperer | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data, Regulation and Policy, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026).
Tokenized bonds are moving from pilots into market structure work. Issuers, dealers, custodians, infrastructure providers, and regulators need practical answers on issuance, settlement, custody, disclosure, and secondary liquidity before tokenized fixed income can scale.
The value of cross chain infrastructure comes down to whether developers can route liquidity without exposing users to bridge complexity. The $230M private beta gives 0x early usage evidence, but the larger test is reliability across payments, RWAs, trading, and agent workflows when volumes move beyond controlled integrations.
Stablecoin licensing is becoming a competitive infrastructure tool for financial centres. Issuers, banks, PSPs, custodians, and regulators should track which jurisdictions turn stablecoin rules into live market access rather than policy design alone.
Tokenized money market funds are becoming part of institutional onchain liquidity infrastructure. Asset managers, custodians, PSPs, stablecoin issuers, and treasury teams should track how stablecoins connect with regulated fund products, redemption workflows, and stablecoin payment infrastructure.
Institutional DeFi is shifting toward custody controlled access models. Asset managers, custodians, exchanges, advisers, and compliance teams should track whether qualified custody plus curated onchain strategies becomes the operating model that brings DeFi exposure into regulated portfolios.
The useful signal is not simply another crypto loan product. It is committed buyer capital behind crypto backed credit, which can make the product more repeatable. The key risks remain collateral volatility, liquidation design, borrower suitability, and whether digital asset wealth can support credit access without turning into hidden leverage.
Crypto collateral can help asset rich borrowers avoid selling Bitcoin or USDC, but housing finance brings stricter expectations around suitability, custody, volatility buffers, and borrower protection. The product will need to prove it expands access without importing crypto market risk into mortgage underwriting.
Large banks are moving from stablecoin observation into direct tokenized money infrastructure. Treasury teams, payment providers, fintechs, custodians, and infrastructure operators now need to track whether commercial bank money becomes a regulated settlement layer for high value payments, liquidity management, and cross border transactions.
Western Union’s stablecoin entering a major crypto exchange channel adds another proof point for stablecoins becoming payment infrastructure. PSPs, exchanges, banks, remittance firms, and compliance teams should track how regulated issuers, fiat channels, and global payout networks connect. This adds a distribution proof point for regulated stablecoins. Western Union brings the remittance brand and global currency footprint, while Bybit brings crypto exchange access. The open question is whether USDPT becomes a settlement asset customers actually use, or another branded stablecoin competing for scarce transaction depth.
Central bank money settlement is being designed for programmable markets. Banks, FMIs, tokenized asset platforms, and settlement operators need to understand how RTGS synchronisation could connect central bank money with external asset ledgers and reduce settlement risk in digital markets.
Domestic real time payment systems are becoming exportable cross border infrastructure. Payment networks, banks, wallets, tourism merchants, and regulators are building direct QR payment links that reduce card dependence and make national payment rails usable outside their home markets.
Access to Canada’s payment infrastructure continues to widen beyond traditional banks and large financial institutions. Fintechs, payment providers, credit unions, foreign exchange firms, and digital finance companies are gaining a larger role in the systems and governance discussions that shape payment modernization.
Open banking is moving from one off payments into repeatable payment schemes with shared rules and commercial terms. Banks, PSPs, merchants, fintech platforms, and regulators should track whether recurring account to account payments become a real alternative to cards, direct debit, and closed wallet systems.
Card settlement is no longer limited to traditional banking hours or traditional settlement assets. Banks, acquirers, PSPs, stablecoin issuers, and fintech platforms should track how major payment networks use regulated stablecoins to support faster settlement, lower liquidity friction, and always on money movement.
Stablecoin remittances are moving from fintech experiments into established money transfer networks. Banks, PSPs, remittance firms, stablecoin issuers, and compliance teams should track how large networks use tokenized dollars to reduce settlement friction while staying inside regulated payment flows.
Pay by bank is becoming a practical payment rail strategy, not just a checkout concept. PSPs, banks, merchants, and fintech platforms should track how instant payment routing, risk controls, and settlement access shape competition against cards and traditional ACH flows.
Stablecoins are gaining traction in regulated payment flows, not just trading markets. Remittances remain one of the clearest real world use cases because settlement speed, foreign exchange costs, and cross border reach matter more than speculative activity. Canadian fintechs, PSPs, banks, and regulators should watch whether stablecoin based remittance models can scale while meeting compliance, safeguarding, and consumer protection requirements.
OpenPayd’s planned Nasdaq listing puts programmable money movement under public market scrutiny. PSPs, banks, stablecoin firms, embedded finance platforms, investors, and regulators should track how the listing exposes the economics, licensing footprint, transaction volume, and risk controls behind global payment infrastructure.
Crypto sanctions enforcement is moving deeper into exchange infrastructure and stablecoin flows. Exchanges, custodians, PSPs, blockchain analytics firms, and compliance teams should track how sanctions screening, stablecoin monitoring, and cross border counterparty controls become core operating requirements.
Technology policy is increasingly becoming infrastructure policy. As governments focus on AI capacity, cloud services, strategic data assets, semiconductor supply chains, and digital resilience, firms may face growing pressure to evaluate technology dependencies, procurement choices, hosting arrangements, and infrastructure risk. The result could be a more fragmented global technology environment shaped by competing sovereignty frameworks.
Consumer AI policy is moving toward practical controls for trust, consent and accountability. Banks, fintechs, AI firms, platforms and regulators should watch how user controls, complaint routes, audit trails and outcomes based duties apply when AI systems influence financial decisions or act for consumers.
The operating change is where AI work happens. If capable agents can run locally, more sensitive analysis, file handling, audio processing, and workflow automation can stay on device instead of moving through cloud APIs. That could change enterprise AI design, human oversight, privacy controls, and bot to bot workflows.
The United States is testing a lighter regulatory model for frontier AI that relies on voluntary participation, security evaluation, and industry cooperation. Financial institutions, fintechs, infrastructure providers, and AI developers should watch whether this approach accelerates deployment while maintaining confidence in systems that increasingly influence payments, capital markets, fraud controls, and critical infrastructure.
Revolut’s U.S. strategy shows why bank charters are becoming infrastructure plays for global fintechs. FDIC insured products, payment rail access, stablecoin services, and securities trading under one app could raise the competitive bar for sponsor bank dependent fintech models.
Stablecoin regulation is becoming a competitiveness question, not only a risk control exercise. Issuers, banks, PSPs, custodians, and policymakers should track whether the UK loosens its approach or keeps tougher safeguards that could limit domestic stablecoin scale.
Stablecoin supervision is becoming cross border supervision. Issuers, exchanges, custodians, payment firms, and compliance teams should expect more information sharing between regulators as stablecoin activity crosses jurisdictions, banking systems, and payment networks.
The word of the week is 'control'. Banks, payment networks, fintechs, custodians, stablecoin issuers, and AI providers are competing closer to the infrastructure layer, where settlement, custody, compliance, data, and distribution decisions get made. Which rails, licenses, partners, and operating models create durable access before the next layer of financial infrastructure gets locked in?
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |

Last Updated: June 3, 2026
Status: Strengthening
Organizations: CIRO, CSA, OSFI, OCC, SEC, TSXV, CSE
The answer is yes. Regulators are opening parts of finance to more firms, lighter processes, and new digital models, but the tradeoff is a higher bar for records, controls, reporting quality, investor protection, supervision, and evidence. Access is getting better for some firms. Operating without strong compliance proof is getting harder.
This is why the market access question isn't only about reducing red tape. It's about whether firms can use simpler rules, new approvals, and digital distribution without creating weak records, unclear accountability, or avoidable investor harm.
The firms to watch are the ones that can turn compliance evidence into a growth asset. Think clean data, fast records production, clear supervision, tested controls, and product design that can withstand review before a problem appears.
Strategic Takeaway
Regulators are trading old friction for stronger proof. Companies that want faster access need better evidence, cleaner controls, and stronger investor protection built into the operating model.
Click each item to expand
The Canadian Securities Administrators adopted a semi annual financial reporting pilot for eligible venture issuers listed on the TSXV and CSE.
OSFI says its streamlined approvals framework will launch in June 2026 for eligible applicants. The framework is intended to create efficiencies for targeted new entrants.
CIRO launched a review of rules for affordable tailored online investment advice, including online and hybrid advisory models.
The SEC Small Business Capital Formation Advisory Committee continued discussion on the regulatory framework for finders and private market liquidity.
Click each item to expand
CIRO launched a Disgorgement Distribution Program to return funds collected through disgorgement orders to harmed investors.
CIRO published an Enforcement Document Production Guide that takes effect May 1, 2026.
CIRO published guidance on third party electronic access to marketplaces, including order execution accounts and related gatekeeper obligations.
The evidence table also tracks counter examples where market access remains fragile, including delayed IPO timing and private market liquidity constraints.
Click each item to expand
The OCC says it is tailoring supervision for community banks by size, complexity, and risk profile, with more focus on material financial risks.
Do you agree the evidence is strengthening?
 2
 1
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 29, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Payments And Market Infrastructure, Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026).
AI compliance is moving from broad principles into operating guidance for agents, automated decisions, procurement, and personal data use. Fintechs, banks, insurers, regtech firms, and AI vendors should track how privacy rules shape AI product design, governance, and customer trust.
Project Agorá's focus is not retail crypto speculation. It is wholesale financial infrastructure, cross border settlement efficiency, programmable payments, and institutional control over tokenized money movement. Go deeper, visit NCFA's curated fintech reports and research library, where the BIS Project Agorá report is listed.
This is not open access to the Fed system. It is a narrower settlement pathway for legally eligible firms operating outside the traditional bank model. Stablecoin issuers, PSPs, crypto firms, tokenization platforms, and embedded finance providers should track whether limited Reserve Bank account access becomes a practical alternative to sponsor bank dependence. This connects to NCFA’s analysis of Fed Payment Accounts and fintech settlement access.
Onchain finance needs shared coordination standards before institutional adoption can scale cleanly. Banks, wallets, PSPs, exchanges, tokenization platforms, and agentic payment builders should track whether identity, messaging, and transaction standards become competitive infrastructure rather than optional middleware.
Large payment networks are adding regulated digital asset permissions to support stablecoin, tokenized settlement, and digital asset infrastructure at institutional scale. Banks, PSPs, exchanges, custodians, and fintech platforms should track which firms secure licences that let crypto services connect with mainstream payment networks.
Stablecoins are moving deeper into consumer banking distribution, not just crypto infrastructure. Banks, fintechs, PSPs, and regulators should watch whether regulated bank issued stablecoins begin competing directly with cards, deposits, remittance products, and embedded payment flows. Also supports this analysis of stablecoins becoming payment infrastructure.
National currency stablecoins are expanding beyond major economies. Stablecoin issuers, banks, PSPs, regulators, and treasury teams should track how smaller jurisdictions use digital fiat infrastructure to compete for payment flows, fintech investment, and cross border settlement.
Climate disclosure is moving back toward company specific materiality rather than a dedicated SEC climate reporting regime. Public companies, fintech lenders, ESG data providers, regtech firms, investors, and capital markets platforms should track how climate risk reporting moves across U.S. federal rules, state rules, EU requirements, and voluntary investor expectations.
Bank charter strategy is becoming part of digital asset and payment infrastructure competition. Banks, fintechs, stablecoin firms, custodians, and compliance teams should track which institutions secure federal supervision, stronger operating permissions, and clearer access to national banking infrastructure.
MiCA is moving from licensing theory into enforcement risk. Crypto exchanges, custodians, wallet providers, brokers, and compliance teams should treat EU authorization, local regulator engagement, and operating perimeter checks as immediate market access priorities.
Prediction markets are moving deeper into conflict with gambling, derivatives, and securities frameworks. Exchanges, fintechs, tokenization firms, and prediction market operators should expect more pressure around licensing, market surveillance, consumer protection, and jurisdictional authority as these platforms expand globally.
USMCA risk is now back inside Canada’s competitiveness file. Fintech lenders, payment firms, investors, marketplaces, and platforms serving SMEs should watch how tariff uncertainty affects customer margins, capital demand, foreign exchange exposure, supplier payments, and cross border expansion.
Crypto sanctions enforcement now reaches deeper into financial infrastructure networks, not just individual wallets or isolated actors. Exchanges, custodians, PSPs, banks, compliance teams, and blockchain monitoring firms should expect more scrutiny around transaction tracing, counterparty checks, and sanctions controls tied to digital asset flows.
Post trading rules are becoming more important as Europe modernizes settlement operations, CSD messaging, and market infrastructure controls. CSDs, brokers, banks, custodians, tokenization platforms, and compliance teams should track how messaging standards affect settlement efficiency, operational risk, and future market infrastructure integration.
Blockchain based settlement is moving into formal U.S. market infrastructure permissions. Brokers, custodians, tokenization platforms, exchanges, and asset managers should track how SEC registered clearing models affect securities settlement, custody design, and tokenized market structure.
Retail investing scale increasingly depends on back end clearing and custody infrastructure. Fintech platforms, brokers, clearing firms, embedded finance providers, and regulators should track how large consumer apps choose clearing partners that can support faster launches, broader products, and stronger operational controls.
This week was less about crypto adoption and more about who gets trusted access to the pipes. The Fed tested a narrow settlement account, Paxos received SEC clearing agency registration, Mastercard secured a BitLicense, SoFi launched a bank issued stablecoin, and Project Agorá moved wholesale tokenized settlement into deeper testing. The fresh lesson is that access is becoming tiered. Firms won’t all get the same rails, licences, or settlement rights.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Last Updated: May 28, 2026
Status: Strengthening
Organizations: Bank of Canada, DTCC, Broadridge, NYSE, Securitize, FCA, LSEG, BIS
The answer is yes, but only in the right legal and market structure. Tokenized real world assets are becoming usable where regulators connect them to securities, custody, fund, settlement, collateral, payment, and investor protection rules. The strongest evidence is not speculative token launches. It is regulated infrastructure that can support bonds, Treasuries, funds, repo, collateral, transfer agency, and settlement.
The practical question is not whether RWAs can be tokenized. They can. NCFA has tracked this progression from experimentation to execution. Earlier evidence showed how tokenization started looking like financial infrastructure, while more recent developments show tokenization finding scale in collateral and cash. European policymakers are also advancing a roadmap for tokenized finance infrastructure, reinforcing the view that tokenization is increasingly being evaluated as market infrastructure rather than a standalone asset class.
The firms to watch are the ones building the boring middle layer. That means custody, transfer agency, collateral management, settlement links, reporting, governance, and legal certainty. RWA growth depends on trust and operating proof, not marketing.
Strategic Takeaway
Tokenized RWAs are becoming market infrastructure where legal rights, custody, settlement, collateral, and investor protections connect. The opportunity is not just putting assets on chain. It is making regulated assets easier to hold, move, finance, and reconcile inside trusted financial systems.
Click each item to expand
The Bank of Canada, Export Development Canada, RBC, TD, and RBC Investor Services completed a tokenized bond experiment using distributed ledger technology. This gives Canada a credible domestic proof point for tokenized securities infrastructure.
DTCC is preparing tokenized real world asset services for production use. This is important because DTCC sits inside regulated post trade infrastructure, not outside the system.
Broadridge’s Distributed Ledger Repo platform shows tokenization already operating in a serious institutional workflow. Repo is market plumbing tied to collateral, liquidity, and funding.
NYSE and Securitize agreed to support tokenized securities infrastructure, including standards for digital transfer agents and tokenization agents.
The UK FCA published rules and guidance for fund tokenisation, giving asset managers a practical framework for tokenized fund operations.
Project Agorá, led by the BIS with central banks and commercial banks, tests tokenized deposits and wholesale central bank money for cross border settlement. This matters because tokenized assets need a reliable cash leg.
Do you agree the evidence is strengthening?
2
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Last Updated: May 28, 2026
Status: Building
Organizations: SoFi, Department of Finance Canada, Bank of Canada, FCA, UK Government
The answer is yes, but not because stablecoins are leaving crypto behind. They are expanding from crypto market use into banking apps, remittances, reserve models, and payment policy. The test is no longer whether tokens can move on chain. The test is whether they can move money inside regulated financial systems.
The link to payment access is important. Stablecoins need banking partners, reserves, payment gateways, custody controls, and settlement routes. That connects directly to limited direct settlement access, because stablecoin utility depends on how close non bank firms can get to trusted payment and reserve infrastructure.
The firms to watch are the ones that can make stablecoins boring enough to use. That means clean reserves, clear redemption, strong compliance, distribution reach, and payment flows that solve real problems.
Strategic Takeaway
Stablecoins are expanding into payment infrastructure where they connect trusted reserves, regulated distribution, and real money movement. The strongest players may be firms that can make tokenized money useful without making users think about crypto at all.
Click each item to expand
SoFiUSD shows stablecoins moving into mainstream financial distribution. The product is positioned as a bank issued, 1:1 redeemable U.S. dollar stablecoin inside the SoFi app.
Canada’s framework gives the stablecoin infrastructure question a domestic policy base. It moves stablecoin activity toward rules for issuance, reserves, custody, redemption, governance, and oversight.
UK policy work shows regulators treating stablecoins as potential payment instruments, not only crypto assets. That means issuance, custody, reserves, and payment services are becoming connected policy questions.
Do you agree the evidence is strengthening?
1
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Last Updated: May 27, 2026
Status: Building
Organizations: Federal Reserve, Neo, Interac, Tether, Government of Georgia
The answer is moving toward yes, but through tighter gates. Regulators are not opening settlement systems to every fintech. They are testing whether some firms can reach parts of the settlement layer without becoming banks.
Canada already allows some narrower access models through Interac participation and registered payment frameworks. The next pressure point may come from real time payments, stablecoin reserve treatment, tokenized settlement, or cross border payment competition from outside Canada.
The firms to watch are not necessarily the biggest fintechs. The advantage may go to companies that can prove resilience, compliance depth, operational uptime, fraud controls, and trusted movement of funds at scale. Regulators appear more willing to test narrower infrastructure access when the activity is tightly defined and operationally mature.
Strategic Takeaway
Limited direct settlement access is becoming a middle layer between sponsor bank dependence and full banking status. That could reshape who controls payment flow, customer relationships, settlement logic, and financial infrastructure over the next few years.
Click each item to expand
The Fed proposal separates limited payment access from full banking status. It gives regulators a way to test settlement and reserve functions without granting the full benefits of a Master Account.
Neo’s Interac access gives the Canadian market a practical proof point. Direct rail participation can improve control over payment flow without turning a fintech into a full bank.
The Georgia stablecoin plan shows why this question is moving beyond traditional payment rails. Stablecoins can connect payments, remittances, programmable finance, and national digital infrastructure.
Do you agree the evidence is strengthening?
0
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 26, 2026 | NCFA Insight | Payments And Market Infrastructure, Regulation And Policy, Digital Assets Blockchain And Tokenization
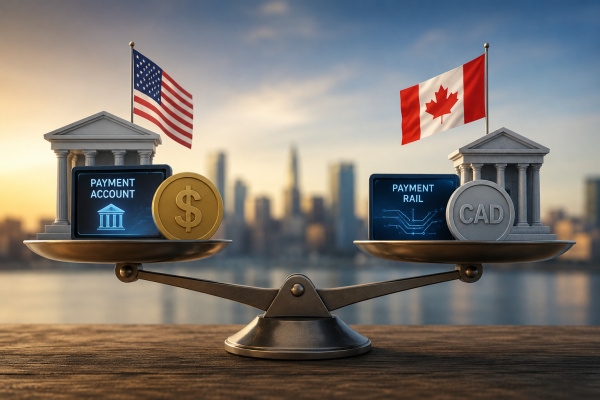
The Fed is proposing limited settlement accounts for eligible firms. The bigger question is whether the U.S. gives qualified fintechs a cleaner infrastructure advantage than Canada.
On May 26, 2026, the Federal Reserve published a Federal Register proposal for special purpose Payment Accounts. Legally eligible institutions could use them to clear and settle certain payment activity through Reserve Bank accounts. Comments are due by July 27, 2026 under Docket No. OP-1878.
The proposal isn't open access to the Fed. Payment Accounts would have no intraday credit, no discount window access, no interest on balances, no correspondent activity, and no respondent activity. Closing balances would generally be capped at $1B. The account would support approved payment settlement, not full banking privileges.
Jerome H. Powell, Fed Chair said:
“The proposed payment account would be tailored to support innovation by serving the clearing and settlement needs of certain eligible institutions while also mitigating material risks to the Reserve Banks and payment system.”
A Master Account gives an eligible institution direct access to Reserve Bank balances and Federal Reserve payment services. The proposed Payment Account is narrower in scope. Firms would not borrow from the Fed, earn interest, receive daylight overdrafts, or use the account as a correspondent banking platform.
The Fed is testing whether limited settlement access can exist without full banking access.
Fintechs, crypto firms, trust companies, and novel chartered institutions have pushed for Fed access because sponsor bank dependence affects cost, timing, liquidity, and settlement certainty. Banks have pushed back because wide access can raise compliance, liquidity, and regulatory arbitrage concerns.
In 2022, the Fed finalized Account Access Guidelines with a tiered review framework. The toughest review applies to institutions that are not federally insured and are not subject to federal prudential supervision at the institution or holding company level.
The 2026 proposal doesn't replace that framework. It creates a tighter account model inside the same access debate.
The proposal discusses use cases raised by commenters, including stablecoin issuer reserve operations, tokenized securities settlement in central bank money, tokenized assets, pay by bank checkout, B2B transfers, instant wages and refunds, and the U.S. dollar leg of cross border transactions.
Those use cases point to the same operating need, clean settlement. Stablecoin issuers need reliable reserve movement. Tokenization platforms need cash settlement closer to central bank money. PSPs need faster payment settlement. Pay by bank providers need lower cost routing. Cross border firms need cleaner dollar leg execution.
Today, many fintechs settle payments through sponsor banks. A fintech sends payment instructions, but the actual settlement usually happens through a commercial bank account connected to central bank rails.
Under the Fed proposal, an approved firm could potentially hold limited settlement balances directly at a Reserve Bank for approved payment activity. That could reduce some dependence on sponsor banks for specific flows.
For a stablecoin issuer, that could improve reserve movement and redemption settlement.
For a pay by bank provider, it could streamline payment routing.
For a tokenization platform, it could support settlement closer to central bank money instead of relying entirely on commercial bank ledger movement.
The proposal would not turn fintechs into banks. Firms would not receive deposit insurance, emergency liquidity, or unrestricted Fed access.
If eligible U.S. firms gain limited Reserve Bank settlement access while Canadian firms remain more dependent on bank intermediaries, U.S. fintechs could gain an operating edge in payment speed, settlement certainty, reserve movement, and cost control.
That edge is important for stablecoins, tokenized securities, pay by bank, B2B payments, cross border transfers, and embedded finance. These markets compete on speed, liquidity use, compliance reliability, and integration cost.
It could also change sponsor bank negotiations. A firm with a credible settlement alternative has more leverage than one with no alternative.
| Question | U.S. Fed Payment Account Proposal | Canada RPAA Registered PSP | Canada Payment Rail Participation |
|---|---|---|---|
| Live today? | No. Proposal only. | Yes | Yes |
| Can hold settlement balances at the central bank? | Only if final rules approve it and the firm qualifies. | No | No by participation alone. |
| Can settle some payments through a central bank account? | Would apply only to approved payment activity. | No | RTR may allow direct settlement for eligible participants that qualify for Bank of Canada settlement accounts. RPAA registration alone doesn't. |
| Still needs sponsor banks? | Yes, but dependence could fall for approved settlement flows. | Yes | Yes, in many cases. |
| Gets full banking powers? | No | No | No |
| Main benefit | Potentially cleaner settlement for stablecoins, tokenized assets, pay by bank, and cross border dollar flows. | Legal operation under Bank of Canada supervision. | Access to payment rails and network participation. |
Canada’s retail payments framework brings PSPs into Bank of Canada supervision. The PSP registry under the RPAA confirms registration status, required fees, and national security screening. Registration does not itself provide limited direct settlement access.
Payments Canada says the Real Time Rail will launch in Q4 2026 as Canada’s instant, data rich exchange and clearing and settlement payment system. RTR is expected to broaden access for eligible participants, including PSPs that meet applicable requirements.
Canada has also legislated a fiat backed stablecoin framework, with detailed rules and implementation still being developed. The framework helps define issuer obligations around reserves, redemption, governance, data security, and Bank of Canada oversight. It does not itself provide payment rail access or limited direct settlement access.
The competitive question is not whether Canada should copy the Fed. It's whether Canada can give qualified PSPs, stablecoin issuers, and tokenization firms a clear access ladder from supervision to rail participation to settlement. If U.S. firms gain a narrow Fed settlement lane while Canadian firms wait for comparable clarity, product speed, treasury efficiency, and sponsor bank leverage may tilt south.
If U.S. firms get limited central bank settlement access, what should Canada let supervised PSPs access once they meet higher standards?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
